
 Dental Engine Market | 2026-2036
Dental Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Engine Market Outlook
Modular handpiece-to-control-unit bundling is rebalancing procurement economics for mid-sized dental practices. Dentsply Sirona leverages its integrated platform architecture to dominate premium system sales across North American dental schools. Planmeca Oy anchors its competitive position through deep specialization in open-architecture CAD/CAM connectivity. A-dec Inc. sustains manufacturing scale advantages in chairside delivery systems that incorporate engine subassemblies.
A dental engine is a motorized rotary instrument that delivers controlled torque to cutting burs at speeds ranging from 5,000 to 400,000 RPM for tooth preparation and hard-tissue modification. Electric variants now displace air-turbine units in restorative workflows because consistent torque output reduces microfracture risk during ceramic crown seating. Application segmentation shows restorative dentistry occupying the dominant revenue position while endodontics represents the fastest-growing procedure category due to nickel-titanium rotary system proliferation. Technology segmentation reveals CAD/CAM integration capturing margin pools at the system level, whereas digital imaging functions as the mature, price-competitive layer.
MDR in Europe, FDA 510(k) clearance pathways in the United States, and PMDA quality management standards in Japan collectively elevate compliance costs for active device manufacturers while creating barriers for unvalidated entrants. These frameworks shape demand by mandating biocompatibility testing for coolant-contact components and traceability protocols for sterilization cycles. Stakeholders must monitor how software-as-medical-device classifications in major jurisdictions affect digital engine control modules.
Market Dynamics
Electric handpiece technology is consolidating procurement decisions around integrated platform ecosystems, compressing vendor selection criteria from standalone performance metrics to system-level compatibility and digital workflow continuity.
Growth Catalysts
- MDR Compliance Mandates:Europe's Medical Device Regulation tightens biocompatibility and traceability requirements for active implantable devices, accelerating replacement cycles among German and French dental clinics seeking validated equipment suppliers.
- CAD/CAM Workflow Integration:Metropolitan dental clusters in Japan and South Korea demand engines with open-architecture connectivity to chairside milling systems, creating specification premiums for digitally native platforms.
- Nickel-Titanium Rotary Proliferation:Endodontic practices worldwide adopt flexible rotary file systems requiring precise torque control, pulling demand toward electric variants with programmable speed-torque curves.
Market Restraints
- Copper and Rare Earth Volatility:Electric motor windings and permanent magnet materials face price instability from concentrated Chinese refining operations, pressuring component cost structures.
- Air-Turbine Installed Base Lock-In:Legacy pneumatic infrastructure in established US and European practices creates switching friction against full electric conversion, extending hybrid equipment transition timelines.
- CE Marking Technical Documentation Burden:MDR Annex I general safety and performance requirements demand expanded clinical evidence for software-controlled torque modulation features.
Strategic Opportunities
- Brazilian Private Dental Network Expansion:ANVISA regulatory alignment with ISO 13485 standards opens pathway for premium electric system penetration in São Paulo and Rio de Janeiro clinic chains.
- Preventive-Restorative Convergence:Air abrasion and micro-preparation techniques create demand for ultra-low-speed precision engines in minimally invasive caries management workflows.
- Leasing and Subscription Models:Equipment-as-a-service arrangements bypass capital expenditure barriers for mid-sized UK and Australian practices, embedding manufacturers in long-term maintenance relationships.
Industry Challenges
- Biomedical Servicing Technician Scarcity:Complex electromechanical repairs require specialized training in brushless motor controllers and sensor calibration that exceeds traditional dental equipment maintenance skill sets.
- Legacy Pneumatic-Electric Interface Standardization:ISO 3964 coupling compatibility gaps between manufacturer-specific quick-connect systems create integration failures during mixed-fleet upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Engine Market |
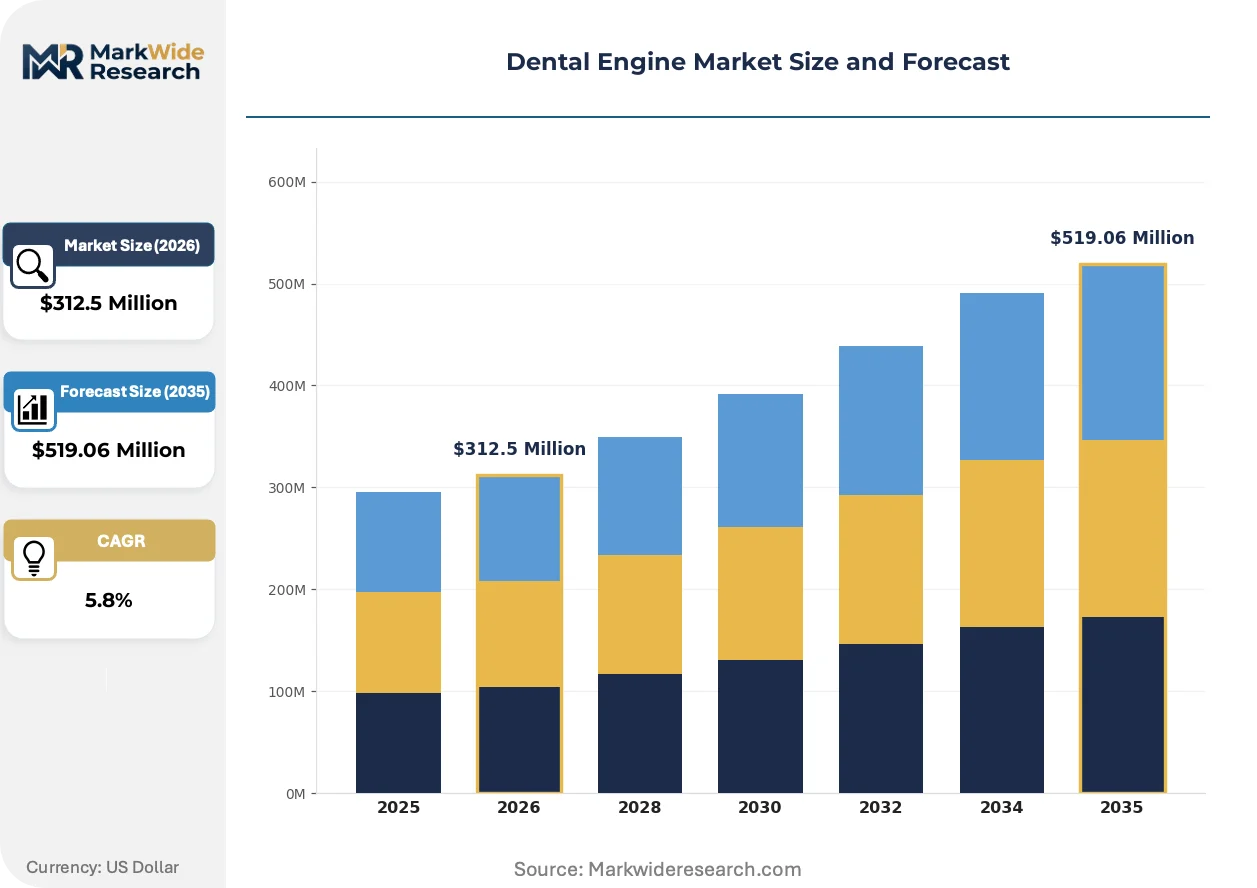
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Air Turbine, Electric, Ultrasonic, Laser Application: Restorative Dentistry, Oral Surgery, Pediatric Dentistry, Endodontics End User: Dental Clinics, Hospitals, Research Laboratories, Dental Schools Technology: CAD/CAM, 3D Printing, Digital Imaging, Simulation Software |
| Companies Covered | Dentsply Sirona, 3M Company, Planmeca Oy, A-dec Inc., GC Corporation, Straumann Holding AG, Aseptico Inc., Envista Holdings, Kavo Kerr, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Engine Market Strategic Shifts
Digital control architectures and connected health frameworks are redefining how torque delivery systems interface with practice management software and remote diagnostics platforms.
Brushless DC motor technology with integrated Hall-effect position sensing is expanding into high-volume restorative workflows. North American dental schools now specify these platforms for student training clinics to ensure consistent cutting performance across operator skill levels. The technology is expanding into mid-market equipment tiers previously served by conventional brushed motors, compressing price-performance boundaries between premium and standard system classifications.
Europe's MDR post-market surveillance requirements now mandate systematic collection of device performance data across the product lifecycle. Manufacturers must implement automated adverse event reporting pipelines and periodic safety update reports for software-enabled torque control modules. German notified bodies are prioritizing technical documentation reviews for engines with cloud-connected maintenance monitoring, creating compliance backlogs for smaller suppliers lacking quality management system maturity.
Metropolitan dental service organizations are consolidating procurement authority from individual practitioners to centralized supply chain functions. These entities negotiate enterprise pricing for standardized equipment fleets across multi-site networks, displacing traditional distributor relationships in Tokyo, London, and New York markets. The concentration of purchasing power favors vendors with configurable platform architectures and dedicated account management infrastructure.
Dental Engine Market Segmentation
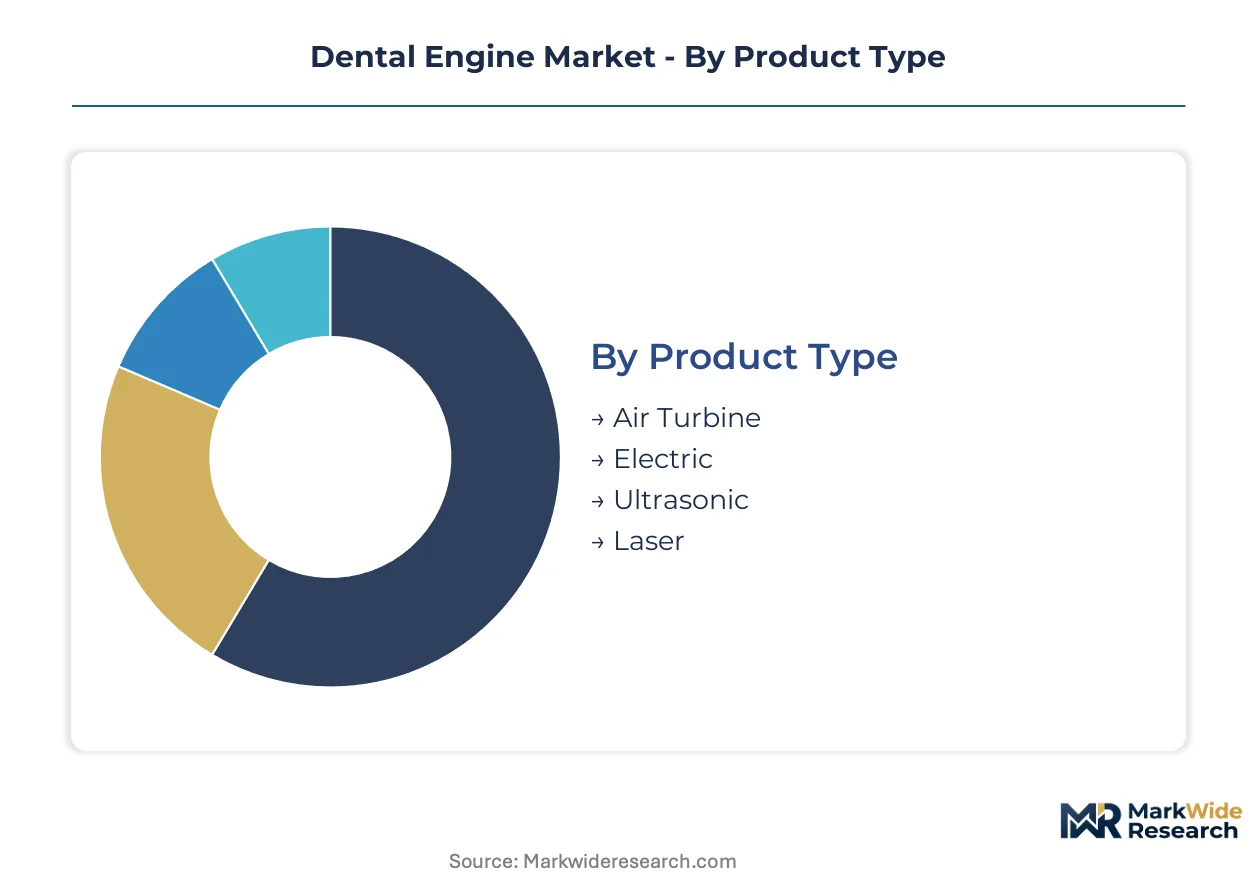
Dental engine procurement varies sharply by clinical setting and procedure type. Capital allocation decisions hinge on torque precision requirements, digital integration needs, and sterilization throughput volumes.
Product Type:
Capital intensity peaks with electric systems requiring precision motor controllers and sensor arrays, while air-turbine infrastructure demands lower upfront outlays but higher lifetime maintenance.
- Electric:Brushless DC motors with Hall-effect position sensing deliver programmable torque curves from 5,000 to 40,000 RPM. German dental clinics prioritize these systems under MDR compliance mandates for active implantable device traceability.
- Air Turbine:Pneumatic rotary instruments operating at 300,000 to 400,000 RPM via compressed air delivery. Legacy installed base in US metropolitan practices creates switching friction against full conversion, extending hybrid transition timelines.
- Ultrasonic:Piezoelectric transducers generating 20-45 kHz vibrations for calculus removal and periodontal debridement.
- Laser:Solid-state and diode systems for soft-tissue modification and caries detection.
Most installed capacity flows through Air Turbine. Expansion is steepest in Electric.
Application:
Procedure complexity determines equipment specification tiers, with crown preparation and implantology driving premium system adoption.
- Restorative Dentistry:Crown preparation, bridge work, and veneer seating require consistent torque output to reduce microfracture risk during ceramic restoration placement. Japanese metropolitan dental clusters specify CAD/CAM-integrated engines for chairside milling workflows.
- Endodontics:Nickel-titanium rotary file systems demand precise speed-torque modulation to prevent instrument separation within root canals. South Korean endodontic practices are gaining share fastest for digitally programmable electric handpieces.
- Oral Surgery:Bone cutting and implant site preparation using surgical handpieces with irrigation channels.
- Pediatric Dentistry:Reduced-speed, reduced-torque systems for primary tooth modification and behavior management.
Restorative Dentistry commands the largest equipment spend. Endodontics is climbing the fastest.
End User:
Purchasing authority concentration varies from centralized hospital procurement to individual practitioner decision-making in private clinics.
- Dental Clinics:Independent and group practices representing the primary volume channel for replacement cycles and technology upgrades.
- Hospitals:Maxillofacial surgery departments with enterprise procurement functions and standardized equipment fleets.
- Dental Schools:North American training clinics specify brushless DC platforms to ensure consistent cutting performance across student skill levels.
- Research Laboratories:Biomechanical testing facilities and materials science departments evaluating cutting dynamics.
Dental Clinics absorb the majority of unit shipments. Dental Schools show the steepest specification upgrade trajectory.
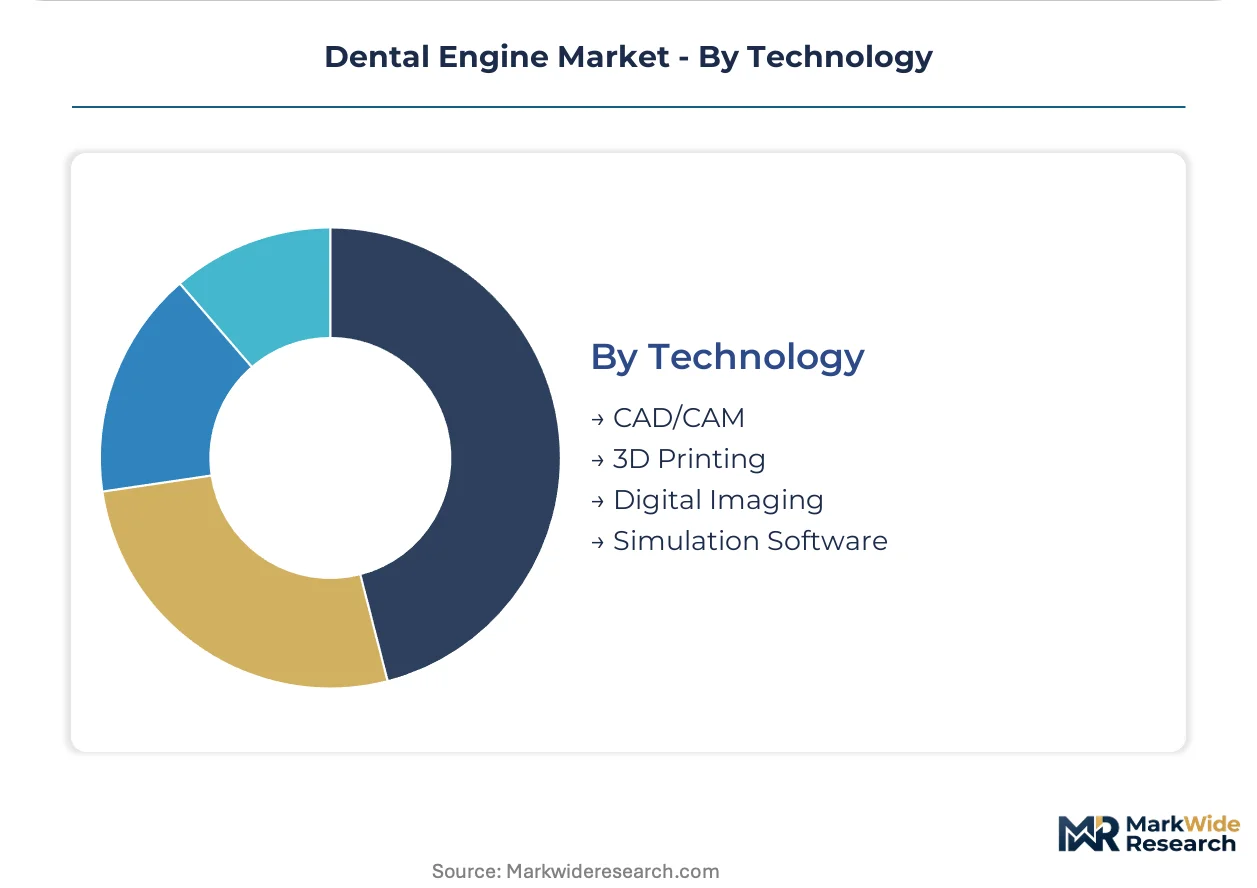
Technology:
Digital layer integration captures margin pools at the system level while mature imaging functions compete on price.
- CAD/CAM:Open-architecture connectivity protocols enabling torque control modules to interface with chairside milling systems. Planmeca Oy anchors competitive position through deep specialization in this layer.
- Digital Imaging:Intraoral scanners and radiographic systems functioning as the mature, price-competitive technology tier.
- 3D Printing:Additive manufacturing for surgical guides and provisional restorations.
- Simulation Software:Haptic training platforms for operator skill development.
CAD/CAM integration commands premium positioning. 3D Printing is gaining share fastest for workflow digitization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The dental engine industry traces its modern scaling to German precision engineering traditions of the early twentieth century, when Stuttgart and Munich manufacturers established standardized rotary instrument specifications that persist in today's ISO 3964 coupling protocols.
Germany
German dental clinics are accelerating replacement cycles under MDR compliance mandates for active implantable device traceability. The country's national medical device regulator enforces expanded clinical evidence requirements for software-controlled torque modulation. Stuttgart manufacturers supply precision motor controllers to metropolitan dental clusters in Munich and Frankfurt, where CAD/CAM integration drives specification premiums.
United States
US metropolitan practices maintain substantial legacy air-turbine infrastructure that creates switching friction against full electric conversion. FDA 510(k) clearance pathways demand biocompatibility documentation for coolant-contact components that elevates compliance costs for new entrants. Dental service organizations in New York and Chicago consolidate procurement authority, negotiating enterprise pricing for standardized equipment fleets across multi-site networks.
Japan
Japanese metropolitan dental clusters specify open-architecture connectivity to chairside milling systems, creating demand premiums for digitally native platforms. PMDA quality management standards mandate traceability protocols for sterilization cycles that shape vendor selection criteria. Tokyo and Osaka endodontic practices are gaining share fastest for digitally programmable electric handpieces with precise speed-torque curves.
South Korea
South Korean endodontic practices pull demand toward electric variants with programmable speed-torque curves for nickel-titanium rotary file systems. The country's pharmaceutical and medical device regulator enforces quality management standards aligned with international ISO 13485 frameworks. Seoul dental clusters drive replacement cycles through CAD/CAM workflow integration with metropolitan clinic chains.
Brazil
Brazilian private dental networks in São Paulo and Rio de Janeiro are opening pathways for premium electric system penetration. ANVISA regulatory alignment with ISO 13485 standards reduces barriers for validated equipment suppliers entering clinic chain procurement processes. São Paulo manufacturers are scaling assembly operations to serve Latin American replacement demand.
Dental Engine Market Competitive Environment
Premium-margin players sit above commodity-margin players across platform integration depth, with bundled handpiece-to-control-unit systems commanding specification premiums while standalone air-turbine components compete on replacement part accessibility. Market structure shows moderate consolidation around integrated platform ecosystems, compressing vendor selection criteria from standalone performance metrics to system-level compatibility. Three archetypes dominate: full-platform integrators with chairside delivery system manufacturing scale, CAD/CAM connectivity specialists with open-architecture protocols, and component suppliers serving hybrid fleet maintenance demand. Competitive moves concentrate on strategic partnerships for digital workflow continuity and backward integration into precision motor controller production.
Within the full-platform integrator tier, Dentsply Sirona and A-dec Inc. represent archetypes of manufacturing scale advantages in chairside delivery systems. Planmeca Oy occupies a position among CAD/CAM connectivity specialists, exemplifying competitive positioning through deep specialization in open-architecture protocols. These three entities anchor the premium-tier vector where procurement decisions consolidate around integrated ecosystem compatibility rather than standalone instrument performance.
| Leading Market Players |
|---|
| Dentsply Sirona |
| 3M Company |
| Planmeca Oy |
| A-dec Inc. |
| GC Corporation |
| Straumann Holding AG |
| Aseptico Inc. |
| Envista Holdings |
| Kavo Kerr |
| Others |
Value Chain & Pricing Dynamics
Copper winding costs and rare earth magnet prices cascade from Chinese refining operations through electric motor controller assemblies into tiered equipment pricing for German and Japanese dental clinics. MDR compliance documentation burdens and CAD/CAM integration premiums stratify procurement economics across mid-sized practices and metropolitan clinic chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates brushless DC platforms with Hall-effect sensing from conventional brushed motors and legacy air-turbine units. Price differentiation hinges on ISO 13485 certification grade and bundled after-sales service contracts. Cost compression in the standard tier intensifies because Chinese motor suppliers are scaling precision controller production. Mid-sized UK practices exhibit highest price sensitivity, while North American dental schools show lowest sensitivity due to grant-funded capital allocations.
Supply Chain Analysis
Refurbishment flows for precision handpiece motors create secondary supply channels that compete with new unit sales in mature European markets. Manufacturing concentrates in Germany, China, and Japan for brushless motor assemblies and sensor calibration subsystems. Permanent magnet materials and copper windings draw from concentrated Chinese refining operations. Single-source vulnerability in rare earth processing generates supply risk during export quota adjustments. Distribution runs through specialized dental equipment distributors and direct manufacturer relationships with dental service organizations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The dental engine market offers margin expansion through brushless motor technology diffusion into mid-market tiers previously served by lower-performance units. Premium-tier specification upgrades at North American dental schools and Japanese metropolitan clusters justify sustained R&D investment in torque precision.
For Market Incumbents: Anticipate compressed pricing windows as Chinese motor suppliers achieve ISO 13485 certification parity by deepening backward integration into Hall-effect sensor production and brushless controller firmware development. Defend installed base lock-in through proprietary quick-connect coupling systems that frustrate mixed-fleet upgrades from competitor handpieces. For New Entrants and Emerging Players: ANVISA regulatory alignment with ISO 13485 standards in Brazil opens a window for premium electric system penetration among São Paulo and Rio de Janeiro clinic chains seeking validated equipment suppliers. Target the endodontic application segment with programmable speed-torque curve differentiation. Pursue equipment-as-a-service leasing arrangements to bypass capital expenditure barriers for mid-sized Australian practices. For Investors and Strategic Acquirers: Consolidation pressure builds where quality management system maturity gaps strand smaller suppliers in MDR technical documentation backlogs for software-enabled torque control modules. Long-term viability favors acquirers of CAD/CAM connectivity specialists with open-architecture protocols and established chairside milling system partnerships. Monitor PMDA cloud-connected maintenance monitoring classification decisions as inflection indicator for digital engine control module compliance costs.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway Investment | MDR Annex I compliance accelerates German clinic replacement cycles toward validated suppliers. |
| Hospital System Partnership | Metropolitan dental service organizations in Tokyo consolidate procurement authority across multi-site networks. |
| Software Companion Development | Cloud-connected torque modulation modules face PMDA quality management scrutiny in Japan. |
| Backward Integration into Motor Controllers | Captive supply of brushless DC assemblies compresses cost structures for mid-market tier competition. |
| Reimbursement Strategy Alignment | Equipment-as-a-service models embed manufacturers in long-term UK practice maintenance relationships. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with dental equipment procurement managers, biomedical engineering directors, GPO contracts specialists, and aftermarket service technicians with secondary validation against FDA 510(k) filings, PMDA quality management disclosures, hospital procurement databases, and GPO contract repositories. Bottom-up unit shipment estimates and top-down equipment spend analysis triangulated market sizing across electric, air-turbine, ultrasonic, and laser product categories.
Segment-weighting approaches distributed value estimates across product type, application, end user, and technology dimensions throughout the forecast period. CAGRs derived from replacement cycle analysis, regulatory compliance mandate timelines, and CAD/CAM adoption curve modeling. Forecast inputs incorporated nickel-titanium rotary file system proliferation rates and MDR post-market surveillance implementation phases.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export quota disruptions or accelerated software-as-medical-device reclassifications in major jurisdictions. Forecasts reflect documented assumptions regarding MDR compliance cost trajectories and air-turbine installed base decay rates. Practitioners should monitor ANVISA regulatory alignment progress and Chinese permanent magnet pricing volatility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Equipment
Global Dental Light Curing Equipment Market
Dental Equipment
France Dental Equipment Market
Dental Equipment
Dental Simulator Market
Dental Equipment
Refurbished Dental Lab Equipment Market
Dental Equipment
Europe Dental Equipment Market
Dental Equipment
Dental Diagnostic and Surgical Equipment Market
Dental Equipment
Dental 3D Printing Scanner Market
Dental Equipment
Dental Radiology Equipment Market
Dental Equipment
Dental Elevator and Luxator Market
Dental Equipment
Asia-Pacific Dental Equipment Market
Dental Equipment
Dental Dust Collector Market
Dental Equipment
Refurbished Dental Equipment and Maintenance Market
Dental Equipment
Brazil Dental Equipment Market
Dental Equipment
Dental Equipment Market
Dental Equipment
Dental Compressors Market
Dental Equipment
Dental CAM Milling Machine Market