
 South America Cardiac Monitoring Market | 2026-2036
South America Cardiac Monitoring Market Size, Share, and Industry Trends Forecast 2026-2036
South America Cardiac Monitoring Market Analytics
The gap between premium implantable systems and commodity Holter monitors is repositioning procurement strategies across South American health networks. Medtronic PLC leverages its vertically integrated manufacturing footprint to dominate high-margin implantable device segments. Abbott differentiates through specialized arrhythmia management portfolios tailored to regional reimbursement structures.
Cardiac monitoring encompasses electrophysiological signal acquisition, processing, and transmission equipment designed to detect rhythm abnormalities, ischemic events, and hemodynamic instability through surface electrodes, implantable leads, or photoplethysmographic sensors. These systems serve the clinical purpose of enabling timely intervention for acute coronary syndromes and chronic heart failure progression. Implantable devices command the deepest margin pools due to technical complexity and regulatory barriers, while wearable devices represent the fastest-expanding category as outpatient preventive screening protocols proliferate. Wireless monitoring technology anchors cloud-based system deployments in Brazilian cardiology centers seeking telemetry integration.
ANVISA governs device registration and post-market surveillance in Brazil, requiring clinical evidence submissions that extend approval timelines and favor established multinationals with dedicated regulatory affairs teams. Argentina's national pharmaceutical regulator maintains parallel import restrictions that shape distribution channel structures for cardiac monitoring equipment. Stakeholders must weigh ANVISA's evolving software-as-medical-device guidance against the capital requirements of localized cloud infrastructure to capture home care monitoring growth.
Market Dynamics
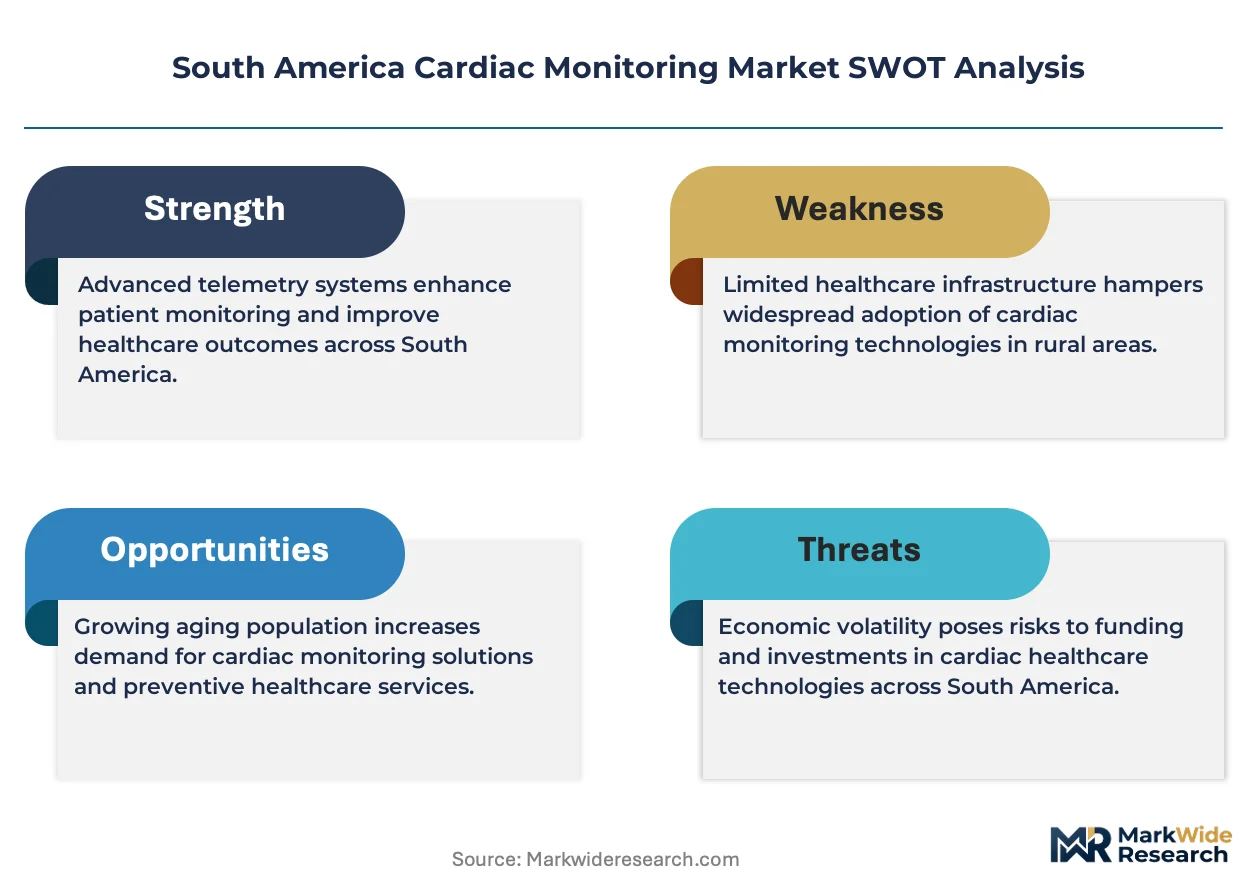
ANVISA's tightened pre-market approval pathways for implantable cardiac devices have elevated compliance costs and consolidated procurement power among established multinationals with dedicated regulatory affairs teams.
Growth Catalysts
- Remote Patient Monitoring Expansion:Hospital systems across Brazil are scaling telemetry programs for post-operative cardiac patients, creating sustained demand for wireless monitoring infrastructure.
- ANVISA Software-as-Medical-Device Guidance:The evolving regulatory framework for cloud-connected cardiac monitors is accelerating vendor investment in localized data infrastructure.
- Wearable ECG Proliferation:Outpatient cardiology centers in Argentina and Colombia are adopting ambulatory monitoring devices for preventive screening protocols.
Market Restraints
- Implantable Device Input Concentration:Specialized cardiac leads and battery chemistries depend on concentrated Asian suppliers, exposing Brazilian manufacturers to freight cost volatility and customs delays.
- ANVISA Clinical Evidence Requirements:Extended approval timelines for novel implantable systems favor incumbents with established dossier libraries and freeze out emerging competitors.
- Commodity Holter Substitution:Low-cost 24-hour ambulatory monitors from unbranded Asian producers are compressing margins in the non-implantable segment.
Strategic Opportunities
- Home Care Monitoring in Colombia:Underpenetrated rural cardiology networks present whitespace for cloud-integrated wearable systems with cellular backhaul.
- Telemedicine Reimbursement Tailwinds:Brazilian private health insurers are expanding coverage for remote cardiac monitoring, enabling subscription revenue models for device vendors.
- AI-ECG Algorithm Convergence:Machine learning diagnostics embedded in patch monitors are opening arrhythmia detection contracts with payers seeking to reduce emergency department utilization.
Industry Challenges
- Electrophysiology Talent Scarcity:Brazilian cardiology centers face shortages of technicians trained in implantable device programming and remote monitoring data interpretation.
- Legacy Hospital IT Integration:Cloud-based cardiac telemetry platforms must interface with fragmented electronic health record systems across Argentine public hospitals, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Cardiac Monitoring Market |
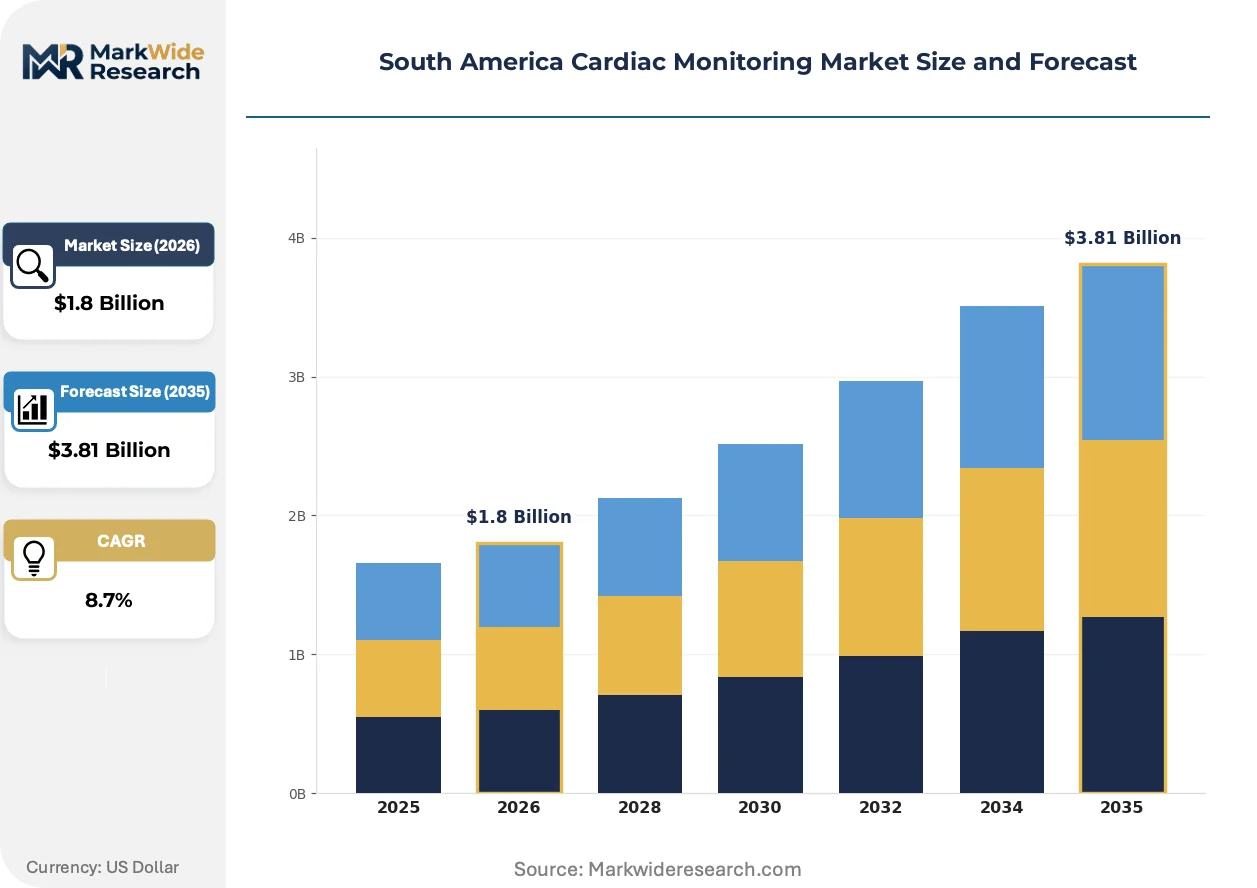
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Holter Monitors, Implantable Devices, ECG Monitors, Wearable Devices End User: Hospitals, Clinics, Home Care, Cardiology Centers Technology: Wireless Monitoring, Cloud-Based Systems, Telemedicine Solutions, Mobile Applications Application: Arrhythmia Management, Heart Failure Monitoring, Post-Operative Care, Preventive Screening |
| Companies Covered | Medtronic PLC, GE Healthcare, Boston Scientific Corporation, Philips Healthcare, Biotronik, Abbott, Stryker Corp, ZOLL Medical Corporation, Koninklijke Philips NV, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Cardiac Monitoring Market Evolving Landscape
Wireless cardiac monitoring architecture is fragmenting into componentized subsystems that separate data acquisition, edge processing, and cloud analytics, enabling vendor specialization and procurement flexibility.
Patch-based ECG monitors are modularizing around disposable adhesive electrodes paired with reusable Bluetooth transmitters, allowing Brazilian outpatient clinics to unbundle hardware costs from consumable recurring revenue. Cardiology networks in São Paulo and Rio de Janeiro are piloting subscription models where device refurbishment and electrode resupply are priced separately from initial capital expenditure.
ANVISA's post-market surveillance requirements for implantable cardiac devices now mandate real-world performance registries, forcing manufacturers to build localized data collection infrastructure or partner with Brazilian academic medical centers. This regulatory pressure is compressing approval timelines for vendors lacking established clinical trial networks within the country.
Hospital procurement committees across Argentina are unbundling cardiac monitoring hardware from long-term service contracts, shifting toward competitive bidding for discrete maintenance and software update packages. This disaggregation is visible most acutely in Buenos Aires province, where public hospital consortia now separately tender for telemetry device supply, cloud hosting, and clinical alert response services.
South America Cardiac Monitoring Market Segmentation
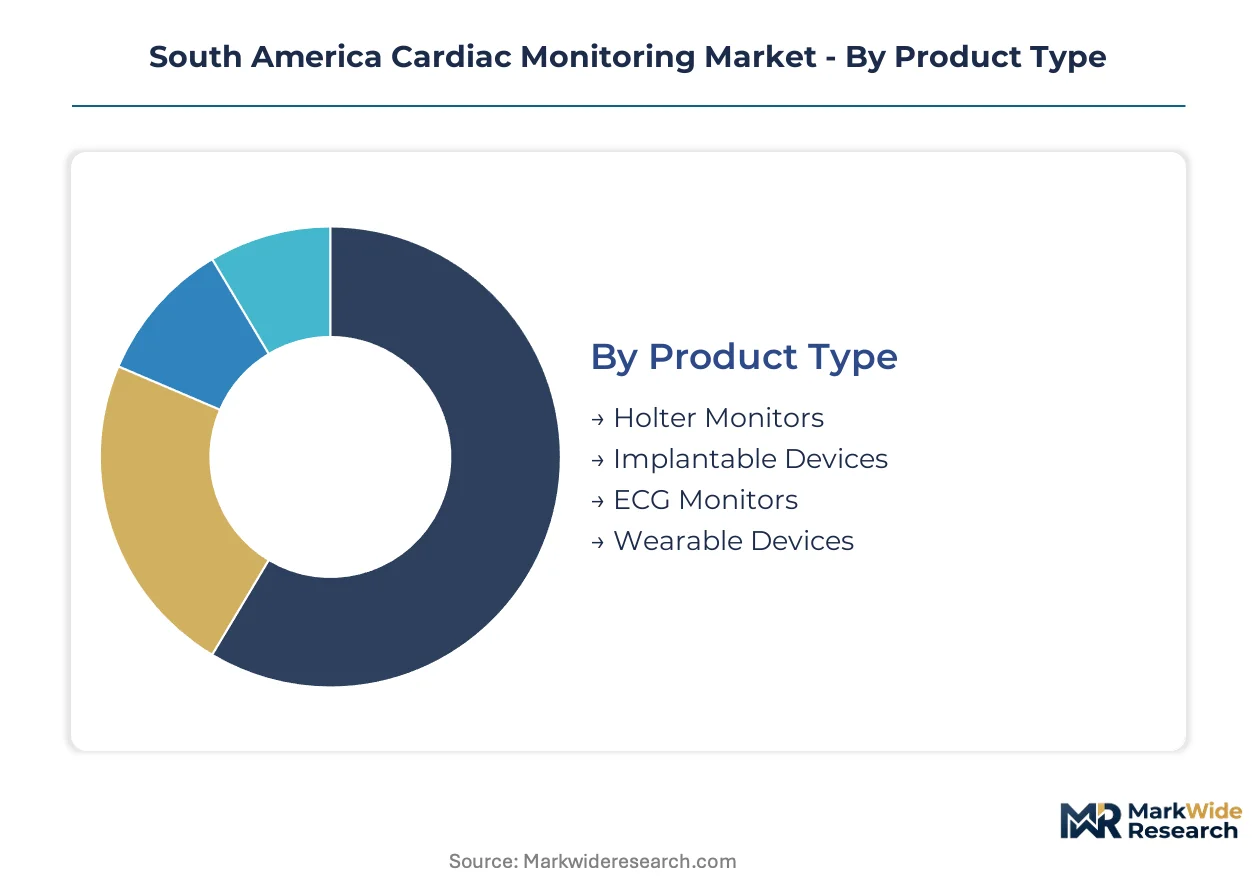
Segmentation in South America's cardiac monitoring market reveals how regulatory burden and reimbursement pathways reshape procurement priorities across product tiers. Understanding these divides enables vendors to align certification investments with margin architecture and channel strategy.
Product Type:
ANVISA's pre-market approval intensity varies sharply across this category, with implantable devices demanding extensive clinical dossiers while wearable monitors navigate lighter software-as-medical-device pathways.
- Holter Monitors:Ambulatory electrocardiography systems capture 24-48 hour rhythm data through surface electrodes and compact recording units. Demand concentrates in Argentine public hospital consortia where procurement committees unbundle hardware from service contracts, compressing margins for vendors lacking localized refurbishment capabilities.
- Implantable Devices:Pacemakers, ICDs, and loop recorders with transvenous or subcutaneous leads. Brazilian cardiology centers in São Paulo and Rio de Janeiro anchor regional demand, though ANVISA's tightened evidence requirements and real-world performance registry mandates favor established multinationals with dedicated regulatory affairs teams and academic medical center partnerships.
- ECG Monitors:Stationary and portable electrocardiography systems for diagnostic and continuous bedside monitoring.
- Wearable Devices:Patch-based and wrist-worn sensors with photoplethysmographic or single-lead ECG acquisition.
Leading the category by volume: Holter Monitors. Growing fastest: Wearable Devices.
End User:
Procurement sophistication and reimbursement access create three distinct cost tiers across this category, from capital-intensive hospital tenders to subscription-based home care models.
- Hospitals:Tertiary care facilities with catheterization laboratories, electrophysiology suites, and post-surgical telemetry wards. Brazilian health networks are expanding remote patient monitoring programs for post-operative cardiac patients, driving sustained demand for wireless infrastructure and cloud-integrated telemetry platforms.
- Cardiology Centers:Specialized outpatient facilities focusing on arrhythmia diagnosis and chronic heart failure management. Buenos Aires province consortia now separately tender for device supply, cloud hosting, and clinical alert response services, fragmenting vendor relationships and compressing bundled pricing power.
- Clinics:General practice and multi-specialty facilities with basic cardiac diagnostic capabilities.
- Home Care:Patient-domiciled monitoring with cellular backhaul and family caregiver interfaces.
Capturing the deepest margin pools: Cardiology Centers. Expanding most quickly: Home Care.
Technology:
Application maturity and IT integration complexity separate legacy deployments from next-generation architectures across this category.
- Wireless Monitoring:Bluetooth, WiFi, and proprietary RF protocols enabling untethered patient mobility within clinical environments. Colombian rural networks present whitespace for cellular-backhaul systems as underpenetrated cardiology infrastructure drives demand for telemetry without fixed-line dependency.
- Cloud-Based Systems:Centralized data aggregation, algorithmic analysis, and multi-site accessibility platforms. Argentine public hospitals face extended deployment timelines due to fragmented electronic health record systems requiring custom interface development.
- Telemedicine Solutions:Integrated video consultation, remote device programming, and clinical decision support workflows.
- Mobile Applications:Patient-facing symptom logging, medication adherence, and alert notification interfaces.
Dominating current procurement volumes: Wireless Monitoring. Gaining share fastest: Cloud-Based Systems.
Application:
Reimbursement coverage depth and clinical outcome measurability determine addressable market size and payer contract viability across this category.
- Arrhythmia Management:Atrial fibrillation detection, ventricular tachycardia intervention, and stroke prevention protocols. Brazilian private health insurers are expanding coverage for remote cardiac monitoring, enabling subscription revenue models where AI-embedded patch monitors secure payer contracts through emergency department utilization reduction guarantees.
- Preventive Screening:Asymptomatic population surveillance for subclinical atrial fibrillation and structural heart disease. Outpatient cardiology centers in Argentina and Colombia are adopting ambulatory monitoring devices, though electrophysiology technician scarcity limits program scale in Brazilian centers.
- Heart Failure Monitoring:Hemodynamic trend analysis, fluid status assessment, and decompensation early warning systems.
- Post-Operative Care:Surgical recovery surveillance, complication detection, and rehabilitation progression tracking.
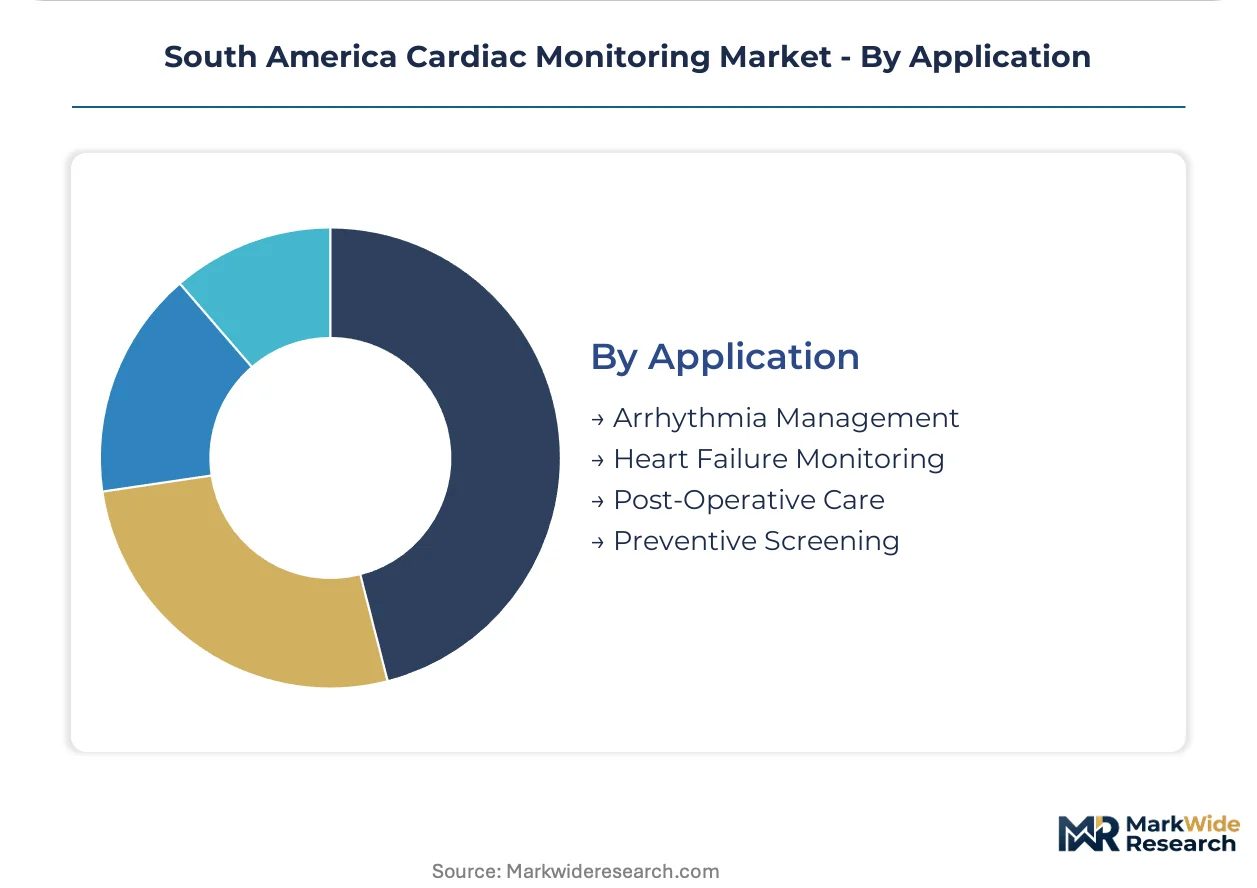
Commanding the largest reimbursement allocations: Arrhythmia Management. Showing the steepest expansion trajectory: Preventive Screening.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo anchors cardiac monitoring deployment across South America, with its tertiary hospital networks driving demand for implantable devices and cloud-integrated telemetry platforms that serve as reference implementations for neighboring markets.
Brazil
Hospital systems in São Paulo and Rio de Janeiro are expanding remote patient monitoring programs for post-operative cardiac patients, creating sustained infrastructure demand. ANVISA governs device registration with tightened pre-market approval pathways that elevate compliance costs and favor established multinationals. Brazilian cardiology centers in these metros anchor regional demand for pacemakers, ICDs, and loop recorders.
Argentina
Outpatient cardiology centers in Buenos Aires province are adopting ambulatory monitoring devices for preventive screening protocols at accelerating rates. The national pharmaceutical regulator maintains parallel import restrictions that shape distribution channel structures for cardiac monitoring equipment. Public hospital consortia in Buenos Aires now unbundle hardware procurement from long-term service contracts, fragmenting vendor relationships.
Colombia
Rural cardiology networks present whitespace for cloud-integrated wearable systems with cellular backhaul as infrastructure penetration remains limited. The country's national health regulator shapes market access requirements for imported cardiac devices. Bogotá-based cardiology centers are piloting subscription models where device refurbishment and electrode resupply are priced separately from initial capital expenditure.
Chile
Private health insurers in Santiago are expanding coverage frameworks for remote cardiac monitoring, enabling subscription revenue models for device vendors. The national pharmaceutical regulator maintains clinical evidence requirements for novel implantable systems. Santiago's hospital networks are deploying wireless telemetry platforms that interface with fragmented electronic health record systems, extending deployment timelines.
South America Cardiac Monitoring Market Competitive Landscape
Premium-margin players sit above commodity-margin players across the implantable-wearable divide, with technical complexity and regulatory barriers protecting deeper margin pools in transvenous and subcutaneous lead systems. The vendor base stratifies into three tiers: established multinationals with dedicated regulatory affairs teams, mid-scale specialists with regional reimbursement expertise, and unbranded Asian producers competing on Holter monitor cost. Dominant competitive moves include backward integration into specialized cardiac leads and battery chemistries, plus partnerships with Brazilian academic medical centers to satisfy ANVISA's real-world performance registry mandates.
Among the established multinational tier, Medtronic PLC and Abbott occupy positions exemplifying divergent strategic archetypes. Medtronic leverages its vertically integrated manufacturing footprint to dominate high-margin implantable device segments. Abbott differentiates through specialized arrhythmia management portfolios tailored to regional reimbursement structures. GE Healthcare and Philips Healthcare represent the diversified medical technology conglomerate archetype, with device offerings that span diagnostic imaging through cloud-based telemetry integration.
| Leading Market Players |
|---|
| Medtronic PLC |
| GE Healthcare |
| Boston Scientific Corporation |
| Philips Healthcare |
| Biotronik |
| Abbott |
| Stryker Corp |
| ZOLL Medical Corporation |
| Koninklijke Philips NV |
| Others |
Value Network & Pricing Analysis
Specialized cardiac leads and lithium-iodine battery chemistries flow from concentrated Asian suppliers through Brazilian distributors to ANVISA-registered manufacturers, with freight cost volatility and customs delays propagating unevenly across implantable device premium tiers versus commoditized Holter monitor economy tiers.
Pricing Analysis
Outcome-based contracts tied to emergency department utilization reduction anchor value-based pricing for AI-embedded patch monitors in Brazilian private insurance networks. Three-tier pricing structure across premium, standard, and economy levels separates implantable systems with real-world performance registries from unbranded Asian Holter monitors and mid-tier wearable ECG devices. Pricing pressure stems from unbundled procurement in Buenos Aires public hospital consortia that separately tender hardware, cloud hosting, and clinical alert services. Outpatient cardiology centers in Argentina and Colombia exhibit highest price sensitivity due to fragmented reimbursement, while São Paulo tertiary hospitals maintain lowest sensitivity given bundled capital budgets and established multilateral vendor relationships.
Supply Chain Analysis
Cardiac lead conductors and battery cell chemistries rest on Japanese, South Korean, and Chinese specialty component producers. Brazilian manufacturers draw from these upstream sources for implantable device subassemblies, while surface electrodes and adhesive patches feed from domestic converting operations. Single-source vulnerability concentrates in transvenous lead insulation polymers subject to ANVISA import documentation delays. Distribution runs through authorized dealer networks in São Paulo and Rio de Janeiro for implantable systems, with direct-to-clinic e-procurement platforms gaining share for wearable and Holter categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Backward integration into specialized cardiac leads and captive battery supply represents the dominant vertical-integration race, with ANVISA's real-world performance registry mandates forcing downstream control over clinical data infrastructure.
For Market Incumbents: Acquire Brazilian academic medical center partnerships to satisfy ANVISA's localized data collection mandates for implantable device registries. Consolidate refurbishment capabilities for Holter monitors to defend margin position against unbranded Asian commodity substitution in Argentine public procurement. Channel control through exclusive service contracts remains critical as Buenos Aires consortia fragment vendor relationships via unbundled tendering. For New Entrants and Emerging Players: Direct-to-clinic digital procurement platforms offer the lowest-friction route for wearable ECG patch distribution in Colombian rural networks lacking fixed-line telemetry infrastructure. Target home care monitoring in underpenetrated Andean cardiology zones where cellular backhaul enables cloud-integrated subscription models without legacy hospital IT integration burdens. Partner with Brazilian private insurers expanding telemedicine reimbursement coverage to secure arrhythmia detection contracts. For Investors and Strategic Acquirers: ANVISA software-as-medical-device guidance finalization is the leading indicator that cloud infrastructure localization requirements will consolidate vendor viability around established regulatory affairs teams. The five-to-ten-year viability window favors acquisition targets with vertically integrated manufacturing footprints and dedicated Brazilian compliance infrastructure. Watch for electrophysiology technician training program scale as the signal that preventive screening protocol penetration is reaching inflection.| Strategic Initiative | Industry Significance |
|---|---|
| ANVISA Real-World Performance Registry Compliance | Localized data collection infrastructure secures implantable device approval timelines against emerging competitors. |
| Backward Integration into Cardiac Lead Manufacturing | In-house conductor production insulates Brazilian assemblers from Asian supplier freight volatility and customs delays. |
| Hospital System Partnership for Telemetry Integration | São Paulo tertiary network deployments create reference implementations that propagate procurement standards regionally. |
| Software-as-Medical-Device Cloud Localization | Brazilian data residency compliance opens subscription revenue models under evolving ANVISA guidance. |
| Electrophysiology Technician Training Program Scale-Up | Workforce development unlocks preventive screening protocol expansion in Brazilian outpatient cardiology centers. |
Research Methodology
Independent corroboration across electrophysiologists at São Paulo tertiary centers, biomedical engineers at Argentine public hospital consortia, and GPO contracts managers at Colombian health networks underwrites the qualitative findings. Secondary validation drew from ANVISA device registration databases, Brazilian hospital procurement disclosures, and regional trade flow records for cardiac monitoring equipment. Bottom-up demand modeling across implantable, wearable, and Holter product tiers triangulated against top-down macroeconomic healthcare expenditure projections.
Comparable-period anchoring to historical ANVISA approval timelines and reimbursement expansion phases shaped the forecast window construction across the analysis window. Segmentation dimensions modeled include product type, end-user facility tier, technology architecture, and application indication, with regional regulatory cluster variations for Brazil, Argentina, Colombia, and Chile. CAGRs derived from installed base growth rates, replacement cycle compression, and subscription revenue model penetration curves for cloud-integrated systems.
The model holds under stable ANVISA regulatory interpretation and sustained Brazilian private insurance telemedicine reimbursement expansion; deviation in trade policy affecting Asian component imports or electrophysiology workforce training program scale would shift demand realization timelines. A small set of named triggers—ANVISA software guidance finalization, Colombian rural cellular infrastructure buildout, and Argentine public procurement unbundling depth—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Blood Pressure Monitors Market
Patient Monitoring
Blood Temperature Indicator Market
Patient Monitoring
Oman Blood Glucose Monitoring Market
Patient Monitoring
Patient Temperature Management Systems Market
Patient Monitoring
Online Patient Observation Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Middle East and Africa Body Temperature Monitoring Market
Patient Monitoring
Medical Telemetry Market
Patient Monitoring
Saudi Arabia Patient Monitoring Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
Critical Care Patient Monitoring Products Market
Patient Monitoring
Remote Patient Monitoring Software and Services Market
Patient Monitoring
United States Cardiac Holter Monitor Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
North America Patient Temperature Management Market