
 ECG Monitoring System Market | 2026-2036
ECG Monitoring System Market Size, Share, and Industry Trends Forecast 2026-2036
ECG Monitoring System Market Analysis
A shift from single-source component procurement to multi-source supplier arrangements is rebalancing supply chain risk across the ECG monitoring system industry. GE Healthcare leverages in-house semiconductor sourcing for critical signal-processing chips. Philips Healthcare sustains broad geographic manufacturing footprints across multiple continents. Medtronic anchors its competitive stance through deep vertical integration in cardiac rhythm management.
An ECG monitoring system captures, amplifies, and records the heart's electrical activity through electrodes placed on the skin, typically sampling at 250–1000 Hz with 12-lead configurations providing diagnostic-grade spatial resolution. These systems serve clinical diagnosis, arrhythmia detection, and longitudinal cardiac surveillance across acute and ambulatory settings. Portable and wireless product types are capturing expanding share as home-based and mobile health models mature, while Holter monitors retain stable demand for extended ambulatory arrhythmia investigation. Cloud-based and AI-driven technology segments are attracting disproportionate R&D investment as automated rhythm classification and predictive analytics reshape clinical workflow economics.
The FDA enforces premarket notification and quality system regulation for ECG devices, while CE marking under the EU MDR mandates clinical evidence and post-market surveillance for European market access. Japan's PMDA maintains stringent electrical safety and software lifecycle requirements that shape product development priorities for Asia-Pacific entry. Stakeholders must weigh regulatory pathway complexity against reimbursement velocity when prioritizing geographic expansion and technology platform bets.
Market Dynamics
AI-driven rhythm classification is compressing diagnostic timelines and forcing hardware manufacturers to embed software capabilities or cede margin to algorithm specialists.
Growth Catalysts
- Ambulatory reimbursement clarity:Germany's Diagnosis-Related Group system and US Medicare remote patient monitoring codes now cover extended Holter and patch monitor deployments, accelerating hospital procurement cycles.
- FDA breakthrough device designation:Expedited review pathways for AI-enabled ECG analytics are shortening time-to-market for predictive arrhythmia platforms, attracting venture funding into cardiac digital health.
- Holter-to-patch substitution:Extended-wear adhesive patch monitors are displacing traditional 24-48 hour Holter systems in arrhythmia screening protocols, creating replacement demand across cardiology practices.
Market Restraints
- Semiconductor supply concentration:Analog front-end chips and low-noise amplifiers for biopotential acquisition concentrate among Taiwan and South Korea foundries, exposing ECG device makers to foundry allocation volatility.
- EU MDR clinical evidence requirements:Post-market surveillance obligations and notified body capacity constraints are extending CE marking timelines for software-as-medical-device ECG platforms.
- Signal artifact vulnerability:Motion noise and dry electrode impedance instability in wearable form factors limit diagnostic equivalence to 12-lead hospital systems, constraining clinical acceptance for critical care applications.
Strategic Opportunities
- Home-based heart failure monitoring:Integration of ECG with pulmonary artery pressure sensors and weight scales creates longitudinal cardiac decompensation alerts, opening reimbursement pathways under chronic care management programs.
- India's PLI scheme for medical electronics:Production-linked incentives for domestic manufacturing of diagnostic devices are attracting component assembly investments to serve price-sensitive South Asian markets.
- 5G-enabled real-time telemetry:Ultra-reliable low-latency communication protocols are enabling ambulance-to-hospital ECG streaming, creating pre-hospital intervention revenue models for emergency medical services.
Industry Challenges
- Algorithm validation workforce scarcity:Clinical data scientists capable of training FDA-compliant arrhythmia classifiers command premium compensation, constraining AI product development velocity at mid-tier device firms.
- Legacy EMR integration complexity:Proprietary data formats from dominant hospital information systems require costly interface engine development, delaying cloud-based ECG platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | ECG Monitoring System Market |
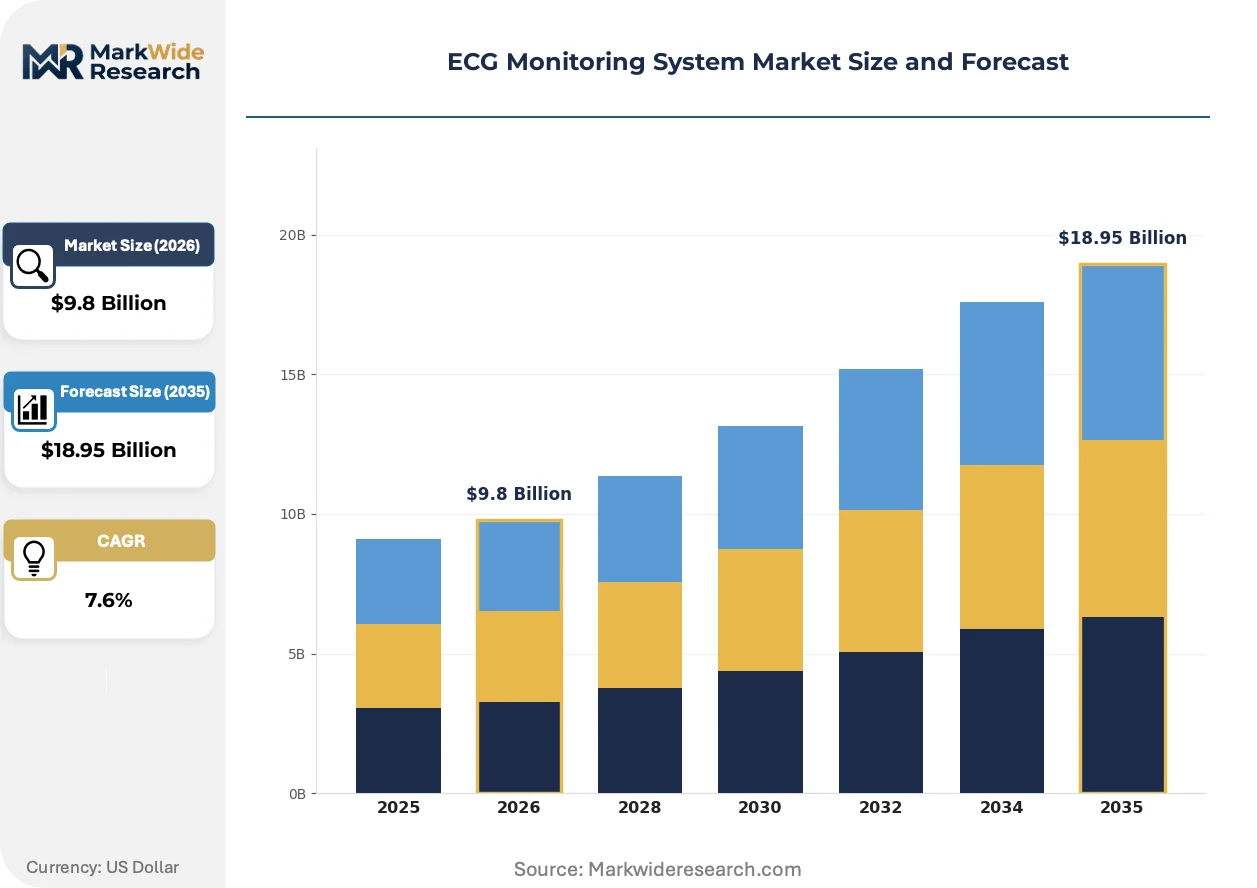
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $18.95 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Wireless, Holter, Wearable Technology: Analogue, Digital, Cloud-Based, AI-Driven End User: Hospitals, Clinics, Home Care, Remote Monitoring Application: Cardiology, Telemedicine, Emergency Care, Fitness |
| Companies Covered | GE Healthcare, Philips Healthcare, Nihon Kohden, Schiller AG, Welch Allyn, Mindray Medical, Medtronic, iRhythm Technologies, Fukuda Denshi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
ECG Monitoring System Market Emerging Trajectories
Deep learning architectures trained on million-scale ECG databases are compressing the diagnostic workflow from specialist interpretation to point-of-care decision support.
Convolutional neural networks with attention mechanisms are automating multi-label arrhythmia detection from single-lead signals. Community health centers and retail clinic operators are deploying these tools to extend cardiology reach into underserved counties. The technology is automating preliminary read workflows and reallocating electrophysiologist time toward complex ablation planning.
The EU MDR's requirement for post-market clinical follow-up is forcing ECG software vendors to maintain active registry participation. Manufacturers must now budget for continuous safety documentation rather than one-time premarket submissions. Wearable ECG patch developers with limited clinical affairs infrastructure face particular compliance cost pressure.
Hospital procurement committees are unbundling device acquisition from long-term service contracts. Cardiology departments now source ECG hardware through capital equipment budgets while purchasing cloud analytics subscriptions separately. This bifurcation is most visible in US integrated delivery networks negotiating multi-year enterprise software agreements independent of device vendor relationships.
ECG Monitoring System Market Segmentation
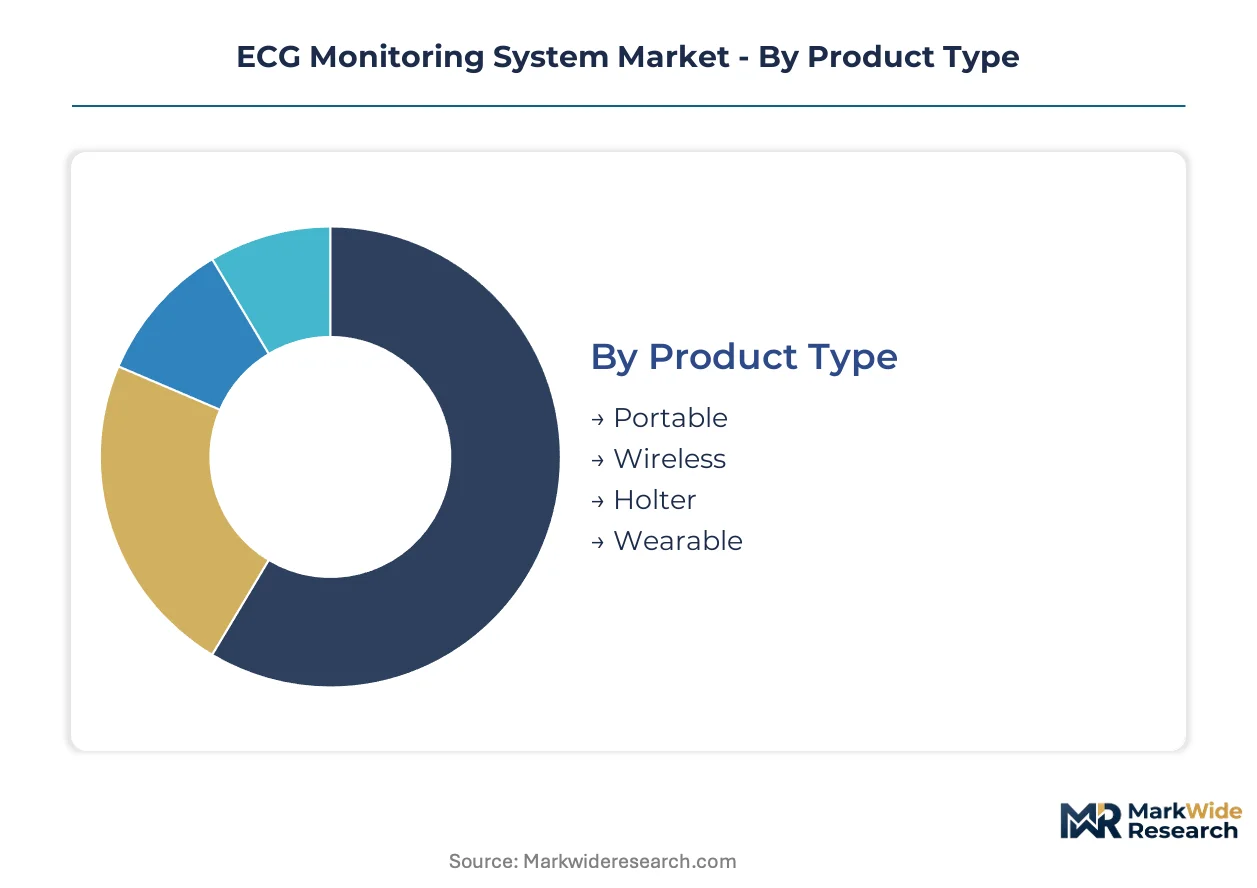
ECG monitoring system segmentation reveals divergent integration architectures. Standalone diagnostic platforms command premium procurement cycles while embedded sensor arrays penetrate consumer wellness ecosystems. Technology choices here determine regulatory pathway complexity and reimbursement velocity.
Product Type:
Portable and wireless systems embed directly into clinical workflows, while Holter and wearable formats operate as patient-attached peripherals with varying degrees of clinician oversight.
- Portable:Battery-powered units with integrated displays and thermal printers serve point-of-care diagnostics in emergency departments and rural clinics. Demand concentrates in United States community health centers where CMS reimbursement codes favor billable diagnostic encounters over capital equipment depreciation.
- Wireless:Bluetooth and Wi-Fi enabled transmitters stream real-time ECG data to centralized monitoring stations, eliminating tethered bedside configurations. German hospital systems are expanding wireless deployments across cardiology wards to reduce nurse alarm fatigue and enable centralized telemetry stations.
- Holter:Extended-wear recorders with 24- to 48-hour memory buffers remain the standard for ambulatory arrhythmia investigation.
- Wearable:Consumer-grade and medical-grade adhesive patches with multi-day wear capability are displacing traditional Holter monitors in screening protocols.
Holter monitors lead volumes today; wearable formats are gaining share fastest.
Technology:
Signal processing depth separates cost tiers, with cloud and AI platforms commanding subscription margins against hardware-centric analogue implementations.
- Analogue:Discrete component amplifiers and analog-to-digital converters with hardware-defined filtering dominate legacy installed bases in price-sensitive procurement environments.
- Digital:Software-defined signal processing with programmable digital filters enables firmware-upgradable feature expansion without hardware replacement.
- Cloud-Based:Edge-to-cloud architectures store raw ECG waveforms in HIPAA-compliant data centers while enabling multi-site specialist access. United States integrated delivery networks are consolidating cloud analytics procurement into enterprise software agreements separate from device vendor relationships.
- AI-Driven:Deep learning classifiers trained on million-scale arrhythmia databases automate preliminary read workflows, reallocating electrophysiologist time toward complex intervention planning. FDA breakthrough device designations for AI-enabled platforms are shortening time-to-market and attracting venture funding into cardiac digital health.
Digital platforms lead volumes today; AI-driven systems are expanding most quickly.
End User:
Clinical acuity requirements shape procurement authority, with hospital cardiology departments controlling capital budgets while home care relies on durable medical equipment channels.
- Hospitals:Acute care settings demand 12-lead diagnostic-grade systems with EMR integration and centralized telemetry infrastructure.
- Clinics:Outpatient cardiology practices prioritize rapid-turnaround interpretation workflows and patient throughput optimization.
- Home Care:Post-discharge monitoring for heart failure patients integrates ECG with weight scales and symptom diaries under chronic care management reimbursement. United States Medicare remote patient monitoring codes now cover extended home-based ECG deployments.
- Remote Monitoring:Third-party monitoring centers provide 24/7 arrhythmia surveillance for implantable and wearable devices, operating on per-patient subscription models.
Hospitals lead volumes today; home care is climbing the fastest.
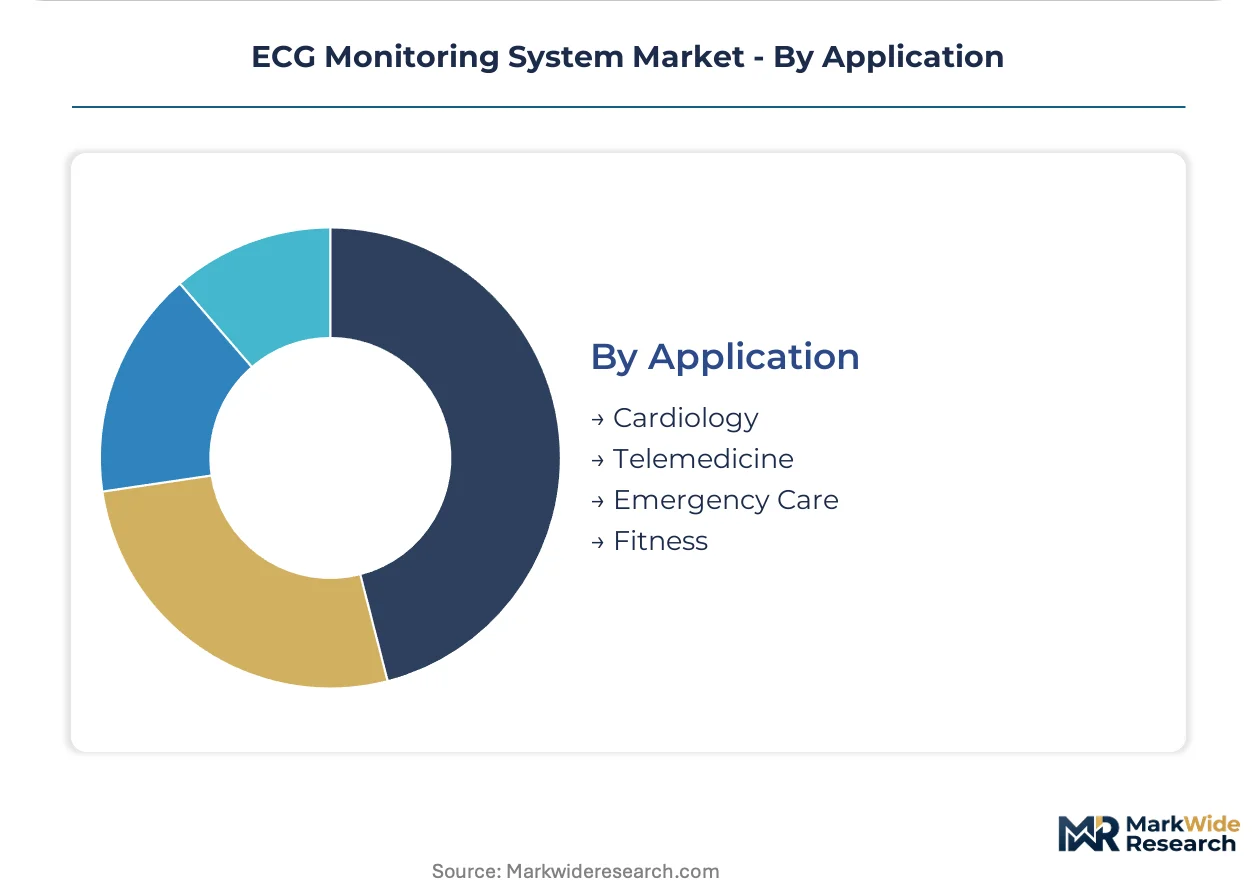
Application:
Use case specificity determines regulatory classification and reimbursement pathway, with diagnostic applications requiring premarket notification while wellness applications face lighter oversight.
- Cardiology:Diagnostic-grade 12-lead systems for arrhythmia detection, ischemia assessment, and structural abnormality identification remain the clinical gold standard. Demand concentrates in Japan where PMDA electrical safety requirements and aging demographics support premium device adoption.
- Telemedicine:Store-and-forward and real-time consultation platforms extend specialist reach into underserved geographies. Community health centers in United States rural counties are deploying single-lead ECG tools to reduce cardiology appointment backlogs.
- Emergency Care:Pre-hospital 12-lead acquisition in ambulances enables catheterization lab activation before hospital arrival. 5G-enabled real-time telemetry is creating ambulance-to-hospital streaming revenue models for emergency medical services.
- Fitness:Consumer wearables with single-lead ECG for atrial fibrillation screening operate under wellness rather than diagnostic regulatory frameworks.
Cardiology leads volumes today; telemedicine is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's medical device manufacturing corridor anchors ECG monitoring system production and procurement intensity, with hospital systems and component suppliers clustering across Bavaria and Baden-Württemberg.
United States
Medicare remote patient monitoring reimbursement codes and FDA breakthrough device pathways accelerate AI-enabled ECG platform adoption. The 21st Century Cures Act mandates interoperability standards that reshape EMR integration requirements for cloud-based systems. Minneapolis and Boston medical device clusters concentrate wearable ECG development and electrophysiology algorithm engineering.
Germany
Diagnosis-Related Group reimbursement clarity and aging demographics drive ambulatory ECG procurement in cardiology practices. EU MDR post-market surveillance obligations extend CE marking timelines for software-as-medical-device platforms. Erlangen and Freiburg host concentrated diagnostic imaging and cardiac monitoring R&D operations.
Japan
PMDA electrical safety and software lifecycle requirements filter market entry toward premium diagnostic-grade systems. METI industrial policy supports domestic production of medical electronics for aging population care. Tokyo and Osaka metropolitan areas concentrate hospital procurement authority and specialist electrophysiologist networks.
India
Production-linked incentive schemes for medical electronics attract component assembly investments targeting price-sensitive South Asian demand. CDSCO medical device rules tighten registration requirements for software-enabled diagnostic equipment. Bengaluru and Hyderabad medical technology clusters expand contract manufacturing for portable ECG hardware.
South Korea
MFDS digital health approval pathways and national health insurance reimbursement for remote cardiac monitoring expand home-based ECG deployment. Government smart hospital initiatives mandate wireless telemetry infrastructure in tertiary care centers. Seoul Capital Area concentrates semiconductor foundry capacity for analog front-end biopotential acquisition chips.
ECG Monitoring System Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue AI-enabled analytics and extended-wear form factors. The vendor base stratifies across three tiers: diversified conglomerates with captive healthcare divisions, pure-play cardiac monitoring specialists, and algorithm-centric software vendors. Competitive positioning depends on regulatory pathway velocity and cloud architecture maturity. Consolidation pressure intensifies as hospital procurement committees unbundle hardware acquisition from analytics subscriptions.
Within the diversified healthcare technology tier, GE Healthcare and Philips Healthcare represent integrated system vendors with broad geographic manufacturing footprints. Medtronic exemplifies deep backward integration in cardiac rhythm management. Among algorithm-focused specialists, iRhythm Technologies occupies a position exemplifying the wearable patch monitor archetype displacing traditional Holter systems.
| Leading Market Players |
|---|
| GE Healthcare |
| Philips Healthcare |
| Nihon Kohden |
| Schiller AG |
| Welch Allyn |
| Mindray Medical |
| Medtronic |
| iRhythm Technologies |
| Fukuda Denshi |
| Others |
Supply Flow & Price Mechanics
Private-equity-rolled-up diagnostic device specialists anchor mid-tier pricing discipline through captive semiconductor sourcing and consolidated GPO contract negotiations, while their supply chain footprints concentrate analog front-end procurement in Taiwan and South Korea foundries. This ownership pattern compresses margin buffers when foundry allocation volatility spikes, forcing hardware vendors toward subscription-based analytics bundling to defend profitability.
Pricing Analysis
Input-cost pass-through from analog front-end chips and low-noise amplifiers concentrates pricing pressure on portable and wireless hardware tiers, where three-tier pricing structure across premium diagnostic-grade, standard clinical, and economy remote-monitoring levels stratifies by FDA breakthrough designation status and EMR integration depth. Price differentiation hinges on AI-enabled rhythm classification capabilities and cloud analytics subscription bundling. Pricing pressure stems from semiconductor foundry allocation constraints and hospital procurement committee unbundling of device acquisition from service contracts. Community health centers exhibit highest price sensitivity due to CMS reimbursement code dependency, while integrated delivery networks prioritize total cost of ownership over unit pricing.
Supply Chain Analysis
Analog front-end biopotential acquisition chips rest on Taiwan and South Korea foundry capacity, with discrete component amplifiers and dry electrode materials drawing from Japanese specialty chemical producers and Chinese contract manufacturers. Raw material dependencies span silicon wafers, biocompatible adhesives, and lithium-polymer cells for extended-wear patches. Single-source vulnerability concentrates in Taiwan semiconductor fabrication, where foundry allocation volatility exposes ECG device makers to production delays. Distribution runs through hospital procurement committees, GPO contracts, and durable medical equipment channels serving home care segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ECG monitoring system market reads as a late-cycle quality story, with demand shifting toward AI-enabled diagnostic-grade platforms that command premium reimbursement under FDA breakthrough pathways and Medicare remote patient monitoring codes.
For Market Incumbents: Lock in backward integration into analog front-end semiconductor sourcing or captive foundry relationships to insulate margins from Taiwan allocation volatility. Deepen cloud analytics subscription penetration across integrated delivery networks before hospital procurement committees complete unbundling of hardware from software contracts. Defend against algorithm-centric software vendors by embedding FDA-compliant arrhythmia classifiers directly into firmware-upgradable digital signal processing platforms. For New Entrants and Emerging Players: Remote monitoring centers offer the most penetrable channel, with third-party arrhythmia surveillance services operating on per-patient subscription models underserved by hardware-centric incumbents. Target India's PLI scheme for medical electronics assembly to serve price-sensitive South Asian demand with localized production. Pursue 5G-enabled ambulance-to-hospital telemetry partnerships with emergency medical services as a go-to-market wedge, bypassing entrenched hospital capital equipment committees. For Investors and Strategic Acquirers: Valuations sit cheapest among wearable patch monitor developers with limited clinical affairs infrastructure facing EU MDR post-market surveillance cost pressure. Long-term viability favors algorithm specialists with FDA breakthrough designations and million-scale ECG training databases, positioned for predictive analytics platform consolidation. Watch for foundry allocation normalization in Taiwan as the inflection signal triggering hardware margin recovery and M&A activity acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses time-to-market for AI-enabled arrhythmia platforms attracting venture funding. |
| CE Marking Under EU MDR | Post-market surveillance obligations extend timelines for software-as-medical-device ECG analytics vendors. |
| Hospital System Partnership | Enterprise software agreements with integrated delivery networks separate cloud analytics from hardware procurement. |
| Software Companion Development | Deep learning classifiers automate preliminary reads, reallocating electrophysiologist time toward complex interventions. |
| Reimbursement Strategy | Medicare remote patient monitoring codes and Germany's Diagnosis-Related Group system accelerate procurement cycles. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with electrophysiologists, hospital purchasing committee members, biomedical engineers, and GPO contracts managers alongside secondary validation through FDA 510(k) filings, CE marking databases under EU MDR, CMS Medicare reimbursement code disclosures, and hospital procurement records. Bottom-up demand modeling across product type, technology, end user, and application segments triangulated against top-down macroeconomic indicators and healthcare expenditure forecasts.
Segment-weighting approaches distributed value and volume estimates across portable, wireless, Holter, and wearable product types; analogue, digital, cloud-based, and AI-driven technology tiers; and hospital, clinic, home care, and remote monitoring end user categories. CAGRs derived from regression analysis of historical adoption curves, reimbursement velocity, and regulatory pathway timelines incorporated AI algorithm training data scale and cloud infrastructure maturity as industry-specific forecast inputs across the projection horizon.
Revisions become necessary when FDA breakthrough designation volume thresholds shift, Taiwan foundry allocation constraints deepen, or EU MDR notified body capacity constraints extend CE marking timelines beyond baseline assumptions. A small set of named triggers—including semiconductor supply normalization, AI diagnostic equivalence validation, and hospital procurement unbundling completion—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Middle East and Africa Remote Patient Monitoring Market
Patient Monitoring
Compartment Syndrome Monitoring Devices Market
Patient Monitoring
MR Vital Sign Monitors Market
Patient Monitoring
Digital Patient Monitoring Devices Market
Patient Monitoring
South America Cardiac Monitoring Market
Patient Monitoring
Italy Patient Monitoring Market
Patient Monitoring
Global Non-Invasive Monitoring Device Market
Patient Monitoring
Artificial Intelligence (AI) in Remote Patient Monitoring Market
Patient Monitoring
Asthma Monitoring Devices Market
Patient Monitoring
RFID Blood Monitoring System Market
Patient Monitoring
North America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Patient Monitoring Pods Market
Patient Monitoring
South America Remote Patient Monitoring Systems Market
Patient Monitoring
Germany Blood Glucose Monitoring Market
Patient Monitoring
Middle East and Africa Fetal and Neonatal Monitoring Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market