
 United States Automotive Connectors Market | 2026-2036
United States Automotive Connectors Market Size, Share, and Industry Trends Forecast 2026-2036
United States Automotive Connectors Market Intelligence
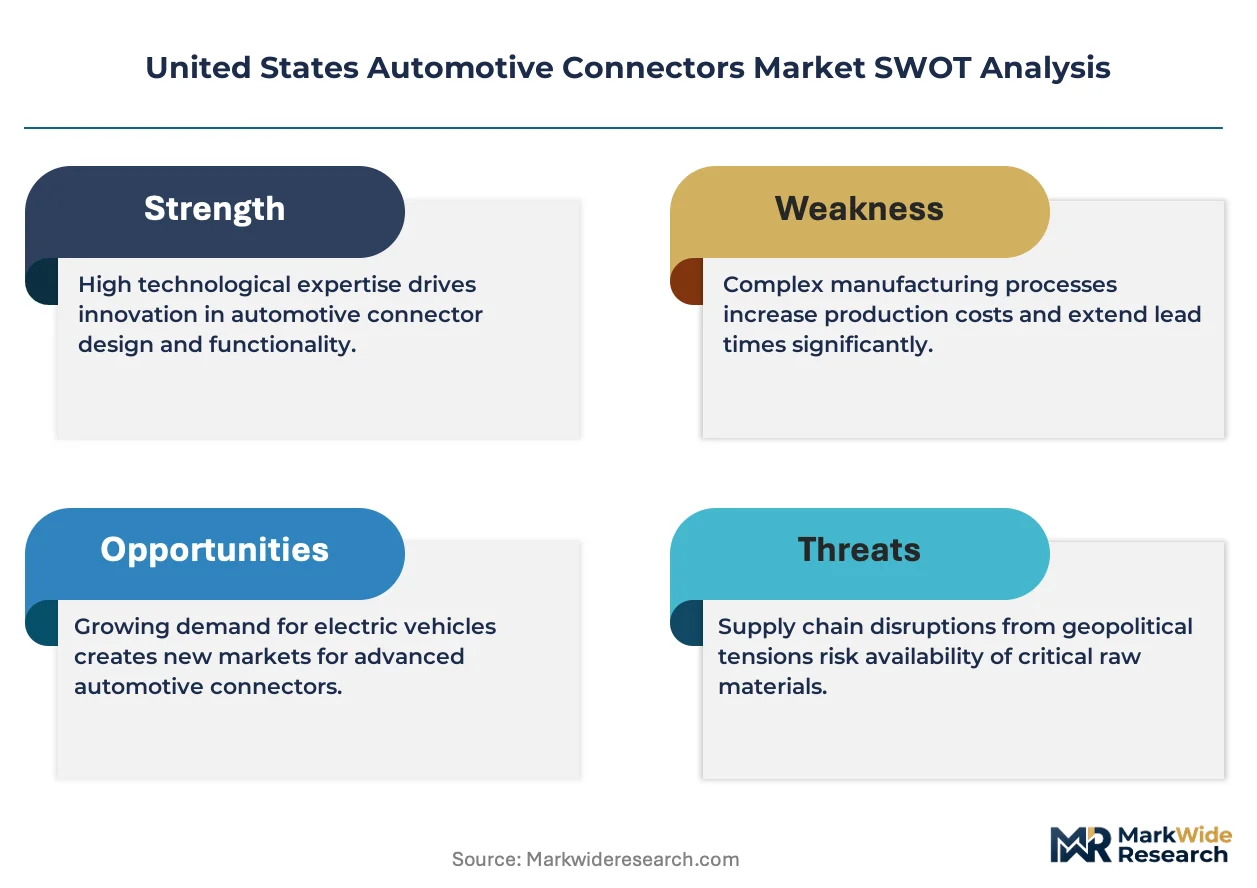
Software-defined vehicle subscription services is pivoting connector vendors toward data-rate-intensive architectures that support over-the-air updates. TE Connectivity leverages its sensor-to-cloud portfolio to anchor high-speed ethernet connector lines for autonomous driving platforms. Amphenol Corporation sustains defense-grade reliability standards that transfer into commercial EV connector specifications.
Automotive connectors are electromechanical interface devices engineered to transmit electrical signals and power across vehicle subsystems, typically rated for temperatures spanning negative forty to one hundred twenty five degrees Celsius and vibration resistance exceeding ten G RMS. Their primary commercial purpose is ensuring signal integrity across powertrain, infotainment, and advanced driver-assistance networks under harsh operating conditions. High voltage technology leads segment value as electrified powertrains demand interconnection systems rated above eight hundred volts, while fiber optic connectors represent the fastest-growing category due to bandwidth requirements for lidar and camera fusion. OEM end users command the largest volume share, though aftermarket channels are gaining margin traction as vehicle electronics complexity extends serviceable lifecycles.
NHTSA crashworthiness protocols, EPA greenhouse gas standards, and ISO two six two six two functional safety requirements collectively mandate connector designs with redundant locking mechanisms and sealed environmental protection. These frameworks shape procurement specifications by embedding compliance costs that favor suppliers with pre-certified testing laboratories. Stakeholders must monitor how FMVSS updates for autonomous vehicle fault tolerance will redefine minimum connector cycle-life thresholds before the next regulatory comment period closes.
Market Dynamics
Electrification mandates from the EPA and California Air Resources Board are forcing connector architectures to accommodate 800V+ powertrains while maintaining signal integrity for autonomous driving sensor fusion networks.
Growth Catalysts
- EPA Fleet Emissions Standards:Corporate Average Fuel Economy targets compel OEMs to expand electric vehicle production, multiplying high-voltage connector demand across powertrain and charging subsystems.
- Sensor Fusion Architectures:Lidar and camera integration requirements for SAE Level 3+ autonomy are accelerating fiber optic and high-speed ethernet connector procurement from Tier-1 suppliers.
- Michigan Manufacturing Corridor:Concentrated OEM and supplier engineering presence in Detroit-Ann Arbor enables rapid prototype-to-production cycles for next-generation interconnection systems.
Market Restraints
- Copper and Silver Price Volatility:Raw material cost swings in conductive alloys compress margin predictability for connector manufacturers serving price-sensitive aftermarket channels.
- Asian Component Concentration:Dependence on East Asian suppliers for precision terminals and housing polymers creates geopolitical exposure and extended lead time risk.
- ISO 26262 Certification Burden:Functional safety validation for ASIL-D rated connectors extends development timelines and locks out smaller competitors lacking accredited testing facilities.
Strategic Opportunities
- Texas EV Engineering Clusters:Austin-San Antonio corridor expansion by Tesla, Rivian, and Lucid Motors creates localized demand for rapid connector customization services.
- Over-the-Air Update Infrastructure:Software-defined vehicle architectures require redundant data pathway connectors that support continuous diagnostic telemetry and remote calibration.
- NHTSA Autonomous Vehicle Framework:Pending fault-tolerance mandates for self-driving systems will mandate redundant connector locking mechanisms, favoring suppliers with pre-validated designs.
Industry Challenges
- High-Voltage Safety Engineering Talent:Scarcity of engineers qualified in arc containment and dielectric isolation for 800V+ systems constrains product development velocity at mid-tier suppliers.
- Legacy 12V Integration Complexity:Hybrid architectures requiring seamless interoperability between conventional low-voltage networks and new high-voltage domains multiply validation testing requirements.
- IP Licensing for Contact geometries:Patent thickets around miniaturized terminal designs force royalty payments or defensive litigation that erodes R&D budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Automotive Connectors Market |
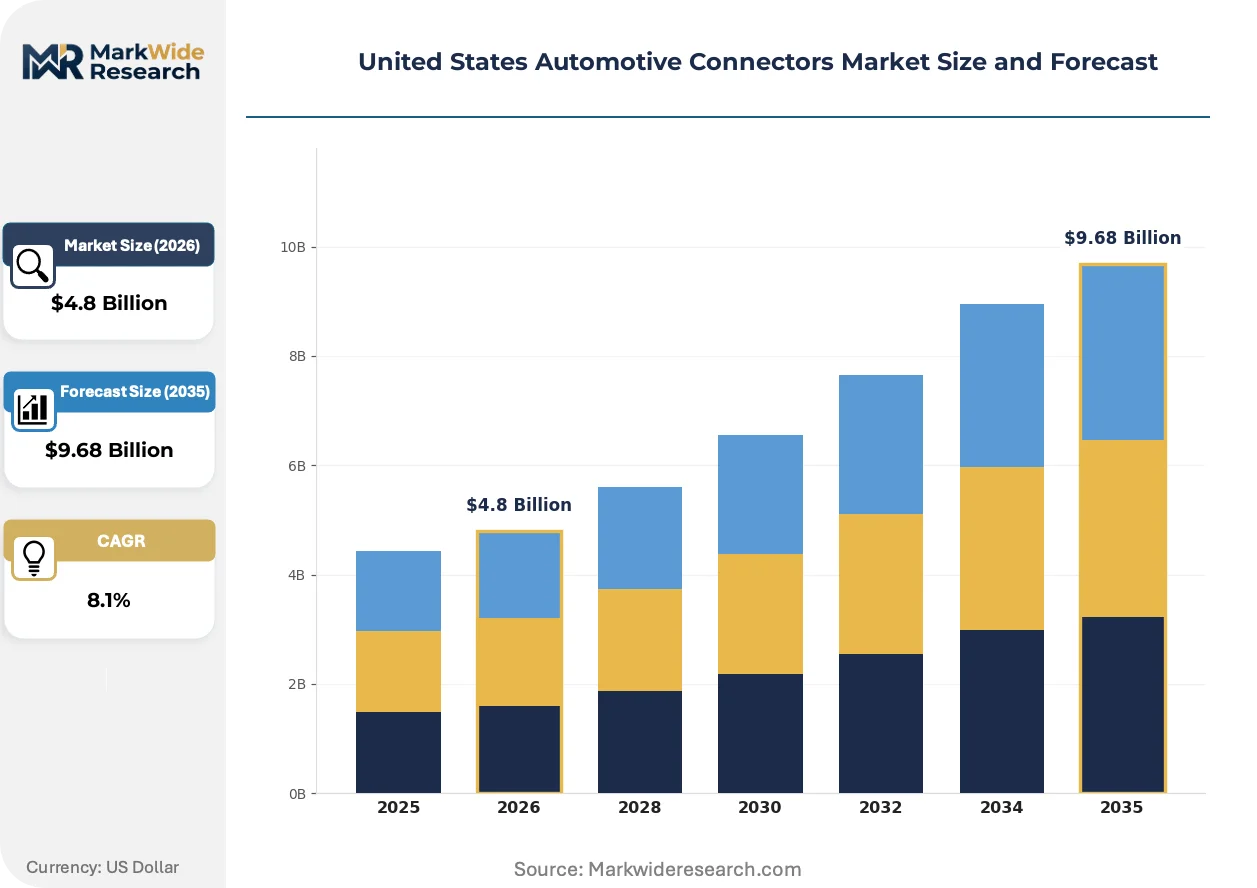
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.68 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electromechanical, Fiber Optic, High Voltage, Waterproof Product Type: Connector Housings, Terminal Pins, Connectors, Crimp Terminals End User: OEMs, Tier-1 Suppliers, Aftermarket, Vehicle Assemblers Mounting Type: Surface Mount, Through-Hole, Hardwired, Modular |
| Companies Covered | TE Connectivity, Amphenol Corporation, Aptiv, Molex, Yazaki Corporation, Sumitomo Electric Industries, Lear Corporation, Furukawa Electric, Rosenberger, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Automotive Connectors Market Strategic Shifts & Innovations
Connector architectures are bifurcating between ultra-high-reliability designs for safety-critical autonomy networks and cost-optimized variants for mass-market electrification platforms.
Shielded twisted-pair ethernet connectors rated for 10Gbps+ throughput are expanding into camera and radar backhaul applications as OEMs consolidate sensor wiring harnesses. Tier-1 suppliers in Michigan and California are adopting these interfaces at production scale for 2026 model year vehicles. The technology is expanding into domains previously served by dedicated coaxial assemblies, compressing supplier portfolios and favoring vendors with integrated electromagnetic compatibility testing capabilities.
NHTSA's updated FMVSS crashworthiness protocols now explicitly address electrical isolation integrity in high-speed collisions, mandating connector designs that maintain dielectric separation after 50G deceleration events. This regulatory pressure is accelerating adoption of redundant locking mechanisms and ceramic-reinforced housings. Powertrain and battery pack segments face the steepest compliance costs, driving consolidation toward suppliers with in-house sled-testing facilities.
Fleet operators and commercial vehicle buyers are unbundling connector procurement from complete wiring harness contracts, establishing direct supplier relationships for standardized high-voltage interfaces. This disintermediation of traditional Tier-1 harness assemblers is most visible in California's heavy-duty trucking electrification programs, where operators specify connectors independently to ensure aftermarket serviceability across mixed-vendor charging infrastructure.
United States Automotive Connectors Market Segmentation
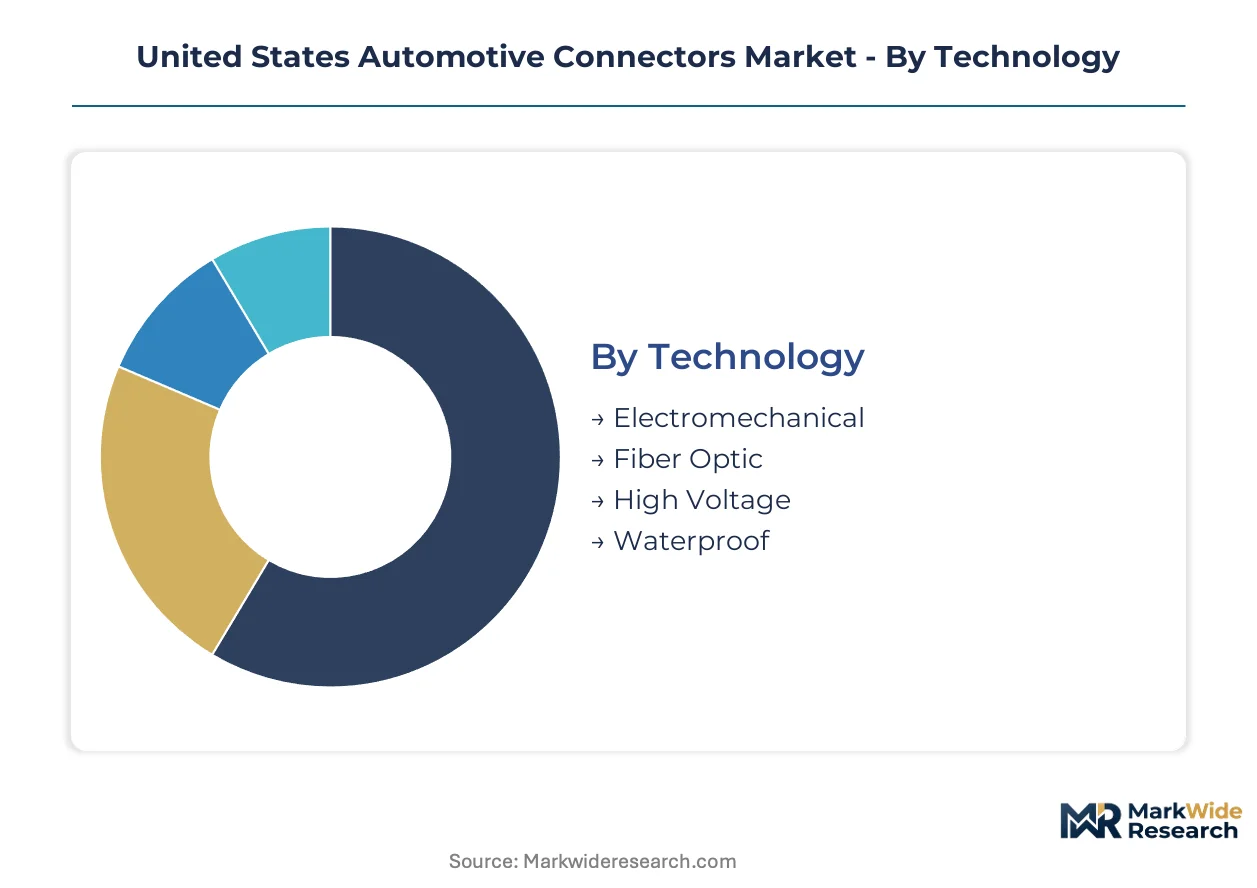
Connector procurement specifications vary sharply across technology tiers and mounting configurations, with NHTSA safety mandates and EPA electrification rules creating divergent certification burdens. Understanding segment-specific compliance pathways enables suppliers to allocate testing resources toward the highest-margin qualification tracks.
Technology:
ISO 26262 functional safety requirements apply asymmetrically across this category, with ASIL-D certification mandatory for high-voltage and fiber optic segments while electromechanical variants face lighter validation protocols.
- Electromechanical:Standard pin-and-socket designs utilizing copper alloys and engineered plastics, rated for 12V-48V architectures. Procurement concentrates in Michigan's legacy powertrain supplier base, where Tier-1 assemblers face margin compression from copper price volatility.
- Fiber Optic:Glass or polymer optical fiber terminations engineered for 10Gbps+ data transmission with electromagnetic immunity. California's autonomous vehicle engineering clusters drive specification intensity, as lidar and camera fusion networks demand redundant signal pathways.
- High Voltage:Interconnection systems rated above 800V with ceramic-reinforced dielectric isolation and arc containment engineering.
- Waterproof:Sealed connector assemblies with IP67+ ingress protection for underhood and chassis applications.
Electromechanical connectors sit at the top of the volume ranking, with fiber optic climbing the fastest.
Product Type:
Cost tier stratification separates premium-certified component families from economy-grade alternatives, with terminal pins commanding the steepest price premiums for ASIL-rated variants.
- Connector Housings:Structural enclosures molded from high-temperature thermoplastics or aluminum alloys, incorporating locking mechanisms and environmental sealing. Michigan OEM engineering centers specify housings with integrated electromagnetic shielding for power electronics modules.
- Terminal Pins:Precision-machined conductive contacts in tin-plated copper or silver-nickel alloys, engineered for 10,000+ mating cycles. California battery pack manufacturers drive demand for high-current terminal geometries rated above 300A continuous.
- Connectors:Fully assembled electromechanical interfaces combining housings, terminals, and secondary locking features.
- Crimp Terminals:Compression-style wire termination components for high-volume harness assembly operations.
Connector housings generate the highest absolute revenue, with terminal pins expanding most quickly.
End User:
Customer type determines contract structure, with OEMs demanding multi-year supply agreements with embedded price-down clauses while aftermarket channels prefer spot purchasing with inventory risk transfer.
- OEMs:Vehicle manufacturers with direct specification authority over connector architectures and qualification protocols. Detroit-Ann Arbor engineering corridors concentrate procurement decisions for powertrain and chassis applications.
- Tier-1 Suppliers:Harness assemblers and subsystem integrators purchasing connectors as bill-of-materials components. Texas EV manufacturing expansion is redirecting Tier-1 engineering resources toward rapid customization services.
- Aftermarket:Independent distributors and service networks sourcing replacement connectors for repair and retrofit applications.
- Vehicle Assemblers:Contract manufacturing operations with limited design authority but significant volume aggregation.
OEMs dominate procurement volume, with aftermarket channels gaining margin traction fastest.
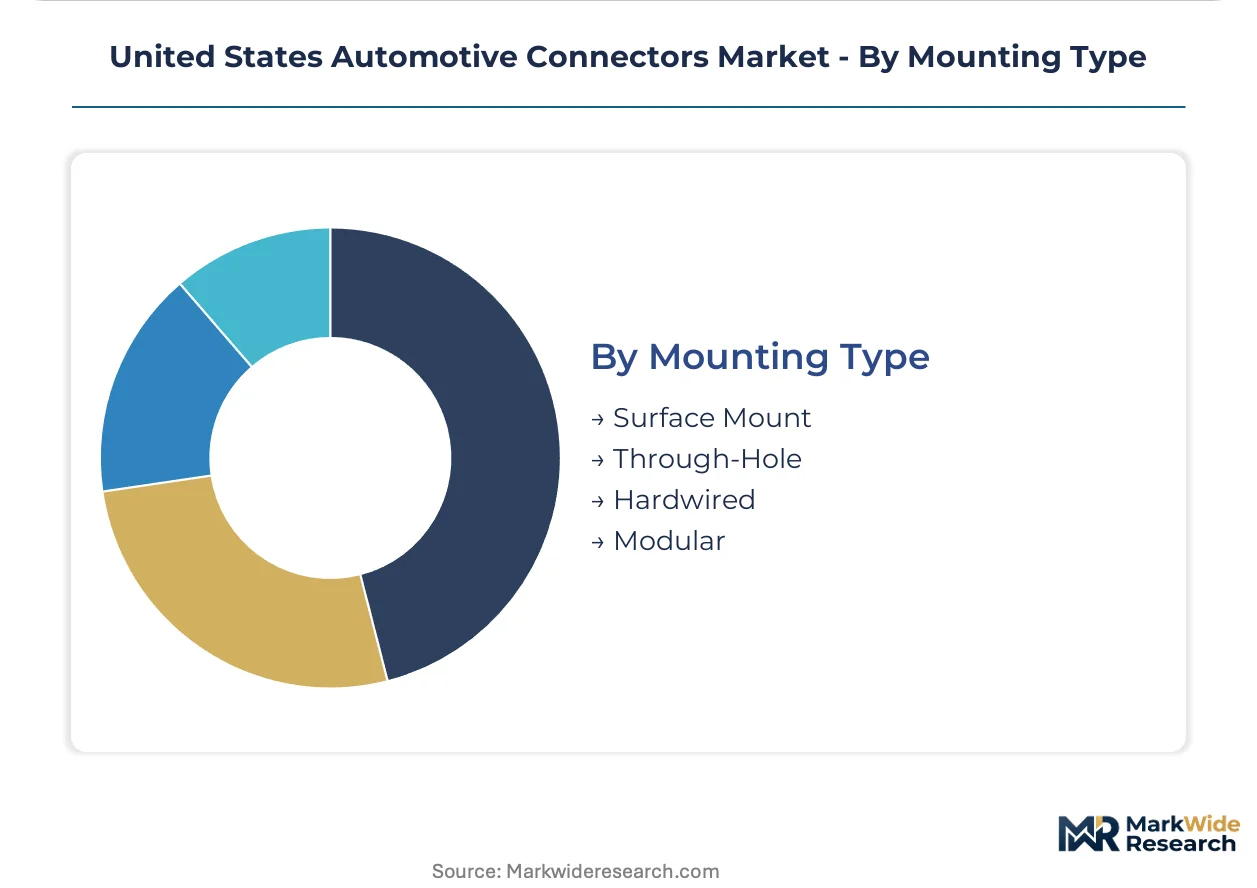
Mounting Type:
Application environment dictates mounting selection, with underhood thermal cycling and vibration exposure favoring through-hole and hardwired approaches over surface-mount alternatives.
- Surface Mount:Reflow-solderable connector packages for printed circuit board integration in compact electronic control units. Infotainment module suppliers in California specify these for space-constrained cabin electronics.
- Through-Hole:Pin-in-hole solder or press-fit terminations providing mechanical strain relief for high-vibration environments. Battery management system manufacturers prioritize through-hole mounting for thermal cycling durability.
- Hardwired:Permanent crimp or weld terminations for high-current power distribution applications.
- Modular:Field-configurable connector systems allowing pin count and keying variations without tooling changes.
Through-hole mounting leads volume rankings, with modular configurations ascending fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's connector procurement concentrates on high-reliability powertrain applications, while the United States diverges toward software-defined vehicle architectures demanding data-rate-intensive interconnection systems. Japan maintains specialized expertise in miniaturized terminal geometries for hybrid platforms. China scales domestic production capacity to serve its accelerating EV transition.
Germany
KBA vehicle type-approval protocols and EU Green Deal electrification timelines drive OEM specification of ASIL-D certified connectors for 800V architectures. The country's national automotive regulator mandates redundant locking mechanisms for autonomous vehicle fault tolerance. Stuttgart engineering centers coordinate Tier-1 supplier qualification for next-generation battery management interconnection systems.
United States
NHTSA FMVSS crashworthiness updates and EPA fleet emissions standards compel connector designs maintaining dielectric integrity after 50G deceleration events. Michigan's Detroit-Ann Arbor manufacturing corridor anchors rapid prototype-to-production cycles for high-voltage powertrain interconnections. California's EV engineering clusters specify fiber optic and ethernet connectors for lidar fusion networks.
Japan
METI carbon neutrality roadmaps and JIS functional safety standards shape procurement of miniaturized connectors for hybrid powertrain integration. The country's industrial ministry promotes domestic supply chain resilience for critical automotive electronics. Nagoya-area manufacturing bases specialize in precision terminal geometries rated for 10,000+ mating cycles.
China
MIIT new energy vehicle mandates and dual carbon goals accelerate domestic connector production for 800V+ charging infrastructure. The Ministry of Industry and Information Technology enforces GB standards for high-voltage interconnection safety in mass-market EV platforms. Yangtze River Delta manufacturing hubs scale capacity to serve BYD, NIO, and XPeng engineering requirements.
South Korea
MFDS-adjacent industrial standards and national hydrogen economy roadmaps diversify connector demand toward fuel cell vehicle applications. The Seoul Capital Area concentrates R&D investment in high-speed data connectors for autonomous driving platforms. Busan-Ulsan industrial complexes manufacture sealed waterproof assemblies for battery pack integration.
United States Automotive Connectors Market Key Industry Players
Top-tier vendors anchor premium-certified supply chains, while mid-scale specialists occupy cost-optimized segments for mass-market electrification platforms. The vendor base stratifies across three functional tiers: integrated component-housing assemblers, terminal geometry specialists, and regional customization service providers. Two dominant competitive moves define current positioning: backward integration into precision terminal manufacturing and geographic expansion toward Texas EV engineering clusters.
Within the integrated systems tier, TE Connectivity and Amphenol Corporation exemplify vendors with sensor-to-cloud portfolio breadth. Aptiv occupies a position bridging OEM specification authority and Tier-1 harness assembly integration. These three companies represent archetypes spanning defense-grade reliability transfer, high-speed ethernet platform anchoring, and autonomous driving subsystem specialization respectively.
| Leading Market Players |
|---|
| TE Connectivity |
| Amphenol Corporation |
| Aptiv |
| Molex |
| Yazaki Corporation |
| Sumitomo Electric Industries |
| Lear Corporation |
| Furukawa Electric |
| Rosenberger |
| Others |
Cost & Logistics Intelligence
Backward integration into precision terminal manufacturing anchors both supply security and pricing power for connector vendors serving NHTSA-certified applications. This upstream control over conductive alloy sourcing and ceramic-reinforced housing production insulates Tier-1 suppliers from copper price volatility while commanding premium positioning in 800V powertrain procurement.
Pricing Analysis
Capacity additions in Mexico and Texas are reshaping price floors for standard-grade electromechanical connectors as regional manufacturing reduces logistics premiums. Three-tier pricing structure across ASIL-D certified, ISO-compliant, and economy-grade variants separates OEM specification tiers by functional safety validation depth. Cost compression in aftermarket channels intensifies because fleet operators unbundle procurement from harness contracts. Tier-1 suppliers exhibit least price sensitivity due to embedded multi-year agreements, while independent distributors face margin erosion from spot-market copper fluctuations.
Supply Chain Analysis
Single-source vulnerability sits with East Asian suppliers of precision terminals and high-temperature polymer housings. Domestic production draws from copper mining operations in Arizona and Utah, silver refining facilities in Idaho, and ceramic substrate manufacturers in Ohio. Tariff exposure on Chinese-sourced engineered plastics threatens dielectric component availability. Distribution runs through Detroit-Ann Arbor OEM engineering centers, California EV clusters, and Texas manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States Automotive Connectors Market represents a late-cycle quality story as EPA electrification mandates shift procurement toward ASIL-D certified architectures with embedded redundancy engineering.
For Market Incumbents: Hedge against copper alloy volatility through captive supply agreements with domestic mining operations and precision terminal foundries. Expand in-house sled-testing facilities to capture NHTSA FMVSS compliance premiums before pending autonomous vehicle fault-tolerance rules take effect. Prioritize backward integration into ceramic-reinforced housing production to defend margin position from Asian polymer price swings. For New Entrants and Emerging Players: The gap between premium ASIL-D certified connectors and economy-grade electromechanical variants creates white-space opportunity in mid-tier waterproof assemblies for commercial vehicle battery packs. Target Texas EV engineering clusters with rapid customization services for 800V charging infrastructure. Penetrate fleet operator procurement channels through standardized high-voltage interface specifications that ensure aftermarket serviceability across mixed-vendor charging networks. For Investors and Strategic Acquirers: Roll-up economics work for regional customization service providers because OEMs are fragmenting connector procurement across specialized geography-specific engineering clusters. Five-to-ten year viability hinges on NHTSA regulatory expansion into autonomous vehicle fault-tolerance mandates. Watch for inflection signals in FMVSS comment period closures that would accelerate redundant locking mechanism adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Standardization | Reduces validation burden for 800V architectures across multiple OEM programs. |
| Battery Supply Agreement | Locks in terminal pin volumes for Michigan and California battery pack manufacturers. |
| Software-Defined Vehicle Investment | Positions fiber optic connectors for lidar fusion and over-the-air update pathways. |
| Geographic Manufacturing Footprint | Texas corridor expansion captures Tesla, Rivian, and Lucid Motors engineering demand. |
| Charging Infrastructure Partnership | Secures aftermarket channel access for standardized high-voltage interface specifications. |
Research Approach
Direct dialogue with OEM platform engineers, Tier-1 supplier procurement leads, aftermarket distributor operations heads, and NHTSA regulatory affairs specialists grounded the qualitative foundation. Secondary validation drew from EPA emissions filings, NHTSA FMVSS docket records, vehicle production databases, and SEC disclosures from connector manufacturers. Bottom-up segment sizing triangulated against top-down market envelope estimates.
Segment-level outputs across technology tier, product type, end-user category, and mounting configuration were generated through the analytical framework. CAGRs were derived from regression analysis against EPA fleet electrification timelines and NHTSA regulatory adoption curves. Propulsion architecture mix and content-per-vehicle trajectories for 800V systems served as primary forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery commercialization would alter the outlook for high-voltage connector demand. Forecasts reflect embedded assumptions regarding NHTSA rulemaking schedules and copper price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Self Loading Trailer Market
Vehicle Components
Electric Wheelbarrow Market
Vehicle Components
Digital Tire Inflator Market
Vehicle Components
2 Wheeler Fuel Tank Market
Vehicle Components
LAMEA Vehicle Exhaust Hose Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Rear Axle Market
Vehicle Components
Automotive NVH Materials Market
Vehicle Components
Spark Plug Accessories Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Wheel Seals Market
Vehicle Components
Automotive Steering Shaft Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Limited Slip Differential (LSD) Market
Vehicle Components
Tow Tractor Market