
 Europe Vehicle Remote Diagnostic Market | 2026-2036
Europe Vehicle Remote Diagnostic Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Vehicle Remote Diagnostic Market Foresight
UNECE WP.29 regulation is rotating competitive access across the Europe Vehicle Remote Diagnostic Market, with only suppliers holding cybersecurity management system certifications qualifying for OEM supply contracts. Robert Bosch GmbH leverages its embedded telematics hardware footprint to sustain service revenue streams through cloud-connected diagnostic platforms. Continental AG anchors its position through deep integration with European OEM electronic architectures, while Vector Informatik GmbH specializes in diagnostic software tools that compete on protocol breadth and calibration precision.
Vehicle remote diagnostic systems encompass hardware modules, communication interfaces, and cloud analytics platforms that extract fault codes, performance metrics, and predictive wear indicators from onboard electronic control units via cellular, Bluetooth, or satellite links. These systems transmit standardized diagnostic trouble codes and proprietary sensor data to centralized servers for pattern recognition, enabling preemptive maintenance scheduling and warranty cost reduction. Telematics solutions dominate current revenue pools due to their integration with insurance and fleet management business models, while software solutions represent the fastest-expanding margin segment as vendors shift from hardware sales to recurring SaaS architectures. Cellular technology leads connectivity deployments across European commercial fleets, though satellite links are gaining traction for rural and cross-border logistics applications where terrestrial coverage fragments.
EU Green Deal emission targets and UNECE WP.29 cybersecurity mandates are reshaping product specifications, forcing suppliers to embed tamper-proof data logging and over-the-air update capabilities as baseline requirements. EMA coordination with national type-approval authorities accelerates harmonized diagnostic protocol standards that reduce fragmentation costs for multi-market operators. Stakeholders must monitor the interaction between CSRD sustainability disclosure rules and emerging battery health monitoring obligations, as these will determine which diagnostic data streams become commercially extractable versus regulatorily mandated.
Market Dynamics
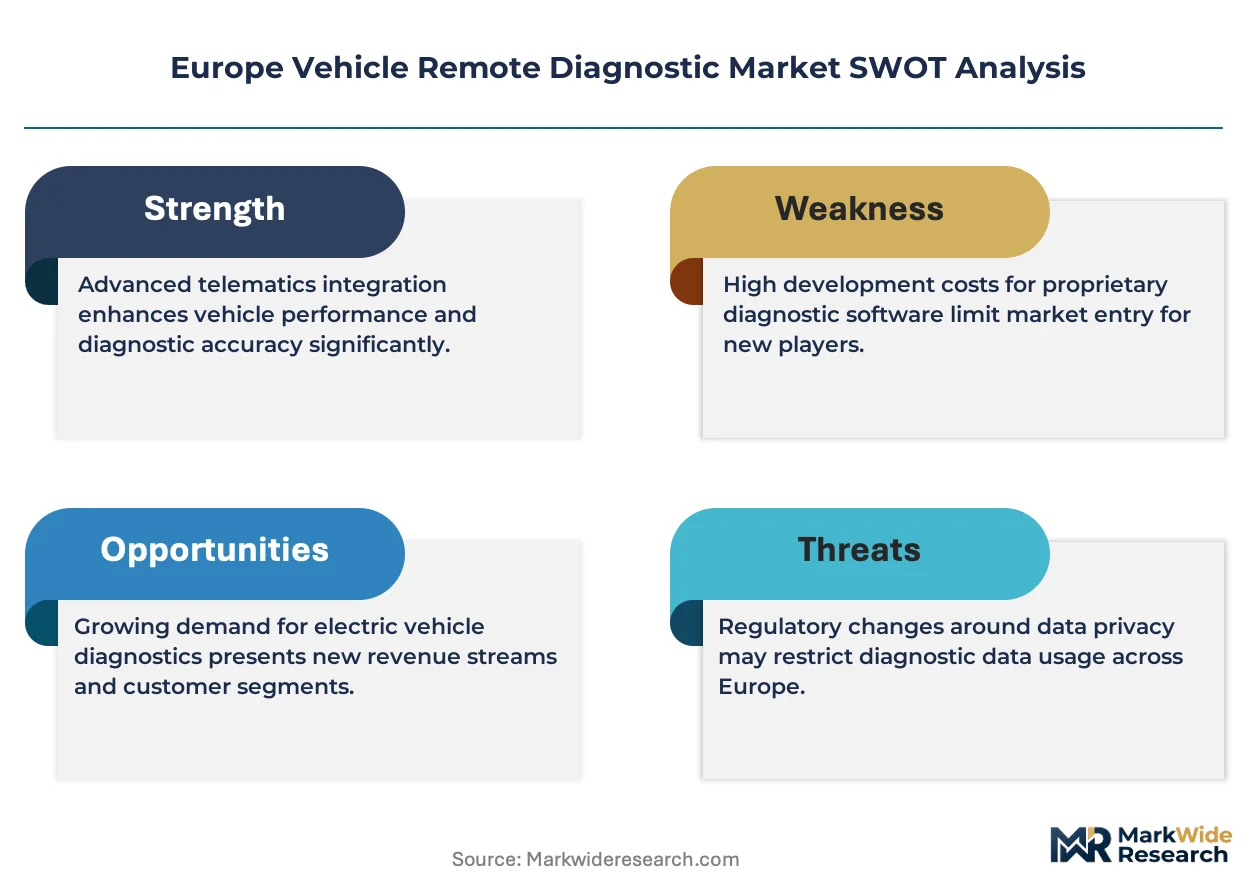
UNECE WP.29 cybersecurity mandates are compressing supplier qualification timelines across Europe, with only ISO/SAE 21434 certified vendors retaining access to OEM telematics programs. This regulatory gatekeeping is redistributing contract volumes toward vertically integrated electronics suppliers while disqualifying legacy diagnostic tool vendors lacking embedded security architectures.
Growth Catalysts
- EU Green Deal emission protocols:Real-time CO2 and NOx monitoring requirements are mandating OBD-II data streaming for commercial vehicle compliance verification.
- Fleet operator consolidation:Large logistics aggregators in Germany and France are standardizing on unified diagnostic platforms to compress maintenance coordination costs across multi-brand vehicle pools.
- Cellular-V2X module integration:5G telematics hardware is collapsing the latency between fault detection and cloud analytics, enabling predictive maintenance at highway speeds.
Market Restraints
- Semiconductor supply concentration:Automotive-grade SoC shortages from Taiwanese foundries are extending telematics control unit lead times to 26-32 weeks.
- UNECE WP.29 certification costs:Cybersecurity management system audits and penetration testing are adding €400,000-€600,000 per supplier platform before market entry.
- Terrestrial coverage fragmentation:Cellular dead zones across Alpine corridors and Eastern European rural highways limit real-time diagnostic reliability for cross-border freight operators.
Strategic Opportunities
- Battery electric vehicle aftermarket:Poland and Czech Republic service networks lack native diagnostic capabilities for high-voltage powertrain systems, creating first-mover windows for specialized tool vendors.
- CSRD sustainability disclosure alignment:Mandatory Scope 3 emissions reporting is converting vehicle health data into auditable carbon accounting inputs for corporate fleet customers.
- Satellite-cellular hybrid connectivity:Low-earth orbit links are penetrating coverage gaps for timber and mining fleets operating in Scandinavian and Carpathian terrain.
Industry Challenges
- Automotive cybersecurity engineering talent:ISO/SAE 21434 implementation requires embedded systems specialists with both functional safety and cryptographic protocol expertise, a skill intersection scarce across European technical universities.
- Legacy fleet integration complexity:Pre-2018 commercial vehicles lack standardized diagnostic ports, forcing retrofit hardware designs that must interface with 12+ proprietary ECU protocols.
- Over-the-air update orchestration:Coordinating firmware patches across heterogeneous vehicle generations without service interruption demands DevOps capabilities foreign to traditional automotive suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Vehicle Remote Diagnostic Market |
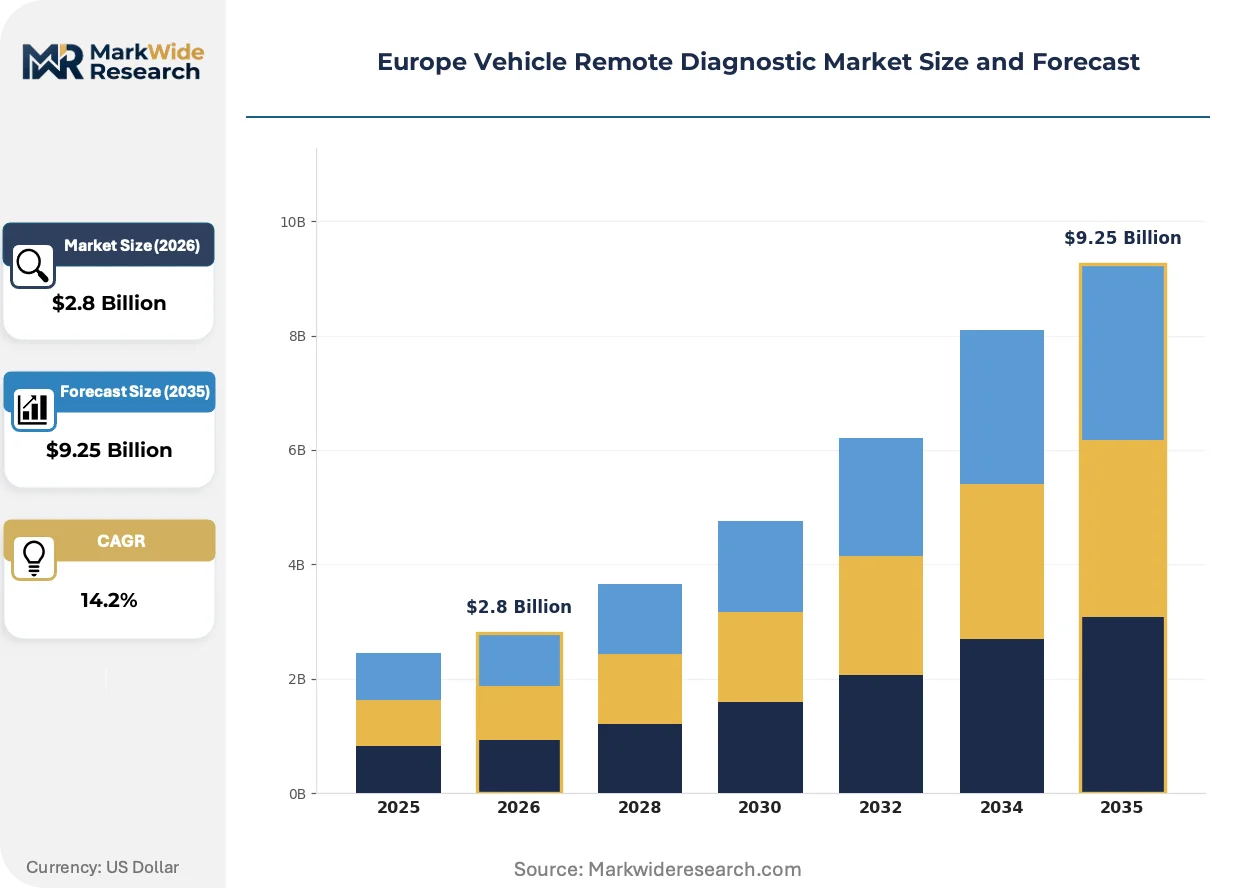
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $9.25 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telematics, On-Board Diagnostics, Software Solutions, Fleet Management Technology: Cellular, Bluetooth, Wi-Fi, Satellite End User: OEMs, Aftermarket Providers, Fleet Operators, Repair Shops Application: Maintenance, Safety Monitoring, Performance Tracking, Emission Control |
| Companies Covered | Robert Bosch GmbH, Continental AG, Vector Informatik GmbH, MAHLE Aftermarket GmbH, ACTIA Group, Softing AG, Hella GmbH, Bosch Automotive Aftermarket, Herth+Buss, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Vehicle Remote Diagnostic Market Shifts & Advancements
Diagnostic hardware architectures are compressing toward edge-computing form factors that preprocess fault codes before cellular transmission, reducing data costs and enabling real-time inference. This shift is redistributing value from cloud analytics vendors toward semiconductor-integrated module suppliers.
Edge AI inference chips are miniaturizing diagnostic processing into telematics control units smaller than 50 cubic centimeters. German commercial fleet operators are deploying these modules at scale across 2024-2025 vehicle replacement cycles. The technology is compressing latency between fault detection and driver notification from minutes to milliseconds, displacing centralized cloud-only architectures for time-critical powertrain alerts.
CSRD sustainability disclosure rules are mandating granular vehicle utilization data for corporate Scope 3 emissions accounting. Large German and French logistics firms must now source telematics platforms with tamper-proof odometer and fuel consumption logging. Heavy-duty trucking segments are responding fastest, integrating blockchain-anchored data verification to satisfy auditor traceability requirements.
Subscription-based diagnostic access is displacing perpetual license sales across European independent repair networks. Mid-sized garage chains in Italy and Spain are consolidating purchasing through platform aggregators that negotiate volume SaaS rates. This behavioral shift is most visible in emission testing workflows, where pay-per-test models are replacing capital-intensive analyzer purchases for smaller service points.
Europe Vehicle Remote Diagnostic Market Segmentation
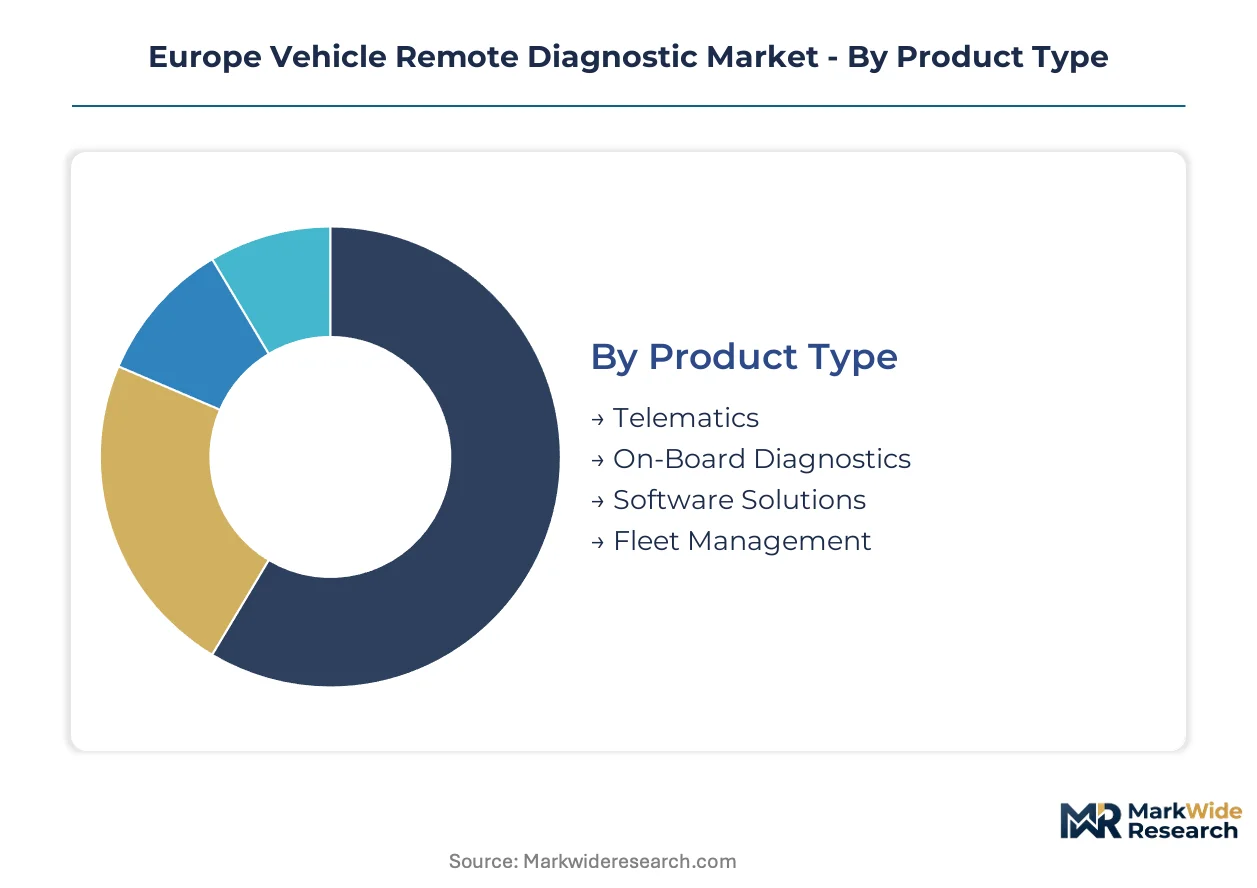
Segmentation in Europe's vehicle remote diagnostic market determines which technology stacks capture fleet procurement budgets versus aftermarket service revenue. Product architecture choices cascade through connectivity requirements, customer relationships, and compliance obligations across EU member states.
Product Type:
Telematics and software solutions flow through fleet management platforms and OEM embedded contracts, while hardware-centric segments concentrate in aftermarket distribution networks.
- Telematics:Integrated hardware-software modules combining GPS positioning, cellular modems, and CAN bus interfaces for real-time data extraction. German and French commercial fleet operators are consolidating procurement through telematics service providers to unify multi-brand vehicle visibility under single dashboards.
- Software Solutions:Cloud-native diagnostic platforms delivering fault code analytics, predictive algorithms, and maintenance scheduling through subscription models. These architectures are climbing the fastest as vendors migrate from perpetual licenses to recurring SaaS revenue across European independent repair networks.
- On-Board Diagnostics:Standalone hardware devices interfacing directly with vehicle OBD-II ports for localized fault retrieval.
- Fleet Management:Integrated operational platforms combining diagnostic data with route optimization, fuel monitoring, and driver behavior analytics.
Telematics dominates installed base. Software Solutions is where expansion concentrates.
Technology:
Connectivity choice hinges on vehicle mobility patterns and data latency requirements, with terrestrial technologies capturing urban logistics and satellite penetrating terrain-constrained operations.
- Cellular:4G/5G modules providing high-bandwidth, low-latency links for continuous streaming diagnostic data. German commercial fleets are deploying cellular-V2X hardware at scale to enable real-time powertrain alerts during highway operation.
- Satellite:Low-earth orbit and geostationary links ensuring coverage across Alpine corridors, Scandinavian timber routes, and Eastern European rural highways where terrestrial networks fragment.
- Bluetooth:Short-range wireless for proximity-based diagnostic sessions between vehicles and technician handheld devices.
- Wi-Fi:High-throughput local connectivity for depot-based bulk data uploads and firmware updates.
Cellular captures volume leadership. Satellite is gaining share fastest in cross-border freight segments.
End User:
Customer type determines pricing architecture and contract structure, with OEMs embedding diagnostics at manufacturing and aftermarket providers retrofitting legacy fleets.
- Fleet Operators:Large logistics aggregators standardizing unified diagnostic platforms across multi-brand vehicle pools to compress maintenance coordination costs. French and German operators are consolidating purchasing power through platform aggregators.
- OEMs:Vehicle manufacturers integrating remote diagnostic capabilities at factory installation to satisfy EU Green Deal emission monitoring mandates and UNECE WP.29 cybersecurity requirements.
- Aftermarket Providers:Independent service networks and parts distributors supplying retrofit hardware and diagnostic tools for out-of-warranty vehicles.
- Repair Shops:Small and mid-sized garage chains accessing diagnostic capabilities through subscription-based SaaS platforms rather than capital-intensive analyzer purchases.
Fleet Operators drive contract value concentration. Repair Shops represent the steepest expansion trajectory for subscription revenue models.
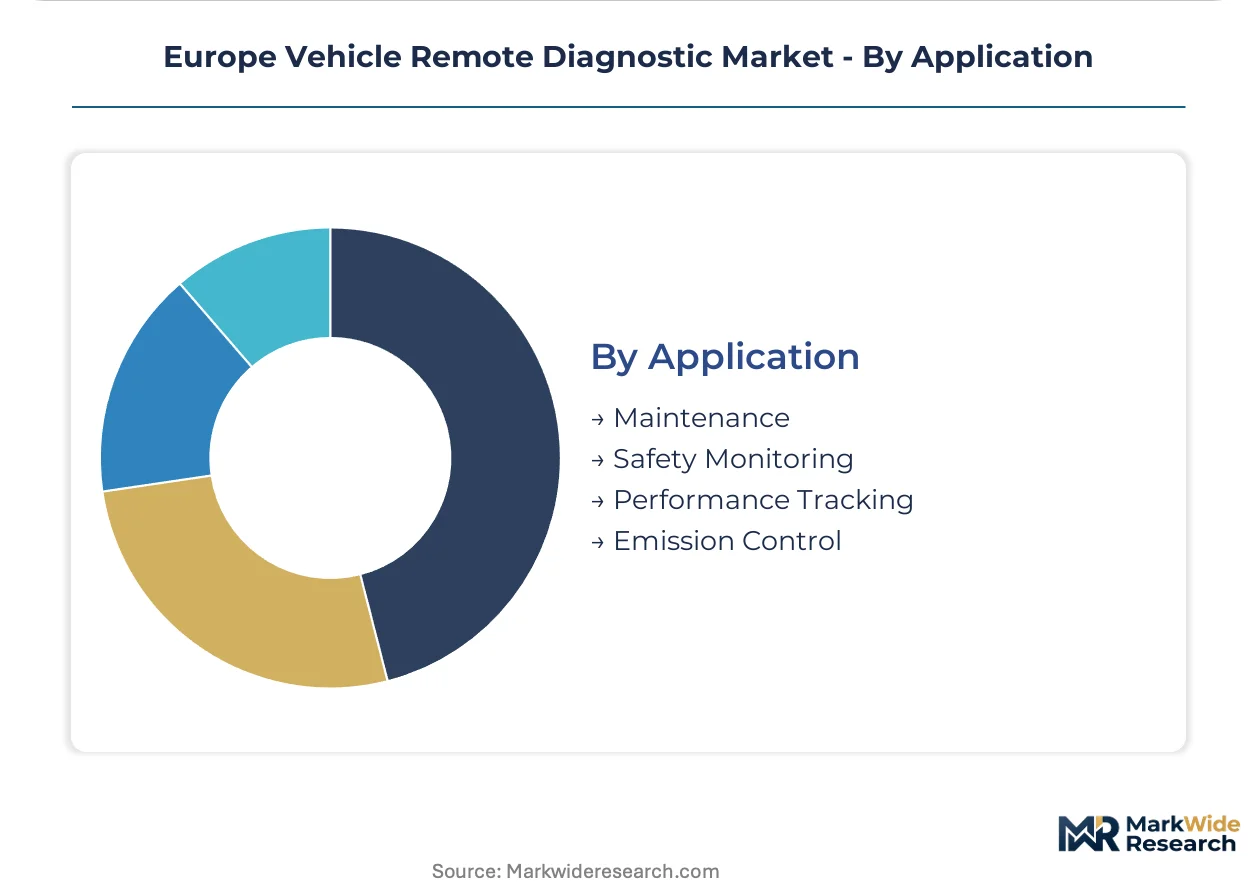
Application:
Use case prioritization reflects regulatory pressure and operational economics, with emission compliance and predictive maintenance commanding procurement attention.
- Emission Control:Real-time CO2 and NOx monitoring systems streaming OBD-II data for EU Green Deal compliance verification. German heavy-duty trucking segments are integrating blockchain-anchored data logging to satisfy auditor traceability requirements.
- Maintenance:Predictive scheduling platforms analyzing fault codes and sensor trends to preempt component failures and minimize vehicle downtime.
- Safety Monitoring:Systems tracking brake wear, tire pressure, and stability control status for driver alert generation.
- Performance Tracking:Powertrain efficiency analytics optimizing fuel consumption and engine calibration across operating conditions.
Emission Control dominates regulatory-driven procurement. Maintenance captures the fastest volume expansion as fleet operators prioritize uptime economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial fleet operators and automotive OEMs concentrate procurement authority across Germany, France, and the United Kingdom, with regulatory pressure from Brussels accelerating standardization investments in connected diagnostic infrastructure.
Germany
Heavy-duty trucking aggregators in the Rhine-Ruhr corridor are consolidating multi-brand fleet visibility under unified telematics dashboards. The KBA enforces UNECE WP.29 cybersecurity certification as mandatory for factory-installed diagnostic modules. Stuttgart's automotive manufacturing cluster drives edge-AI diagnostic hardware integration into 2024-2025 vehicle replacement cycles.
France
Paris-based logistics platforms are standardizing predictive maintenance scheduling across pooled vehicle assets to compress coordination costs. The EU Green Deal's emission verification protocols mandate real-time OBD-II data streaming for commercial vehicle compliance. The Île-de-France region anchors software development for cloud-native diagnostic analytics serving pan-European fleet operators.
United Kingdom
Post-Brexit regulatory divergence is compelling UK fleet operators to maintain parallel diagnostic data streams for EU and domestic compliance verification. The Driver and Vehicle Standards Agency coordinates with UNECE frameworks to preserve market access for British telematics vendors. Midlands manufacturing corridors sustain aftermarket diagnostic tool distribution networks serving independent repair chains.
Italy
Mid-sized garage chains in Lombardy and Emilia-Romagna are migrating from capital-intensive analyzer purchases to subscription-based SaaS diagnostic access. EMA coordination with national type-approval authorities accelerates harmonized protocol standards. Turin's automotive supplier ecosystem specializes in retrofit hardware for legacy fleet integration.
Poland
Independent service networks in the Silesian and Greater Poland voivodeships lack native diagnostic capabilities for high-voltage battery electric powertrains. The country's national automotive regulator aligns type-approval processes with EU cybersecurity mandates. Warsaw-based fleet operators are piloting satellite-cellular hybrid connectivity for cross-border freight corridors into Ukraine and the Baltic states.
Europe Vehicle Remote Diagnostic Market Competitive Landscape
Player mix skews toward diversified automotive electronics suppliers with embedded telematics hardware footprints and specialized diagnostic software vendors competing on protocol breadth. The supplier base concentrates around vertically integrated Tier-1 electronics manufacturers and independent software tool developers. Two strategic archetypes dominate: hardware-anchored platform vendors monetizing through recurring cloud service revenue, and pure-play software specialists licensing diagnostic protocol libraries. Competitive moves center on cybersecurity certification pre-qualification for OEM supply contracts and SaaS pricing model migration to capture aftermarket subscription revenue.
Within the diversified electronics tier, Robert Bosch GmbH and Continental AG exemplify hardware-anchored platform strategies, while Vector Informatik GmbH occupies a position among specialized diagnostic software developers. Bosch leverages its embedded telematics control unit installed base to sustain service revenue through cloud-connected architectures. Continental anchors its competitive position through deep integration with European OEM electronic architectures. Vector Informatik competes on diagnostic protocol breadth and calibration precision within software-centric procurement channels.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| Vector Informatik GmbH |
| MAHLE Aftermarket GmbH |
| ACTIA Group |
| Softing AG |
| Hella GmbH |
| Bosch Automotive Aftermarket |
| Herth+Buss |
| Others |
Supply & Pricing Matrix
UNECE WP.29 cybersecurity certification gates both supply qualification and price differentiation simultaneously, compressing vendor margins through mandatory audit costs while enabling certified suppliers to command premium positioning against uncertified competitors. German and French fleet operators absorb these cost passthroughs differently, with large logistics aggregators negotiating volume SaaS rates while independent repair chains face steeper per-unit hardware pricing.
Pricing Analysis
Cost-plus contracts with semiconductor indexation dominate telematics control unit procurement, binding OEM pricing to Taiwanese foundry output costs. Pricing stratifies across ISO/SAE 21434 certified premium tiers, uncertified standard hardware, and economy retrofit modules lacking over-the-air capabilities. Cost compression in the economy tier intensifies because Polish and Czech aftermarket distributors compete aggressively on entry-level OBD-II devices. Independent repair shops in Italy and Spain exhibit the highest price sensitivity, while German commercial fleet operators prioritize cybersecurity assurance over unit cost.
Supply Chain Analysis
Rotterdam port congestion and container availability constraints on the Asia-Europe trade lane are extending inbound lead times for automotive-grade SoCs and cellular modem modules. Manufacturing concentrates in Germany, Taiwan, and South Korea, with final assembly drawing from Czech and Romanian electronics clusters. Supply chain risk centers on single-source vulnerability for 5G baseband processors from Qualcomm and MediaTek. Distribution runs through Tier-1 automotive electronics suppliers directly into OEM assembly plants, with aftermarket channels feeding through regional parts distributors in Milan, Stuttgart, and Warsaw.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's vehicle remote diagnostic market represents a high-growth disruption as edge-AI inference chips collapse latency thresholds and CSRD sustainability mandates convert vehicle health data into auditable compliance infrastructure.
For Market Incumbents: Consolidate cybersecurity engineering capabilities through acquisition of ISO/SAE 21434 specialist consultancies, as talent scarcity threatens OEM contract retention. Deepen backward integration into edge-computing semiconductor design to capture value migrating from cloud analytics vendors. Lock in multi-year fleet operator contracts before satellite-cellular hybrid connectivity commoditizes terrestrial coverage advantages.
For New Entrants and Emerging Players: ISO/SAE 21434 fast-track certification programs in Germany and France open immediate OEM supply channel access for qualified vendors. Battery electric vehicle aftermarket service networks in Poland and Czech Republic offer the most penetrable white space, with native high-voltage diagnostic capabilities absent from incumbent tool portfolios. Pursue SaaS platform partnerships with Italian and Spanish garage chain aggregators to bypass capital-intensive direct sales infrastructure.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across software-centric diagnostic platforms as vendors migrate from hardware sales to recurring SaaS architectures. Five-to-ten year viability favors targets with embedded telematics hardware footprints already deployed at scale, enabling cloud service revenue extraction without incremental customer acquisition cost. Monitor satellite-cellular hybrid connectivity adoption rates in Scandinavian timber and Carpathian mining fleets as inflection indicator for coverage-agnostic platform valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Cybersecurity Certification Fast-Track | UNECE WP.29 compliance gates OEM supply contracts and disqualifies legacy tool vendors lacking embedded security architectures. |
| Edge-AI Hardware Integration | German fleet operators deploy sub-50cc telematics modules compressing fault-to-alert latency from minutes to milliseconds. |
| SaaS Platform Migration | Subscription diagnostic access displaces perpetual licenses across Italian and Spanish independent repair networks. |
| Satellite-Cellular Hybrid Deployment | Low-earth orbit links penetrate Alpine and Scandinavian coverage gaps for timber and mining fleet operators. |
| CSRD Data Verification Infrastructure | Blockchain-anchored logging satisfies auditor traceability requirements for German heavy-duty trucking Scope 3 emissions reporting. |
Research Methodology
Initial hypotheses were tested against primary input from OEM platform engineers, Tier-1 supplier procurement leads, fleet operator maintenance directors, and aftermarket distributor operations heads, then refined through secondary validation. Primary fieldwork combined structured interviews with automotive electronics executives and fleet management technology officers across Germany, France, and Poland. Secondary sources encompassed UNECE regulatory filings, KBA type-approval databases, EU Green Deal implementation guidelines, and vehicle production registration data. Bottom-up segment sizing triangulated against top-down market value estimates derived from supplier revenue disclosures.
Variance decomposition across product type, connectivity technology, end-user category, and application use case anchored the analytical framework over the projection horizon. Modeled dimensions included telematics hardware versus software solutions, cellular versus satellite connectivity, OEM embedded versus aftermarket retrofit channels, and emission compliance versus predictive maintenance applications. CAGRs were derived from segment-level growth rate reconciliation against aggregate market expansion. Forecast inputs incorporated EU Green Deal implementation timelines, UNECE WP.29 certification penetration curves, and fleet operator replacement cycle patterns.
Underlying assumptions cover sustained regulatory enforcement of cybersecurity mandates, semiconductor supply normalization, and CSRD disclosure rule adoption across German and French logistics sectors, with deviation risk concentrated in legacy fleet retrofit complexity and automotive cybersecurity engineering talent availability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telematics and Infotainment
Automotive Dashboard Camera Market
Telematics and Infotainment
Trailer Telematics Market
Telematics and Infotainment
Global Automotive Remote Diagnostics Market
Telematics and Infotainment
Car DVR Market
Telematics and Infotainment
Global Automotive Navigation System Market
Telematics and Infotainment
United States Commercial Telematics Market
Telematics and Infotainment
Europe Automotive Navigation System Market
Telematics and Infotainment
Automotive Navigation Solutions Market
Telematics and Infotainment
Global Car Sharing Telematics Market
Telematics and Infotainment
Global Taxi-Sharing Software Market
Telematics and Infotainment
Asia-Pacific Automotive Telematics Market
Telematics and Infotainment
Vehicle to Vehicle (V2V) Communication Market
Telematics and Infotainment
APAC Telematics Market
Telematics and Infotainment
Automotive Infotainment Market
Telematics and Infotainment
Europe Automotive Infotainment Systems Market
Telematics and Infotainment
North America Automotive Navigation System Market