
 Rear Axle Market | 2026-2036
Rear Axle Market Size, Share, and Industry Trends Forecast 2026-2036
Rear Axle Market Intelligence
Software-defined torque vectoring and predictive maintenance subscriptions are recalibrating the traditional hardware-centric sales model for rear axles. Dana Incorporated leverages its expertise in electrification to integrate smart features into its axle systems. ZF Friedrichshafen AG competes through its comprehensive portfolio spanning from conventional to electric driveline components. American Axle & Manufacturing, Inc. sustains its position with a focus on manufacturing efficiency and supply chain control for light truck applications.
A rear axle is a drivetrain assembly that transfers power from the differential to the drive wheels. Engineered with specific gear ratios and load capacities, these components are typically made from high-strength steel or cast iron. Heavy trucks constitute a dominant segment, often requiring robust tandem axle or tri-axle configurations for load-bearing. While steel remains the primary material, aluminum and composites are gaining traction in passenger cars to reduce vehicle weight.
Regulations from the US EPA and the EU Green Deal framework push for greater powertrain efficiency, influencing axle design and material choice. In parallel, China's GB standards impose strict safety and performance criteria for commercial vehicle components, including axles. Component manufacturers must decide whether to invest in lightweighting technologies for electric vehicles or optimize existing designs for internal combustion engine platforms.
Market Dynamics
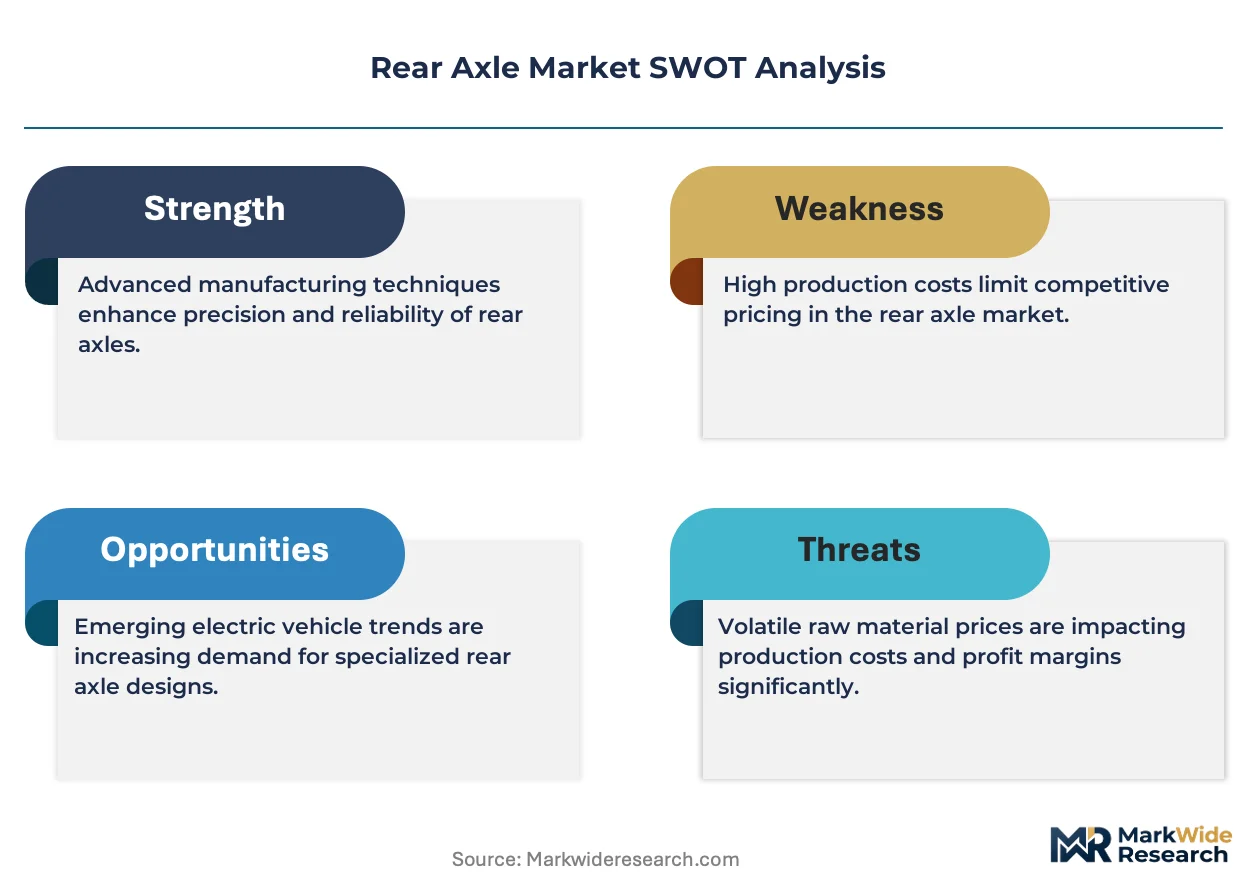
The central tension in the rear axle market stems from the divergent engineering paths required for legacy internal combustion engine platforms versus new battery electric vehicle architectures, forcing difficult capital allocation decisions upon component manufacturers.
Growth Catalysts
- Heavy Truck Demand:Expansion in e-commerce logistics and government-led infrastructure projects, particularly in Asia, sustains demand for robust tandem and tri-axle configurations for heavy commercial vehicles.
- Lightweighting Initiatives:The push for improved fuel economy and extended electric vehicle range drives the adoption of axles made from aluminum and composite materials, creating value-added opportunities.
- Efficiency Regulations:Mandates like the EU Green Deal framework and US EPA standards for powertrain efficiency compel fleets to upgrade to axles with lower friction and optimized gear ratios.
Market Restraints
- Raw Material Volatility:Price fluctuations in high-strength steel and aluminum, the core materials for axle manufacturing, directly impact production costs and place pressure on supplier margins.
- High R&D Investment:Developing next-generation e-axles and lightweight components requires significant upfront research and development expenditure with long payback periods, posing a barrier for smaller players.
- Manufacturing Complexity:The shift from traditional steel axle manufacturing to working with advanced composites and integrated electronics demands new production processes and specialized equipment.
Strategic Opportunities
- Integrated E-Axle Systems:Designing and supplying fully integrated e-axle modules, which combine the motor, inverter, and gearbox, presents a significant opportunity to capture more value within the EV powertrain.
- Predictive Maintenance Subscriptions:Embedding sensors in axles to monitor for wear and performance allows for the creation of recurring revenue streams through software and data-analytics services for fleet operators.
- Aftermarket for Electrified Fleets:As the first generation of commercial electric vehicles ages, a new aftermarket for specialized EV axle repair, refurbishment, and replacement will emerge.
Industry Challenges
- Talent Skill Gaps:A scarcity of engineers with combined expertise in mechanical systems, power electronics, and software development hinders the creation of advanced, software-defined axle systems.
- Capital-Intensive Retooling:Upgrading or building new manufacturing facilities to produce lightweight aluminum or composite axles for EV platforms requires substantial capital investment.
- Divergent Standards Compliance:Manufacturers face increased design and testing costs to ensure products comply with differing regional regulations, such as China's GB standards and North American safety rules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rear Axle Market |
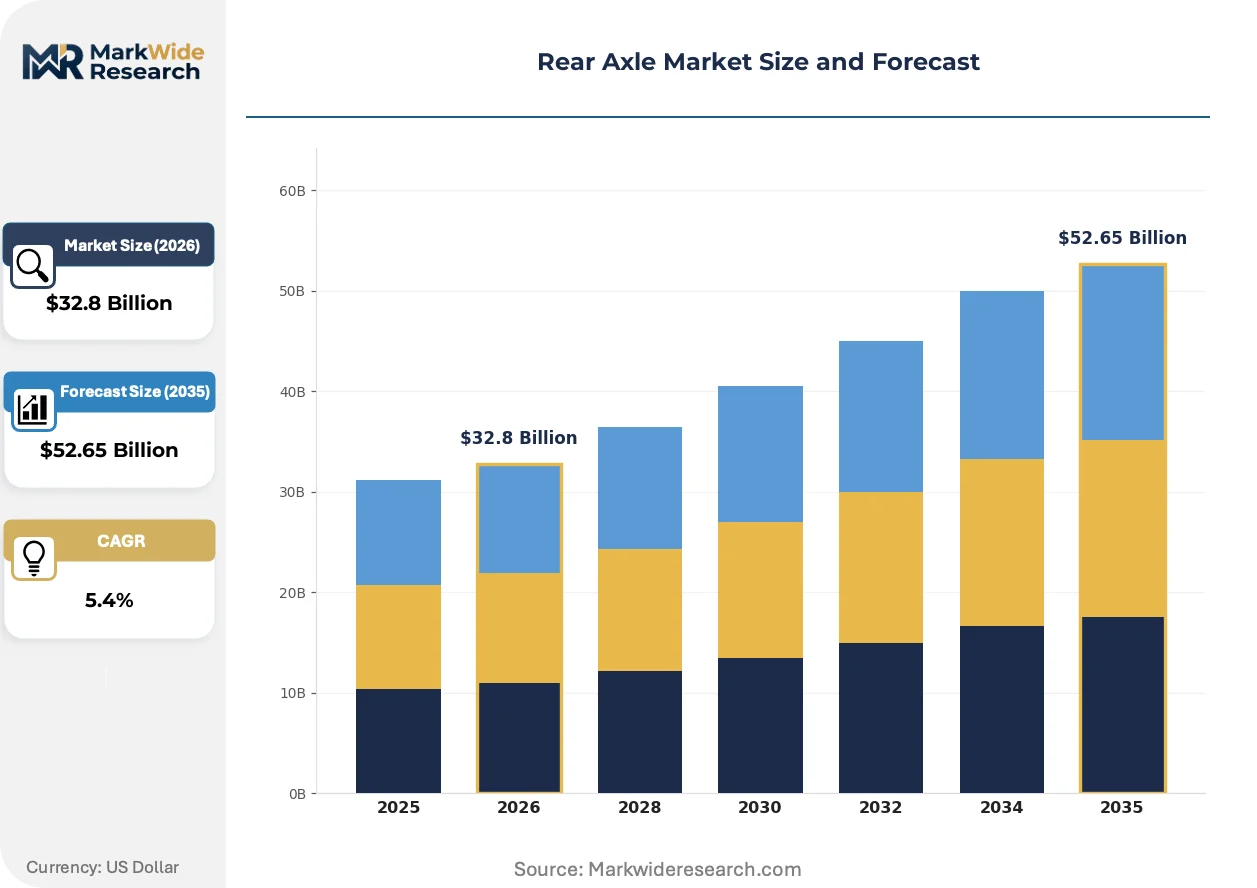
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $52.65 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Vehicle Type: Passenger Cars, Light Trucks, Heavy Trucks, Buses Axle Configuration: Single Axle, Tandem Axle, Tri-axle, Lift Axle Material Type: Steel, Aluminum, Composite, Cast Iron Application Area: OEMs, Aftermarket, Commercial Use, Recreational Vehicles |
| Companies Covered | American Axle & Manufacturing, Inc., Dana Incorporated, ZF Friedrichshafen AG, GKN Automotive Limited, Hyundai WIA Corporation, Meritor, Inc., BENTELER International Aktiengesellschaft, Marelli Holdings Co., Ltd., Automotive Axles Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rear Axle Market Strategic Shifts & Innovations
The evolution from a hardware-centric model to a systems-based approach defines the rear axle market. Performance is increasingly dictated by the intelligent integration of mechanical components with sophisticated software controls, recalibrating competitive advantage around system-level expertise.
Software-defined torque vectoring utilizes advanced control algorithms to precisely manage power delivery to individual wheels, significantly improving vehicle stability and traction. This technology is seeing rapid adoption in the premium passenger and performance electric vehicle segments. This software capability is integrating the once-passive mechanical axle into the vehicle's core electronic architecture, transforming it into an active chassis control system.
Regulations from the US EPA, specifically the Phase 2 GHG standards for heavy-duty trucks, impose strict targets for powertrain efficiency. These rules create direct pressure on manufacturers to minimize parasitic energy losses within the drivetrain. Consequently, the heavy truck segment is accelerating its adoption of low-friction bearings, advanced lubricants, and optimized gear designs to meet compliance.
Fleet operators are shifting their focus from the initial purchase price of components to the total cost of ownership over the vehicle's lifecycle. This change disrupts the traditional transactional sales model, favoring suppliers who can provide integrated axle systems bundled with predictive maintenance analytics. This demand-side shift is most pronounced within the commercial logistics sector in Europe, where uptime and fuel efficiency are paramount.
Rear Axle Market Segmentation
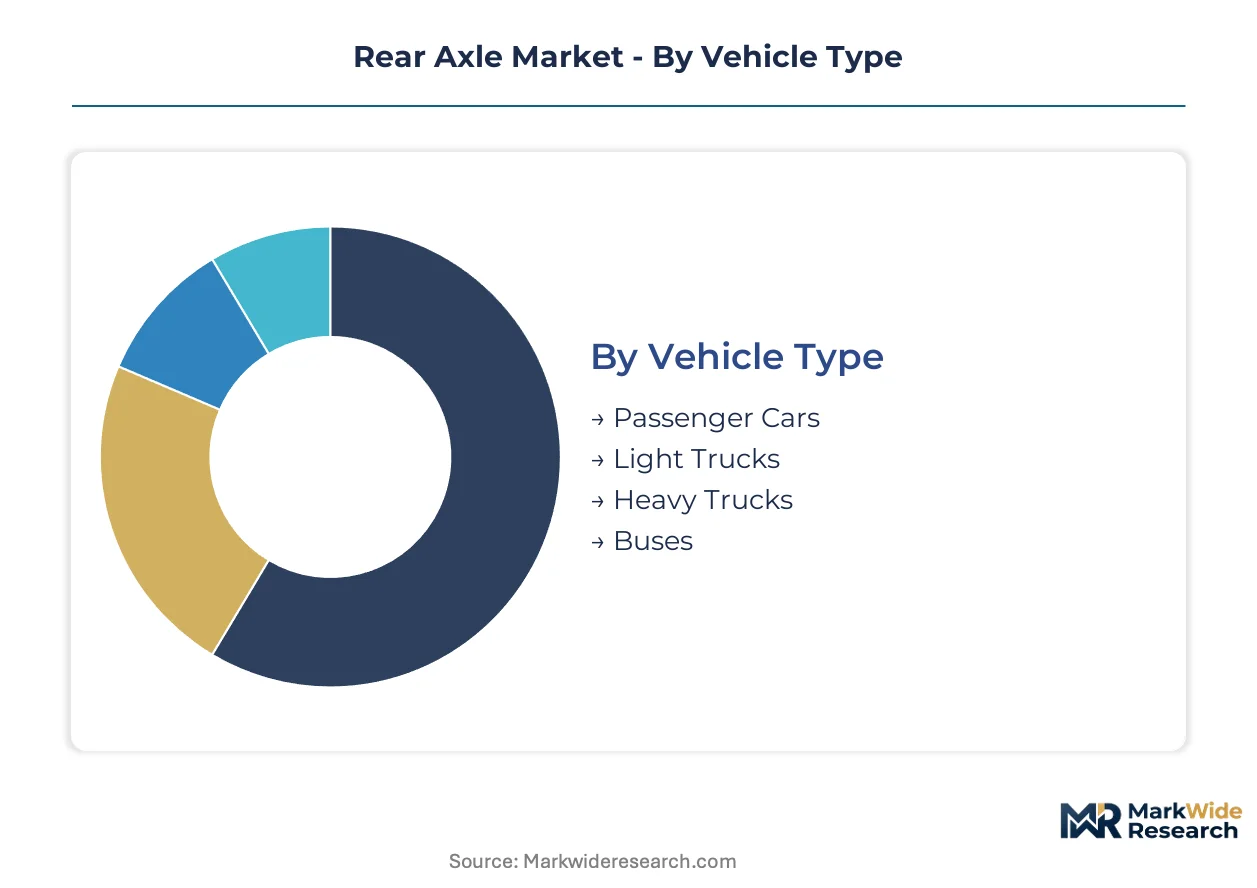
The rear axle market's segmentation reveals the diverse engineering requirements and application-specific demands driving product development. Understanding these distinct segments is crucial for manufacturers to align their investment strategies with evolving vehicle architectures and operational needs.
Vehicle Type:
The integration depth of rear axles varies significantly by vehicle type, ranging from standalone mechanical systems to fully integrated e-axle modules within electrified platforms.
- Heavy Trucks:These axles are engineered for extreme load capacities and continuous operation, often featuring robust tandem or tri-axle configurations. Demand is concentrating in China and India due to sustained e-commerce logistics and government-led infrastructure projects.
- Light Trucks:Axles for light trucks prioritize a balance of payload capability and fuel efficiency, frequently incorporating advanced materials and optimized gear ratios. North American markets show strong demand, driven by consumer preferences for utility vehicles and commercial last-mile delivery fleets.
- Passenger Cars:Rear axles in passenger cars focus on ride comfort, handling dynamics, and noise reduction, with lightweight designs increasingly prevalent.
- Buses:These components are designed for high durability and passenger safety, supporting public transportation networks in urban and intercity environments.
Heavy Trucks leads volumes today; Light Trucks is gaining share fastest.
Axle Configuration:
Application focus dictates the specific axle configuration, with specialized setups addressing varied load distribution and traction requirements across different vehicle categories.
- Tandem Axle:This configuration features two drive axles working in unison, providing superior load-carrying capacity and improved traction for heavy-duty applications. Tandem axles see significant use in long-haul trucking and construction vehicles across Europe.
- Tri-axle:Offering the highest load distribution and stability, tri-axle systems are essential for specialized heavy transport, such as crane carriers and oversized cargo vehicles. Demand for these highly specialized units is strong in mining operations in Australia and South America.
- Single Axle:A common configuration for passenger cars and lighter commercial vehicles, a single axle transfers power to a single pair of wheels.
- Lift Axle:These auxiliary axles can be raised or lowered to adjust load distribution and reduce tire wear when not carrying a full load.
Demand for Single Axle remains dominant, while Tri-axle exhibits strong growth in specialized niches.
Material Type:
The maturity of material technology influences axle design, with traditional metals offering proven performance and newer composites providing lightweighting advantages for efficiency gains.
- Steel:High-strength steel remains the primary material for rear axles due to its durability, cost-effectiveness, and established manufacturing processes. This material is widely used in heavy trucks and commercial vehicles, particularly in Asian markets.
- Aluminum:Aluminum axles offer significant weight reduction, contributing to improved fuel economy and extended electric vehicle range, particularly in passenger car and light truck segments. European vehicle manufacturers are increasingly specifying aluminum for their new platforms.
- Composite:These advanced materials offer superior strength-to-weight ratios and design flexibility, though their higher cost and manufacturing complexity limit broader adoption.
- Cast Iron:A traditional material offering good vibration damping and cost efficiency, cast iron is still utilized in specific heavy-duty and older vehicle applications.
Traditional Steel materials maintain market share, but Aluminum materials are transforming vehicle design.
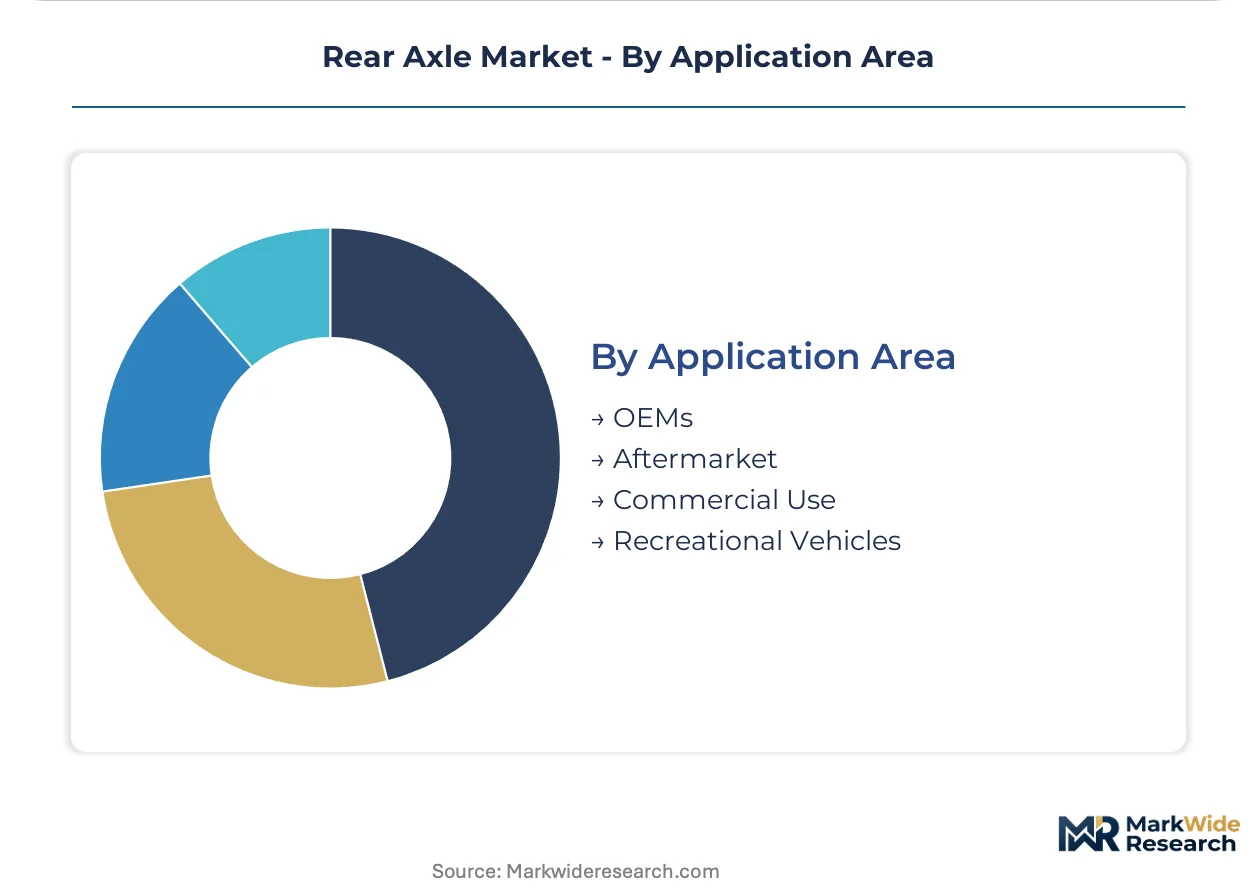
Application Area:
Customer type defines the application area, segmenting the market between new vehicle production and the ongoing maintenance and upgrade needs of existing fleets.
- OEMs:Original Equipment Manufacturers integrate rear axles directly into new vehicle production lines, requiring high-volume supply and adherence to specific design and performance standards. OEMs in Germany and Japan drive demand for advanced, customized axle solutions.
- Aftermarket:This segment caters to the replacement, repair, and upgrade needs of vehicles already in operation, including parts for maintenance and performance enhancements. The aftermarket for heavy trucks is substantial across North America, supporting vast logistics fleets.
- Commercial Use:This category encompasses axles for vehicles primarily used in business operations, such as delivery vans, buses, and construction equipment.
- Recreational Vehicles:Axles designed for RVs and other leisure vehicles prioritize durability and smooth operation over varied terrains.
The OEMs channel dictates initial product specifications, with Aftermarket becoming increasingly strategic for lifecycle revenue.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While China's commercial vehicle manufacturing base drives substantial rear axle demand, the United States focuses on light truck applications. European markets emphasize efficiency regulations, influencing design and material choices. Developing regions like India and Brazil are expanding their logistics infrastructure, requiring robust axle systems.
China
Sustained e-commerce logistics and infrastructure projects fuel demand for heavy truck axles in China. The country's GB standards impose strict safety and performance criteria for commercial vehicle components. Manufacturing hubs in the Yangtze River Delta, such as Shanghai, are centers for high-volume axle production.
United States
Consumer preferences for utility vehicles and last-mile delivery fleets sustain strong demand for light truck axles. US EPA standards, particularly Phase 2 GHG regulations, push for greater powertrain efficiency. Detroit's automotive cluster remains a key area for axle R&D, integrating lightweight materials.
Germany
European vehicle manufacturers, particularly in Germany, drive demand for advanced axle solutions for passenger cars and heavy trucks. The EU Green Deal framework compels fleets to upgrade to lower friction axles. Stuttgart and Munich automotive centers concentrate on integrated e-axle development and high-performance component manufacturing.
India
Expanding logistics networks and infrastructure development projects in India sustain demand for robust tandem and tri-axle configurations. The country's vehicle emission norms and road safety regulations influence axle specifications. Chennai and Pune are emerging as significant manufacturing hubs for commercial vehicle axles.
Brazil
Logistics expansion and agricultural sector growth generate demand for durable axles in Brazil's heavy and light commercial vehicle segments. National automotive regulations and emission standards encourage the adoption of more efficient drivetrain components. São Paulo's industrial belt serves as a primary production and distribution center for automotive parts.
Rear Axle Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with some focusing on high-value e-axle systems and others on traditional component supply. The market structure exhibits a tiered consolidation, where large, diversified players compete with niche component suppliers. Strategic archetypes include integrated system providers, material innovation leaders, and regional manufacturing specialists. Companies are primarily engaging in portfolio diversification towards electrification and strategic partnerships to develop integrated e-axle modules.
Specialists in integrated axle systems and electrification solutions include Dana Incorporated, which leverages its expertise to integrate smart features into axle systems. ZF Friedrichshafen AG exemplifies a comprehensive portfolio approach, spanning from conventional to electric driveline components across various vehicle types. American Axle & Manufacturing, Inc. occupies a position focused on manufacturing efficiency and supply chain control for specific light truck applications, sustaining its market presence through operational excellence.
| Leading Market Players |
|---|
| American Axle & Manufacturing, Inc. |
| Dana Incorporated |
| ZF Friedrichshafen AG |
| GKN Automotive Limited |
| Hyundai WIA Corporation |
| Meritor, Inc. |
| BENTELER International Aktiengesellschaft |
| Marelli Holdings Co., Ltd. |
| Automotive Axles Limited |
Cost & Logistics Intelligence
The clear divergence between advanced e-axle systems and traditional mechanical axles defines pricing and supply chain configurations. This gap shapes both pricing power and material sourcing strategies for manufacturers.
Pricing Analysis
Capacity additions in China are reshaping price floors for standard steel axles. Per-unit transactional pricing dominates, but integrated e-axle modules command value-based premiums. Price differentiation arises from performance specifications, brand reputation, and comprehensive after-sales service. Pricing softness stems from raw material volatility, impacting supplier margins. The commercial logistics sector in Europe exhibits lower price sensitivity for uptime, while OEMs prioritize initial component cost.
Supply Chain Analysis
Regional distribution centers and hub-and-spoke patterns characterize the aftermarket for rear axles. Geographic supply concentrates in manufacturing hubs across China, Germany, and the United States. Production relies on high-strength steel, aluminum, and critical power electronics components. Commodity price volatility represents a structural supply chain risk. Distribution runs through direct OEM channels and a network of specialized aftermarket distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rear axle market offers significant margin expansion opportunities. This potential is driven by the premium pricing of integrated e-axle systems and software-defined functionalities.
For Market Incumbents: Cement leadership by investing heavily in advanced lightweight materials R&D for composite axles. Expand e-axle production capacity in Germany to counter emerging e-axle specialists. Form strategic partnerships for software integration to embed predictive maintenance capabilities. This defends against margin erosion from stringent EU Green Deal regulations.
For New Entrants and Emerging Players: US EPA standards in the United States open a window for specialized e-axle modules targeting urban delivery vehicles. Focus on the aftermarket for EV conversions, particularly for last-mile delivery fleets in North America. Offer bundled hardware-software solutions that emphasize total cost of ownership. This strategy bypasses high capital requirements for traditional OEM supply.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized technology firms integrating software into axle systems. The long-term viability favors component suppliers who can transition from hardware-centric to systems-based offerings. Target niche providers of torque vectoring software or advanced composite manufacturing capabilities. Increased OEM outsourcing of e-axle development serves as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| E-Axle Module Development | Integrates motor, inverter, and gearbox, capturing more value in the EV powertrain. |
| Lightweight Material R&D | Reduces vehicle weight, directly improving fuel efficiency and electric vehicle range. |
| Predictive Maintenance Platform | Creates recurring revenue streams through data analytics for fleet operators. |
| Global Manufacturing Footprint | Mitigates regional supply chain risks and optimizes delivery to key OEM markets. |
| Software-Defined Torque Vectoring | Enhances vehicle stability and traction, transforming axles into active chassis systems. |
Research Approach
Direct dialogue with R&D directors, procurement managers, fleet operators, and material scientists formed the primary research. This was validated by extensive secondary research from vehicle production databases, US EPA and EU Green Deal regulations, and corporate financial reports. Bottom-up data aggregation and top-down market sizing ensured robust data triangulation.
A bottom-up approach quantified granular segments, while top-down analysis validated overall market size across the analysis window. Segmentation dimensions modeled included vehicle type, axle configuration, material type, application area, and regional production clusters. Compound annual growth rates were derived from historical data analysis and projected market shifts. Key forecast inputs included vehicle electrification rates and global infrastructure spending.
Revisions become necessary when raw material price shocks or significant regulatory changes materialize. Forecasts reflect assumptions regarding technological adoption and economic stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Automotive Battery Terminals Market
Vehicle Components
Snowplows Market
Vehicle Components
Bicycle Accessories Market
Vehicle Components
Navigation Light Market
Vehicle Components
Global Electric Vehicle Parts and Components Market
Vehicle Components
Vehicle-To-X Products Market
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Global Air Spring Components Market
Vehicle Components
South Africa Automotive Thermoplastic Polymer Composites Market
Vehicle Components
Automotive Displacement Sensor Market
Vehicle Components
Automotive Aftermarket Shock Absorbers Market
Vehicle Components
Two-Wheeled Containers Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market