
 Tow Tractor Market | 2026-2036
Tow Tractor Market Size, Share, and Industry Trends Forecast 2026-2036
Tow Tractor Market Analysis
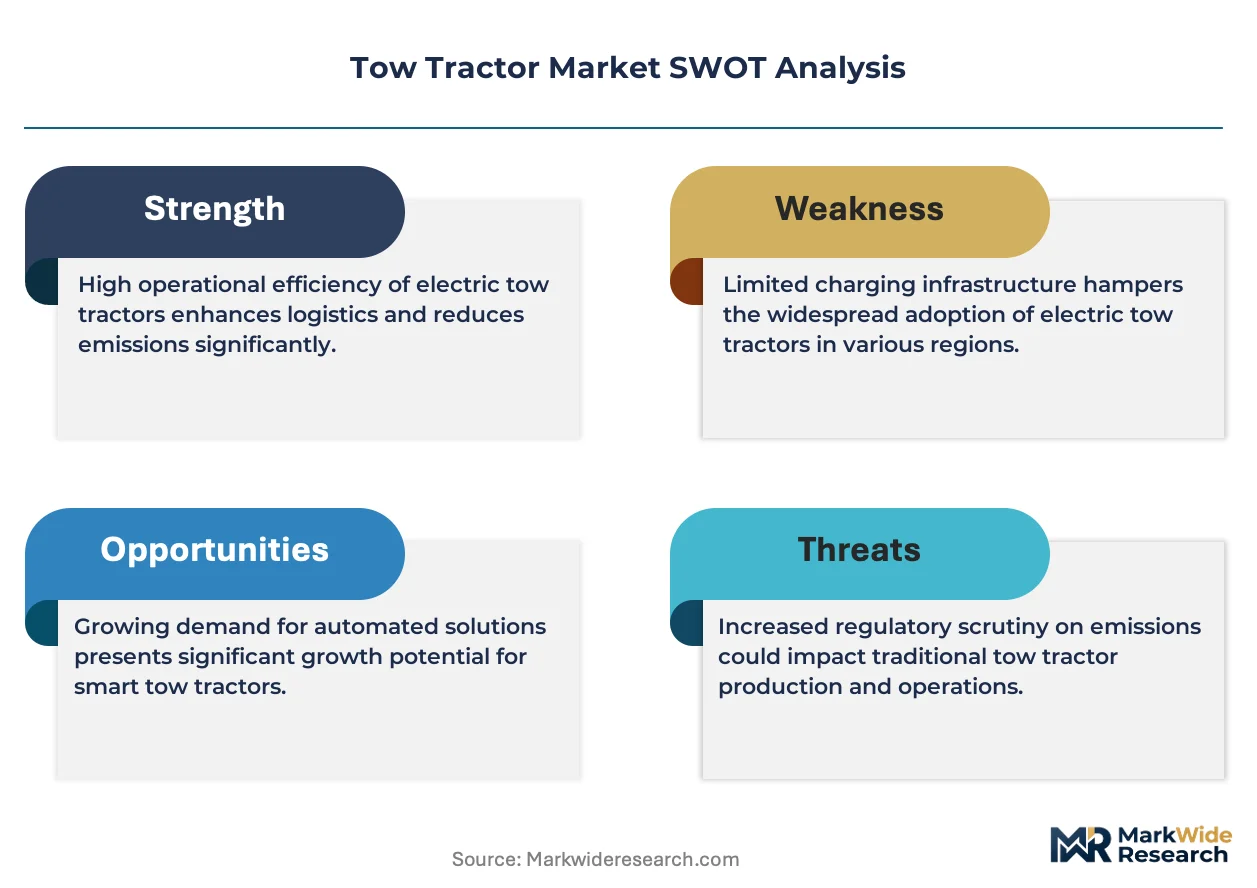
ISO 3691-6 safety certification for industrial trucks is unwinding the competitive landscape for tow tractor suppliers, forcing smaller assemblers to retool braking and stability systems. Toyota Material Handling leverages its captive lithium-ion cell production to control battery pack costs across electric tow tractor lines. Jungheinrich AG anchors its position through integrated fleet management software that ties tow tractors to warehouse execution systems. Hyster-Yale Materials Handling competes on manufacturing scale, operating dual assembly plants in North America and Europe to shorten delivery lead times.
A tow tractor is a powered industrial vehicle designed to pull wheeled loads, typically rated from 2,000 kg to 50,000 kg drawbar pull, using electric AC drive motors or internal combustion engines to move carts through manufacturing plants, airport aprons, and distribution centers. Electric tow tractors dominate procurement in warehousing applications where zero-emission mandates restrict diesel equipment, while diesel variants retain share in outdoor aviation and shipping yards lacking charging infrastructure. Automated tow tractors represent the fastest-expanding technology segment as logistics providers retrofit distribution centers with magnetic tape and LiDAR-guided tugger trains to reduce labor dependency in repetitive horizontal transport loops.
FAA ground support equipment directives and OSHA powered industrial truck standards shape product design requirements for braking performance and operator visibility in the United States, while the EU Machinery Directive and CE marking govern tow tractor safety architecture across Europe. EPA Tier 4 Final and Euro Stage V emissions regulations are accelerating diesel model phase-outs in favor of electric and hybrid platforms. Stakeholders must monitor battery supply chain bottlenecks and charging infrastructure build-out pace when committing to fleet electrification roadmaps.
Market Dynamics
The tow tractor market is pivoting around electrification mandates and battery supply chain localization, with airport authorities and warehouse operators facing simultaneous pressure to decarbonize fleets while securing lithium-ion cell availability.
Growth Catalysts
- EU Green Deal fleet mandates:European distribution centers must replace diesel tow tractors with electric variants by 2030, accelerating procurement cycles for AC drive motor systems.
- Aviation ground support expansion:Hub-and-spoke logistics networks in Germany, the United States, and China require high-availability electric tugs to support narrow-body aircraft turnaround times.
- Lithium iron phosphate chemistry:Extended duty cycles and reduced recharge windows enable 24-hour continuous operations in automotive assembly plants.
Market Restraints
- Battery raw material concentration:Cathode active material processing clusters in China create supply vulnerability for European and North American tow tractor assemblers.
- Charging infrastructure gaps:Outdoor aviation and shipping yards lack grid capacity for high-power DC fast charging, preserving diesel tow tractor share in these segments.
- OSHA powered industrial truck standards:Compliance costs for braking performance and operator visibility systems compress margins for smaller regional suppliers.
Strategic Opportunities
- India warehouse automation:E-commerce fulfillment centers in Mumbai and Delhi-NCR present underpenetrated demand for automated tow tractor fleets.
- FAA NextGen ground support integration:Telematics-enabled tow tractors can feed real-time equipment location data into airport collaborative decision-making systems.
- Magnetic tape and LiDAR convergence:Retrofit automation kits allow logistics providers to convert manual tugger trains to autonomous operation without infrastructure overhaul.
Industry Challenges
- ISO 3691-6 certification timelines:Smaller assemblers face 18-24 month retooling periods to meet updated braking and stability system requirements.
- Legacy warehouse management system integration:Automated tow tractor fleets require API-level connectivity to existing execution software, complicating deployment in brownfield facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tow Tractor Market |
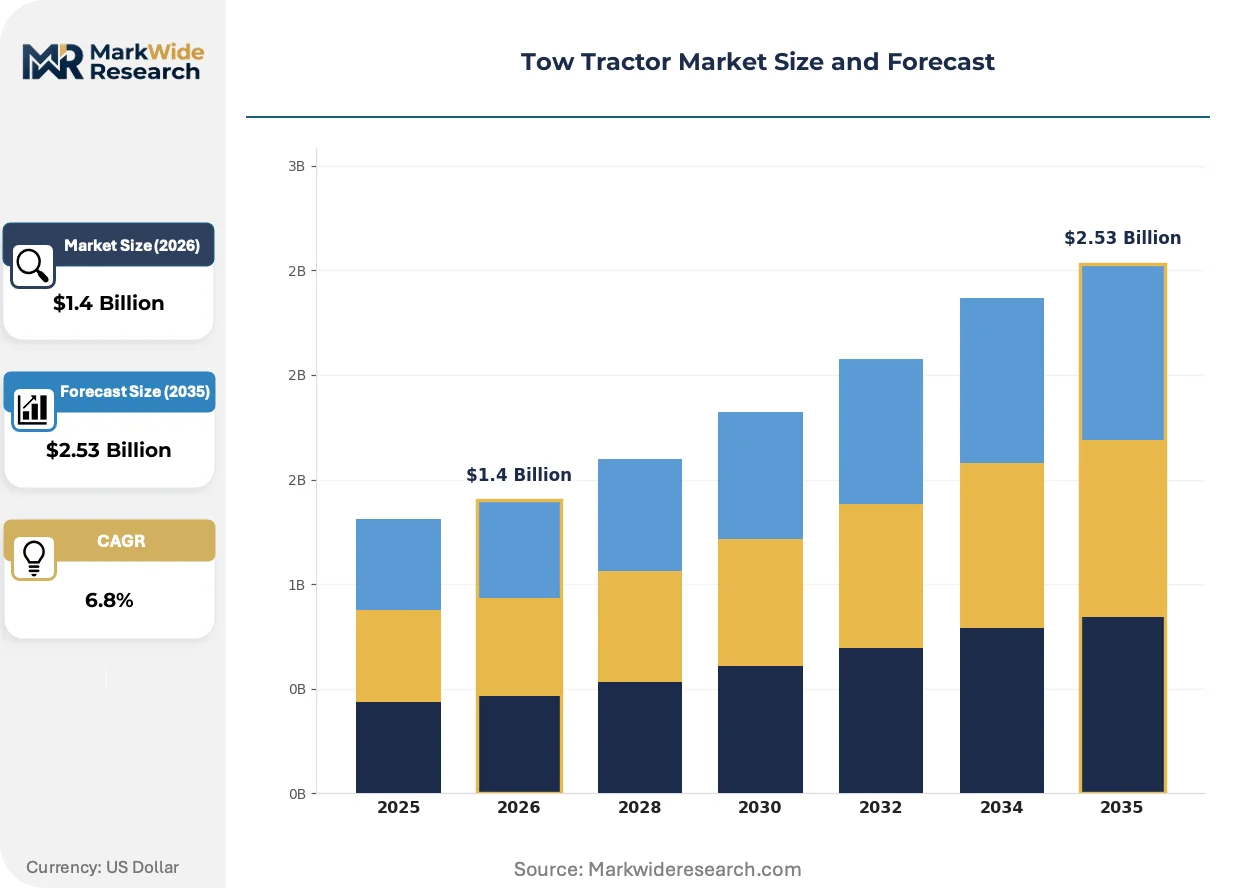
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.53 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric Tow Tractor, Diesel Tow Tractor, Hybrid Tow Tractor, Manual Tow Tractor Application: Aviation, Warehousing, Shipping, Manufacturing End User: Logistics Providers, Airport Authorities, Retailers, Industrial Facilities Technology: Automated Tow Tractors, Conventional Tow Tractors, Smart Tow Tractors, Gas Tow Tractors |
| Companies Covered | Toyota Material Handling, Linde Material Handling, Jungheinrich AG, Hyster-Yale Materials Handling, Crown Equipment Corporation, Clark Material Handling Company, The Raymond Corporation, Eagle Tugs, Alke, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tow Tractor Market Emerging Trajectories
Electrification and automation are converging to redefine tow tractor architecture, with battery chemistry advances enabling new operational models while regulatory pressure compresses diesel equipment lifecycles.
Lithium iron phosphate battery packs are supplanting lead-acid and nickel-manganese-cobalt alternatives in heavy-duty tow tractor applications. Airport authorities in the United States and Germany are specifying these systems for apron operations where thermal stability and fast-charge capability reduce ground time. The chemistry shift is compressing total cost of ownership calculations and displacing diesel-electric hybrid configurations from procurement shortlists.
EPA Tier 4 Final and Euro Stage V emissions regulations are accelerating diesel model phase-outs across ground support equipment fleets. These rules impose particulate matter and nitrogen oxide limits that require expensive exhaust after-treatment, making pure electric platforms economically competitive on a lifecycle basis. Aviation segments in California and the Netherlands are responding fastest, with airport authorities embedding zero-emission mandates into ground handling concession agreements.
Leasing and equipment-as-a-service models are displacing capital purchase arrangements in mid-sized logistics operations. Third-party fleet management providers now bundle tow tractors with predictive maintenance software and guaranteed uptime commitments. This shift is most visible in German automotive supply chain networks, where just-in-sequence delivery contracts demand equipment availability guarantees that owner-operators struggle to match.
Tow Tractor Market Segmentation
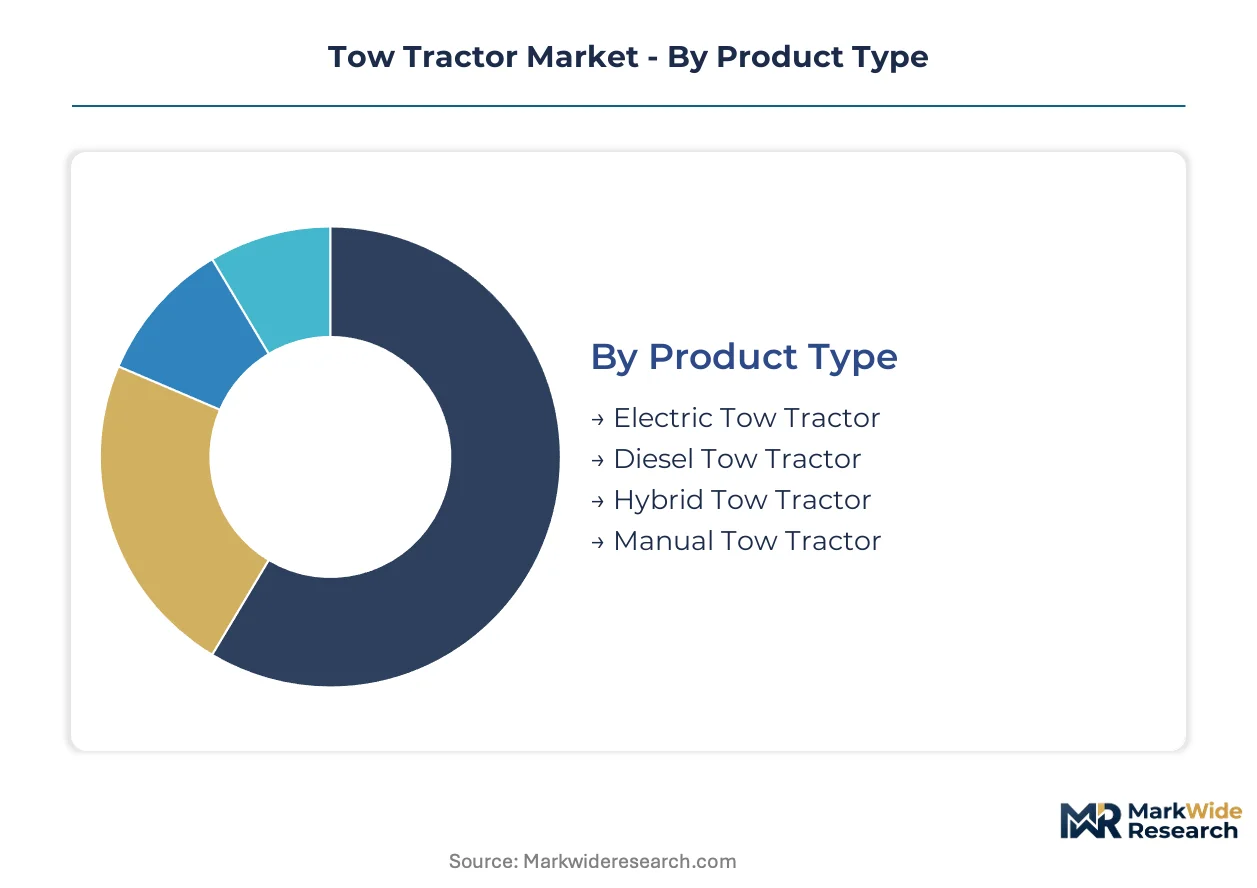
Tow tractor procurement patterns diverge sharply across product architectures and operational environments. Electrification mandates and automation roadmaps are compressing legacy segment lifecycles while elevating premium technology tiers.
Product Type:
Electric tow tractors face the most intense substitution pressure as diesel variants confront emissions phase-outs and manual equipment loses share to powered alternatives.
- Electric Tow Tractor:AC drive motor systems rated from 2,000 kg to 50,000 kg drawbar pull dominate warehouse procurement where zero-emission mandates restrict diesel equipment. German automotive assembly plants and California distribution centers specify lithium iron phosphate packs for 24-hour continuous operations.
- Diesel Tow Tractor:Internal combustion engines retain foothold in outdoor aviation and shipping yards lacking charging infrastructure. EPA Tier 4 Final and Euro Stage V after-treatment costs are eroding lifecycle economics against electric platforms.
- Hybrid Tow Tractor:Diesel-electric configurations occupy narrowing niche in mixed indoor-outdoor operations. Airport authorities in the Netherlands are embedding zero-emission mandates into ground handling concessions that exclude hybrid equipment.
- Manual Tow Tractor:Human-powered units persist in small-scale retail backrooms and legacy manufacturing cells. E-commerce fulfillment velocity requirements are displacing these systems from new facility designs.
Electric tow tractors anchor the volume base while automated variants gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive aviation deployments from high-volume warehousing contracts with compressed payback horizons.
- Aviation:Narrow-body aircraft turnaround requirements demand high-availability electric tugs with FAA-compliant braking and visibility systems. Hub airports in Germany, the United States, and China specify telematics-enabled units for collaborative decision-making integration.
- Warehousing:E-commerce fulfillment centers in Mumbai and Delhi-NCR drive demand for automated tugger trains in repetitive horizontal transport loops. Magnetic tape and LiDAR retrofit kits allow brownfield automation without infrastructure overhaul.
- Shipping:Container yards lacking grid capacity preserve diesel equipment share despite emissions regulations. OSHA powered industrial truck standards govern braking performance in US port operations.
- Manufacturing:Just-in-sequence delivery contracts in German automotive supply chains demand equipment availability guarantees. Leasing and equipment-as-a-service models are displacing capital purchases in this segment.
Warehousing applications lead volume concentration while aviation commands the highest unit economics.
End User:
Customer type determines procurement sophistication, with logistics providers adopting fleet management software while industrial facilities lag in connectivity integration.
- Logistics Providers:Third-party operators bundle predictive maintenance software with guaranteed uptime commitments. API-level connectivity to warehouse execution systems is becoming a procurement prerequisite.
- Airport Authorities:Ground handling concession agreements increasingly embed zero-emission equipment mandates. FAA NextGen integration requirements favor telematics-enabled electric platforms.
- Retailers:Omnichannel fulfillment networks require flexible tow tractor fleets scaling between store replenishment and direct-to-consumer operations. Smaller regional suppliers struggle with ISO 3691-6 certification compliance costs.
- Industrial Facilities:Brownfield manufacturing plants face legacy warehouse management system integration barriers for automated tow tractor deployment. Brownfield automation retrofit kits are penetrating this resistant segment.
Logistics providers anchor fleet modernization spending while airport authorities set the steepest electrification timelines.
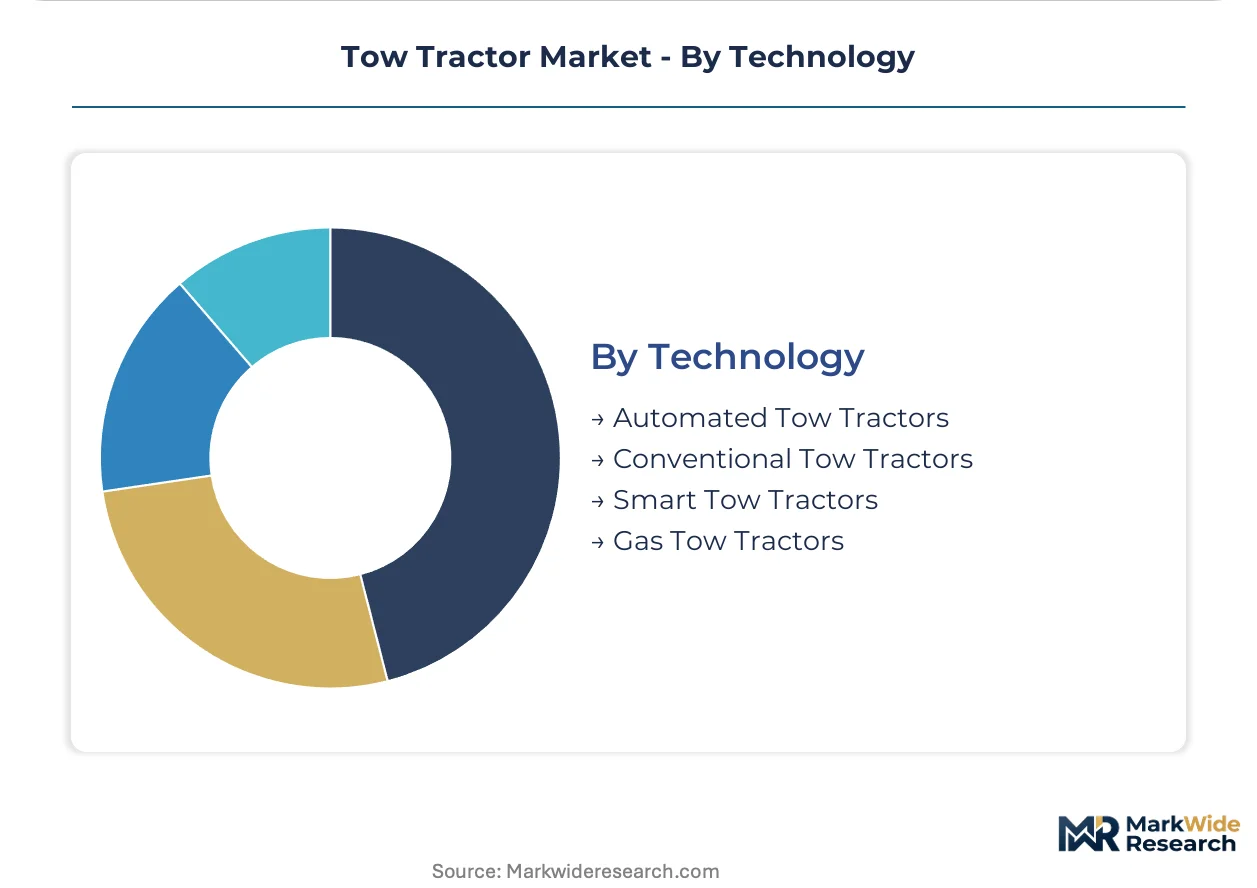
Technology:
Supply concentration in battery cell production is tilting competitive advantage toward assemblers with captive lithium-ion supply or deep supplier partnerships.
- Automated Tow Tractors:Magnetic tape and LiDAR-guided systems reduce labor dependency in repetitive transport loops. Retrofit automation kits are expanding addressable market beyond greenfield facilities.
- Conventional Tow Tractors:Human-operated electric and diesel units remain majority share in transitional fleets. Smaller assemblers face 18-24 month retooling periods for ISO 3691-6 braking and stability compliance.
- Smart Tow Tractors:Telematics-enabled platforms feed real-time location data into airport collaborative decision-making systems. Predictive maintenance algorithms are compressing total cost of ownership calculations.
- Gas Tow Tractor:LPG and CNG variants occupy declining niche in indoor applications with ventilation constraints. Electrification is displacing these systems from procurement shortlists.
Conventional technology anchors installed base volumes while automated platforms climb the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FAA ground support equipment directives and EU Green Deal fleet mandates are accelerating electric tow tractor procurement across aviation and logistics clusters. Battery supply chain localization and charging infrastructure build-out pace vary sharply by jurisdiction.
United States
Aviation ground support expansion at hub airports drives electric tug demand for narrow-body aircraft turnaround operations. FAA NextGen integration requirements favor telematics-enabled platforms feeding real-time location data into collaborative decision-making systems. California distribution centers specify lithium iron phosphate packs for 24-hour continuous operations under state zero-emission mandates.
Germany
Automotive assembly plants demand equipment availability guarantees for just-in-sequence delivery contracts in supply chain networks. EU Machinery Directive and CE marking govern tow tractor safety architecture while EU Green Deal mandates diesel replacement by 2030. Bavaria-based logistics providers bundle predictive maintenance software with guaranteed uptime commitments.
China
Hub-and-spoke logistics networks require high-availability ground support equipment for aviation and e-commerce fulfillment operations. GB standards and dual carbon goals from MEE accelerate electric fleet transitions in manufacturing and warehousing. Yangtze River Delta distribution centers retrofit magnetic tape and LiDAR-guided tugger trains for automation.
India
E-commerce fulfillment centers in Mumbai and Delhi-NCR present demand for automated tow tractor fleets in repetitive horizontal transport loops. BIS certification requirements and PLI scheme incentives support domestic assembly capacity expansion. Maharashtra-based warehouse operators face legacy management system integration barriers for brownfield automation deployment.
Netherlands
Airport authorities embed zero-emission mandates into ground handling concession agreements that exclude hybrid equipment. REACH and RoHS compliance shape battery chemistry selection for apron operations. Amsterdam-Schiphol logistics clusters specify pure electric platforms with fast-charge capability to reduce aircraft ground time.
Tow Tractor Market Vendor Landscape
Player mix skews toward diversified industrial truck manufacturers with captive powertrain capabilities. Market structure concentrates around integrated material handling groups and specialized aviation ground support suppliers. Strategic archetypes divide between battery-captive assemblers leveraging in-house cell production and software-integrated fleet management providers. Competitive moves center on manufacturing scale expansion and automation technology licensing partnerships.
Within the diversified industrial truck tier, Toyota Material Handling and Jungheinrich AG exemplify archetypes combining captive lithium-ion supply with integrated fleet management software. Hyster-Yale Materials Handling occupies a position representing scale-driven manufacturing with dual continent assembly footprints. Specialized aviation ground support sits with Eagle Tugs, which anchors the apron-specific equipment segment. These three company structures illustrate the competitive spectrum from diversified industrial conglomerates to focused aviation suppliers.
| Leading Market Players |
|---|
| Toyota Material Handling |
| Linde Material Handling |
| Jungheinrich AG |
| Hyster-Yale Materials Handling |
| Crown Equipment Corporation |
| Clark Material Handling Company |
| The Raymond Corporation |
| Eagle Tugs |
| Alke |
| Others |
Supply Flow & Price Mechanics
Eighteen-to-twenty-four-month lead times for ISO 3691-6 certification compliance concentrate pricing power with diversified industrial truck manufacturers possessing captive engineering resources, while smaller assemblers absorb margin compression from retooling costs and extended delivery windows.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with CE-marked and FAA-compliant units commanding substantial premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects bundling of fleet management software and predictive maintenance guarantees. Cost compression in the standard tier intensifies because lithium iron phosphate battery pack commoditization erodes differentiation. Logistics providers show least price sensitivity due to equipment-as-a-service uptake, while regional retailers face acute margin pressure from ISO 3691-6 compliance investments.
Supply Chain Analysis
Extended lead times for lithium iron phosphate cathode active materials stretch 12-16 weeks for European and North American assemblers, reflecting geographic supply concentration in China, South Korea, and Japan. Battery cell production draws from processed lithium carbonate, electrolyte formulations, and copper foil current collectors. Single-source vulnerability concentrates in cathode precursor processing clusters. Distribution runs through OEM direct sales for aviation ground support and third-party fleet management providers for warehousing contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Tow tractor procurement cycles track aviation passenger volume recovery and e-commerce fulfillment expansion, positioning this market for cyclical uplift as hub-and-spoke logistics networks rebuild capacity.
For Market Incumbents: Secure backward integration into lithium iron phosphate cell supply or binding offtake agreements with cathode material processors to insulate margins from raw material volatility. Defend position by accelerating manufacturing scale expansion in dual-continent assembly footprints, shortening delivery lead times against emerging regional competitors. ISO 3691-6 certification investment represents a critical lever to exclude smaller assemblers from procurement shortlists. For New Entrants and Emerging Players: Predictive maintenance software integration gaps in brownfield manufacturing facilities present service-layer white space where incumbents under-serve. Target India's Mumbai and Delhi-NCR e-commerce fulfillment clusters as the most penetrable geography, where BIS certification requirements favor domestic assembly partnerships. Go-to-market angle centers on retrofit automation kits enabling magnetic tape and LiDAR conversion without warehouse management system overhaul. For Investors and Strategic Acquirers: Long-term, this sits as a fleet-as-a-service consolidation play because equipment availability guarantees displace capital purchases in German automotive supply chains and California distribution centers. Acquisition target archetype: regional assemblers with ISO 3691-6 compliance progress and established aviation ground support relationships. Signal to watch: FAA NextGen telematics integration mandates accelerating obsolescence of non-connected equipment.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Supply Agreement | Binding cathode material offtakes insulate margins from Chinese processing concentration. |
| Certification Investment | ISO 3691-6 compliance creates exclusionary barriers against smaller regional competitors. |
| Fleet Management Platform | API-level warehouse execution system integration locks in logistics provider switching costs. |
| Retrofit Automation Kit Development | Magnetic tape and LiDAR convergence expands addressable market beyond greenfield facilities. |
| Dual-Continent Manufacturing Footprint | Parallel assembly plants in North America and Europe compress delivery lead times. |
Methodological Framework
Desk research of customs trade databases, SEC filings from diversified industrial truck manufacturers, and aviation ground support equipment procurement records preceded structured interviews with maintenance directors at automotive assembly plants, airport ground handling operations managers, warehouse automation engineers at third-party logistics providers, and aftermarket service heads at material handling distributors. Primary fieldwork combined with secondary validation across FAA directive documentation, EU Machinery Directive implementation guidance, and battery chemistry patent filings. Bottom-up unit demand modeling triangulated against top-down fleet replacement cycle analysis.
Variance decomposition across product architecture, application environment, and technology tier informed segment-level growth trajectories over the projection horizon. Modeled dimensions span electric-diesel-hybrid-manual propulsion types, aviation-warehousing-shipping-manufacturing end uses, and automated-conventional-smart technology tiers. CAGRs derived from equipment replacement cycle analysis, electrification mandate compliance timelines, and automation retrofit penetration curves. Forecast inputs incorporate lithium iron phosphate battery cost trajectories and charging infrastructure build-out pace by jurisdiction.
Underlying assumptions cover regulatory mandate adherence timelines, battery chemistry substitution rates, and aviation traffic recovery patterns, with deviation risk concentrated in raw material supply disruptions and ISO 3691-6 certification timeline extensions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Driveline Systems for Electric Vehicle Market
Vehicle Components
Russia Automotive Composites Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Forklift Seats Market
Vehicle Components
United Kingdom Vacuum Truck Market
Vehicle Components
Fuel Sensor Market
Vehicle Components
Bicycle Chain Device Market
Vehicle Components
Trailer Canopy Market
Vehicle Components
Global Navigation Lighting Market
Vehicle Components
Bicycle Chain Market
Vehicle Components
Vehicle Pillar Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Locomotive Pantographs Market
Vehicle Components
EV Connectors Market
Vehicle Components
Car Modification Market
Vehicle Components
Crank Case Ventilation Valve Market