
 Wheel Seals Market | 2026-2036
Wheel Seals Market Size, Share, and Industry Trends Forecast 2026-2036
Wheel Seals Market Insights
Aftermarket service revenue is rewriting competitive economics across the wheel seals value chain. Stemco leverages its proprietary engineered sealing systems to capture recurring replacement demand from North American heavy-duty fleets. SKF sustains technology leadership through integrated sensor-enabled seal designs that monitor bearing condition in real time. Freudenberg Sealing Technologies anchors its position with backward integration into advanced elastomer compounding for extreme-temperature wheel end applications.
Wheel seals are precision-engineered closure devices manufactured from nitrile rubber, fluorocarbon compounds, or metal-reinforced composites, designed to exclude contaminants and retain lubricants within rotating wheel assemblies operating across temperature ranges exceeding 150°C. Rubber seals dominate unit volume in light-duty automotive applications where cost sensitivity and standardized geometries prevail, while composite seals command premium positioning in heavy equipment and agricultural machinery where abrasive environments and extended duty cycles demand multi-material barrier architectures. Elastomer seals represent the fastest-growing product category as formulation chemistry advances enable longer service intervals in commercial vehicle wheel ends.
The EPA regulates heavy-duty vehicle emissions and fuel efficiency standards that indirectly mandate seal integrity to maintain driveline efficiency, while NHTSA safety standards govern wheel end performance under severe braking and thermal loading conditions. China's MIIT enforces GB standards for commercial vehicle component durability that shape seal qualification requirements for suppliers targeting domestic OEMs. ISO contamination control standards further define performance benchmarks for seals deployed in precision gearboxes and transmissions. Stakeholders must monitor regulatory convergence around extended producer responsibility frameworks and decide whether to prioritize material recyclability or performance longevity in next-generation seal architectures.
Market Dynamics
Commercial vehicle fleet operators are consolidating maintenance spend around predictive replacement cycles as fluorocarbon elastomer chemistry extends seal life beyond traditional service intervals. This compression of replacement frequency is forcing suppliers to capture value through integrated sensor systems and aftermarket service bundling rather than unit volume alone.
Growth Catalysts
- EPA heavy-duty emissions standards:Mandates for driveline efficiency maintenance drive seal integrity requirements across North American commercial vehicle fleets.
- Fluorocarbon formulation advances:Extended service intervals under severe thermal and chemical exposure expand addressable fleet maintenance windows.
- China heavy-duty vehicle production:Concentrated OEM demand in Shandong and Hubei provinces anchors capacity expansion for domestic and export seal supply.
Market Restraints
- Fluorocarbon raw material concentration:Specialty polymer supply chains cluster with limited qualified compounders in Germany and Japan.
- Metal-reinforced composite cost structure:Multi-material barrier architectures carry 40-60% premium over nitrile rubber equivalents, constraining light-duty adoption.
- REACH substance restrictions:ECHA scrutiny of perfluorinated compounds creates compliance pathway uncertainty for next-generation formulations.
Strategic Opportunities
- India commercial vehicle aftermarket:Underdeveloped organized service infrastructure creates first-mover positioning for integrated seal-and-bearing replacement programs.
- Sensor-seal convergence:Real-time bearing condition monitoring embedded in wheel end architectures enables outcome-based fleet contracts.
- EU Green Deal extended producer responsibility:Material recyclability mandates favor suppliers with backward integration into reprocessable elastomer compounding.
Industry Challenges
- Fluorocarbon compounding expertise scarcity:Specialized polymer chemistry and high-temperature molding process knowledge concentrates among aging technical workforces in Germany and Japan.
- ISO contamination control certification timelines:Multi-year qualification protocols for precision gearbox applications delay new entrant market access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wheel Seals Market |
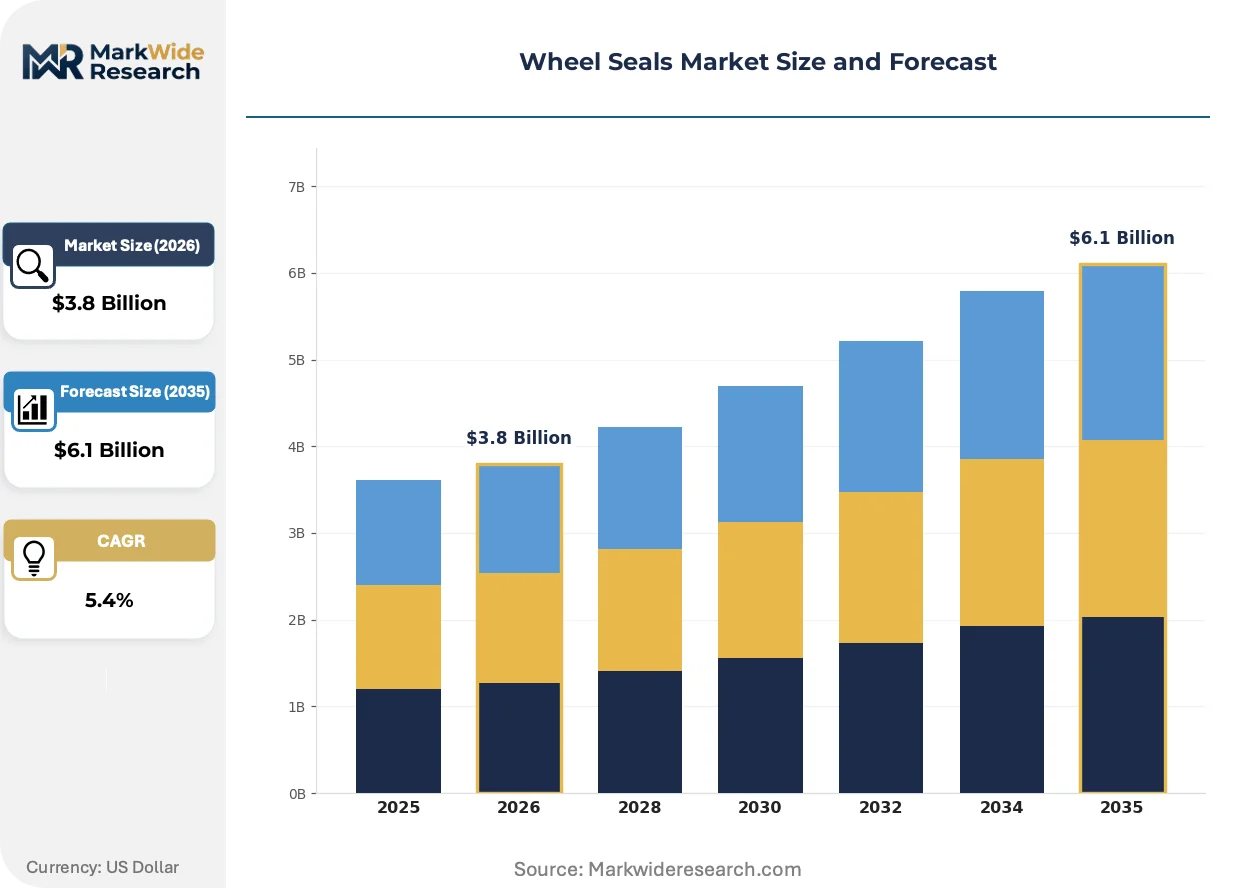
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.1 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rubber Seals, Metal Seals, Composite Seals, Elastomer Seals End User: Automotive OEMs, Commercial Vehicles, Heavy Equipment, Agricultural Machinery Application: Wheel Axles, Gearboxes, Transmissions, Suspension Systems Installation Method: Press-Fit, Bolt-On, Clip-On, Seamless |
| Companies Covered | Stemco, SKF, Dana Incorporated, Meritor, ACDelco, ConMet, Freudenberg Sealing Technologies, Timken Company, Trelleborg AB, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wheel Seals Market Trends and Innovations
Active sensor integration and predictive maintenance algorithms are redefining how wheel seals generate value, shifting revenue models from component supply to continuous condition monitoring services.
Multi-layer fluorocarbon-nitrile hybrid seals are collapsing the traditional trade-off between cost and temperature performance in commercial vehicle wheel ends. Tier 1 suppliers are adopting these architectures for 2026 platform launches. The technology is collapsing service interval differentiation between premium and standard fleet segments.
China's MIIT GB standards for commercial vehicle component durability are tightening qualification thresholds for domestic OEM supply. Foreign suppliers must demonstrate 500,000-kilometer validated life under combined thermal-mechanical loading. Heavy-duty truck manufacturers in Shandong and Hubei provinces are accelerating local seal qualification to meet 2026 model year requirements.
Fleet maintenance departments are unbundling seal replacement from bundled wheel end service packages, creating direct procurement relationships with specialized seal suppliers. Independent service networks in the US Midwest and German Ruhr region are capturing this disintermediation opportunity. The shift is most pronounced among operators with centralized procurement functions managing 1,000+ vehicle fleets.
Wheel Seals Market Segmentation
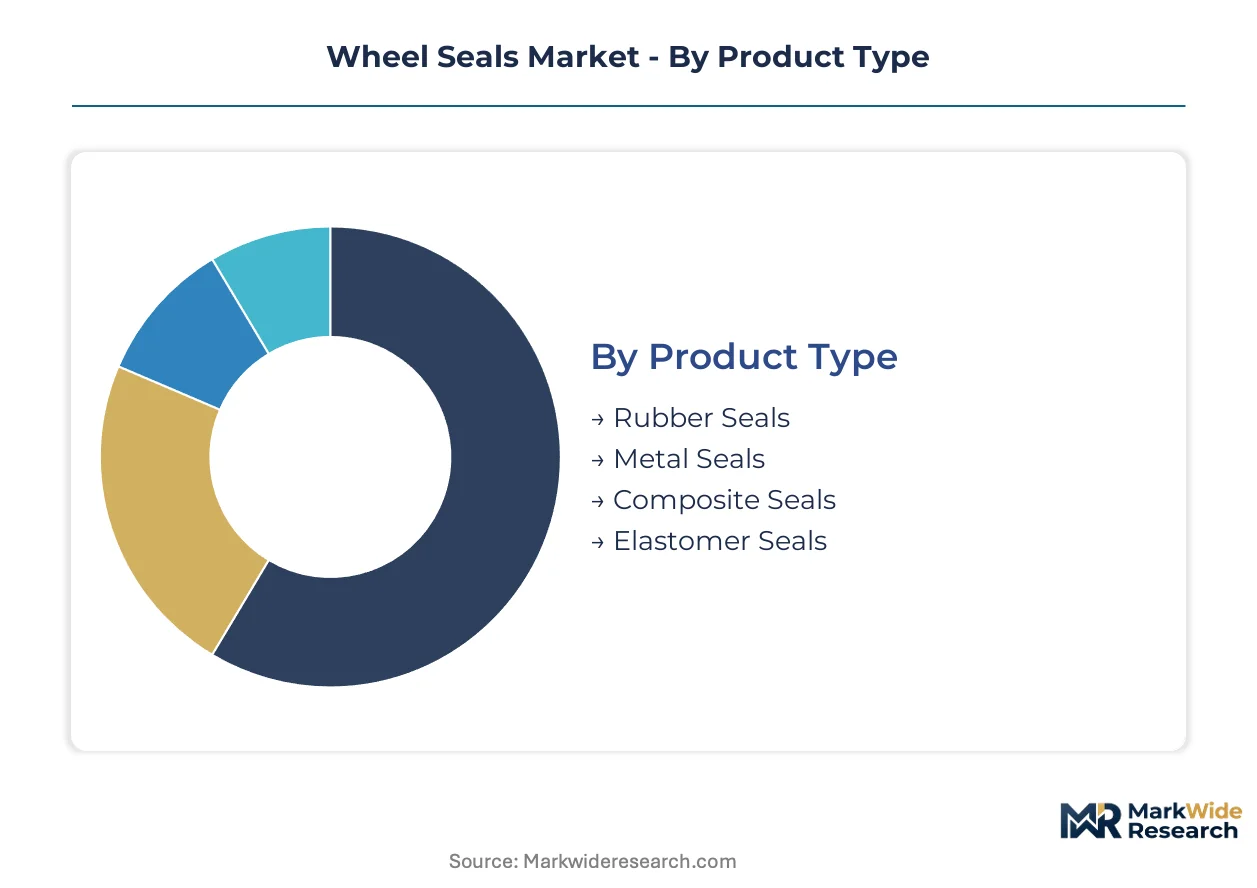
Wheel seal procurement patterns diverge sharply between OEM specification cycles and aftermarket replacement intensity. Understanding these segment boundaries reveals where suppliers can capture recurring service revenue versus one-time platform wins.
Product Type:
Aftermarket service intensity varies dramatically by seal material chemistry, with fluorocarbon formulations commanding premium replacement scheduling while nitrile rubber drives high-frequency, low-margin volume.
- Elastomer Seals:Advanced fluorocarbon and hydrogenated nitrile compounds withstand sustained temperatures above 150°C in commercial vehicle wheel ends. Fleet operators in Germany and China's Shandong province are consolidating procurement around these formulations as extended drain intervals compress replacement windows.
- Composite Seals:Multi-layer metal-reinforced architectures combine elastomer flexibility with rigid structural backing for abrasive mining and construction environments. The 40-60% cost premium over rubber alternatives limits penetration to heavy equipment where unplanned downtime costs dwarf component price.
- Rubber Seals:Standard nitrile and polyacrylate formulations dominate light-duty automotive where unit economics favor disposable replacement over extended service life.
- Metal Seals:Machined steel or aluminum housings with integrated sealing lips serve extreme-pressure hydraulic applications in agricultural implements.
Rubber seals hold the largest share; momentum sits with elastomer seals as formulation chemistry advances.
End User:
Customer procurement sophistication spans from centralized fleet technical offices to decentralized agricultural equipment dealers, shaping pricing power and contract structure.
- Commercial Vehicles:Heavy-duty truck and bus operators with 500-plus unit fleets negotiate predictive replacement contracts based on telematics-derived wear models. India's organized logistics sector is emerging as a concentrated demand pocket where first-mover suppliers can embed sensor-enabled seal systems.
- Heavy Equipment:Mining and construction OEMs specify seals for 10,000-hour service life under continuous abrasive loading. Equipment deployed in Australia's Pilbara region and Chile's Atacama copper belt drives specification for multi-barrier composite architectures.
- Automotive OEMs:Passenger car manufacturers prioritize unit cost and supply security over technical differentiation, with platform-common seals specified across multiple vehicle lines.
- Agricultural Machinery:Seasonal use patterns and dealer-service dependency create fragmented procurement with limited supplier concentration.
Commercial vehicles command the deepest aftermarket penetration; agricultural machinery presents the most underdeveloped organized service infrastructure.
Application:
Functional location within the driveline determines thermal exposure, contamination risk, and accessibility for replacement—factors that reshape margin structure.
- Wheel Axles:Constant rotational speed and road spray exposure make these the most failure-prone sealing points. EPA fuel efficiency mandates for heavy-duty trucks indirectly tighten tolerance requirements as bearing friction becomes regulated.
- Transmissions:Precision gear meshing demands ISO-certified contamination control, with multi-year qualification protocols delaying new supplier entry.
- Gearboxes:Industrial and off-highway gearboxes subject seals to pressure spikes and lubricant shear degradation.
- Suspension Systems:Low-speed oscillating motion with intermittent pressure exposure permits simpler seal geometries.
Wheel axles generate the highest replacement frequency; transmission applications carry the steepest certification barriers.
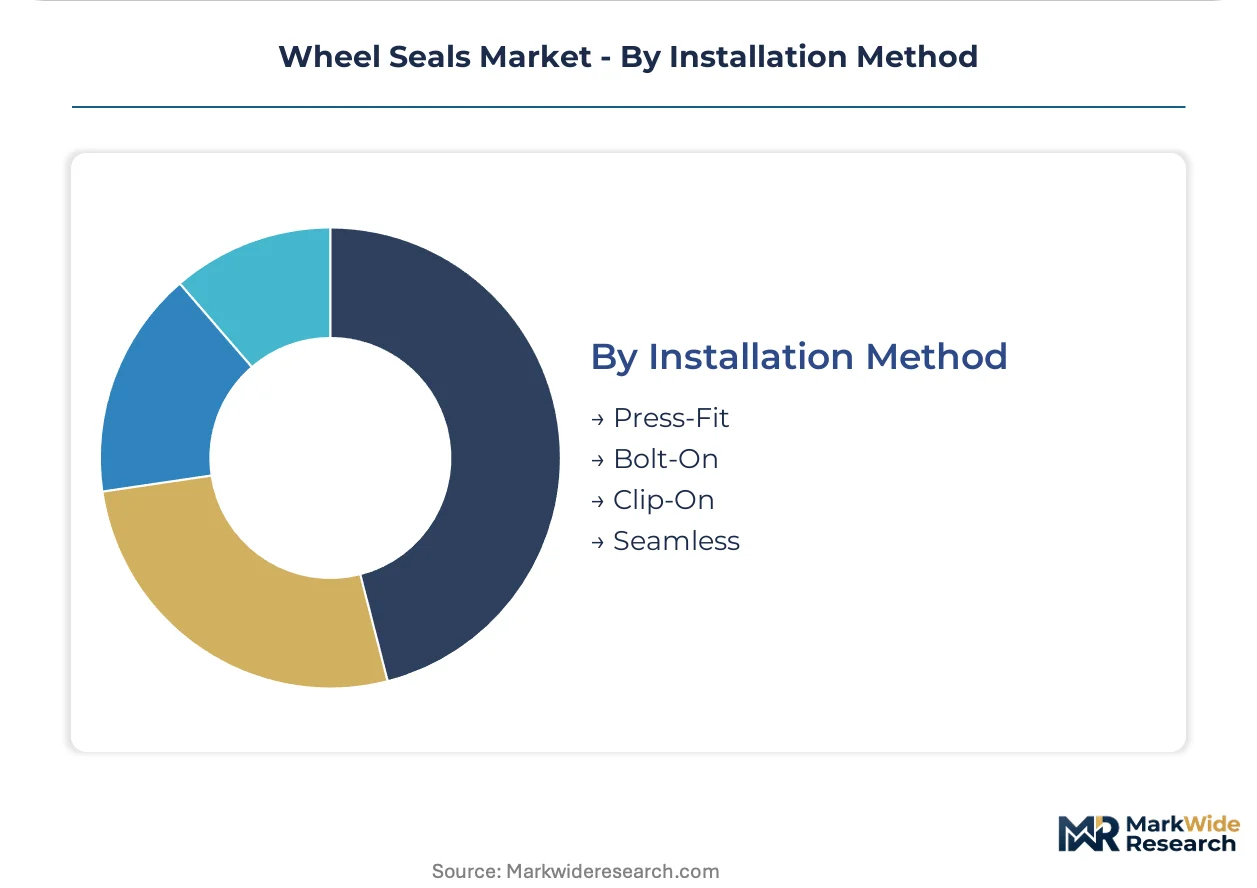
Installation Method:
Service bay tooling and technician training requirements segment the aftermarket between independent repair networks and captive dealer operations.
- Press-Fit:Interference-fit designs require hydraulic installation equipment and skilled alignment to prevent lip damage. German Ruhr region independent shops have invested in this capability to capture fleet disintermediation.
- Bolt-On:Flanged designs with through-bolts permit field replacement without specialized tooling, dominating remote mining and agricultural service.
- Clip-On:Retainer-integrated seals snap into stamped housing grooves for high-speed assembly line installation.
- Seamless:Unitized cartridge designs eliminate separate installation steps but require complete hub assembly replacement upon failure.
Press-fit retains the technical premium; bolt-on is expanding fastest in underdeveloped service infrastructures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys wheel seals for extended commercial vehicle duty cycles exceeding 500,000 kilometers, while India concentrates replacement demand in fragmented aftermarket channels with minimal organized service penetration. Germany anchors premium fluorocarbon formulation supply for European heavy-duty fleets. The United States generates predictive maintenance revenue through sensor-integrated seal architectures.
China
Shandong and Hubei provinces concentrate heavy-duty truck manufacturing that drives OEM seal specification for 2026 model year compliance. MIIT enforces GB standards for component durability requiring validated life under combined thermal-mechanical loading. Domestic suppliers in Weifang and Wuhan industrial clusters are accelerating local qualification to displace imported seal volumes.
Germany
Ruhr region independent service networks capture fleet disintermediation through press-fit installation capability investments. ECHA scrutiny of perfluorinated compounds under REACH creates formulation compliance uncertainty for next-generation elastomer development. Stuttgart and Munich anchor specialized fluorocarbon compounding expertise concentrated among aging technical workforces.
United States
Midwest fleet operators with 1,000-plus vehicle counts unbundle seal replacement from bundled wheel end service packages. EPA heavy-duty emissions standards mandate driveline efficiency maintenance that indirectly tightens wheel seal integrity requirements. Michigan and Ohio service bays drive predictive replacement cycle adoption.
India
Maharashtra and Gujarat logistics corridors generate concentrated commercial vehicle density with underdeveloped organized aftermarket infrastructure. Central Pollution Control Board emission norms for heavy-duty vehicles indirectly shape seal replacement scheduling. Pune and Ahmedabad fleet operators present first-mover positioning for integrated seal-and-bearing replacement programs.
Japan
METI industrial standards govern precision sealing performance for transmission and gearbox applications with multi-year qualification protocols. Nagoya and Osaka manufacturing clusters concentrate high-temperature molding process knowledge for fluorocarbon seal production. Domestic compounders supply specialty polymer formulations to regional automotive OEMs.
Wheel Seals Market Competitive Landscape
Capability concentration sits with specialized elastomer compounders possessing fluorocarbon formulation expertise; scale advantage sits with diversified sealing system integrators serving global automotive platforms. The vendor base stratifies across three tiers: integrated sensor-enabled seal designers, backward-integrated material specialists, and regional fabrication houses serving aftermarket replacement channels. Dominant competitive moves include capacity expansion in China's Shandong manufacturing corridor and strategic partnerships embedding real-time condition monitoring into wheel end architectures.
Within the integrated sealing systems tier, Stemco and SKF exemplify divergent approaches to aftermarket value capture. Freudenberg Sealing Technologies anchors the material-specialist vector through captive elastomer compounding capabilities. These three entities collectively represent the competitive frontier where sensor convergence and extended service interval chemistry reshape revenue models beyond component supply.
| Leading Market Players |
|---|
| Stemco |
| SKF |
| Dana Incorporated |
| Meritor |
| ACDelco |
| ConMet |
| Freudenberg Sealing Technologies |
| Timken Company |
| Trelleborg AB |
| Others |
Pricing and Supply Chain Analysis
Specialty fluorocarbon polymer supply chains in Germany and Japan concentrate upstream compounding expertise, directing margin capture toward seal designers with backward integration into captive elastomer production rather than pure-play fabricators. Fleet procurement offices in North America and Europe negotiate predictive replacement contracts that bundle sensor-enabled monitoring with component supply, compressing spot-market pricing power for undifferentiated nitrile rubber alternatives.
Pricing Analysis
Long-term offtake agreements dominate commercial vehicle fleet procurement, with 500-plus unit operators locking in predictive replacement schedules based on telematics-derived wear models. Price differentiation hinges on fluorocarbon formulation grade and ISO contamination control certification tier, with premium multi-layer architectures commanding substantial premiums over standard nitrile compounds. Cost compression in light-duty rubber seals is intensifying as Chinese domestic suppliers scale Weifang and Wuhan production capacity. Agricultural machinery dealers exhibit the highest price sensitivity due to seasonal cash flow constraints, while mining operators in Australia's Pilbara region prioritize unplanned downtime avoidance over unit cost.
Supply Chain Analysis
Contract manufacturing for precision fluorocarbon molding concentrates among specialized compounders in Stuttgart, Munich, Nagoya, and Osaka industrial clusters. Raw material flows draw from German and Japanese specialty polymer producers, with nitrile rubber feedstocks sourcing from broader petrochemical networks in China and South Korea. Single-source vulnerability around perfluorinated compound formulations under ECHA REACH scrutiny poses structural risk as regulatory pathways for next-generation chemistries remain unresolved. Distribution runs through captive OEM supply chains for initial equipment fitment, while independent service networks in the US Midwest and German Ruhr region capture aftermarket disintermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wheel seal value capture is shifting from component supply to continuous condition monitoring platforms, with sensor-bearing convergence creating interoperability standards that determine ecosystem membership. This platform economics inflection rewards first movers embedding predictive algorithms into fleet management systems.
For Market Incumbents: Insulate fluorocarbon formulation expertise through targeted retention programs for aging technical workforces in Germany and Japan, while accelerating captive sensor development to offset replacement frequency compression from extended service interval chemistry. Capacity expansion in China's Shandong corridor defends OEM specification position against domestic qualification acceleration.
For New Entrants and Emerging Players: India's Maharashtra and Gujarat logistics corridors present the most penetrable white-space, with underdeveloped organized aftermarket infrastructure enabling first-mover positioning for integrated seal-and-bearing replacement programs. Partnerships with centralized fleet procurement functions bypass fragmented dealer networks.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across sensor-integrated seal architectures as embedded electronics and telemetry capabilities reshape manufacturing footprints. Target acquisition archetypes include specialized fluorocarbon compounders with validated 500,000-kilometer life certification under MIIT GB standards. Watch for REACH regulatory clarity on perfluorinated compounds as the signal for formulation investment timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Seal Convergence | Embedded bearing condition monitoring enables outcome-based fleet contracts with telematics-derived pricing. |
| Backward Integration into Fluorocarbon Compounding | Captive polymer chemistry protects margin pools as REACH restrictions reshape qualified supplier bases. |
| Capacity Expansion in Shandong Corridor | Proximity to Hubei and Shandong heavy-duty truck manufacturing accelerates domestic OEM qualification timelines. |
| Predictive Maintenance Platform Development | Algorithm-driven replacement scheduling shifts revenue from unit volume to continuous service subscriptions. |
| EU Green Deal Compliance Positioning | Reprocessable elastomer compounding capabilities secure extended producer responsibility framework advantage. |
Research Methodology
Cross-validation between fleet maintenance director interviews and OEM procurement data anchors the qualitative findings on predictive replacement cycle adoption. Primary discussions with aftermarket service network operators, commercial vehicle fleet technical officers, fluorocarbon compounder R&D leads, and heavy-duty truck platform engineers combined with secondary validation from EPA emissions filings, MIIT GB standard documentation, ECHA REACH substance registrations, and IHS Markit vehicle production databases. Bottom-up seal demand modeling triangulates against top-down commercial vehicle parc analysis.
Calibration against historical replacement frequency data and validated service life claims from 500,000-kilometer qualification testing shapes the analytical framework across the projection horizon. Segmentation dimensions span product type chemistry tiers, end-user procurement sophistication, application thermal exposure profiles, and installation method service infrastructure requirements. CAGRs derive from elasticity-adjusted fleet expansion and replacement intensity curves, with fluorocarbon formulation penetration and sensor adoption curves as industry-specific forecast inputs.
Practitioners should monitor ECHA regulatory determinations on perfluorinated compounds and MIIT enforcement intensity on GB standard compliance for early signals of supply-side disruption. Forecasts reflect assumptions on fleet telematics penetration and predictive maintenance algorithm accuracy that could shift replacement window calculations. Quarterly review of commercial vehicle production data from Shandong and Hubei provinces alongside REACH substance restriction timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Navigation Light Market
Vehicle Components
Italy Automotive Composites Market
Vehicle Components
Electric Brake Actuator Systems for Passenger Vehicles Market
Vehicle Components
Automotive Composite Suspension Components Market
Vehicle Components
Brake Hoses Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Portable Truck Access System Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Railroad Equipment Manufacturing Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Marine Wheel Bearings Market
Vehicle Components
Automotive and Transportation Connector Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Tipper Body Equipment Market
Vehicle Components
Steering Column Module Market