
 Electric Wheelbarrow Market | 2026-2036
Electric Wheelbarrow Market Size, Share, and Industry Trends Forecast 2026-2036
Electric Wheelbarrow Market Analysis
Skilled construction labor scarcity is redrawing competitive dynamics across material-handling equipment. SuperHandy leverages direct-to-consumer channel control to capture DIY and small-contractor segments with compact electric models. Landworks anchors its position through R&D intensity in off-road traction systems for agricultural and landscaping buyers. MechMaxx competes on manufacturing scale, sustaining cost advantages in heavy-duty electric wheelbarrows rated for sustained commercial use.
An electric wheelbarrow is a battery-powered motorized cart with a DC brushless or brushed motor, typically rated between 250W and 1,000W, designed to transport loads across uneven terrain with minimal operator exertion. The primary industrial purpose centers on reducing musculoskeletal strain and accelerating material movement on construction sites, farms, and landscaping projects where manual wheelbarrows create bottlenecks. Heavy-duty models dominate margin pools due to higher unit pricing and replacement part attachment rates, while compact variants show the fastest trajectory as residential users and light commercial operators downsize from gas-powered alternatives. Battery-powered configurations lead volume, though solar-augmented designs are gaining specification in remote agricultural settings where grid access remains unreliable.
EPA emissions standards in the United States and California Air Resources Board (CARB) regulations are phasing out small off-road gasoline engines, directly expanding addressable demand for electric substitutes. CE marking requirements under EU machinery directives enforce electromagnetic compatibility and operator safety protocols that favor established manufacturers with compliance infrastructure over import-only distributors. OSHA workplace ergonomics guidelines in the United States further legitimize motorized material-handling investments by employers seeking to reduce injury liability exposure. Stakeholders must monitor how rapidly evolving battery chemistry standards and regional charger interoperability mandates reshape product development roadmaps and aftermarket service requirements.
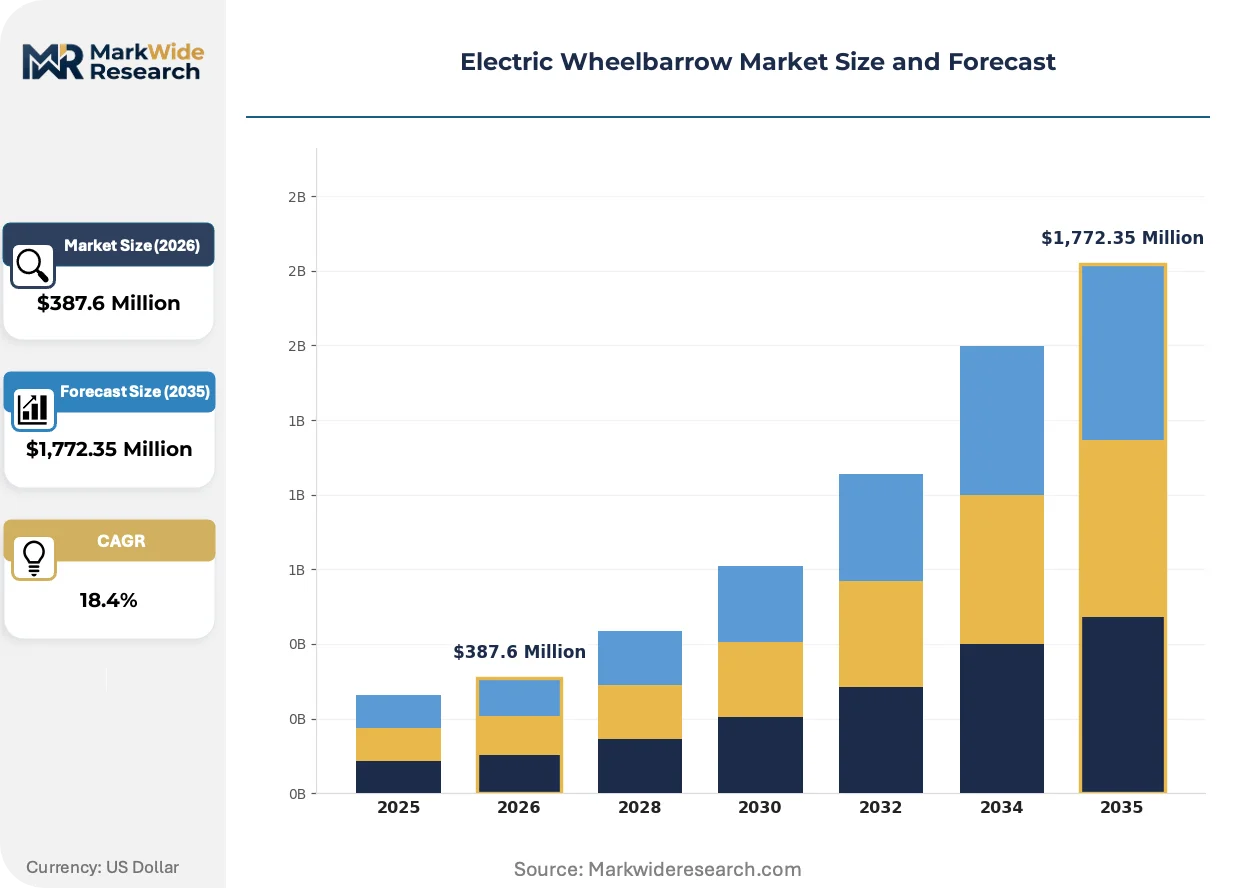
Market Dynamics
Skilled labor scarcity across construction and landscaping sectors is forcing material-handling equipment toward electrification, with battery chemistry improvements simultaneously compressing total cost of ownership differentials versus gasoline alternatives.
Growth Catalysts
- EPA Phase 3 Standards:The Environmental Protection Agency's tightened emissions limits on small off-road engines eliminate gasoline wheelbarrow options across federal projects, redirecting procurement toward battery-electric configurations.
- Agricultural Mechanization:Vineyards and orchards in California, Italy, and Chile are adopting motorized carts for harvest transport where terrain prevents tractor access.
- Lithium Iron Phosphate Chemistry:Improved thermal stability and cycle life in LiFePO4 cells are extending operational runtime for commercial crews without midday charging interruptions.
Market Restraints
- Battery Raw Material Concentration:Cathode precursor processing concentrates in Chinese industrial zones, exposing manufacturers to supply disruption and price volatility.
- Upfront Capital Intensity:Commercial-grade electric wheelbarrows carry three to four times the acquisition cost of manual alternatives, stretching small contractor budgets.
- Charging Infrastructure Gaps:Remote construction sites and agricultural fields lack reliable grid access, limiting deployment flexibility for pure battery configurations.
Strategic Opportunities
- Swappable Battery Architectures:Standardized pack formats enabling hot-swapping during shifts address downtime concerns for commercial landscaping fleets.
- EU Machinery Directive Expansion:CE marking requirements for electromagnetic compatibility favor established manufacturers with compliance infrastructure over import-only distributors.
- Solar-Augmented Designs:Photovoltaic panel integration creates autonomous charging capability for off-grid agricultural applications in Australia and sub-Saharan Africa.
Industry Challenges
- Field Service Technician Scarcity:Diagnosis and repair of brushless motor controllers and battery management systems requires electronics expertise uncommon in traditional equipment dealer networks.
- Certification Timeline Compression:UL 2580 battery safety testing and UN 38.3 transportation compliance add months to product launch schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electric Wheelbarrow Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $1,772.35 Million |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard, Heavy-Duty, Compact, Off-Road Power Source: Battery, Electric, Solar, Hybrid Capacity: 500 lbs, 1000 lbs, 1500 lbs, 2000 lbs End User: Construction, Landscaping, Agriculture, DIY |
| Companies Covered | Vevor, MechMaxx, SuperHandy, Arczorix, Happybuy, Landworks, Cardinal, Siavonce, Chore Warrior, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electric Wheelbarrow Market Emerging Trajectories
Electrification is rewriting competitive boundaries between material-handling equipment categories, with battery platform standardization enabling modular attachment ecosystems that expand use cases beyond traditional wheelbarrow functions.
Brushless DC motor systems rated above 750W are displacing brushed alternatives in commercial-grade units. Landscaping contractors operating on sloped terrain specifications favor these configurations for sustained torque delivery without commutator maintenance. The shift is compressing aftermarket parts revenue streams while extending product replacement cycles.
California Air Resources Board enforcement actions against non-compliant small off-road gasoline engines are accelerating fleet turnover decisions. Equipment rental yards face liability exposure for maintaining gas-powered inventory. The regulatory pressure concentrates most visibly in municipal landscaping contracts where procurement officers mandate zero-emission specifications.
Equipment-as-a-service arrangements are penetrating commercial landscaping segments where capital constraints previously blocked electric adoption. Subscription models bundle maintenance and battery replacement, transferring technical risk from operator to manufacturer. This restructuring appears strongest in United States metropolitan markets where seasonal demand volatility makes ownership economics unfavorable.
Electric Wheelbarrow Market Segmentation
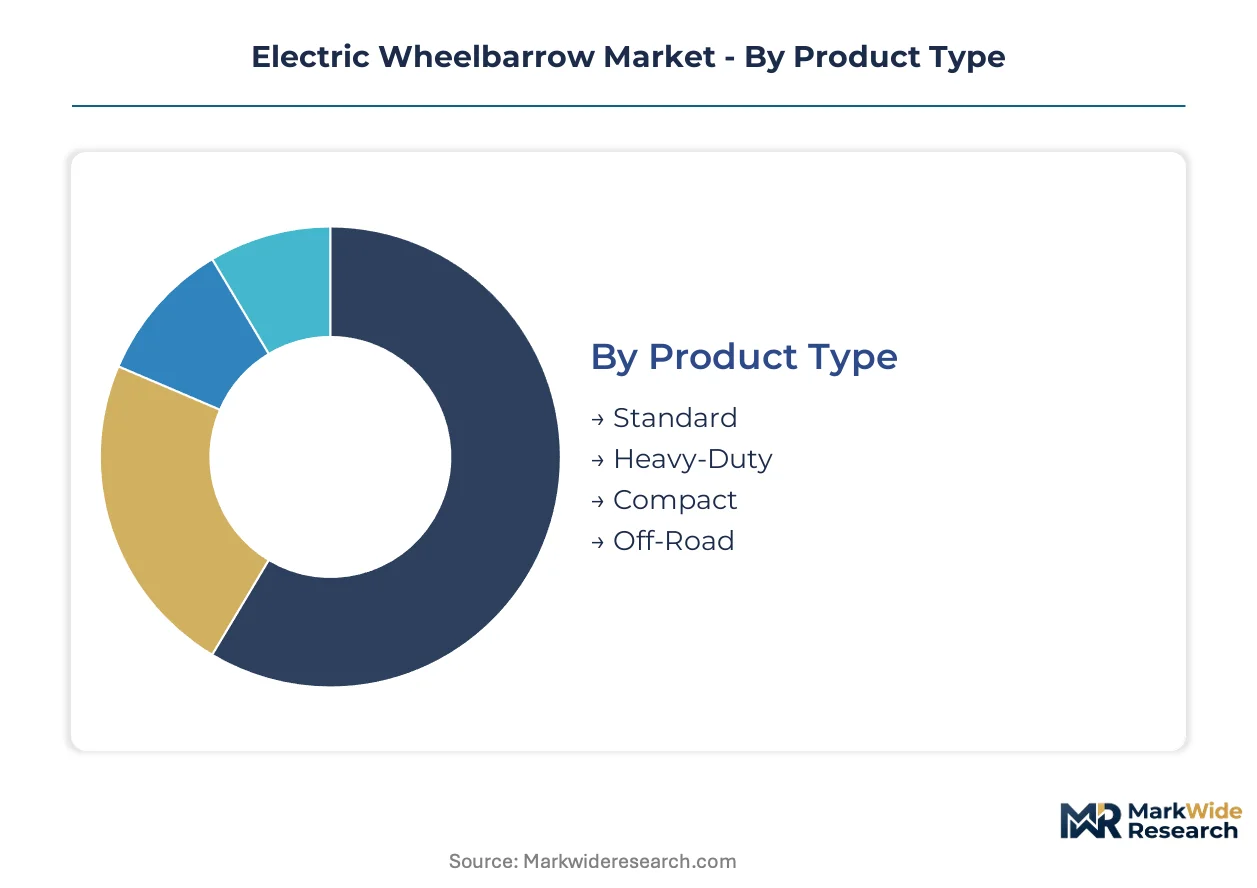
Segmentation in the electric wheelbarrow market reveals how procurement channels fragment across contractor tiers and use intensities. Equipment dealers, direct-to-consumer platforms, and rental yards each favor distinct product configurations that reshape manufacturer portfolio priorities.
Product Type:
Channel mix varies sharply by product type, with heavy-duty units flowing through commercial dealers while compact models dominate e-commerce direct sales.
- Heavy-Duty:Reinforced steel frames and 750W+ brushless motors handle sustained commercial loads exceeding 1,500 lbs. Municipal landscaping fleets in California specify these for slope work where gas alternatives face CARB prohibition.
- Compact:Lightweight aluminum construction with 250-500W motors targets residential users and small contractors. These units gain traction fastest through Amazon and Home Depot digital channels where DIY buyers compare runtime specifications.
- Standard:Mid-range polymer tubs with 500-750W systems serve general construction crews seeking manual wheelbarrow replacement without premium pricing.
- Off-Road:Knobby tires and sealed electronics enable vineyard and orchard deployment where mud and moisture destroy conventional units.
Heavy-Duty dominates installed base. Compact is where expansion concentrates.
Power Source:
Cost tier stratification separates premium battery configurations from entry-level electric corded units and emerging solar-augmented designs.
- Battery:Lithium iron phosphate packs with 4-8 hour runtime command premium positioning. Construction contractors in Germany adopt these for emissions-compliant urban sites where diesel generators face restrictions.
- Solar:Photovoltaic panel integration enables autonomous charging for off-grid agricultural applications in Australia and Chilean wine regions lacking reliable grid infrastructure.
- Electric:Corded AC motor designs serve fixed-site material handling where tethered operation eliminates battery cost and weight.
- Hybrid:Dual-mode battery-gasoline configurations address range anxiety in remote earthmoving projects, though regulatory pressure is compressing their addressable market.
Battery configurations anchor revenue. Solar-augmented designs are climbing the fastest as agricultural mechanization spreads.
Capacity:
Application intensity dictates capacity selection, with volume buyers in commercial landscaping and construction favoring higher-rated units despite capital premium.
- 1500 lbs:Reinforced chassis and dual-motor drive systems serve commercial earthmoving where load density matches compact excavator output. These units concentrate in United States infrastructure rehabilitation contracts.
- 500 lbs:Single-motor polymer designs target residential gardening and light maintenance where maneuverability outweighs payload maximization.
- 1000 lbs:Balanced specifications serve general construction crews handling mixed material types without dedicated heavy equipment.
- 2000 lbs:Industrial-grade steel construction with four-wheel stability systems addresses quarry and mining auxiliary transport where conventional loaders cannot access.
1500 lbs units dominate fleet procurement. 500 lbs configurations show steepest expansion trajectory through consumer retail channels.
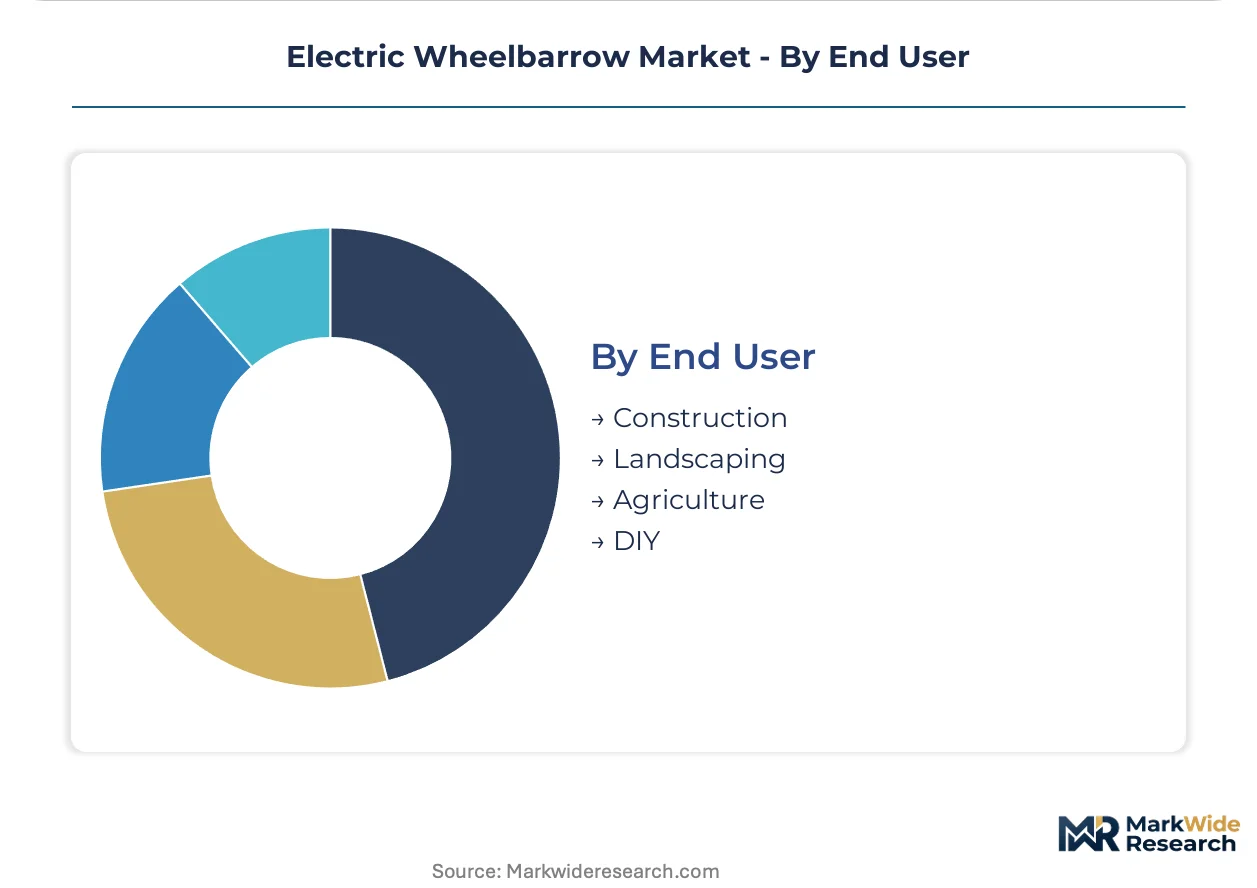
End User:
Customer type determines specification complexity, with professional segments demanding integrated fleet management and maintenance contracts unavailable to DIY purchasers.
- Construction:OSHA ergonomic compliance requirements and EPA emissions mandates drive motorized adoption on federally funded projects. Equipment-as-a-service models penetrate this segment where capital constraints previously blocked electric procurement.
- DIY:Price-sensitive homeowners prioritize compact battery units with tool-sharing compatibility across cordless power tool platforms. These buyers concentrate through Lowe's and Amazon seasonal promotions.
- Landscaping:Seasonal demand volatility favors rental arrangements over ownership, with commercial crews specifying swappable battery architectures to eliminate midday charging downtime.
- Agriculture:Terrain limitations and emissions regulations in EU member states redirect vineyard and orchard operations toward electric alternatives where tractor access is impossible.
Construction anchors commercial volume. Agriculture is gaining share fastest as mechanization penetrates specialty crop operations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA Phase 3 standards and CARB enforcement actions in the United States are redirecting procurement toward battery-electric configurations. Germany's emissions protocols and the EU Machinery Directive are compressing gasoline alternatives across member states. Demand concentrates in construction corridors and agricultural belts where labor scarcity intersects with regulatory pressure.
United States
Infrastructure rehabilitation contracts and warehouse logistics upgrades drive replacement cycles in Texas and the Southeast. OSHA workplace ergonomics guidelines legitimize motorized material-handling investments by employers seeking injury liability reduction. California's Central Valley agricultural operations specify electric carts for vineyard transport where tractor access fails.
Germany
Emissions-compliant urban construction sites in North Rhine-Westphalia and Bavaria eliminate diesel generator dependencies. CE marking requirements under EU machinery directives enforce electromagnetic compatibility standards that favor established manufacturers. Stuttgart's industrial machinery cluster hosts R&D facilities developing sealed electronics for moisture-intensive agricultural deployment.
China
Battery cell manufacturing scale in the Yangtze River Delta compresses pack costs for export-oriented wheelbarrow assemblers. The country's national industrial regulator enforces GB standards for electric vehicle safety that extend to material-handling equipment categories. Shenzhen's electronics corridor supplies brushless motor controllers to domestic and overseas manufacturers.
Australia
Remote agricultural applications in Queensland and Western Australia favor solar-augmented designs where grid infrastructure remains unreliable. The national electrical safety regulator mandates compliance testing for battery systems used in outdoor commercial environments. Perth's mining services sector deploys heavy-duty electric carts for quarry auxiliary transport.
Chile
Wine region mechanization in the Central Valley redirects harvest transport toward motorized carts on slopes preventing tractor access. The national agricultural development agency subsidizes equipment modernization for small and medium vineyard operators. Santiago's equipment distribution networks channel imported battery-electric units to specialty crop operations.
Electric Wheelbarrow Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier, with mid-scale fabricators occupying the volume middle. The vendor base separates into three strategic archetypes: direct-to-consumer channel controllers, R&D-intensive traction specialists, and manufacturing-scale cost leaders. Competitive moves concentrate on swappable battery architecture development and equipment-as-a-service subscription structuring.
Within the direct-to-consumer tier, SuperHandy occupies a position exemplifying channel control strategies, while Landworks represents R&D-intensive positioning in off-road traction systems. MechMaxx anchors the scale-driven end, exemplifying manufacturing volume advantages in heavy-duty commercial ratings. These three names illustrate how competitive positioning fragments across procurement channel preferences and use-intensity segments.
| Leading Market Players |
|---|
| Vevor |
| MechMaxx |
| SuperHandy |
| Arczorix |
| Happybuy |
| Landworks |
| Cardinal |
| Siavonce |
| Chore Warrior |
| Others |
Supply Flow & Price Mechanics
Lithium iron phosphate cell chemistry replacing nickel-cobalt-manganese alternatives is redrawing procurement geography toward Yangtze River Delta manufacturing zones while compressing pack cost premiums against lead-acid legacy systems. This substitution simultaneously concentrates cathode precursor processing in Chinese industrial corridors and transfers pricing power from cell assemblers to raw material processors exposed to lithium carbonate volatility.
Pricing Analysis
Price spreads between German commercial-grade units and Chinese export configurations exceed fifty percent landed cost differentials. Three-tier pricing structure across premium brushless-motor systems, standard brushed-motor mid-range, and economy corded AC designs stratifies buyer access. Cost compression in compact residential tiers is intensifying because Amazon marketplace sellers are absorbing freight costs to capture DIY seasonal demand. Small landscaping contractors exhibit highest price sensitivity, while municipal fleet managers prioritize total cost of ownership over acquisition outlay.
Supply Chain Analysis
Inventory strategy preferences split between just-in-time cell procurement for high-volume assemblers and strategic stockpiling of brushless motor controllers by dealers anticipating lead time volatility. Manufacturing gravity centers on China for battery pack integration, Vietnam for polymer tub molding, and Germany for sealed electronics assembly. Supply chains draw from lithium carbonate, rare-earth magnets, and steel chassis feedstocks. Single-source vulnerability concentrates in Shenzhen controller fabrication. Distribution runs through equipment dealers for commercial tiers and direct-to-consumer platforms for residential segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward consolidated municipal landscaping fleets and rental yard networks that command volume pricing and service bundling, fragmenting price-setting authority away from manufacturer list structures.
For Market Incumbents: Shield margin pools in heavy-duty commercial ratings by deepening captive supply of LiFePO4 cells through backward integration into Yangtze River Delta partnerships. Prioritize CE marking infrastructure investment to exploit EU Machinery Directive enforcement gaps that disadvantage import-only distributors facing electromagnetic compliance delays. For New Entrants and Emerging Players: Differentiate on solar-augmented autonomy for Australian and Chilean agricultural applications where grid infrastructure gaps block incumbent battery-only configurations. Target vineyard mechanization in Central Valley California and Western Australia as the most penetrable white-space segment, entering through equipment-as-a-service subscription models that transfer technical risk from operator to manufacturer. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors vertically integrated manufacturers with in-house battery management system firmware development. Long-term viability over the next decade hinges on swappable battery architecture standardization that enables fleet interoperability. Watch California Air Resources Board enforcement action timelines as the inflection signal indicating fleet turnover velocity and rental yard liability exposure thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Swappable Battery Architecture Development | Standardized pack formats eliminate midday charging downtime for commercial landscaping crews operating across extended shifts. |
| Equipment-as-a-Service Subscription Launch | Bundled maintenance contracts transfer brushless motor controller technical risk from seasonal operators to manufacturers. |
| CE Marking Infrastructure Investment | Electromagnetic compliance capabilities exploit EU Machinery Directive gaps disadvantaging import-only distribution channels. |
| Solar-Augmented Design Integration | Photovoltaic panel autonomy unlocks vineyard and orchard deployment in Queensland and Chilean wine regions lacking grid access. |
| Backward Integration into Cell Supply | Captive lithium iron phosphate sourcing insulates margin pools from cathode precursor price volatility concentrated in Chinese processing zones. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with equipment procurement managers at municipal landscaping fleets, aftermarket service directors at rental yard networks, and plant engineers at construction contractors; alongside secondary validation through EPA Phase 3 regulatory filings, CARB enforcement action databases, EU machinery directive compliance registries, and customs trade records for battery-powered material-handling equipment. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, power source, capacity rating, and end-user segmentation dimensions.
Across the analysis window, volume and value outputs reflect analytical framework segmentation by heavy-duty, compact, standard, and off-road product configurations; battery, solar, electric corded, and hybrid power sources; and construction, DIY, landscaping, and agricultural end-user categories. CAGRs derived from logistic growth curve fitting anchored in replacement cycle dynamics and regulatory phase-out timelines. Forecast inputs incorporated OSHA ergonomic guideline adoption rates and lithium iron phosphate cell cost compression trajectories.
The analysis sits within stated boundaries; outcomes outside sustained EPA enforcement continuity and stable lithium carbonate supply conditions would require recalibration. Forecasts reflect documented assumptions regarding skilled labor scarcity persistence and emissions protocol stringency trajectories in Germany and California. Revision becomes warranted when battery raw material concentration risk crosses disruption thresholds or charging infrastructure deployment in remote agricultural regions accelerates beyond modeled penetration rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Wheel Chocks Market
Vehicle Components
Car Diffuser Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Electric Wheelchair Market
Vehicle Components
Tail Lifts Market
Vehicle Components
Vehicle Retarder Market
Vehicle Components
Piston Market
Vehicle Components
UK Automotive Glass Fiber Composites Market
Vehicle Components
Engine Valve Market
Vehicle Components
Asia-Pacific Industrial Brakes Market
Vehicle Components
Global Automotive Carbon Fiber Composites Market
Vehicle Components
Rear-Wheel Steering Actuator Systems for SUVs Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
Two-Wheeled Containers Market