
 Self Loading Trailer Market | 2026-2036
Self Loading Trailer Market Size, Share, and Industry Trends Forecast 2026-2036
Self Loading Trailer Market Analytics
ISO 1726 towing compatibility certification is collapsing the supplier base for self loading trailers entering European commercial fleets. Hammar Maskin AB leverages its Swedish engineering heritage to dominate side-loader designs for intermodal terminals. Schmitz Cargobull anchors its position through in-house axle and chassis production, sustaining margin control across German manufacturing. CIMC Vehicles Group extends its cost architecture from Chinese steel sourcing into Southeast Asian export channels.
A self loading trailer integrates a dedicated lifting mechanism—typically hydraulic, electric, or mechanical—mounted to a road-legal chassis, enabling single-operator cargo handling without external lifting equipment. These units commonly achieve payload capacities from 20 to 40 tonnes with self-contained power packs, serving construction sites, agricultural yards, and logistics hubs where dock infrastructure is absent or unavailable. Flatbed configurations lead unit shipments due to versatility across general freight and equipment transport, while enclosed trailers command premium positioning in high-value cargo segments. Hydraulic systems retain the dominant technology share given proven reliability in heavy-lift cycles, though electric actuation is gaining traction in urban delivery applications where noise and emissions restrictions tighten.
The European Union's F-Gas Regulation and CE marking directives shape refrigerant and component standards for temperature-controlled enclosed variants, while the U.S. NHTSA and FMCSA govern braking, lighting, and coupling requirements for interstate highway operation. China's MIIT enforces GB standards on axle loading and dimensional limits that directly constrain product design for domestic manufacturers exporting under CIMC's umbrella. Buyers must monitor diverging regional certification timelines to avoid stranded inventory as electrified lift systems trigger new safety testing protocols.
Market Dynamics
ISO 1726 towing compatibility certification is compressing the supplier base for European fleet entry, forcing manufacturers to absorb testing costs or exit the market entirely. Hydraulic lift technology faces displacement pressure from electric actuation systems as urban noise ordinances tighten across freight corridors.
Growth Catalysts
- E-Commerce Fulfillment Pressures:Last-mile operators in Germany and the Netherlands are deploying self-loading units to eliminate dock wait times at urban micro-fulfillment centers lacking fixed material handling infrastructure.
- F-Gas Regulation Compliance:The European Union's refrigerant phase-down mandates are accelerating replacement cycles for temperature-controlled enclosed trailers, pulling forward capital expenditure in refrigerated self-loading configurations.
- Intermodal Terminal Expansion:Rail-served logistics hubs across Poland and the Czech Republic are standardizing on side-loader designs to enable direct container transfers without gantry crane dependency.
Market Restraints
- High-Strength Steel Price Volatility:Swedish and German chassis manufacturers face margin compression when alloy input costs spike, given limited substitution options for weight-critical structural members.
- Hydraulic Fluid Supply Concentration:Specialty hydraulic oil formulations for extreme-temperature operation source predominantly from Belgian and Dutch blenders, creating single-point vulnerability in the lifting mechanism supply chain.
- Battery Energy Density Limitations:Electric lift systems remain constrained to sub-25-tonne payload ratings due to lithium-ion pack weight penalties, capping addressable market share in heavy construction applications.
Strategic Opportunities
- Southeast Asian Port Modernization:Indonesian and Vietnamese container terminals are procuring self-loading trailers to bypass congested crane queues, opening export channels for Chinese manufacturers with established cost architectures.
- CE Marking Harmonization:The European Union's consolidated machinery directive reduces certification duplication across member states, lowering market entry costs for specialized lifting mechanism suppliers.
- Telematics-Enabled Predictive Maintenance:Integration of lift cycle sensors with fleet management platforms allows rental operators to monetize usage data through outcome-based service contracts.
Industry Challenges
- Certification Timeline Compression:New electrified lift systems trigger extended safety testing protocols under updated EU machinery directives, delaying product launches by 8-14 months versus hydraulic equivalents.
- Cross-Border Spare Parts Logistics:Fleet operators running pan-European routes struggle with inconsistent parts availability when hydraulic seal specifications vary between German and Swedish OEM service networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self Loading Trailer Market |
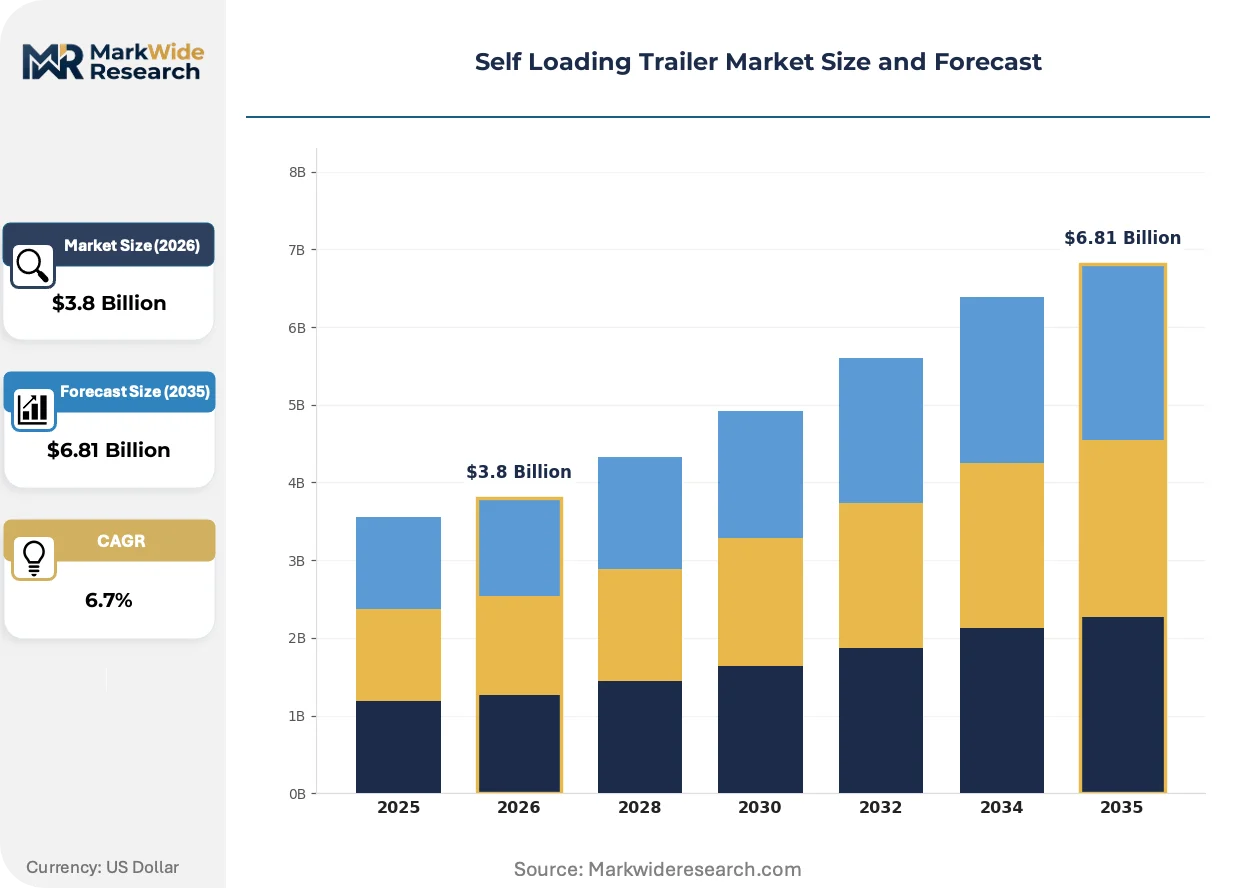
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flatbed Trailers, Dump Trailers, Enclosed Trailers, Lowboy Trailers End User: Construction Companies, Logistics Providers, Agricultural Operators, Waste Management Firms Technology: Hydraulic Systems, Electric Systems, Pneumatic Systems, Mechanical Systems Distribution Channel: Direct Sales, Online Retail, Dealerships, Third-Party Distributors |
| Companies Covered | China International Marine Containers Ltd. (CIMC), Steelbro Container Handling Equipment, Hammar Maskin AB, J & J Trailer Manufacturers & Sales Inc, Sauber Mfg. Co., Schutt Industries, Andros Engineering, CIMC Vehicles Group, Schmitz Cargobull, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self Loading Trailer Market Evolving Landscape
Electrification and digital integration are restructuring competitive positioning across the self-loading trailer value chain. Three developments are actively reshaping product architecture and procurement patterns.
Electric linear actuation systems are supplanting traditional hydraulic cylinders in urban delivery configurations. Municipal fleet operators in Copenhagen and Amsterdam are specifying battery-powered lift mechanisms to comply with nighttime noise restrictions. This shift is compressing maintenance revenue pools for hydraulic component suppliers while opening aftermarket opportunities for battery management specialists.
The European Union's F-Gas Regulation is forcing refrigerant architecture redesigns in temperature-controlled variants. Enclosed trailer manufacturers must phase out high-global-warming-potential working fluids by 2030, accelerating R&D expenditure on CO2-based and hydrocarbon alternatives. German cold-chain logistics providers are front-loading procurement to secure grandfathered equipment before phase-down deadlines tighten.
Asset-light procurement models are gaining traction among mid-sized freight operators. Rental and lease-to-own structures are displacing outright purchase for seasonal construction and agricultural applications. This pattern is most visible in France and Spain, where harvest timing unpredictability makes fixed ownership economically unattractive for grain cooperatives and vineyard logistics contractors.
Self Loading Trailer Market Segmentation
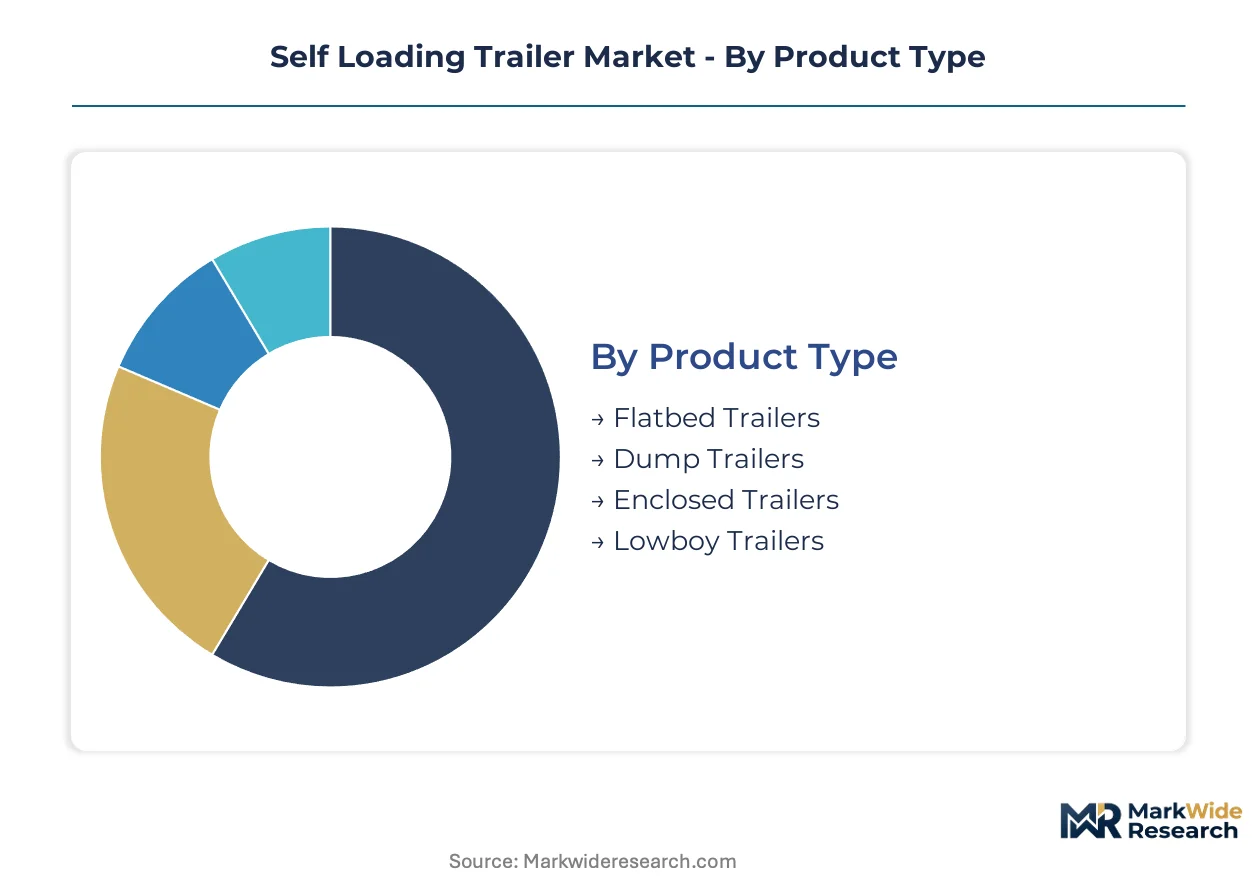
Self loading trailer procurement patterns diverge sharply across product configurations and buyer profiles. Regulatory pressure on emissions and noise is fragmenting technology preferences, while infrastructure availability shapes end-user adoption curves.
Product Type:
CE marking requirements under the EU machinery directive impose distinct testing burdens on enclosed variants versus open configurations.
- Flatbed Trailers:Open-deck designs accommodate general freight and equipment transport without dimensional constraints from fixed walls. German logistics corridors and Dutch agricultural cooperatives concentrate procurement here for versatility across mixed cargo loads.
- Enclosed Trailers:Insulated and refrigerated variants face F-Gas Regulation compliance deadlines that compress replacement cycles. Temperature-controlled units command premium positioning in pharmaceutical and food-grade cold chains serving Scandinavian population centers.
- Dump Trailers:Hydraulic cylinder arrays enable rapid unloading of aggregates and construction debris. French quarry operators and Spanish infrastructure contractors specify reinforced chassis ratings for abrasive material handling.
- Lowboy Trailers:Drop-deck geometry accommodates heavy equipment transport with reduced center of gravity. German wind turbine component haulers and Polish rail equipment movers dominate specialized procurement.
Flatbed configurations handle the majority of throughput; enclosed variants are expanding most quickly on share as cold-chain infrastructure tightens.
End User:
Customer procurement scale ranges from single-unit agricultural buyers to hundred-unit fleet operators, with service contract structures varying accordingly.
- Logistics Providers:Fleet standardization programs favor ISO 1726-compatible towing interfaces for interoperability across subcontractor networks. Last-mile operators in German urban zones prioritize electric lift systems to comply with municipal noise ordinances.
- Construction Companies:Project-based demand cycles drive seasonal procurement spikes aligned with infrastructure tender awards. Italian and Spanish civil contractors favor rental structures over ownership to match equipment availability to contract duration.
- Agricultural Operators:Harvest timing unpredictability pushes French grain cooperatives toward lease-to-own arrangements. Vineyard logistics contractors in Spain's Rioja region specify compact side-loader designs for narrow rural access roads.
- Waste Management Firms:Municipal collection contracts specify hydraulic compaction integration for transfer station efficiency. Swedish environmental services operators lead electrification trials for urban residential routes.
Logistics providers concentrate the largest fleet volumes; construction companies show the steepest expansion trajectory as infrastructure stimulus packages deploy.
Technology:
Power system selection hinges on payload rating requirements and operating environment constraints.
- Hydraulic Systems:Proven reliability in heavy-lift cycles above 25 tonnes sustains dominant positioning. Belgian blenders supply specialty fluid formulations for extreme-temperature Nordic operations.
- Electric Systems:Battery weight penalties currently cap ratings at sub-25-tonne thresholds. Copenhagen and Amsterdam municipal fleets specify these for nighttime delivery compliance.
- Pneumatic Systems:Compressed air actuation serves niche applications in explosive atmosphere environments. Chemical processing logistics in Germany's Ruhr region maintain limited procurement.
- Mechanical Systems:Manual winch and screw-jack configurations persist in emerging market price-sensitive segments. Southeast Asian port modernization programs source these for basic container handling.
Hydraulic systems retain the dominant installed base; electric configurations are gaining share fastest as battery energy density improves.
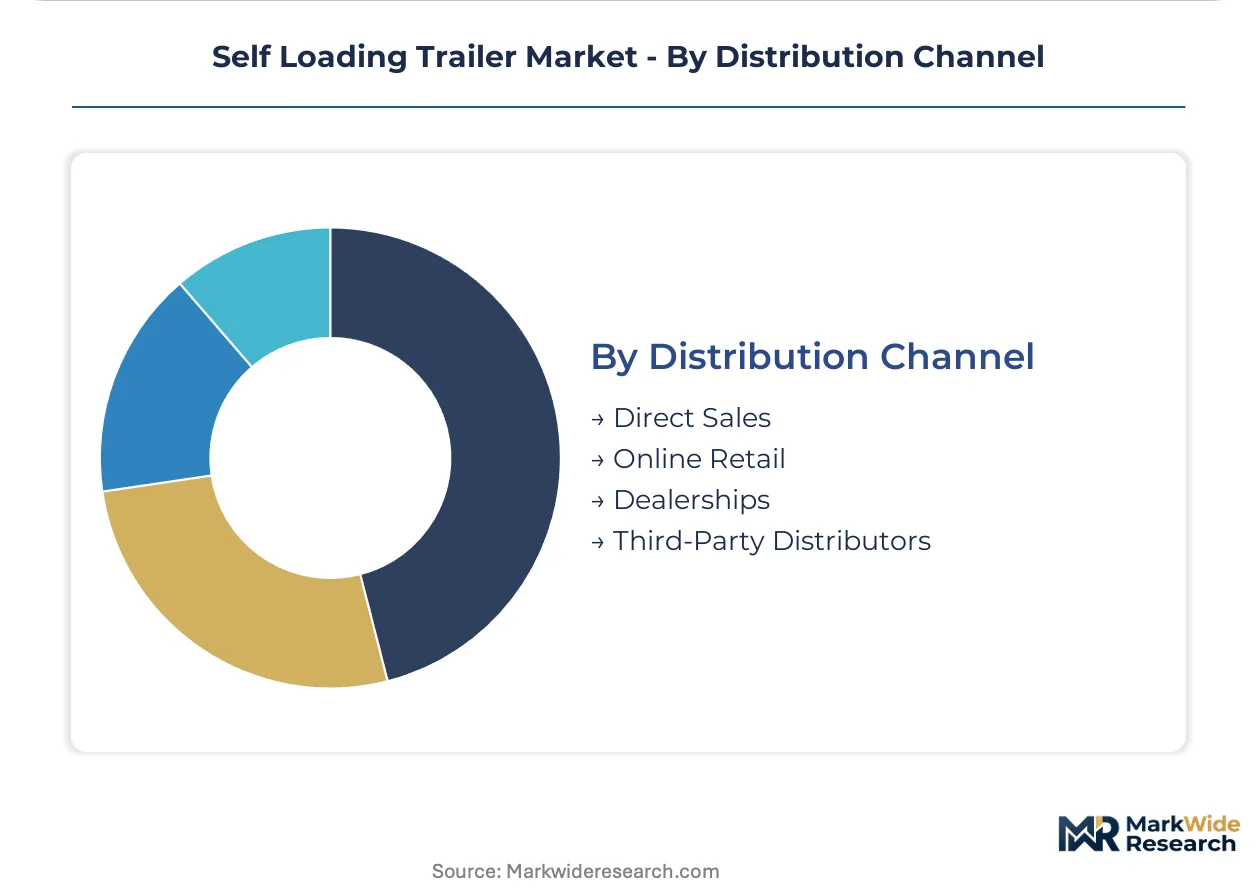
Distribution Channel:
Channel selection correlates with buyer sophistication and aftermarket service requirements.
- Direct Sales:Manufacturer-direct relationships dominate fleet orders above ten units, with integrated maintenance contracts. Schmitz Cargobull and Hammar Maskin AB cultivate long-term operator partnerships through this channel.
- Dealerships:Regional service networks provide spare parts availability for pan-European route operators. German and Swedish OEM service networks maintain inconsistent hydraulic seal specifications, complicating cross-border fleet management.
- Third-Party Distributors:Independent channels serve price-sensitive mid-market buyers with standardized configurations. Polish and Czech intermodal terminal operators source side-loader designs through this route.
- Online Retail:Digital procurement platforms emerge for standardized flatbed variants in agricultural and small contractor segments. French equipment marketplaces facilitate used unit transactions with telematics history verification.
Direct sales capture the largest transaction values; online retail is climbing the fastest as digital procurement tools mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government infrastructure stimulus and emissions regulations are redirecting fleet procurement across major economies. National policies on axle loading, towing compatibility, and noise restrictions are reshaping manufacturer market access and operator equipment choices.
Germany
Fleet operators in the Rhine-Ruhr corridor are replacing aging hydraulic units to meet KBA enforcement of updated braking standards. The EU F-Gas Regulation accelerates refrigerated trailer replacement cycles ahead of 2030 phase-down deadlines. Manufacturing clusters in North Rhine-Westphalia and Baden-Württemberg sustain captive axle and chassis production for margin control.
United States
Interstate logistics providers are expanding self-loading fleets to reduce dwell times at distribution hubs lacking fixed material handling infrastructure. NHTSA and FMCSA govern braking, lighting, and coupling requirements for cross-state highway operation. Midwest agricultural cooperatives concentrate procurement around harvest-season rental structures.
China
MIIT enforcement of GB standards on axle loading and dimensional limits constrains domestic product design for export-focused manufacturers. Southeast Asian port modernization programs are opening procurement channels for cost-optimized container handling equipment. Yangtze River Delta fabrication clusters serve Indonesian and Vietnamese terminal operators.
Sweden
Municipal fleet operators in Stockholm and Gothenburg are specifying electric lift mechanisms to comply with nighttime noise ordinances in urban freight corridors. The country's national environmental regulator enforces strict emissions standards for equipment operating in residential zones. Engineering heritage in side-loader design anchors regional specialization for intermodal terminal applications.
France
Harvest timing unpredictability pushes grain cooperatives in the Île-de-France and Grand Est regions toward lease-to-own procurement structures. ANSM and CNIL oversight shapes telematics data handling for predictive maintenance platforms. Vineyard logistics contractors in Bordeaux specify compact side-loader designs for narrow rural access roads.
Self Loading Trailer Market Competitive Landscape
Listed leaders compete with private specialists across capital access and engineering agility. The supplier base compresses under ISO 1726 towing compatibility certification costs, forcing smaller fabricators toward exit or acquisition. Three archetypes dominate: integrated chassis-axle manufacturers controlling upstream components, lifting mechanism specialists licensing designs to regional assemblers, and scale-driven Chinese exporters leveraging steel cost advantages. Competitive moves concentrate on backward integration into high-strength steel sourcing and telematics-enabled service contract development.
Within the integrated manufacturing tier, Schmitz Cargobull and Hammar Maskin AB exemplify European engineering-led positioning through in-house structural component production. CIMC Vehicles Group occupies the scale-driven export archetype, extending cost architectures from domestic steel sourcing into Southeast Asian procurement channels. These three anchors represent divergent strategic paths: captive supply chain control, specialized lifting mechanism dominance, and volume-based geographic expansion.
| Leading Market Players |
|---|
| China International Marine Containers Ltd. (CIMC) |
| Steelbro Container Handling Equipment |
| Hammar Maskin AB |
| J & J Trailer Manufacturers & Sales Inc |
| Sauber Mfg. Co. |
| Schutt Industries |
| Andros Engineering |
| CIMC Vehicles Group |
| Schmitz Cargobull |
| Others |
Value Network & Pricing Analysis
ISO 1726 towing compatibility certification gates both supplier qualification and price differentiation simultaneously, compressing the vendor base while stratifying procurement costs across fleet operators. Buyers face tiered entry barriers where certified manufacturers command premium positioning against uncertified regional fabricators.
Pricing Analysis
Certification level (ISO 1726/CE marking) creates the primary spread between premium hydraulic systems and economy mechanical configurations. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales bundling intensity and telematics integration depth. Pricing pressure stems from Chinese steel cost architectures entering Southeast Asian procurement channels. Small agricultural cooperatives exhibit highest price sensitivity; German logistics providers with standardized fleet programs demonstrate lowest.
Supply Chain Analysis
Just-in-time inventory strategies dominate hydraulic component procurement, while strategic stockpiling persists for high-strength steel alloy inputs subject to Nordic supply volatility. Manufacturing gravity centers on Germany, Sweden, and China, with Yangtze River Delta fabrication clusters feeding Indonesian and Vietnamese terminal modernization. Raw material dependencies include Swedish specialty steel, Belgian hydraulic fluid formulations, and Chinese structural components. Single-source vulnerability concentrates in extreme-temperature hydraulic oil blending. Distribution runs through manufacturer-direct channels for fleet orders above ten units, regional dealership networks for aftermarket service, and emerging digital platforms for standardized agricultural configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers durable defensive moats through regulatory entrenchment—ISO 1726 certification costs create switching barriers that protect incumbent positioning against price-based competition.
For Market Incumbents: Consolidate backward integration into high-strength steel sourcing to defend margin control against alloy price volatility from Swedish suppliers. Deepen captive axle and chassis production capabilities to sustain cost architecture advantages over Chinese exporters penetrating Southeast Asian channels. Prioritize telematics-enabled service contract development to lock in fleet operator relationships through predictive maintenance revenue streams. For New Entrants and Emerging Players: Differentiate on electric lift system specialization for urban municipal fleets facing nighttime noise ordinances in Copenhagen, Amsterdam, and Stockholm. Target lease-to-own procurement structures in French agricultural cooperatives where harvest timing unpredictability discourages fixed ownership. Pursue white-label manufacturing partnerships with established OEMs seeking to outsource lifting mechanism production without certification investment. For Investors and Strategic Acquirers: Carve-out targets emerge from distressed European fabricators facing ISO 1726 compliance cost absorption pressure. Long-term viability hinges on regulatory entrenchment durability and electrification transition execution speed. Monitor battery energy density improvement trajectories as inflection indicator for electric system addressable market expansion beyond current sub-25-tonne payload constraints.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Steel Sourcing | Captive supply of Swedish high-strength alloys insulates German manufacturers from input cost volatility. |
| Electric Lift System Development | Battery-powered mechanisms unlock Copenhagen and Amsterdam municipal procurement restricted by noise ordinances. |
| Telematics Platform Integration | Lift cycle sensor data enables rental operators to monetize usage patterns through outcome-based contracts. |
| CE Marking Harmonization Investment | Consolidated machinery directive compliance reduces certification duplication costs across EU member states. |
| Southeast Asian Distribution Partnership | Indonesian and Vietnamese port modernization opens export channels for Chinese cost-optimized configurations. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across fleet procurement directors, hydraulic system engineers, intermodal terminal managers, and agricultural cooperative equipment buyers. Secondary validation drew from customs trade databases, EU machinery directive filings, SEC 10-K disclosures from listed trailer manufacturers, and KBA enforcement bulletins. Bottom-up unit shipment estimates triangulated against top-down fleet replacement cycle analysis.
Across the analysis window, volume and value outputs reflect segmentation modeling across product configuration, end-user vertical, power system technology, and distribution channel. CAGRs were derived from fitted growth curves applied to replacement cycle timing and infrastructure stimulus deployment patterns. Industry-specific forecast inputs include F-Gas Regulation compliance deadlines and battery energy density improvement trajectories.
The analysis sits within stated boundaries; outcomes outside sustained infrastructure stimulus continuation or accelerated electrification technology maturation would require recalibration. Forecasts reflect documented assumptions on regulatory enforcement intensity and raw material cost stability. Revision becomes warranted when high-strength steel price volatility or certification timeline compression crosses thresholds that materially alter manufacturer margin structures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Car Seat and Accessories Market
Vehicle Components
Mechanical Control Cables Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Global Truck and Trailer Landing Gear Market
Vehicle Components
Vehicle Radiator Market
Vehicle Components
Steering Knuckle Market
Vehicle Components
Oil Filter Elements Market
Vehicle Components
Vehicle Air Deflector Market
Vehicle Components
Idler Arm Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Global Automotive Constant Vehicle Joint Boots Market
Vehicle Components
4-Wheeled Containers Market
Vehicle Components
Intake-Air Temperature Sensor Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Automotive Brake Valves Market
Vehicle Components
Russia Automotive Composites Market