
 Limited Slip Differential (LSD) Market | 2026-2036
Limited Slip Differential (LSD) Market Size, Share, and Industry Trends Forecast 2026-2036
Limited Slip Differential (LSD) Market Insights
Electromechanical torque-vectoring architecture is tilting LSD development toward software-defined drivetrain control. BorgWarner Inc. leverages its powertrain electronics portfolio to integrate clutch-type LSDs with vehicle dynamics controllers. Eaton Corporation anchors North American heavy-duty truck applications through specialized differential locking systems. GKN Automotive dominates European OEM supply through in-house production of geared-type differentials for all-wheel-drive platforms.
A limited slip differential is a torque-sensing driveline component that distributes rotational force between two output shafts while permitting differential wheel speeds during cornering, typically employing friction plates, helical gears, or viscous fluid couplings with torque bias ratios ranging from 2:1 to 6:1 depending on configuration. Its primary commercial purpose is to prevent traction loss in asymmetric grip conditions without the steering bind of locked differentials. Electronic-type LSDs command premium positioning as they enable real-time torque modulation through brake-based or clutch-based actuation, while clutch-type units sustain volume leadership in cost-sensitive truck and SUV applications. Racing vehicle demand concentrates in hydraulic and mechanical configurations where FIA homologation requirements favor proven architectures with minimal electronic dependency.
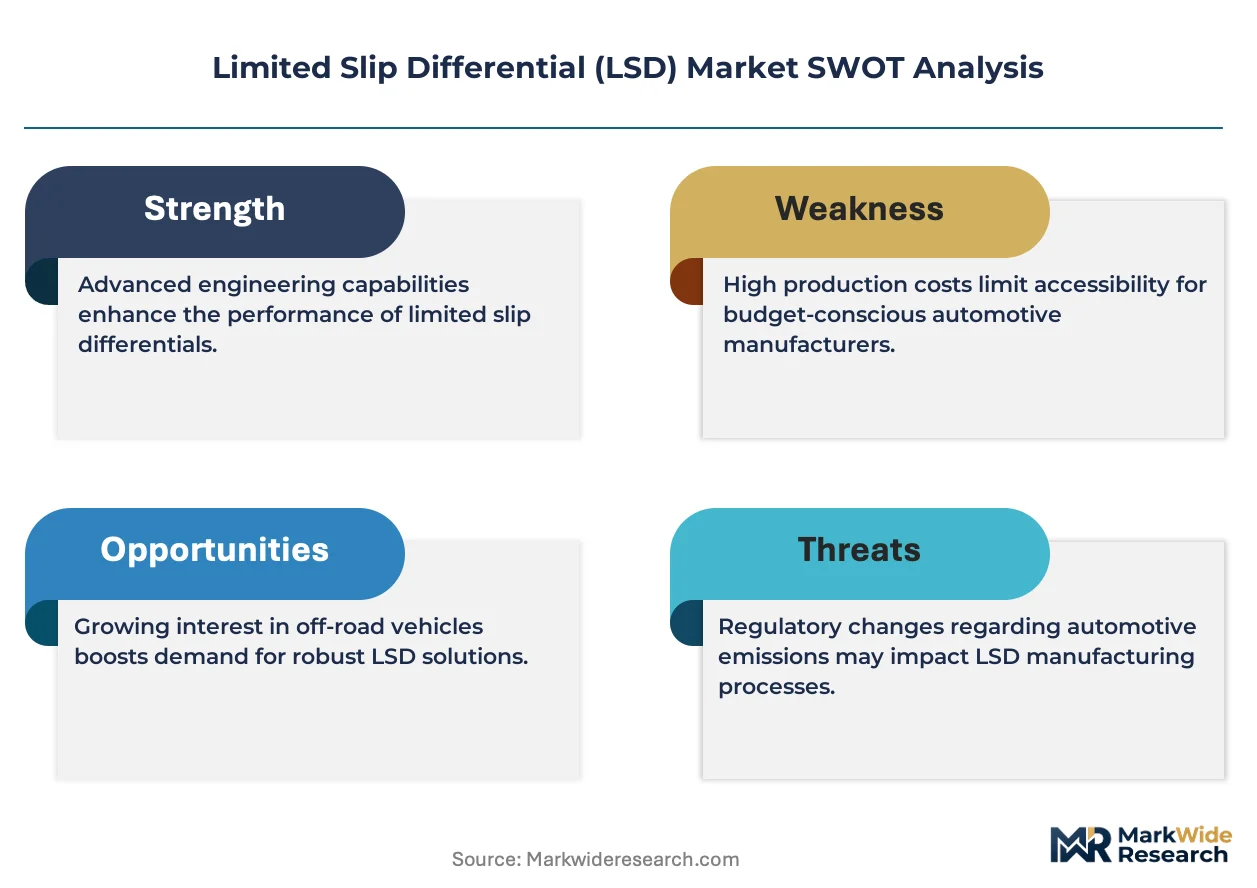
NHTSA safety standards for vehicle stability control create compliance pull for electromechanical LSD integration in US-bound platforms, while EU REACH regulations constrain friction material formulations used in clutch-pack differentials. Japan's METI energy-efficiency guidelines incentivize lighter viscous-type designs in compact passenger car segments. Stakeholders must monitor how software-defined vehicle architectures reshape hardware-software boundaries in torque management systems.
Market Dynamics
Electromechanical actuation architectures are restructuring competitive boundaries in the limited slip differential sector, compressing hardware margins while elevating software and calibration capabilities as primary value drivers.
Growth Catalysts
- NHTSA Stability Control Mandates:Federal vehicle safety standards in the United States mandate electronic stability control integration, creating compliance-driven pull for electromechanical LSD architectures in light truck and SUV platforms.
- Torque-Vectoring Performance Demand:Performance SUV manufacturers require precision torque distribution across axles, expanding clutch-type and electronic LSD specifications in premium all-wheel-drive drivetrains.
- Germany's Precision Manufacturing Ecosystem:Concentrated supplier engineering capabilities around Stuttgart and Munich enable rapid OEM prototyping cycles for next-generation geared differentials.
Market Restraints
- Friction Material Cost Volatility:EU REACH regulations constrain traditional copper and heavy-metal formulations used in clutch-pack friction plates, forcing reformulation investments that compress supplier margins.
- Electronics Supply Concentration:Semiconductor and sensor sourcing for electronic LSD modules concentrates among East Asian foundries, exposing tier-one suppliers to geopolitical disruption risk.
- Mechanical Architecture Substitution Ceiling:Purely mechanical helical and viscous LSD designs face technical limitations in real-time torque modulation, constraining their addressable market in software-defined vehicle platforms.
Strategic Opportunities
- India Commercial Vehicle Penetration:Underpenetrated heavy-duty truck and off-highway equipment segments present white-space expansion for cost-optimized clutch-type differential locking systems.
- Software-Defined Vehicle Convergence:Integration of LSD control logic with central vehicle dynamics computers enables predictive torque distribution based on navigation and sensor fusion data.
- Japan METI Energy Efficiency Incentives:Lightweight viscous-type differential designs qualify for regulatory credits in compact passenger car segments, creating policy-tied demand pull.
Industry Challenges
- Embedded Software Talent Scarcity:Torque-vectoring algorithm development requires specialized control systems engineers, with competition intensifying from autonomous driving and battery management sectors.
- Homologation Timeline Compression:FIA racing certification and OEM platform validation cycles for new differential architectures extend 18-36 months, delaying revenue recognition for advanced designs.
- Legacy Drivetrain Integration Complexity:Electromechanical LSD retrofitting into existing transmission and axle architectures demands extensive calibration engineering, fragmenting development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Limited Slip Differential (LSD) Market |
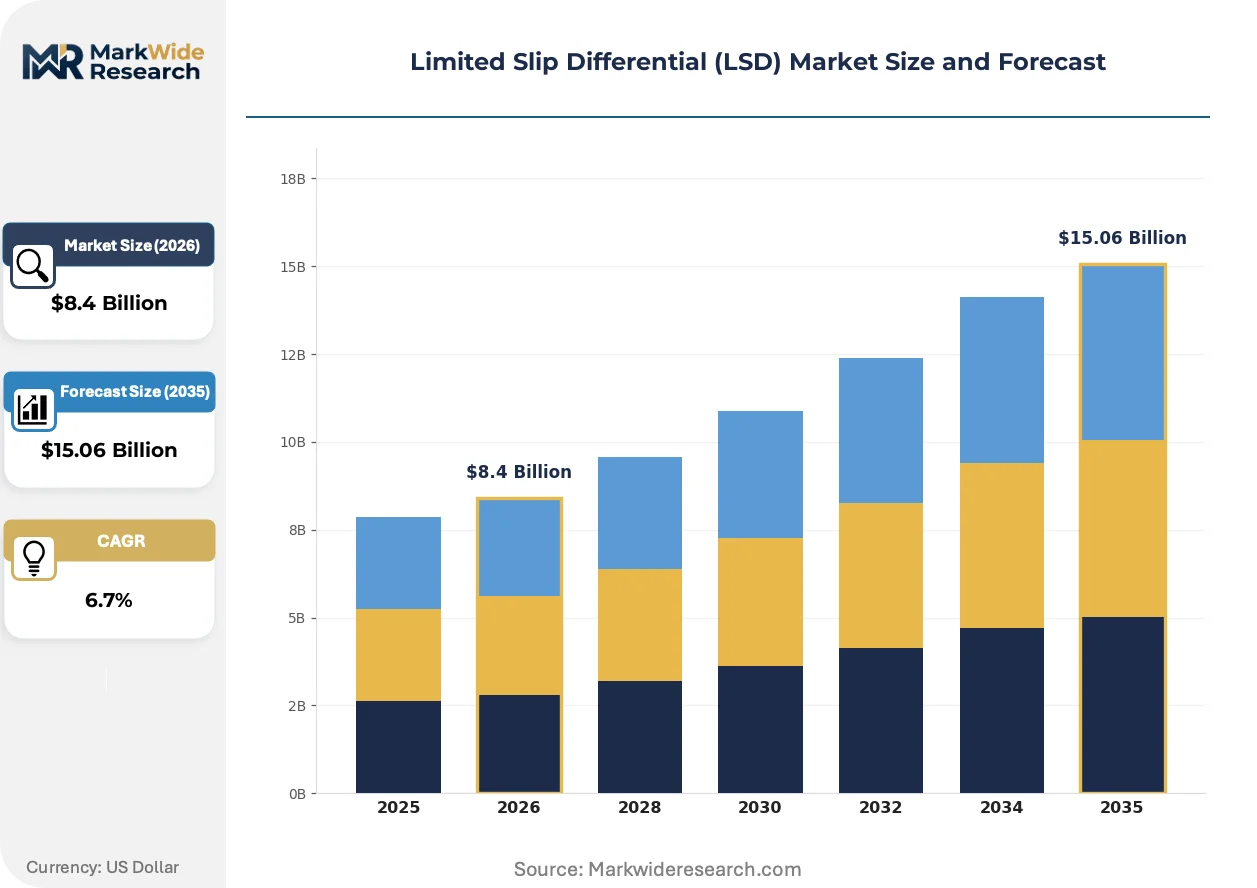
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $15.06 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Clutch Type, Geared Type, Viscous Type, Electronic Type End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Application: Passenger Cars, SUVs, Trucks, Racing Vehicles Technology: Mechanical, Hydraulic, Electromechanical, Digital |
| Companies Covered | Eaton Corporation, JTEKT Corporation, GKN Automotive, BorgWarner Inc., ZF Friedrichshafen AG, Dana Incorporated, American Axle & Manufacturing, Magna International, Drexler Automotive GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Limited Slip Differential (LSD) Market Trends and Innovations
Torque management intelligence is migrating from hardware-centric mechanical bias systems toward software-calibrated electromechanical architectures, redefining supplier value propositions and buyer procurement criteria.
Multi-plate clutch LSD technology is migrating from purely hydraulic actuation toward integrated electric motor control. Premium SUV and performance car manufacturers are specifying electronically modulated clutch packs that enable millisecond torque redistribution. This migration from mechanical to electromechanical control compresses hardware differentiation while elevating calibration IP as the primary competitive moat.
EU REACH chemical safety regulations are forcing friction material reformulation across European-sourced clutch-type differentials. The regulatory pressure bans traditional heavy-metal additives in friction plates, compelling suppliers to validate ceramic and carbon-fiber composite alternatives. German and Italian OEM supply chains are absorbing the highest compliance costs, accelerating consolidation among tier-two friction material processors.
Service unbundling is disrupting traditional aftermarket distribution for differential rebuild kits. Fleet operators and independent repair networks are sourcing friction plates, seals, and actuator modules separately rather than purchasing complete remanufactured units. This pattern concentrates in North American commercial vehicle channels where total cost of ownership analytics drive component-level procurement decisions.
Limited Slip Differential (LSD) Market Segmentation
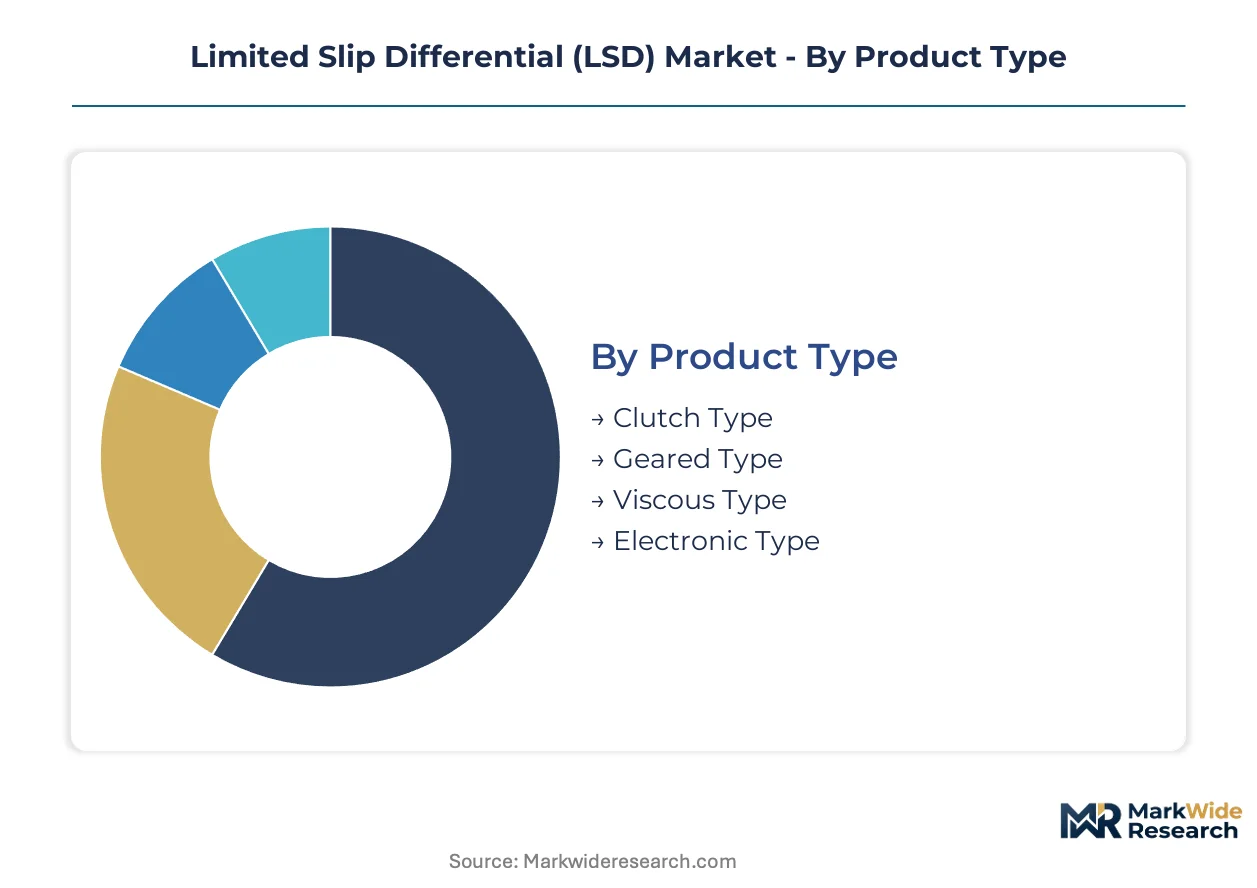
Limited slip differential segmentation reveals divergent technology maturities and diverging value capture models across the torque management landscape. Product architecture and actuation method determine margin structures, while end-user channel dynamics reshape supplier competitive positioning.
Product Type:
Mature mechanical configurations coexist with emerging electromechanical architectures, creating tiered investment requirements across supplier portfolios.
- Clutch Type:Multi-plate friction disc packs generate torque bias through spring preload and friction coefficient differentials, typically achieving 2:1 to 4:1 torque transfer ratios. Heavy-duty truck OEMs in the United States specify clutch-type units for their field-proven durability under sustained load cycles, though EU REACH friction material regulations force costly reformulation programs.
- Electronic Type:Integrated motor-actuated clutch packs or brake-based torque vectoring enable millisecond response times through vehicle dynamics controller integration. Premium SUV manufacturers in Germany and Japan specify electronic LSDs for precision torque distribution, with software calibration emerging as the primary supplier differentiator.
- Geared Type:Helical gear differentials use worm gear geometry to create speed-sensitive torque bias without friction plate wear. Compact passenger car platforms favor these units for maintenance-free operation.
- Viscous Type:Silicone fluid shear between concentric plates generates torque transfer proportional to speed differential. Japan METI energy-efficiency guidelines incentivize lightweight viscous designs in kei-car and compact segments.
Clutch-type units handle the majority of throughput; electronic type is expanding most quickly on share.
End User:
Channel concentration varies by volume scale and technical integration depth, with captive production and merchant supply competing across tier levels.
- OEMs:Vehicle manufacturers source LSDs as integrated axle or transmission subsystems, specifying torque bias curves and durability targets for platform-specific validation. German and Japanese OEMs maintain the most demanding electromechanical integration requirements.
- Tier-1 Suppliers:Axle and transmission specialists procure LSD cores for assembly into complete driveline modules, absorbing calibration responsibility and warranty exposure. North American heavy-duty channels concentrate demand here.
- Aftermarket Providers:Independent distributors and remanufacturers serve fleet operators and performance enthusiasts with replacement units and upgrade kits. Service unbundling trends in US commercial vehicle channels favor component-level procurement over complete units.
- Vehicle Assemblers:Contract manufacturers and specialty vehicle builders specify LSDs for low-volume production runs, often sourcing through distributor networks rather than direct supplier relationships.
OEMs dominate volume absorption; aftermarket providers climb the fastest as fleet age extends replacement cycles.
Application:
Vehicle category determines torque capacity requirements and actuation sophistication, with performance and utility segments pulling divergent technology specifications.
- SUVs:All-wheel-drive and four-wheel-drive platforms require axle-differential or center-differential LSDs for off-road traction and on-road stability. Torque-vectoring demand in premium SUVs accelerates electromechanical specification.
- Trucks:Heavy-duty commercial vehicles specify locking differentials for severe traction conditions, with North American Class 8 trucks representing the highest torque capacity requirements. Eaton Corporation anchors supply for this segment.
- Passenger Cars:Front-wheel-drive and rear-wheel-drive performance variants specify LSDs for launch traction and cornering balance. European hot hatch and sport sedan platforms sustain geared-type and clutch-type demand.
- Racing Vehicles:FIA-sanctioned competition categories mandate mechanical or hydraulic LSDs with minimal electronic dependency. Homologation requirements favor proven architectures with extensive track validation.
Trucks absorb the highest unit torque loads; SUVs post the steepest specification upgrade trajectory.
Technology:
Actuation method defines the hardware-software boundary, with control intelligence migration reshaping supplier value propositions.
- Electromechanical:Electric motor or solenoid actuation enables closed-loop torque control through vehicle network integration. NHTSA stability control mandates in the United States accelerate adoption in light truck platforms.
- Mechanical:Spring preload, gear geometry, or viscous shear provide passive torque bias without external power or control inputs. Cost-sensitive applications and racing homologation sustain mechanical dominance in specific niches.
- Hydraulic:Pump-generated pressure modulates clutch pack engagement in response to wheel speed differentials. Racing applications favor hydraulic systems for tunability and mechanical simplicity.
- Digital:Brake-based torque vectoring simulates differential locking through selective wheel braking, eliminating dedicated LSD hardware in some front-wheel-drive platforms. Software-defined vehicle architectures extend digital torque management scope.
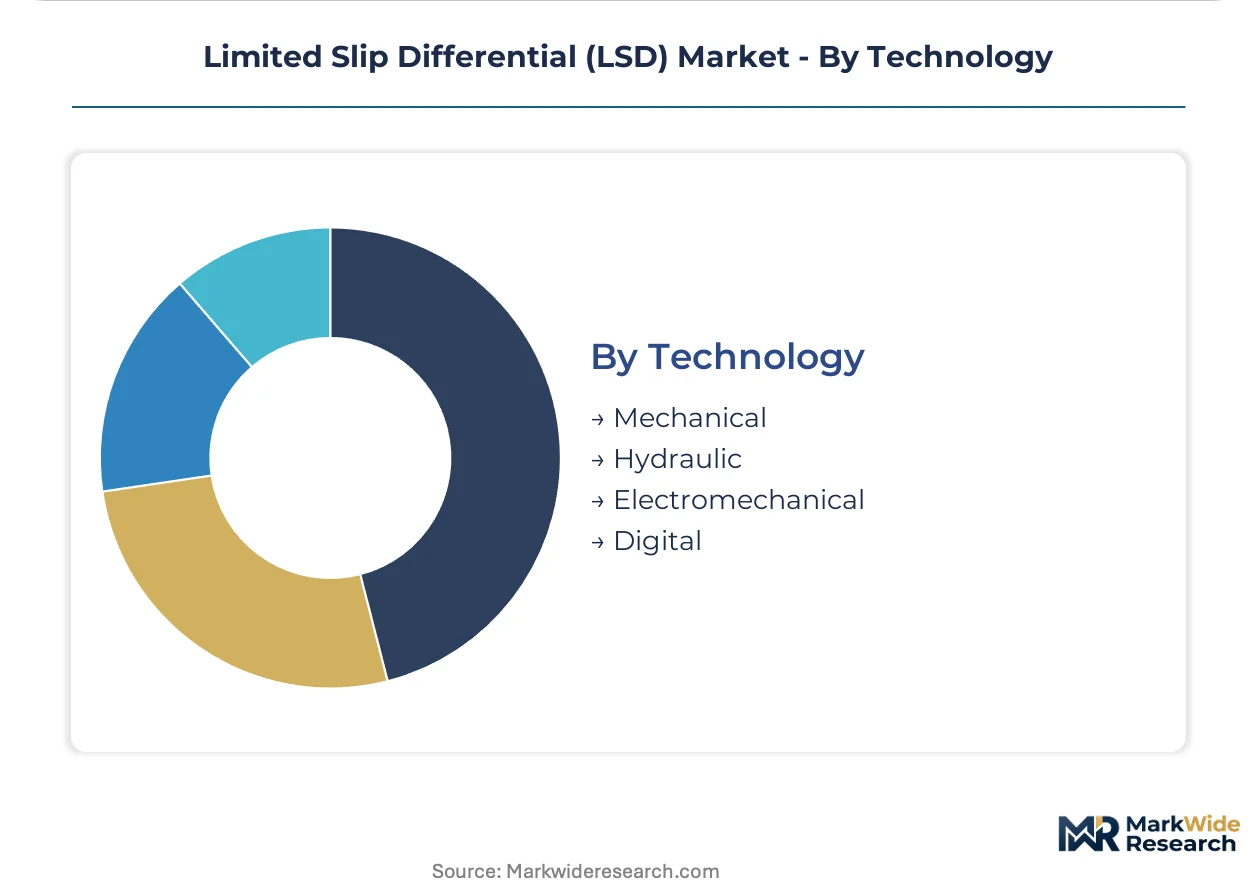
Mechanical technology retains the largest installed base; electromechanical systems gain share fastest as vehicle dynamics control integration deepens.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision-engineered LSD assemblies to premium SUV manufacturers across North America and Asia, with Stuttgart-based suppliers managing just-in-time delivery to assembly plants in the United States and Japan.
United States
Heavy-duty truck OEMs in Michigan and Ohio specify clutch-type locking differentials for Class 8 commercial vehicles. NHTSA electronic stability control mandates accelerate electromechanical LSD integration in light truck platforms. Detroit-area axle manufacturers source differential cores through consolidated tier-1 supply channels.
Germany
Premium performance SUV manufacturers around Stuttgart demand torque-vectoring differentials with millisecond response capabilities. EU REACH regulations force friction material reformulation in clutch-pack assemblies. Munich engineering clusters prototype next-generation geared differentials for all-wheel-drive platforms.
Japan
Compact passenger car producers prioritize lightweight viscous-type designs for kei-car segments. METI energy-efficiency guidelines create regulatory credits for reduced driveline mass. Nagoya-area transmission specialists integrate LSD modules into continuously variable transmission architectures.
India
Commercial vehicle assemblers in Maharashtra and Tamil Nadu represent underpenetrated demand for cost-optimized differential locking systems. The country's automotive component PLI scheme incentivizes local clutch-pack manufacturing. Pune-based heavy-duty truck builders expand specification of mechanical locking differentials for mining and construction applications.
South Korea
Domestic SUV manufacturers specify electronic torque-vectoring systems for premium all-wheel-drive variants. The national industrial regulator enforces stringent durability testing protocols for driveline components. Ulsan automotive clusters source electromechanical actuator modules through captive supplier relationships.
Limited Slip Differential (LSD) Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered supply relationships. The market structure concentrates around three to five integrated driveline suppliers with captive OEM relationships, while specialized differential manufacturers occupy niche racing and aftermarket segments. Strategic archetypes include full-system integrators owning axle-to-wheel torque management, component specialists focusing exclusively on friction plate or gear set production, and electronics-anchored suppliers leveraging powertrain control software. Dominant competitive moves encompass backward integration into friction material processing and strategic partnerships with vehicle dynamics controller suppliers.
Within the full-system integrator tier, Eaton Corporation and GKN Automotive exemplify scale-driven positioning through captive relationships with heavy-duty truck and European OEM channels respectively. BorgWarner Inc. occupies a distinctive position bridging mechanical hardware with powertrain electronics integration. These three entities represent divergent strategic bets on electromechanical convergence, with each anchoring a different geographic demand cluster and regulatory compliance framework.
| Leading Market Players |
|---|
| Eaton Corporation |
| JTEKT Corporation |
| GKN Automotive |
| BorgWarner Inc. |
| ZF Friedrichshafen AG |
| Dana Incorporated |
| American Axle & Manufacturing |
| Magna International |
| Drexler Automotive GmbH |
| Others |
Pricing and Supply Chain Analysis
East Asian semiconductor foundries and sensor module suppliers anchor electromechanical LSD production, concentrating margin capture downstream with calibration software vendors and tier-one axle integrators. Cost-plus contracts with steel and copper indexation dominate raw material procurement, while friction plate reformulation costs under EU REACH regulations compress tier-two supplier margins.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation govern friction plate and steel housing procurement, with copper and alloy steel prices passed through on quarterly adjustments. Price differentiation hinges on torque-vectoring calibration IP and NHTSA compliance certification tiers, with electronic LSD modules commanding substantial premiums over mechanical units. Pricing pressure stems from REACH-driven friction material reformulation investments, which erode clutch-type supplier margins. Fleet operators in North American commercial vehicle channels exhibit the highest price sensitivity, while German premium SUV OEMs prioritize performance specifications over unit cost.
Supply Chain Analysis
Contract manufacturing for electromechanical actuator modules concentrates among South Korean and Taiwanese EMS providers, with Bosch and Continental subsidiary operations holding significant capacity. Raw material flows draw from German precision gear steel, Japanese silicone fluid for viscous couplings, and Chinese rare-earth magnets for torque motor assemblies. Single-source vulnerability in semiconductor sensor sourcing exposes tier-one suppliers to geopolitical disruption risk. Distribution runs through captive OEM supply agreements for volume platforms, with aftermarket channels fragmenting toward component-level procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded software talent for torque-vectoring algorithm development is scarcer than mechanical engineering capacity, creating asymmetric bargaining power for control systems specialists. Suppliers must secure calibration IP and firmware capabilities to capture value in electromechanical architectures.
For Market Incumbents: Harden software calibration capabilities through acquisition of vehicle dynamics controller specialists, as brake-based torque vectoring and digital differential simulation threaten hardware attach rates. Deepen backward integration into friction material processing to absorb REACH compliance costs internally. Prioritize captive relationships with Stuttgart and Nagoya engineering clusters where OEM integration requirements are most demanding. For New Entrants and Emerging Players: Pursue white-space expansion in Indian heavy-duty truck differential locking systems, where PLI scheme incentives and underpenetrated mining equipment fleets create accessible entry points. Target cost-optimized mechanical clutch-type architectures for Maharashtra-based commercial vehicle assemblers. Establish technical partnerships with Pune-based axle manufacturers to bypass direct OEM validation cycles. For Investors and Strategic Acquirers: Capital is best deployed toward tier-two calibration software houses with embedded vehicle dynamics expertise, as electromechanical convergence elevates firmware margins over hardware manufacturing. Long-term viability favors suppliers with dual competence in mechanical durability and closed-loop torque control. Monitor NHTSA rulemaking on stability control mandate expansion as the primary demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Software-Defined Vehicle Investment | Integration of LSD control with central domain controllers enables predictive torque distribution using navigation data. |
| Backward Integration into Friction Materials | In-house ceramic and carbon-fiber composite production absorbs EU REACH compliance costs and secures supply continuity. |
| Geographic Manufacturing Footprint | Pune and Chennai production facilities capture Indian PLI incentives and reduce logistics exposure for commercial vehicle platforms. |
| Platform Standardization | Modular clutch-pack architectures across SUV and truck segments amortize validation engineering across higher volumes. |
| Strategic Partnership with Sensor Suppliers | Long-term offtake agreements with South Korean EMS providers mitigate semiconductor concentration risk in actuator modules. |
Research Methodology
Operator-level perspectives from OEM platform engineers, tier-one axle procurement managers, aftermarket fleet maintenance directors, and racing homologation specialists anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation through NHTSA regulatory filings, EU REACH substance restriction updates, METI energy-efficiency guideline documentation, and vehicle production databases from IHS Markit. Bottom-up segment sizing triangulated against top-down macroeconomic overlays to ensure internal consistency.
Scenario-bracketing around regulatory adoption timelines and electrification penetration rates structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product architecture, actuation method, vehicle class, OEM tier positioning, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to unit shipment and value-per-unit trajectories, with torque-vectoring adoption curves and friction material cost pass-through assumptions as key forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in automotive production cycles, copper price volatility, or semiconductor availability would shift the trajectory. Forecasts reflect documented assumptions on regulatory enforcement timing and OEM platform refresh cadence. Quarterly review of NHTSA rulemaking dockets, EU ECHA substance restriction proposals, and Indian PLI scheme disbursement data is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Brake Hoses Market
Vehicle Components
Passenger Car Sensors Market
Vehicle Components
Bicycle Chain Tensioner Market
Vehicle Components
Trailers and Semi-Trailers Market
Vehicle Components
Rear Axle Market
Vehicle Components
Bicycle Brake Cable Market
Vehicle Components
Wheel Studs Market
Vehicle Components
Automotive Air Flow Sensors Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
Global Undercarriage Components Market
Vehicle Components
Trailer Axle Market
Vehicle Components
Bicycle Front Hub Market
Vehicle Components
Composite Bearings Market
Vehicle Components
Autonomous Trains Components Market
Vehicle Components
Automotive Position Sensor Market
Vehicle Components
Latin America Two-Wheeler Components Market