
 Digital Tire Inflator Market | 2026-2036
Digital Tire Inflator Market Size, Share, and Industry Trends Forecast 2026-2036
Digital Tire Inflator Market Outlook
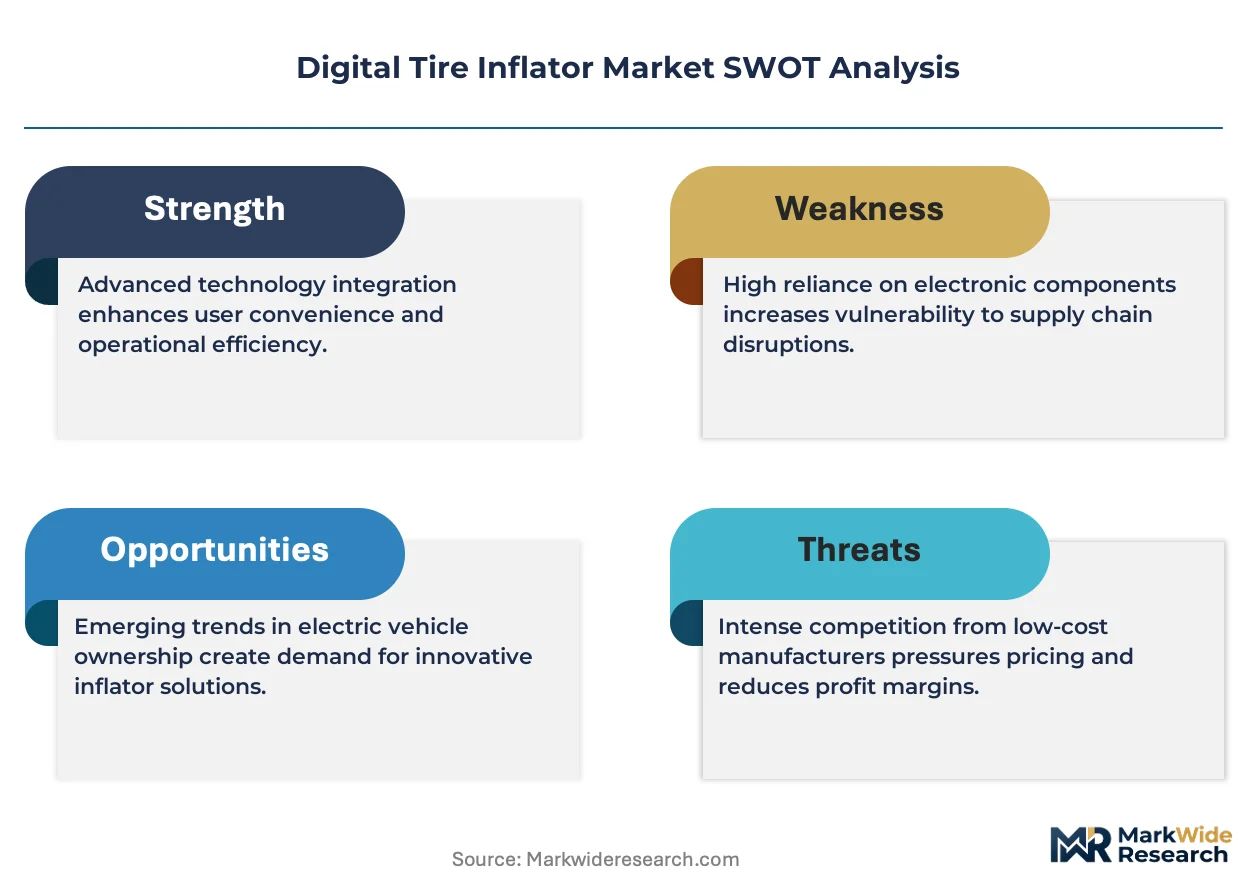
E-commerce distribution is rewriting how digital tire inflators reach end buyers, with direct-to-consumer platforms displacing traditional automotive retail networks. Milwaukee leverages its battery ecosystem dominance to anchor premium cordless inflator sales through professional trade channels. Fanttik competes on compact portability, while AstroAI specializes in multi-functional units that integrate pressure sensing with emergency lighting.
A digital tire inflator is a precision pneumatic device employing electronic pressure sensors and microprocessor-controlled motors to deliver calibrated airflow to vehicle tires, typically achieving accuracy within one PSI and operating via 12V DC, lithium-ion battery, or 120V AC power sources. Its primary commercial purpose is to eliminate manual gauge reading errors while enabling preset inflation cycles for automotive service efficiency. Portable units lead consumer-facing revenue due to roadside emergency appeal, while heavy-duty configurations capture margin pools in fleet maintenance bays where durability specifications command premium positioning. Battery-operated power sources represent the fastest-growing segment as lithium-ion energy density improvements enable cordless operation at previously unattainable pressure outputs.
NHTSA enforces tire pressure monitoring system compliance that indirectly stimulates aftermarket digital inflator demand, while EPA fuel economy standards heighten manufacturer emphasis on optimal tire inflation. China's SAMR administers GB standards for automotive electrical accessories that govern digital inflator safety certifications for domestic and export markets. Stakeholders must monitor evolving battery transportation regulations and regional voltage standard harmonization to determine manufacturing localization and product certification sequencing.
Market Dynamics
Battery chemistry advances and cordless motor efficiency gains are compressing the performance gap between portable and fixed-bay tire inflators, forcing incumbent suppliers to reconfigure product portfolios around lithium-ion ecosystems rather than pneumatic tethering.
Growth Catalysts
- NHTSA TPMS mandates:US commercial fleet regulations indirectly stimulate aftermarket digital inflator procurement as operators standardize maintenance protocols across vehicle classes.
- Automotive workshop digitization:China's domestic service centers upgrade from mechanical gauges to microprocessor-controlled units, driving replacement demand for precision inflation equipment.
- Lithium-ion energy density improvements:Higher-capacity battery cells enable cordless operation at pressure outputs previously restricted to AC-powered units, expanding addressable use cases.
Market Restraints
- Cobalt and lithium price volatility:Battery pack input costs fluctuate with mining supply constraints, compressing margins on cordless product lines.
- GB standards compliance complexity:China's SAMR certification requirements for automotive electrical accessories create extended approval timelines for export-oriented manufacturers.
- Pneumatic tethering legacy infrastructure:Established fleet maintenance bays with compressed air systems face sunk-cost disincentives against cordless conversion.
Strategic Opportunities
- Emergency roadside service unbundling:Insurance and mobility service providers seek white-label portable inflators as customer retention tools, creating B2B2C channel expansion.
- Dual carbon goals alignment:China's national emissions targets incentivize tire pressure optimization as fuel economy lever, elevating inflator status from commodity to compliance instrument.
- Smart pressure sensing convergence:Integration of Bluetooth connectivity and fleet telematics enables predictive maintenance workflows for logistics operators.
Industry Challenges
- Battery transportation certification delays:UN 38.3 lithium-ion testing protocols and IATA shipping restrictions complicate inventory positioning across regional distribution centers.
- Cross-voltage standard harmonization:Divergent AC input requirements between North American 120V and European 230V markets fragment SKU rationalization efforts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Digital Tire Inflator Market |
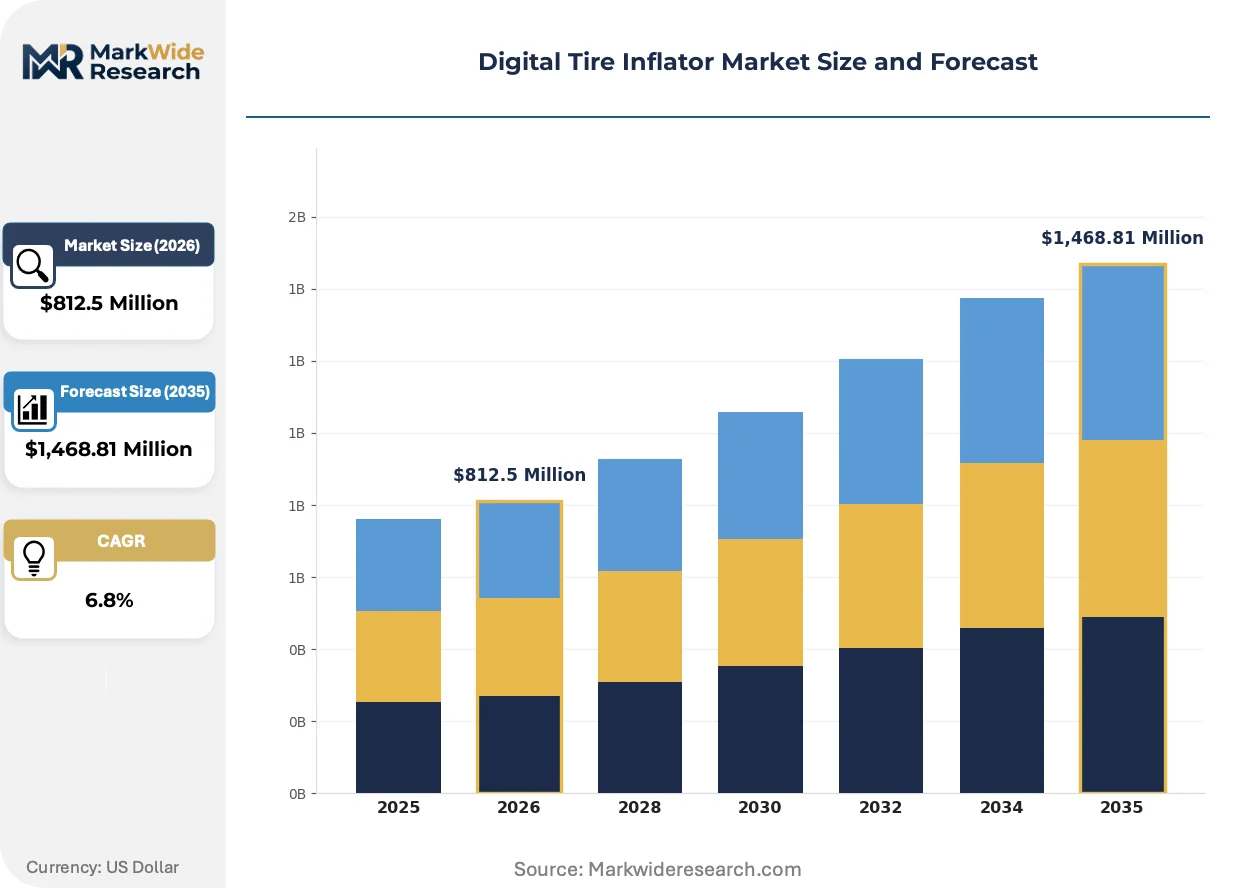
| Market Size in 2026 | $812.5 Million |
| Market Size in 2035 | $1,468.81 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable, Built-in, Multi-functional, Heavy-Duty Power Source: Battery-Operated, Electric, DC, Manual End User: Consumers, Vehicle Manufacturers, Automotive Workshops, Fleet Operators Distribution Channel: Online Retail, Specialty Stores, Automotive Stores, Wholesale |
| Companies Covered | Baseus, Milwaukee, Fanttik, Slime, Avid Power, AstroAI, Viair, Ring Automotive, DeWalt, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Digital Tire Inflator Market Strategic Shifts
Sensor miniaturization and algorithmic pressure control are elevating digital tire inflators from simple pneumatic tools to connected maintenance endpoints, with implications for how fleet operators structure roadside service workflows and inventory spare tire strategies.
Brushless DC motor technology is migrating from premium cordless power tools into mid-tier tire inflators, delivering higher torque density and thermal efficiency. Fleet maintenance departments in North America are adopting these units for roadside truck tire service, displacing pneumatic impact wrench tethering requirements and enabling mobile repair operations without compressor support.
EPA fuel economy standards enforcement is tightening manufacturer emphasis on optimal tire inflation as a compliance pathway. Vehicle OEMs now specify precision inflator protocols for dealership service departments, with California Air Resources Board alignment pressures extending these requirements to heavy-duty commercial segments seeking emissions credits.
Direct-to-consumer platform purchasing is compressing traditional automotive retail distribution for portable inflator categories. Amazon and specialty e-commerce channels capture volume from auto parts chains, with Germany and UK markets showing strongest channel shift velocity as DIY vehicle maintenance culture intersects with subscription delivery preferences.
Digital Tire Inflator Market Segmentation
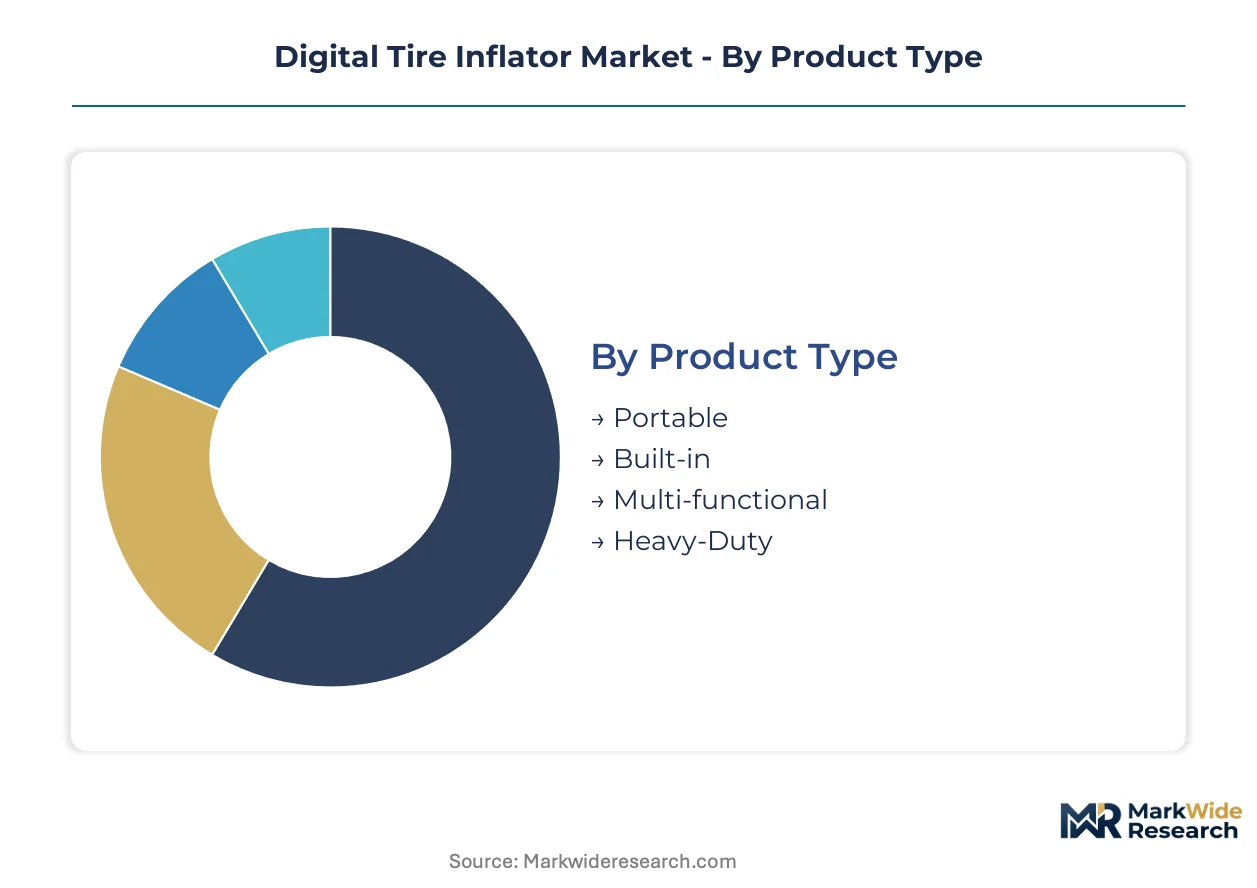
Digital tire inflator purchasing patterns diverge sharply across use-case intensity, from emergency roadside consumers to precision-calibrated fleet maintenance protocols. Segment boundaries are blurring as lithium-ion portability erases traditional divides between consumer convenience and commercial-grade performance.
Product Type:
Cycle times vary dramatically: portable units turn inventory fastest through e-commerce impulse channels, while heavy-duty configurations sit in procurement cycles stretching 12-18 months for fleet authorization.
- Portable:Compact lithium-ion units with integrated pressure sensors and preset inflation cycles dominate consumer-facing revenue through Amazon and direct-to-consumer platforms. Emergency roadside appeal drives replacement purchases every 3-5 years as battery degradation accelerates obsolescence.
- Heavy-Duty:Fixed-bay pneumatic systems with high-flow compressors and reinforced hose assemblies command premium positioning in commercial fleet maintenance facilities. North American trucking operators specify these units for 24/7 uptime requirements despite higher capital outlay.
- Built-in:Vehicle-integrated compressor systems factory-installed in pickup trucks and commercial vans.
- Multi-functional:Hybrid units combining inflation with emergency lighting, USB charging, and tire pressure monitoring integration.
Portable units anchor the volume base while heavy-duty configurations gain share at the steepest rate as fleet electrification eliminates onboard pneumatic infrastructure.
Power Source:
Cost tier stratification runs from premium cordless ecosystems to economy manual alternatives, with battery-operated systems capturing margin expansion as energy density improvements justify price premiums.
- Battery-Operated:Brushless DC motor systems powered by 18V-40V lithium-ion packs deliver cordless mobility at pressure outputs previously restricted to AC tethering. China's domestic automotive workshops upgrade to these units as GB standards compliance costs decline.
- Electric:120V AC stationary compressors with continuous-duty motors serve dealership service departments requiring sustained high-volume inflation.
- DC:12V vehicle-powered units plug into cigarette lighter sockets for roadside emergency use.
- Manual:Foot-pump and hand-pump mechanical systems retain niche demand in price-sensitive emerging markets.
Electric systems retain installed-base dominance in fixed facilities while battery-operated configurations climb the fastest as cordless performance gaps close.
End User:
Application intensity separates occasional DIY consumers from protocol-driven commercial operators, with automotive workshops representing the densest concentration of replacement demand.
- Automotive Workshops:Precision-calibrated service bay equipment with NIST-traceable pressure accuracy supports warranty compliance and customer retention protocols. China's SAMR certification requirements accelerate upgrade cycles from mechanical gauges to microprocessor-controlled units.
- Fleet Operators:Standardized maintenance protocols across vehicle classes drive bulk procurement of battery-operated units for roadside service efficiency. NHTSA TPMS mandates indirectly stimulate aftermarket digital inflator adoption as operators harmonize equipment across truck classes.
- Consumers:Emergency preparedness purchases through online retail channels with price-sensitive feature tradeoffs.
- Vehicle Manufacturers:Bundled accessory specifications for new commercial fleet deliveries.
Automotive workshops anchor replacement volume while fleet operators expand procurement fastest as telematics integration enables predictive maintenance workflows.
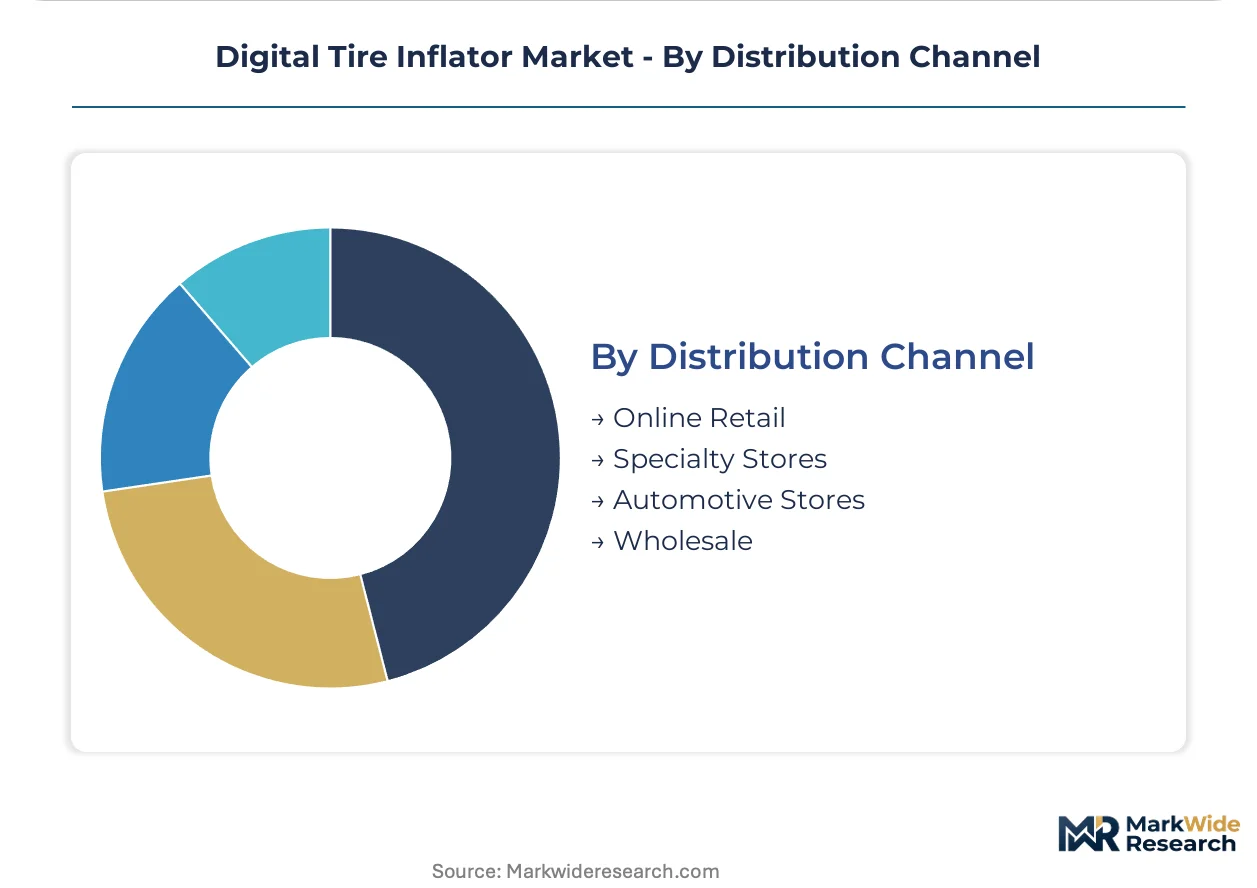
Distribution Channel:
Customer type alignment separates self-directed online purchasers from relationship-dependent wholesale accounts, with channel migration accelerating as technical specifications standardize.
- Online Retail:Amazon and specialty e-commerce platforms displace traditional automotive retail through subscription delivery preferences and review-driven selection. Germany and UK markets show strongest channel shift velocity as DIY maintenance culture intersects with digital purchasing habits.
- Wholesale:Distributor networks serving independent repair shops and fleet maintenance departments with volume pricing and technical support. Procurement consolidation among multi-location operators compresses vendor counts.
- Specialty Stores:Outdoor recreation and camping retailers targeting adventure vehicle owners.
- Automotive Stores:Auto parts chains with counter staff consultation for compatibility verification.
Wholesale retains fleet and commercial lock-in while online retail expands most quickly as portable unit specifications commoditize.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Shanghai anchors Asia-Pacific logistics corridors for lithium-ion battery cells and precision motor components feeding digital tire inflator assembly lines across the Yangtze River Delta manufacturing belt.
United States
NHTSA tire pressure monitoring mandates drive fleet operator standardization of maintenance equipment across commercial vehicle classes. EPA fuel economy standards tighten manufacturer emphasis on optimal tire inflation protocols. Detroit-area automotive service clusters upgrade dealership service bays with precision-calibrated digital inflator systems.
China
Domestic automotive workshops accelerate replacement of mechanical gauges with microprocessor-controlled units under GB standards compliance pressure. SAMR certification requirements for automotive electrical accessories govern safety protocols for export-bound production. Shenzhen electronics manufacturing hubs concentrate brushless DC motor assembly for cordless inflator platforms.
Germany
KBA vehicle inspection standards elevate tire pressure accuracy requirements for commercial fleet compliance documentation. EU Green Deal emissions targets incentivize tire optimization as fuel economy lever for logistics operators. Stuttgart automotive engineering clusters develop integrated pressure sensing systems for OEM bundled accessory specifications.
Japan
METI industrial efficiency programs promote workshop digitization among domestic service centers transitioning from pneumatic tethering. JIS standards for automotive electrical accessories establish certification baselines for precision inflation equipment. Nagoya manufacturing corridors supply high-torque density brushless motors for premium cordless configurations.
India
BIS quality control orders for automotive components tighten import certification requirements for digital inflator safety specifications. PLI scheme incentives for advanced chemistry cell manufacturing reduce battery pack input costs for domestic cordless assembly. Chennai automotive component clusters expand precision sensor sourcing for workshop-grade equipment.
Digital Tire Inflator Market Competitive Environment
On the supply side, the industry is bifurcated between battery ecosystem incumbents and specialist pneumatic tool manufacturers, with mid-tier challengers compressing price bands through direct-to-consumer platform access. Three strategic archetypes dominate: power tool conglomerates leveraging cordless battery platform dominance, automotive accessory specialists integrating multi-functional feature sets, and compact portability innovators targeting emergency roadside demand. Competitive moves center on lithium-ion ecosystem lock-in through battery platform compatibility and e-commerce channel capture bypassing traditional automotive retail networks.
Within the battery ecosystem tier, Milwaukee and DeWalt exemplify power tool conglomerates extending cordless platform dominance into tire inflation categories. Fanttik occupies a position among compact portability specialists, while AstroAI represents the multi-functional integration archetype combining pressure sensing with auxiliary emergency features. These anchors illustrate how competitive positioning stratifies across professional trade channels, direct-to-consumer platforms, and automotive retail networks respectively.
| Leading Market Players |
|---|
| Baseus |
| Milwaukee |
| Fanttik |
| Slime |
| Avid Power |
| AstroAI |
| Viair |
| Ring Automotive |
| DeWalt |
| Others |
Value Chain & Pricing Dynamics
Cobalt and lithium price volatility from mining supply constraints in the Democratic Republic of Congo and Chile compresses margin pools across cordless product tiers while simultaneously forcing manufacturers toward dual-sourcing strategies that reshape regional assembly footprints.
Pricing Analysis
Volume-discount tiering structures separate fleet procurement contracts from individual consumer transactions. Three-tier pricing stratifies across premium brushless motor configurations with NIST-traceable calibration, standard lithium-ion units for automotive workshops, and economy DC-powered alternatives for price-sensitive emergency purchasers. Cost compression in the economy tier intensifies as direct-to-consumer platforms displace retail markups. Fleet operators exhibit lowest price sensitivity due to total-cost-of-ownership calculations, while roadside consumers prioritize unit economics over specification depth.
Supply Chain Analysis
Tariff exposure between China and North America dominates supply chain risk calculations for battery pack and precision sensor sourcing. Manufacturing concentrates in Shenzhen electronics corridors for brushless DC motors, Yangtze River Delta assembly facilities for finished units, and Nagoya precision engineering clusters for high-torque density components. Lithium-ion cells, pressure sensor MEMS, and reinforced hose assemblies draw from geographically concentrated supplier bases. Distribution runs through Port of Shanghai logistics nodes for Asia-Pacific fulfillment and Rotterdam warehousing for European market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as lithium-ion energy density improvements unlock cordless performance parity with AC-tethered systems, accelerating replacement demand from pneumatic infrastructure.
For Market Incumbents: Pre-empt cordless platform fragmentation by locking fleet operators into proprietary battery ecosystem contracts before Milwaukee and DeWalt extend power tool dominance. Deepen backward integration into brushless motor production through Nagoya engineering partnerships to defend margin pools against mid-tier challengers. Accelerate SAMR pre-certification for GB standards compliance to capture China's workshop upgrade cycle ahead of export-oriented competitors. For New Entrants and Emerging Players: Pursue white-space positioning in white-label portable units for insurance roadside assistance programs, where B2B2C channel structures bypass established retail gatekeepers. Target India's PLI-subsidized battery assembly corridors for cost-advantaged cordless production serving domestic price-sensitive demand. Anchor go-to-market through Amazon subscription delivery models in Germany and UK markets where DIY maintenance culture intersects with digital purchasing habits. For Investors and Strategic Acquirers: The market sits at a platform-consolidation phase that favors battery ecosystem specialists with captive cell supply agreements. Long-term viability hinges on lithium-ion chemistry roadmaps and regulatory harmonization across NHTSA, SAMR, and KBA jurisdictions. Monitor UN 38.3 certification backlogs as inflection signal for inventory positioning delays that favor regional assembly investments over pure export plays.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Ecosystem Lock-In | Proprietary 18V-40V platforms anchor fleet procurement contracts through Milwaukee and DeWalt compatibility. |
| GB Standards Pre-Certification | SAMR compliance acceleration captures China's automotive workshop digitization replacement cycle. |
| White-Label B2B2C Partnerships | Insurance roadside programs create defensible channel positions outside retail price compression. |
| Brushless Motor Backward Integration | Nagoya engineering partnerships secure torque density advantages for premium cordless configurations. |
| Direct-to-Consumer Platform Capture | Amazon and specialty e-commerce displace auto parts chains in Germany and UK portable segments. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with fleet maintenance directors, automotive workshop owners, battery procurement managers, and aftermarket distribution heads; and secondary validation through NHTSA regulatory filings, SAMR certification databases, UN 38.3 transportation test protocols, and customs trade records for lithium-ion battery exports. Bottom-up triangulation against top-down production capacity estimates from Yangtze River Delta and Shenzhen manufacturing clusters anchored volume assumptions.
Forecast inputs considered product type segmentation across portable, heavy-duty, and multi-functional configurations; power source differentiation between battery-operated, AC electric, and DC vehicle-powered systems; and end-user intensity variation from consumer emergency purchases to protocol-driven fleet standardization. CAGRs derived from replacement cycle analysis, workshop upgrade penetration curves, and cordless performance parity milestones. Lithium-ion energy density improvement trajectories and TPMS mandate compliance timelines shaped adoption curve assumptions across the projection horizon.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by power tool conglomerates or sudden cobalt supply disruptions would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
Forestry Trailers Market
Vehicle Components
Forklift Seats Market
Vehicle Components
Wheelhouse Liner Market
Vehicle Components
Rail Wheel Market
Vehicle Components
Automotive Exhaust Gas Sensor Market
Vehicle Components
UK Automotive Carbon Fiber Composites Market
Vehicle Components
Freight Railcar Parts Market
Vehicle Components
2 Wheeler Fuel Injection System Market
Vehicle Components
South Africa Automotive Carbon Fiber Composites Market
Vehicle Components
HCV Axles Market
Vehicle Components
Steering Tie Rod Market
Vehicle Components
Airport Ground Support Vehicle Market
Vehicle Components
High Security Registration Plates Market
Vehicle Components
Tailgate Chip Spreader Market
Vehicle Components
Front Forks Market
Vehicle Components
Air Brake Reservoirs Market