
 Colloidal Metal Particles Market | 2026-2036
Colloidal Metal Particles Market Size, Share, and Industry Trends Forecast 2026-2036
Colloidal Metal Particles Market Analysis
Germany's precision chemical corridor is narrowing the gap between laboratory-scale synthesis and industrial throughput for noble metal colloids. BASF SE leverages its Ludwigshafen integrated site to control precursor supply chains for pharmaceutical-grade gold nanoparticles. Sigma-Aldrich sustains dominance in research-grade materials through Merck Group's global distribution network for analytical standards. Johnson Matthey Plc anchors catalytic applications with specialized palladium colloid portfolios for hydrogenation processes.
Colloidal metal particles are nanoscale dispersions of metallic elements—typically 1–100 nm in diameter—stabilized in liquid media by surfactants, polymers, or electrostatic repulsion to prevent agglomeration. Chemical reduction remains the dominant manufacturing route, though laser ablation gains traction for producing ligand-free surfaces in biomedical formulations. Gold nanoparticles command the premium segment due to established bioconjugation protocols for imaging and therapeutic delivery, while silver nanoparticles compete aggressively in antimicrobial coatings where cost sensitivity shapes procurement decisions. Palladium colloids occupy a specialized niche in catalysis, with margin pools concentrated in batch consistency for pharmaceutical intermediates.
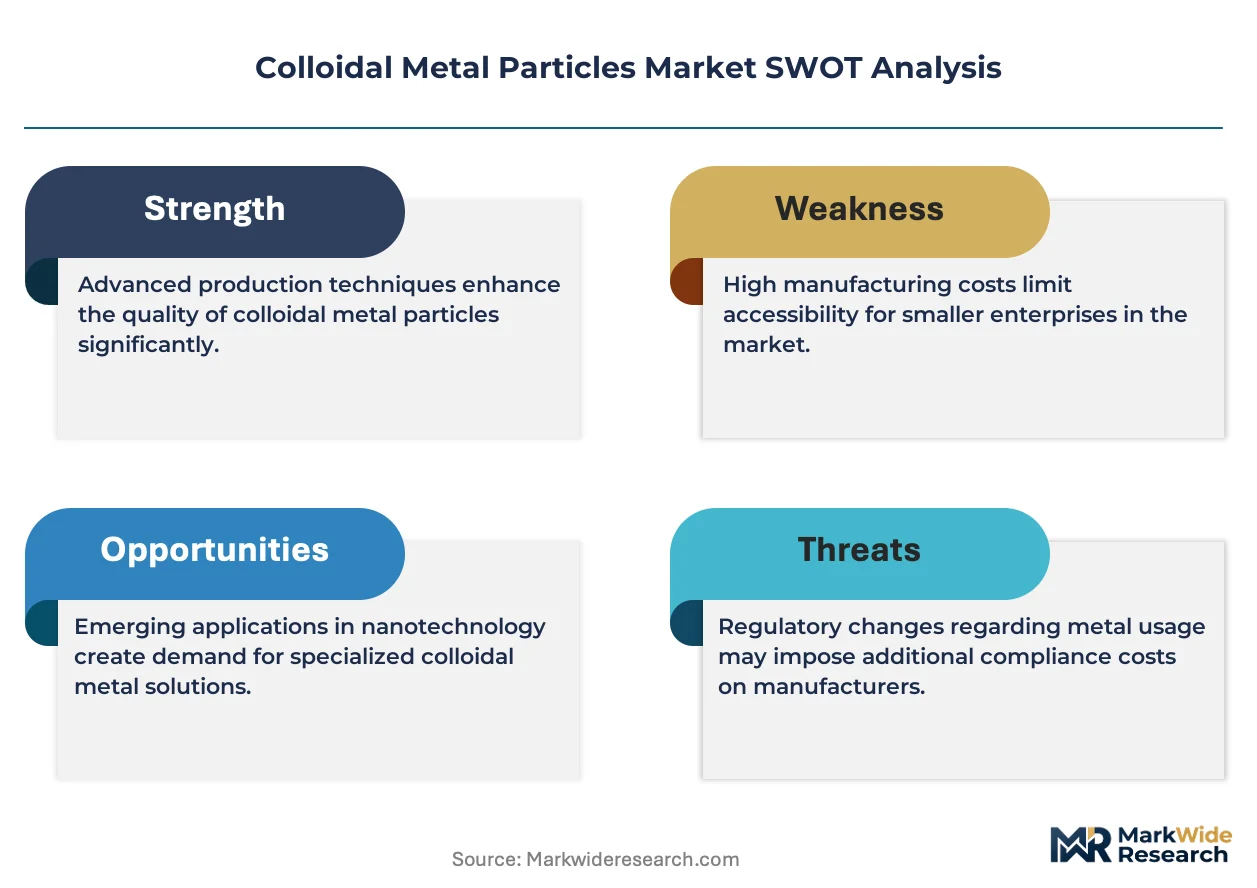
EPA nanomaterial reporting rules under the Toxic Substances Control Act shape market access for US-sourced colloids, while REACH registration requirements in Europe mandate extensive toxicity dossiers for silver and copper variants above threshold volumes. ISO/TS 19337 provides the analytical benchmark for size distribution characterization, yet harmonization gaps between FDA guidance for nanomaterial drugs and EMA reflection papers create compliance friction for multinational suppliers. Stakeholders must monitor evolving definitions of "nanomaterial" in regulatory frameworks, as threshold adjustments could reclassify entire product lines and trigger additional safety testing obligations without warning.
Market Dynamics
The colloidal metal particles market is undergoing structural recalibration as REACH registration dossiers force silver and copper variant manufacturers to consolidate production in fewer, higher-capability facilities. This regulatory compression is concentrating supply-side power while downstream buyers face elongated qualification timelines for new sources.
Growth Catalysts
- Plasmonic biosensing platforms:Clinical laboratories in Germany and Switzerland are integrating gold nanoparticle-based diagnostic assays at accelerating pace, driving pharmaceutical-grade demand.
- EPA nanomaterial reporting under TSCA:US-based manufacturers achieving early compliance are capturing preferential supply relationships with federally funded research institutions.
- Laser ablation synthesis:Ligand-free surface production is expanding addressable applications in intracellular imaging where chemical reduction residues previously blocked regulatory approval.
Market Restraints
- Silver price volatility:Antimicrobial coating manufacturers face margin compression when London Bullion Market Association spot prices spike, forcing formula adjustments or pass-through failures.
- Precursor supply concentration:Chloroauric acid and palladium chloride feedstocks cluster in South African platinum group metal refining corridors, exposing buyers to logistics disruptions.
- Batch-to-batch size distribution variance:Chemical reduction protocols without inline dynamic light scattering feedback produce out-of-specification material that fails ISO/TS 19337 certification.
Strategic Opportunities
- India's CDSCO nanomaterial pathway:The regulator's emerging framework for pharmaceutical-grade colloids creates first-mover advantage for suppliers establishing local analytical partnerships.
- Photothermal therapy convergence:Near-infrared-responsive gold nanorods combined with checkpoint inhibitor protocols are opening oncology applications beyond diagnostic imaging.
- Direct-to-laboratory distribution:Research-grade material suppliers are bypassing traditional chemical distributor markups through specialized e-commerce platforms serving academic core facilities.
Industry Challenges
- Surface chemist scarcity:Formulation scientists capable of tuning zeta potential for specific bioconjugation protocols command premium compensation, constraining R&D expansion.
- Multi-jurisdiction dossier harmonization:Suppliers must maintain parallel FDA IND-supporting documentation and EMA quality modules without unified submission templates, duplicating regulatory affairs overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Colloidal Metal Particles Market |
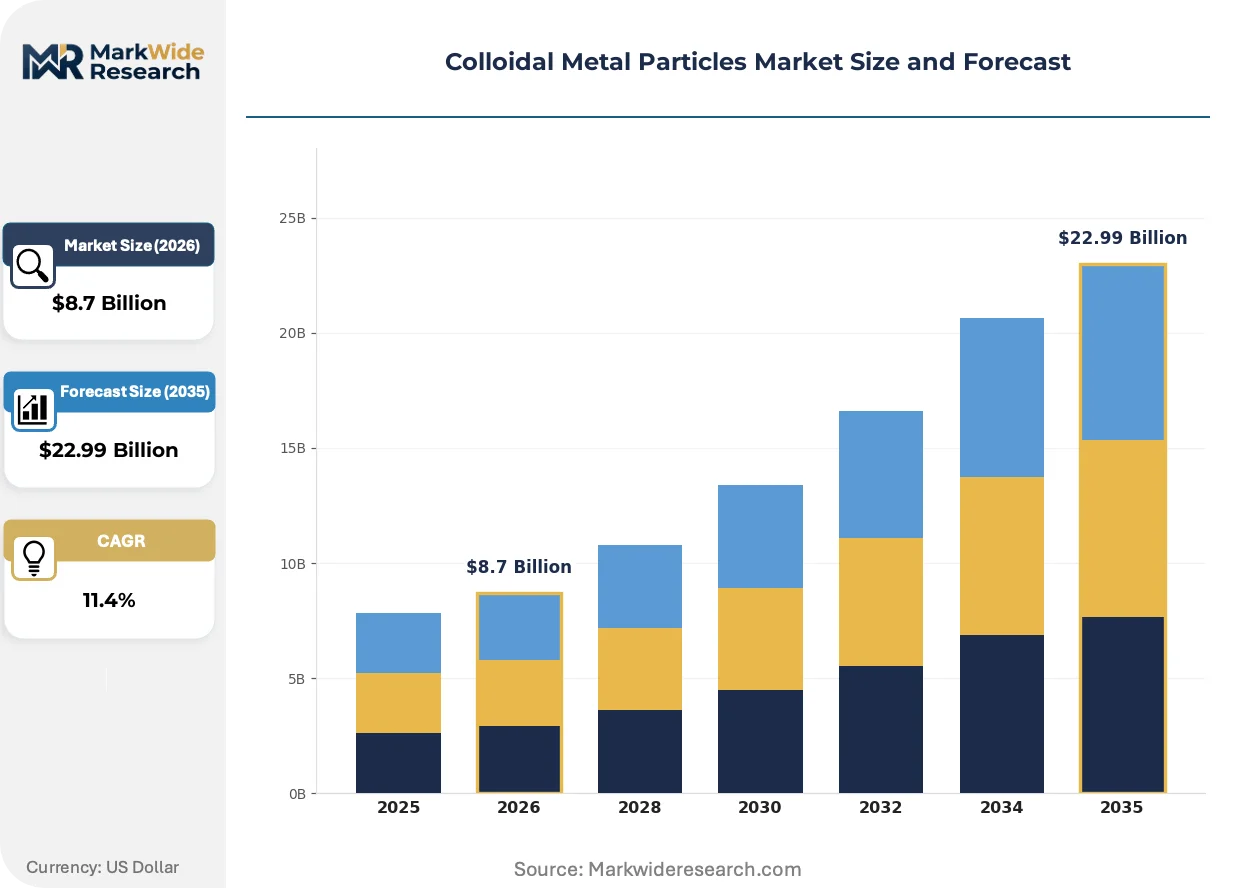
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gold Nanoparticles, Silver Nanoparticles, Copper Nanoparticles, Palladium Nanoparticles Application: Biomedical Applications, Electronics, Catalysis, Environmental Remediation Technology: Solvated Metal Deposition, Chemical Reduction, Laser Ablation, Electrochemical Synthesis End User: Pharmaceuticals, Electronics Manufacturers, Research Institutions, Environmental Agencies |
| Companies Covered | BASF SE, Sigma-Aldrich (Merck Group), nanoComposix, Strem Chemicals, SkySpring Nanomaterials, American Elements, Johnson Matthey Plc, Meliorum Technologies, BBI Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Colloidal Metal Particles Market Emerging Trajectories
Manufacturing protocols and buyer qualification standards are diverging sharply between pharmaceutical-grade and industrial-grade material streams. This bifurcation is forcing suppliers to choose capability investments rather than serving both tiers from common production assets.
Laser ablation synthesis is migrating from academic research settings to contract manufacturing organizations serving diagnostic developers. CDMOs in Germany and Massachusetts are installing femtosecond systems to produce ligand-free gold and silver colloids for conjugation-sensitive applications. This equipment transition is compressing the addressable market for traditional citrate-reduced material in high-value segments.
REACH Article 57 authorization requirements for certain surfactant stabilizers are compelling reformulation of legacy colloidal silver products. ECHA's 2023-2024 candidate list expansions have flagged cetyltrimethylammonium bromide and related quaternary ammonium compounds, forcing antimicrobial coating manufacturers toward polyethylene glycol or polysorbate alternatives. German and Dutch formulators are absorbing requalification costs fastest due to existing analytical infrastructure.
Academic core facilities are consolidating procurement through group purchasing organizations rather than maintaining individual supplier relationships. University of California and Max Planck Society systems now negotiate framework agreements for research-grade colloids, displacing fragmented laboratory-level purchasing. This concentration is visible most acutely in gold nanoparticle standards for electron microscopy calibration, where volume commitments now determine pricing tiers.
Colloidal Metal Particles Market Segmentation
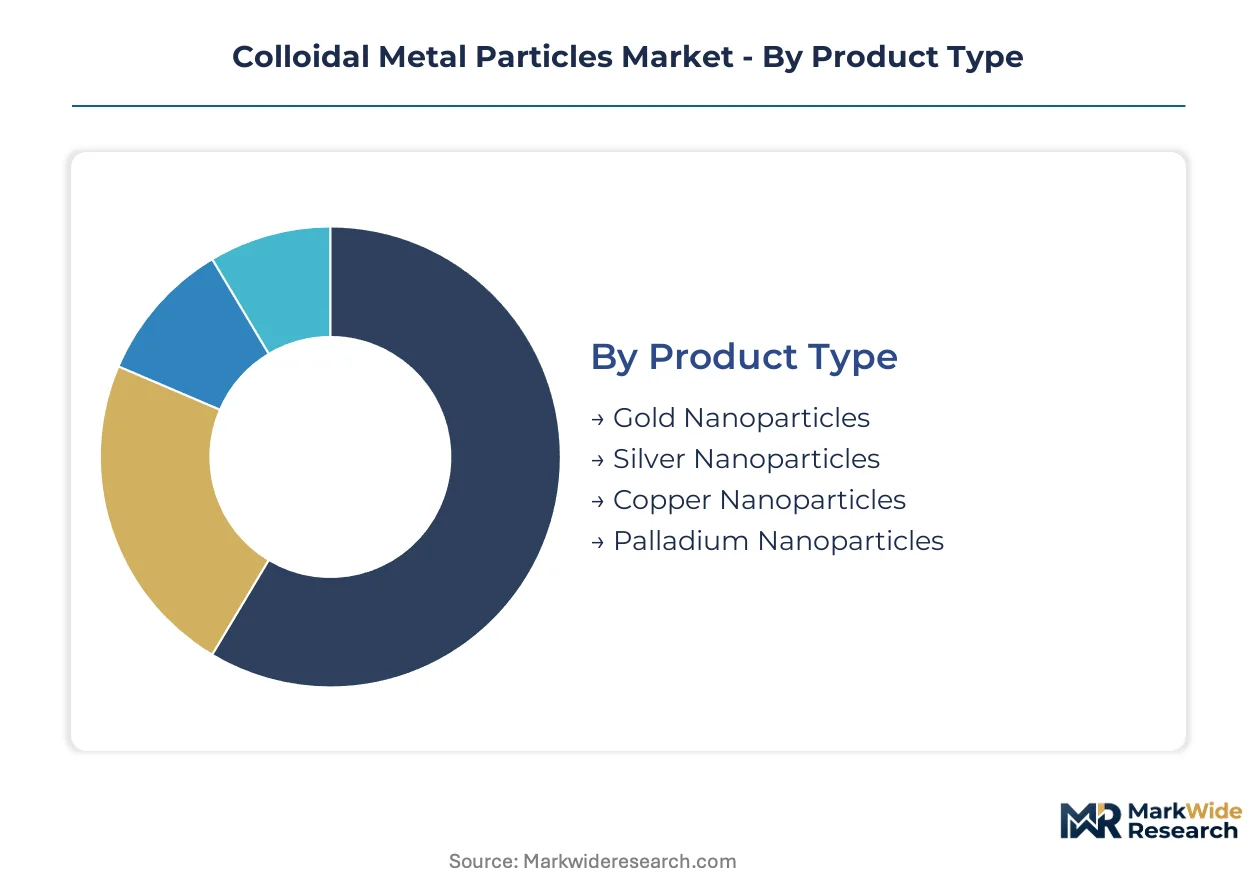
Segmentation in colloidal metal particles separates premium pharmaceutical-grade streams from commodity industrial supply, with purity thresholds and surface chemistry specifications determining qualification pathways for buyers.
Product Type:
After-sales service intensity varies sharply across metal chemistries, with gold nanoparticle buyers demanding lot-specific certificates of analysis and dedicated technical support for bioconjugation troubleshooting.
- Gold Nanoparticles:Spherical and anisotropic morphologies dominate diagnostic imaging and photothermal therapy applications. Demand concentrates in German clinical laboratories integrating plasmonic biosensing platforms, driven by REACH-mandated purity documentation for pharmaceutical use. Surface plasmon resonance tunability commands premium positioning in therapeutic delivery systems.
- Silver Nanoparticles:Antimicrobial efficacy against gram-positive and gram-negative bacteria shapes formulation specifications. Procurement clusters in US coating manufacturers facing EPA TSCA nanomaterial reporting obligations, constrained by London Bullion Market Association spot price volatility compressing margins.
- Copper Nanoparticles:Cost-effective conductivity solutions for printed electronics and heat transfer fluids.
- Palladium Nanoparticles:Specialized hydrogenation catalysis for pharmaceutical intermediates with batch consistency requirements.
By volume, silver nanoparticles lead. By growth pace, gold nanoparticles are expanding most quickly.
Application:
Application segmentation tracks margin stratification, with biomedical formulations capturing value pools far exceeding commodity electronics or environmental uses.
- Biomedical Applications:Diagnostic imaging, drug delivery vectors, and photothermal therapy platforms require sterile manufacturing environments and endotoxin testing. German and Swiss clinical laboratories are accelerating assay integration, propelled by CDSCO and FDA parallel pathway submissions for companion diagnostics.
- Electronics:Conductive inks, transparent electrodes, and thermal interface materials demand tight size distribution control. South Korean display manufacturers and Massachusetts-based printed circuit board fabricators are qualifying new suppliers, pressured by ISO/TS 19337 certification requirements for batch consistency.
- Catalysis:Selective hydrogenation and carbon-carbon coupling reactions in pharmaceutical synthesis.
- Environmental Remediation:Groundwater treatment and air filtration systems utilizing reactive metal surfaces.
Biomedical applications command the steepest expansion trajectory, while electronics maintains the largest installed base.
Technology:
Technology choice determines surface ligand profiles and regulatory qualification complexity, with laser ablation gaining share in conjugation-sensitive segments.
- Chemical Reduction:Citrate, borohydride, and ascorbic acid reduction protocols dominate industrial-scale production. Ludwigshafen and Leverkusen chemical clusters sustain capacity leadership, though ECHA surfactant authorization requirements are forcing reformulation of legacy stabilizer systems.
- Laser Ablation:Femtosecond and nanosecond pulsed laser systems generate ligand-free surfaces without chemical residues. Massachusetts and Bavaria contract manufacturing organizations are installing production capacity, responding to FDA guidance on nanomaterial drug impurities that previously blocked approval pathways.
- Solvated Metal Deposition:Vacuum-based physical vapor condensation for ultra-high purity requirements.
- Electrochemical Synthesis:Controlled potential reduction enabling precise size tuning for research-scale batches.
Chemical reduction retains volume leadership. Laser ablation is gaining share fastest in premium segments.
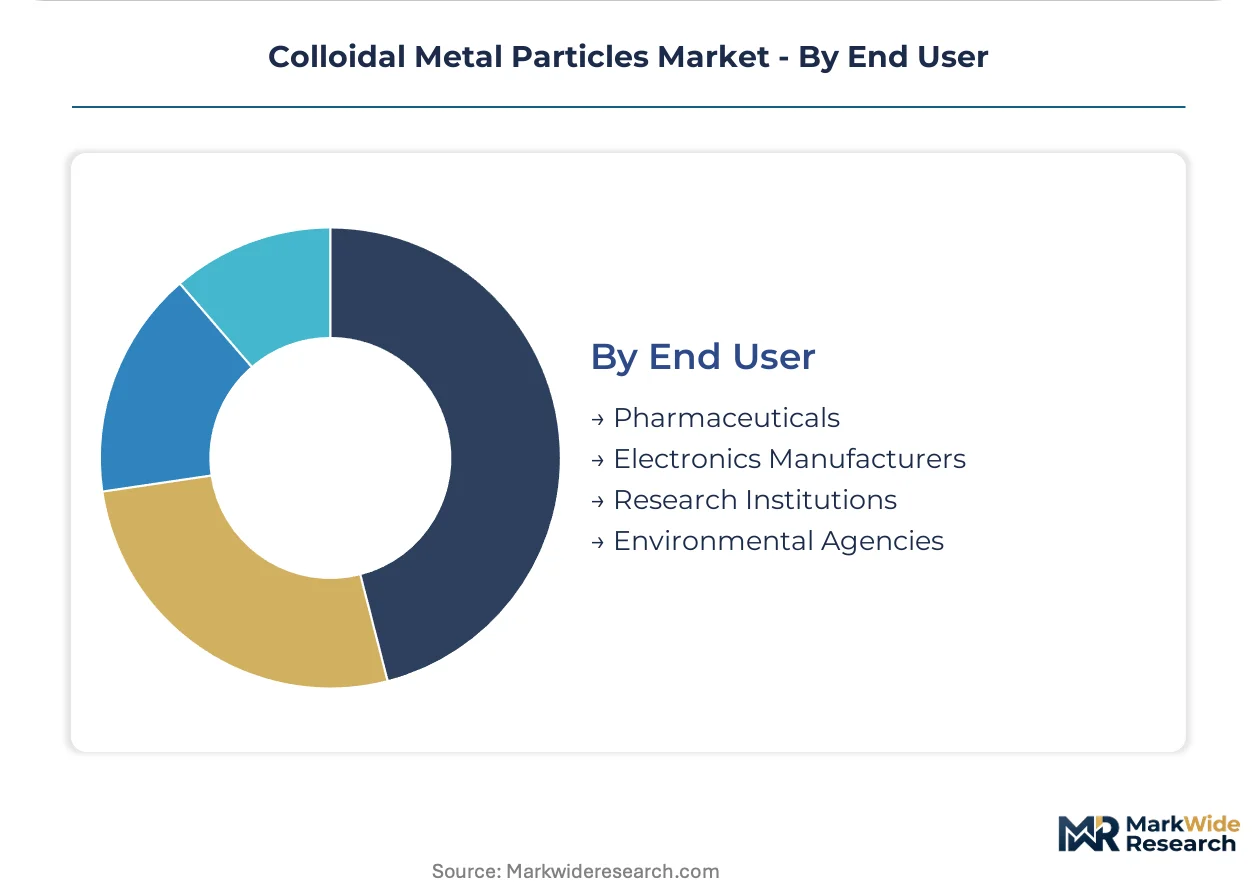
End User:
End user segmentation reveals procurement concentration patterns, with pharmaceutical buyers consolidating supplier relationships and research institutions fragmenting across specialized distributors.
- Pharmaceuticals:Formulation scientists and regulatory affairs teams require extensive documentation packages for IND and NDA submissions. Merck Group and Johnson Matthey are capturing framework agreements, leveraging integrated quality systems that satisfy both FDA and EMA module requirements simultaneously.
- Electronics Manufacturers:Process engineers prioritize conductivity stability and shelf-life consistency. South Korean and Taiwanese display panel producers are qualifying second-source suppliers, hedging against South African precursor supply disruptions affecting chloroauric acid availability.
- Research Institutions:Academic core facilities and national laboratories purchasing analytical standards and calibration materials.
- Environmental Agencies:Remediation contractors and municipal water treatment operators deploying reactive metal systems.
Pharmaceuticals drives the highest per-kilogram pricing. Research institutions represent the most fragmented procurement landscape.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's chemical handling infrastructure anchors European colloidal metal distribution, while the Rhine River corridor feeds Ludwigshafen's integrated production sites with chloroauric acid precursors from South African refining corridors.
Germany
Clinical laboratories in Munich and Heidelberg are integrating plasmonic biosensing platforms for companion diagnostic assays. REACH Article 57 authorization requirements for surfactant stabilizers are forcing reformulation of legacy colloidal silver products. The Ludwigshafen-Leverkusen chemical cluster sustains pharmaceutical-grade gold nanoparticle production through BASF SE's captive precursor supply chains.
United States
Massachusetts-based contract manufacturing organizations are installing femtosecond laser ablation systems for ligand-free colloid production. EPA nanomaterial reporting rules under the Toxic Substances Control Act are compressing qualification timelines for federally funded research institutions. Greater Boston's diagnostic developers are capturing preferential supply relationships with early-compliant domestic manufacturers.
India
CDSCO's emerging nanomaterial pathway for pharmaceutical-grade colloids is accelerating local analytical partnership formation. The regulator's framework creates first-mover positioning for suppliers establishing Bangalore and Hyderabad-based quality infrastructure. Maharashtra's pharmaceutical formulation corridors are absorbing requalification costs for imported research-grade standards.
Switzerland
Swissmedic's parallel pathway submissions for companion diagnostics are driving gold nanoparticle demand in Basel's clinical laboratory networks. The country's precision medicine clusters are qualifying laser-ablated material for intracellular imaging applications. Zurich's analytical standards distributors are consolidating procurement through framework agreements with Max Planck Society systems.
South Korea
Display manufacturers in Gyeonggi Province are qualifying second-source suppliers for conductive ink applications. MFDS alignment with ISO/TS 19337 certification requirements is tightening batch consistency standards for electronics-grade material. The Busan-Ulsan industrial corridor is hedging against South African precursor supply disruptions affecting chloroauric acid availability.
Colloidal Metal Particles Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream in precursor and analytical standards supply. The market structure concentrates around integrated chemical conglomerates controlling feedstock refining, mid-scale specialists serving diagnostic developers, and research-grade distributors capturing academic procurement consolidation. Three archetypes dominate: captive producers with backward integration into noble metal refining, contract manufacturing organizations with laser ablation capabilities, and analytical standards houses with global distribution networks. Competitive moves center on REACH dossier harmonization investments and femtosecond system capacity installation.
Among German-integrated producers, BASF SE anchors the captive production archetype through its Ludwigshafen site control over pharmaceutical-grade gold nanoparticle supply chains. Sigma-Aldrich, operating within Merck Group's global distribution network, exemplifies the analytical standards consolidation pattern serving research institutions. Johnson Matthey Plc occupies a position in catalytic applications, representing specialized palladium colloid portfolios for hydrogenation process requirements.
| Leading Market Players |
|---|
| BASF SE |
| Sigma-Aldrich (Merck Group) |
| nanoComposix |
| Strem Chemicals |
| SkySpring Nanomaterials |
| American Elements |
| Johnson Matthey Plc |
| Meliorum Technologies |
| BBI Solutions |
| Others |
Supply Flow & Price Mechanics
London Bullion Market Association silver price volatility determines both the spread between pharmaceutical-grade and industrial-grade pricing tiers and the geographic distribution of manufacturing capacity. Buyers facing spot price spikes absorb margin compression or reformulate toward copper alternatives, while suppliers cluster production near South African precursor refining corridors to hedge chloroauric acid supply disruptions.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and industrial-grade levels separates lot-certified diagnostic materials from commodity antimicrobial coatings. Certification tier and volume scale drive price differentiation, with ISO/TS 19337-compliant batches commanding substantial premia over uncertified research material. Pricing pressure stems from silver spot volatility compressing antimicrobial coating margins, forcing pass-through negotiations with coating manufacturers. Research institutions exhibit highest price sensitivity due to fragmented procurement and budget constraints, while pharmaceutical formulation teams prioritize qualification reliability over unit cost.
Supply Chain Analysis
Extended payment terms from South Korean display manufacturers and supply-chain finance facilities from German chemical distributors are tightening working capital requirements for mid-scale producers. Feedstock concentration in South Africa, Germany, and the United States draws from chloroauric acid, palladium chloride, and silver nitrate precursor streams. Single-source vulnerability in South African platinum group metal refining exposes buyers to logistics disruptions from port congestion. Distribution runs through specialized chemical distributors serving diagnostic developers and direct-to-laboratory e-commerce platforms displacing traditional channel markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical support and lot-specific certificate of analysis bundling are expanding faster than base material sales as diagnostic developers demand regulatory documentation packages. Service-attach revenue from bioconjugation troubleshooting and IND-supporting dossier preparation is reshaping supplier economics.
For Market Incumbents: Entrench framework agreements with German and Swiss clinical laboratory networks by embedding regulatory affairs teams within customer organizations. Deepen backward integration into chloroauric acid precursor refining to neutralize South African supply concentration risk. Laser ablation capacity expansion in Massachusetts and Bavaria defends premium positioning against citrate-reduced commodity alternatives. For New Entrants and Emerging Players: Build out CDSCO-compliant analytical partnerships in Bangalore and Hyderabad to capture first-mover positioning under India's emerging nanomaterial pathway. Photothermal therapy convergence in oncology applications represents the most penetrable white-space segment. Direct-to-laboratory e-commerce platforms serving academic core facilities offer a channel bypass of established distributor relationships. For Investors and Strategic Acquirers: The market sits at a regulatory consolidation phase that favors contract manufacturing organizations with femtosecond laser ablation capabilities and parallel FDA-EMA quality systems. Long-term viability over the next decade hinges on dossier harmonization investments rather than commodity scale. Watch for REACH Article 57 surfactant authorization decisions as inflection indicators for reformulation cost absorption capacity.| Strategic Initiative | Industry Significance |
|---|---|
| Femtosecond Laser Ablation Capacity Installation | Enables ligand-free surface production for FDA-compliant intracellular imaging applications. |
| REACH Dossier Harmonization Investment | Reduces regulatory affairs overhead for suppliers serving both EMA and FDA submission pathways. |
| Backward Integration into Precursor Refining | Captive chloroauric acid supply from South African platinum group metal corridors secures batch consistency. |
| Direct-to-Laboratory Distribution Platform | Bypasses traditional chemical distributor markups through specialized e-commerce serving academic core facilities. |
| CDSCO Analytical Partnership Formation | Establishes local quality infrastructure for first-mover positioning under India's emerging nanomaterial framework. |
Methodological Framework
Initial hypotheses were tested against primary input from diagnostic assay developers, pharmaceutical formulation scientists, regulatory affairs directors, and chemical procurement managers at academic core facilities and refined through secondary validation. FDA guidance documents, EMA reflection papers, REACH registration dossiers, and ISO/TS 19337 certification records provided regulatory benchmarking. Customs trade data, SEC filings from integrated chemical conglomerates, and specialized nanomaterial distributor transaction records supplied volume and pricing context. Bottom-up demand modeling from end-use applications was triangulated against top-down supply capacity assessments.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by metal chemistry, grade tier, synthesis technology, and end-use industry. Pharmaceutical-grade, electronics-grade, and industrial-grade purity thresholds shaped pricing tier assumptions. CAGRs were derived from rolling adoption curves for plasmonic biosensing platforms and laser ablation manufacturing transitions. Forecast inputs included clinical laboratory integration timelines for companion diagnostics and CDSCO regulatory pathway maturation.
The forecast holds incumbent behavior within observed patterns; aggressive moves by contract manufacturing organizations with femtosecond capacity or integrated chemical conglomerates with captive precursor supply would shift outcomes. Macroeconomic deviation in precious metal prices, threshold adjustments to nanomaterial definitions in regulatory frameworks, or breakthroughs in electrochemical synthesis scale-up would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Bismuth Oxide Market
Metals
United States Metal Casting Market
Metals
Cobalt Market
Metals
Global Ultra Fine Copper Powder Market
Metals
Copper Clad Aluminum Wire Market
Metals
Weathering Steel Market
Metals
Beryllium Copper Billet Market
Metals
Motor Lamination Material Market
Metals
Saudi Arabia Aluminum Market
Metals
Global Copper Market
Metals
Precious Metals Wire Market
Metals
Steel Wire Market
Metals
Aluminum Flat Products Market
Metals
Silver Cyanide Market
Metals
High Purity Base Metals Market
Metals
Beryllium Copper for Industrial Equipment Market