
 Iron Ore Market | 2026-2036
Iron Ore Market Size, Share, and Industry Trends Forecast 2026-2036
Iron Ore Market Analytics
EU Carbon Border Adjustment Mechanism is pivoting the cost-of-entry calculus for iron ore exporters serving European steel mills. BHP Group leverages integrated rail-port infrastructure across Western Australia to sustain cost advantages in seaborne trade. Rio Tinto anchors its position through autonomous haulage systems that compress operating expenditures across the Pilbara. Vale competes via deep-water port access in Brazil, though it navigates tailings dam compliance costs that differentiate its risk profile from Australian peers.
Iron ore denotes rocks and minerals from which metallic iron is extracted economically, typically containing iron oxides such as hematite with Fe₂O₃ or magnetite with Fe₃O₄, then processed through crushing, grinding, magnetic separation, and pelletizing to achieve blast furnace feed specifications between 62% and 65% iron content. Pellets command structural preference in direct reduction and electric arc furnace routes where emissions regulations tighten, while fines dominate volume flows into traditional blast furnace operations across Asia. High-grade concentrates attract widening margin pools as steelmakers chase lower coke rates and slag volumes to meet decarbonization targets.
Environmental regulators including Australia's Department of Climate Change, Energy, the Environment and Water, Brazil's environmental licensing framework under IBAMA, and China's Ministry of Ecology and Environment shape extraction permits, tailings standards, and import quality thresholds that filter market access. The EU ETS linkage through CBAM certificates now imposes embedded carbon accounting on ore destined for European steel integration. Stakeholders must monitor how carbon intensity disclosure requirements reconfigure contract terms between miners and mill operators before regulatory phase-ins harden into binding procurement filters.
Market Dynamics
Blast furnace operators in China's coastal steel clusters are retrofitting capacity to accommodate higher-grade pellet feed, forcing miners to recalibrate product slates and logistics configurations toward premium concentrate streams.
Growth Catalysts
- Direct reduction compatibility:Electric arc furnace operators in the Middle East and Europe are expanding pellet contracts to meet Scope 3 emissions accounting under the EU Carbon Border Adjustment Mechanism.
- India's infrastructure buildout:The country's PLI scheme for specialty steel is pulling additional seaborne fines into Odisha and Jharkhand mill complexes.
- Autonomous haulage diffusion:Rio Tinto's driverless truck fleets in Western Australia are compressing unit costs and resetting benchmark productivity expectations for Pilbara exporters.
Market Restraints
- Geographic supply concentration:Australian producers control roughly three-fifths of seaborne trade, creating systemic vulnerability to cyclone disruptions in the Pilbara.
- Coking coal price volatility:Blast furnace economics remain tethered to metallurgical coal markets, amplifying margin compression when carbon fuel costs spike.
- Grade degradation:Chinese domestic mine output averages sub-30% iron content, forcing mills to absorb higher processing energy per ton of hot metal.
Strategic Opportunities
- Green hydrogen integration:Swedish steelmakers are piloting HYBRIT-style direct reduction with Brazilian pellet suppliers, creating premium pricing tiers for low-carbon ore certification.
- West African greenfield development:Guinea's Simandou deposits offer untapped high-grade hematite reserves for exporters seeking diversification beyond Australian and Brazilian basins.
- Carbon border arbitrage:Miners with verified low-emission extraction credentials can capture contract premiums from European mills facing CBAM compliance deadlines.
Industry Challenges
- Tailings engineering expertise:Vale's Brumadinho legacy has tightened IBAMA licensing timelines, forcing Brazilian operators to recruit geotechnical specialists at inflated compensation rates.
- Legacy system integration:Autonomous haulage deployment requires retrofitting decades-old pit infrastructure with fiber-optic networks and edge computing nodes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iron Ore Market |
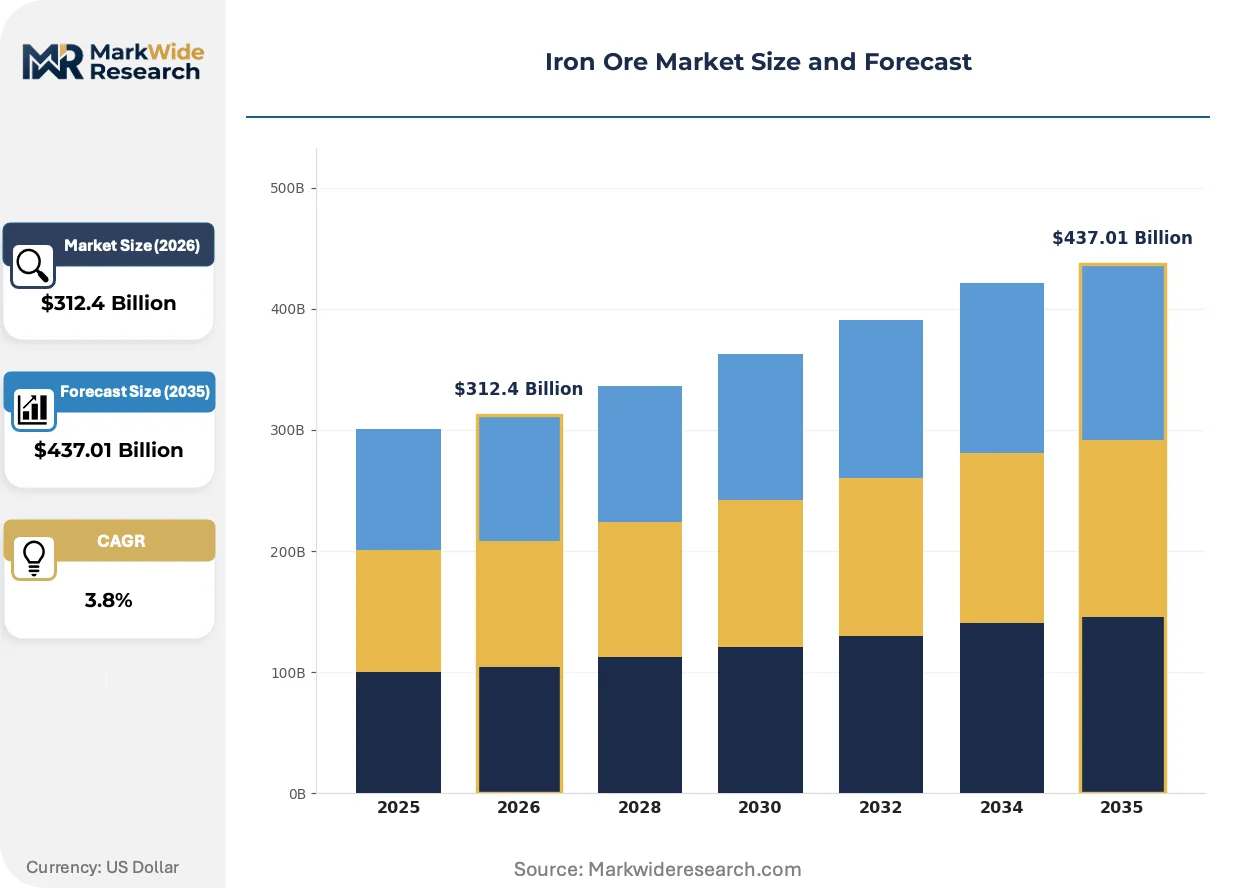
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $437.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Fines, Lump, Concentrates End User: Steel Producers, Foundries, Metal Fabricators, Power Plants Distribution Channel: Direct Sales, Distributors, Traders, Online Platforms Grade: High-Grade, Medium-Grade, Low-Grade, Others |
| Companies Covered | Fortescue Metals Group, Cleveland-Cliffs Inc., BHP Group, Glencore, Zijin Mining, Rio Tinto, ArcelorMittal Mining, Anglo American, Vale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iron Ore Market Evolving Landscape
Decarbonization mandates are fragmenting the historical uniformity of blast furnace feed specifications, creating parallel product hierarchies for carbon-intensive versus green steel routes.
Direct reduction-grade pellets with elevated iron content and controlled silica levels is overtaking traditional sinter feed in contract negotiations with European and Gulf steelmakers. EAF operators in Saudi Arabia's Ras Al-Khair complex are accelerating pellet procurement timelines to align with renewable hydrogen offtake agreements. This specification divergence is compressing margins for miners without beneficiation capacity to upgrade fines into pelletizable concentrates.
REACH compliance extensions under the EU Green Deal are imposing embedded carbon disclosure requirements on ore shipments entering Rotterdam and Hamburg terminals. Miners must now submit verified emissions data per ton of product to avoid CBAM certificate penalties. Australian exporters with integrated solar-powered rail networks are capturing preferential contract terms against higher-carbon Brazilian alternatives.
Steelmakers are consolidating procurement desks into centralized hubs in Singapore and Dubai, displacing bilateral negotiations with individual mine marketers. Trading houses are inserting themselves as risk intermediaries for freight and quality arbitrage. This channel restructuring concentrates volume leverage among the largest coastal mill clusters in China's Bohai Rim and India's eastern seaboard.
Iron Ore Market Segmentation
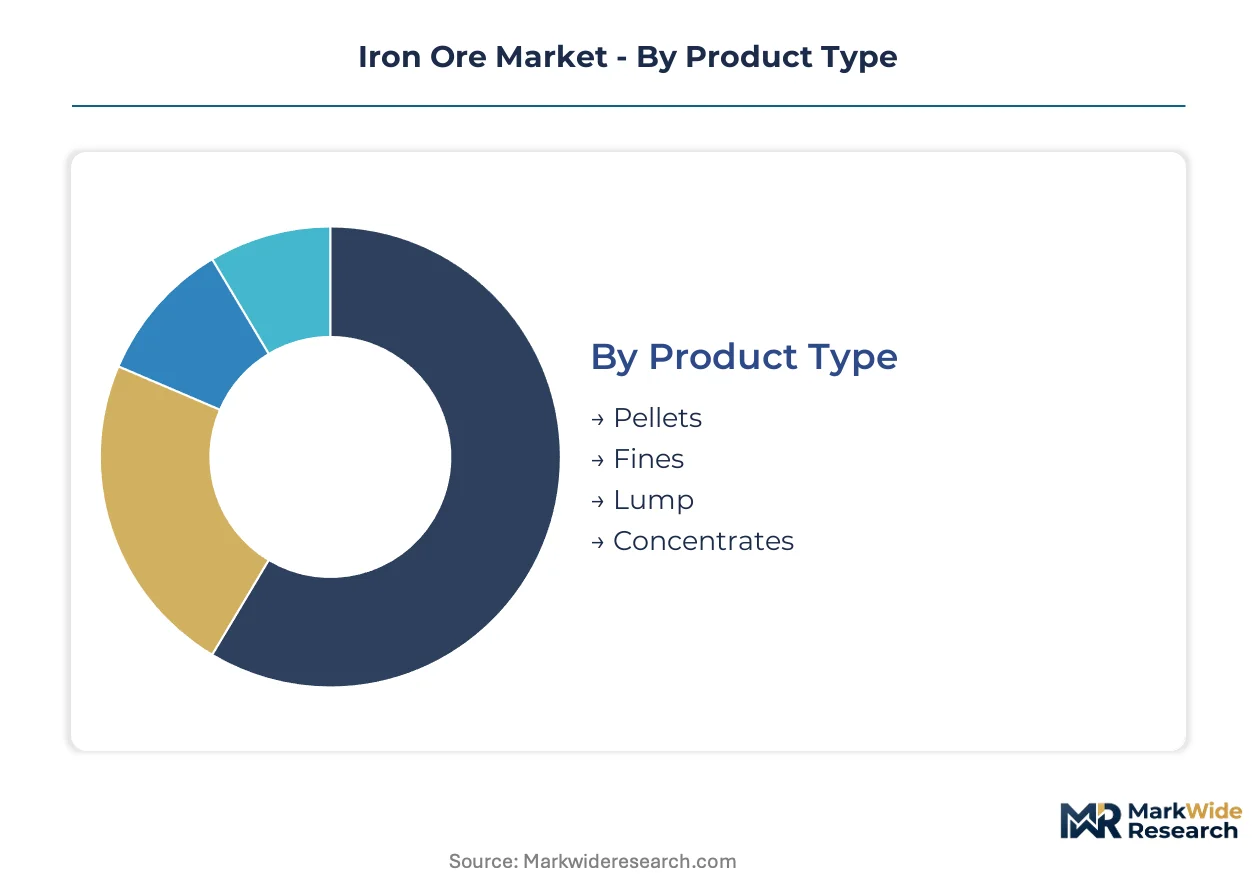
Iron ore segmentation tracks diverging metallurgical requirements across decarbonizing steel routes. Product specifications now split between blast furnace feed and direct reduction compatibility, while grade differentiation determines carbon intensity accounting under border adjustment regimes.
Product Type:
Pellet chemistry and sizing standards anchor the technology axis for low-emission steelmaking transitions.
- Pellets:Spherical agglomerates with 65-67% iron content and sub-2% silica, engineered for direct reduction and electric arc furnace feed. European steelmakers at Rotterdam terminals prioritize pellet contracts to satisfy EU Carbon Border Adjustment Mechanism certificate requirements. Demand concentrates with Saudi Arabia's Ras Al-Khair complex and Swedish HYBRIT pilot facilities.
- Fines:Granular material below 10mm requiring sintering before blast furnace injection, dominating volume flows into China's Tangshan and Rizhao mill clusters. Mills retrofitting for higher-grade feed face margin compression when processing fines with elevated alumina content.
- Lump:Coarse ore chunks 6.3-31.5mm suitable for direct blast furnace charging without agglomeration, preferred by Japanese coastal mills for operational simplicity.
- Concentrates:Beneficiated products exceeding 68% iron content from magnetic separation circuits, commanding premiums from Chinese mills chasing lower coke rates.
Mature deployment sits with fines. Newer deployment is concentrated in pellets.
End User:
Customer segmentation reflects diverging technical specifications and procurement scale across metallurgical applications.
- Steel Producers:Integrated blast furnace operators and electric arc furnace specialists consuming 90%+ of seaborne trade, with procurement desks consolidating in Singapore and Dubai trading hubs.
- Foundries:Smaller-volume consumers of high-purity lump and pellet for cast iron production, sourcing through distributor networks rather than direct offtake.
- Metal Fabricators:Secondary processors purchasing scrap-complementary direct reduction feed, expanding fastest among end-use categories as EAF capacity multiplies.
- Power Plants:Niche consumers of low-grade ore for flue gas desulfurization and heavy media separation, operating on spot-market procurement cycles.
Volume concentrates with steel producers. Margin expansion concentrates with metal fabricators.
Distribution Channel:
Channel structure tracks risk intermediation needs across freight volatility and quality arbitrage.
- Direct Sales:Long-term offtake contracts between Pilbara miners and Chinese coastal mill clusters, locking in volume commitments through dedicated berth arrangements.
- Distributors:Regional stockholders supplying foundries and fabricators with smaller lot sizes, absorbing inventory risk for price-sensitive customers.
- Traders:Merchants at Singapore and Dubai hubs managing freight derivatives and grade blending, inserting margin between mine gate and mill receipt.
- Online Platforms:Emerging spot-market portals for standardized fines parcels, capturing liquidity from fragmented Chinese domestic traders.
Contract security sits with direct sales. Spot flexibility concentrates with traders.
Grade:
Grade stratification determines carbon intensity per ton of hot metal and corresponding border adjustment exposure.
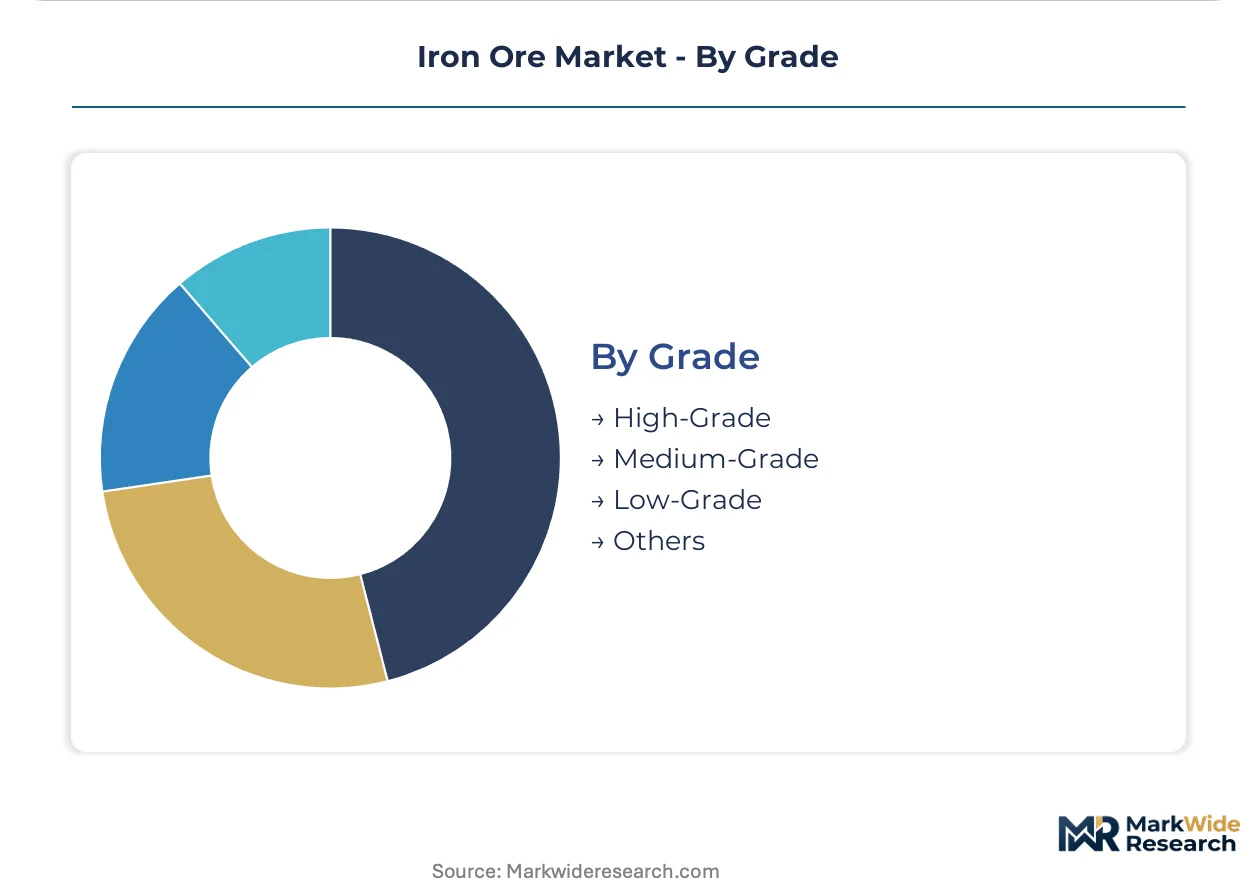
- High-Grade:Exceeding 65% iron content with minimal impurities, enabling 15-20% coke rate reductions in blast furnace operations. Australian producers with solar-powered rail networks capture preferential terms against Brazilian alternatives at Rotterdam.
- Medium-Grade:62-65% iron content representing historical benchmark pricing, facing margin compression as mills upgrade feed specifications.
- Low-Grade:Sub-62% iron content requiring extensive beneficiation, dominating Chinese domestic mine output with sub-30% iron content forcing energy-intensive processing.
- Others:Blended products and non-standard specifications serving niche direct reduction trials.
Premium capture sits with high-grade. Volume retention concentrates with medium-grade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pilbara producers in Western Australia leverage integrated rail-port corridors to dominate seaborne trade. China's coastal steel clusters around Tangshan and Rizhao absorb the bulk of import volumes. Brazil's Carajás deposits anchor South American supply despite regulatory headwinds.
China
Tangshan and Rizhao mill clusters drive import demand through blast furnace retrofits for higher-grade feed. The Ministry of Ecology and Environment enforces dual carbon goals that tighten emission intensity thresholds for coastal steelmakers. Hebei Province concentrates capacity expansion where mills upgrade pellet compatibility to reduce coke rates.
Australia
Western Australia's Pilbara region sustains export dominance through autonomous haulage systems and dedicated port berths. The Department of Climate Change, Energy, the Environment and Water administers carbon border adjustment frameworks that pivot export economics toward premium grades. Port Hedland and Dampier terminals channel volume into Asian mill contracts with embedded carbon disclosure requirements.
Brazil
Carajás high-grade hematite reserves attract European direct reduction trials seeking lower-carbon feedstock. IBAMA licensing timelines have tightened following tailings dam incidents, forcing operators to recruit geotechnical specialists at premium rates. São Luís port terminals serve Atlantic basin steelmakers pursuing HYBRIT-style hydrogen reduction partnerships.
India
Odisha and Jharkhand mill complexes absorb seaborne fines under the PLI scheme for specialty steel capacity expansion. The Bureau of Indian Standards enforces quality thresholds that filter import access for beneficiated concentrates. Paradip and Visakhapatnam ports concentrate procurement activity for eastern seaboard integrated producers.
Sweden
HYBRIT pilot facilities at Luleå and Gällivare drive premium pellet demand for fossil-free steel production. The EU Carbon Border Adjustment Mechanism imposes certificate requirements on ore shipments entering Rotterdam and Hamburg terminals. Norrbotten steel clusters anchor European green steel transition with Brazilian pellet offtake agreements.
Iron Ore Market Competitive Landscape
Australian producers anchor one tier; Brazilian specialists hold differentiated positions through deep-water port access. The market structure concentrates around three-fifths seaborne supply originating from Pilbara operations, creating systemic exposure to cyclone disruptions. Strategic archetypes include integrated majors with captive rail infrastructure, diversified miners with copper-gold cross-subsidies, and pure-play iron ore specialists. Competitive moves center on autonomous haulage deployment and carbon certification programs to capture European contract premiums.
Among Australian-integrated majors, BHP Group, Rio Tinto, and Fortescue Metals Group exemplify the infrastructure-anchored archetype through Pilbara rail-port control. Vale occupies a position representing the high-grade, Atlantic-facing alternative with Carajás deposit access. Cleveland-Cliffs Inc. sits within the North American integrated steel-mining model, supplying captive blast furnace operations.
| Leading Market Players |
|---|
| Fortescue Metals Group |
| Cleveland-Cliffs Inc. |
| BHP Group |
| Glencore |
| Zijin Mining |
| Rio Tinto |
| ArcelorMittal Mining |
| Anglo American |
| Vale |
| Others |
Value Network & Pricing Analysis
China's coastal steel mill clusters around Tangshan and Rizhao anchor procurement volume, locking in contract-based long-term offtake pricing that rewards dedicated berth arrangements and penalizes spot-market fragmentation.
Pricing Analysis
Short lead-time premiums concentrate with European direct reduction trials at Rotterdam terminals seeking HYBRIT-compatible pellet certification under EU CBAM requirements. Contract-based long-term offtake dominates seaborne trade, with price differentiation driven by carbon intensity disclosure grades and volume scale commitments. Cost compression in medium-grade fines is intensifying because Chinese mills retrofit blast furnaces for higher-grade pellet feed. Spot-market traders show greatest price sensitivity, while integrated steel producers with captive port access accept premium pricing for supply security.
Supply Chain Analysis
Single-source vulnerability sits with Australian Pilbara operations controlling roughly three-fifths of seaborne trade. Geographic supply concentrates in Australia, Brazil, and emerging West African greenfield developments. Raw material dependencies rest on diesel fuel for autonomous haulage fleets, explosives for pit blasting, and steel grinding media for beneficiation circuits. Cyclone disruption in Western Australia represents the dominant structural risk. Distribution runs through dedicated rail-port corridors into Singapore and Dubai trading hubs before final mill delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iron ore market is becoming a vertical-integration race as miners pursue captive rail-port infrastructure to defend margin position against trading house intermediation.
For Market Incumbents: Acquire autonomous haulage technology assets to compress unit operating expenditures below Pilbara productivity benchmarks. Secure carbon certification credentials through solar-powered rail networks to capture EU CBAM contract premiums before regulatory phase-ins harden. Defend against emerging West African greenfield entrants by locking Chinese coastal mills into decade-long offtake arrangements with embedded price collars. For New Entrants and Emerging Players: Premium-to-economy grade spreads in European direct reduction feed offer white-space entry for certified low-carbon pellet suppliers. Target Swedish HYBRIT pilot facilities and Saudi Ras Al-Khair EAF complexes as most penetrable demand nodes. Pursue geotechnical specialist recruitment from Brazilian operators facing IBAMA licensing delays to accelerate permitting timelines. For Investors and Strategic Acquirers: The window for entry favors pure-play iron ore specialists with unencumbered high-grade hematite reserves outside Australian cyclone exposure. Long-term viability hinges on positioning ahead of green hydrogen integration curves in European steelmaking. Watch for Simandou development milestone signals as inflection indicator for West African supply diversification.| Strategic Initiative | Industry Significance |
|---|---|
| Autonomous Haulage Deployment | Rio Tinto's driverless truck fleets reset Pilbara productivity expectations for cost leadership. |
| Carbon Certification Program | Australian solar-powered rail networks capture preferential contract terms at Rotterdam terminals. |
| Greenfield Development | Guinea's Simandou deposits offer diversification beyond Australian and Brazilian supply basins. |
| Long-term Supply Agreement | Chinese coastal mills lock volume commitments through dedicated berth arrangements. |
| Backward Integration | Steelmakers consolidate procurement desks into Singapore and Dubai trading hubs. |
Research Methodology
Multi-period observation of blast furnace retrofit timelines, pellet contract premiums, and autonomous haulage adoption rates anchored the trend analysis, supplemented by interviews with mine operations directors, port logistics managers, steel procurement leads, and carbon accounting specialists at European mills. Secondary validation drew from Australian Bureau of Statistics export data, China Customs import records, EU ETS transaction registries, and IBAMA licensing disclosure databases. Bottom-up volume modeling triangulated against top-down steel production forecasts.
Segment-weighting applied product type splits between fines, pellets, lump, and concentrates, crossed with end-use segmentation across blast furnace operators, electric arc furnace specialists, and direct reduction trials. Grade stratification and distribution channel structures provided additional analytical dimensions across the projection horizon. CAGRs derived from elasticity-adjusted demand functions incorporating coke rate reduction targets and carbon border adjustment exposure curves.
Inputs from primary field interviews and disclosed regulatory filings were available through the study window; gaps in real-time carbon intensity verification at Brazilian operations introduce uncertainty bands around premium pricing capture assumptions. Forecasts reflect documented assumptions regarding Chinese blast furnace retrofit schedules and EU CBAM phase-in stringency. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Iron Casting Market
Metals
Copper and Copper Alloy Foil Market
Metals
Ferro Aluminum Market
Metals
Silver Enamel Market
Metals
Europe Welding Consumables Market
Metals
Europe Aluminium Powder Market
Metals
Beryllium Market
Metals
Middle-East and Africa Metal Finishing Market
Metals
Nickel Oxide Target Market
Metals
India Steel Market
Metals
North America Aluminum Market
Metals
Lithium Tungstate Market
Metals
Chrome Metal Powder Market
Metals
GCC Metal Forging Market
Metals
Ferrosilicon Market
Metals
Global Aluminium Wire Rod Market