
 Global Ultra Fine Copper Powder Market | 2026-2036
Global Ultra Fine Copper Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Global Ultra Fine Copper Powder Market Foresight
Defense and aerospace procurement is collapsing toward additive manufacturing feedstock specifications, displacing legacy metallurgy orders. Sumitomo Metal Mining Co., Ltd. anchors Japanese supply through captive electrolytic refining capacity. JX Nippon Mining & Metals Corporation dominates high-purity atomized grades for semiconductor thermal interface materials. GGP Metalpowder navigates European regulatory complexity through dedicated carbonyl powder purification lines.
Ultra fine copper powder comprises metallic copper particles engineered below twenty microns, typically produced through atomization, electrolysis, or carbonyl decomposition to achieve controlled morphology and oxygen content below two thousand parts per million for conductivity-critical applications. Electrolytic grades occupy the margin pool in electronics due to dendritic structure advantages in conductive inks, while atomized powder leads volume through additive manufacturing qualification. Submicron segments compete fastest in thermal management as chip packaging power densities escalate.
REACH restrictions on heavy metal impurities and RoHS substance thresholds shape European formulation requirements, while China's GB standards and NMPA oversight govern medical electronics-grade powder certification. Japan's METI promotes domestic critical minerals processing through JIS standards alignment. Stakeholders must monitor evolving purity benchmarks across FDA, EMA, and China's SAMR to secure multi-regional qualification.
Market Dynamics
Additive manufacturing qualification protocols in aerospace and defense are compressing legacy powder metallurgy procurement cycles. Submicron-grade specifications for thermal interface materials in semiconductor packaging are simultaneously pulling electrolytic refining capacity away from traditional conductive ink applications.
Growth Catalysts
- REACH and RoHS compliance thresholds:European electronics manufacturers are reformulating conductive inks to meet ECHA purity mandates. This is redirecting demand toward electrolytic grades with oxygen content below 500 ppm.
- Chip packaging power density escalation:Advanced thermal management architectures in high-performance computing are specifying sub-5-micron copper powders. Japanese semiconductor fabricators are qualifying atomized grades for direct bonding applications.
- Aerospace feedstock specifications:Defense procurement offices are mandating additive manufacturing feedstock traceability. This is displacing conventional wrought copper bar stock in structural component supply chains.
Market Restraints
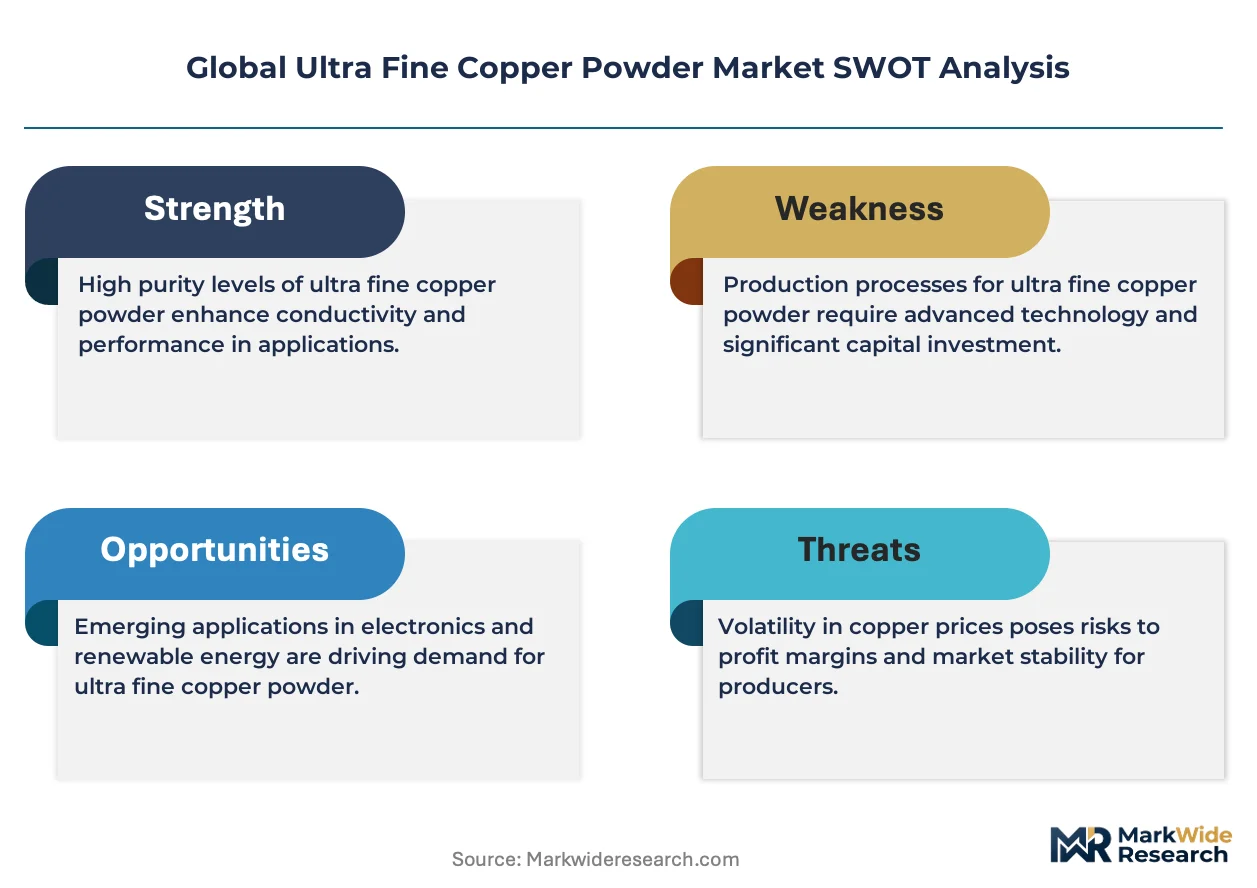
- Electrolytic refining concentration:Captive smelter capacity in Japan and China controls over 60% of battery-grade electrolytic output. This geographic concentration exposes downstream formulators to supply rationing during smelter maintenance cycles.
- Silver flake substitution in conductive inks:Nanosilver formulations are capturing flexible electronics applications where sintering temperature flexibility outweighs copper's cost advantage. Printed antenna and RFID tag manufacturers are pivoting procurement toward silver pastes.
- Carbonyl process energy intensity:European carbonyl copper production faces natural gas price volatility. BASF Ludwigshafen and GGP Metalpowder facilities incur input cost premiums versus Asian electrolytic routes.
Strategic Opportunities
- Indian electronics manufacturing clusters:PLI scheme incentives for semiconductor packaging are attracting thermal interface material formulators. Domestic powder atomization capacity remains underdeveloped relative to projected demand.
- Solid-state battery current collector applications:Sub-10-micron copper powders are enabling thin-film deposition for next-generation lithium-metal architectures. Korean battery manufacturers are screening atomized grades for dry electrode compatibility.
- Medical electronics-grade certification:FDA and EMA biocompatibility pathways for implantable device components remain sparsely contested. Powder suppliers with ISO 13485 alignment can capture premium positioning in neurostimulation and pacemaker markets.
Industry Challenges
- Submicron classification workforce scarcity:Sedigraph and laser diffraction operators with semiconductor-grade powder characterization experience command wage premiums. Training pipelines at German and Japanese technical institutes lag sector expansion.
- Multi-regional qualification timeline compression:Simultaneous FDA, EMA, and NMPA filings for medical electronics grades extend certification cycles. Documentation harmonization across jurisdictions remains incomplete.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Ultra Fine Copper Powder Market |
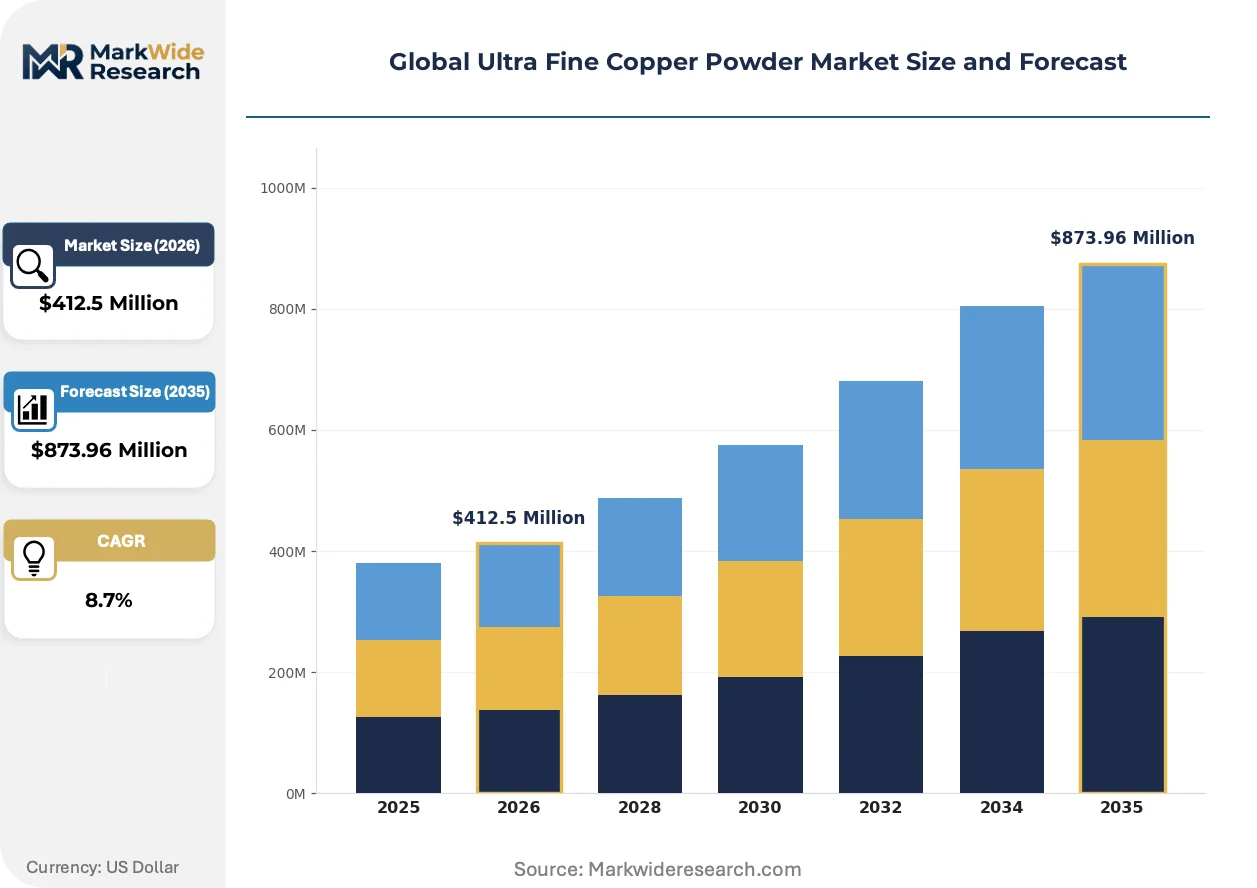
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $873.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Atomized, Electrolytic, Regenerated, Flake, Carbonyl Particle Size: Submicron, 1-5 Microns, 5-10 Microns, 10-20 Microns, Above 20 Microns Application: Conductive Inks, Electronics, Thermal Management, Coatings, Additive Manufacturing End User Industry: Electrical Equipment, Aerospace, Consumer Electronics, Metallurgy, Renewable Energy |
| Companies Covered | GGP Metalpowder, Fukuda Metal Foil & Powder, Sumitomo Metal Mining Co., Ltd., Suzhou Canfuo Nanotechnology, GRIPM Advanced Materials, Mitsui Mining & Smelting Co., Ltd., Kymera International, Shanghai CNPC Powder Material, JX Nippon Mining & Metals Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Ultra Fine Copper Powder Market Shifts & Advancements
Plasma atomization and ultrasonic dispersion technologies are redefining morphology control thresholds. Regulatory convergence on heavy metal impurity limits is forcing purification process reinvestment. Procurement centralization among semiconductor packaging houses is compressing supplier qualification windows.
Gas-phase plasma atomization is decomposing traditional water atomization's dominance in spherical powder production. Aerospace OEMs are specifying plasma-atomized feedstock for laser powder bed fusion qualification. This is decomposing the historical cost advantage of water-atomized grades in non-critical applications.
China's GB standards for electronic materials are tightening heavy metal impurity thresholds below REACH baseline requirements. Domestic formulators serving export markets must maintain dual certification protocols. Medical electronics-grade powder suppliers are absorbing incremental testing costs to maintain multi-regional qualification.
Direct procurement relationships between semiconductor packaging houses and powder producers are displacing distributor intermediaries. Samsung and TSMC procurement teams are negotiating long-term offtake agreements with Japanese electrolytic refiners. This channel consolidation is most visible in South Korea's Pyeongtaek and Hwaseong manufacturing corridors.
Global Ultra Fine Copper Powder Market Segmentation
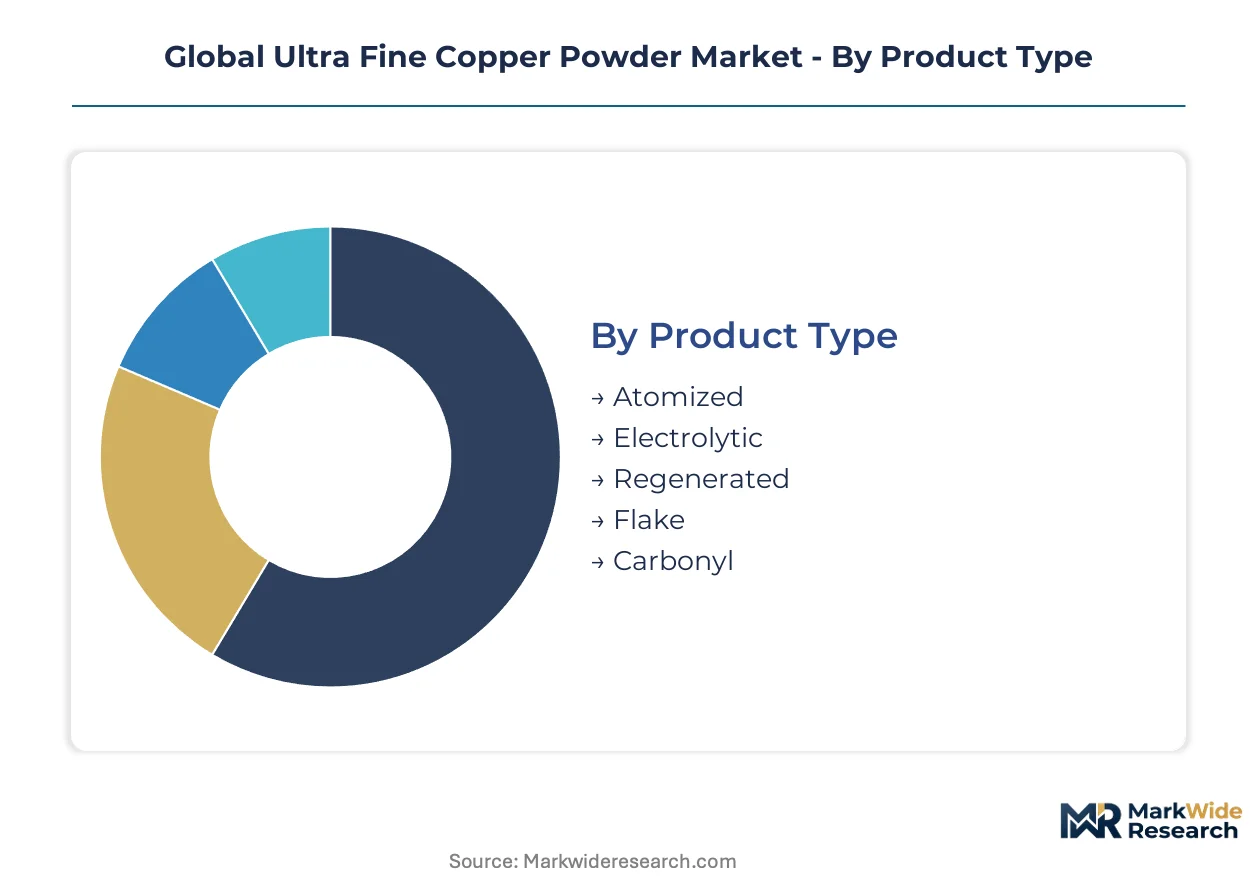
Ultra fine copper powder segmentation reveals divergent margin pools across production methods and particle size tiers. Powder morphology and oxygen content specifications determine qualification pathways for high-value electronics versus commodity metallurgy applications.
Product Type:
Electrolytic and atomized grades command premium positioning through distinct purity and morphology advantages.
- Atomized:Spherical particle morphology achieved through water or gas atomization delivers superior flowability for laser powder bed fusion. Aerospace OEMs in Germany and the United States are mandating plasma-atomized feedstock for structural component qualification, compressing water-atomized share in non-critical segments.
- Electrolytic:Dendritic particle structure with oxygen content below 500 ppm enables high-conductivity conductive ink formulations. Japanese and South Korean electronics manufacturers prioritize electrolytic grades for flexible circuit printing, though smelter capacity concentration in East Asia creates supply vulnerability.
- Regenerated:Recovered powder from machining waste streams serves cost-sensitive metallurgy applications in India and Southeast Asia.
- Flake:Lamellar morphology produced through mechanical milling targets EMI shielding coatings for consumer electronics housings.
- Carbonyl:Ultra-high purity through iron pentacarbonyl decomposition commands medical electronics and specialty catalyst applications; European producers face natural gas cost premiums versus Asian electrolytic routes.
Electrolytic holds installed capacity. Atomized is rotating up the share rankings.
Particle Size:
Submicron specifications concentrate value capture as semiconductor packaging power densities escalate.
- Submicron:Particles below one micron enable thin-film thermal interface materials for advanced chip packaging. TSMC and Samsung procurement teams are qualifying sub-5-micron atomized grades for direct bonding applications in Pyeongtaek and Tainan manufacturing corridors.
- 1-5 Microns:Intermediate sizing balances sintering activity with handling characteristics for conductive paste formulations. Chinese conductive ink formulators are expanding 1-5 micron electrolytic procurement to meet export-grade REACH compliance.
- 5-10 Microns:Standard powder metallurgy feedstock for electrical contacts and brushes; volume leader through mature automotive and industrial demand.
- 10-20 Microns:Coarse fraction serves traditional friction materials and brake pad applications with lower purity tolerance.
- Above 20 Microns:Near-boundary sizing competes with standard copper powder grades in commodity metallurgy; minimal ultra fine premium capture.
5-10 Microns dominates volume throughput. Submicron is expanding most quickly.
Application:
Thermal management and additive manufacturing applications are displacing legacy conductive ink procurement priorities.
- Conductive Inks:Screen and inkjet printable formulations for flexible electronics and RFID antennas. Nanosilver substitution is eroding copper's cost advantage in flexible antenna applications where sintering temperature flexibility outweighs material economics.
- Electronics:Passive component terminations, multilayer ceramic capacitor electrodes, and printed circuit board metallization. Japanese passive component manufacturers specify electrolytic grades with JIS-standard impurity profiles.
- Thermal Management:Thermal interface materials, heat spreaders, and phase change materials for high-performance computing. Submicron copper loading in polymer matrices enables thermal conductivity above 10 W/mK for data center GPU packaging.
- Coatings:Conductive and antimicrobial surface treatments for medical devices and consumer goods; functional rather than structural applications.
- Additive Manufacturing:Laser powder bed fusion and binder jetting feedstock for copper and copper alloy components. NASA and ESA procurement specifications for spacecraft thermal management components are accelerating plasma-atomized qualification.
Electronics maintains broadest qualification footprint. Thermal Management is gaining share fastest.
End User Industry:
Aerospace and consumer electronics procurement patterns are diverging toward specification stringency versus cost optimization.
- Electrical Equipment:Switchgear, motors, generators, and power distribution components. Indian electrical equipment manufacturers under PLI scheme incentives are expanding domestic powder metallurgy capacity.
- Aerospace:Structural heat exchangers, rocket combustion chambers, and satellite thermal control systems. Defense procurement offices in the United States and France are mandating additive manufacturing feedstock traceability to displace wrought bar stock.
- Consumer Electronics:Smartphones, tablets, wearables, and hearables requiring miniaturized conductive and thermal solutions. Chinese OEMs are consolidating supplier bases to capture scale economies in 1-5 micron electrolytic procurement.
- Metallurgy:Powder forging, metal injection molding, and traditional press-and-sinter operations; mature demand with limited growth velocity.
- Renewable Energy:Wind turbine slip rings, solar cell interconnects, and emerging solid-state battery current collector applications. Korean battery manufacturers are screening sub-10-micron atomized grades for dry electrode compatibility in next-generation lithium-metal architectures.
Electrical Equipment anchors volume demand. Aerospace is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's metals handling infrastructure underwrites European distribution of high-purity copper powders, while the China-Europe rail corridor accelerates East Asian feedstock delivery to German additive manufacturing clusters.
China
GB standards for electronic materials now mandate heavy metal impurity thresholds below REACH baselines, forcing dual certification for export-oriented formulators. The Yangtze River Delta concentration of semiconductor packaging houses in Suzhou and Wuxi is absorbing sub-10-micron atomized grades for thermal interface production. Shanghai CNPC Powder Material anchors domestic electrolytic capacity serving conductive ink manufacturers in the Pearl River Delta.
Japan
METI's critical minerals processing promotion through JIS standards alignment is reinforcing captive smelter advantages for battery-grade electrolytic output. Sumitomo Metal Mining Co., Ltd. and JX Nippon Mining & Metals Corporation control refining infrastructure in the Kanto corridor. The Nagoya-Tokyo manufacturing belt is qualifying plasma-atomized feedstock for aerospace OEM laser powder bed fusion specifications.
South Korea
Samsung and TSMC procurement teams negotiate long-term offtake agreements directly with Japanese refiners, bypassing distributor intermediaries. The Pyeongtaek and Hwaseong semiconductor corridors are screening sub-5-micron grades for direct bonding in advanced chip packaging. Korean battery manufacturers are testing atomized powders for solid-state battery current collector dry electrode compatibility.
Germany
ECHA REACH mandates and RoHS substance thresholds are redirecting conductive ink demand toward electrolytic grades below 500 ppm oxygen content. GGP Metalpowder's carbonyl purification lines in North Rhine-Westphalia navigate regulatory complexity for medical electronics certification. The Bavarian aerospace cluster is mandating additive manufacturing feedstock traceability for structural heat exchanger components.
United States
NASA and Department of Defense procurement specifications for spacecraft thermal management are accelerating plasma-atomized powder qualification. The Southeast manufacturing corridor lacks domestic submicron atomization capacity relative to semiconductor packaging demand growth. FDA biocompatibility pathways for implantable device components remain sparsely contested by powder suppliers with ISO 13485 alignment.
Global Ultra Fine Copper Powder Market Competitive Landscape
Listed leaders compete with private specialists across electrolytic refining and atomized powder production, creating a tiered structure where captive smelter capacity anchors premium positioning. The vendor base fragments across geographic concentrations in East Asia and specialized European purification operations. Three archetypes dominate: integrated mining-smelting conglomerates with captive powder output, independent atomization specialists serving aerospace qualification protocols, and carbonyl process operators targeting medical electronics purity thresholds. Capacity expansion and direct procurement relationship formation represent the dominant competitive moves.
Among Japanese integrated conglomerates, Sumitomo Metal Mining Co., Ltd. and JX Nippon Mining & Metals Corporation exemplify the captive refining archetype, while Mitsui Mining & Smelting Co., Ltd. occupies a parallel position. GGP Metalpowder represents European carbonyl specialization. Fukuda Metal Foil & Powder and Kymera International sit within the independent atomization tier serving qualification-intensive end uses.
| Leading Market Players |
|---|
| GGP Metalpowder |
| Fukuda Metal Foil & Powder |
| Sumitomo Metal Mining Co., Ltd. |
| Suzhou Canfuo Nanotechnology |
| GRIPM Advanced Materials |
| Mitsui Mining & Smelting Co., Ltd. |
| Kymera International |
| Shanghai CNPC Powder Material |
| JX Nippon Mining & Metals Corporation |
| Others |
Supply & Pricing Matrix
Plasma atomization displacing water atomization for aerospace feedstock qualification simultaneously concentrates supply geography in Japanese and German manufacturing corridors and compresses pricing premiums for spherical morphology grades. Nanosilver substitution in flexible electronics conductive inks forces copper powder suppliers to absorb testing cost burdens for dual REACH and GB certification, eroding margin pools in legacy screen-printing applications.
Pricing Analysis
Three-tier pricing structure across plasma-atomized aerospace grades, electrolytic electronics grades, and regenerated metallurgy feedstock governs transaction economics. Price differentiation rests on oxygen content certification below 500 ppm for semiconductor thermal interface materials versus commodity tolerance above 2000 ppm. Cost compression in water-atomized non-critical segments intensifies as Chinese capacity expansion floods standard powder metallurgy channels. Indian electrical equipment manufacturers under PLI scheme incentives exhibit highest price sensitivity, while NASA and ESA procurement offices for spacecraft thermal management components demonstrate lowest sensitivity to lot premiums.
Supply Chain Analysis
Strategic stockpiling of submicron atomized grades dominates procurement behavior among Samsung and TSMC thermal interface material formulators, displacing just-in-time legacy practices. Supply concentrates in Japan, China, and South Korea through captive electrolytic refining infrastructure and dedicated atomization facilities. Raw material flows draw from copper cathode feedstock, iron pentacarbonyl precursor chemicals, and high-purity process gases. Single-source vulnerability permeates the sub-5-micron segment where JX Nippon Mining and Sumitomo Metal Mining control qualification pathways. Distribution runs through direct offtake agreements between semiconductor packaging houses and refiners, bypassing distributor intermediaries in Pyeongtaek and Tainan manufacturing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Powder characterization and certification services represent a service-attach opportunity expanding faster than base powder hardware sales, as semiconductor fabricators outsource Sedigraph and laser diffraction testing to qualified laboratories.
For Market Incumbents: Compound captive smelter advantages through backward integration into plasma atomization capacity for aerospace qualification protocols. Defend electrolytic grade margin pools by accelerating ISO 13485 alignment for medical electronics certification before FDA and EMA pathways become contested. Add atomization capacity in the Kanto corridor to intercept submicron demand from Korean battery manufacturers screening dry electrode compatibility. For New Entrants and Emerging Players: Differentiate on carbonyl process specialization for medical electronics purity thresholds where European natural gas cost premiums have constrained incumbent expansion. Target Indian electronics manufacturing clusters under PLI scheme incentives where domestic atomization capacity remains underdeveloped relative to projected semiconductor packaging demand. Pursue toll processing arrangements with established refiners to bypass electrolytic refining capital intensity. For Investors and Strategic Acquirers: The market sits at a qualification-window compression phase that favors independent atomization specialists with aerospace OEM relationships and existing plasma-atomized feedstock certifications. Long-term viability over the next decade hinges on positioning within submicron thermal interface material supply chains as chip packaging power densities escalate. Monitor Korean battery manufacturer dry electrode screening results as the inflection indicator for solid-state battery current collector demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Atomization Capacity Expansion | Aerospace OEMs in Germany and the United States mandate plasma-atomized feedstock for laser powder bed fusion qualification protocols. |
| ISO 13485 Certification Investment | FDA and EMA biocompatibility pathways for implantable neurostimulation and pacemaker components remain sparsely contested. |
| Long-term Supply Agreement | Samsung and TSMC procurement teams negotiate direct offtake agreements with Japanese electrolytic refiners, displacing distributor intermediaries. |
| Backward Integration into Copper Cathode Refining | Captive smelter capacity in Japan and China controls over sixty percent of battery-grade electrolytic output, anchoring supply security. |
| Joint Venture for Indian Atomization Facility | PLI scheme incentives for semiconductor packaging attract thermal interface material formulators where domestic powder atomization capacity lags demand. |
Research Methodology
The analysis maps electrolytic refining, atomization, carbonyl decomposition, and regeneration sub-sectors, each validated through powder metallurgy plant managers, semiconductor procurement leads, aerospace additive manufacturing engineers, and conductive ink formulators. Primary interviews with these stakeholders combined with secondary validation from customs and trade data, JIS and GB standards filings, SEC 10-K disclosures from integrated mining conglomerates, and ECHA REACH substance restriction updates. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across production methods.
Consistency checks against external benchmarks validated output plausibility across the projection horizon. The analytical framework models particle size tiers, application segments, end-use industries, and regional production hub clustering. CAGRs derive from segmented demand elasticity analysis and capacity expansion pipeline tracking. Forecast inputs incorporate semiconductor packaging power density roadmaps and aerospace additive manufacturing qualification timelines without specific year anchoring.
Decision-makers should treat outputs as directional under assumptions of continued REACH and RoHS compliance stringency and sustained chip packaging thermal management demand; material deviation would warrant model refresh. Specific risk factors include silver flake substitution acceleration in flexible electronics, European natural gas price volatility affecting carbonyl process economics, and smelter maintenance cycle disruptions in East Asian electrolytic capacity. Revision becomes warranted when submicron classification workforce scarcity crosses thresholds that constrain qualification throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Global Bronze Market
Metals
Aluminium Forging Market
Metals
Lithium Tungstate Market
Metals
Europe Metal Service Centers Market
Metals
Hafnium Foil Market
Metals
Clutch Spring Wires Market
Metals
Stainless Steel Round Bar Market
Metals
Weathering Steel Market
Metals
Global Stainless Steel Lashing Wire Market
Metals
Aluminium Rolled Products Market
Metals
Niobium Market
Metals
Stainless Steel Panels Market
Metals
Copper Chromium Black Market
Metals
Ore Metals Market
Metals
Bismuth Oxide Market
Metals
Global Brass Rods Market