
 Polar Polymers Market | 2026-2036
Polar Polymers Market Size, Share, and Industry Trends Forecast 2026-2036
Polar Polymers Market Analytics
Healthcare formulators is reorganizing procurement priorities as pharmaceutical-grade polar polymers displace conventional excipients in controlled-release and bioadhesive platforms. Covestro AG sustains technology leadership through specialized polycarbonate and polyurethane derivatives engineered for medical device compatibility. Evonik Industries AG dominates high-purity polyethylene glycol production, leveraging pharmaceutical certification pipelines that lock in multi-year supply agreements with European drug manufacturers. DuPont de Nemours Inc. anchors North American demand through ionomer and ethylene copolymer portfolios tailored to electronics packaging and semiconductor adhesion layers.
Polar polymers constitute macromolecular chains bearing permanent dipole moments from electronegative functional groups such as hydroxyl, amide, or ether moieties, enabling hydrogen bonding, water solubility, and surface adhesion with dielectric constants typically exceeding 3.5 at 25°C. These materials function as compatibilizers, film formers, and rheology modifiers across formulations requiring controlled hydrophilicity or ionic conductivity. Polyvinyl alcohol leads product type demand in textile sizing and paper coating where complete biodegradability commands premium positioning, while polyethylene glycol margin pools concentrate in injectable-grade pharmaceutical applications governed by USP and EP monographs. Nanocomposite technology variants represent the fastest-expanding segment as layered silicate and carbon nanotube reinforcements enhance barrier properties without sacrificing optical clarity in flexible electronics substrates.
EMA pharmaceutical quality guidelines and REACH substance registration requirements shape European material qualification timelines, while FDA's ICH Q3D elemental impurity standards force upstream purification investments for excipient-grade outputs. EPA industrial effluent limitations under the Clean Water Act constrain acrylamide monomer discharge from U.S. polyacrylamide manufacturing, redirecting capacity toward lower-toxicity copolymer chemistries. Stakeholders must monitor evolving EU Green Deal restrictions on fossil-derived feedstocks and assess biopolymer technology readiness for performance-critical automotive and aerospace adhesion applications.
Market Dynamics
Pharmaceutical-grade certification requirements are compressing supplier qualification timelines as controlled-release drug delivery systems absorb higher-purity polar polymer volumes.
Growth Catalysts
- REACH substance registration:European chemical compliance protocols are locking in multi-year supply contracts with certified manufacturers, reducing buyer switching frequency.
- Controlled-release drug delivery:Bioadhesive and sustained-release pharmaceutical platforms are absorbing pharmaceutical-grade polyethylene glycol at expanding volumes.
- Germany's specialty chemical corridor:Production clustering around Leverkusen and Marl is generating knowledge spillovers that accelerate formulation innovation.
Market Restraints
- Acrylamide monomer discharge limits:EPA Clean Water Act effluent constraints are raising capital requirements for U.S. polyacrylamide purification infrastructure.
- Fossil-derived feedstock dependency:EU Green Deal carbon border adjustments threaten margin structures for conventional petroleum-based polymer production.
- Biopolymer performance gaps:Bio-based alternatives currently fail moisture-barrier specifications for flexible electronics substrate applications.
Strategic Opportunities
- India's pharmaceutical manufacturing expansion:CDSCO certification pipelines for excipient-grade imports are opening procurement channels for European suppliers.
- Layered silicate nanocomposites:Reinforced barrier films are penetrating organic light-emitting diode encapsulation markets previously served by glass.
- EU CSRD disclosure mandates:Sustainability reporting requirements are creating premium pricing tiers for mass-balance certified circular feedstocks.
Industry Challenges
- ICH Q3D elemental impurity compliance:Heavy metal detection protocols are extending pharmaceutical qualification cycles by 8-14 months.
- Multi-site audit coordination:FDA and EMA inspection scheduling conflicts are delaying dual-territory product launches.
- Legacy equipment retrofitting:Existing extrusion lines require capital-intensive modification to process nanocomposite masterbatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polar Polymers Market |
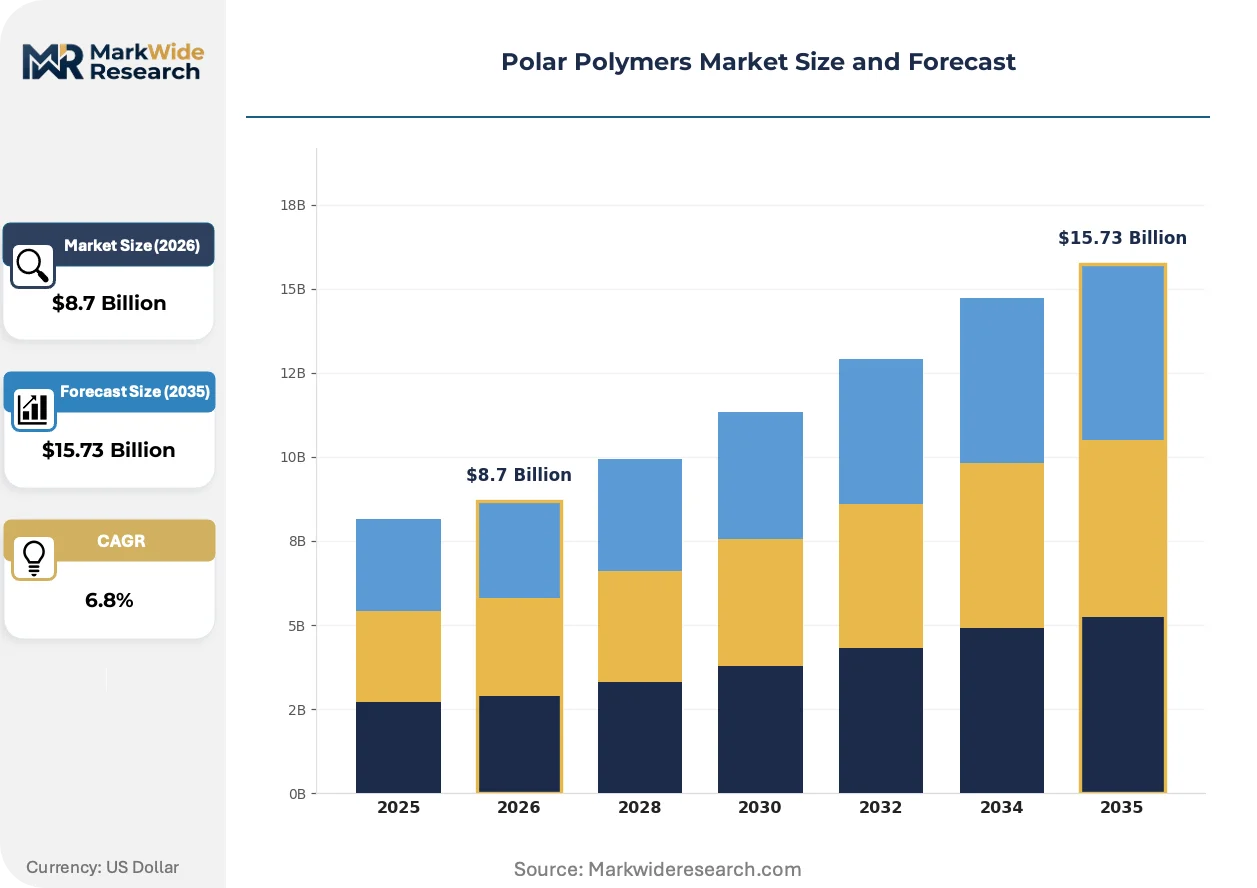
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene Glycol, Polyvinyl Alcohol, Polyethylene Oxide, Polyacrylamide Application: Adhesives, Coatings, Textiles, Pharmaceuticals End User: Automotive, Aerospace, Electronics, Healthcare Technology: Biopolymer, Nanocomposite, Thermoplastic, Cross-linked |
| Companies Covered | Evonik Industries AG, Covestro AG, DuPont de Nemours Inc., Toray Industries Inc., LG Chem Ltd., BASF SE, Solvay SA, Eastman Chemical Company, Arkema Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polar Polymers Market Evolving Landscape
Material science convergence with pharmaceutical formulation science is redefining performance specifications across adhesion, barrier, and controlled-release applications.
Reactive extrusion compounding is fragmenting traditional batch polymerization economics. Medical device manufacturers in Minnesota and Massachusetts are adopting continuous processing for polycarbonate-urethane alloys at pilot scale. This technology is fragmenting capital allocation patterns as producers defer large-scale reactor investments in favor of modular extrusion lines.
EMA's ICH Q3D guideline implementation is forcing elemental impurity testing downstream into excipient supply chains. German and Swiss polymer distributors are building in-house inductively coupled plasma mass spectrometry capabilities to preserve margin capture. High-purity polyethylene glycol grades face the steepest compliance cost escalation as pharmaceutical certification thresholds tighten.
Formulator buying committees are consolidating supplier rosters around vertically integrated producers with captive pharmaceutical certification pipelines. Electronics packaging buyers in South Korea and Taiwan are prioritizing ionomer suppliers with integrated resin-to-compound capabilities. This concentration is most visible in semiconductor adhesion layer procurement, where dual-source requirements are compressing to single-source plus qualified alternative structures.
Polar Polymers Market Segmentation
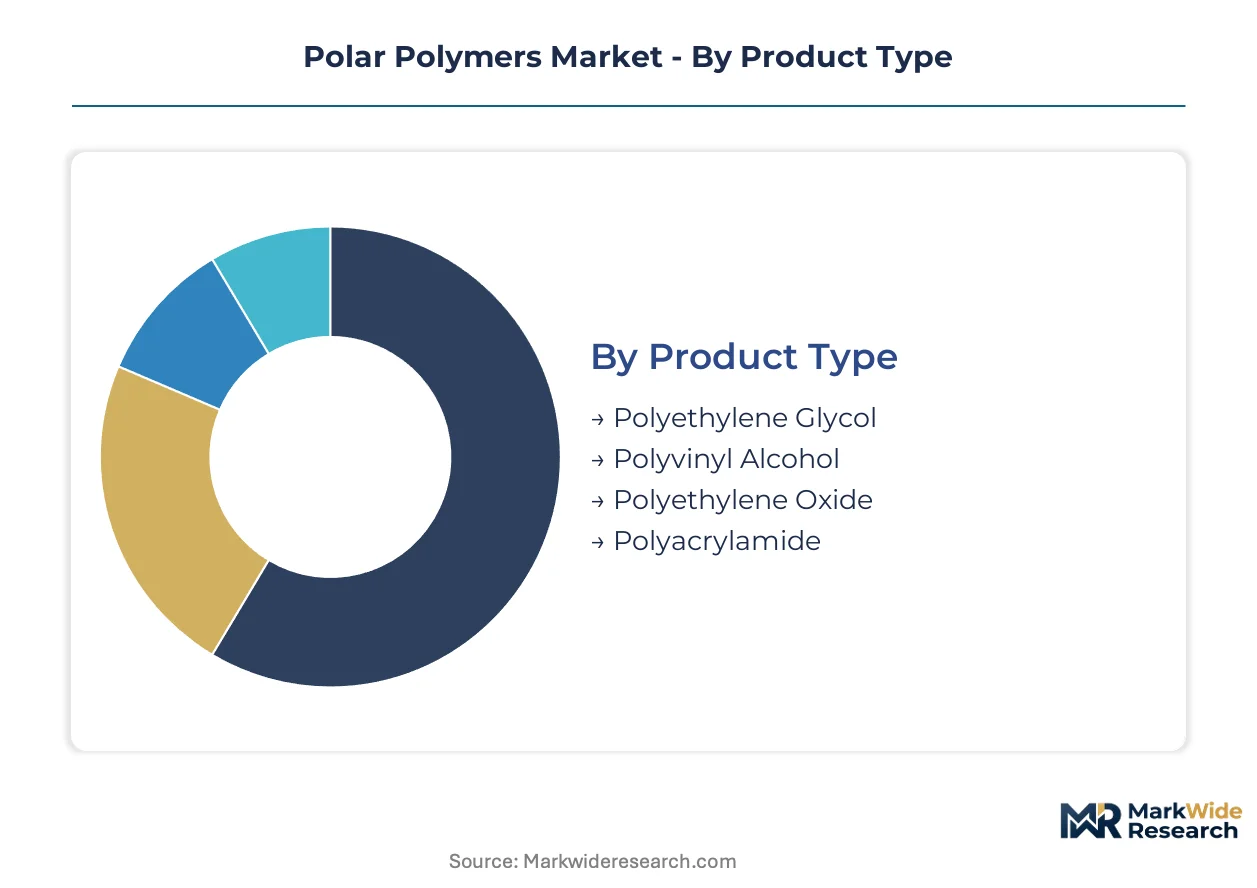
Polar polymer value pools fragment across distinct performance tiers, with pharmaceutical certification and nanoscale reinforcement commanding premium positioning. Material selection criteria diverge sharply between regulated healthcare applications and industrial formulations where cost efficiency dominates procurement.
Product Type:
Margin concentration tracks purity gradients, with pharmaceutical-grade outputs capturing value multiples over industrial commodity grades.
- Polyethylene Glycol:Linear polyether with terminal hydroxyl groups enabling hydrogen bonding and water miscibility across molecular weight ranges. Injectable-grade demand concentrates in German and Swiss drug manufacturing corridors where EMA pharmaceutical certification pipelines lock in multi-year supply agreements. REACH substance registration requirements compress supplier qualification timelines for European healthcare formulators.
- Polyvinyl Alcohol:Partially or fully hydrolyzed polyvinyl acetate derivative with crystallinity tunable through degree of hydrolysis. Textile sizing applications in South Korean and Taiwanese synthetic fiber operations absorb volume grades where complete biodegradability commands positioning premiums against petrochemical alternatives.
- Polyethylene Oxide:Ultra-high molecular weight linear polyether with exceptional chain entanglement enabling drag reduction and flocculation.
- Polyacrylamide:Acrylamide monomer polymer with anionic, cationic, or non-ionic charge variants for water treatment and oilfield applications.
Polyethylene glycol holds installed capacity. Polyvinyl alcohol is rotating up the share rankings.
Application:
Adhesion and barrier functionality requirements are concentrating procurement around suppliers with integrated formulation laboratories.
- Adhesives:Structural and pressure-sensitive formulations leveraging polar polymer hydrogen bonding for substrate wetting and cohesive strength. Automotive interior lamination in Stuttgart and Wolfsburg manufacturing clusters absorbs moisture-curing polyurethane dispersions where VOC emission limits tighten material specifications.
- Pharmaceuticals:Excipient and active pharmaceutical ingredient carrier systems governed by USP and EP monographs. Controlled-release matrix tablets and bioadhesive transdermal patches in Massachusetts and New Jersey pharmaceutical corridors demand elemental impurity testing under FDA ICH Q3D guidelines.
- Coatings:Film-forming barriers for corrosion protection and optical clarity in electronics and industrial substrates.
- Textiles:Sizing agents and fiber finishes enabling weaving efficiency and hand modification in synthetic and natural yarn processing.
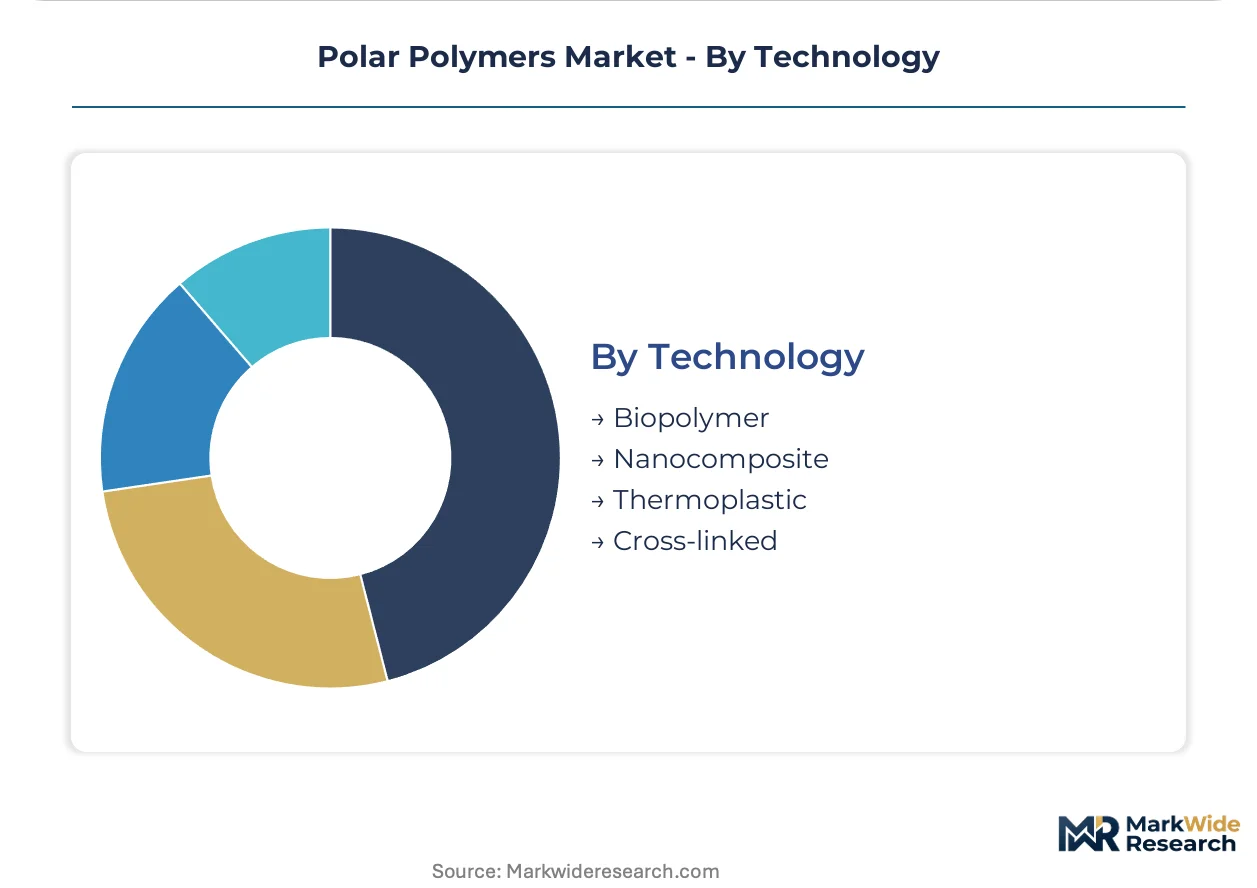
Pharmaceutical applications concentrate value capture. Adhesives are expanding most quickly as automotive electrification multiplies bonding surface complexity.
End User:
Electronics packaging specifications are fragmenting supplier portfolios between semiconductor-grade purity and industrial performance tiers.
- Electronics:Semiconductor adhesion layers, flexible display encapsulation, and printed circuit board protection requiring ionic purity below ppm thresholds. South Korean and Taiwanese packaging houses prioritize ionomer suppliers with captive resin-to-compound capabilities for flip-chip underfill and wafer-level packaging.
- Healthcare:Medical device compatibility and drug delivery system integration with biocompatibility certification under ISO 10993 protocols. Minnesota and Massachusetts device manufacturers pilot continuous processing for polycarbonate-urethane alloys at reduced capital intensity versus batch polymerization.
- Automotive:Lightweight structural bonding and interior lamination for electrified powertrain architectures.
- Aerospace:High-performance composites and surface protection requiring outgassing control and flame resistance certification.
Healthcare commands qualification premiums. Electronics is climbing the fastest as organic light-emitting diode encapsulation displaces glass barriers.
Technology:
Reinforcement architectures are redefining performance boundaries without sacrificing processability in conventional extrusion equipment.
- Nanocomposite:Layered silicate or carbon nanotube dispersions at sub-micron scale enhancing barrier properties and mechanical modulus. Organic light-emitting diode encapsulation markets previously served by glass substrates now adopt nanocomposite films for flexibility and weight reduction in South Korean display manufacturing.
- Biopolymer:Fermentation-derived or bio-based feedstock polymers with mass-balance certification under EU Green Deal frameworks. Circular feedstock claims create premium pricing tiers as CSRD disclosure mandates intensify supply chain transparency requirements for European automotive and packaging buyers.
- Thermoplastic:Melt-processable linear polymers with reversible thermal transitions enabling injection molding and extrusion.
- Cross-linked:Covalent network architectures providing dimensional stability and chemical resistance through irreversible bond formation.
Thermoplastic platforms hold installed capacity. Nanocomposite is gaining share fastest as display packaging requirements fragment incumbent material hierarchies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Healthcare formulators and electronics packagers concentrate procurement around certified suppliers with captive pharmaceutical pipelines and semiconductor-grade purification capabilities.
Germany
Leverkusen and Marl chemical corridors anchor European polyethylene glycol production for injectable-grade pharmaceutical applications. REACH substance registration requirements compress supplier qualification timelines for drug manufacturers seeking multi-year supply security. Covestro AG maintains specialized polycarbonate derivative capacity serving medical device compatibility testing under EMA pharmaceutical quality guidelines.
United States
Minnesota and Massachusetts medical device manufacturers pilot continuous processing for polycarbonate-urethane alloys at reduced capital intensity versus batch polymerization. FDA ICH Q3D elemental impurity standards force upstream purification investments for excipient-grade polyethylene glycol outputs. EPA Clean Water Act effluent constraints on acrylamide monomer discharge redirect polyacrylamide capacity toward lower-toxicity copolymer chemistries.
South Korea
Display packaging houses in Seoul and Busan prioritize ionomer suppliers with integrated resin-to-compound capabilities for organic light-emitting diode encapsulation. MFDS pharmaceutical certification pipelines open procurement channels for European excipient-grade imports. Samsung and LG display manufacturing clusters absorb nanocomposite barrier films displacing glass substrates in flexible electronics.
India
Maharashtra and Gujarat pharmaceutical corridors expand CDSCO certification pipelines for excipient-grade polar polymer imports from European suppliers. Controlled-release drug delivery system manufacturing in Hyderabad and Mumbai absorbs pharmaceutical-grade polyethylene glycol at expanding volumes. Domestic formulators reorganize procurement priorities around USP and EP monograph compliance for export-oriented production.
Japan
Kansai region electronics packaging specialists demand ionic purity below ppm thresholds for semiconductor adhesion layer applications. PMDA pharmaceutical quality guidelines align with ICH Q3D standards, extending elemental impurity testing into excipient supply chains. Toray Industries anchors regional production of high-performance polymer films for flexible display encapsulation markets.
Polar Polymers Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with captive pharmaceutical certification pipelines and specialized polymer divisions. Tiering separates vertically integrated producers with in-house resin-to-compound capabilities from formulation-dependent distributors. Two archetypes dominate: German and Swiss high-purity specialists with EMA-locked supply agreements, and Asian diversified conglomerates with scale-driven electronics packaging positions. Competitive moves concentrate on strategic partnerships for nanocomposite masterbatch technology access and geographic expansion into Indian pharmaceutical manufacturing corridors.
Within the high-purity specialist tier, Evonik Industries AG and Covestro AG exemplify European producers with pharmaceutical certification pipelines that lock in multi-year supply agreements. DuPont de Nemours Inc. occupies a position among North American diversified chemical producers with ionomer portfolios tailored to semiconductor adhesion applications. BASF SE and Solvay SA represent scale-driven conglomerates with broad polar polymer portfolios spanning industrial and regulated healthcare tiers.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Covestro AG |
| DuPont de Nemours Inc. |
| Toray Industries Inc. |
| LG Chem Ltd. |
| BASF SE |
| Solvay SA |
| Eastman Chemical Company |
| Arkema Group |
| Others |
Value Network & Pricing Analysis
EMA pharmaceutical quality guidelines gate both supply qualification timelines and price differentiation simultaneously, compressing supplier rosters to certified manufacturers who capture multi-year contract premiums while locking out uncertified competitors from healthcare procurement channels.
Pricing Analysis
Cost-plus contracts indexed to ethylene oxide and propylene oxide feedstock benchmarks dominate pharmaceutical-grade polyethylene glycol procurement. Three-tier pricing structure across injectable-grade, technical-grade, and industrial-grade levels separates EMA-certified outputs from commodity alternatives. Cost compression in technical-grade tiers is intensifying because South Korean electronics packagers are consolidating volumes around qualified suppliers. Hospital formulators in Germany and Switzerland exhibit lowest price sensitivity due to regulatory compliance mandates, while Indian generic drug manufacturers face acute cost pressure in export markets.
Supply Chain Analysis
Germany and the United States anchor high-purity polar polymer production for pharmaceutical and medical device applications. Acrylamide monomer, ethylene oxide, and vinyl acetate feedstock supplies draw from petrochemical complexes in the US Gulf Coast and Rotterdam-Antwerp corridor. Single-source vulnerability concentrates in pharmaceutical-grade polyethylene glycol purification, where EMA-locked capacity at Leverkusen and Marl facilities limits buyer switching. Distribution runs through certified distributors with in-house inductively coupled plasma mass spectrometry capabilities serving European healthcare formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polar polymer supply chains constitute a defensive-moat market structure where regulatory entrenchment through pharmaceutical certification pipelines creates durable competitive positioning against unqualified entrants.
For Market Incumbents: Fortify EMA-locked supply agreements by expanding captive pharmaceutical certification pipelines into Indian CDSCO corridors, while deepening backward integration into high-purity ethylene oxide production to offset feedstock volatility. Emerging biopolymer substitutes threaten margin structures in automotive adhesion applications, necessitating nanocomposite masterbatch R&D investment to preserve barrier performance advantages. For New Entrants and Emerging Players: Technical service gaps in nanocomposite formulation support offer white-space entry points for regional compounders lacking in-house laboratories. India's pharmaceutical manufacturing expansion presents the most penetrable geography, where CDSCO certification timelines lag European equivalents by 12-18 months. A go-to-market angle centered on rapid qualification support for Hyderabad and Mumbai formulators can bypass incumbent EMA-locked relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across continuous processing extrusion technologies, enabling modular capacity expansion without batch reactor commitments. Long-term viability favors vertically integrated producers with captive resin-to-compound capabilities and pharmaceutical certification pipelines. The signal to watch is MFDS approval acceleration for European excipient-grade imports into South Korean display packaging markets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Purity Feedstocks | Covestro and Evonik anchor margin control through captive ethylene oxide supply at Leverkusen complexes. |
| Pharmaceutical Certification Pipeline Expansion | CDSCO qualification investments unlock procurement channels in Maharashtra and Gujarat pharmaceutical corridors. |
| Nanocomposite Masterbatch Technology Access | Layered silicate dispersions enable South Korean OLED encapsulation markets previously served by glass barriers. |
| Continuous Processing Extrusion Deployment | Minnesota and Massachusetts medical device manufacturers reduce capital intensity versus batch polymerization. |
| Long-Term Supply Agreement Structuring | Multi-year EMA-locked contracts compress buyer switching frequency in German drug manufacturing clusters. |
Research Methodology
Operator-level perspectives from pharmaceutical formulators, medical device procurement managers, specialty chemical plant engineers, and electronics packaging specialists anchored the qualitative base. Primary fieldwork combined structured interviews with downstream OEM procurement leads and distribution channel partners across German, US, South Korean, and Indian markets. Secondary validation drew from EMA pharmaceutical quality guidelines, FDA ICH Q3D submissions, REACH substance registration databases, and SEC 10-K filings of diversified chemical conglomerates. Bottom-up volume estimates triangulated against top-down value projections across grade tier, end-use industry, and regional production hub dimensions.
Sensitivity analysis tested forecast robustness across feedstock price volatility scenarios and regulatory approval timeline variations over the projection horizon. Segmentation modeling captured product type, application, end user, and technology dimensions alongside pharmaceutical certification tier and nanocomposite reinforcement architecture. CAGRs derived from compound growth trajectory fitting to historical shipment data and capacity expansion announcements. Industry-specific inputs incorporated EMA implementation schedules for elemental impurity testing and EU Green Deal carbon border adjustment timelines.
Underlying assumptions cover sustained REACH compliance enforcement and pharmaceutical-grade demand expansion, with deviation risk concentrated in biopolymer technology readiness acceleration and acrylamide monomer discharge limit tightening. Forecasts reflect these documented assumptions with explicit scenario weighting for regulatory and feedstock variables. Recalibration cycles align with material shifts in EMA guideline implementation and CDSCO certification pipeline throughput.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
North America Plastic Compounding Market
Polymers & Resins
South America Polymer Emulsion Market
Polymers & Resins
Nylon Resins Market
Polymers & Resins
Global Polymer Chameleons Market
Polymers & Resins
Methyl Methacrylate Acrylonitrile Butadiene Styrene (MABS) Market
Polymers & Resins
Polyamide Resins Market
Polymers & Resins
Polylactic Acid Market
Polymers & Resins
Bio-Based Polypropylene in Medical Devices Market
Polymers & Resins
Polyphthalamide (PPA) Resin Market
Polymers & Resins
Polymer Microinjection Molding Market
Polymers & Resins
Global Graft Polyols Market
Polymers & Resins
Paste PVC Resin Market
Polymers & Resins
Copolyesters Market
Polymers & Resins
Acrylonitrile Butadiene Styrene (ABS) Market
Polymers & Resins
Bakelite Market
Polymers & Resins
Styrenics Market