
 Global Polyamide 6 Market | 2026-2036
Global Polyamide 6 Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polyamide 6 Market Foresight
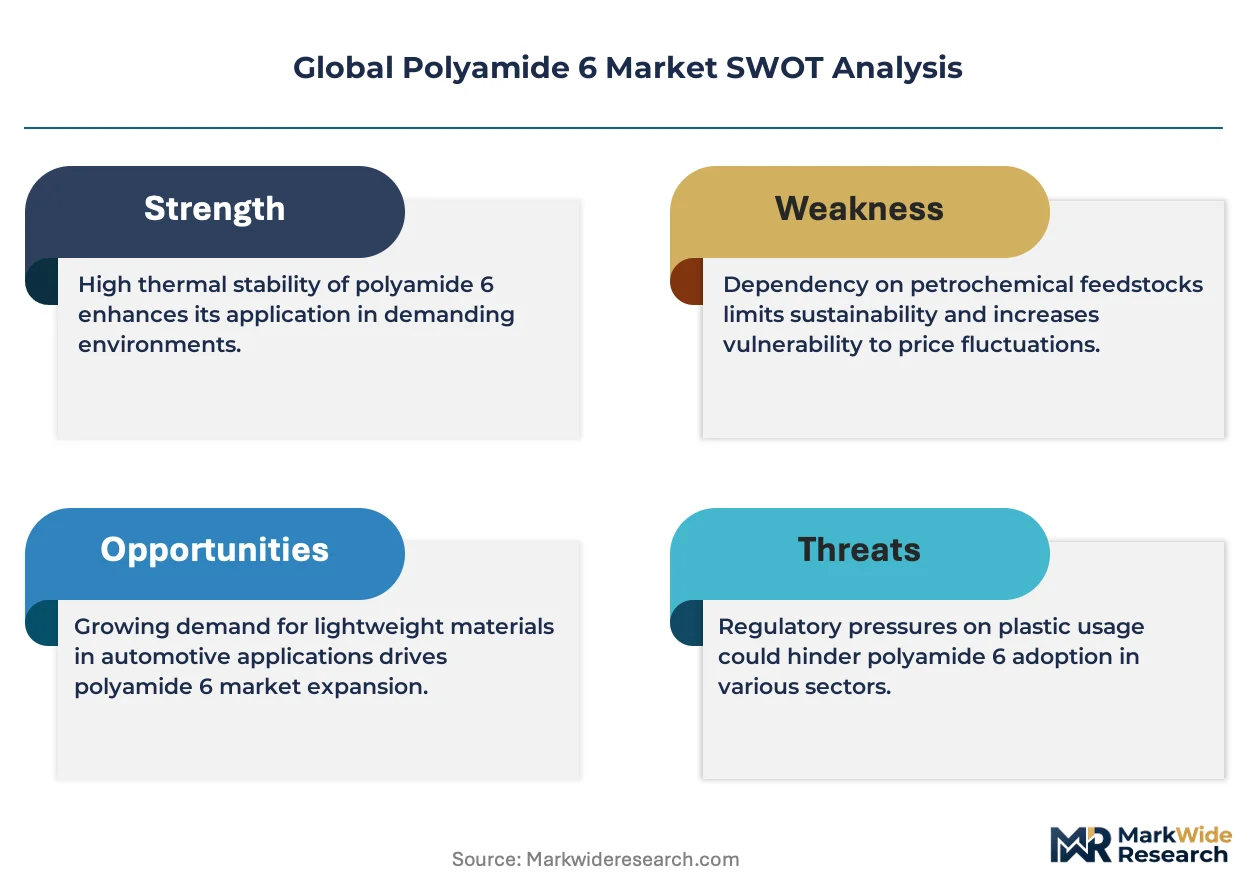
Engineering-grade polyamide 6 with higher relative viscosity specifications is rotating toward premium automotive and electrical applications. BASF SE leverages its integrated caprolactam complexes in Ludwigshafen and Antwerp to sustain cost-competitive supply of high-purity grades. DOMO Chemicals anchors its position through specialized nylon compounds for thermal management in electric powertrains. Ascend Performance Materials differentiates via its vertically controlled hexamethylene diamine and adipic acid feedstock chain across the US Gulf Coast.
Polyamide 6 is a semi-crystalline thermoplastic polymer synthesized primarily through ring-opening polymerization of caprolactam, exhibiting melting points between 215°C and 225°C and tensile strengths of 70–85 MPa in unfilled grades. Its molecular structure delivers fatigue resistance, chemical compatibility with hydrocarbons, and processability via injection molding and extrusion, serving load-bearing components in transportation, industrial machinery, and consumer durables. Fiber-grade material still occupies the largest volume share, though resin formulations for under-hood automotive and connector housings represent the fastest-expanding margin pool. Automotive applications lead value generation, while electronics demand for surface-mount-compatible grades is gaining share as miniaturization intensifies thermal performance requirements.
REACH registration requirements and RoHS substance restrictions in Europe compel reformulation of flame-retardant PA6 compounds away from legacy halogenated systems, while EPA toxicity evaluations under TSCA influence US import and processing standards for caprolactam monomer. China's GB standards for automotive interior emissions and MIIT new energy vehicle material specifications are converging to accelerate substitution of metal and lower-performance plastics. Stakeholders must monitor caprolactam feedstock cost trajectories and regulatory timelines for recycled-content mandates to calibrate capacity and formulation investments.
Market Dynamics
Integrated caprolactam-to-PA6 production corridors in East China's Yangtze River Delta and Germany's Rhine-Ruhr basin are compressing supply chains and redrawing competitive boundaries around feedstock security rather than compound formulation alone.
Growth Catalysts
- EU F-Gas Regulation:Tightening fluorinated gas restrictions are accelerating substitution of metal engine components with lightweight PA6 grades in German and French automotive assembly.
- Electric powertrain thermal management:Battery enclosure and inverter housing specifications are pulling engineering-grade PA6 with enhanced heat deflection temperatures into EV platforms across multiple OEM supply chains.
- Yangtze River Delta cluster concentration:Caprolactam producers in Jiangsu and Zhejiang provinces are achieving cost positions that support export-competitive fiber-grade supply to Southeast Asian textile manufacturers.
Market Restraints
- Caprolactam feedstock volatility:Benzene and cyclohexane cost swings transmit directly to PA6 resin pricing, compressing compounder margins during upstream crude derivative spikes.
- Single-region supply concentration:Overreliance on integrated Chinese caprolactam complexes exposes downstream processors to logistics disruptions and export policy shifts affecting Yangtze River port operations.
- Polypropylene substitution in interior automotive:Lower-cost filled PP grades with improved scratch resistance are displacing PA6 in non-structural cabin components where temperature loads permit.
Strategic Opportunities
- India automotive localization:PLI scheme incentives for advanced chemistry cell and component manufacturing are creating demand for localized PA6 compounding capacity serving domestic OEMs.
- Bio-based caprolactam pathways:Fermentation-derived feedstocks from agricultural waste streams offer positioning for premium grades targeting EU Green Deal circular economy procurement mandates.
- Direct e-commerce distribution to processors:Specialty compounders are bypassing traditional distributor networks to serve mid-tier injection molders with tailored lot sizes and technical service.
Industry Challenges
- REACH SVHC compliance timelines:ECHA substance of very high concern evaluations for legacy flame-retardant additives are forcing rapid reformulation cycles with uncertain approval durations.
- Recycled-content verification infrastructure:Mass balance accounting for chemically recycled caprolactam lacks standardized third-party certification, complicating customer claims and auditor scrutiny.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polyamide 6 Market |
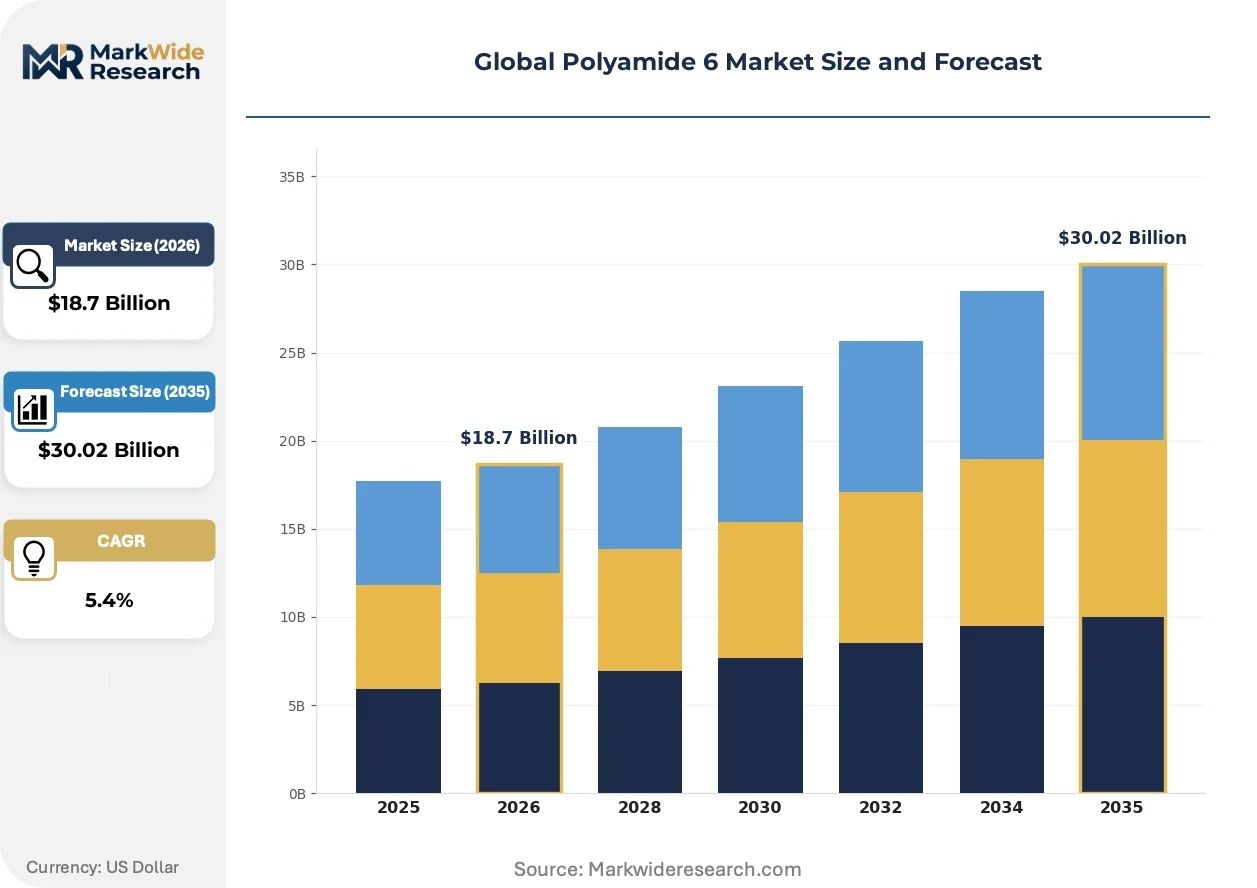
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $30.02 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber, Resin, Film, Bead Application: Automotive, Electronics, Textiles, Consumer Goods End User: Manufacturers, OEMs, Retailers, Distributors Distribution Channel: Online, Offline, Direct, Wholesale |
| Companies Covered | BASF SE, DOMO Chemicals, Ascend Performance Materials, Lanxess AG, Arkema Group, Toray Industries, UBE Corporation, Highsun Holding Group, RadiciGroup, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polyamide 6 Market Shifts & Advancements
Material science advances and regulatory chemistry restrictions are fragmenting the traditional PA6 grade hierarchy into application-specific performance tiers with diverging technical specifications and price positioning.
Glass fiber reinforcement loadings are bifurcating between 30-35% standard compositions for commodity automotive under-hood parts and 50-60% ultra-high stiffness grades for structural metal replacement in electric vehicle battery trays. Tier-1 suppliers in Germany and China are qualifying the higher-load formulations for crash-critical applications, compressing the addressable market for intermediate 40-45% grades that lack clear performance differentiation.
REACH authorization requirements for halogenated flame retardants are compelling reformulation toward phosphorus-nitrogen synergist systems in European electrical housing applications. Compounders serving connector and breaker markets are absorbing elevated raw material costs and extended qualification periods, with appliance manufacturers in Poland and Italy accelerating validation timelines to maintain CE marking compliance.
Automotive OEMs are consolidating resin specifications across platform architectures to reduce supplier qualification overhead and inventory complexity. Procurement teams at German and Japanese manufacturers are narrowing approved material lists to three viscosity grades per polymer family, concentrating volume with compounders capable of global specification consistency across Ludwigshafen, Shanghai, and Detroit supply points.
Global Polyamide 6 Market Segmentation
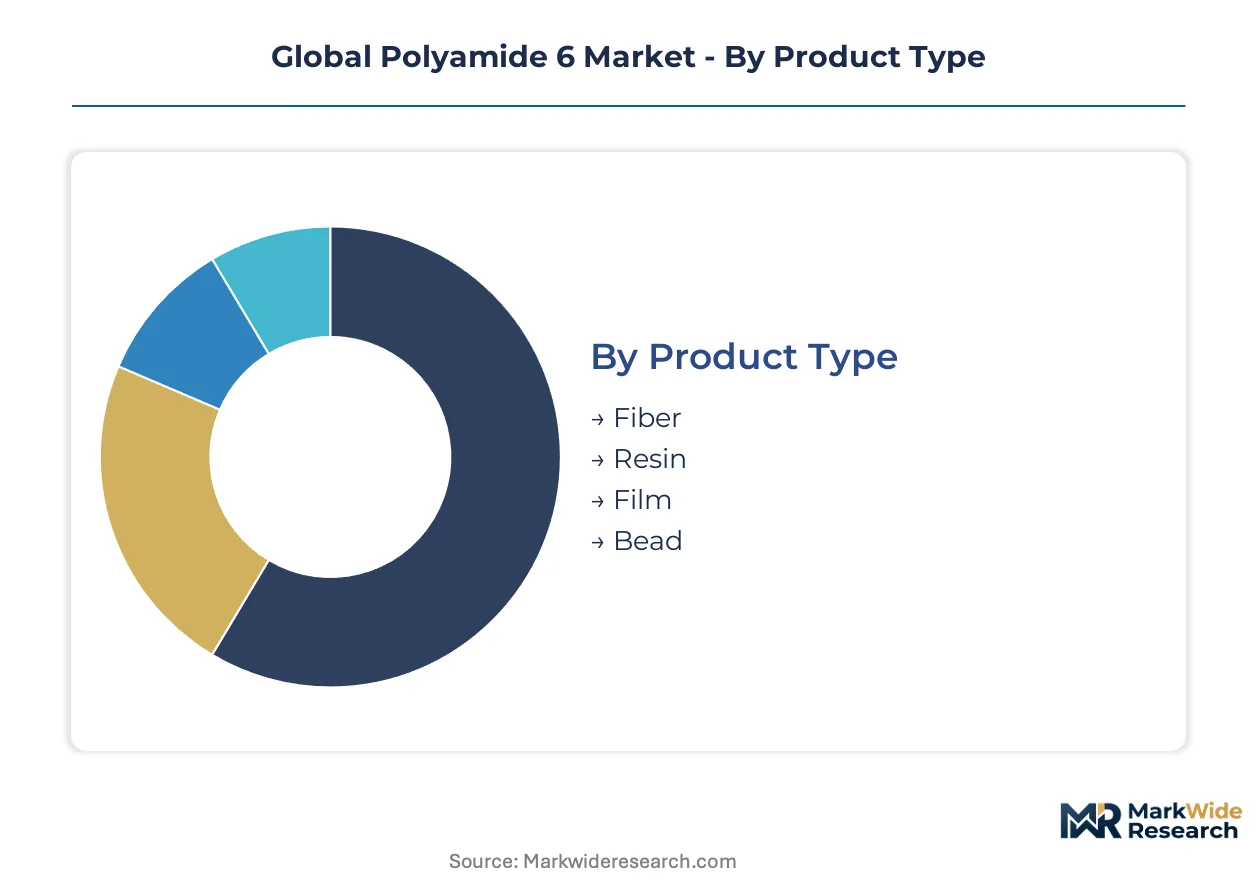
Polyamide 6 market segmentation reveals divergent supply chain configurations across product forms, with fiber-grade production concentrating in East Asian chemical corridors while engineering resins serve geographically dispersed automotive and electronics manufacturing. Understanding these segment boundaries enables precise capacity planning and margin capture across distinct technical specifications and customer qualification requirements.
Product Type:
Domestic consumption dominates fiber and film grades through integrated caprolactam-to-textile corridors in China and India, whereas resin and bead formulations serve export-oriented compounders in Germany, the US, and Japan with specialized automotive and electrical specifications.
- Fiber:Ring-spun and industrial filament grades spun from high-relative-viscosity polymer serve tire cord, carpet, and apparel applications. Yangtze River Delta producers supply Southeast Asian textile manufacturers with cost-competitive fiber-grade material, though benzene cost volatility compresses spinner margins during upstream petrochemical spikes.
- Resin:Engineering-grade formulations with tailored viscosity specifications feed injection molding and extrusion processes for under-hood automotive components and electrical housings. German compounders in Ludwigshafen and Shanghai-based suppliers are qualifying 50-60% glass-filled grades for EV battery tray structural applications, pulling material away from commodity 30-35% loadings.
- Film:Biaxially oriented and cast film structures serve food packaging and industrial barrier applications with controlled crystallinity and puncture resistance.
- Bead:Precision-cut spherical particles enable rotational molding and powder coating processes for tank fabrication and metal surface protection.
Fiber holds the largest share; momentum sits with resin as electric powertrain thermal management specifications intensify.
Application:
Margin structures bifurcate sharply across applications, with automotive and electronics commanding formulation premiums for flame-retardant and heat-stabilized grades while textiles and consumer goods compete on throughput efficiency and feedstock cost position.
- Automotive:Under-hood components, air intake manifolds, and cooling system housings utilize glass-reinforced and mineral-filled grades replacing metal castings. EU F-Gas Regulation tightening is accelerating PA6 substitution for aluminum engine parts in German and French assembly plants, with procurement teams consolidating resin specifications across platform architectures to reduce supplier qualification overhead.
- Electronics:Connector housings, circuit breaker bodies, and surface-mount-compatible enclosures demand halogen-free flame-retardant formulations meeting RoHS and REACH SVHC requirements. Polish and Italian appliance manufacturers are absorbing elevated raw material costs and extended qualification periods to maintain CE marking compliance as ECHA evaluations force phosphorus-nitrogen synergist system adoption.
- Textiles:Carpet fiber, industrial yarn, and apparel filament consume volume-dominant fiber-grade output with specifications tuned for dye uptake and abrasion resistance.
- Consumer Goods:Power tool housings, sporting equipment, and furniture components utilize standard-impact grades where polypropylene substitution pressures pricing in non-structural applications.
Automotive commands the value pool; electronics climbs fastest as miniaturization intensifies thermal performance requirements.
End User:
Procurement patterns separate volume-committed OEMs with multi-year supply agreements from fragmented distributors serving spot-market processors, with manufacturers occupying intermediate positions based on captive compounding capabilities.
- Manufacturers:Integrated textile spinners and resin compounders with captive caprolactam supply or backward integration into adipic acid and hexamethylene diamine chains. Ascend Performance Materials maintains vertically controlled feedstock positions across the US Gulf Coast, while BASF SE leverages Ludwigshafen and Antwerp complexes for high-purity grade supply.
- OEMs:Automotive assemblers and appliance brands with direct material specifications and approved supplier lists narrowed to three viscosity grades per polymer family for global consistency.
- Retailers:Big-box chains and specialty distributors serving consumer goods fabricators with standard-grade inventory positions.
- Distributors:Regional chemical traders providing technical service and tailored lot sizes to mid-tier injection molders bypassing traditional networks.
Manufacturers capture margin through feedstock control; distributors gain traction via technical service specialization.
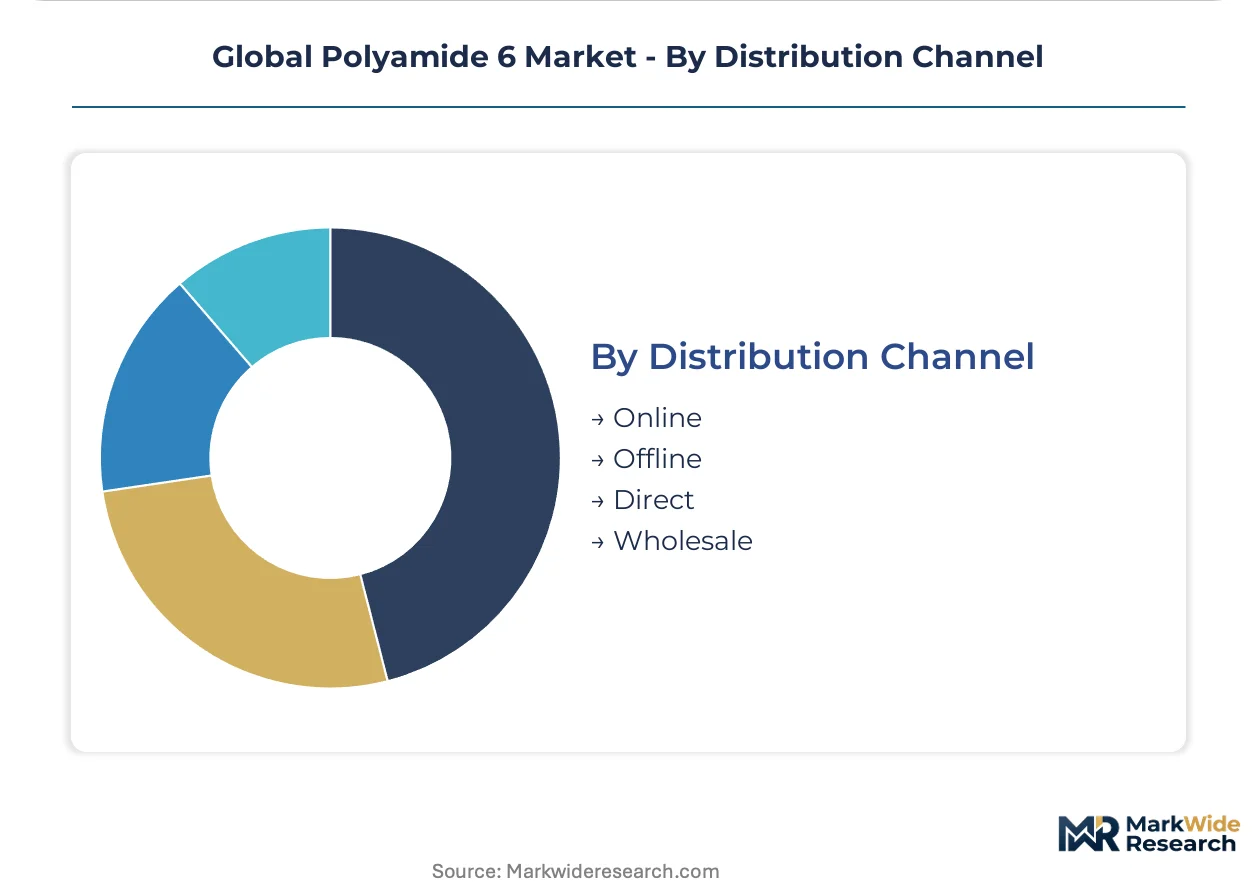
Distribution Channel:
Channel selection correlates with order scale and formulation complexity, with direct relationships dominating engineered resin volumes while wholesale networks handle commodity fiber and film movements.
- Online:Digital platforms enabling spot purchasing and technical documentation access for standardized grades with published specifications.
- Offline:Traditional field sales and technical service relationships supporting qualification-intensive automotive and electronics applications.
- Direct:Producer-to-processor contracts for high-volume OEM supply with dedicated inventory and collaborative formulation development.
- Wholesale:Consolidated distribution for fiber-grade material serving dispersed textile manufacturers with regional warehouse positioning.
Direct channels dominate engineered resin value; wholesale retains fiber-grade volume leadership.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China exports cost-competitive fiber-grade polyamide 6 to Southeast Asian textile manufacturers while Germany supplies engineering-grade resin to automotive OEMs across the EU and North America. This trade-flow pattern concentrates production in integrated chemical corridors and fragments compounding capacity near end-use manufacturing.
Germany
Automotive OEM procurement teams at Volkswagen, BMW, and Mercedes-Benz are consolidating approved resin specifications to three viscosity grades per polymer family. The EU F-Gas Regulation tightens fluorinated gas restrictions, accelerating PA6 substitution for aluminum engine components in assembly plants across Bavaria and Baden-Württemberg. BASF SE leverages its Ludwigshafen caprolactam complex to sustain cost-competitive supply of high-purity grades for under-hood applications.
China
MIIT new energy vehicle material specifications and GB standards for automotive interior emissions are converging to accelerate metal substitution in electric powertrains. The dual carbon goals tighten emissions standards that favor recycled and bio-based polyamide grades. Integrated caprolactam-to-PA6 production corridors in Jiangsu and Zhejiang provinces within the Yangtze River Delta dominate supply and achieve export-competitive positions for fiber-grade material.
United States
EPA toxicity evaluations under TSCA influence import and processing standards for caprolactam monomer, affecting compounder qualification timelines. Automotive manufacturers in Michigan and Ohio are expanding PA6 adoption for lightweight engine components as NHTSA fuel economy standards tighten. Ascend Performance Materials maintains vertically controlled hexamethylene diamine and adipic acid feedstock positions across the US Gulf Coast.
India
PLI scheme incentives for advanced chemistry cell and component manufacturing are creating demand for localized PA6 compounding capacity serving domestic OEMs such as Tata Motors and Mahindra. BIS standards for automotive materials are evolving to align with global specifications. Gujarat and Maharashtra industrial corridors are attracting resin compounders to position near emerging EV battery and powertrain assembly operations.
Japan
METI industrial policy supports domestic production of high-performance engineering plastics for electronics and automotive applications. JIS standards for electrical housing materials align with RoHS and REACH restrictions, compelling reformulation of flame-retardant compounds. Toray Industries and UBE Corporation anchor supply from Chubu and Kansai manufacturing bases, serving precision connector and surface-mount component demand across East Asian electronics supply chains.
Global Polyamide 6 Market Competitive Landscape
Listed leaders compete with private specialists across feedstock integration and formulation complexity. The vendor base concentrates around integrated petrochemical complexes in Germany, China, and the United States, with compounders occupying intermediate positions based on captive compounding capabilities. Three archetypes dominate: integrated petrochemical majors with backward control into caprolactam, specialized nylon compounders focused on thermal management grades, and regional fiber-grade producers serving textile export markets. Competitive moves center on M&A to secure feedstock positions and capacity expansion in high-viscosity engineering resin grades.
Among German and Belgian integrated producers, BASF SE and Lanxess AG occupy positions defined by Ludwigshafen and Antwerp chemical complex access. DOMO Chemicals exemplifies the specialized compounder archetype through its focus on electric powertrain thermal management formulations. Ascend Performance Materials anchors the US-based feedstock-integrated tier with Gulf Coast hexamethylene diamine and adipic acid supply control. These three represent divergent strategic paths: complex-scale dominance, application-specific formulation depth, and upstream feedstock security.
| Leading Market Players |
|---|
| BASF SE |
| DOMO Chemicals |
| Ascend Performance Materials |
| Lanxess AG |
| Arkema Group |
| Toray Industries |
| UBE Corporation |
| Highsun Holding Group |
| RadiciGroup |
| Others |
Supply & Pricing Matrix
PA6 substitution for aluminum engine components under EU F-Gas Regulation simultaneously redistributes production geography toward German automotive corridors and compresses pricing premiums for engineering-grade resin formulations.
Pricing Analysis
Current-generation 50-60% glass-filled grades command substantial premiums over prior-generation 30-35% loadings and next-generation bio-based formulations still in qualification. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and volume scale commitments from German OEM procurement teams. Cost compression in fiber-grade material is intensifying because Yangtze River Delta producers are achieving export-competitive positions for Southeast Asian textile manufacturers. Tier-1 automotive suppliers exhibit least price sensitivity due to crash-critical qualification requirements, while mid-tier injection molders serving consumer goods face acute margin pressure from polypropylene substitution.
Supply Chain Analysis
Benzene and cyclohexane feedstock transit through Rotterdam-Antwerp chemical corridors anchors European PA6 resin pricing and exposes compounders to crude derivative volatility. Supply concentrates in Germany, China, and the United States, with integrated caprolactam-to-PA6 production corridors in Ludwigshafen and the Yangtze River Delta dominating engineering-grade output. Raw material dependencies rest on benzene, cyclohexane, and caprolactam monomer supply security. Single-source vulnerability from overreliance on Chinese integrated complexes creates exposure to Yangtze River port logistics disruptions. Distribution runs through direct producer-to-processor contracts for engineered resin and wholesale networks for fiber-grade material.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Polyamide 6 supply chains are approaching a platform-economics inflection as automotive OEMs consolidate approved material lists and demand interoperable specifications across Ludwigshafen, Shanghai, and Detroit supply points.
For Market Incumbents: Compound feedstock security through backward integration into caprolactam or adipic acid supply chains, particularly across the US Gulf Coast where Ascend Performance Materials has demonstrated viable positioning. Defend margin pools by accelerating qualification of 50-60% glass-filled grades for EV battery tray applications before commodity compounders achieve technical parity. Prioritize certification investment for phosphorus-nitrogen flame-retardant systems as ECHA SVHC evaluations force rapid reformulation cycles. For New Entrants and Emerging Players: Lead with bio-based caprolactam pathways targeting EU Green Deal circular economy procurement mandates where premium positioning remains undercontested. Target India automotive localization under PLI scheme incentives, where domestic compounding capacity serving Tata Motors and Mahindra procurement teams remains undersupplied. Pursue direct e-commerce distribution to mid-tier injection molders seeking tailored lot sizes and technical service bypassing traditional distributor networks. For Investors and Strategic Acquirers: Capital is best deployed toward specialized nylon compounders with demonstrated electric powertrain thermal management formulation depth and captive customer qualification relationships. Long-term viability over the next decade hinges on positioning ahead of recycled-content mandate enforcement where mass balance accounting infrastructure remains immature. Watch for inflection signals around third-party certification standardization for chemically recycled caprolactam as the trigger for accelerated capacity consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration | Captive adipic acid supply secures margin stability against benzene volatility for German compounders. |
| Green Manufacturing Transition | Fermentation-derived caprolactam unlocks premium positioning under EU Green Deal procurement rules. |
| Long-term Supply Agreement | Multi-year contracts with Volkswagen and BMW procurement teams reduce qualification overhead. |
| Capacity Expansion | Engineering-grade resin additions in Gujarat and Maharashtra corridors capture India PLI scheme demand. |
| Joint Venture | Collaborative compounding partnerships with Yangtze River Delta producers optimize fiber-grade export economics. |
Research Methodology
Initial hypotheses were tested against primary input from caprolactam plant managers, automotive Tier 1 procurement leads, resin distribution channel partners, and technical R&D directors at compounders, then refined against customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up segment sizing triangulated with top-down market validation across grade tier, end-use industry, and regional production hub dimensions.
Variance decomposition across the modeling period isolates volume drivers from price-mix effects within automotive, electronics, and textile end-use segments. CAGRs were derived from segment-level growth trajectory analysis incorporating electric vehicle platform penetration rates, REACH SVHC compliance timelines, and MIIT new energy vehicle material specification adoption curves.
The analysis sits within stated boundaries; outcomes outside sustained benzene cost stability or accelerated ECHA authorization timelines would require recalibration. Forecasts reflect documented assumptions around caprolactam feedstock availability and OEM specification consolidation patterns. Practitioners should keep alternative scenarios live as EU F-Gas Regulation enforcement stringency and China dual carbon goal implementation pace evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Polymers & Resins
Global Acrylic Polymer Market
Polymers & Resins
Polymer Reinforcing Filler Market
Polymers & Resins
Polymer Memory Market
Polymers & Resins
Bio-Based and Synthetic Polyamide Market
Polymers & Resins
Calendering Resins Market
Polymers & Resins
Polymer Microspheres Market
Polymers & Resins
Global Vinyl Ester Market
Polymers & Resins
Polymer Excipients Market
Polymers & Resins
TPEE in Automotive Industry Market
Polymers & Resins
Polybutylene Succinate (PBS) Market
Polymers & Resins
Acrylic Styrene Acrylonitrile Resin Market
Polymers & Resins
Expanded Polypropylene Market
Polymers & Resins
ASEAN Superabsorbent Polymers (SAP) Market
Polymers & Resins
Middle East Polyamide Market
Polymers & Resins
Saturated Polyester Resin Market
Polymers & Resins
Expanded Polystyrene (EPS) Market