
 Bismuth Oxide Market | 2026-2036
Bismuth Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Bismuth Oxide Market Analysis
Aftermarket service revenue for high-purity bismuth oxide is tilting toward pharmaceutical and electronics customers who require certified batch documentation and technical support. 5N Plus leverages its vertical integration from metal refining to oxide production to sustain margin capture across the value chain. Shepherd Chemical anchors its position through specialized nanoparticle formulations that dominate North American coatings demand. Hunan Jinwang Bismuth Industry competes on manufacturing scale from its integrated smelting base in central China.
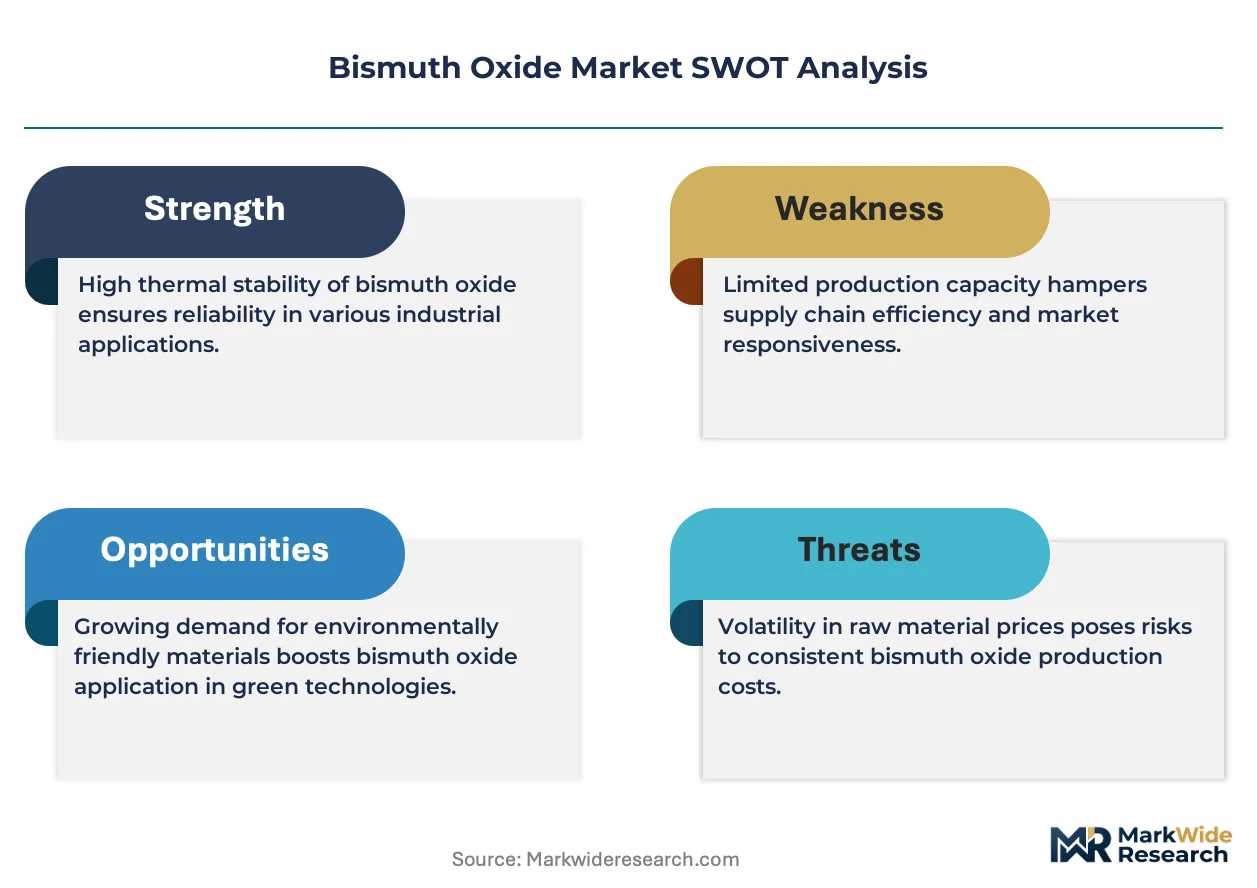
Bismuth oxide is a yellow crystalline powder with the chemical formula Bi₂O₃, existing primarily in alpha and beta polymorphs with melting points near 817°C, serving as a functional material in lead-free pigments, ceramic dielectrics, and catalytic systems. The powder segment occupies the largest volume share due to its versatility across industrial catalyst and pigment applications. Pharmaceutical-grade material is recording the fastest expansion as medical device manufacturers substitute bismuth oxide for lead-based radiation shielding under tightening toxic substance rules. Nanoparticle formulations concentrate margin pools in optical coatings and precision electronics where particle size distribution directly determines performance.
EPA oversight of heavy metal discharge limits shapes US-based oxide purification investments, while REACH restrictions on lead compounds redirect European coatings demand toward bismuth alternatives. China's SAMR enforces GB standards for electronic-grade materials that govern export qualification for domestic refiners. Stakeholders must monitor regulatory harmonization between EU Green Deal chemical phase-outs and emerging Asian green chemistry frameworks to anticipate supply chain qualification requirements.
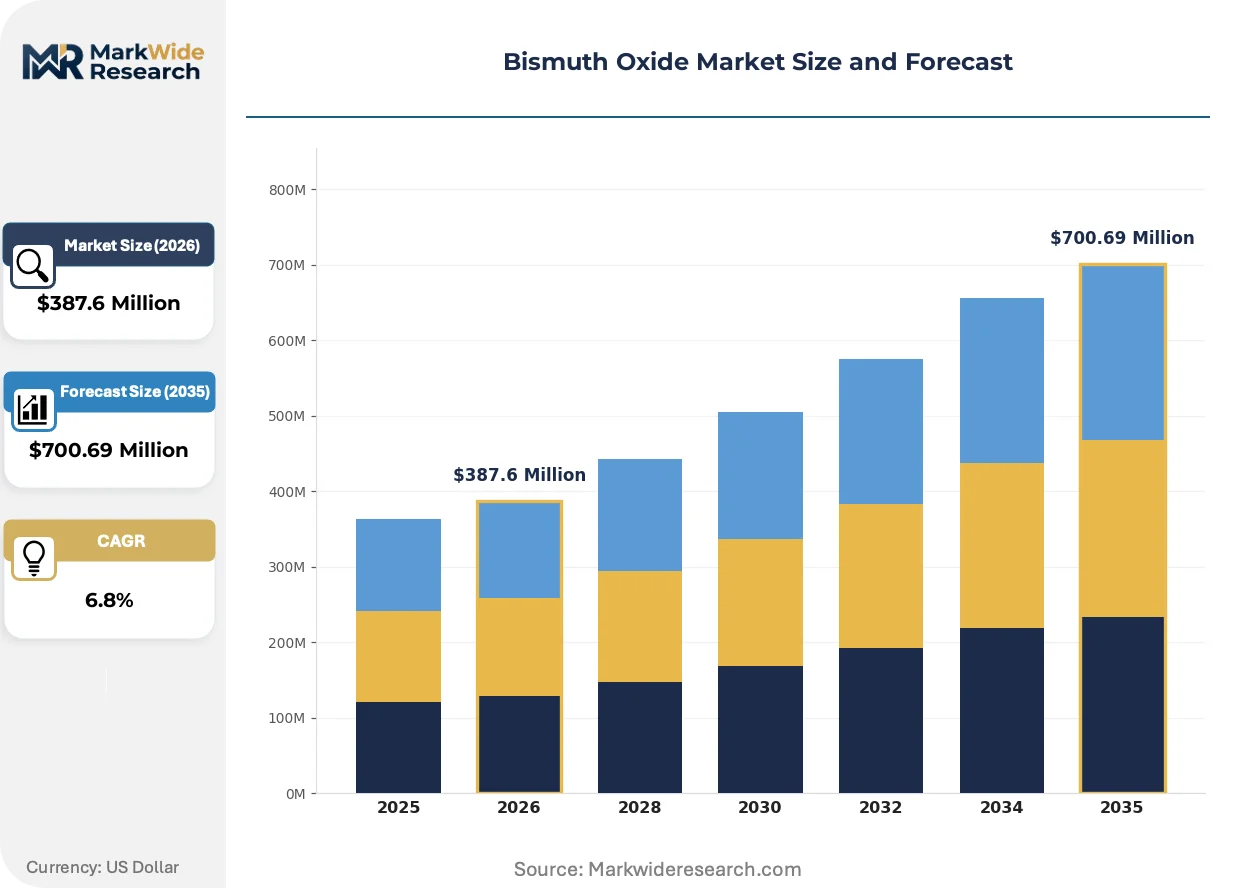
Market Dynamics
REACH and RoHS mandates across Europe and Asia are systematically stripping lead compounds from coatings and electronics, forcing manufacturers to qualify bismuth oxide as the primary functional substitute. This regulatory displacement is concentrating procurement leverage among refiners capable of pharmaceutical-grade certification.
Growth Catalysts
- RoHS Lead Substitution Mandates:European electronics manufacturers face binding restrictions on hexavalent chromium and lead compounds in electrical equipment, redirecting dielectric and solder formulations toward bismuth oxide alternatives.
- Medical Device Radiation Shielding:FDA and EMA scrutiny of lead leaching from implantable devices accelerates biocompatibility testing for bismuth-based shielding materials in diagnostic equipment housings.
- China's Electronic Manufacturing Clusters:Concentrated downstream demand from Shenzhen and Suzhou PCB fabricators creates captive consumption pull for high-purity oxide from Hunan refining bases.
Market Restraints
- Bismuth Metal Price Volatility:Supply tightness from Chinese smelter consolidation and byproduct recovery rates from lead-zinc mining creates input cost unpredictability for oxide converters.
- Single-Source Refining Concentration:Over 80 percent of global bismuth metal output originates from Chinese integrated lead smelters, exposing downstream oxide buyers to geopolitical supply disruption.
- Performance Gap in High-Temperature Solders:Bismuth oxide-modified formulations exhibit inferior thermal cycling reliability versus traditional lead-tin alloys in automotive underhood applications.
Strategic Opportunities
- India's PLI Scheme for Electronics:Production-linked incentives for semiconductor and component manufacturing in Gujarat and Tamil Nadu create virgin demand for electronic-grade oxide qualification.
- Nanoparticle Optical Coatings:Converging advances in sol-gel processing and thin-film deposition enable sub-100 nanometer oxide particles for anti-reflective lens applications.
- EU Green Deal Chemical Phase-Outs:The Chemicals Strategy for Sustainability designates lead chromate pigments for sunset review, opening decorative coatings to bismuth oxide substitution.
Industry Challenges
- Pharmaceutical GMP Certification Timelines:FDA and EMA validation of active pharmaceutical ingredient manufacturing sites for medical-grade oxide extends qualification cycles beyond 24 months.
- Analytical Chemist Shortage:Scarce expertise in ICP-MS trace metal analysis and polymorph characterization constrains batch certification throughput at specialty oxide producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bismuth Oxide Market |
| Market Size in 2026 | $387.6 Million |
| Market Size in 2035 | $700.69 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Powders, Crystals, Pellets End User: Pharmaceuticals, Electronics, Coatings, Ceramics Application: Medical Devices, Optical Devices, Pigments, Catalysts Grade: Industrial, Laboratory, Pharmaceutical, Technical |
| Companies Covered | 5N Plus, Shepherd Chemical, Hunan Jinwang Bismuth Industry, Xianyang Yuehua Bismuth, Beijing Easpring, Clark Manufacturing, Sichuan Shunda, Henan Maiteer, Shudu Nanomaterials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bismuth Oxide Market Emerging Trajectories
Formulation science and regulatory chemistry are converging to reposition bismuth oxide from commodity pigment feedstock to precision functional material. Three developments are restructuring competitive advantage.
Sol-gel derived bismuth oxide nanoparticles is hybridizing conventional powder synthesis with atomic-layer deposition techniques. Precision optics manufacturers in Germany and Japan are adopting these hybrid materials for ultraviolet-blocking coatings. The convergence is compressing qualification timelines for medical device applications while raising technical barriers for commodity producers.
REACH authorization requirements for lead compounds entered enforcement phase for chromate pigments and stabilizers. Coating formulators in Italy and Spain face mandatory substitution deadlines for architectural applications. The pressure is accelerating bismuth oxide qualification programs at automotive OEM paint shops.
Certification-driven procurement now dominates pharmaceutical and medical device channels. Buyers in Massachusetts and Bavaria require ISO 13485 quality system documentation and elemental impurity testing per ICH Q3D guidelines. The shift favors oxide suppliers with captive analytical laboratories over trading houses.
Bismuth Oxide Market Segmentation
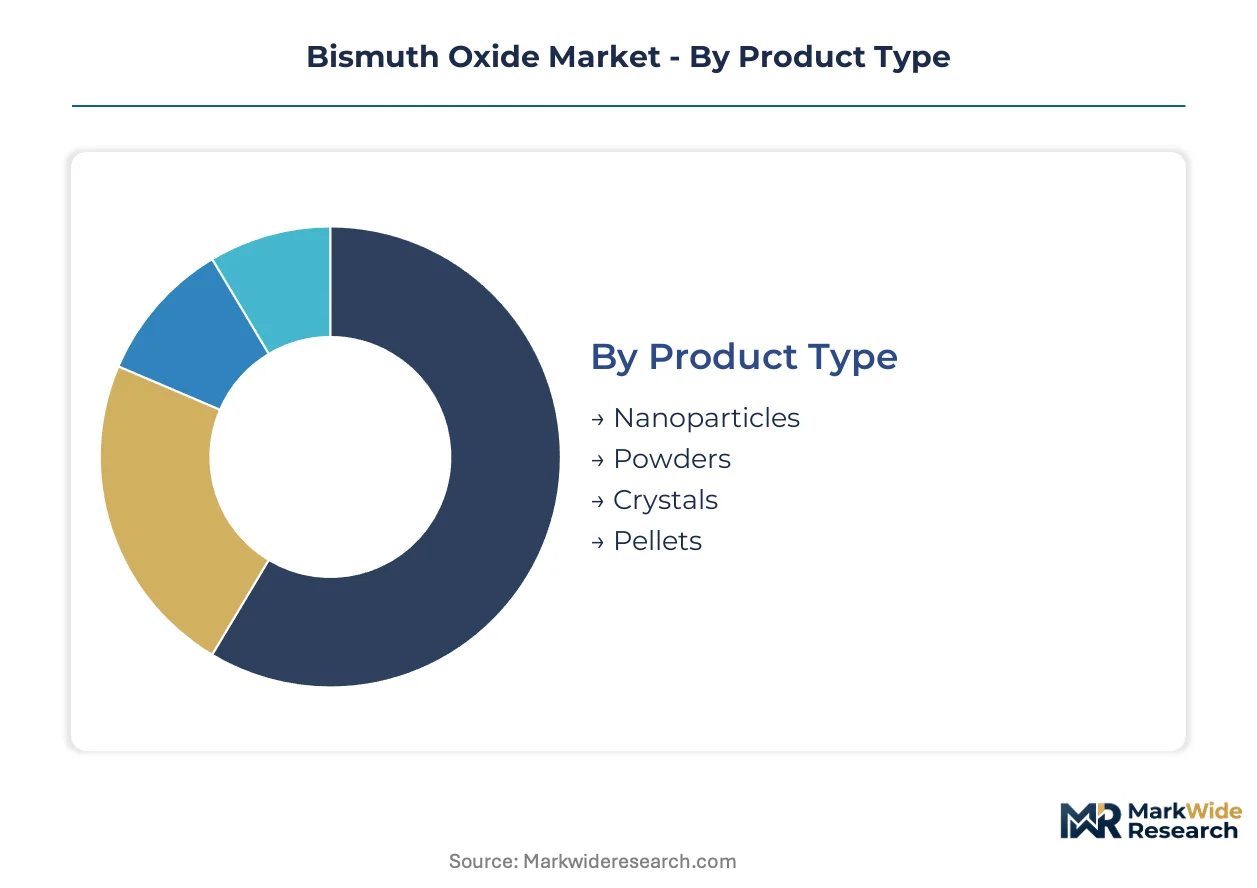
Bismuth oxide demand fragments across four distinct classification schemes. Each segmentation reveals divergent margin structures, certification requirements, and procurement patterns that shape supplier positioning.
Product Type:
Particle morphology spans four distinct formats serving divergent performance thresholds from bulk catalysis to atomic-layer deposition.
- Nanoparticles:Sub-100 nanometer particles synthesized via sol-gel or hydrothermal routes enable ultraviolet-blocking optical coatings and precision dielectric thin films. German and Japanese optics manufacturers in Jena and Osaka drive qualification programs for anti-reflective lens stacks.
- Powders:Conventional micron-grade material dominates catalyst and pigment feedstock demand. Chinese refiners in Hunan province supply multi-tonne batches to industrial formulators seeking cost-efficient lead substitution in ceramic dielectrics.
- Crystals:Single-crystal boules grown by Czochralski or Bridgman methods serve piezoelectric substrate applications.
- Pellets:Pressed and sintered forms optimize handling in vacuum deposition and thermal spray operations.
The dominant share belongs to powders, while nanoparticles are closing the gap fastest.
End User:
Customer archetypes separate by regulatory intensity and technical documentation burden.
- Pharmaceuticals:Medical device manufacturers and radiopharmaceutical compounders require ISO 13485 quality systems and ICH Q3D elemental impurity documentation. FDA and EMA validation cycles extend beyond 24 months for active pharmaceutical ingredient manufacturing sites.
- Electronics:PCB fabricators in Shenzhen and Suzuo clusters consume electronic-grade oxide for lead-free solder formulations and multilayer ceramic capacitors. SAMR GB standards govern export qualification from domestic refiners.
- Coatings:Architectural and automotive paint formulators substitute bismuth oxide for lead chromate pigments under EU Green Deal Chemicals Strategy phase-outs.
- Ceramics:Dielectric and structural ceramic producers leverage oxide fluxing properties in high-temperature processing.
Electronics commands the largest volume position, though pharmaceuticals exhibits the steepest expansion trajectory.
Application:
Functional use cases concentrate in four domains where oxide properties address specific technical gaps.
- Medical Devices:Radiation shielding housings for diagnostic equipment substitute bismuth oxide for lead to eliminate leaching risks under FDA biocompatibility scrutiny.
- Optical Devices:Precision lenses and filters exploit high refractive index and UV absorption in German and Japanese manufacturing clusters.
- Pigments:Yellow crystalline powder serves lead-free coloration in REACH-compliant European coatings.
- Catalysts:Selective oxidation and environmental remediation applications leverage redox-active surface chemistry.
Pigments retains the broadest installed base, while medical devices is gaining share fastest.
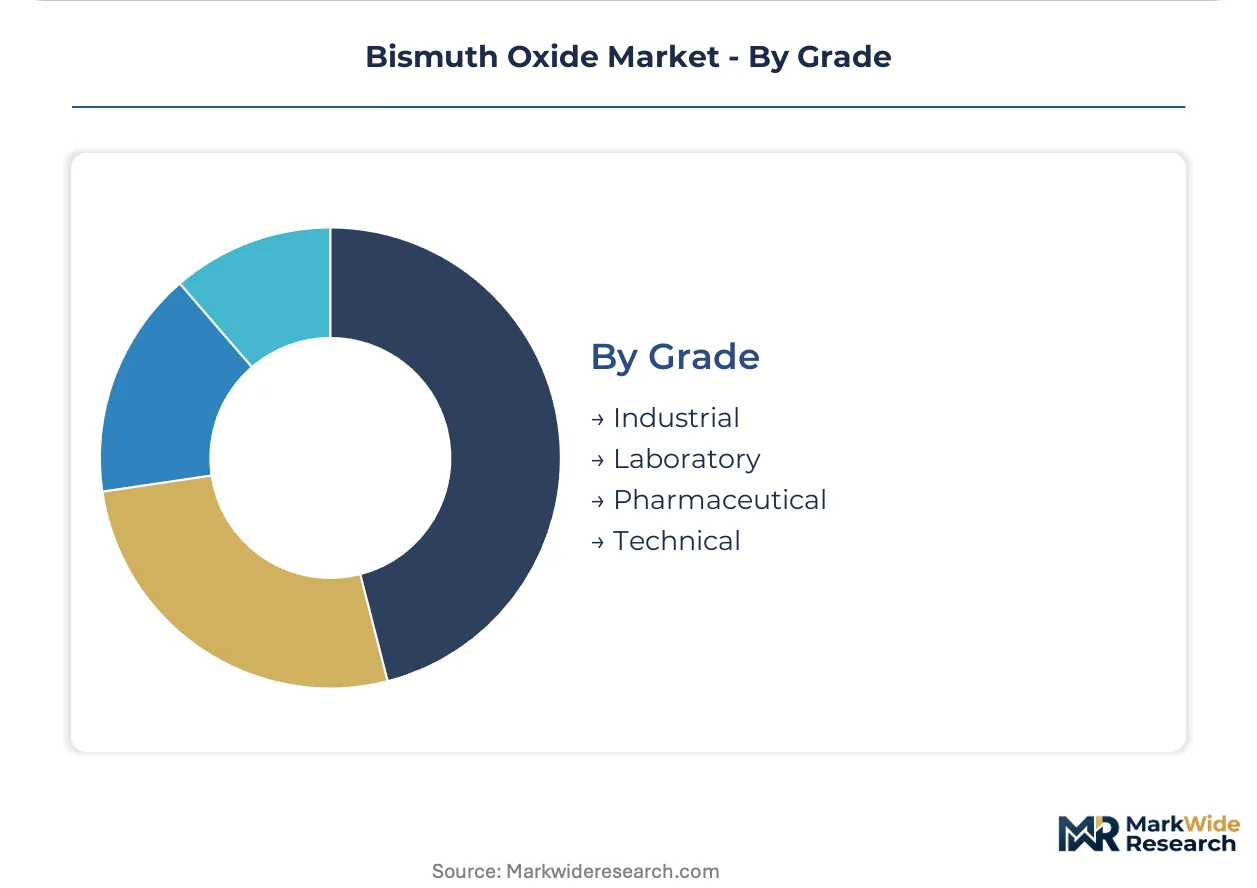
Grade:
Purity tiers stratify by analytical certification depth and trace metal specification stringency.
- Pharmaceutical:99.99%+ purity with full ICP-MS trace metal reporting and polymorph characterization satisfies FDA and EMA active pharmaceutical ingredient requirements.
- Technical:99.9% purity with controlled impurity profiles serves electronics and advanced ceramics where performance depends on consistent stoichiometry.
- Industrial:Standard purity grades meet bulk catalyst and pigment volume demand with minimal certification overhead.
- Laboratory:Research-scale quantities support analytical method development and materials science investigation.
Industrial grade holds the volume lead, while pharmaceutical grade is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese smelters control over four-fifths of global bismuth metal output, creating downstream oxide supply dependencies across electronics and pharmaceutical channels worldwide. This concentration shapes procurement risk profiles for manufacturers in Germany, Japan, and the United States.
China
Hunan province hosts integrated lead-zinc smelters that feed bismuth oxide refineries serving Shenzhen and Suzhou PCB clusters. SAMR enforces GB standards for electronic-grade materials that govern export qualification. Central Chinese refining bases capture margin through captive consumption in downstream multilayer ceramic capacitor manufacturing.
United States
Medical device manufacturers in Massachusetts and Minnesota drive pharmaceutical-grade oxide demand for radiation shielding applications. EPA oversight of heavy metal discharge limits shapes domestic purification investments. Aftermarket technical support concentrates near Boston and Minneapolis analytical service hubs.
Germany
Precision optics manufacturers in Jena and Munich qualify sol-gel derived nanoparticles for ultraviolet-blocking lens coatings. ECHA REACH restrictions on lead chromate pigments redirect architectural coatings demand toward bismuth alternatives. Automotive OEM paint shops in Bavaria accelerate substitution timelines under EU Green Deal Chemicals Strategy enforcement.
Japan
Osaka-based electronics fabricators consume high-purity oxide for lead-free solder formulations in automotive underhood applications. METI industrial standards govern material specifications for domestic multilayer ceramic capacitor production. Kyushu semiconductor packaging clusters create specialized demand for sub-100 nanometer particle formulations.
India
Gujarat and Tamil Nadu electronics manufacturing zones emerge as virgin demand centers under PLI scheme incentives for semiconductor components. CDSCO pharmaceutical regulations govern medical device material qualifications. Domestic refiners in Rajasthan and Jharkhand expand byproduct bismuth recovery from lead-zinc operations.
Bismuth Oxide Market Vendor Landscape
Vertically integrated metal refiners and specialized oxide formulators split the market between scale-driven commodity supply and certification-intensive specialty grades. The vendor base concentrates around Chinese integrated smelters with captive oxide conversion, North American technical specialists with analytical laboratories, and European nanoparticle innovators with sol-gel processing capabilities. Strategic moves center on backward integration into bismuth metal sourcing and forward integration into pharmaceutical GMP certification.
Among North American specialists, 5N Plus and Shepherd Chemical exemplify divergent archetypes. 5N Plus occupies a position spanning metal refining through oxide production with captive supply chain control. Shepherd Chemical anchors the formulation-specialist tier through nanoparticle expertise serving coatings demand. Chinese scale players including Hunan Jinwang Bismuth Industry represent the integrated smelter archetype with manufacturing concentration in central refining bases.
| Leading Market Players |
|---|
| 5N Plus |
| Shepherd Chemical |
| Hunan Jinwang Bismuth Industry |
| Xianyang Yuehua Bismuth |
| Beijing Easpring |
| Clark Manufacturing |
| Sichuan Shunda |
| Henan Maiteer |
| Shudu Nanomaterials |
| Others |
Supply Flow & Price Mechanics
Chinese integrated lead-zinc smelters in Hunan province anchor upstream bismuth metal supply, concentrating margin capture downstream among pharmaceutical-grade oxide converters with captive analytical laboratories and ISO 13485 certification. This upstream-downstream asymmetry forces commodity powder suppliers into volume-based competition while nanoparticle specialists command premium positioning through sol-gel processing expertise.
Pricing Analysis
Aftermarket service revenue from certified batch documentation and technical support drives lifetime value more than base material sales. Three-tier pricing structure across pharmaceutical, technical, and industrial grades reflects ICP-MS trace metal reporting depth and polymorph characterization rigor. Cost compression in industrial-grade powders intensifies because Chinese smelter consolidation limits spot market liquidity. Pharmaceutical buyers in Massachusetts and Bavaria exhibit lowest price sensitivity due to FDA and EMA validation lock-in, while ceramic pigment formulators face acute margin pressure from substitute mineral fluxes.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk calculus for oxide converters dependent on Hunan refining bases. Geographic supply concentration centers on China, with secondary nodes in Vietnam and Mexico for tariff-advantaged oxide finishing. Raw material dependencies draw from lead-zinc mining byproduct recovery, sulfuric acid leaching inputs, and high-purity precipitation reagents. Single-source vulnerability from over 80 percent Chinese metal origination exposes downstream buyers to SAMR export license unpredictability. Distribution runs through direct mill relationships for electronic-grade oxide to Shenzhen PCB fabricators, with specialized distributors handling pharmaceutical certification documentation in Europe and North America.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technical service contracts and analytical certification subscriptions expand faster than base oxide tonnage, reframing this market as a service-attach opportunity where GMP documentation and ICH Q3D compliance support command recurring revenue streams.
For Market Incumbents: Entrench pharmaceutical-grade positioning by deepening backward integration into bismuth metal sourcing and expanding captive ICP-MS laboratory capacity in Bavaria and Massachusetts. Counter nanoparticle specialists in Jena and Osaka through joint development programs with precision optics manufacturers. Certification investment remains the critical defensive lever as FDA validation timelines extend beyond 24 months. For New Entrants and Emerging Players: Establish a beachhead in India's Gujarat semiconductor packaging clusters under PLI scheme incentives before domestic Rajasthan refiners achieve electronic-grade purity. Target medical device radiation shielding applications where biocompatibility testing requirements create qualification barriers for commodity suppliers. Go-to-market leverage rests on partnerships with Massachusetts analytical service hubs for ISO 13485 documentation. For Investors and Strategic Acquirers: Secondary-cycle assets sit with North American nanoparticle formulators possessing sol-gel processing IP and pharmaceutical GMP certifications. Five-to-ten-year viability hinges on REACH authorization enforcement accelerating lead chromate substitution in European architectural coatings. Watch ECHA sunset review timelines for lead pigment phase-outs as the definitive demand inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bismuth Metal Refining | Hunan smelter acquisition secures captive supply for pharmaceutical-grade oxide converters facing Chinese export license volatility. |
| GMP Certification Laboratory Expansion | Massachusetts analytical hub addition accelerates FDA validation throughput for medical device radiation shielding qualifications. |
| Nanoparticle Sol-Gel Processing Scale-Up | Jena precision optics partnerships leverage sub-100 nanometer UV-blocking coatings for German lens manufacturers. |
| Long-Term Supply Agreement with Shenzhen PCB Clusters | Suzhou multilayer ceramic capacitor fabricators provide captive consumption anchor for electronic-grade oxide volume. |
| Joint Venture with Indian Domestic Refiners | Rajasthan lead-zinc byproduct recovery integration addresses PLI scheme demand in Gujarat semiconductor zones. |
Methodological Framework
Two parallel data streams informed the analysis: primary field engagement with oxide plant managers, pharmaceutical procurement leads, medical device regulatory affairs directors, and precision optics R&D heads; and secondary validation through SAMR GB standard filings, ECHA REACH authorization databases, SEC 10-K chemical segment disclosures, and customs trade flow records. Bottom-up capacity modeling from Hunan refining bases was triangulated against top-down demand estimates from Shenzhen electronics clusters and Massachusetts medical device manufacturers.
Forecast inputs span grade tier stratification, end-use industry regulatory intensity, particle morphology performance premiums, and regional production hub concentration across the projection horizon. CAGRs were derived from segment-level volume elasticity modeling against RoHS enforcement timelines and pharmaceutical GMP certification adoption curves. Specific forecast inputs include lead-zinc mining byproduct recovery rates and sol-gel nanoparticle qualification velocity in German and Japanese optics channels.
Stress conditions across bismuth metal price volatility bands, Chinese smelter consolidation scenarios, and REACH authorization enforcement delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory harmonization between EU Green Deal phase-outs and emerging Asian green chemistry frameworks. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Metals
Finished Steel Products Market
Metals
Metal Recycling Market
Metals
GCC Aluminium Powder Market
Metals
India Metal Fabrication Market
Metals
Japan Aluminium Powder Market
Metals
Metal Alloys Market
Metals
Aluminium Conductors Market
Metals
Ferro Vanadium Market
Metals
US and Mexico Stainless Steel Market
Metals
Molybdenum Market
Metals
Metallurgical Coal Market
Metals
Rhodium Market
Metals
Zinc Dust Market
Metals
Gold Smelting Market
Metals
Silver Cyanide Market
Metals
Beryllium Copper Plate Market