
 United Kingdom Plastic Bottles Market | 2026-2036
United Kingdom Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Plastic Bottles Market Insights
A capital-intensity divergence between blow-molding equipment portfolios is reorganizing competitive tiers across the United Kingdom plastic bottles landscape. Amcor Group GmbH leverages integrated resin-to-bottle operations across multiple UK sites. Berry Global Inc. anchors its position through high-volume PET preform capacity serving beverage clients. Robinson plc differentiates via specialized pharmaceutical-grade barrier bottles.
United Kingdom plastic bottles are hollow thermoplastic containers manufactured through extrusion or injection-stretch blow molding, typically ranging from 10 milliliters to 20 liters in capacity, with PET grades offering clarity and carbonation barrier properties for carbonated drinks and personal care formulations. PET beverage packaging commands the largest volume share due to water and soft drink bottler procurement scale, while pharmaceutical-grade HDPE bottles capture disproportionate margin pools through stringent extractables testing and child-resistant closure compatibility. Cosmetic bottling applications in LDPE and PETG variants are gaining traction among personal care brands seeking squeezable formats and premium decoration surfaces.
The UK's Plastic Packaging Tax, enforced by HM Revenue and Customs, mandates minimum 30 percent recycled content thresholds and is redirecting converter capital toward rPET flake washing and decontamination infrastructure. British Standards Institution specifications for food-contact plastics, alongside Environment Agency waste tracking protocols, shape material certification burdens and supplier qualification timelines. Stakeholders must monitor evolving extended producer responsibility fee structures and recycled content verification mechanisms to secure long-term supply agreements with major FMCG procurement teams.
Market Dynamics
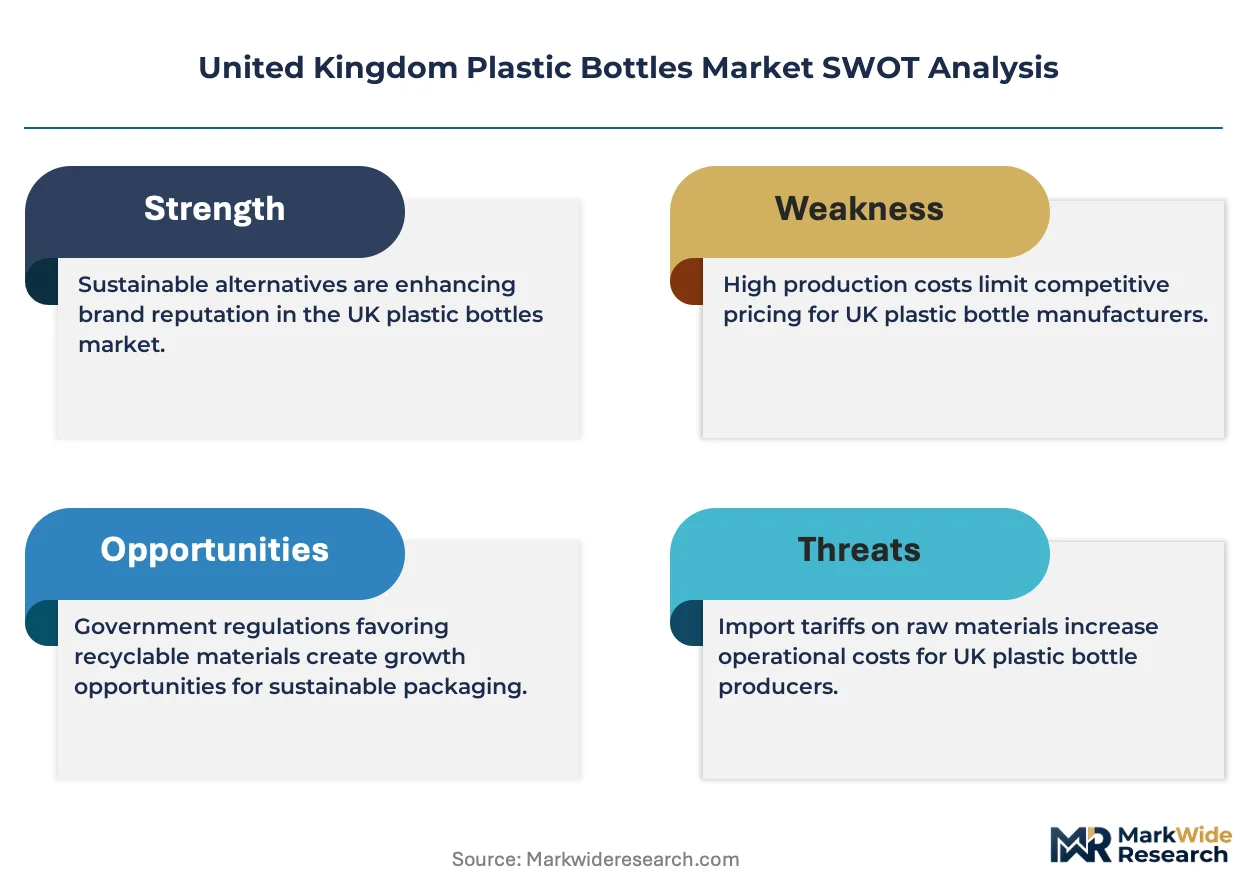
The United Kingdom Plastic Packaging Tax is compressing converter margins while simultaneously redirecting capital toward rPET infrastructure, creating a bifurcation between recyclers with decontamination capabilities and commodity blow-molders.
Growth Catalysts
- Ready-to-drink beverage proliferation:Bottled water and functional drink brands are lifting PET preform orders across the Midlands manufacturing corridor.
- HM Revenue and Customs recycled content mandates:The 30 percent threshold is forcing brand owners to secure long-term rPET supply agreements.
- Lightweighting technologies:Advanced stretch blow-molding processes are reducing gram weights per bottle without compromising carbonation barrier performance.
Market Restraints
- rPET flake supply concentration:Domestic collection infrastructure lags processing capacity, creating feedstock bottlenecks for converters.
- Energy cost volatility:Natural gas price swings directly impact extrusion and blow-molding operational expenditures.
- Mechanical recycling limitations:Contamination sensitivity restricts food-contact applications for certain post-consumer waste streams.
Strategic Opportunities
- Pharmaceutical barrier bottles:Extractables-tested HDPE formats command premium positioning in oncology and biologics packaging.
- Chemical recycling partnerships:Pyrolysis and glycolysis investments could unlock food-grade rPET beyond mechanical processing limits.
- Scottish and Northern Irish manufacturing expansion:Underutilized industrial zones offer lower utility costs and proximity to North Sea logistics.
Industry Challenges
- Food-contact certification timelines:British Standards Institution approval cycles for novel barrier layers extend supplier qualification periods.
- Legacy blow-molding asset retrofitting:Existing equipment requires substantial modification to process high-percentage recycled content without quality degradation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Plastic Bottles Market |
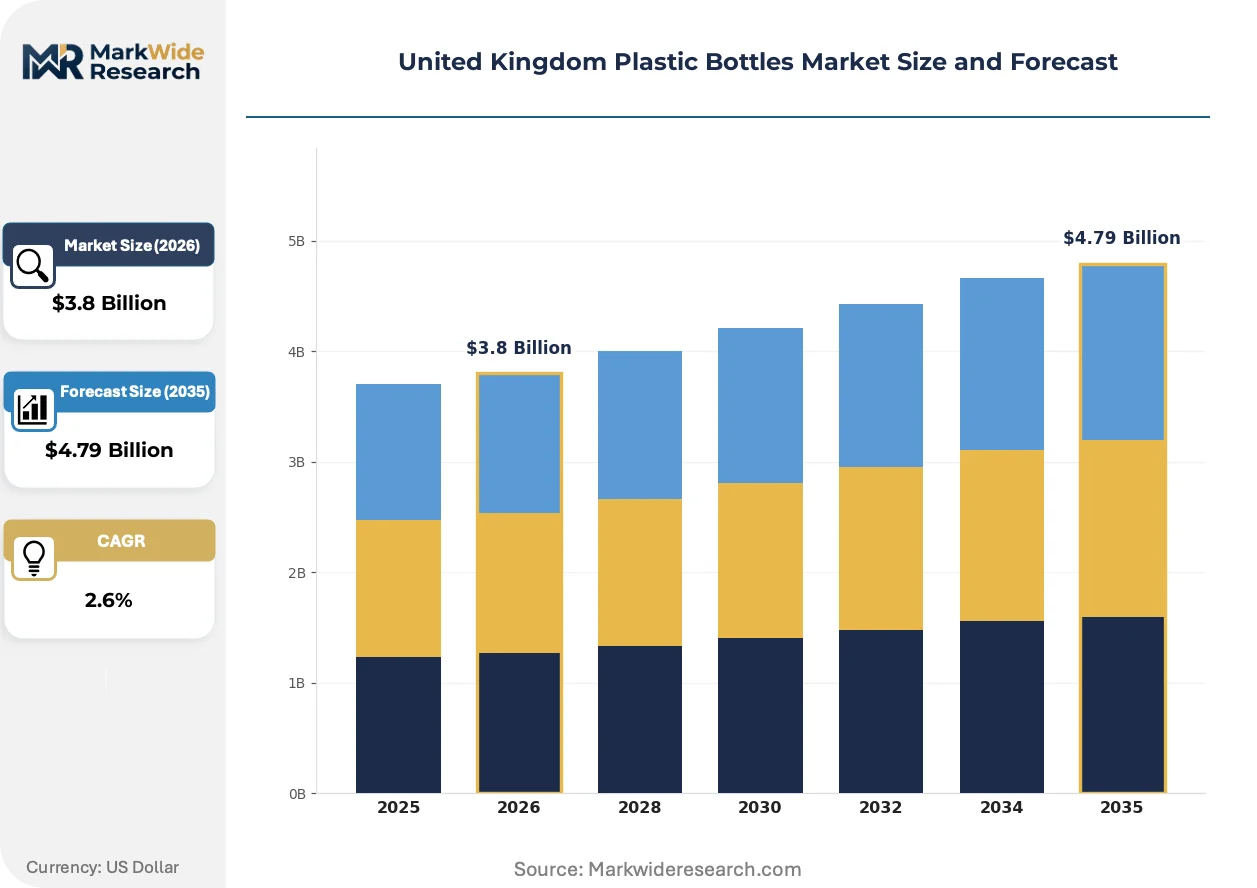
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $4.79 Billion |
| CAGR (2026 – 2036) | 2.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC End User: Food & Beverage, Personal Care, Household, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesalers Application: Beverage Packaging, Cosmetic Bottling, Household Products, Industrial Uses |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., Aptar Group Inc., Esterform Packaging, Coda Plastics Ltd., Berlin Packaging UK, Robinson plc, Cambrian Packaging, Fernhill Packaging Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Plastic Bottles Market Trends and Innovations
Active investment patterns across the United Kingdom plastic bottles sector reveal three converging forces: material substitution economics, regulatory compliance automation, and buyer consolidation effects on contract structures.
Advanced rPET decontamination systems are supplanting conventional flake washing in converter facilities serving major beverage brands. Coca-Cola Europacific Partners and other bottlers are mandating super-clean processing certifications for supply base retention. This technology shift is compressing margins for mid-tier recyclers lacking capital-intensive solid-state polymerization capabilities.
HM Revenue and Customs has tightened recycled content verification protocols, requiring mass-balance documentation across converter supply chains. The Environment Agency's waste tracking mandates are extending compliance burdens to smaller blow-molders. Pharmaceutical and food-contact segments are responding fastest, deploying blockchain-based provenance systems to satisfy audit requirements.
Buyer concentration among multinational FMCG procurement teams is compressing contract renewal cycles and unbundling tooling investments from unit pricing. Major retailers are consolidating bottle specifications to reduce SKU complexity. This pattern is most visible in England's Greater London corridor, where Sainsbury's and Tesco packaging specifications increasingly dictate converter production schedules.
United Kingdom Plastic Bottles Market Segmentation
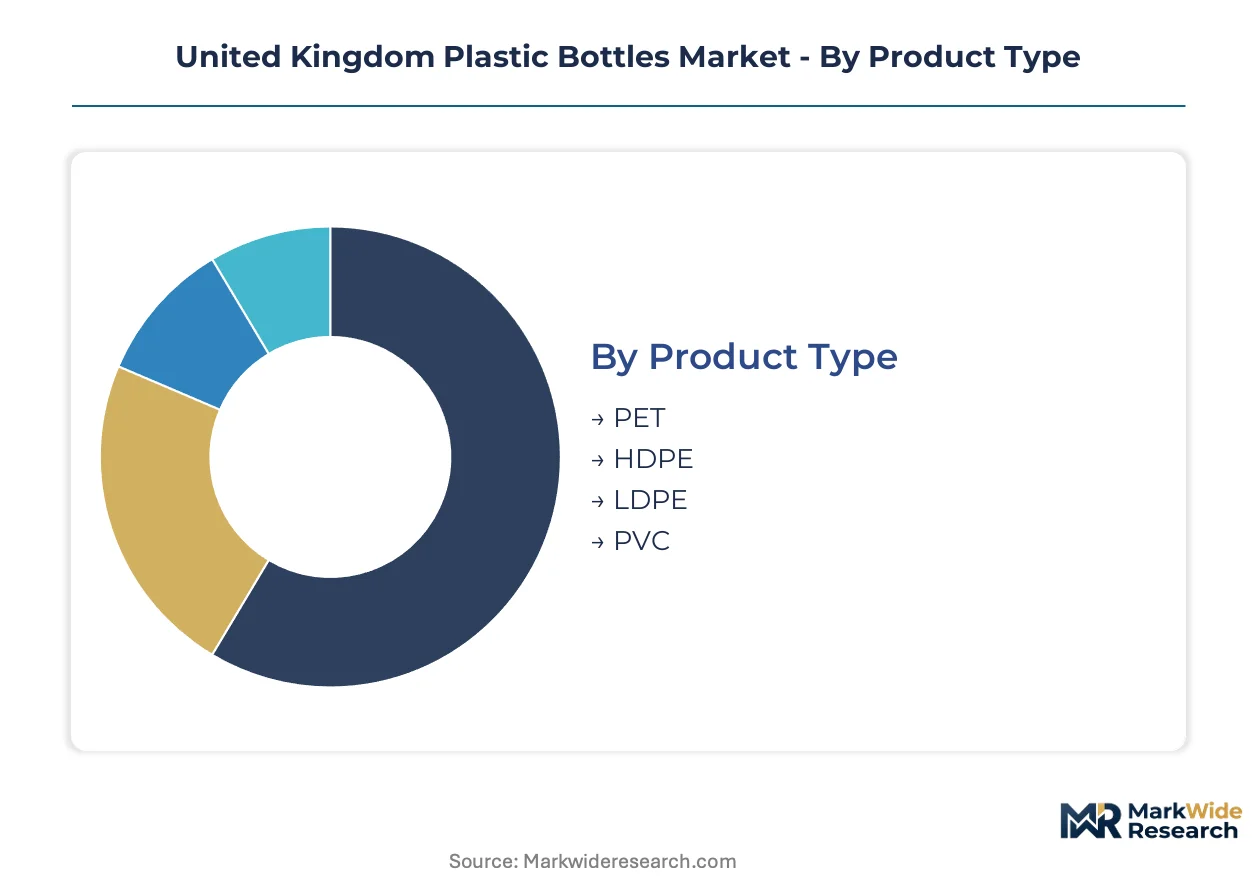
Segmentation of the United Kingdom plastic bottles market reveals how material chemistry, end-use specifications, and channel economics partition margin capture. HM Revenue and Customs recycled content mandates are compressing commodity grades while amplifying value in certified barrier formats.
Product Type:
Premium margin pools concentrate in barrier-grade PET and pharmaceutical-compliant HDPE, where certification burdens filter out commodity converters.
- PET:Injection-stretch blow-molded grades deliver clarity and carbonation barrier for beverage applications. Water and soft drink bottlers across England's Midlands corridor are lifting preform orders as lightweighting investments reduce gram weights. HM Revenue and Customs 30 percent recycled content thresholds are redirecting capital toward rPET decontamination infrastructure.
- HDPE:Extrusion blow-molded formats offer chemical resistance and child-resistant closure compatibility. Pharmaceutical-grade specifications in oncology and biologics packaging command disproportionate margin pools through British Standards Institution extractables testing protocols. The material dominates household and industrial chemical containment.
- LDPE:Squeezable formats serve personal care applications requiring soft-touch dispensing. Cosmetic brands specify LDPE for travel-size and sample packaging where flexibility trumps barrier performance.
- PVC:Rigid clarity applications persist in niche pharmaceutical blister packaging and certain chemical storage. Environmental scrutiny under extended producer responsibility frameworks is compressing deployment in food-contact applications.
PET holds installed capacity across multiple UK converter sites. HDPE is rotating up the share rankings in pharmaceutical barrier segments.
End User:
Volume concentration diverges sharply from value capture, with beverage procurement scale masking thinner margins than pharmaceutical qualification timelines generate.
- Food & Beverage:Carbonated drinks, bottled water, and ready-to-drink functional beverages drive PET preform demand at scale. Coca-Cola Europacific Partners and other major bottlers are consolidating supplier bases around super-clean rPET certification capabilities.
- Personal Care:Shampoo, conditioner, and body wash brands specify squeezable HDPE and PETG formats with premium decoration surfaces. Greater London procurement teams are unbundling tooling investments from unit pricing in contract renegotiations.
- Household:Cleaning product and laundry detergent packaging favors HDPE for chemical compatibility. Retailer consolidation of bottle specifications at Sainsbury's and Tesco is reducing SKU complexity across this segment.
- Pharmaceuticals:Extractables-tested HDPE bottles for oral solids and barrier PET for liquid formulations capture the steepest margin trajectories. British Standards Institution approval cycles extend supplier qualification periods, entrenching incumbent positions.
Food & Beverage anchors volume procurement. Pharmaceuticals is climbing the fastest in margin contribution per liter.
Distribution Channel:
Channel economics fragment around lot size flexibility, with direct-to-manufacturer contracts compressing wholesaler intermediation in high-volume beverage supply.
- Online Retail:E-commerce direct-to-consumer shipments of personal care and household samples are gaining traction. Amazon and Ocado specifications are shaping secondary packaging requirements for bottle protection.
- Supermarkets:Tesco, Sainsbury's, and Asda dominate procurement volume, consolidating specifications to reduce converter changeover costs. Private label bottled water and soft drinks drive PET bottle demand through this channel.
- Convenience Stores:Smaller lot sizes and regional distribution patterns favor local blow-molders with flexible production scheduling. The channel captures impulse beverage purchases and travel-size personal care.
- Wholesalers:Cash-and-carry and foodservice distribution serve independent retailers and hospitality. Bulk packaging of condiments and cooking oils in HDPE jerrycans persists through this channel.
Supermarkets hold installed capacity in beverage supply chain integration. Online Retail is rotating up the share rankings in personal care sample formats.
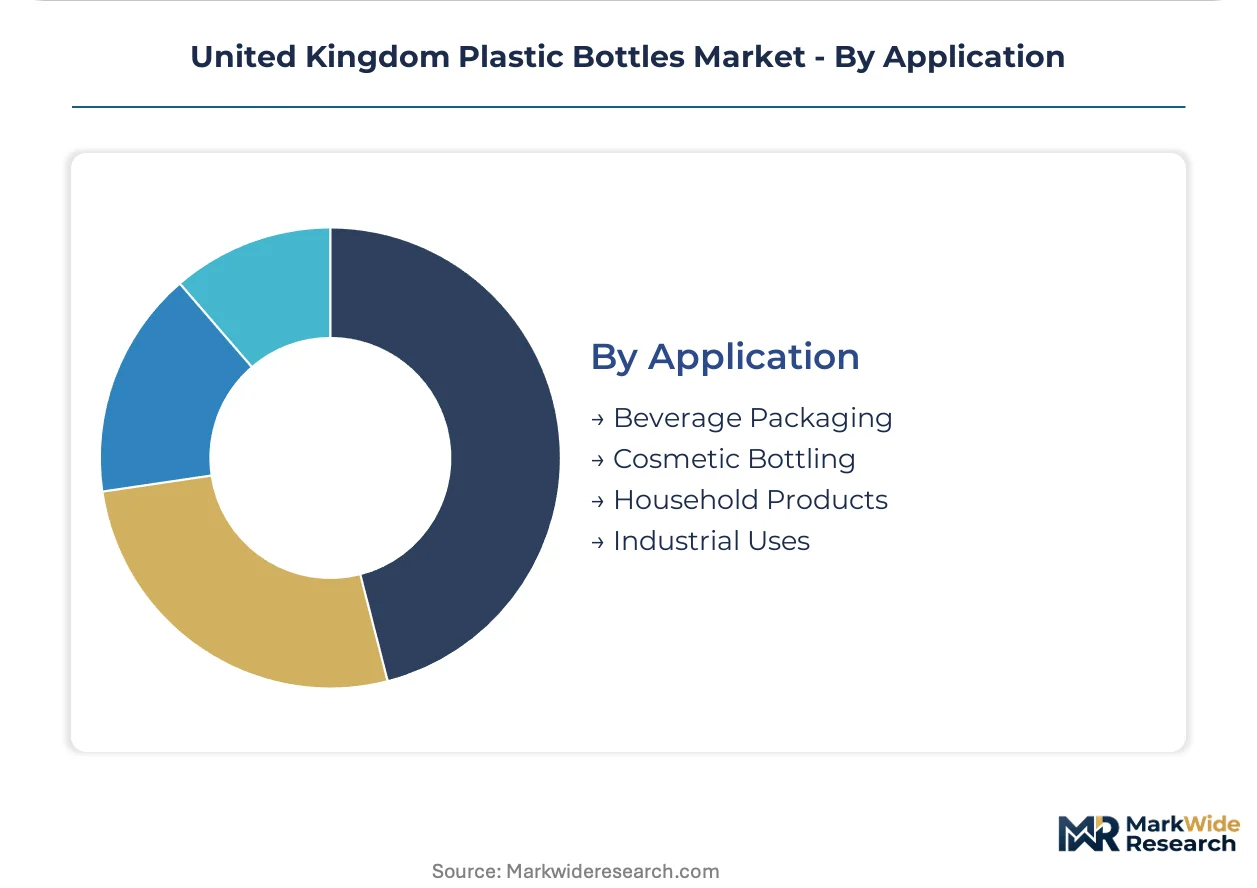
Application:
Barrier performance requirements and decoration sophistication create tiered margin structures, with industrial applications trading specification intensity for volume scale.
- Beverage Packaging:Carbonated soft drinks, bottled water, and functional beverages demand PET clarity and carbonation retention. Lightweighting technologies are reducing material throughput per bottle without compromising barrier performance.
- Cosmetic Bottling:Premium skincare and fragrance applications specify PETG clarity and LDPE squeezability. Decoration investments in silk-screening and metallization support brand differentiation in Greater London brand headquarters corridors.
- Household Products:Cleaning chemicals and laundry detergents require HDPE chemical resistance and child-resistant closure compatibility. Concentrate and refill formats are reshaping bottle size specifications.
- Industrial Uses:Adhesives, lubricants, and agricultural chemical containment favor HDPE durability and UN certification for hazardous materials. Scottish and Northern Irish manufacturing zones offer lower utility costs for this volume-driven segment.
Beverage Packaging holds installed capacity across Midlands converter corridors. Cosmetic Bottling is rotating up the share rankings in premium personal care brand procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Beverage bottlers in Greater London and the Midlands show the least price elasticity, absorbing rPET premiums to meet HM Revenue and Customs mandates. Industrial chemical buyers in Northern England and Scotland remain highly price-sensitive, favoring virgin HDPE over recycled alternatives.
London and the Southeast
Coca-Cola Europacific Partners and major soft drink bottlers drive PET preform demand across Greater London distribution hubs. HM Revenue and Customs recycled content verification protocols concentrate compliance investment in this corridor. Premium cosmetic brands in Mayfair and Chelsea specify PETG bottles with metallized decoration, supporting converter margins.
Midlands Manufacturing Corridor
Water bottlers and functional drink producers anchor injection-stretch blow-molding capacity across Birmingham and Leicester industrial zones. The Environment Agency's waste tracking mandates shape supplier qualification timelines for food-contact applications. Berry Global Inc. maintains high-volume preform operations serving national beverage distribution.
North England
Household chemical and cleaning product manufacturers favor HDPE formats for cost efficiency in Manchester and Leeds production basins. Extended producer responsibility fee structures under review by HM Treasury are delaying capital commitments. Local blow-molders serving cash-and-carry wholesalers compete on lot-size flexibility rather than recycled content certification.
Scotland
Whisky and spirits bottlers sustain specialized glass-to-plastic substitution trials in Glasgow and Edinburgh packaging facilities. Scottish Government circular economy targets run ahead of UK-wide mandates, accelerating rPET collection infrastructure investment. North Sea logistics connectivity offers export advantages for industrial chemical packaging.
Wales and Northern Ireland
Underutilized industrial zones in Wrexham and Belfast attract lightweighting equipment investments seeking lower utility costs. The Welsh Government's plastics roadmap and Northern Ireland Department for Agriculture, Environment and Rural Affairs protocols create divergent compliance landscapes. Regional blow-molders focus on short-run personal care formats for independent retailers.
United Kingdom Plastic Bottles Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the United Kingdom plastic bottles landscape. Integrated resin-to-bottle operators command supply security advantages, while specialized barrier converters capture certification-driven premiums. Three archetypes dominate: multinational packaging conglomerates with UK manufacturing footprints, mid-cap converters with pharmaceutical-grade capabilities, and regional blow-molders serving flexible lot-size requirements. Competitive moves center on rPET decontamination capacity additions and strategic partnerships with major beverage bottlers.
Within the multinational tier, Amcor Group GmbH and Berry Global Inc. exemplify scale-driven positioning across multiple UK sites. Robinson plc occupies a specialist position in pharmaceutical-grade barrier formats. These three anchors represent divergent strategic bets: integrated operations, high-volume beverage supply, and extractables-tested premium positioning.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| Aptar Group Inc. |
| Esterform Packaging |
| Coda Plastics Ltd. |
| Berlin Packaging UK |
| Robinson plc |
| Cambrian Packaging |
| Fernhill Packaging Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day rPET flake inventory cycles across Midlands converter sites concentrate pricing power with decontamination-capable recyclers while squeezing commodity blow-molders unable to pass HM Revenue and Customs compliance costs downstream. This lead-time asymmetry between certified and uncertified supply tiers is restructuring contract negotiations across England's beverage packaging corridor.
Pricing Analysis
After-sales revenue from technical service contracts and barrier-layer recertification drives lifetime value for pharmaceutical-grade converters. Three-tier pricing structure across premium, standard, and economy levels separates extractables-tested oncology bottles from commodity food-contact grades. Cost compression in standard-tier PET is intensifying because virgin resin price volatility outpaces rPET premium absorption. Beverage bottlers in Greater London show least price sensitivity, while industrial chemical buyers in Northern England remain highly price-sensitive.
Supply Chain Analysis
Strait of Dover transit bottlenecks for rPET flake imports from continental European recyclers concentrate feedstock risk for UK converters lacking domestic washing capacity. Supply draws from Germany, Netherlands, and Belgium for food-grade flake, while pharmaceutical resin sources from Saudi Arabia and South Korea. Single-source vulnerability runs through super-clean decontamination equipment providers. Distribution runs through direct-to-manufacturer contracts for beverage volume, with wholesaler intermediation persisting in personal care short-runs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-economics inflection is accelerating as blockchain-based provenance systems create interoperability between HM Revenue and Customs verification protocols and major FMCG procurement platforms.
For Market Incumbents: Secure backward integration into rPET flake washing infrastructure to defend against commodity blow-molder margin erosion. Anchor capacity expansion in Scottish and Northern Irish zones where utility costs undercut Midlands operations. Entrench pharmaceutical barrier positions through British Standards Institution certification fast-tracks that extend incumbent qualification timelines. For New Entrants and Emerging Players: British Standards Institution extractables fast-track for oncology packaging opens white-space in pharmaceutical-grade HDPE where incumbent capacity constraints create supply gaps. Target underpenetrated convenience store channel for flexible lot-size production. Lead with chemical recycling partnerships as differentiated go-to-market angle beyond mechanical rPET limitations. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational packaging conglomerates divesting non-core UK blow-molding assets amid rPET capital intensity pressures. Long-term viability favors converters with decontamination capabilities and pharmaceutical certification moats. Watch rPET collection infrastructure build-out rates as inflection indicator for feedstock security premiums.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Decontamination Capacity Addition | Super-clean certification unlocks Coca-Cola Europacific Partners supply base retention. |
| Backward Integration into Flake Washing | Captive rPET supply hedges HM Revenue and Customs compliance cost volatility. |
| Pharmaceutical Barrier Certification Investment | British Standards Institution approval extends incumbent positioning in oncology packaging. |
| Scottish Manufacturing Footprint Expansion | North Sea logistics and lower utility costs improve industrial chemical segment margins. |
| Chemical Recycling Partnership Formation | Pyrolysis alliances bypass mechanical recycling limits for food-grade rPET supply. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of HM Revenue and Customs regulatory filings, Environment Agency waste tracking data, and British Standards Institution certification records. Primary interviews engaged blow-molding plant managers, procurement leads at beverage bottlers, pharmaceutical packaging engineers, and rPET recycler technical directors. Secondary validation drew from converter SEC disclosures, trade customs data, and FMCG sustainability reports. Bottom-up capacity assessments triangulate against top-down demand modeling across material grades and end-use segments.
Segmentation dimensions modeled span material chemistry, end-use application, and regional manufacturing corridor. Volume and value trajectories across the projection horizon integrate lightweighting technology adoption curves, recycled content mandate compliance timelines, and pharmaceutical qualification cycle durations. CAGRs derive from installed capacity utilization rates and capital expenditure announcements by major converters.
Underlying assumptions cover HM Revenue and Customs recycled content threshold stability and rPET collection infrastructure build-out pace, with deviation risk concentrated in energy cost volatility and chemical recycling technology maturation timelines. Practitioners should keep alternative scenarios live as extended producer responsibility fee structures evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Plastic Keg Market
Plastic Packaging
Thailand Plastic Bottles Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
North America Single-Use Plastic Packaging Market
Plastic Packaging
Asia Pacific Single-Use Plastic Packaging Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Russia Plastic Packaging Market
Plastic Packaging
Global Micro Injection Molded Plastic Market
Plastic Packaging
Mushroom Plastics Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
France Plastic Packaging Market