
 Asia Pacific Single-Use Plastic Packaging Market | 2026-2036
Asia Pacific Single-Use Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Single-Use Plastic Packaging Market Insights
Food delivery and quick-service restaurant verticals are decoupling from traditional retail packaging formats across Southeast Asia and South Asia. Amcor Group GmbH leverages its flexible pouch technology leadership to capture share in India's burgeoning meal-kit segment. Huhtamaki Oyj anchors its regional position through thermoformed container capacity clustered near Bangkok and Ho Chi Minh City. SCG Packaging dominates Thai domestic supply with integrated resin-to-conversion operations that sustain cost advantages against importers.
Asia Pacific single-use plastic packaging denotes disposable containers, films, and vessels engineered from thermoplastic resins for one-cycle containment and protection, typically manufactured through injection molding, thermoforming, or blown film extrusion at thicknesses below 250 microns for cost-driven disposability. Flexible pouches command expanding share in liquid and semi-solid food applications where material efficiency reduces freight costs versus rigid alternatives. Polyethylene grades lead volume due to their heat-seal compatibility and widespread availability across Indonesian and Vietnamese converter networks, while PET bottles retain structural importance in beverage distribution where clarity and carbonation barrier properties remain non-negotiable.
India's Central Pollution Control Board enforces extended producer responsibility frameworks that obligate brand owners to finance collection infrastructure, directly elevating demand for mono-material polyethylene designs that simplify mechanical recycling streams. Thailand's MEE and Vietnam's MONRE are tightening restrictions on oxo-degradable additive claims, compelling converters to validate compositional transparency through third-party certification. Stakeholders must monitor regulatory divergence between ASEAN harmonization proposals and national implementation timelines to avoid stranded inventory in cross-border supply chains.
Market Dynamics
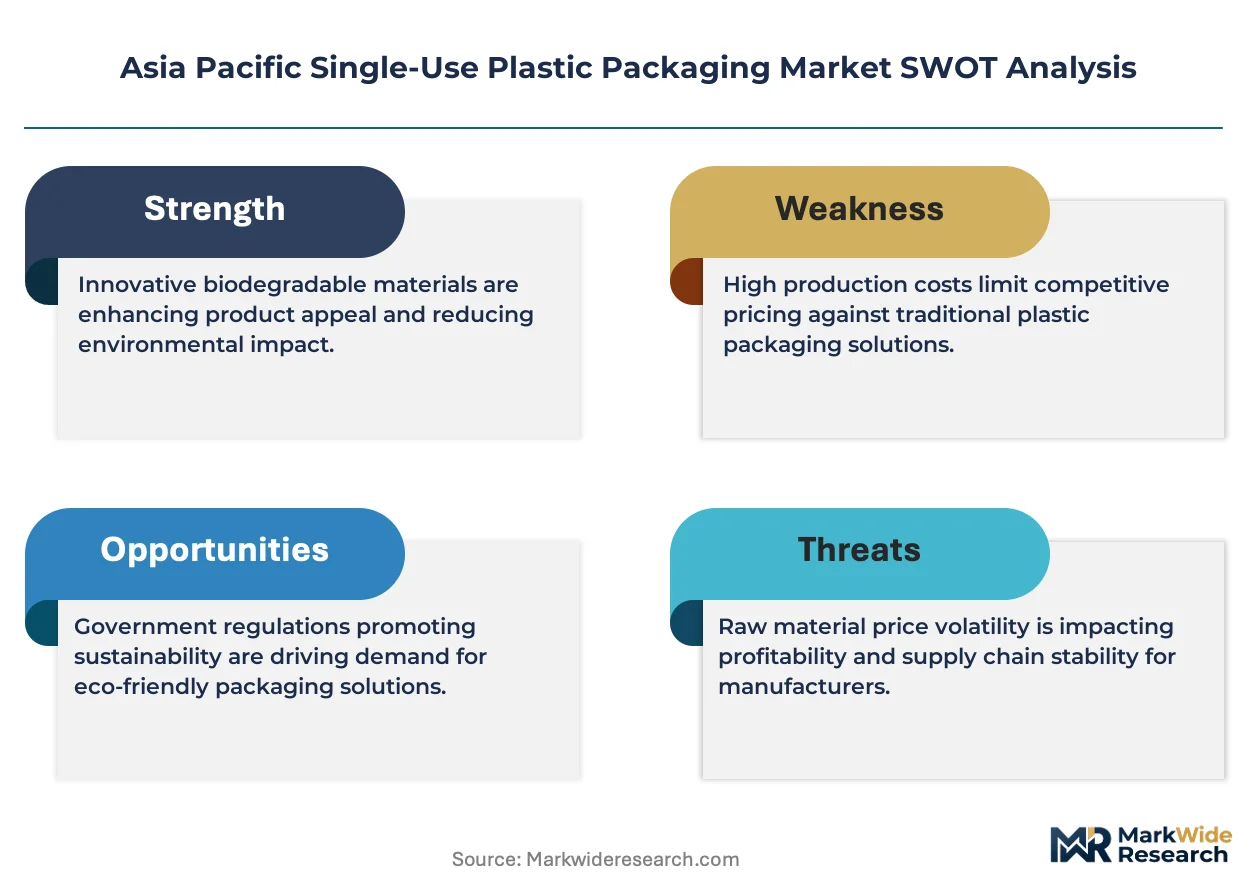
India's extended producer responsibility mandates under the PWM Rules are compressing design cycles as converters race to certify mono-material polyethylene formats before enforcement deadlines hit.
Growth Catalysts
- Food Delivery Infrastructure:Quick-service restaurant chains across Southeast Asia are expanding thermoformed container procurement for delivery and takeaway formats, pulling film and tray volumes upward.
- PWM Rules Compliance:India's Central Pollution Control Board enforcement is obligating brand owners to finance collection infrastructure, elevating demand for recyclable polyethylene grades.
- Seafood Export Processing:Vietnam's export-oriented seafood processing zones are absorbing flexible pouch capacity for frozen and value-added products bound for Japanese and European buyers.
Market Restraints
- Feedstock Volatility:Naphtha-linked polyethylene resin costs swing with regional refinery output, squeezing converter margins in Indonesia and Thailand.
- Import Dependence:Vietnamese converters rely on Chinese resin supply, exposing them to cross-border tariff friction and port congestion.
- Technical Barrier:Multi-layer barrier films for retort applications resist mechanical recycling, limiting circular economy compliance options.
Strategic Opportunities
- Meal-Kit Penetration:India's urban food delivery corridors present white space for portion-controlled flexible pouches with modified atmosphere properties.
- Thailand's MEE Certification:Early alignment with the ministry's compositional transparency requirements creates first-mover positioning for export-ready converters.
- Digital Print Convergence:Combining flexographic decoration with thin-gauge thermoforming enables SKU proliferation without plate cost penalties.
Industry Challenges
- Collection Infrastructure Gap:India's post-consumer polyethylene recovery rates lag mandated targets, forcing brand owners to subsidize informal sector integration.
- Certification Timeline Compression:Third-party validation for compositional claims under Vietnam's MONRE rules extends product launch windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Single-Use Plastic Packaging Market |
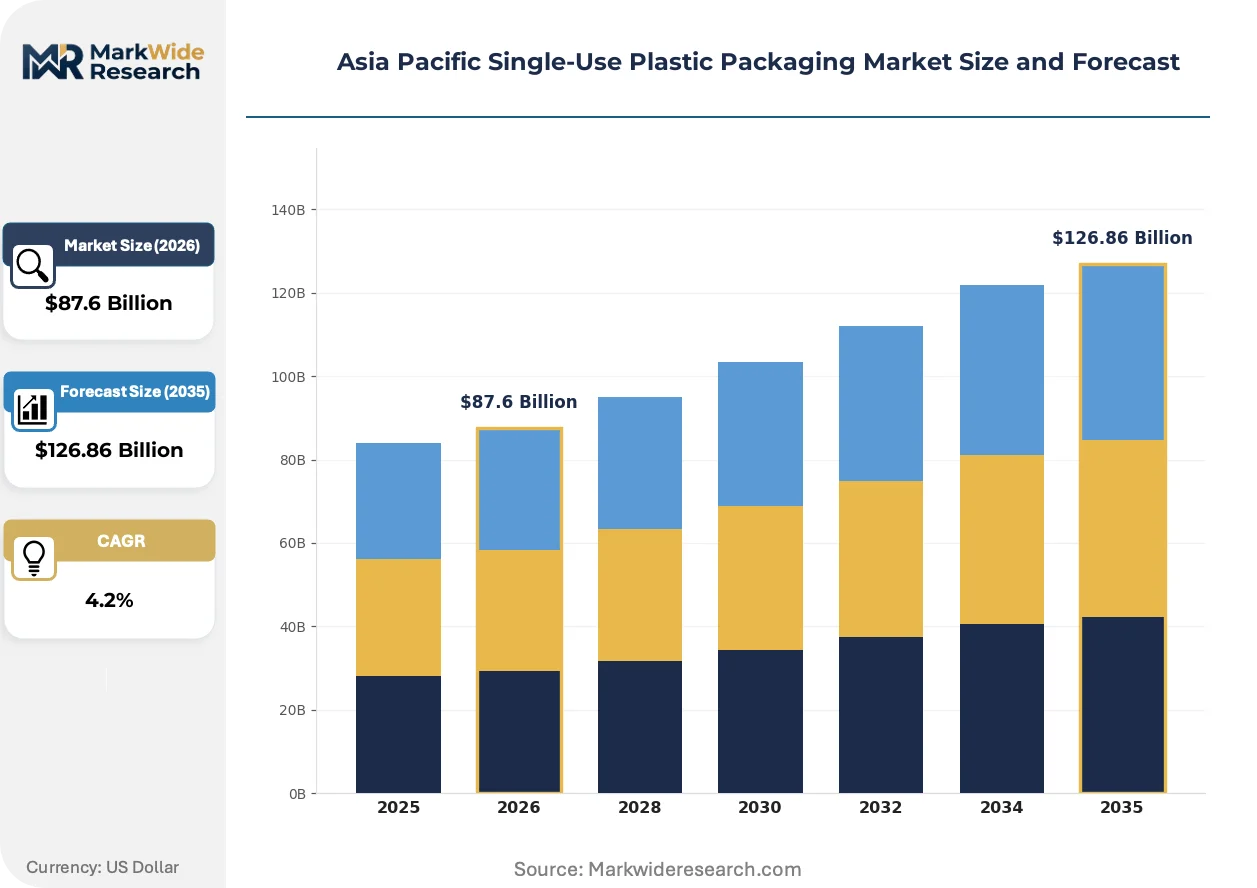
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $126.86 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoformed Containers, Flexible Pouches, Bottles, Trays Material: Polyethylene, Polypropylene, Polystyrene, PET End User: Food & Beverage, Healthcare, Personal Care, Consumer Goods Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Berry Global Inc, Amcor Group GmbH, Huhtamaki Oyj, Hotpack Packaging Industries LLC, Graphic Packaging International, LLC, UFlex Limited, SCG Packaging, TOPPAN Inc., Sonoco Products Company, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Single-Use Plastic Packaging Market Trends and Innovations
Material science and regulatory architecture are rewriting competitive boundaries across Asia Pacific single-use packaging, with converters racing to decouple performance from environmental liability.
Mono-material polyethylene barrier films are rewriting the technical trade-off between shelf-life extension and recyclability. Food manufacturers in Thailand and Vietnam are qualifying these structures for retort and hot-fill applications at accelerated timelines. The shift is compressing demand for legacy nylon-EVOH multi-layer constructions that dominate existing installed capacity.
Thailand's MEE and Vietnam's MONRE are tightening restrictions on oxo-degradable additive claims, compelling converters to validate compositional transparency through third-party certification. This regulatory friction is disqualifying legacy product lines that relied on unsubstantiated environmental marketing. Brand owners are responding by consolidating supplier bases around certified mono-material specialists.
Direct-to-restaurant procurement platforms are disintermediating traditional distributor networks across Southeast Asia. Cloud kitchen operators in Jakarta and Bangkok are aggregating packaging demand through digital channels, compressing order cycles and forcing converters to absorb smaller batch sizes. This behavioral shift is most visible in Vietnam's Ho Chi Minh City corridor, where platform-mediated purchasing now dominates quick-service restaurant supply.
Asia Pacific Single-Use Plastic Packaging Market Segmentation
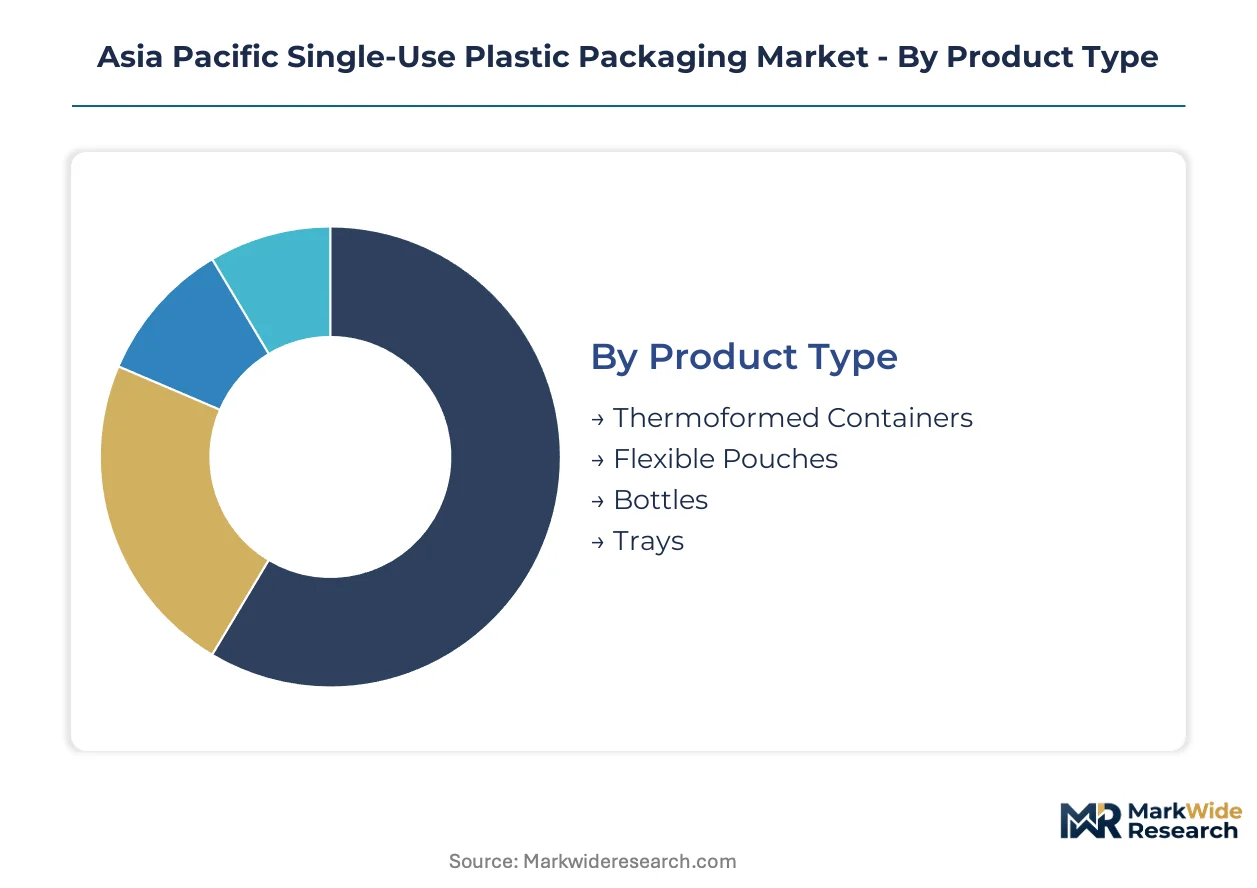
Segmentation in Asia Pacific single-use plastic packaging reveals how converters balance standardized resin platforms against application-specific performance requirements. Material choices and end-use specifications drive divergent margin structures across the region's converter base.
Product Type:
Standardized thermoforming equipment dominates high-volume segments while flexible formats demand customized barrier engineering for shelf-life extension.
- Thermoformed Containers:Injection-stretched polystyrene and crystallized PET structures serve quick-service restaurant chains across Bangkok and Jakarta with standardized depth configurations. India's food delivery corridors absorb expanding volumes as cloud kitchen operators consolidate procurement around modular tray sizes compatible with automated sealing lines.
- Flexible Pouches:Multi-layer coextruded films with ethylene vinyl alcohol barriers protect retort seafood exports from Vietnam's processing zones bound for Japanese buyers. Mono-material polyethylene variants are displacing legacy nylon constructions as Thailand's MEE tightens compositional transparency requirements.
- Bottles:Stretch blow-molded PET dominates carbonated beverage distribution where clarity and pressure resistance remain non-negotiable specifications.
- Trays:Shallow-draw polystyrene formats serve fresh produce merchandising through supermarket chilled cabinets.
Leading the category by volume: Thermoformed Containers. Growing fastest: Flexible Pouches.
Material:
Resin selection maps directly to heat-seal requirements, barrier specifications, and recycling stream compatibility across national regulatory frameworks.
- Polyethylene:Linear low-density grades dominate flexible pouch construction for their puncture resistance and heat-seal initiation temperatures. India's PWM Rules enforcement is accelerating demand for mono-material high-density formats that simplify mechanical recycling at Mumbai and Delhi collection hubs.
- Polypropylene:Clarified random copolymers serve hot-fill and retort applications where dimensional stability above 100°C prevents container deformation. Vietnamese converters favor this resin for domestic sauce and condiment packaging where microwave reheating compatibility drives consumer preference.
- Polystyrene:General-purpose crystal grades remain cost-competitive for thermoformed trays despite thinning pressure from environmental regulations.
- PET:Bottle-grade intrinsic viscosity specifications sustain dominance in carbonated soft drink and bottled water categories.
Volume leadership: Polyethylene. Steepest expansion trajectory: Polypropylene.
End User:
End-use concentration determines converter technical capabilities, with food contact compliance requirements creating tiered supplier qualification barriers.
- Food & Beverage:Quick-service restaurant chains and meal-kit platforms across Southeast Asia specify oxygen transmission rates below 0.1 cc/m²/day for protein packaging. Thailand's integrated seafood processors demand vacuum skin packaging with modified atmosphere properties for European export compliance.
- Healthcare:Sterile barrier systems for pharmaceutical distribution require validated sealing processes and particulate-controlled manufacturing environments that exclude generalist converters.
- Personal Care:Squeeze tubes and laminated sachets serve shampoo and conditioner sampling programs through convenience store channels.
- Consumer Goods:Blister packs and clamshells protect electronics and hardware through retail theft-deterrent display requirements.
Food & Beverage commands the largest share. Healthcare posts the highest margin expansion.
Distribution Channel:
Channel structure determines order cycle frequency and batch size economics, with digital platforms compressing traditional distributor intermediation.
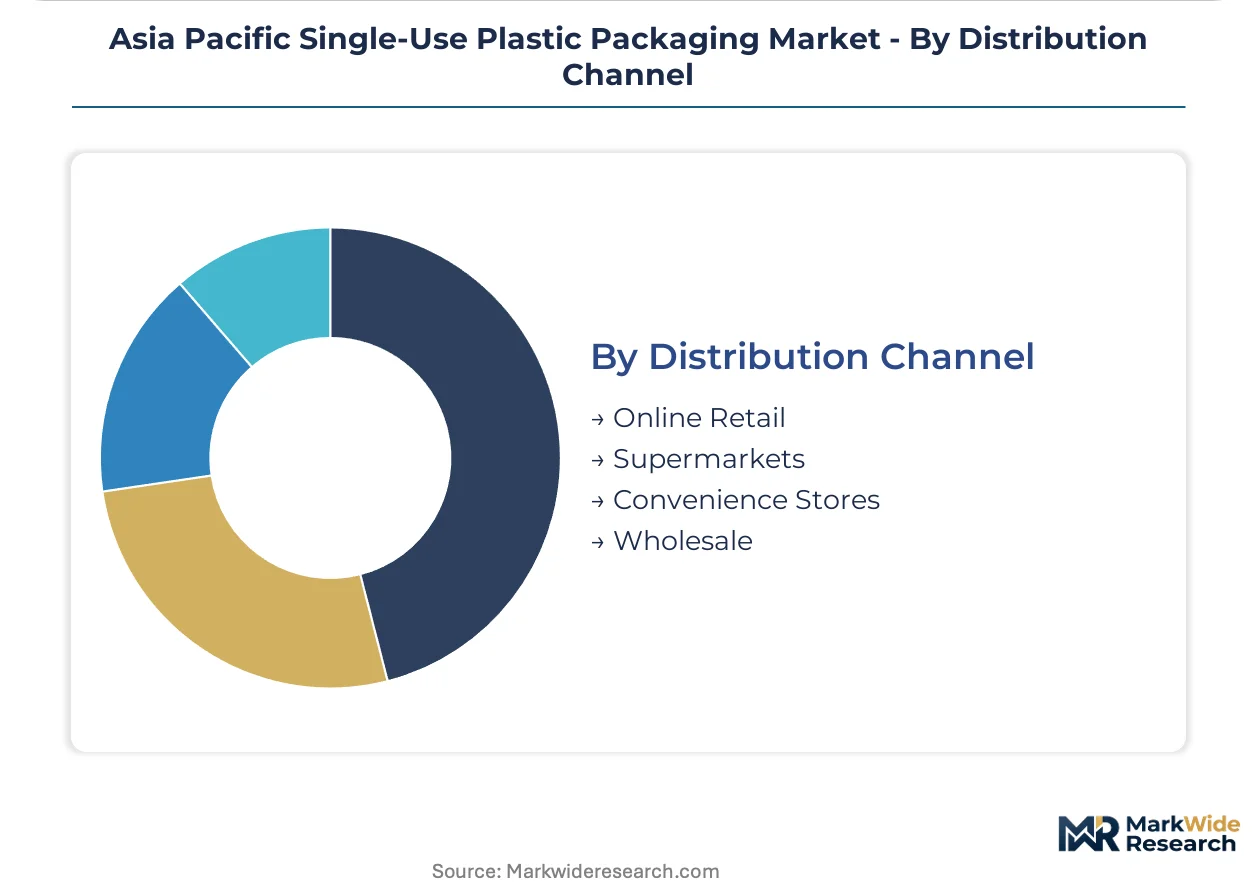
- Online Retail:Direct-to-restaurant procurement platforms aggregate fragmented quick-service demand across Ho Chi Minh City and Jakarta, forcing converters to absorb smaller lot sizes with compressed lead times.
- Supermarkets:Centralized category management at Thai and Vietnamese retail chains standardizes private-label packaging specifications across store networks.
- Convenience Stores:High-velocity replenishment cycles favor lightweight flexible formats with minimal shelf footprint.
- Wholesale:Traditional distributor networks persist in Indonesian outer-island regions where platform penetration remains limited.
Online Retail is gaining share fastest. Wholesale retains volume leadership in secondary cities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand's Eastern Economic Corridor tax incentives concentrate resin-to-conversion operations near Rayong and Chonburi, drawing packaging investment away from import-dependent markets.
India
Urban food delivery corridors in Mumbai, Delhi-NCR, and Bangalore absorb expanding thermoformed container volumes as cloud kitchen operators consolidate procurement. The Central Pollution Control Board enforces PWM Rules extended producer responsibility mandates that obligate brand owners to finance collection infrastructure. Converter clusters in Maharashtra and Gujarat race to certify mono-material polyethylene formats before enforcement deadlines compress design cycles.
Thailand
Integrated seafood processors and quick-service restaurant chains drive flexible pouch and thermoformed tray demand through Bangkok and Eastern Seaboard manufacturing zones. The Ministry of Natural Resources and Environment tightens restrictions on oxo-degradable additive claims, compelling third-party certification for compositional transparency. SCG Packaging anchors domestic supply from Rayong with captive resin production that sustains cost advantages against regional importers.
Vietnam
Export-oriented seafood processing zones in Ho Chi Minh City and Mekong Delta provinces absorb multi-layer flexible pouch capacity for Japanese and European buyers. The Ministry of Natural Resources and Environment extends certification timelines for compositional claims, delaying product launches for uncertified converters. Binh Duong and Dong Nai industrial parks host expanding thermoforming capacity serving domestic quick-service restaurant growth.
Indonesia
Jakarta and Surabaya quick-service restaurant chains pull film and tray volumes upward through platform-mediated procurement that compresses order cycles. National regulations on plastic waste management push brand owners toward recyclable polyethylene grades, though enforcement remains uneven across archipelago logistics. Converter networks in Java rely on naphtha-linked resin supply exposed to regional refinery output swings.
South Korea
Seoul Capital Area food delivery platforms specify modified atmosphere packaging for premium meal-kit segments where portion control and shelf-life extension justify material cost premiums. The Ministry of Environment advances separate collection mandates that elevate demand for mono-material designs compatible with mechanical recycling infrastructure. Incheon and Gyeonggi-do converter clusters supply both domestic quick-service chains and export markets across Northeast Asia.
Asia Pacific Single-Use Plastic Packaging Market Competitive Landscape
Top-tier vendors anchor integrated resin-to-conversion operations, while mid-scale converters compete on geographic proximity to food processing clusters. The market structure reflects a tiered hierarchy where multinational specialists with regional manufacturing footprints command premium positioning against domestic price competitors. Three archetypes dominate: integrated petrochemical-packaging conglomerates with captive raw material supply; flexible packaging specialists with barrier film technology leadership; and regional thermoforming operators serving quick-service restaurant procurement platforms. Competitive moves concentrate on capacity expansion near Bangkok and Ho Chi Minh City logistics corridors, alongside portfolio diversification toward certified mono-material formats that satisfy tightening environmental compliance.
Within the multinational specialist tier, Amcor Group GmbH and Huhtamaki Oyj exemplify technology-led positioning through flexible pouch and thermoformed container platforms respectively. Berry Global Inc represents North American-headquartered diversification into Asia Pacific food contact applications. Among Asia-based integrated operators, SCG Packaging anchors Thai domestic supply with operations that span resin production through finished conversion. UFlex Limited occupies a position as India-based flexible packaging specialist with regional export reach. These named entities sit within a broader competitive set where technology certification and logistics proximity determine contract outcomes more than price alone.
| Leading Market Players |
|---|
| Berry Global Inc |
| Amcor Group GmbH |
| Huhtamaki Oyj |
| Hotpack Packaging Industries LLC |
| Graphic Packaging International, LLC |
| UFlex Limited |
| SCG Packaging |
| TOPPAN Inc. |
| Sonoco Products Company |
| Others |
Pricing and Supply Chain Analysis
Mono-material polyethylene certification is compressing converter cost structures while concentrating supply among integrated resin producers in Thailand and Vietnam. This technical transition simultaneously elevates compliance expenditure and rewards backward-integrated operators with captive polyethylene supply.
Pricing Analysis
Premium pricing attaches to certified mono-material formats with validated lead times under Thailand's MEE and Vietnam's MONRE compliance windows. Three-tier pricing structure separates premium-certified mono-material grades from standard multi-layer constructions and economy spot-market polyethylene. Pricing pressure stems from naphtha-linked resin volatility squeezing Indonesian and Thai converter margins. Small-batch quick-service restaurant procurement through platform-mediated channels exhibits highest price sensitivity, while export-oriented seafood processors absorb material premiums for Japanese and European compliance.
Supply Chain Analysis
Polyethylene resin supply rests on naphtha crackers concentrated in Thailand, South Korea, and Singapore, with Vietnamese converters drawing heavily from Chinese petrochemical exports. Critical inputs span linear low-density polyethylene for flexible pouch construction, clarified polypropylene for hot-fill applications, and injection-grade polystyrene for thermoformed trays. Single-source vulnerability runs through cross-border resin dependence exposing Vietnamese converters to port congestion and tariff friction. Distribution runs through Bangkok and Ho Chi Minh City logistics corridors feeding quick-service restaurant clusters and seafood processing zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified mono-material conversion capacity operates under supply constraint, with Thailand's MEE and Vietnam's MONRE deadlines propping pricing for qualified converters.
For Market Incumbents: Acquire third-party certification assets ahead of enforcement deadlines compressing product launch windows. Defensive consolidation centers on backward integration into polyethylene resin production and capacity clustering near Bangkok and Ho Chi Minh City logistics corridors. Threat substitution from fiber-based alternatives and emerging biodegradable material platforms demands R&D allocation toward barrier-performance parity. For New Entrants and Emerging Players: Enter via India's urban food delivery corridors where cloud kitchen procurement consolidation outpaces certified converter supply. White-space targets span portion-controlled flexible pouches with modified atmosphere properties and digital-print-enabled SKU proliferation for quick-service restaurant platforms. Go-to-market leverage rests on direct platform partnerships bypassing traditional distributor networks. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated petrochemical conglomerates seeking downstream packaging exposure. Long-term viability favors mono-material specialists with validated certification and geographic positioning near Southeast Asian food processing clusters. Watch Thailand's MEE enforcement intensity and India's PWM Rules collection infrastructure buildout as inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Certification Investment | Validates compositional transparency for Thailand's MEE and Vietnam's MONRE compliance windows. |
| Backward Integration into Resin Production | Captures margin compression from naphtha-linked polyethylene volatility affecting Indonesian converters. |
| Capacity Clustering Near Bangkok Logistics Corridor | Reduces freight cost to quick-service restaurant procurement platforms dominating Southeast Asian demand. |
| Digital Print Convergence for SKU Proliferation | Enables small-batch flexibility for cloud kitchen operators compressing order cycles in Ho Chi Minh City. |
| Joint Venture with Seafood Processors | Locks flexible pouch offtake from Vietnam's export zones bound for Japanese and European buyers. |
Research Methodology
Independent corroboration across converter production data, resin trade flows, and regulatory filing timelines underwrites the qualitative findings. Primary interviews spanned plant managers at Thai and Vietnamese converter facilities, procurement leads at quick-service restaurant chains, regulatory affairs specialists navigating PWM Rules and MEE compliance, and distribution channel partners in Jakarta and Bangkok. Secondary validation drew from customs and trade databases, petrochemical industry association reports, and ministry enforcement disclosures. Bottom-up capacity assessment triangulated against top-down demand modeling across food delivery, seafood export, and meal-kit end uses.
Rate-of-change decomposition across material substitution velocity, regulatory enforcement intensity, and platform procurement adoption shaped the analytical framework. Segmentation dimensions modeled encompass product type, material grade, end-use vertical, and distribution channel complexity. CAGRs derived from elasticity-adjusted volume projections incorporating resin price pass-through coefficients and compliance cost absorption rates. Forecast inputs included naphtha-linked polyethylene price trajectories and certified converter capacity expansion timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt regulatory enforcement acceleration or resin supply disruption. Projections reflect documented assumptions on PWM Rules collection infrastructure buildout and MEE certification timeline adherence. A small set of named triggers warrants ongoing watch: Thailand's MEE third-party validation queue length, India's informal sector integration progress, and Vietnamese cross-border resin tariff adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Recycled Plastic Envelope Market
Plastic Packaging
Plastic Ready Meal Trays Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Global Plastic Pails Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market