
 France Plastic Packaging Market | 2026-2036
France Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Plastic Packaging Market Foresight
Multi-sourced resin procurement is expanding across the French plastic packaging value chain as converters diversify away from single-supplier petrochemical dependencies. Amcor leverages European film extrusion networks to sustain flexible packaging leadership for French dairy and meat clients. Berry Global anchors rigid container supply through blow-molding assets serving personal care brands in the Rhône-Alpes manufacturing belt. Constantia Flexibles specializes in high-barrier laminates, competing for pharmaceutical blister contracts against Sealed Air's medical-grade sterile packaging portfolio.
France plastic packaging encompasses thermoformed, extruded, and molded polymer structures engineered to protect, preserve, and present consumer and industrial goods, with specifications typically spanning 50-micron films to 20-liter HDPE containers processed via injection-stretch-blow or cast film techniques. Its primary commercial purpose centers on extending shelf stability, enabling automated filling lines, and satisfying retail display requirements across temperature-variable supply chains. Bottles and containers capture dominant volume within rigid formats as beverage brand owners prioritize lightweight PET designs with recycled content thresholds. Flexible bags and films represent the fastest-expanding structural category, driven by pouched pet food and liquid detergent refills displacing traditional rigid formats in French supermarkets. Clamshells occupy a mature margin position, pressured by paperboard alternatives yet sustained by produce visibility requirements in Carrefour and E.Leclerc fresh departments.
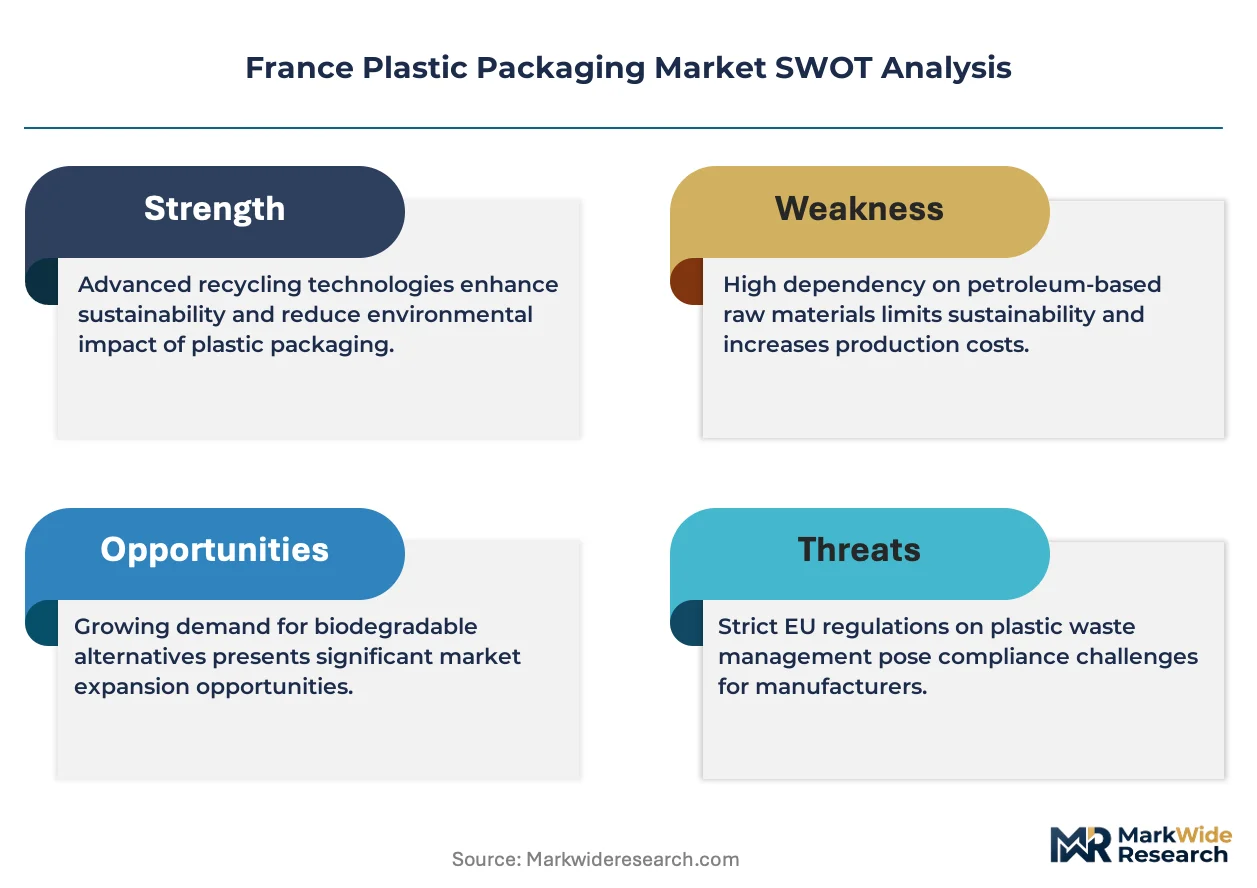
ANSM governs pharmaceutical packaging materials through stability testing protocols that dictate barrier performance minimums for moisture-sensitive drug formats. France's transposition of the EU Packaging and Packaging Waste Regulation, alongside ECHA REACH substance restrictions on intentionally added microplastics, reshapes material selection and recycling infrastructure investment timelines. The national anti-waste law (AGEC) imposes recycled content mandates and extended producer responsibility fees that directly alter converter cost structures. Stakeholders must monitor evolving éco-organisme fee schedules and mechanical recycling yield rates to determine whether chemical recycling partnerships or bio-based polymer pivots offer superior compliance economics.
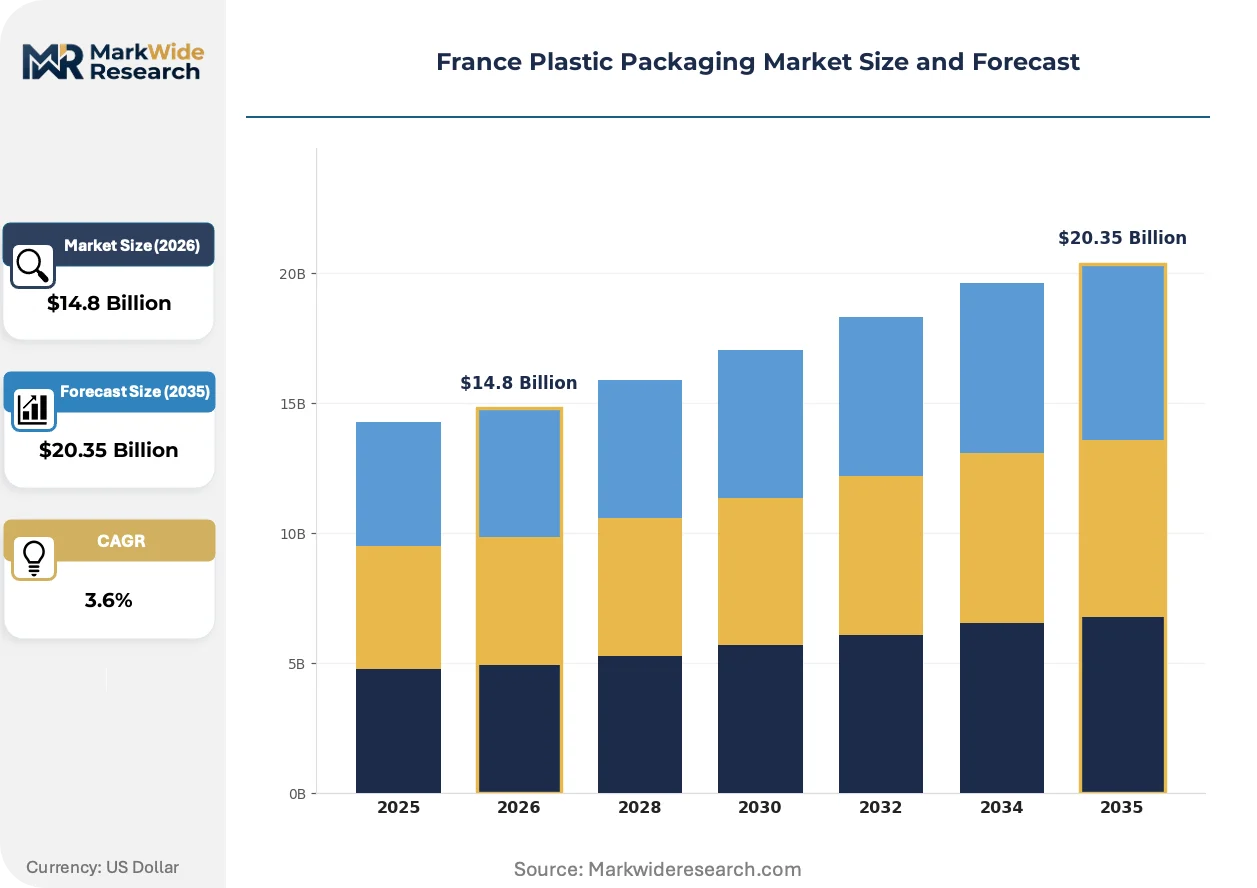
Market Dynamics
France's plastic packaging sector operates under intense regulatory compression as AGEC mandates and ECHA REACH substance restrictions force converters to reengineer material formulations and recycling economics simultaneously.
Growth Catalysts
- Extended Producer Responsibility Frameworks:France's éco-organisme fee structures incentivize mechanical recycling infrastructure investment and lightweight design innovation across dairy and personal care formats.
- Barrier Film Technology:High-performance coextruded laminates enable extended shelf stability for sensitive food products, driving replacement of traditional rigid containers in Carrefour and E.Leclerc supply chains.
- Île-de-France Industrial Corridor:Concentrated converter and brand owner presence around Paris creates dense innovation ecosystems and rapid pilot-to-scale pathways for sustainable packaging trials.
Market Restraints
- Recycled PET Feedstock Volatility:Mechanical recycling yield rates fluctuate between 55-70% depending on collection stream contamination, constraining supply security for beverage bottle mandates.
- Chemical Recycling Capital Intensity:Pyrolysis and depolymerization facilities require €200-400 million per plant, limiting participation to integrated petrochemical majors and excluding mid-cap converters.
- Paperboard Substitution Pressure:Fiber-based alternatives capture fresh produce and dry goods applications previously held by thermoformed clamshells and trays.
Strategic Opportunities
- Pharmaceutical Blister Packaging:ANSM stability testing protocols create certification moats for converters mastering high-barrier PVC-PVDC-aluminum laminate structures against moisture-sensitive drug formats.
- Refill Pouch Expansion:Liquid detergent and cleaning product brands accelerate format conversion from rigid HDPE bottles to flexible stand-up pouches, reducing transport emissions and shelf space requirements.
- Bio-based Polymer Pilots:PLA and PHA formulations gain traction in single-serve foodservice applications where industrial composting infrastructure exists in Lyon and Marseille metropolitan zones.
Industry Challenges
- Multi-material Separation Expertise:Complex laminate structures combining PE, PA, EVOH, and aluminum layers require specialized delamination equipment and chemist-trained technical staff scarce in regional conversion facilities.
- Legacy Extrusion Asset Stranding:Existing cast film and blow-molding lines engineered for virgin resin specifications face retrofit costs or obsolescence under escalating recycled content thresholds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Plastic Packaging Market |
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $20.35 Billion |
| CAGR (2026 – 2036) | 3.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Bags, Clamshells, Containers End Use Industry: Food & Beverage, Personal Care, Pharmaceuticals, Household Products Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Form: Rigid, Flexible, Semi-rigid, Blow-molded |
| Companies Covered | Coveris, Sonoco Products Company, Amcor, Silgan Holdings, Tetra Laval, Berry Global, Sealed Air, Wipak Group, Constantia Flexibles, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Plastic Packaging Market Shifts & Advancements
Digital printing and smart packaging integration are compressing minimum order quantities and enabling mass customization for French brand owners seeking regionalized SKU strategies without inventory proliferation.
Mono-material polyethylene laminates are consolidating flexible packaging specifications across snack, pet food, and frozen vegetable segments. Danone and Nestlé France procurement teams specify these structures for mechanical recycling compatibility. This consolidation is compressing multi-layer coextrusion demand and forcing adhesive and barrier coating suppliers to reformulate for single-substrate adhesion.
France's transposition of the EU Packaging and Packaging Waste Regulation imposes harmonized extended producer responsibility fees and recycled content targets across all packaging categories. Industrial consequence includes accelerated partnerships between converters and chemical recycling operators to secure mass balance certification for food-contact applications. Pharmaceutical and cosmetic segments face the steepest compliance timelines due to ANSM safety validation requirements.
Refill station networks in French supermarkets are altering primary packaging specifications toward concentrated formats and durable dispensing vessels. E.Leclerc and Intermarché pilot programs replace single-use bottles with bulk dispensers for household cleaners and personal care products. This channel shift concentrates demand in Rhône-Alpes and Occitanie regions where retail infrastructure investment precedes national rollout.
France Plastic Packaging Market Segmentation
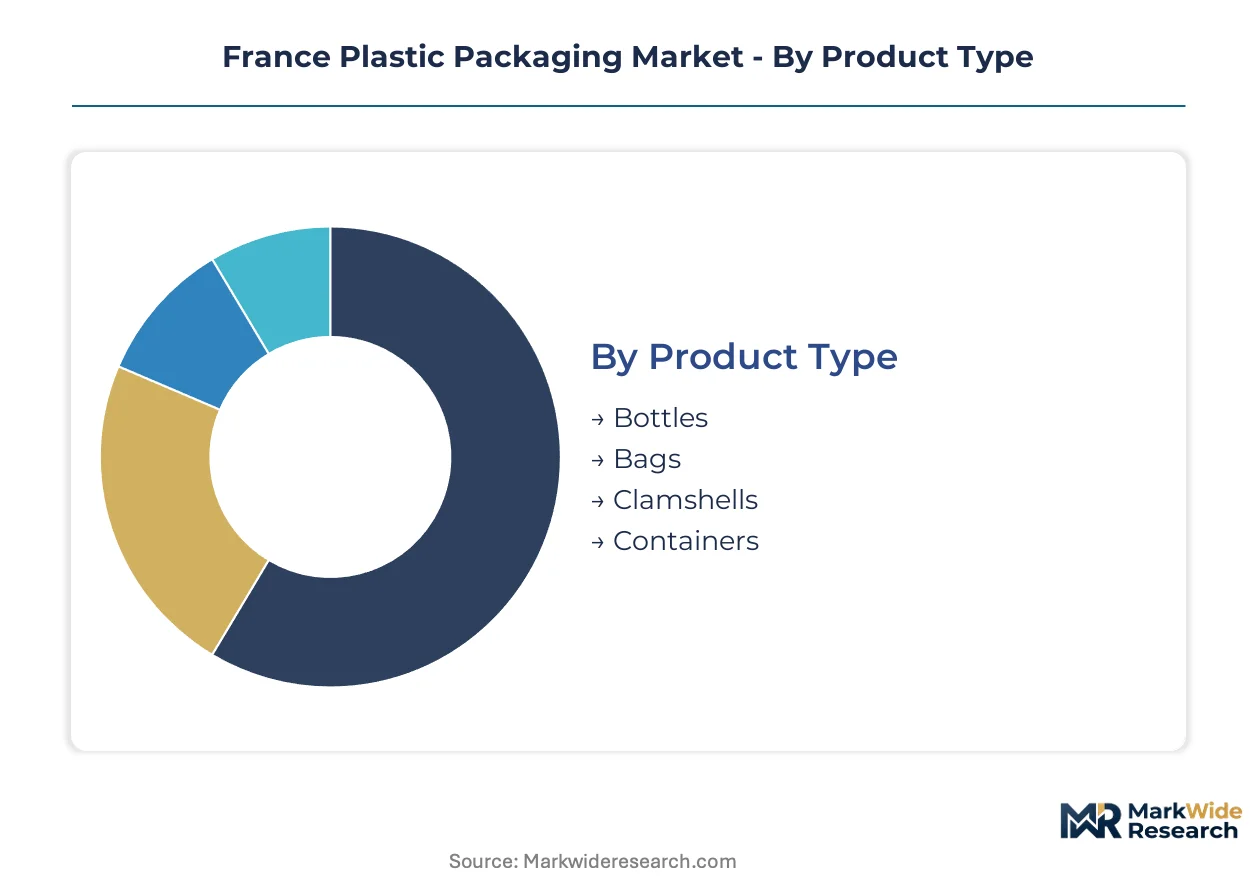
Segmentation in the France plastic packaging market reveals how regulatory pressure and format innovation create divergent margin profiles across converter portfolios. Understanding these divisions exposes where AGEC compliance costs concentrate and where barrier technology investments yield defensive positioning.
Product Type:
Buyers differentiate primarily by filling line compatibility and shelf-presence requirements rather than material cost alone.
- Bottles:PET and HDPE injection-stretch-blow structures dominate beverage and personal care lines. Danone and L'Oréal procurement teams specify lightweight designs with recycled content thresholds that strain mechanical recycling feedstock security.
- Bags:Coextruded polyethylene laminates and stand-up pouches displace rigid formats in detergent and pet food aisles. Carrefour and E.Leclerc refill station pilots accelerate concentrated pouch specifications over traditional bottles.
- Clamshells:Thermoformed PET structures retain produce visibility advantages despite paperboard substitution pressure in fresh departments.
- Containers:Injection-molded PP and HDPE tubs serve dairy and prepared meal segments where oxygen barrier requirements determine material selection.
Volume sits with bottles; growth tilts toward bags.
End Use Industry:
Margin structures vary sharply by validation burden and shelf-life specification intensity.
- Food & Beverage:Barrier film innovation concentrates here as dairy and meat processors demand extended stability without refrigeration compromise. Île-de-France converter clusters pilot mono-material laminates for mechanical recycling compatibility.
- Personal Care:Rigid bottle demand persists for premium positioning, though refill pouch conversion accelerates in mass-market shampoo and body wash lines.
- Pharmaceuticals:ANSM stability testing protocols create certification barriers for blister pack converters. PVC-PVDC-aluminum laminates dominate moisture-sensitive drug protection.
- Household Products:Concentrated refill formats and durable dispensing vessels reshape primary packaging specifications around bulk retail infrastructure.
Revenue concentrates in food and beverage; compliance complexity peaks in pharmaceuticals.
Material:
Selection criteria have shifted from cost-per-kilogram to recycling pathway compatibility under extended producer responsibility frameworks.
- Polyethylene:LDPE and HDPE grades anchor flexible film and bottle applications where mechanical recycling infrastructure achieves highest yield rates. Mono-material PE laminates consolidate snack and frozen vegetable specifications.
- Polypropylene:Injection-molded PP serves dairy tubs and pharmaceutical caps with clarity and chemical resistance profiles. Random copolymer grades compete for thermoformed tray applications.
- Polyvinyl Chloride:Pharmaceutical blister packs and medical device packaging sustain demand despite environmental scrutiny. ANSM validation timelines slow material substitution.
- Polystyrene:Expanded PS retains insulated foodservice applications where industrial composting alternatives remain underdeveloped outside Lyon and Marseille zones.
Polyethylene captures volume leadership; polypropylene climbs fastest on dairy format conversion.
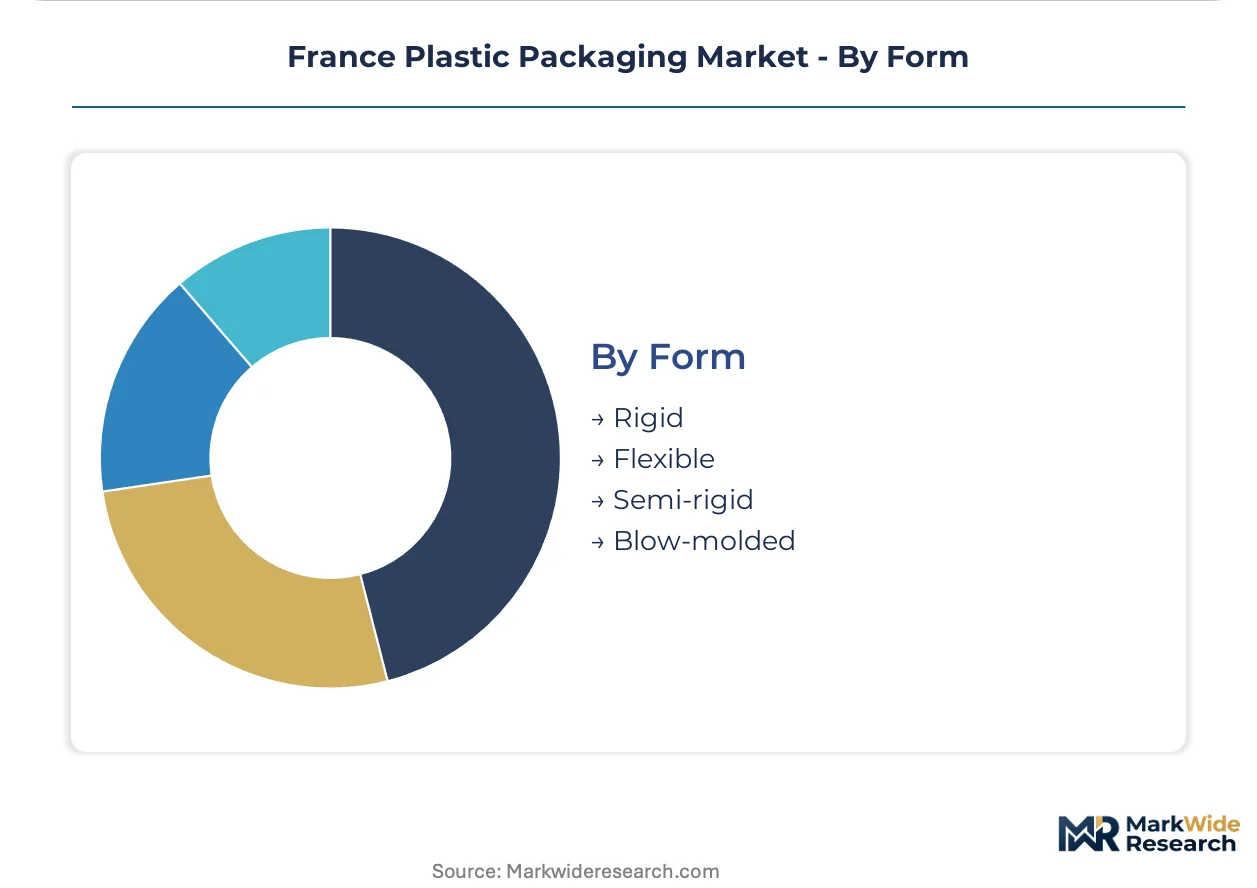
Form:
Equipment amortization schedules and line speed requirements lock converters into rigid or flexible specialization.
- Rigid:Blow-molded and injection-molded structures dominate beverage and personal care with established filling line infrastructure. Legacy asset stranding risks emerge under recycled content mandates.
- Flexible:Cast film and extrusion coating lines produce pouches and wraps with superior transport efficiency. Digital printing integration enables regionalized SKU strategies.
- Semi-rigid:Thermoformed trays balance visibility and protection for fresh protein and prepared meals. Paperboard substitution pressure concentrates in this intermediate zone.
- Blow-molded:Distinct from general rigid category, this sub-segment captures extrusion and injection-stretch processes for hollow containers with handle integration and neck finish precision.
Flexible formats gain share fastest; rigid retains absolute volume dominance.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's plastic packaging demand concentrates in the Île-de-France industrial corridor, where converter density and brand owner headquarters create dense innovation ecosystems for sustainable format trials.
Île-de-France
Paris metropolitan demand centers on premium personal care and pharmaceutical packaging where ANSM validation requirements create certification barriers for new entrants. The AGEC anti-waste law imposes recycled content mandates that alter converter cost structures in this high-value zone. Nanterre and Saint-Denis host flexible film extrusion clusters piloting mono-material laminates for mechanical recycling compatibility.
Auvergne-Rhône-Alpes
Lyon anchors rigid container demand for dairy and prepared meal segments where oxygen barrier specifications determine material selection. ECHA REACH substance restrictions on intentionally added microplastics reshape material selection timelines for converters serving export markets. Saint-Étienne and Grenoble manufacturing belts concentrate blow-molding assets for personal care brands.
Provence-Alpes-Côte d'Azur
Marseille metropolitan demand focuses on foodservice and single-serve applications where industrial composting infrastructure supports bio-based polymer pilots. The EU Packaging and Packaging Waste Regulation accelerates partnerships between regional converters and chemical recycling operators. Aix-en-Provence hosts flexible packaging specialists supplying olive oil and wine export markets.
Hauts-de-France
Lille industrial corridor demand concentrates in beverage bottling and logistics packaging serving Northern European export channels. Extended producer responsibility frameworks through éco-organisme fee structures incentivize lightweight design innovation. Dunkirk and Calais processing zones leverage port proximity for recycled PET feedstock import operations.
Occitanie
Toulouse and Montpellier demand centers on agricultural packaging and pharmaceutical blister formats where moisture barrier requirements sustain PVC-PVDC laminate specifications. ANSM stability testing protocols slow material substitution despite environmental scrutiny. Perpignan conversion facilities supply fresh produce clamshells to Spanish and Italian retail chains.
France Plastic Packaging Market Competitive Landscape
Capacity expansion dominates the current landscape as integrated converters retrofit legacy extrusion lines for recycled content thresholds. The vendor base stratifies across three tiers: multinational film and rigid specialists with European network leverage, mid-cap regional converters with flexible asset bases, and niche barrier technology specialists. Strategic archetypes include mechanical recycling infrastructure owners, mono-material laminate innovators, and pharmaceutical certification holders. M&A activity and chemical recycling partnerships constitute the dominant competitive moves.
Among European-headquartered specialists, Amcor and Berry Global exemplify scale-driven archetypes with network leverage across flexible and rigid formats respectively. Constantia Flexibles occupies a position within the high-barrier laminate tier where ANSM pharmaceutical validation creates defensive moats. These three anchors represent contrasting strategic postures: film extrusion breadth, rigid container verticality, and pharmaceutical certification depth.
| Leading Market Players |
|---|
| Coveris |
| Sonoco Products Company |
| Amcor |
| Silgan Holdings |
| Tetra Laval |
| Berry Global |
| Sealed Air |
| Wipak Group |
| Constantia Flexibles |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap converters across Normandy and Brittany anchor supply-side discipline through conservative balance sheets and selective capacity additions, insulating pricing power from volatile resin procurement cycles while AGEC compliance costs force financially stretched competitors toward distressed exits.
Pricing Analysis
Volume concentrates in standard-grade PE films and rigid containers where éco-organisme fee pass-throughs compress margins, while premium tiers capture ANSM-certified pharmaceutical laminates and high-barrier dairy specifications with pricing power anchored in validation timelines and technical staff scarcity. Price differentiation hinges on mechanical recycling compatibility certification and barrier coating sophistication, with Carrefour and E.Leclerc procurement teams demanding transparency on mass balance allocation. Cost compression in flexible formats intensifies as mono-material specifications consolidate snack and frozen vegetable demand around fewer substrate suppliers. Mass-market beverage bottlers exhibit acute price sensitivity due to rPET feedstock insecurity, whereas pharmaceutical brand owners absorb premium laminates with limited substitution alternatives.
Supply Chain Analysis
ANSM stability testing protocols and ECHA REACH substance registrations gate supplier qualification, extending onboarding timelines to 18-24 months for pharmaceutical-grade resin and additive sourcing. Feedstock draws from Belgium, Germany, and the Netherlands for virgin polyethylene and polypropylene, while mechanical recycling concentrates in domestic Hauts-de-France and Spanish border facilities. Supply chain risk centers on single-source dependency for EVOH barrier resins and specialized PVDC coatings in high-performance laminates. Distribution runs through converter-direct relationships with Danone, L'Oréal, and Nestlé France procurement hubs, supplemented by regional distribution centers serving Carrefour and Intermarché private-label networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's plastic packaging sector is consolidating as AGEC recycled content mandates and chemical recycling capital requirements force sub-scale converters toward acquisition or exit, with éco-organisme fee structures accelerating this Darwinian pressure.
For Market Incumbents: Lock in mechanical recycling feedstock security through backward integration into collection and sorting infrastructure in Hauts-de-France, while defending pharmaceutical certification moats against emerging barrier coating specialists from Germany and Italy. Prioritize mono-material laminate R&D partnerships with Danone and Nestlé France to capture format conversion demand in pet food and frozen vegetable segments before competitors achieve ANSM-equivalent validation timelines. For New Entrants and Emerging Players: Refill station operators and bulk dispensing equipment providers offer the most penetrable channel partnership angle, with E.Leclerc and Intermarché pilot programs in Rhône-Alpes and Occitanie creating white-space for concentrated pouch and durable vessel specifications. Target household products and mass-market personal care where barrier requirements remain modest and brand owner procurement teams prioritize sustainability credentials over incumbent relationships. A go-to-market angle emphasizing industrial composting compatibility in Lyon and Marseille metropolitan zones bypasses mechanical recycling infrastructure gaps. For Investors and Strategic Acquirers: Distressed-cycle entries favor pharmaceutical-certified laminate specialists in Île-de-France and Auvergne-Rhône-Alpes where ANSM validation creates irreplaceable intangible assets. Long-term viability hinges on positioning for food-contact chemical recycling mass balance certification as pyrolysis capacity scales. The signal to watch is éco-organisme fee schedule revisions that mechanically advantage integrated recyclers over merchant converters.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Backward Integration | Captures rPET and rPE feedstock security for AGEC compliance without merchant market volatility. |
| Mono-Material Laminate Platform Launch | Aligns with Danone and Carrefour procurement specifications for mechanical recycling compatibility. |
| ANSM Pharmaceutical Certification Investment | Creates 18-24 month regulatory moats against emerging barrier technology competitors. |
| Chemical Recycling Joint Venture | Secures mass balance certification pathways for food-contact applications under EU Packaging Regulation. |
| Refill Station Infrastructure Partnership | Positions for E.Leclerc and Intermarché bulk dispensing rollout beyond pilot regions. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving flexible film extrusion plant managers, pharmaceutical packaging procurement leads at Sanofi and Ipsen, dairy processor technical directors, éco-organisme fee schedule administrators, and barrier coating R&D specialists. Bottom-up triangulation against converter capacity databases and top-down validation through ANSM submission trend analysis ensured segmentation integrity.
Reconciliation of production volume streams, import-export trade flows, and end-use consumption patterns structured the analytical framework across product type, material grade, and regional industrial cluster dimensions. CAGRs derived from elasticity-adjusted demand modeling incorporated rPET yield rate assumptions, AGEC mandate phase-in schedules, and chemical recycling capacity buildout timelines as industry-specific forecast inputs.
Caveats apply where ECHA REACH substance restriction expansions or ANSM stability testing protocol revisions could materially shift the outlook for barrier material specifications and validation economics. A model refresh is warranted upon material change in éco-organisme fee structures or mechanical recycling infrastructure yield rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
PCR Plastic Packaging Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
Indonesia Plastic Packaging Market
Plastic Packaging
Vietnam Plastic Bottles Market
Plastic Packaging
Global Plastic Packaging Sacks Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
South Africa Flexible Plastic Packaging Market
Plastic Packaging
Thermoformed Plastic Trays Market
Plastic Packaging
PE Blow Molded Products Market
Plastic Packaging
GCC Plastic Packaging Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
Germany Plastic Bottles Market