
 Injection Molded Plastics Market | 2026-2036
Injection Molded Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Injection Molded Plastics Market Analysis
Aftermarket service revenue for mold maintenance and hot-runner refurbishment is reconfiguring margin pools away from virgin resin sales toward lifecycle partnerships. Dow Inc. leverages its materials science portfolio to anchor long-term supply contracts with tier-one automotive suppliers. BASF SE competes through specialized polyamide grades engineered for thermal management in electric powertrains. LyondellBasell Industries sustains manufacturing scale across multiple continents, securing feedstock flexibility that smaller compounders cannot match.
Injection molded plastics are thermoplastic or thermoset polymers heated to viscous flow, forced into precision steel cavities under clamp pressure, then cooled to net-shape parts with tolerances routinely held to ±0.1 mm; this process yields repeatable, high-volume components for industries where metal substitution and design integration matter. Polypropylene dominates automotive interior and under-hood applications due to its fatigue resistance and density advantage over engineering resins. Acrylonitrile Butadiene Styrene concentrates margin in medical devices and consumer electronics housings where surface aesthetics and sterilization compatibility command premium pricing. Polyethylene anchors packaging solutions as blow-molding and thin-wall injection grades optimize cycle economics for high-throughput converters.
The EPA regulates volatile organic compound emissions from resin production and molding operations, pushing processors toward electric presses and closed-loop material handling. REACH compliance in Europe restricts phthalate plasticizers and certain halogenated flame retardants, forcing reformulation of Polyvinyl Chloride compounds for construction and cable applications. China's MEE enforces stricter wastewater and air emission standards around petrochemical clusters, raising capital requirements for new compounding capacity. Stakeholders must weigh regulatory compliance costs against the pricing power available in certified medical and food-contact grades as end-users tighten supplier qualification protocols.
Market Dynamics
Automotive lightweighting mandates are forcing resin compounders to reformulate glass-filled polyamides and long-fiber thermoplastics for structural load-bearing applications, compressing traditional metal-to-plastic conversion timelines from years to months.
Growth Catalysts
- Electric vehicle battery enclosures:Thermal runaway containment requirements in EV powertrains are pulling flame-retardant polypropylene compounds into pack housings and module frames.
- REACH Annex XVII restrictions:Phthalate plasticizer bans in Europe are redirecting PVC formulation investments toward bio-based and non-phthalate alternatives for cable and construction markets.
- Medical device sterilization compatibility:Gamma and e-beam resistant grades of polycarbonate and ABS are capturing share in single-use surgical instruments and diagnostic housings.
Market Restraints
- Propylene feedstock volatility:Naphtha-cracking economics and PDH unit outages in the US Gulf Coast and Middle East are injecting margin instability into polypropylene compounders.
- Tooling lead-time bottlenecks:High-precision mold fabrication capacity concentrates in German, Japanese, and Chinese machine shops, creating 16-24 week procurement queues for complex multi-cavity tools.
- Mechanical property ceilings:Fiber-reinforced thermoplastics face stiffness and creep limitations under sustained load above 150°C, blocking adoption in certain under-hood structural brackets.
Strategic Opportunities
- Chemical recycling feedstock integration:Pyrolysis-derived naphtha and monomer recovery technologies are enabling food-contact certified recycled polypropylene for packaging converters.
- India automotive supplier qualification:PLI scheme incentives for component localization are opening qualification windows for global compounders with in-country compounding assets.
- Overmolding with continuous fiber:Hybrid injection-compression processes combining discontinuous bulk molding with unidirectional tape inserts are unlocking aerospace and sporting goods applications.
Industry Challenges
- Hot-runner system maintenance expertise:Specialized technicians capable of diagnosing valve-gate sequencing faults and manifold thermal uniformity issues remain scarce across North American molders.
- Automotive IATF 16949 certification timelines:New supplier qualification protocols require 12-18 month track records of statistical process control data before volume awards.
- Legacy ERP integration with MES:Real-time cavity pressure monitoring and adaptive process control systems face data architecture friction with older manufacturing execution platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Injection Molded Plastics Market |
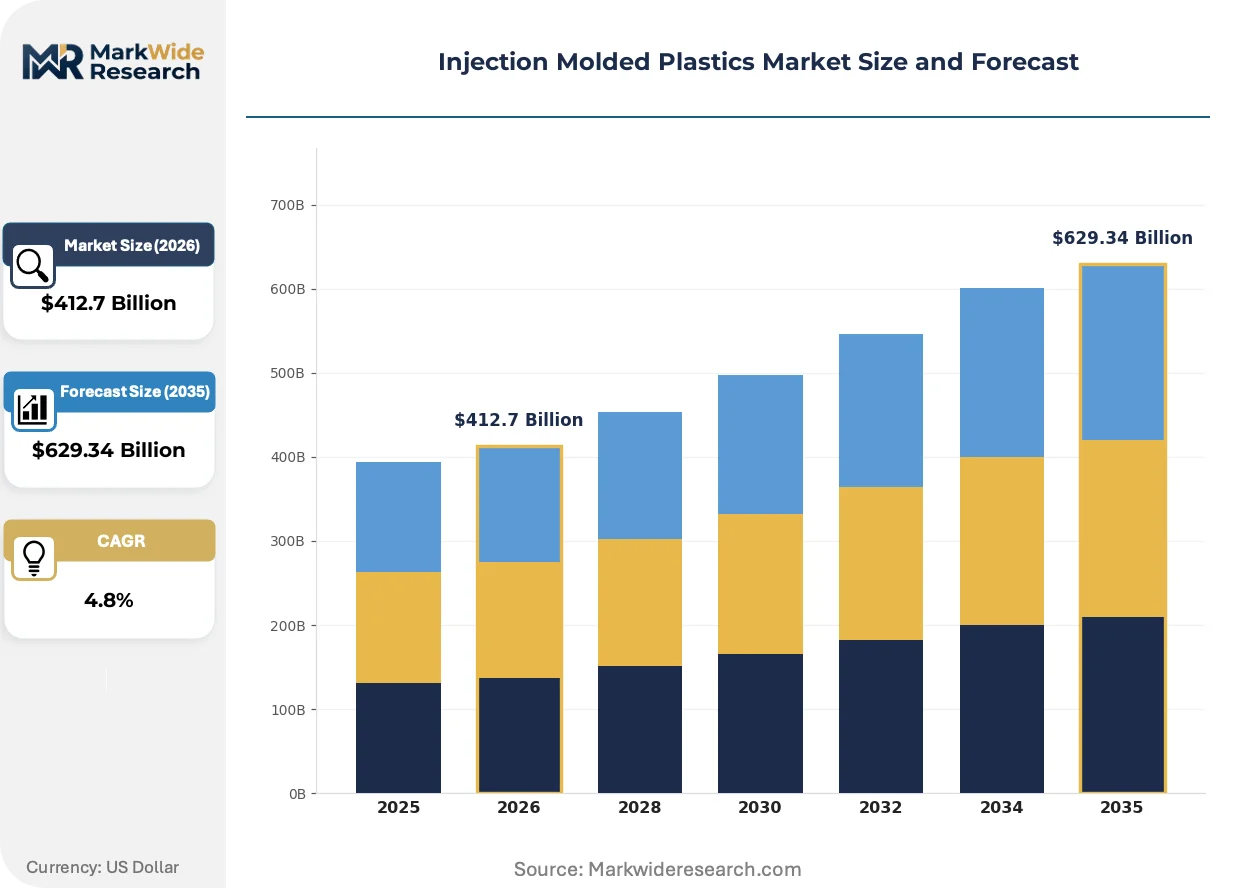
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $629.34 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyethylene, Polypropylene, Polyvinyl Chloride, Acrylonitrile Butadiene Styrene Application: Automotive Components, Consumer Goods, Medical Devices, Packaging Solutions End User: Electronics, Healthcare, Aerospace, Construction Distribution Channel: Direct Sales, Online Sales, Distributors, Retailers |
| Companies Covered | BASF SE, Dow Inc., DuPont, SABIC, LyondellBasell Industries, Huntsman Corporation, INEOS Group, Covestro AG, HTI Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Injection Molded Plastics Market Emerging Trajectories
Digital twin technology is compressing mold design iteration cycles and enabling predictive maintenance, while regulatory pressure on carbon intensity is reshaping both feedstock sourcing and processing equipment selection across major manufacturing clusters.
Simulation software is virtualizing mold filling, cooling, and warpage prediction before steel is cut, allowing automotive tier-one suppliers to validate multi-cavity family tools digitally. BMW and Volkswagen have deployed these platforms across powertrain and interior programs, collapsing traditional prototype tooling stages. This capability is virtualizing the historical reliance on physical mold trials and iterative steel welding.
ECHA's SCIP database requirements under the Waste Framework Directive are forcing disclosure of Substances of Very High Concern throughout complex plastic articles. Electronics and automotive OEMs must now trace candidate list substances through multi-tier supply chains. Medical device and food-contact segments are responding fastest, locking in compliant formulations ahead of enforcement deadlines.
Automotive OEMs are consolidating resin procurement through direct material call-off agreements, bypassing traditional distributor stocking models. Tier-one molders now manage consignment inventory at line-side, with compounders bearing working capital burdens previously held by channel intermediaries. This pattern is most pronounced in German and Chinese automotive supply chains, where just-in-sequence delivery mandates dominate.
Injection Molded Plastics Market Segmentation
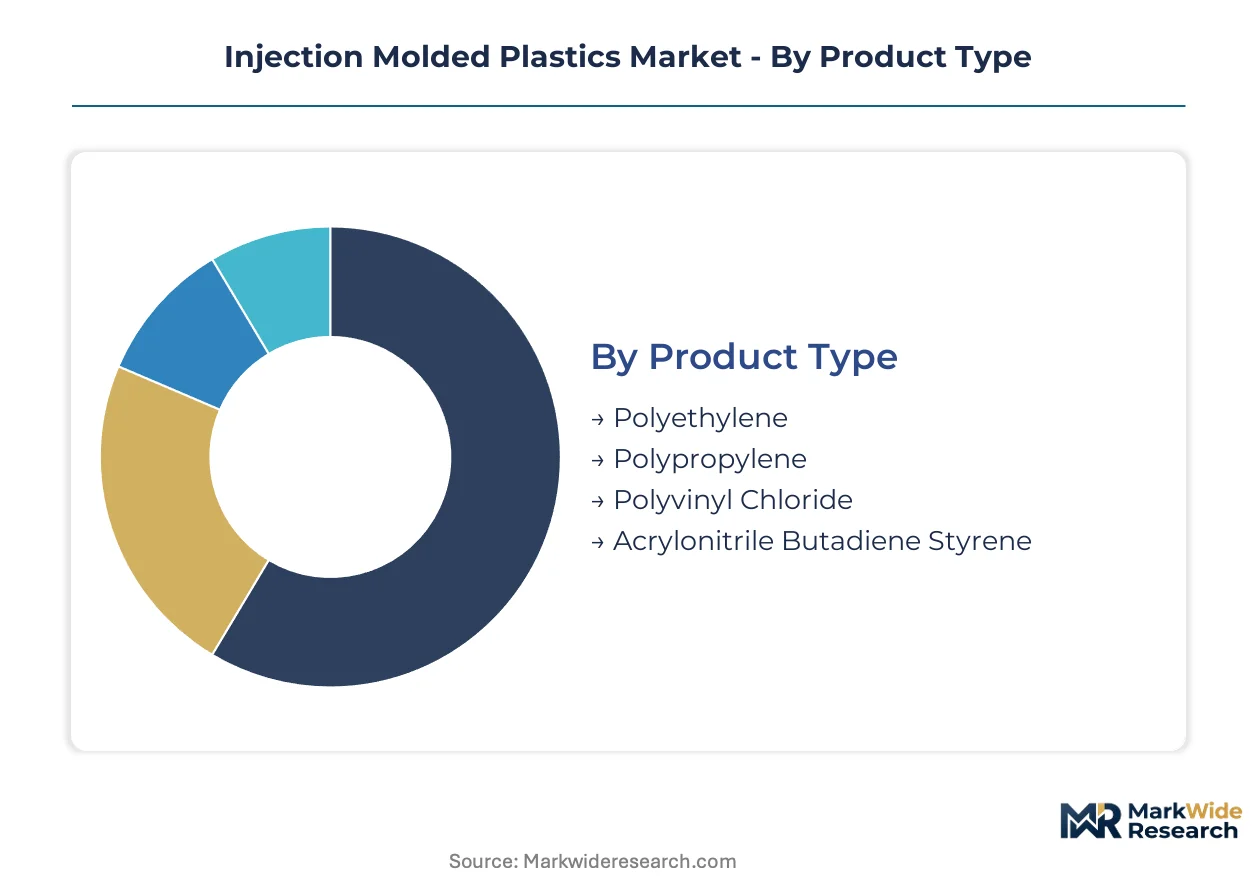
Segmentation in injection molded plastics reveals how cycle economics, regulatory thresholds, and tooling amortization rates fragment purchasing behavior across converter tiers. Resin selection and distribution channel choices diverge sharply between high-volume automotive programs and low-lot medical device qualifications.
Product Type:
Polyethylene and polypropylene dominate high-cavitation packaging tools with sub-30-second cycles, while engineering resins like ABS and PVC lock into longer-run automotive and construction applications where tool complexity extends procurement timelines.
- Polyethylene:Linear low-density and high-density grades optimize thin-wall container molding with melt flow indices exceeding 30 g/10min. Food-contact certified recyclate demand from German and Chinese packaging converters is pulling post-consumer resin into virgin-competitive specifications.
- Polypropylene:Homopolymer and copolymer variants anchor automotive interior panels and battery module housings with density advantages over engineering resins. China's EV production clusters are absorbing flame-retardant compounded grades for thermal runaway containment applications.
- Polyvinyl Chloride:Rigid and flexible formulations serve construction piping and medical tubing with plasticizer-dependent property tuning. REACH Annex XVII phthalate restrictions are forcing compounders toward bio-based alternative plasticizers for European cable markets.
- Acrylonitrile Butadiene Styrene:High-gloss grades command premium positioning in consumer electronics housings and diagnostic device enclosures. Gamma-sterilizable transparent variants are capturing share in single-use surgical instrument handles.
Polyethylene anchors the volume base while polypropylene gains share at the steepest rate.
Application:
Automotive programs amortize multi-million-dollar tooling across million-unit annual volumes, whereas medical device applications absorb higher per-part costs through regulatory-certified process validation.
- Automotive Components:Structural load-bearing brackets and powertrain housings demand glass-filled polyamides and long-fiber thermoplastics with creep resistance above 120°C. German and Chinese OEMs are consolidating resin procurement through direct call-off agreements bypassing distributor intermediaries.
- Packaging Solutions:Thin-wall containers and closures optimize cycle economics through hot-runner systems and high-speed robotic extraction. US and Indian food-contact converters are integrating pyrolysis-derived recycled polypropylene to meet brand-owner sustainability commitments.
- Consumer Goods:Durable appliances and housewares balance aesthetic surface finish with cost-competitive homopolymer specifications. Japanese electronics brands specify high-flow ABS grades for television and gaming console enclosures.
- Medical Devices:Sterilization-compatible polycarbonate and ABS grades require ISO 13485 process validation and biocompatibility testing. US FDA and EU MDR compliance timelines extend supplier qualification to 18-24 months before volume awards.
Packaging Solutions generates the highest unit volumes while Automotive Components commands the steepest value-per-kilogram premiums.
End User:
Electronics and healthcare buyers impose the most stringent material certification protocols, while construction and aerospace purchasers prioritize batch-to-batch consistency over innovation velocity.
- Electronics:RoHS and REACH SVHC compliance mandates traceability of flame retardants and plasticizers through multi-tier supply chains. ECHA's SCIP database requirements are forcing full material disclosure for complex plastic articles sold into European markets.
- Healthcare:Gamma and e-beam sterilization compatibility constrains resin selection to specific polycarbonate and ABS grades with validated color stability. US FDA 21 CFR compliance and EU MDR technical documentation requirements extend development cycles.
- Construction:Pressure-rated PVC piping and weatherable siding compounds must meet national building codes with decades-long service life specifications. China's GB standards and India's BIS certification create divergent testing requirements for regional suppliers.
- Aerospace:Flame-smoke-toxicity specifications limit resin selection to inherently halogen-free or phosphorous-modified grades. Continuous fiber-reinforced thermoplastic composites are displacing thermoset prepregs in interior panel applications.
Healthcare end-use absorbs the longest qualification cycles while Electronics expands most quickly on 5G infrastructure and wearable device demand.
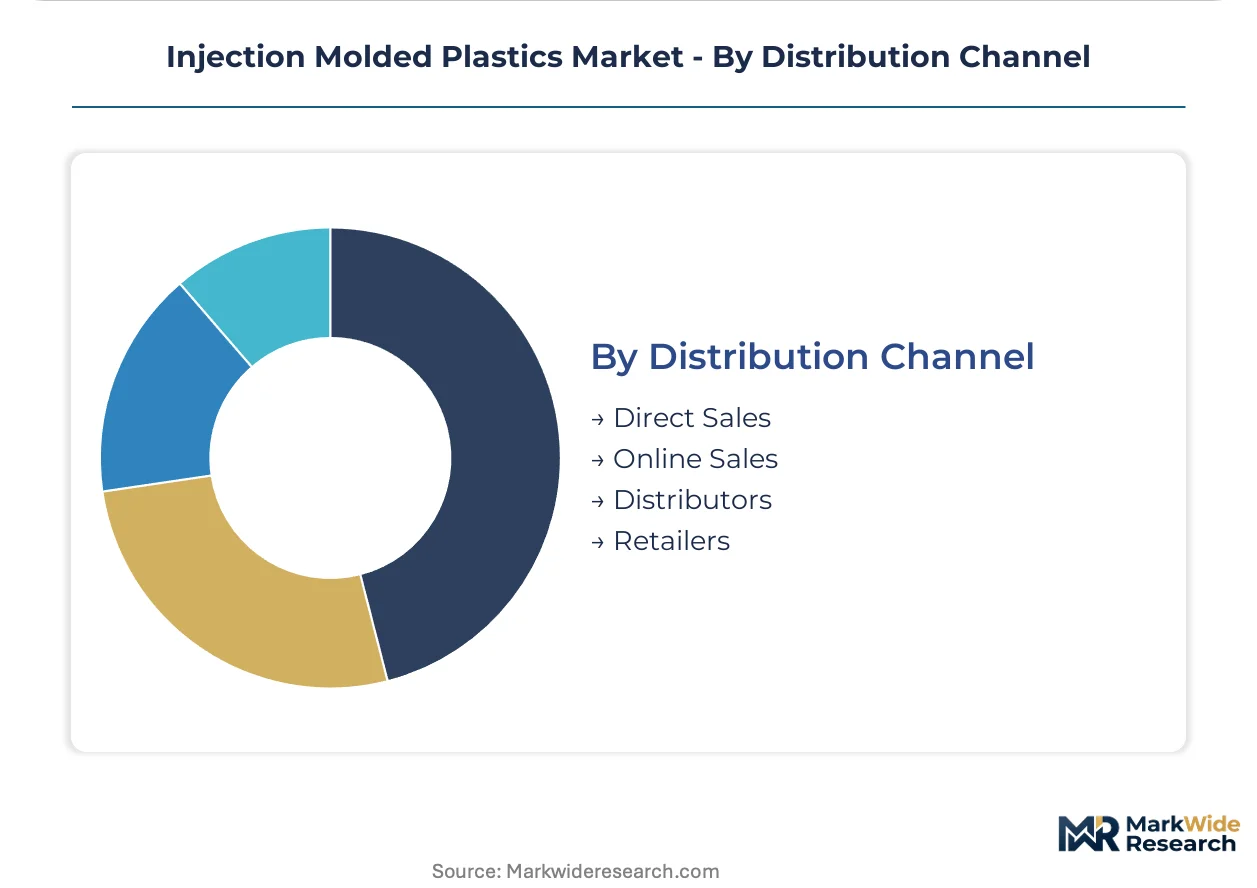
Distribution Channel:
Channel selection correlates with order predictability and technical service intensity, with direct sales capturing program-based automotive accounts and distributors serving fragmented converter bases.
- Direct Sales:Long-term supply contracts with tier-one automotive suppliers include consignment inventory and line-side delivery commitments. Dow and BASF anchor direct relationships through technical service teams embedded at customer manufacturing sites.
- Distributors:Regional stocking points serve small-to-mid converters with just-in-time resin delivery and credit terms. European distributors are consolidating as REACH compliance costs eliminate sub-scale compounders from the supplier base.
- Online Sales:E-procurement platforms capture standard grades from buyers with established material specifications and reduced technical support needs. Chinese B2B marketplaces are aggregating spot resin purchases from packaging converters.
- Retailers:Limited to consumer-facing small-lot sales of filament, prototyping resins, and hobbyist molding supplies. Retail channel penetration remains marginal outside North American maker communities.
Direct Sales captures the highest revenue concentration per account while Online Sales climbs fastest on digital procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: China's EV battery housing programs pull flame-retardant polypropylene at scale, while European converters absorb reformulated PVC compounds under REACH Annex XVII, and US medical device molders prioritize gamma-stable polycarbonate grades for surgical instruments.
China
Domestic EV production clusters in Ningbo and Shenzhen are absorbing specialized polypropylene compounds for thermal runaway containment in battery pack housings. MEE enforces stricter wastewater standards around petrochemical hubs, raising capital barriers for new compounding entrants. Local molders in the Yangtze River Delta are upgrading to electric and hybrid injection systems to meet dual carbon goals.
Germany
Automotive OEMs in Stuttgart and Munich are consolidating resin procurement through direct call-off agreements that bypass traditional distributor channels. REACH compliance costs are eliminating sub-scale compounders from the supplier base, concentrating volume with integrated materials science portfolios. Tooling fabrication capacity concentrates in precision machine shops around Stuttgart, creating procurement queues for complex multi-cavity molds.
United States
EPA regulations on volatile organic compound emissions are pushing processors toward electric presses and closed-loop material handling systems. Medical device converters in Minnesota and Massachusetts require ISO 13485 validation and biocompatibility testing for gamma-sterilizable grades. The US Gulf Coast propylene supply faces margin instability from naphtha-cracking economics and PDH unit outages.
India
PLI scheme incentives for automotive component localization are opening qualification windows for global compounders with in-country compounding assets. BIS certification creates divergent testing requirements for pressure-rated PVC piping and construction compounds. Gujarat and Maharashtra industrial corridors are attracting molders serving domestic appliance and two-wheeler OEMs.
Japan
Electronics brands specify high-flow ABS grades for television and gaming console enclosures, pulling premium resin specifications from domestic compounders. METI guidance on carbon intensity is reshaping feedstock sourcing decisions for packaging converters. Precision mold fabrication in Nagoya and Osaka maintains 16-24 week lead times for complex multi-cavity family tools.
Injection Molded Plastics Market Vendor Landscape
Capability concentration sits with integrated materials science portfolios; scale advantage sits with multi-continental manufacturing footprints. The market structures around three tiers: petrochemical majors with captive resin supply, specialized engineering resin compounders, and regional distributors serving fragmented converter bases. Dominant competitive moves include backward integration into pyrolysis-derived feedstocks and embedded technical service teams at customer manufacturing sites.
Within the integrated petrochemical tier, BASF SE and Dow Inc. exemplify archetypes anchored by materials science breadth and long-term automotive supply contracts. LyondellBasell Industries occupies a position defined by manufacturing scale across multiple continents and feedstock flexibility. These three entities represent the structural poles around which mid-cap compounders and regional distributors organize their competitive positioning.
| Leading Market Players |
|---|
| BASF SE |
| Dow Inc. |
| DuPont |
| SABIC |
| LyondellBasell Industries |
| Huntsman Corporation |
| INEOS Group |
| Covestro AG |
| HTI Plastics |
| Others |
Supply Flow & Price Mechanics
Yangtze River Delta port congestion and trans-Pacific container rates transmit cost volatility directly into polypropylene compounder margins, concentrating pricing power with integrated petrochemical majors while forcing smaller molders toward consignment inventory arrangements with automotive OEMs. This freight corridor's turbulence amplifies the divergence between long-term contract stability and spot market exposure across converter tiers.
Pricing Analysis
Long-term offtake agreements dominate automotive supply relationships, with BASF and Dow anchoring multi-year contracts that include consignment inventory and line-side delivery commitments. Price differentiation separates REACH-certified medical grades from standard packaging resins, with gamma-sterilizable polycarbonate commanding substantial premiums over commodity polypropylene. Cost compression in construction-grade PVC intensifies as bio-based plasticizer reformulations raise input costs without corresponding price recovery. Tier-one automotive buyers exhibit lowest price sensitivity due to qualification lock-in, while small packaging converters face acute margin pressure from resin volatility.
Supply Chain Analysis
Tariff exposure between the United States and China dominates strategic planning for electronics housings and automotive component sourcing, with compounders restructuring regional manufacturing footprints to preserve market access. Feedstock supply concentrates in Saudi Arabia, the United States, and China, with naphtha-cracking economics and PDH unit outages injecting instability into propylene availability. Raw material flows draw from Middle Eastern ethane, US shale gas, and Asian coal-to-chemicals complexes, creating divergent cost structures across regional production hubs. Single-source vulnerability in German and Japanese precision mold fabrication creates procurement bottlenecks for complex multi-cavity tools. Distribution runs through direct sales for automotive programs and regional distributors for fragmented converter bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Injection molded plastics sits in early-cycle expansion as EV battery enclosure programs accelerate engineered resin adoption faster than historical metal-to-plastic conversion timelines. Flame-retardant polypropylene for thermal runaway containment represents a structural demand inflection with multi-year visibility.
For Market Incumbents: Build captive pyrolysis feedstock capacity to secure food-contact certified recycled resin supply ahead of brand-owner sustainability mandates. Deepen technical service embedding at Chinese and German automotive manufacturing sites to defend against emerging compounders with localized compounding assets. Consolidate distributor relationships as REACH compliance costs eliminate sub-scale European compounders from the supplier base. For New Entrants and Emerging Players: Build out in-country compounding capacity in Gujarat and Maharashtra to capture PLI scheme automotive localization incentives before global majors complete qualification cycles. Target medical device sterilization-compatible grades where 18-24 month FDA and EU MDR timelines deter rapid incumbent response. Lead with ISO 13485 process validation capabilities as the go-to-market differentiator against commodity resin distributors. For Investors and Strategic Acquirers: Specialized engineering resin compounders with IATF 16949 certification and existing automotive qualification track records represent the most defensible acquisition archetype in this consolidation phase. Long-term viability rests on backward integration into chemical recycling feedstocks and embedded customer technical service relationships. Watch for inflection in pyrolysis-derived naphtha cost parity against virgin feedstocks as the signal for recycled resin margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pyrolysis Feedstocks | Chemical recycling capacity secures food-contact certified recycled polypropylene for packaging converters ahead of brand-owner mandates. |
| Long-term Supply Agreement | Direct call-off contracts with BMW and Volkswagen consolidate resin procurement and bypass distributor intermediaries in German automotive supply chains. |
| Capacity Expansion | Electric and hybrid injection system upgrades in Ningbo and Shenzhen align molders with China's MEE emission standards and dual carbon goals. |
| Joint Venture | Localized compounding partnerships in Gujarat capture PLI scheme incentives while navigating BIS certification requirements for pressure-rated PVC piping. |
| Green Manufacturing Transition | Electric press adoption and closed-loop material handling systems satisfy EPA volatile organic compound regulations for US processors. |
Methodological Framework
Initial hypotheses were tested against primary input from plant managers at tier-one automotive molders, procurement leads at packaging converters, technical R&D directors at compounders, and distribution channel partners across European and Asian markets, then refined against secondary validation from customs and trade data, ACC and Cefic industry reports, SEC 10-K filings, and vehicle production databases. Bottom-up resin demand modeling by application and grade tier was cross-checked against top-down macroeconomic drivers and regional automotive production forecasts.
Demand-supply balance dynamics across the analysis window were modeled through segmentation by resin type, end-use industry, regulatory certification tier, and regional production hub. CAGRs were derived from iterative reconciliation of historical consumption patterns with projected EV battery enclosure penetration, REACH reformulation timelines, and medical device sterilization grade adoption curves. Feedstock cost trajectories and tooling capacity constraints were integrated as boundary conditions.
Stress conditions across propylene feedstock volatility, German mold fabrication lead times, and automotive qualification cycle extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect assumptions about regulatory enforcement consistency and brand-owner sustainability commitment durability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
North America Plastic Bottles Market
Plastic Packaging
Brazil Plastic Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Japan Plastic Packaging Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Morocco Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Plant-Based Plastic Packaging Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
PET Clamshell Market