
 Thailand Plastic Bottles Market | 2026-2036
Thailand Plastic Bottles Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand Plastic Bottles Market Insights
Lightweighting-as-a-service is expanding as Thai converters bundle design optimization with multi-year supply contracts. Victor Group leverages captive resin compounding to lock in margin across PET and HDPE grades. ALPLA Group anchors its position through blow molding automation at plants in Pathum Thani and Rayong. Amcor Group GmbH differentiates via pharmaceutical-grade barrier bottles that meet ASEAN harmonized standards.
Plastic bottles are hollow thermoplastic containers formed through extrusion blow molding, injection stretch blow molding, or reheat stretch blow molding, typically ranging from 10 milliliters to 20 liters in capacity and engineered for containment, distribution, and shelf stability of liquid and semi-solid contents. PET dominates the product type landscape due to its clarity, barrier performance, and established recycling stream in Thailand, while HDPE occupies the chemical and personal care segments where opacity and stress crack resistance command premium positioning. Closure type selection tracks application severity, with screw caps retaining share in carbonated beverages and flip tops gaining traction in on-the-go personal care formats.
Thailand's Ministry of Natural Resources and Environment enforces plastic waste management rules under the BCG economic model, while the Thai Industrial Standards Institute mandates TIS specifications for food-contact plastics, and the Pollution Control Department phases in extended producer responsibility obligations that reshape converter investment timelines. Stakeholders must monitor how deposit-return scheme pilots in Bangkok and Chiang Mai redirect collection infrastructure economics before scaling rPET content commitments.
Market Dynamics
Thailand's Bio-Circular-Green economy agenda is compressing virgin resin demand while mandating rPET integration, forcing converters to reconfigure compounding lines and secure food-grade flake supply ahead of enforcement deadlines.
Growth Catalysts
- Extended Producer Responsibility:Thailand's Pollution Control Department mandates producer-funded collection infrastructure, redirecting capital toward closed-loop systems and domestic recycling capacity.
- ASEAN Harmonized Standards:Pharmaceutical-grade barrier bottles meeting regional specifications unlock cross-border supply contracts for Thai converters serving Southeast Asian drug manufacturers.
- rPET Blow Molding:Reheat stretch blow molding lines retrofitted for 30-50% recycled content run rates enable beverage bottlers to meet BCG compliance without sacrificing clarity.
Market Restraints
- Food-Grade Flake Scarcity:Domestic collection infrastructure yields insufficient PET flake purity for bottle-to-bottle applications, forcing reliance on imported feedstock priced in volatile USD terms.
- Pathum Thani Converter Cluster:Blow molding capacity concentrates within a 50-kilometer corridor, creating logistics bottlenecks and single-source vulnerability for Greater Bangkok filling plants.
- HDPE Substitution Ceiling:Polyethylene terephthalate clarity requirements in carbonated beverages limit HDPE penetration despite its superior stress crack resistance in chemical applications.
Strategic Opportunities
- Chiang Mai Collection Pilot:Deposit-return scheme trials in Thailand's northern economic hub test reverse logistics models replicable across secondary cities lacking formal waste streams.
- Personal Care Flip-Top Formats:On-the-go consumption patterns in Thai urban centers drive demand for single-handed dispensing closures requiring specialized injection molding tooling.
- Lightweighting Bundling:Design optimization services packaged with multi-year supply contracts lock in converter margins while reducing resin consumption per unit.
Industry Challenges
- Food-Contact Certification Timelines:Thai Industrial Standards Institute TIS testing protocols for recycled content bottles extend qualification cycles, delaying rPET product launches.
- Barrier Coating Integration:Plasma-enhanced chemical vapor deposition systems for pharmaceutical bottles require cleanroom retrofit investments beyond mid-cap converter balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand Plastic Bottles Market |
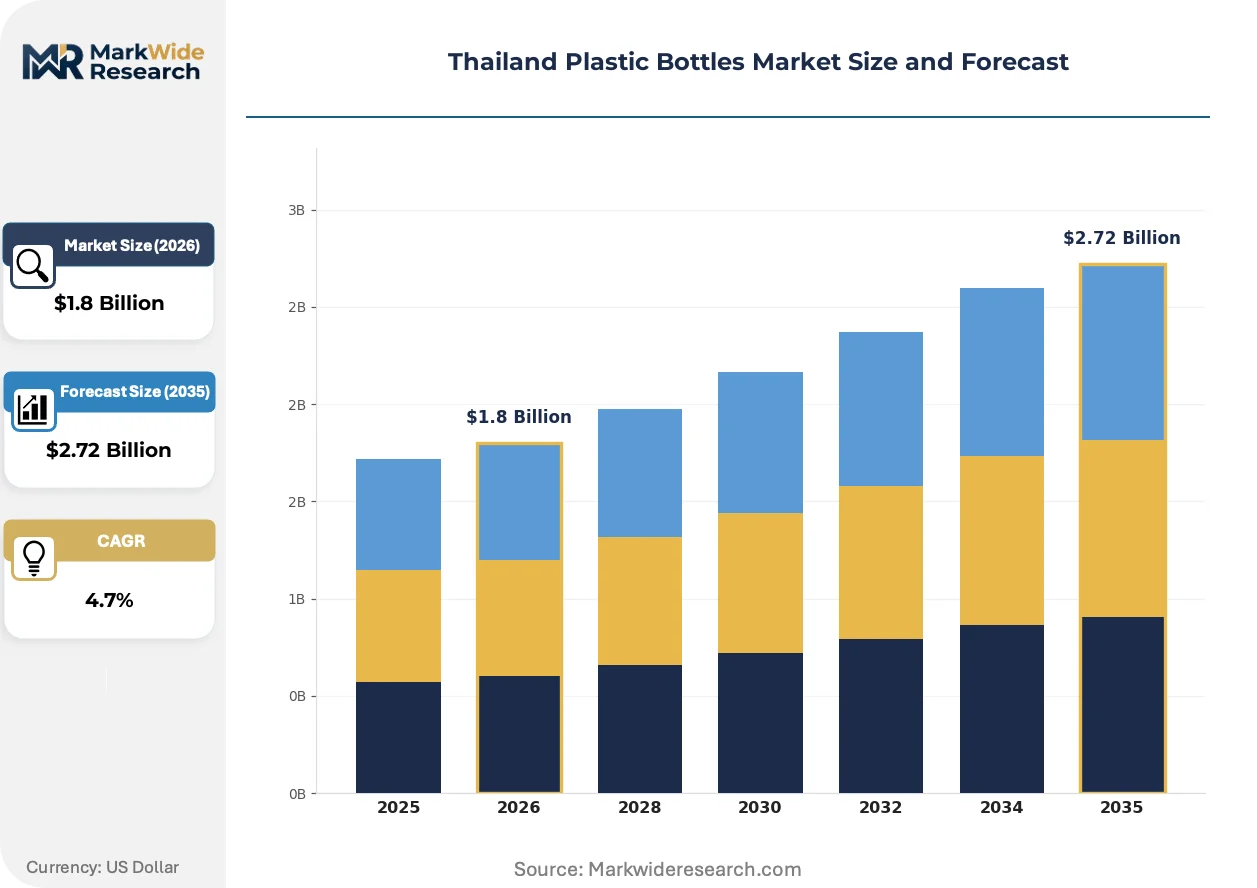
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PET, HDPE, LDPE, PVC Closure Type: Screw Cap, Flip Top, Snap Cap, Others Application: Consumer Goods, Food & Beverage, Pharmaceuticals, Personal Care End User: Retail, Wholesale, E-commerce, Industrial |
| Companies Covered | Union Thai Polyplast Co., Ltd., Victor Group, Berli Dynaplast Co., Ltd., ALPLA Group, Amcor Group GmbH, AGROPACK INDUSTRY CO LTD, Thai Viwat Plastic Industry, THAI PET INDUSTRIAL COMPANY LIMITED, Berry Global Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand Plastic Bottles Market Trends and Innovations
Digital manufacturing controls and materials science advances are compressing development cycles for Thai bottle converters, while regulatory pressure on recycled content accelerates process innovation.
Reheat stretch blow molding with infrared preform heating is rewriting quality consistency benchmarks for rPET containers. Beverage bottlers in Greater Bangkok are retrofitting lines at 15-20% annual rates to handle 30-100% recycled content without haze defects. This thermal precision is enabling food-grade bottle production from lower-purity domestic flake, reducing import dependency for Thai converters.
Thailand's Ministry of Natural Resources and Environment enforces plastic waste management rules under the BCG economic model with escalating recycled content floors. The Pollution Control Department's extended producer responsibility obligations reshape converter investment timelines toward collection infrastructure ownership. Beverage and personal care segments face the steepest compliance curves, with filling plants demanding supply chain documentation from resin to retail shelf.
Buyer concentration among Thai beverage conglomerates is consolidating procurement decisions toward integrated design-to-delivery contracts. Single-source relationships with captive compounding capabilities are displacing spot-market resin purchasing in Greater Bangkok. This vendor consolidation is most visible in carbonated soft drink and bottled water categories, where annual volume commitments exceed 500 million units.
Thailand Plastic Bottles Market Segmentation
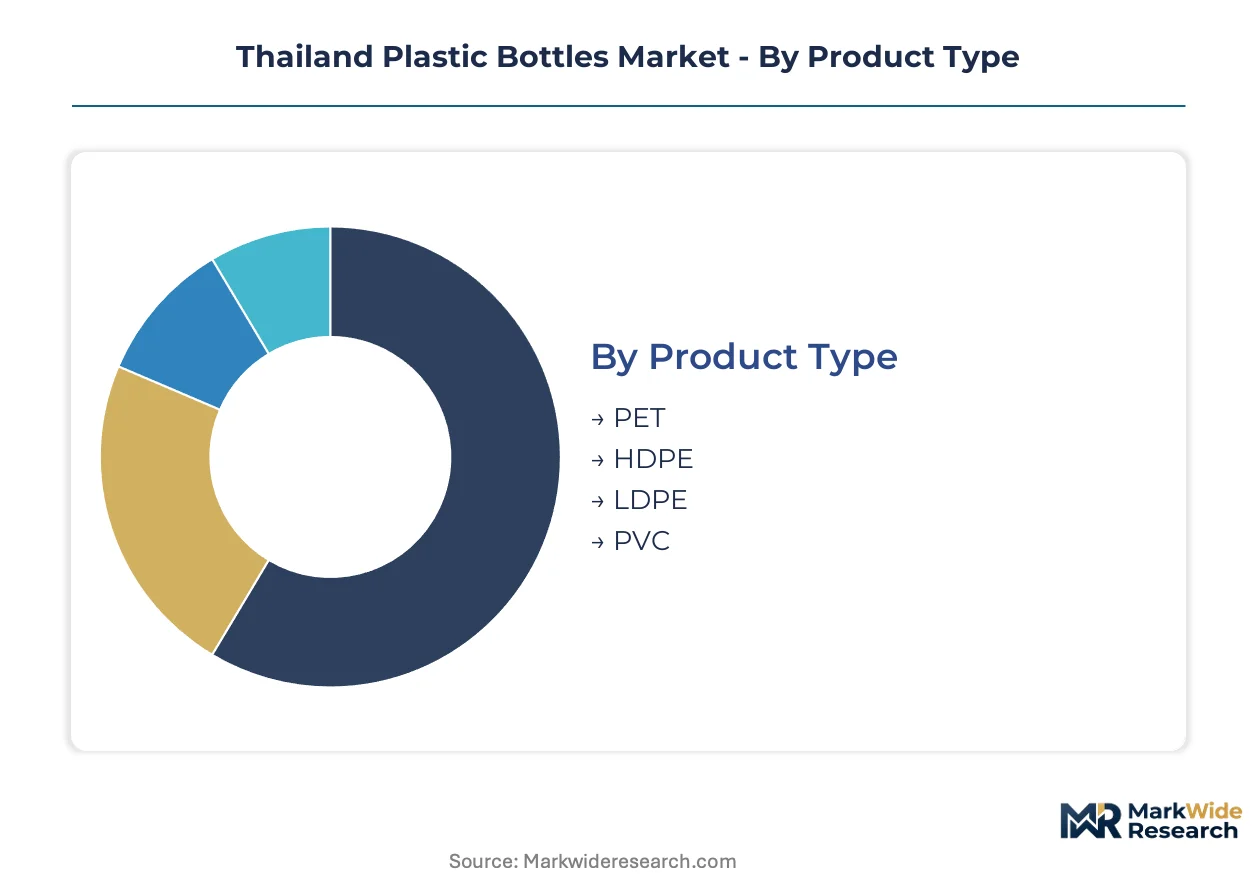
Thailand's plastic bottles market fragments across material chemistry, dispensing mechanics, and channel economics. Each segmentation layer reveals distinct margin profiles and regulatory exposure under the BCG economy framework.
Product Type:
Customization intensity spans from commodity resin grades to engineered barrier specifications, with converter investment thresholds rising sharply at the premium end.
- PET:Polyethylene terephthalate delivers optical clarity and carbonation barrier performance through reheat stretch blow molding. Beverage bottlers in Greater Bangkok specify PET for carbonated soft drinks and bottled water where shelf visibility drives purchase decisions. Thai Industrial Standards Institute TIS food-contact certification requirements favor established PET recycling streams over experimental polymers.
- HDPE:High-density polyethylene occupies chemical and personal care applications where stress crack resistance and opacity outweigh clarity requirements. Blow molding converters in Pathum Thani and Rayong run HDPE for household cleaners and industrial solvents. The material's lower moisture barrier limits penetration into carbonated beverage segments despite superior drop impact resistance.
- LDPE:Low-density polyethylene serves squeeze dispensing formats and flexible tube laminations where conformability matters more than structural rigidity.
- PVC:Polyvinyl chloride retains niche positioning in pharmaceutical blister packs and certain chemical containers despite environmental scrutiny under Pollution Control Department guidelines.
Most installed capacity flows through PET. Expansion is steepest in HDPE as chemical and personal care bottlers diversify beyond beverage-dependent converters.
Closure Type:
Mechanism selection tracks consumption occasion and单手操作性 requirements, with premium differentiation concentrated in convenience-oriented formats.
- Screw Cap:Threaded closures dominate carbonated beverage and bulk chemical applications where hermetic seal integrity prevents pressure loss or spillage. Thai filling plants specify 28mm PCO neck finishes for standardization across bottling lines. The format's maturity limits margin expansion despite volume concentration.
- Flip Top:Hinged dispensing closures command tooling premiums for on-the-go personal care and condiment applications. Bangkok's urban commuter patterns drive demand for single-handed operation in travel-size shampoo and hand sanitizer formats. Specialized injection molding requirements create supplier stickiness once qualification cycles complete.
- Snap Cap:Press-fit closures serve single-serve dairy and juice portions where resealability is secondary to cost minimization.
- Others:Pump dispensers, trigger sprayers, and child-resistant formats address pharmaceutical and household chemical safety mandates.
Screw cap volumes anchor converter revenue. Flip top applications are climbing the fastest as Thai personal care brands chase convenience positioning.
Application:
Regulatory stringency and barrier requirements create tiered qualification barriers that segment converter capabilities.
- Consumer Goods:Non-food containers for household products and industrial chemicals emphasize chemical compatibility and drop resistance over optical properties. HDPE blow molders in Thailand's Eastern Economic Corridor serve this segment with standardized neck finishes and commodity pricing.
- Food & Beverage:The largest demand pool spans carbonated drinks, bottled water, edible oils, and sauces requiring oxygen and moisture barrier performance. rPET integration mandates under the BCG economy are reshaping procurement specifications toward documented recycled content.
- Pharmaceuticals:Barrier bottles meeting ASEAN harmonized standards require cleanroom manufacturing and extractables testing. Plasma-enhanced coating systems for moisture-sensitive drug products sit beyond mid-cap converter capital access.
- Personal Care:Aesthetic differentiation through custom colors, soft-touch finishes, and ergonomic shaping commands design service bundling from Thai converters.
Food and beverage applications absorb the majority of Thai blow molding output. Pharmaceutical barrier formats are gaining share fastest as regional drug manufacturing concentrates in Thailand.
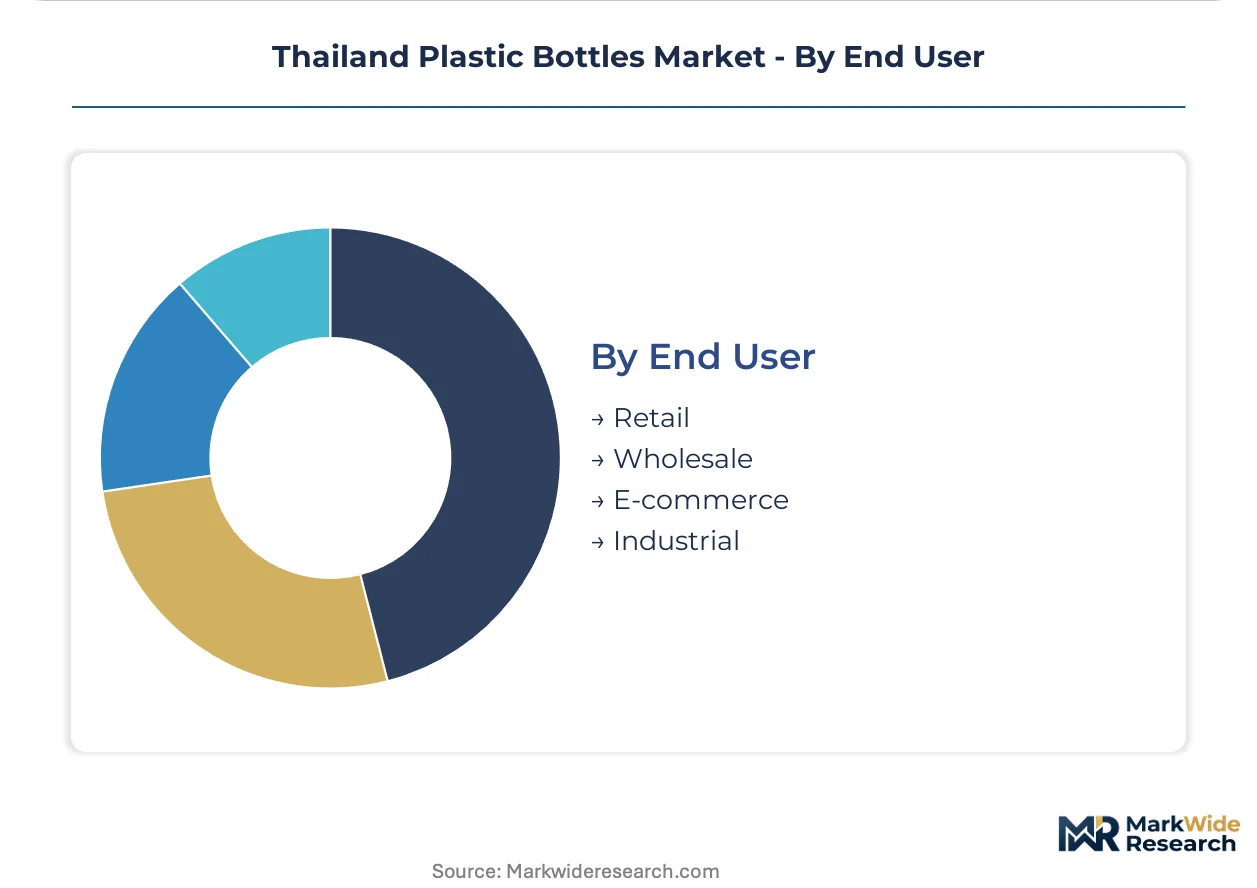
End User:
Channel structure determines order cadence, customization depth, and logistics configuration for converter operations.
- Retail:Hypermarket and convenience store chains drive standardized SKUs with high volume predictability and stringent shelf-ready packaging requirements. Central Group and CP All procurement specifications influence converter design priorities.
- Wholesale:Institutional and foodservice buyers prioritize unit cost over aesthetic refinement, favoring HDPE formats in larger capacities.
- E-commerce:Direct-to-consumer shipment resilience demands enhanced drop resistance and right-sized dimensional optimization to minimize freight cost per unit.
- Industrial:Chemical processors and contract fillers specify UN-certified containers with documented traceability for hazardous material handling.
Retail channel volumes dominate converter scheduling. E-commerce specifications are expanding most quickly as Thai digital grocery penetration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Converters migrate capacity toward jurisdictions with softer rPET mandates and lower extended producer responsibility fees, creating regulatory-arbitrage corridors that reshape procurement geography across Southeast Asia.
Thailand
Thailand's Bio-Circular-Green economy agenda mandates 30% recycled content floors for beverage packaging by 2030. The Pollution Control Department enforces producer-funded collection infrastructure that redirects converter capital toward closed-loop systems. Blow molding capacity clusters in Pathum Thani and Rayong provinces, where ALPLA Group and Thai PET Industrial operate integrated plants serving Greater Bangkok filling operations.
Vietnam
Vietnam's Ministry of Natural Resources and Environment drafts circular economy decrees modeled on Thai BCG frameworks but with delayed enforcement timelines. Foreign converters target Da Nang and Binh Duong industrial zones to supply ASEAN beverage brands seeking lower compliance costs. The country's informal waste collection sector yields inconsistent flake quality, delaying food-grade rPET adoption.
Indonesia
Indonesia's National Plastic Action Roadmap targets 70% reduction in ocean plastic leakage through domestic recycling infrastructure. The Ministry of Environment and Forestry coordinates with brand owners to fund collection systems in Java and Sumatra. Jakarta-Bandung manufacturing corridor attracts mid-cap converters from Thailand seeking tariff advantages under ASEAN trade frameworks.
Malaysia
Malaysia's Department of Environment enforces plastic waste import bans that redirect regional flake trade flows. Selangor and Penang states host Japanese and Taiwanese converter joint ventures serving halal-certified beverage exports. The country's dual-track certification system for food-contact recycled plastics creates qualification bottlenecks for Thai exporters.
Philippines
Philippine plastic bottle demand concentrates in Metro Manila and Cebu manufacturing zones serving domestic beverage consumption. The National Solid Waste Management Commission lacks enforcement capacity for extended producer responsibility, preserving virgin resin cost advantages. Thai converters maintain trading relationships but limit fixed-asset exposure pending regulatory clarity.
Thailand Plastic Bottles Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated resin-to-bottle operators commanding premium positioning in rPET-compliant supply chains. The vendor base concentrates around three capability tiers: multinational converters with captive compounding, regional specialists with design-to-delivery bundling, and commodity blow molders competing on unit economics. Strategic differentiation flows from backward integration into resin sourcing, lightweighting engineering services, and pharmaceutical-grade barrier certifications. Competitive intensity manifests through multi-year supply contract lock-ins and geographic clustering near filling plant corridors.
Among Thailand-based fabricators, Union Thai Polyplast Co., Ltd. and Thai Viwat Plastic Industry occupy positions within the mid-cap specialist tier, while Victor Group exemplifies the integrated resin-compounding archetype. ALPLA Group and Amcor Group GmbH represent multinational converters with regional hub strategies. These five entities collectively illustrate the market's structural segmentation between domestic specialists and global packaging platforms.
| Leading Market Players |
|---|
| Union Thai Polyplast Co., Ltd. |
| Victor Group |
| Berli Dynaplast Co., Ltd. |
| ALPLA Group |
| Amcor Group GmbH |
| AGROPACK INDUSTRY CO LTD |
| Thai Viwat Plastic Industry |
| THAI PET INDUSTRIAL COMPANY LIMITED |
| Berry Global Inc |
| Others |
Pricing and Supply Chain Analysis
rPET integration mandates under Thailand's BCG economy agenda are forcing converters to absorb food-grade flake premiums or pass costs to beverage bottlers, reshaping contract structures toward multi-year supply lock-ins that bundle lightweighting services with resin price hedging.
Pricing Analysis
Direct-to-filler contracts command steeper discounts than distributor-mediated channels serving smaller personal care brands. Three-tier pricing structure across pharmaceutical-grade barrier, food-contact certified, and industrial commodity bottles reflects TIS certification investment and cleanroom manufacturing overhead. Cost compression in standard PET beverage containers is intensifying because imported flake volatility and domestic collection infrastructure gaps squeeze converter margins. Wholesale institutional buyers exhibit highest price sensitivity, while pharmaceutical barrier bottle procurement prioritizes ASEAN harmonized compliance over unit cost.
Supply Chain Analysis
Food-grade PET flake supply rests on Thai domestic collection pilots, imported Southeast Asian feedstock, and Japanese reprocessing technology for pharmaceutical-grade purity. Virgin resin compounding draws from Thai petrochemical complexes and Singaporean polymer traders, while barrier coating systems for drug containers source from German and Japanese specialty chemical producers. Single-source vulnerability concentrates in Pathum Thani's 50-kilometer converter corridor where ALPLA and Thai PET Industrial anchor capacity. Distribution runs through filling plant co-location in Greater Bangkok, with secondary logistics nodes emerging in Rayong's Eastern Economic Corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thailand's plastic bottles market offers margin expansion through captive rPET compounding and pharmaceutical barrier certification premiums that offset commodity PET price erosion.
For Market Incumbents: Cement backward integration into food-grade flake washing and compounding to lock in margin against imported feedstock volatility. Secure TIS certification for 100% rPET bottle-to-bottle applications ahead of BCG enforcement deadlines. Pathum Thani cluster congestion and emerging Vietnamese converter competition represent immediate threats requiring capacity diversification toward Rayong.
For New Entrants and Emerging Players: Begin with Chiang Mai deposit-return scheme logistics contracts to establish collection infrastructure relationships before scaling to bottle production. Personal care flip-top formats for Bangkok's urban commuter segment offer lowest qualification barriers and fastest design-to-revenue cycles. Partner with Thai beverage conglomerates on lightweighting-as-a-service pilots to bypass capital-intensive blow molding equipment.
For Investors and Strategic Acquirers: Asymmetric upside sits with mid-cap converters possessing captive compounding and unfilled pharmaceutical barrier capacity. Long-term viability hinges on rPET integration depth and ASEAN cross-border supply relationships. Watch Pollution Control Department EPR fee schedules as the inflection trigger for consolidation toward integrated resin-to-bottle operators.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into rPET Compounding | Captive food-grade flake supply insulates margins from USD-denominated import volatility under BCG rules. |
| Pharmaceutical Barrier Certification Investment | ASEAN harmonized standards unlock cross-border contracts with Thai drug manufacturers expanding regional footprint. |
| Lightweighting-as-a-Service Bundling | Design optimization packaged with multi-year contracts locks in converter revenue while reducing resin consumption per unit. |
| Chiang Mai Collection Infrastructure Pilot | Deposit-return scheme participation establishes reverse logistics capabilities replicable across Thailand's secondary cities. |
| Rayong Eastern Economic Corridor Expansion | Geographic diversification beyond Pathum Thani cluster reduces logistics bottlenecks and single-source vulnerability. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged blow molding plant managers, beverage procurement leads at Thai conglomerates, Pollution Control Department policy officers, and pharmaceutical packaging regulatory specialists. Secondary validation drew from Thai Industrial Standards Institute TIS specifications, Pollution Control Department EPR draft regulations, customs trade data on PET resin imports, and SEC filings of listed packaging converters. Bottom-up capacity modeling across Pathum Thani and Rayong production clusters triangulated against top-down demand estimates from Central Group and CP All procurement patterns.
Historical reference periods anchored volume and value projections across the analysis window. Segmentation dimensions modeled include material chemistry tier, closure mechanism complexity, application barrier requirements, and end-user channel structure. CAGRs derived from converter capacity expansion announcements, filling plant retrofit timelines, and BCG mandate phase-in schedules. Forecast inputs incorporated rPET blow molding line retrofit rates and food-grade flake import dependency ratios.
Caveats apply where Pollution Control Department EPR enforcement delays or food-grade flake purity breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding domestic collection infrastructure scaling and ASEAN harmonized standard adoption timelines. A small set of named triggers—EPR fee levels, rPET import tariff adjustments, and pharmaceutical barrier coating technology access—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
US Plastic Packaging Market
Plastic Packaging
Plastic Water Storage Tank Market
Plastic Packaging
South Africa Flexible Packaging Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
France Plastic Packaging Market
Plastic Packaging
United States Plastic Packaging Films Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
UVI Stretch Films Market
Plastic Packaging
Poland Plastic Bottles Market
Plastic Packaging
PET Clamshell Market
Plastic Packaging
Injection Molded Plastics Market
Plastic Packaging
Europe BPA Free Plastic Market
Plastic Packaging
Shrink Plastic Films Market
Plastic Packaging
United States PET Packaging Market
Plastic Packaging
Indonesia Plastic Packaging Market