
 Mushroom Plastics Market | 2026-2036
Mushroom Plastics Market Size, Share, and Industry Trends Forecast 2026-2036
Mushroom Plastics Market Analytics
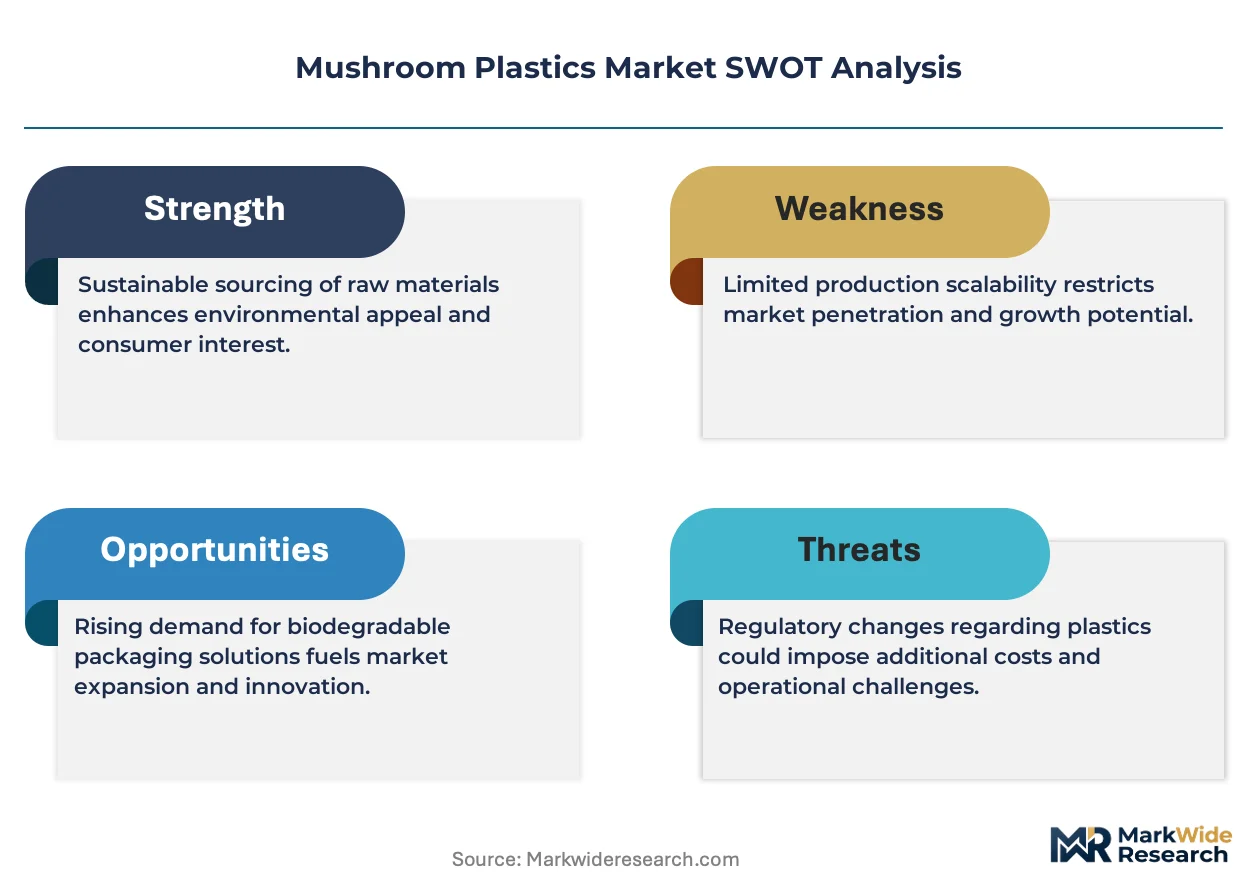
ASTM D6400 compostability certification is rotating competitive access in mushroom plastics, filtering suppliers by industrial biodegradation benchmarks. Ecovative Design LLC leverages mycelium cultivation expertise to anchor North American supply capacity. MycoWorks differentiates through luxury-grade material performance in consumer goods partnerships. Sealed Air Corporation extends distribution infrastructure across European packaging channels.
Mushroom plastics comprise mycelium-bound agricultural substrates that form rigid, lightweight composites through controlled fermentation, typically achieving densities between 0.08–0.15 g/cm³ for packaging-grade applications. These materials replace expanded polystyrene in protective packaging and thermal insulation systems where end-of-life compostability determines procurement decisions. Bio-based Packaging leads volume shipments as retail and electronics sectors mandate sustainable protective materials, while Construction applications represent the fastest-expanding segment as building codes integrate biogenic carbon accounting. Furniture applications occupy narrower premium positioning where aesthetic grain patterns command margin premiums over commodity foam substitutes.
FDA food-contact substance notifications govern mycelium packaging eligibility for direct food applications in the United States, while EFSA novel food and material assessments shape European market entry pathways. REACH compliance obligations for substrate additives and the EU Packaging and Packaging Waste Regulation are tightening permissible material footprints across member states. Stakeholders must monitor evolving composting infrastructure certification reciprocity between national standards bodies to anticipate which production locations will unlock cross-border commercial scale.
Market Dynamics
EU Green Deal packaging waste directives are compressing substitution timelines for petroleum-based foams, forcing material buyers to validate compostable alternatives before 2030 mandates take full effect. This regulatory pressure is concentrating procurement decisions around ASTM D6400 and EN 13432 certification pathways.
Growth Catalysts
- EU Packaging and Packaging Waste Regulation:Mandatory recycled content quotas and extended producer responsibility schemes are redirecting food packaging procurement toward mycelium-based protective materials that satisfy industrial compostability benchmarks.
- Biogenic carbon accounting in building codes:Construction sector sustainability scoring systems are incorporating cradle-to-grave carbon metrics that favor mycelium insulation over synthetic foams in commercial and residential developments.
- Germany's mycelium research clusters:Concentrated academic-industry collaboration around Berlin and Munich is accelerating strain optimization and substrate formulation for packaging-grade applications.
Market Restraints
- Agricultural substrate cost volatility:Hemp hurds, corn stalks, and sawdust compete with livestock bedding and biofuel feedstock markets, creating input price instability for mycelium cultivators.
- Composting infrastructure gaps:Industrial composting facility coverage remains concentrated in Northern Europe and select US coastal corridors, limiting end-of-life value proposition in Midwest American and Southern European markets.
- Expanded polystyrene incumbent lock-in:Existing molded foam tooling and established supplier relationships create switching friction for electronics and appliance manufacturers despite sustainability mandates.
Strategic Opportunities
- Underpenetrated French market:Lagging mycelium production capacity relative to Germany creates white space for facility investment serving Southern European packaging demand.
- Automotive interior panels:OEM sustainability scorecards are opening specifications for mycelium-based trim components that reduce vehicle lifecycle carbon footprints.
- Direct-to-grower supply contracts:Bypassing commodity substrate markets through captive agricultural partnerships is securing input cost stability for scaled producers.
Industry Challenges
- Fermentation technician scarcity:Controlled mycelium cultivation requires specialized skills spanning microbiology, agricultural science, and process engineering that outpace current vocational training pipelines.
- ASTM D6400 certification timelines:Industrial biodegradation testing cycles extend 180-270 days, delaying product launches and locking working capital in inventory.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mushroom Plastics Market |
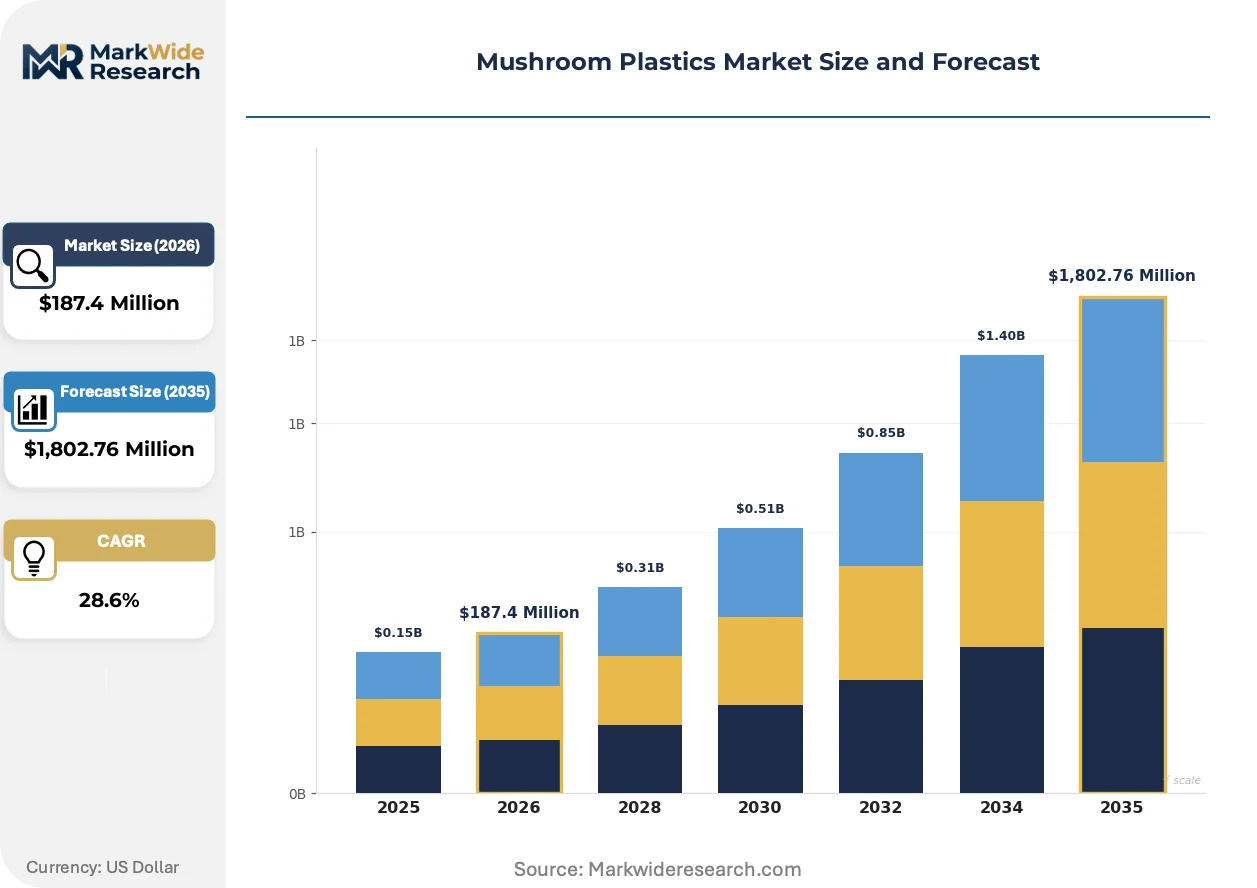
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $1,802.76 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bio-based Packaging, Insulation Panels, Furniture, Trays Application: Packaging, Construction, Automotive, Consumer Goods End User: Retail, Construction Companies, Food Industry, Electronics Material Grade: High Density, Low Density, Composite, Specialty |
| Companies Covered | Ecovative Design LLC, Sealed Air Corporation, Magical Mushroom Company, Grown Bio BV, MycoWorks, Shroom Labs, BioFab, Steelcase Inc., Mushroom Packaging, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mushroom Plastics Market Evolving Landscape
Process intensification in mycelium cultivation is collapsing production cycles while quality consistency improves. These advances are unlocking specification-grade applications beyond commodity packaging.
Precision environmental control systems are supplanting open-air grow room methods in commercial mycelium operations. Electronics manufacturers with zero-defect packaging requirements are adopting these closed-loop fermentation systems fastest. This technology shift is compressing batch-to-batch density variation from 15% to under 4%, enabling protective packaging for high-value semiconductor shipments.
REACH compliance obligations for substrate additives are tightening permissible chemical footprints across EU member states. ECHA substance restriction proposals targeting flame retardants and plasticizers are forcing reformulation of competing bio-based foams. Construction insulation suppliers are responding by accelerating pure mycelium formulations that avoid synthetic additive dependencies entirely.
Brand sustainability mandates are consolidating supplier rosters around certified compostable material providers. Food retailers with net-zero packaging commitments are replacing multi-material laminates with single-substrate mycelium solutions. This specification compression is most visible in German and Dutch supermarket private label programs where shelf-ready packaging must satisfy both performance and circularity audits.
Mushroom Plastics Market Segmentation
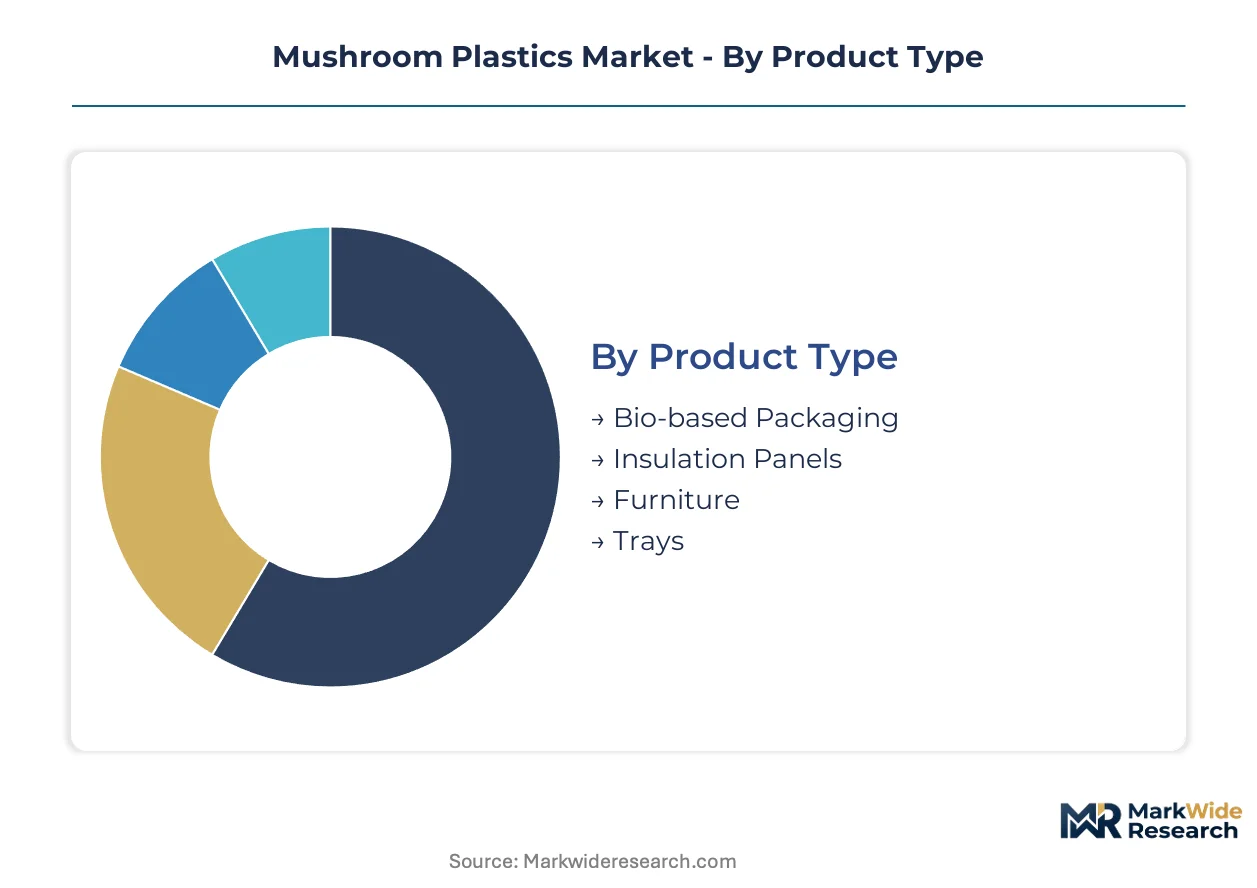
Mushroom plastics segment along performance specifications and end-use requirements that determine fermentation protocols and substrate formulations. Buyers select grades based on load-bearing needs, thermal properties, and compostability certification timelines.
Product Type:
Bio-based packaging moves through distributor networks serving electronics and appliance manufacturers with protective foam replacements. Insulation panels and furniture reach construction and retail channels through specification-driven procurement.
- Bio-based Packaging:Mycelium-bound agricultural substrates form rigid, lightweight protective structures with densities calibrated for shock absorption. Retail and electronics sectors in Germany and the Netherlands are scaling purchases as EU Packaging and Packaging Waste Regulation mandates tighten.
- Insulation Panels:Controlled-density mycelium composites achieve thermal resistance values competitive with synthetic foams while sequestering biogenic carbon. Construction applications in Germany are expanding most quickly as building codes integrate cradle-to-grave carbon accounting.
- Furniture:Aesthetic grain patterns and tactile surfaces command premium positioning in contract and residential interiors.
- Trays:Food-contact grade mycelium formulations serve single-use serving applications requiring FDA or EFSA compliance.
Bio-based packaging dominates installed base. Insulation panels are where expansion concentrates.
Application:
Cost tiers separate commodity protective materials from specification-grade building and automotive components. Packaging applications compete on unit economics against expanded polystyrene, while construction and automotive segments justify premium pricing through performance certification and sustainability scoring.
- Packaging:Protective foam replacement for electronics, appliances, and temperature-sensitive shipments. Food industry buyers in Germany validate ASTM D6400 and EN 13432 certification pathways ahead of 2030 mandates.
- Construction:Wall and roof insulation systems where biogenic carbon storage improves project sustainability ratings. German building code revisions favoring cradle-to-grave metrics are accelerating specification.
- Automotive:Interior trim panels and acoustic insulation where OEM sustainability scorecards drive material selection.
- Consumer Goods:Luggage inserts, footwear components, and personal care packaging with brand-led circularity commitments.
Packaging commands volume leadership. Construction delivers margin expansion.
End User:
Customer type determines order scale, certification requirements, and supply chain integration depth. Retail and electronics buyers prioritize protective performance and compostability verification, while construction companies negotiate project-based volume commitments.
- Retail:Supermarket private label programs in Germany and the Netherlands consolidate supplier rosters around certified compostable providers. Shelf-ready packaging must satisfy circularity audits and performance benchmarks simultaneously.
- Construction Companies:Commercial and residential developers in Germany source insulation panels through specification-based procurement tied to sustainability scoring systems.
- Food Industry:Direct food contact applications require FDA food-contact substance notifications or EFSA novel material assessments, extending validation timelines.
- Electronics:Zero-defect packaging requirements favor precision-controlled fermentation systems with batch-to-batch density variation under 4 percent.
Retail anchors current demand. Construction companies are where procurement volumes are scaling fastest.
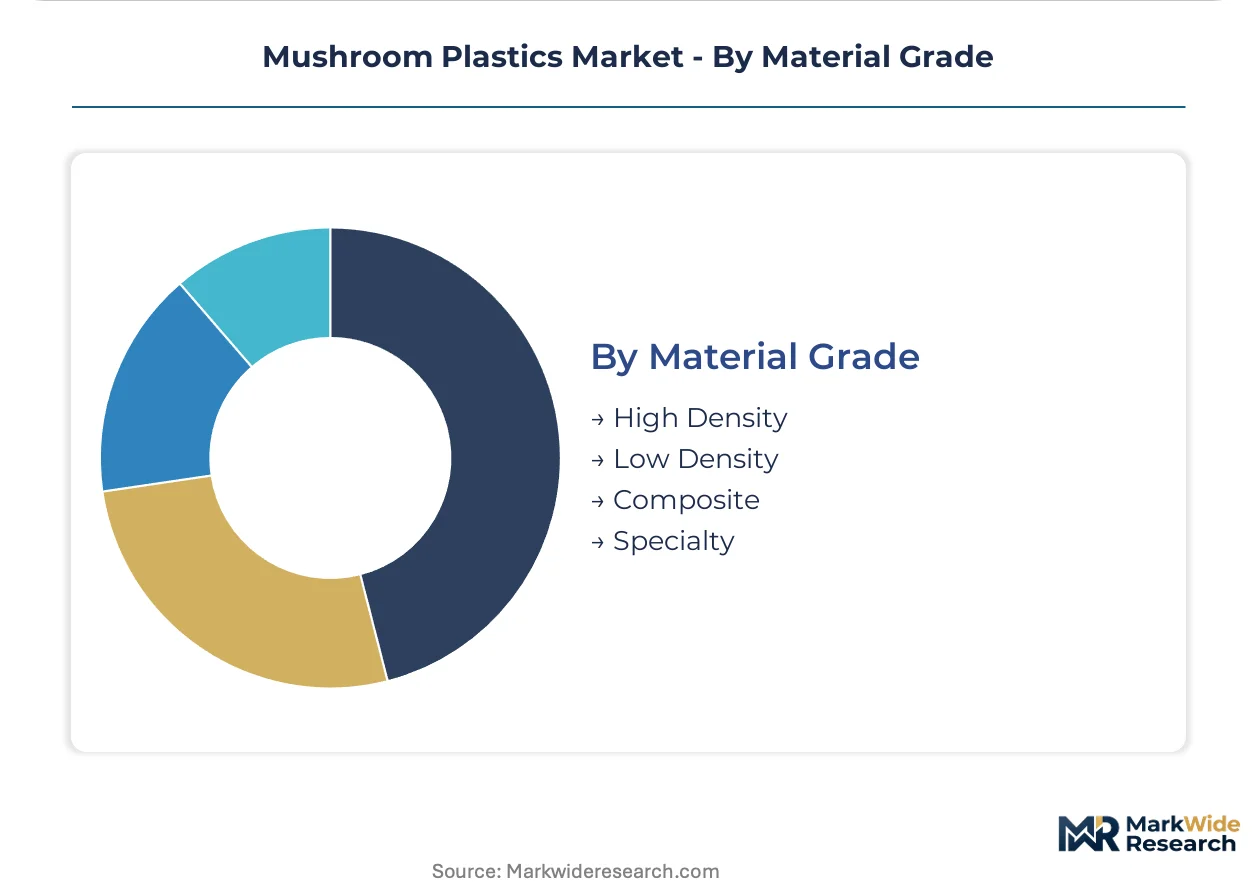
Material Grade:
Volume concentration sits with standard grades serving packaging applications, while specialty formulations capture margin in performance-critical construction and automotive segments. Density and additive content differentiate pricing tiers.
- High Density:Structural load-bearing applications requiring compression resistance above 200 kPa. Automotive interior panels and heavy-duty protective packaging specify these grades.
- Low Density:Lightweight protective structures for electronics and temperature-controlled shipments where thermal insulation and shock absorption balance against shipping weight.
- Composite:Mycelium substrates blended with natural fibers or bio-resins for enhanced mechanical properties in furniture and architectural applications.
- Specialty:Pure mycelium formulations avoiding synthetic additives to satisfy REACH compliance and ECHA substance restriction proposals targeting flame retardants.
Low density dominates shipment volumes. Specialty grades are where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Green Deal packaging waste directives are compressing substitution timelines across member states, forcing material buyers to validate compostable alternatives before 2030 mandates take full effect. Germany's mycelium research clusters and brand sustainability mandates are concentrating demand. Agricultural substrate cost volatility and composting infrastructure gaps create divergent regional adoption curves.
Germany
Food retailers and electronics manufacturers are scaling ASTM D6400-certified purchases ahead of EU Packaging and Packaging Waste Regulation enforcement. The Federal Environment Agency enforces extended producer responsibility schemes that redirect procurement toward industrial compostable materials. Berlin and Munich host concentrated academic-industry collaboration accelerating strain optimization for packaging-grade applications.
United States
Electronics manufacturers with zero-defect packaging requirements are adopting precision-controlled fermentation systems fastest. FDA food-contact substance notifications govern mycelium packaging eligibility for direct food applications, extending validation timelines. Industrial composting facility coverage concentrates in coastal corridors, limiting end-of-life value proposition in Midwest markets.
France
Lagging mycelium production capacity relative to Germany creates white space for facility investment serving Southern European packaging demand. EFSA novel food and material assessments shape market entry pathways for food-contact applications. The country's national packaging waste regulator enforces recyclability and compostability benchmarks that favor single-substrate mycelium solutions over multi-material laminates.
Netherlands
Supermarket private label programs are consolidating supplier rosters around certified compostable providers. REACH compliance obligations for substrate additives are tightening permissible chemical footprints. Randstad logistics hubs enable distribution infrastructure serving Northern European electronics and appliance manufacturers with protective foam replacements.
United Kingdom
Construction sector sustainability scoring systems are incorporating cradle-to-grave carbon metrics that favor mycelium insulation. The national environmental regulator implements packaging waste directives with recycled content quotas redirecting procurement. London-based brand sustainability mandates are driving specification compression in consumer goods packaging.
Mushroom Plastics Market Competitive Landscape
Player mix skews toward specialized mycelium cultivators with proprietary fermentation expertise rather than diversified chemical conglomerates. Market structure exhibits tiered concentration with a handful of scaled producers anchoring supply capacity alongside numerous regional fabricators. Strategic archetypes include research-intensive strain developers, brand-integrated design partners, and substrate-secured volume producers. Competitive moves center on captive agricultural partnerships securing input cost stability and certification acceleration compressing ASTM D6400 timeline exposure.
Within the research-intensive tier, Ecovative Design LLC and MycoWorks exemplify divergent positioning strategies. Ecovative anchors North American supply capacity through mycelium cultivation expertise, while MycoWorks occupies a premium position through luxury-grade material performance in consumer goods partnerships. Sealed Air Corporation represents the distribution-integrated archetype, extending established packaging channel infrastructure across European markets. These three companies collectively illustrate how technical specialization, brand alignment, and logistics scale define competitive positioning in early-stage material substitution markets.
| Leading Market Players |
|---|
| Ecovative Design LLC |
| Sealed Air Corporation |
| Magical Mushroom Company |
| Grown Bio BV |
| MycoWorks |
| Shroom Labs |
| BioFab |
| Steelcase Inc. |
| Mushroom Packaging |
| Others |
Value Network & Pricing Analysis
One-hundred-eighty to two-hundred-seventy day ASTM D6400 certification cycles lock working capital in inventory and compress supplier margins, concentrating pricing power with German and Dutch producers who have already secured industrial compostability verification. This lead-time burden intersects with agricultural substrate cost volatility to reshape competitive positioning around captive supply contracts and regional production clustering.
Pricing Analysis
Certification grade creates the primary spread, with ASTM D6400 and EN 13432 verified materials commanding premiums over uncertified alternatives. Three-tier pricing structure separates premium food-contact grades from standard packaging tiers and economy insulation variants. Cost compression in standard packaging runs through hemp hurd and corn stalk input markets competing with biofuel feedstock demand. Electronics manufacturers with zero-defect requirements show least price sensitivity, while commodity protective foam buyers in retail anchor the economy tier.
Supply Chain Analysis
Just-in-time substrate procurement dominates smaller cultivators, while scaled producers in Germany and the Netherlands maintain strategic stockpiles of hemp hurds and sawdust to buffer agricultural commodity swings. Geographic supply concentration centers on Germany, the Netherlands, and select US coastal corridors where composting infrastructure validates end-of-life claims. Mycelium cultivation draws from agricultural waste streams that compete with livestock bedding and biofuel markets, creating single-source vulnerability during harvest seasons. Distribution runs through electronics packaging distributors in Northern Europe and direct-to-brand relationships for furniture and consumer goods applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mushroom plastics sit in early-cycle expansion as EU Green Deal packaging mandates compress substitution timelines for petroleum-based foams ahead of enforcement deadlines. This regulatory tailwind accelerates penetration in food retail and electronics protective packaging where compostability certification unlocks procurement decisions.
For Market Incumbents: Shield margin position by deepening backward integration into captive hemp and corn stalk supply contracts in Germany and the Netherlands. Accelerate ASTM D6400 certification pipelines to maintain competitive access as EU Packaging and Packaging Waste Regulation tightens. Incumbent producers must defend against emerging substrate-secured entrants by locking multi-year supply agreements with agricultural cooperatives before commodity competition intensifies.
For New Entrants and Emerging Players: Differentiate on automotive interior panel specifications where OEM sustainability scorecards remain underpenetrated relative to saturated packaging segments. Target French production capacity gaps serving Southern European demand lagging German supply clusters. White space exists in precision-controlled fermentation systems for semiconductor packaging where batch-to-batch density variation under four percent commands specification premiums.
For Investors and Strategic Acquirers: Long-term, this sits as a materials substitution play because regulatory-driven petroleum foam displacement creates durable demand tailwinds across multiple industrial verticals. Acquisition targets should display proprietary strain optimization capabilities or locked substrate supply agreements rather than commodity toll-processing models. The signal to watch is reciprocity expansion between national composting certification bodies, which would unlock cross-border scale for regional producers.
| Strategic Initiative | Industry Significance |
|---|---|
| Captive Agricultural Partnership | Locks hemp hurd and corn stalk supply costs against biofuel feedstock competition in German cultivation clusters. |
| ASTM D6400 Certification Acceleration | Compresses validation timelines to capture EU Packaging and Packaging Waste Regulation procurement windows. |
| Precision Fermentation System Deployment | Enables electronics sector entry through batch-to-batch density variation reduction below four percent thresholds. |
| French Production Facility Investment | Addresses Southern European supply gap relative to concentrated German and Dutch capacity. |
| Automotive Interior Panel Specification | Captures OEM sustainability scorecard-driven material substitution in underpenetrated vehicle trim segments. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interviews with mycelium cultivation technicians, fermentation process engineers, packaging procurement managers at electronics manufacturers, construction sustainability officers, and food retail private label directors. Secondary validation drew from EU Packaging and Packaging Waste Regulation filings, EFSA novel material assessment databases, ASTM D6400 certification registries, and German Federal Environment Agency extended producer responsibility reports. Bottom-up substrate cost modeling and top-down end-use demand aggregation were triangulated against trade flow data.
Across the analysis window, the forecasting framework modeled volume and value trajectories by product type, application, end user, and material grade dimensions. CAGRs were derived from elasticity-adjusted substitution curves tracking expanded polystyrene displacement rates and composting infrastructure deployment timelines. Industry-specific inputs incorporated EU Green Deal mandate phase-in schedules and biogenic carbon accounting integration into German building code revisions.
The analysis sits within stated boundaries; outcomes outside sustained EU regulatory enforcement or accelerated composting infrastructure buildout would require recalibration. Forecasts reflect assumptions regarding certification reciprocity expansion and agricultural substrate market stability. Revision becomes warranted when hemp hurd or corn stalk price volatility crosses thresholds that disrupt mycelium cost parity with synthetic foams.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
Germany Plastic Packaging Market
Plastic Packaging
Nigeria Plastic Bottles Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
E-Commerce Plastic Packaging Market
Plastic Packaging
Polypropylene Corrugated Packaging Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Plastic Shrink Wrap Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
Global Stretch Films Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
HDPE Jug Market