
 Global Micro Injection Molded Plastic Market | 2026-2036
Global Micro Injection Molded Plastic Market Size, Share, and Industry Trends Forecast 2026-2036
Global Micro Injection Molded Plastic Market Outlook
A capital-intensity divergence between players is unwinding as automated micro-cell technology separates scalable producers from job-shop operators. MTD Micro Molding leverages all-electric presses and in-house tooling to sustain repeatability at sub-gram shot weights. Spectrum Plastics Group anchors its position through multi-site cleanroom capacity across North American medical corridors. Makuta Micro Molding competes via high-speed cycles in Asian electronics supply chains.
Micro injection molded plastic denotes thermoplastic or thermoset resin formed through precision injection units with shot volumes below one gram and tolerances reaching ±0.001 inches, serving industries requiring miniaturized, dimensionally stable components. Engineering plastics command premium positioning due to thermal and mechanical performance in medical and automotive connectors. Multi-cavity molding extends throughput economics for high-volume electronics housings, while insert molding captures margin pools in device assemblies requiring metal-polymer integration.
FDA device regulations, ISO 10993 biocompatibility standards, and EU MDR conformity requirements collectively elevate barrier-to-entry for new molders while redirecting procurement toward certified suppliers. REACH substance restrictions and RoHS hazardous substance limits further constrain material selection, favoring bio-based and halogen-free compound development. Stakeholders must monitor evolving polymer qualification protocols and automation capex thresholds as decisive variables for supplier viability.
Market Dynamics
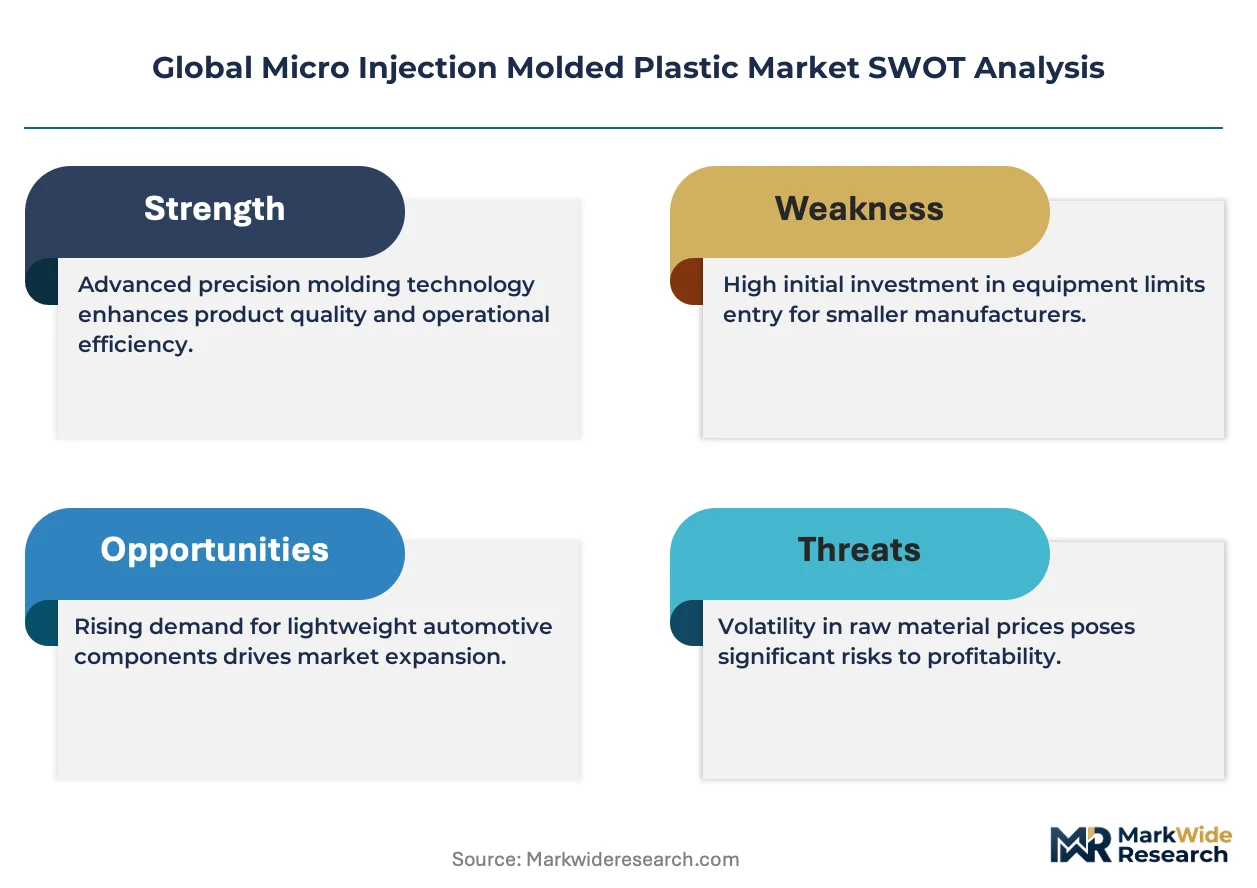
Automated micro-cell technology is bifurcating the supplier base, separating capital-rich scalable producers from job-shop operators unable to fund all-electric press conversions and in-house tooling capabilities.
Growth Catalysts
- Minimally Invasive Surgery Expansion:Medical device OEMs are scaling procurement of micro-molded cannulae and forceps tips as laparoscopic and robotic procedures displace open surgery protocols. FDA 510(k) clearance volume for micro-molded instrument sets has accelerated supplier qualification timelines.
- REACH and RoHS Compliance:European substance restrictions are redirecting material selection toward bio-based polyamides and halogen-free compounds, creating first-mover advantage for compounders with pre-qualified sustainable resin portfolios.
- Precision Engineering Clusters:Contract manufacturing capacity around Stuttgart and Munich serves pan-European OEM demand, concentrating tooling expertise and metrology infrastructure that reduces qualification cycles for new medical device programs.
Market Restraints
- Specialized Steel Volatility:Mold core and cavity steels from Swedish and Austrian suppliers face price instability tied to energy-intensive production, compressing tooling margins for mid-scale molders.
- Cleanroom Capital Requirements:ISO 14644 Class 7 and 8 certification for medical-grade production demands HVAC and environmental monitoring investments that exclude sub-$10M revenue operators from qualified supplier pools.
- Thermoplastic Substitution Limits:Liquid silicone rubber (LSR) molding captures applications requiring extreme flexibility and autoclave resistance, capping addressable market expansion in certain catheter and seal geometries.
Strategic Opportunities
- Indian Medical Device Manufacturing:PLI scheme incentives and CDSCO regulatory streamlining are attracting contract molding investment for export-oriented orthopedic and diagnostic component production.
- Metal-Polymer Integration:Insert molding of PEEK onto titanium and stainless steel substrates opens margin pools in implantable device assemblies where biocompatibility and structural load-bearing converge.
- High-Speed Vision Inspection Convergence:Integration of AI-driven defect detection with micro-cell automation enables zero-defect supply commitments that secure multi-year OEM contracts.
Industry Challenges
- Micro-Molding Process Engineering Talent:The intersection of polymer rheology, precision tooling, and statistical process control requires specialized expertise that outpaces vocational training pipeline output in Germany, Switzerland, and the United States.
- ISO 13485 Certification Timelines:Medical device quality management system audits and corrective action cycles extend supplier onboarding to 18-24 months, delaying revenue recognition for capital-deployed capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Micro Injection Molded Plastic Market |
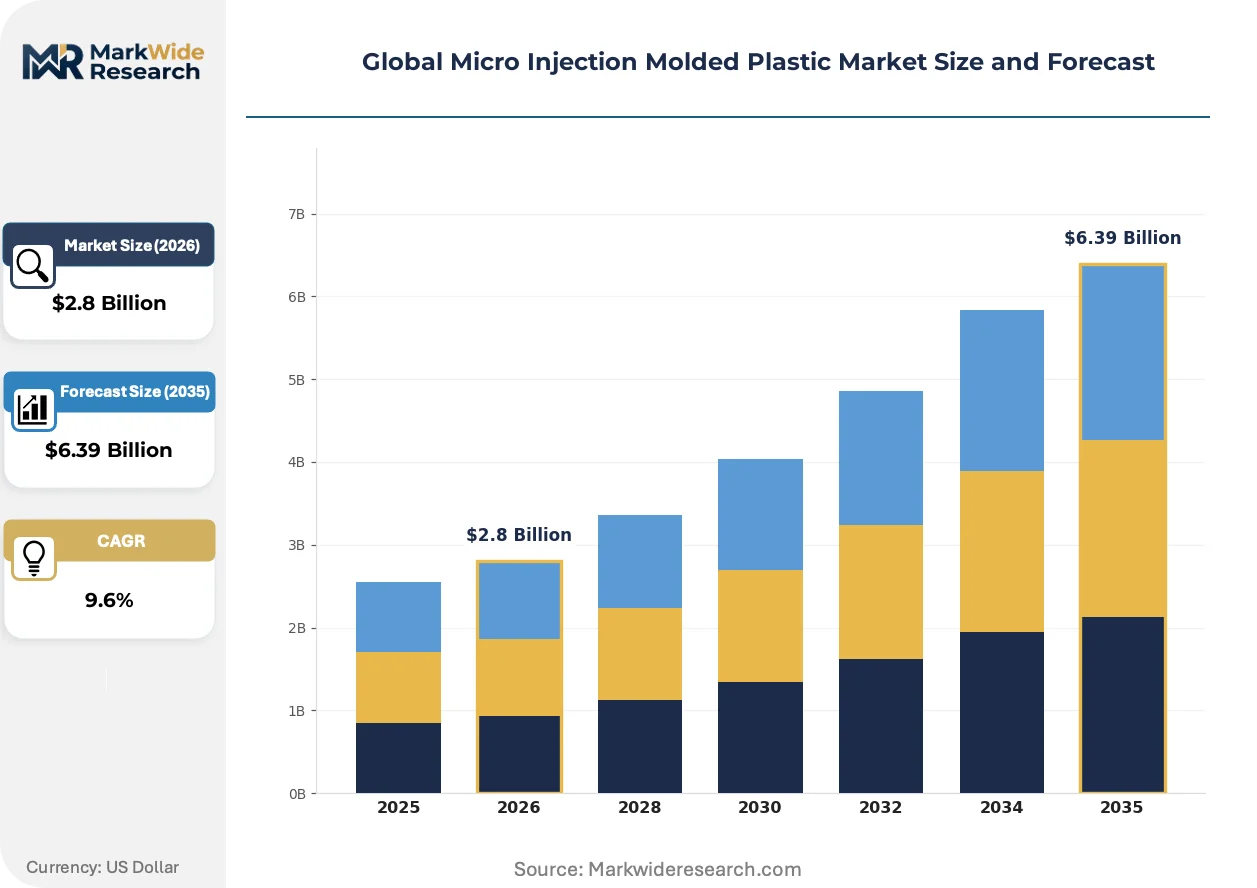
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.39 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Thermoplastics, Thermosetting Plastics, Bio-based Plastics, Engineering Plastics End User: Electronics, Automotive Components, Medical Devices, Consumer Goods Technology: Conventional Molding, Multi-Cavity Molding, Insert Molding, Co-Injection Molding Application: Connectors, Prototyping, Housing, Gears |
| Companies Covered | Accu-Mold, Isometric Micro Molding, MTD Micro Molding, SMC Ltd., Makuta Micro Molding, Spectrum Plastics Group, Paragon Medical, Arterex, PreciKam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Micro Injection Molded Plastic Market Strategic Shifts
Convergence of sub-gram shot control, in-mold sensing, and real-time cavity pressure monitoring is redefining process capability benchmarks and compressing defect rates in medical and electronics applications.
All-electric micro-injection presses with servo-driven screw control and sub-millisecond response times are supplanting hydraulic systems in medical cleanroom environments. Device OEMs in Germany and Switzerland now specify electric platforms for programs requiring Cpk values above 1.67. The technology is enabling single-cavity economics that previously demanded multi-cavity tooling, reducing validation burden for low-volume, high-mix production.
EU MDR conformity assessment requirements and notified body capacity constraints are extending technical documentation review periods for legacy device families. Manufacturers must resubmit clinical evidence and biocompatibility data under stricter ISO 10993-1 interpretation. European orthopedic and cardiovascular device segments are responding by consolidating supplier panels to reduce audit surface area and streamline post-market surveillance obligations.
Device OEMs are unbundling tooling ownership from component supply agreements, demanding mold design files and maintenance protocols as contract termination insurance. This pattern disrupts historical captive tooling models that locked buyers to single-source relationships. The shift is most visible in North American medical corridors where private equity-backed device platforms prioritize supply chain optionality over unit cost minimization.
Global Micro Injection Molded Plastic Market Segmentation
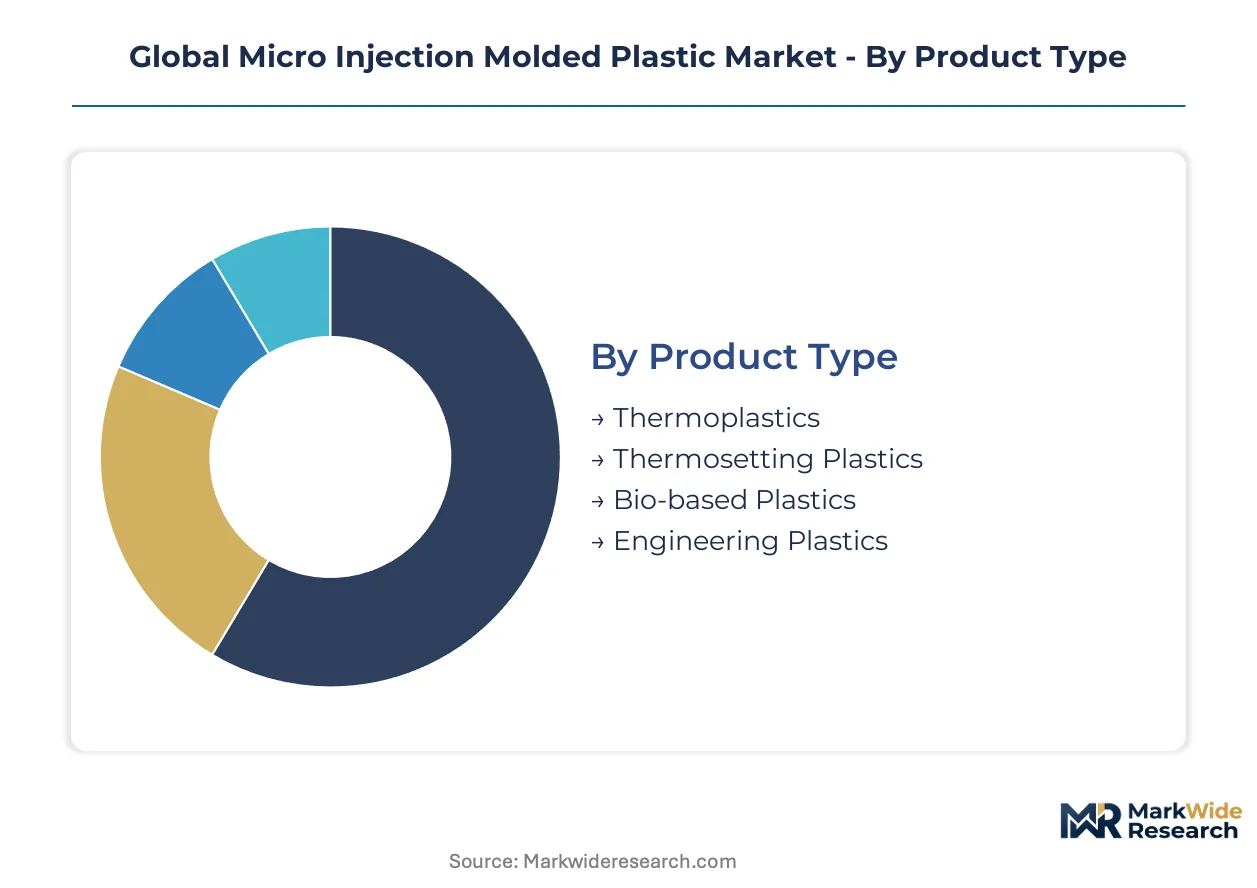
Material selection and process technology determine qualification pathways for micro-molded components. Regulatory compliance costs vary dramatically across polymer families and end-use categories, creating tiered supplier economics.
Product Type:
REACH substance restrictions and RoHS hazardous substance limits constrain resin selection, favoring compounders with pre-qualified sustainable portfolios.
- Engineering Plastics:PEEK, PPS, and LCP formulations deliver thermal stability above 200°C and chemical resistance for autoclave-sterilized surgical instruments. German and Swiss device OEMs specify these grades for implantable assemblies requiring ISO 10993-5 cytotoxicity clearance.
- Thermoplastics:Polyamide and polycarbonate dominate high-volume electronics housings where dimensional tolerance demands remain moderate. Asian contract manufacturers in Shenzhen and Seoul leverage multi-cavity tooling economics for connector backshell production.
- Thermosetting Plastics:Epoxy and phenolic resins serve high-heat automotive underhood sensors where creep resistance exceeds thermoplastic limits.
- Bio-based Plastics:Polylactic acid and bio-polyamides from castor oil derivatives address EU Green Deal procurement mandates for single-use medical disposables.
Engineering plastics handles the majority of throughput; bio-based plastics is the fastest mover on share.
End User:
Cleanroom certification requirements and FDA 510(k) clearance timelines segment supplier pools by customer category.
- Medical Devices:Micro-molded cannulae, forceps tips, and implantable housings demand ISO 13485 quality systems and ISO 14644 Class 7 environments. Stuttgart-area contract manufacturers concentrate metrology infrastructure that reduces qualification cycles for European orthopedic OEMs.
- Electronics:Sub-millimeter connector pins and fiber optic ferrules require Cpk values above 1.67, driving adoption of all-electric presses with servo-driven screw control. Taiwanese and South Korean EMS providers anchor procurement for smartphone camera module assemblies.
- Automotive Components:Miniaturized sensors and connector seals for electric powertrains face temperature cycling specifications from -40°C to 150°C.
- Consumer Goods:Cosmetic dispensing mechanisms and wearable device housings prioritize cycle speed over dimensional precision.
Medical devices commands the highest margin pool; electronics expands most quickly on unit volume.
Technology:
Capital intensity and process control sophistication separate scalable producers from job-shop operators across molding platforms.
- Multi-Cavity Molding:8-to-32 cavity tooling extends throughput economics for high-volume electronics and consumer applications. Japanese press manufacturers dominate the precision hot-runner systems required for balanced fill across micro-scale geometries.
- Insert Molding:Metal-polymer integration of PEEK onto titanium substrates captures margin pools in implantable device assemblies. The process demands specialized tooling for metal substrate positioning and polymer flow simulation.
- Conventional Molding:Single-cavity configurations persist in medical prototyping and low-volume surgical instrument development.
- Co-Injection Molding:Multi-material sequences enable soft-touch overmolding for diagnostic device grips and sealing surfaces.
Multi-cavity molding carries the heaviest installed base; insert molding climbs the fastest on revenue per machine hour.
Application:
Functional criticality and tolerance specifications segment pricing power across component categories.
- Connectors:Micro-USB, RF, and board-to-board interfaces require sub-gram shot weights with ±0.001 inch tolerances. German automotive OEMs specify these for autonomous vehicle sensor arrays.
- Housing:Miniaturized enclosures for implantable pacemakers and drug delivery pumps combine hermetic sealing with biocompatibility certification.
- Gears:Micro-scale transmission components for surgical robotics and optical equipment demand wear-resistant engineering plastics with tight pitch control.
- Prototyping:Bridge tooling and soft molds accelerate design validation before hardened steel production tooling commitment.
Connectors generates the largest revenue base; housing shows the steepest expansion trajectory on implantable device demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Asian electronics corridors squeeze unit economics hardest, while German and Swiss medical OEMs absorb premiums for validated supply chains. This elasticity divergence concentrates investment in high-certification zones and commoditizes volume production elsewhere.
United States
Medical device OEMs in Minneapolis and Boston corridors demand ISO 13485-certified micro-molding for robotic surgical instruments. FDA 510(k) clearance volume for minimally invasive tool sets has accelerated supplier qualification timelines to 12-18 months. Private equity-backed device platforms in Research Triangle Park now unbundle tooling ownership from component supply agreements.
Germany
Precision engineering clusters around Stuttgart and Munich serve pan-European orthopedic OEM demand with dedicated cleanroom capacity. EU MDR conformity requirements extend technical documentation review periods, compressing margins for mid-scale molders. Baden-Württemberg contract manufacturers concentrate metrology infrastructure that reduces qualification cycles for new implantable device programs.
Switzerland
Swissmedic oversight and ISO 10993-1 biocompatibility mandates anchor premium positioning for implantable micro-components. Device OEMs in Basel and Zürich specify all-electric press platforms requiring Cpk values above 1.67. The Jura Arc micro-technology cluster integrates precision tooling with polymer rheology expertise for cardiac and neurological applications.
China
Shenzhen and Dongguan contract manufacturers leverage multi-cavity tooling economics for smartphone camera module and connector backshell production. NMPA regulatory streamlining for Class II medical devices attracts domestic molding investment, though import substitution policies favor local resin compounders. Yangtze River Delta electronics EMS providers anchor procurement for sub-millimeter fiber optic ferrules.
India
PLI scheme incentives and CDSCO regulatory harmonization are attracting contract molding capacity for export-oriented orthopedic component production. Maharashtra and Gujarat industrial corridors host emerging cleanroom operations serving European diagnostic OEMs. Bangalore-based device startups increasingly specify domestic micro-molders for single-use surgical disposables.
Global Micro Injection Molded Plastic Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with capital access determining scalability in automated micro-cell deployment. The supplier base separates into three archetypes: all-electric press operators with in-house tooling, multi-site cleanroom consolidators, and high-speed cycle specialists serving electronics supply chains. Competitive moves center on mold design file ownership unbundling and AI-driven vision inspection integration for zero-defect supply commitments.
Among North American medical-focused operators, MTD Micro Molding and Spectrum Plastics Group exemplify the integrated archetype through captive tooling and multi-site cleanroom infrastructure. SMC Ltd. represents the contract manufacturing consolidator model with pan-regional medical corridor presence. These three occupy positions where validated quality systems and electric press platforms intersect to secure multi-year OEM agreements.
| Leading Market Players |
|---|
| Accu-Mold |
| Isometric Micro Molding |
| MTD Micro Molding |
| SMC Ltd. |
| Makuta Micro Molding |
| Spectrum Plastics Group |
| Paragon Medical |
| Arterex |
| PreciKam |
| Others |
Value Chain & Pricing Dynamics
Tooling lead times stretching 14-20 weeks for hardened steel molds concentrate pricing power with German and Swiss suppliers holding captive metrology infrastructure, while Asian contract manufacturers compete on cycle economics for electronics volumes.
Pricing Analysis
After-sales tooling maintenance contracts and mold refurbishment services generate lifetime value multiples exceeding initial component sales for qualified medical suppliers. Three-tier pricing structure across ISO 13485-certified premium, FDA-registered standard, and uncertified economy levels segments buyer pools by validation burden. Pricing pressure stems from Asian EMS providers squeezing connector backshell economics through multi-cavity automation. Medical device OEMs in Stuttgart and Minneapolis corridors show lowest price sensitivity due to unbundled tooling ownership demands and zero-defect supply requirements.
Supply Chain Analysis
Port congestion on Asia-Europe container lanes and air freight capacity constraints elevate inbound logistics costs for Swedish and Austrian mold steel deliveries. Supply concentrates in Germany, Switzerland, and China, with Baden-Württemberg housing precision tooling clusters and Shenzhen anchoring high-volume electronics molding. Raw material dependencies include specialized tool steels, medical-grade PEEK compounds, and halogen-free polyamides. Single-source vulnerability runs through Swedish Uddeholm and Austrian Böhler-Uddeholm for cavity steels. Distribution runs through validated logistics partners maintaining chain-of-custody documentation for ISO 14644 cleanroom environments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through ISO 13485 and FDA 510(k) validation creates multi-year switching costs that protect incumbent positioning.
For Market Incumbents: Consolidate through captive tooling ownership models and multi-site cleanroom expansion across North American medical corridors. Liquid silicone rubber substitution threatens certain catheter geometries; defend through PEEK-titanium insert molding capability investments and AI-driven vision inspection integration for zero-defect commitments. For New Entrants and Emerging Players: Rapid-prototyping and bridge-tooling services represent underserved white space where incumbents force 12-18 month qualification timelines. Target Indian orthopedic component production under PLI scheme incentives with cleanroom investments in Maharashtra and Gujarat corridors. Pursue European diagnostic OEMs through CDSCO-harmonized quality systems as a go-to-market angle. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-complexity play because certification entrenchment compounds returns through multi-year supply agreements and limited supplier panel competition. Acquisition targets should display integrated electric press platforms with in-house tooling and existing ISO 13485 scope. Monitor notified body capacity constraints under EU MDR as the signal for qualification timeline inflection and pricing power shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Capacity Expansion | ISO 14644 Class 7 certification unlocks medical device supplier panel access in Stuttgart and Minneapolis corridors. |
| All-Electric Press Conversion | Servo-driven screw control platforms achieve Cpk values above 1.67 for Swiss cardiac implant specifications. |
| In-House Tooling Integration | Captive mold design and maintenance capabilities respond to OEM unbundling demands for supply chain optionality. |
| AI Vision Inspection Deployment | Real-time defect detection enables zero-defect supply commitments that secure multi-year orthopedic contracts. |
| Indian Manufacturing Footprint | PLI scheme incentives and CDSCO streamlining attract export-oriented orthopedic component production capacity. |
Study Parameters
The analysis maps engineering plastics, thermoplastics, thermosetting plastics, and bio-based resin sub-sectors, each validated through plant managers at contract molding facilities, procurement leads at medical device OEMs, distribution channel partners in Asian electronics corridors, and technical R&D directors at compounders. Primary interviews with these stakeholders combined with secondary validation through FDA 510(k) filings, EU MDR notified body registries, SEC 10-K disclosures from listed suppliers, and customs trade data for mold steel imports. Bottom-up capacity modeling and top-down demand segmentation triangulate volume estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models material type, end-use category, process technology, and application geometry as core segmentation dimensions. CAGRs derive from installed press capacity growth, OEM procurement pipeline visibility, and regulatory approval velocity. Industry-specific forecast inputs include cleanroom certification timelines and all-electric press adoption curves in medical corridors.
Forecasts assume regulatory continuity in FDA, EU MDR, and CDSCO regimes; material policy shifts would require re-modeling. Practitioners should keep alternative scenarios live as REACH substance restriction expansions and notified body capacity constraints evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
Spain Plastic Bottles Market
Plastic Packaging
Plastic Packaging Market
Plastic Packaging
Blow Molded Bottles Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
Global Plastic Straps Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
China Plastic Bottles Market
Plastic Packaging
PCR Films Market
Plastic Packaging
Plastic Tubes Market
Plastic Packaging
Latin America Single-Use Plastic Packaging Market
Plastic Packaging
Philippines Plastics Market
Plastic Packaging
Disposable Straw Market