
 Japan Plastic Packaging Market | 2026-2036
Japan Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Plastic Packaging Market Foresight
Convenience store supply chains are rewriting procurement patterns across Japan's plastic packaging sector. Toppan Inc. leverages its printing and barrier film expertise to dominate shelf-ready formats for retail clients. Toyo Seikan Group Holdings anchors the rigid container segment through extensive beverage can and bottle operations. Futamura Chemical specializes in cellulose-based films, competing on sustainability credentials against petroleum-derived alternatives.
Japan plastic packaging encompasses films, containers, bottles, and bags engineered from polyethylene, polypropylene, and polyvinyl chloride with thickness tolerances often below 25 microns for food-contact applications, serving preservation, logistics, and retail display functions. Films lead product type revenue due to pervasive use in fresh food wrapping and industrial palletization, while flexible formats outpace rigid growth in healthcare end users driven by sterilizable pouch demand. Polyethylene captures the largest material share though polypropylene gains ground in hot-fill and retort applications where thermal resistance commands premium positioning.
METI enforces recycling targets under the Act on Promotion of Resource Circulation for Plastics, compelling manufacturers toward mono-material designs compatible with mechanical reprocessing. The country's national standards body mandates JIS-compliant testing for migration limits and seal integrity, restricting market access for non-certified imports. Stakeholders must monitor evolving EPR fee structures and bio-based material qualification pathways to preserve margin structures.
Market Dynamics
Japan's Container and Packaging Recycling Law is forcing manufacturers toward mono-material designs compatible with mechanical reprocessing, reshaping R&D priorities across the value chain. Convenience store supply chains are compressing lead times and demanding shelf-ready formats that integrate barrier performance with retail display functionality.
Growth Catalysts
- Food and beverage sector expansion:Fresh food wrapping requirements and ready-meal proliferation drive demand for high-barrier films with sub-25-micron tolerances.
- METI recycling mandates:The Act on Promotion of Resource Circulation for Plastics compels packaging redesign toward circular material flows, creating compliance-driven equipment upgrades.
- Healthcare sterilizable pouches:Flexible formats outpace rigid growth in medical end uses as hospitals shift toward pre-sterilized, single-use delivery systems.
Market Restraints
- Petrochemical feedstock volatility:Polyethylene and polypropylene resin prices fluctuate with naphtha cracking economics, compressing converter margins.
- Import certification barriers:JIS-compliant testing for migration limits restricts non-certified foreign suppliers from accessing food-contact applications.
- Cellulose film competition:Bio-based alternatives from domestic producers compete on sustainability credentials against petroleum-derived conventional films.
Strategic Opportunities
- Kansai industrial corridor:Osaka and Kyoto prefectures show underpenetrated demand for pharmaceutical-grade barrier packaging relative to Kanto saturation.
- Hot-fill and retort applications:Polypropylene thermal resistance commands premium positioning in ready-to-eat meal segments requiring pasteurization compatibility.
- EPR fee structure evolution:Extended producer responsibility adjustments create first-mover advantages for converters with verified closed-loop collection systems.
Industry Challenges
- Mono-material engineering expertise:Reformulating multi-layer barrier films into recyclable single-polymer structures requires polymer science capabilities in short supply.
- Legacy equipment retrofitting:Existing extrusion and thermoforming lines demand capital-intensive modifications to process bio-based feedstocks at commercial scale.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Plastic Packaging Market |
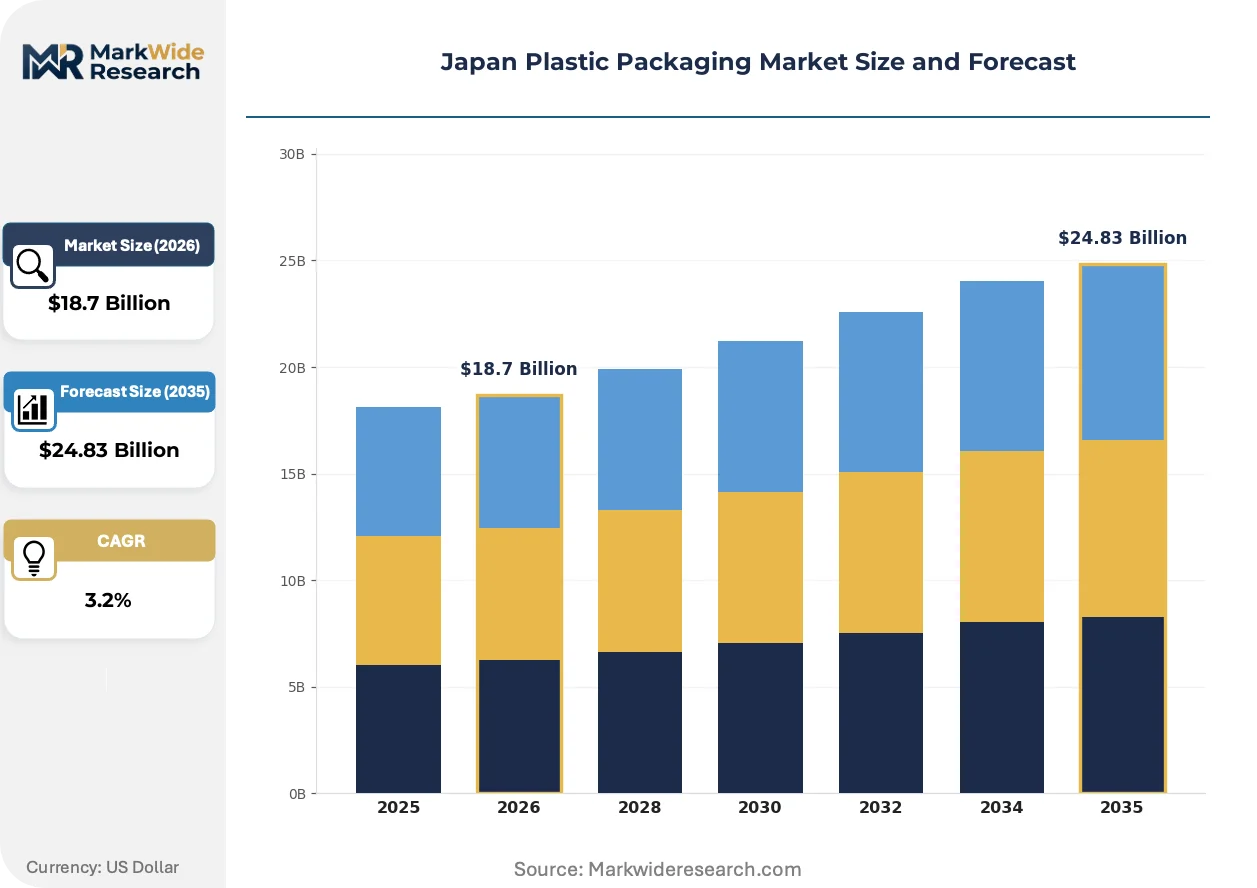
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $24.83 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Bags, Containers, Films End User: Food & Beverage, Healthcare, Personal Care, Household Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Others Form: Rigid, Flexible, Semi-Rigid, Blister |
| Companies Covered | Toppan Inc., Toray Advanced Film Co Ltd, Toyo Seikan Group Holdings, Ltd., Futamura Chemical Co Ltd, Rengo Co. Ltd., Takemoto Yohki Co. Ltd., Amcor Group, Gunze Limited, Takigawa Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Plastic Packaging Market Shifts & Advancements
Digital printing and smart packaging technologies are collapsing minimum order quantities and enabling mass customization for regional retail chains. Material science advances are dissolving the performance gap between petroleum-derived and bio-based alternatives.
Barrier film virtualization is compressing the distinction between physical substrate and digital information layer. Toppan and comparable converters deploy printed electronics integration to embed temperature tracking and authentication directly into packaging substrates. Pharmaceutical and high-value food exporters adopt these formats fastest, accepting per-unit cost premiums for supply chain visibility. The technology is virtualizing quality assurance from post-production inspection to real-time distributed monitoring.
METI's phased implementation of plastic circulation targets tightens compliance timelines through 2030. Manufacturers must demonstrate recycled content thresholds or pay escalating EPR fees, redirecting capital toward sorting infrastructure partnerships. Small and mid-size converters face disproportionate burden as certification costs scale nonlinearly with volume.
Convenience store operators now specify packaging performance through outcome metrics—shelf-life extension, theft deterrence, and scan-rates—rather than material prescriptions. This specification shift transfers design liability upstream to converters while opening margin capture for integrated solution providers. The Kanto corridor exhibits this procurement evolution most acutely, with Lawson and 7-Eleven Japan piloting supplier scorecards weighting circularity metrics at 30% of contract value.
Japan Plastic Packaging Market Segmentation
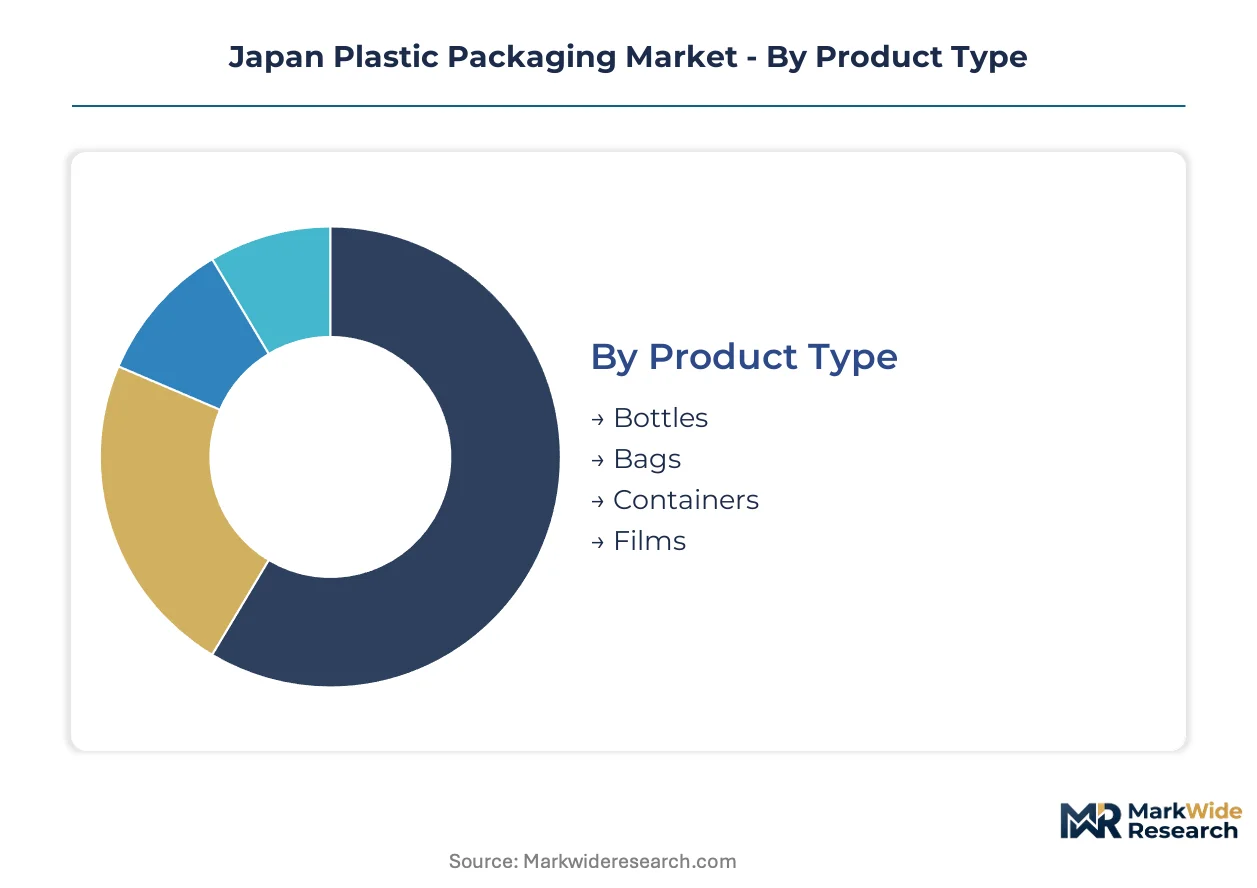
Japan's plastic packaging sector fragments across performance requirements that diverge sharply by preservation needs, thermal tolerance, and recycling compatibility. Understanding these segment boundaries clarifies where converter investments concentrate and which material specifications command premium positioning.
Product Type:
Application function determines format selection, with barrier performance and shelf-life extension driving procurement specifications across retail and industrial channels.
- Films:Thin-gauge polyethylene and polypropylene structures, often sub-25-micron for food-contact applications, dominate fresh produce wrapping and industrial palletization. Convenience store supply chains in the Kanto corridor specify high-barrier metallized variants for ready-meal formats.
- Containers:Injection-molded and thermoformed rigid structures serve beverage, dairy, and condiment segments requiring stack strength and tamper evidence. Hot-fill and retort compatibility commands premium positioning in ready-to-eat meal applications.
- Bottles:Blow-molded polyethylene terephthalate and high-density polyethylene formats anchor carbonated soft drink and personal care dispensing. Lightweighting initiatives compete against refillable deposit systems under evolving EPR frameworks.
- Bags:Converted film structures with heat-seal layers address waste collection, retail carryout, and industrial liner applications. METI recycling mandates are compressing multi-layer complexity toward mono-material designs compatible with mechanical reprocessing.
Films command the established base. The steepest expansion runs through flexible healthcare pouches.
End User:
Customer procurement patterns diverge between commodity volume buyers and specification-intensive sectors where compliance documentation commands price premiums.
- Food & Beverage:The largest demand concentration spans fresh food wrapping, ready-meal packaging, and beverage containment. Lawson and 7-Eleven Japan pilot supplier scorecards weighting circularity metrics at substantial contract value shares.
- Healthcare:Sterilizable flexible pouches and barrier films for pharmaceutical delivery represent the fastest-climbing segment. Hospitals shift toward pre-sterilized single-use systems, displacing rigid glass and metal formats.
- Personal Care:Dispensing pumps, tubes, and sachets for cosmetics and toiletries emphasize aesthetic surface quality and precise dosing mechanisms. Premium brand owners specify custom color matching and soft-touch finishes.
- Household:Detergent bottles, cleaning wipe canisters, and air-freshener housings prioritize chemical resistance and child-resistant closure integration. Private-label retail chains dominate volume procurement with standardized specifications.
Food & Beverage absorbs the dominant volume share. Healthcare applications are gaining share fastest on sterilization technology conversion.
Material:
Polymer selection balances cost position, processing characteristics, and compliance with Japan's Container and Packaging Recycling Law targets.
- Polyethylene:Low-density and linear low-density variants capture the largest material share across film, bag, and bottle applications. Naphtha cracking economics drive resin price volatility that compresses converter margins.
- Polypropylene:Superior thermal resistance enables hot-fill, retort, and microwaveable applications where polyethylene fails. Random copolymer grades command premium positioning in ready-meal trays and pharmaceutical blister packs.
- Polyvinyl Chloride:Clarity and oxygen barrier properties sustain demand in pharmaceutical blister and blood bag applications despite environmental scrutiny. Alternative material substitution pressures intensify under circular economy directives.
- Others:Bio-based polylactic acid, cellulose derivatives from domestic producers like Futamura Chemical, and emerging chemically recycled feedstocks compete on sustainability credentials. JIS-compliant certification requirements restrict import penetration.
Polyethylene anchors the installed base. Polypropylene is climbing fastest on thermal performance premiums.
Form:
Structural rigidity determines equipment compatibility, logistics efficiency, and end-of-life recycling pathway clarity.
- Flexible:Roll-fed films, pouches, and bags minimize material weight and transportation cube. Healthcare sterilizable formats are displacing rigid alternatives in hospital supply chains.
- Rigid:Injection-molded and thermoformed containers, bottles, and closures provide stack strength and precise dimensional tolerance. Beverage canning and bottling operations in the Kanto industrial corridor concentrate demand.
- Semi-Rigid:Thermoformed trays and tubs bridge performance between flexible films and rigid containers for protein and produce packaging. Mono-material engineering challenges complicate recycling stream compatibility.
- Blister:Form-fill-seal pharmaceutical and consumer goods formats combine thermoformed cavities with lidding foil for unit-dose protection. PMDA compliance documentation requirements elevate qualification barriers for new suppliers.
Flexible formats command volume leadership. Rigid applications are expanding most quickly on beverage and dairy containment demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
METI's phased plastic circulation targets are redirecting converter investments toward prefectural recycling infrastructure. The Kanto corridor maintains packaging demand dominance while Kansai and Chubu regions attract pharmaceutical-grade specialization.
Kanto
Tokyo and surrounding prefectures concentrate convenience store supply chains demanding shelf-ready barrier formats. The Container and Packaging Recycling Law enforcement tightest here, compelling Lawson and 7-Eleven Japan to weight circularity metrics at substantial contract shares. Yokohama and Kawasaki industrial zones host integrated film-to-container manufacturing clusters serving retail procurement evolution.
Kansai
Osaka and Kyoto prefectures exhibit underpenetrated demand for pharmaceutical-grade barrier packaging relative to Kanto saturation. PMDA compliance documentation requirements elevate qualification barriers, favoring domestic converters with established certification pathways. Amagasaki and Sakai production corridors attract sterilizable pouch investments as hospitals shift toward pre-sterilized single-use systems.
Chubu
Nagoya's automotive and precision manufacturing heritage transfers into high-tolerance packaging equipment production. Polypropylene thermal resistance development for hot-fill applications concentrates here, serving ready-meal pasteurization requirements. Toyota City adjacent suppliers leverage polymer science capabilities for mono-material engineering challenges.
Kyushu
Fukuoka prefecture hosts emerging bio-based material qualification pathways as regional governments pilot extended producer responsibility adjustments. Chemical resistance testing for household product containment migrates toward this lower-cost manufacturing zone. Kitakyushu recycling infrastructure investments target closed-loop collection system verification.
Hokkaido
Sapporo's food processing industry drives fresh food wrapping demand with extended shelf-life requirements for distant distribution. Cold-chain logistics specialization creates niche opportunities for high-barrier metallized variants. Local METI regional bureau enforcement of recycled content thresholds lags Honshu implementation timelines.
Japan Plastic Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated converters with polymer science capabilities and established PMDA certification pathways. Tiered competitive positioning separates printing-integrated barrier film specialists from rigid container manufacturers and emerging bio-based material purists. Dominant competitive moves include backward integration into resin compounding and strategic partnerships with convenience store operators for supplier scorecard optimization.
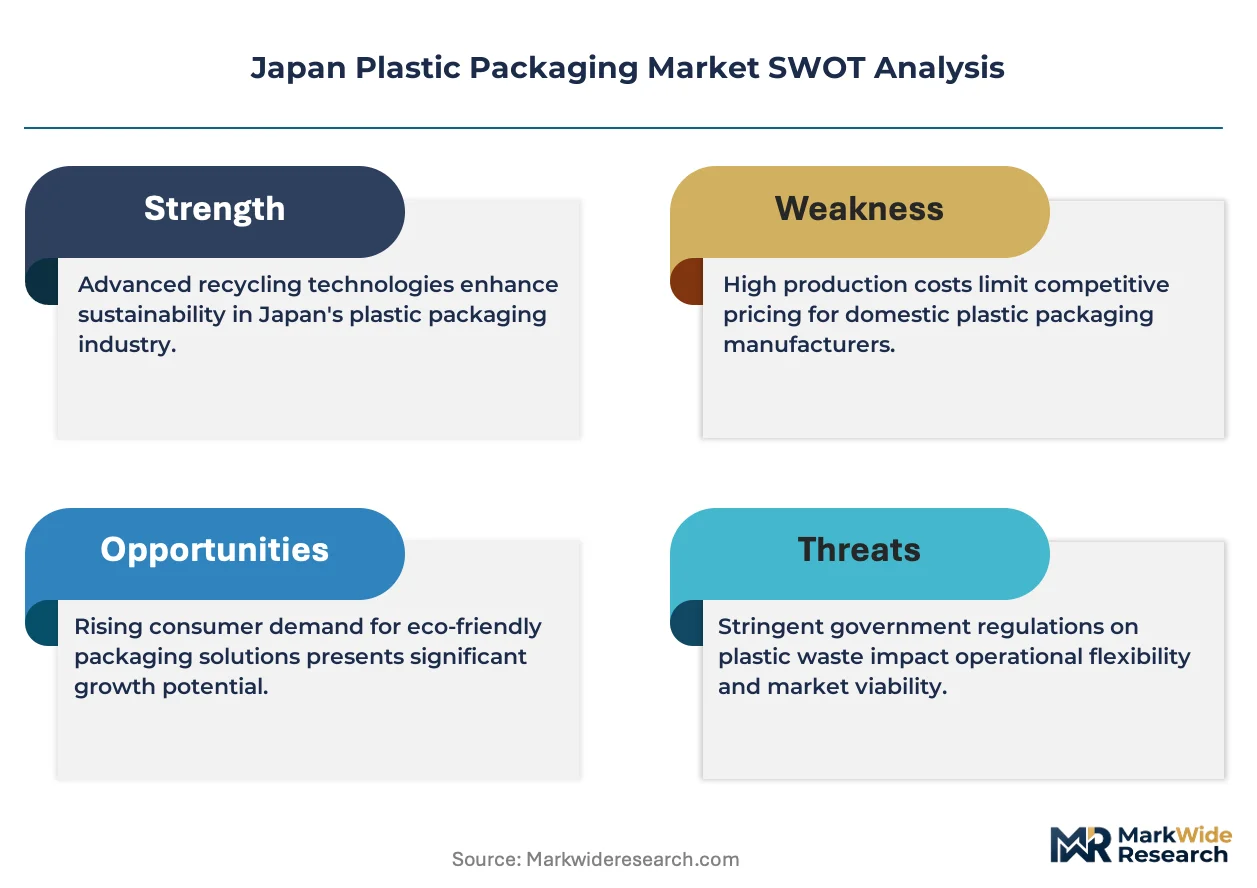
Within the integrated converter tier, Toppan Inc. and Toyo Seikan Group Holdings occupy positions exemplifying distinct strategic archetypes—printing-to-packaging integration versus rigid container scale. Futamura Chemical Co Ltd represents the sustainability-focused specialist model competing on cellulose-based credentials. Toray Advanced Film Co Ltd and Gunze Limited sit within the advanced materials segment where barrier performance premiums command positioning. These five entities collectively illustrate the competitive spectrum from petroleum-derived conventional formats through bio-based alternatives.
| Leading Market Players |
|---|
| Toppan Inc. |
| Toray Advanced Film Co Ltd |
| Toyo Seikan Group Holdings, Ltd. |
| Futamura Chemical Co Ltd |
| Rengo Co. Ltd. |
| Takemoto Yohki Co. Ltd. |
| Amcor Group |
| Gunze Limited |
| Takigawa Corporation |
| Others |
Supply & Pricing Matrix
Naphtha cracking economics in South Korea and Saudi Arabia anchor resin cost structures that compress converter margins across Japan's packaging value chain. Domestic buyers absorb volatility through long-term offtake contracts while METI recycling mandates redirect capital toward mono-material qualification premiums.
Pricing Analysis
Volume-discount tiering separates pharmaceutical-grade barrier films from commodity food-wrap grades. Three-tier pricing structure across premium, standard, and economy levels tracks JIS certification status and thermal resistance specifications. Cost compression in polyethylene film tiers is intensifying because naphtha feedstock volatility transfers directly to converter quotations. Convenience store procurement teams exhibit highest price sensitivity, while pharmaceutical exporters accept substantial premiums for PMDA-compliant documentation.
Supply Chain Analysis
Contract manufacturing concentration rests with Toyo Seikan and Toppan operating integrated film-to-container facilities in Kanto. Geographic supply draws from South Korean resin compounders, Saudi petrochemical feedstock, and domestic cellulose processors like Futamura. Single-source vulnerability concentrates in metallized barrier film substrates where Korean suppliers dominate. Distribution runs through convenience store logistics cooperatives and pharmaceutical wholesale channels with divergent service requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in cyclical recovery as METI's phased EPR fee escalation forces compliance-driven equipment replacement. Naphtha price normalization creates margin expansion headroom for qualified converters.
For Market Incumbents: Pre-empt cellulose substitution threats by accelerating mono-material engineering partnerships with polymer science institutes. Backward integration into resin compounding secures margin capture against petrochemical volatility. Dominate supplier scorecard optimization for Lawson and 7-Eleven Japan procurement evolution.
For New Entrants and Emerging Players: Pursue Kansai pharmaceutical-grade barrier packaging where PMDA certification barriers favor agile domestic specialists. Sterilizable pouch demand in Osaka-Kyoto corridors offers penetrable white space. Lead with JIS-compliant qualification services as differentiated go-to-market anchor.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier converters with verified closed-loop collection systems and established METI recycling infrastructure partnerships. Long-term viability hinges on mono-material patent portfolios and regional sorting facility access. Watch EPR fee structure adjustments as inflection signal for consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Engineering Partnership | Collaboration with Toyota City polymer institutes accelerates recyclable barrier film development for METI compliance. |
| Backward Integration into Resin Compounding | In-house polyethylene and polypropylene formulation reduces naphtha price volatility exposure for Kanto converters. |
| Supplier Scorecard Optimization | Circularity metric weighting at 30% of contract value creates first-mover advantage with convenience store chains. |
| Kansai Pharmaceutical Certification Investment | PMDA documentation capabilities unlock sterilizable pouch demand in underpenetrated Osaka-Kyoto corridors. |
| Closed-Loop Collection System Verification | EPR fee avoidance through verified recycling infrastructure partnerships preserves margin structures against regulatory tightening. |
Research Methodology
A standing panel of polymer science directors, convenience store procurement leads, pharmaceutical packaging engineers, and METI recycling policy officers provided ongoing calibration across the study period. Primary interviews with film extrusion plant managers and secondary validation against JIS standards documentation, customs trade data, and PMDA submission records anchored segmentation boundaries. Bottom-up converter capacity assessments triangulated with top-down end-use demand modeling.
Scenario-bracketing framed low, base, and high cases across the projection horizon without specifying discrete years. The analytical framework segmented by product type, material composition, thermal performance tier, and regional industrial corridor. CAGRs derived from historical volume trajectories adjusted for regulatory compliance cost step-changes and feedstock price cycle positioning. Forecast inputs incorporated METI EPR phase-in schedules and convenience store format expansion plans.
Sensitivities concentrate around naphtha cracking margin volatility, cellulose substitution acceleration, and EPR fee structure evolution. Forecasts reflect documented assumptions on recycling infrastructure buildout pace and pharmaceutical outsourcing conversion rates. Quarterly review of METI circular economy implementation bulletins and Korean resin export pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Plastic Caulk Tube Market
Plastic Packaging
Corrugated Plastic Box Market
Plastic Packaging
India Plastic Bottles Market
Plastic Packaging
Polyethylene Corrugated Packaging Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Plastic Bottles Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
Indonesia Plastic Food Tray Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Middle East and Africa Plastic Packaging Market
Plastic Packaging
FFS Rigid Films Market
Plastic Packaging
Cast Films Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
Plastic Lab Totes Market
Plastic Packaging
Global Micro Injection Molded Plastic Market