
 North America Single-Use Plastic Packaging Market | 2026-2036
North America Single-Use Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
North America Single-Use Plastic Packaging Market Insights
Subscription-based packaging replenishment is shifting how foodservice distributors contract for single-use items. Pactiv LLC leverages its thermoforming scale to anchor supply agreements with national restaurant chains. Sealed Air Corporation sustains competitive positioning through proprietary barrier film technologies for protein packaging. Berry Global Inc dominates rigid container output across dairy and prepared food segments.
North America single-use plastic packaging encompasses disposable containment and protection systems manufactured from polyethylene, polypropylene, polystyrene, or polyethylene terephthalate through extrusion, thermoforming, or injection molding processes, engineered for one-cycle product handling before disposal. These systems serve primarily to extend shelf stability, enable portion control, and reduce contamination risk across food, beverage, pharmaceutical, and personal care supply chains. Flexible packaging leads material throughput due to lower resin intensity and logistics efficiency in e-commerce fulfillment channels. Rigid containers capture concentrated margin pools in pharmaceutical blister and dairy bottle applications where barrier precision commands specification premiums. Bags and wraps compete on volume scale in retail grocery and quick-service restaurant back-of-house operations.
The EPA oversees municipal solid waste frameworks that determine landfill diversion targets affecting post-consumer recovery economics for plastic packaging. Health Canada and the FDA administer food-contact substance notifications that govern migration limits and additive approvals for polyethylene and polypropylene food packaging. State-level extended producer responsibility mandates in California, Oregon, and Canadian provincial jurisdictions are reshaping design-for-recycling specifications and recycled content minimums. Stakeholders must monitor regulatory fragmentation between U.S. federal inaction and accelerating state-level material bans to calibrate capital allocation between virgin resin capacity and chemical recycling infrastructure.
Market Dynamics
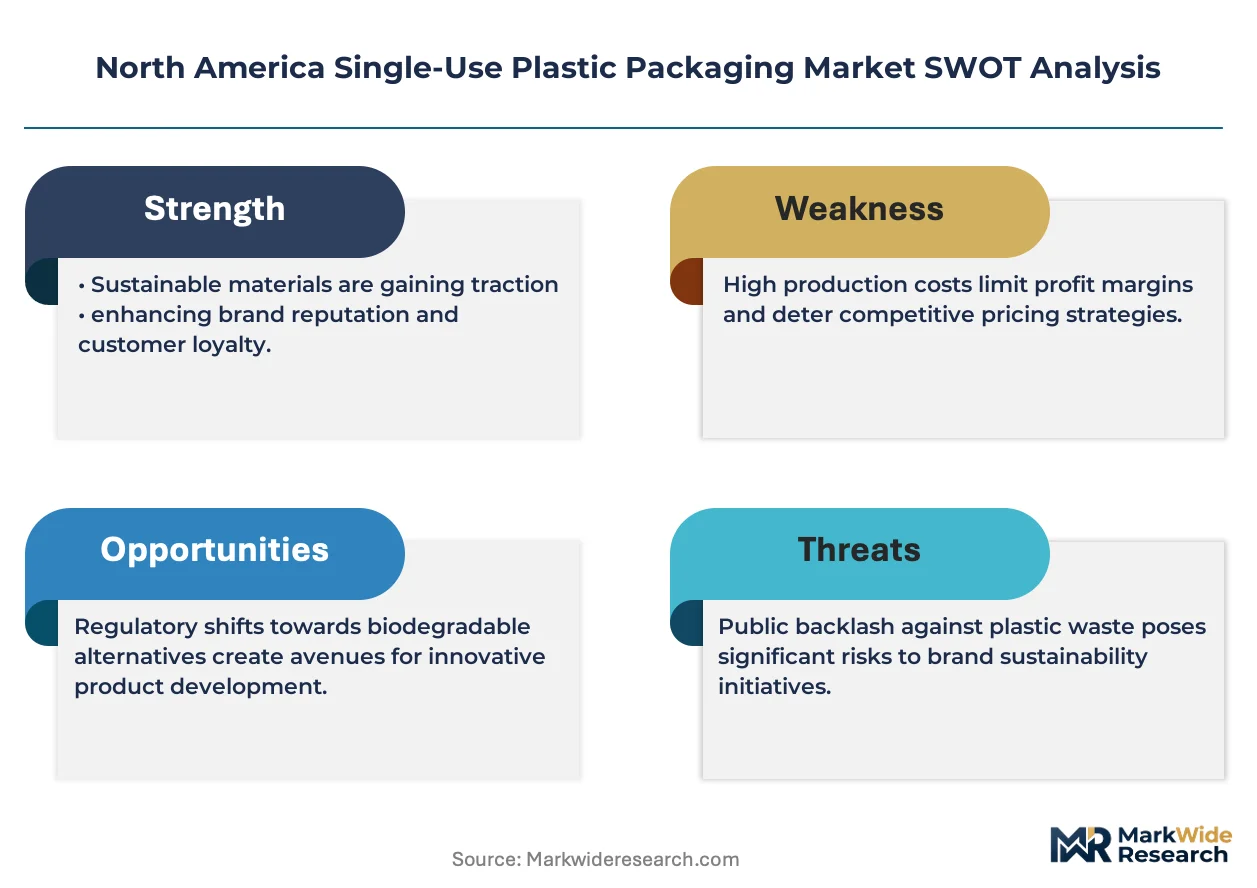
Extended Producer Responsibility mandates in California, Oregon, and Canadian provinces are forcing resin-dependent converters to reconfigure supply chains around post-consumer recycled content minimums and design-for-recycling specifications.
Growth Catalysts
- California's SB 54 EPR framework:Mandatory recycled content thresholds and producer funding obligations are accelerating investment in chemical recycling infrastructure and monomaterial design across food packaging applications.
- Quick-service restaurant delivery expansion:National chains are scaling thermoformed container procurement for off-premise consumption formats, pulling resin throughput toward polypropylene clarity grades.
- Southeast U.S. resin clustering:Ethane feedstock proximity and Gulf Coast petrochemical capacity concentration continue attracting extrusion and thermoforming capital deployment.
Market Restraints
- Post-consumer resin price volatility:Baled PET and HDPE bale supply fluctuations create margin compression for converters attempting to meet state-mandated recycled content floors.
- Monomaterial barrier performance gaps:Current polyethylene and polypropylene structures fail to match multi-layer oxygen and moisture barriers required for protein shelf-life extension.
- Landfill tipping fee arbitrage:Disparate municipal solid waste economics across U.S. states distort post-consumer collection incentive alignment.
Strategic Opportunities
- Canadian provincial EPR harmonization:Ontario and British Columbia packaging stewardship programs are creating standardized recovery infrastructure that rewards early design-for-recycling adopters.
- Pharmaceutical blister-to-bottle conversion:Unit-dose compliance packaging demand is expanding rigid PVC and PETG thermoforming capacity for senior care and clinical trial applications.
- Pyrolysis-oflex integration:Chemical recycling output is qualifying for food-contact regulatory pathways that mechanical recycling cannot satisfy, opening virgin displacement routes.
Industry Challenges
- Migration testing backlog:FDA food-contact substance notification review timelines are extending 18-24 months, delaying novel barrier additive commercialization.
- Legacy thermoformer retooling capex:Converting from polystyrene to polypropylene tooling requires mold redesign and forming press modification investments that strain mid-cap balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Single-Use Plastic Packaging Market |
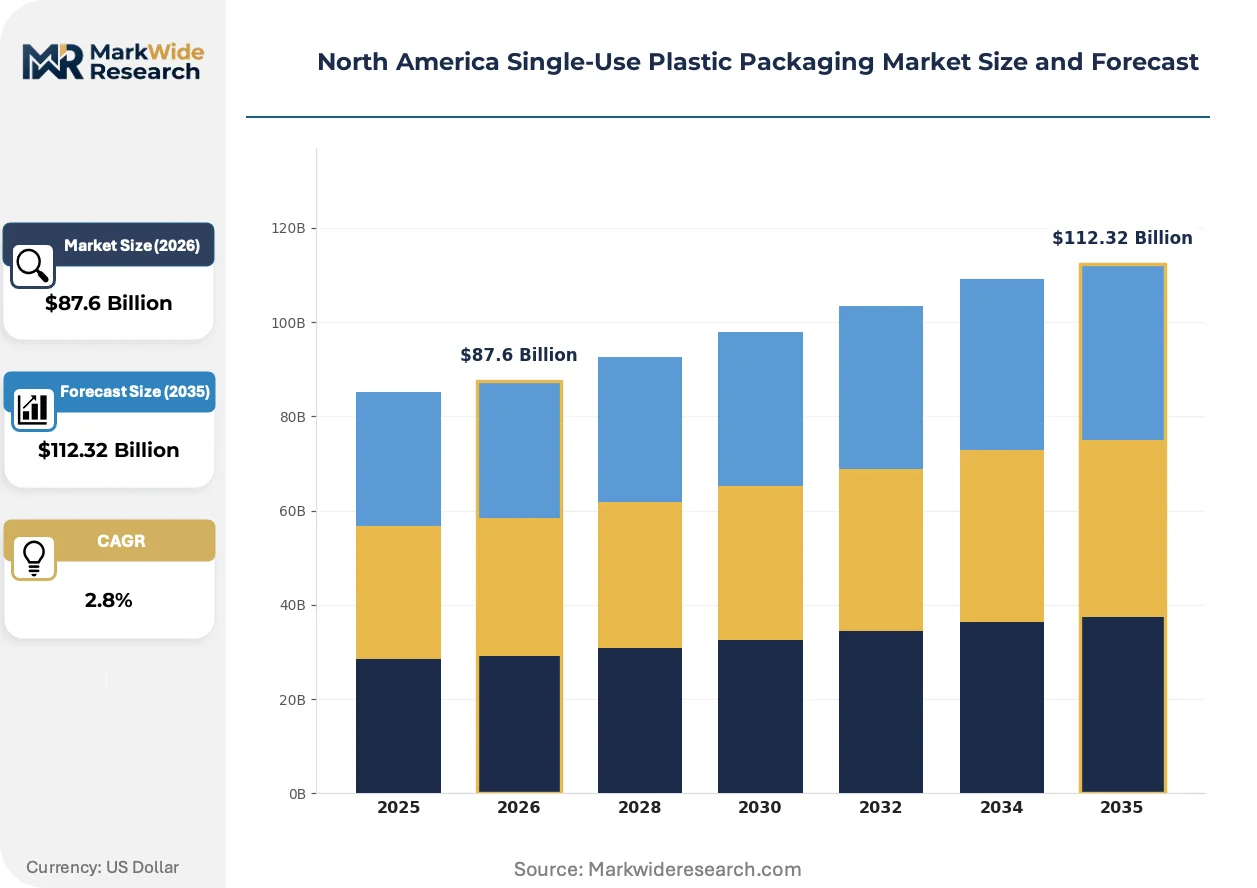
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $112.32 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rigid Containers, Flexible Packaging, Bags, Wraps End User: Food, Beverages, Pharmaceuticals, Personal Care Material: Polyethylene, Polypropylene, Polystyrene, Polyethylene Terephthalate Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Wholesale |
| Companies Covered | Pactiv LLC, Sealed Air Corporation, Berry Global Inc, Winpak Ltd., Sonoco Products Company, Amcor Group GmbH, Dart Container Corporation, Graphic Packaging International Inc, Novolex, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Single-Use Plastic Packaging Market Trends and Innovations
Material science advances and regulatory compliance architectures are converging to redefine specification standards across food-contact and pharmaceutical containment applications.
Advanced pyrolysis and purification technologies are rewriting the food-contact regulatory pathway for recycled polyethylene. Major dairy brands are qualifying chemically recycled resin for direct food-contact bottles ahead of state-mandated minimums. This capability is compressing the virgin resin premium that mechanical recycling could never displace.
Health Canada's proposed single-use plastics prohibition order is accelerating polystyrene displacement across foodservice applications. The draft regulation targets black plastic cutlery and expanded polystyrene containers with 2025 implementation timelines. Quick-service operators in Ontario and Quebec are pre-emptively shifting procurement to polypropylene and molded fiber alternatives.
Subscription-based replenishment contracts are consolidating foodservice distributor purchasing power. National restaurant chains are unbundling single-use item procurement from broadline distribution agreements. This concentration is most visible in the U.S. Southeast, where pooled volume commitments are reshaping converter capacity allocation decisions.
North America Single-Use Plastic Packaging Market Segmentation
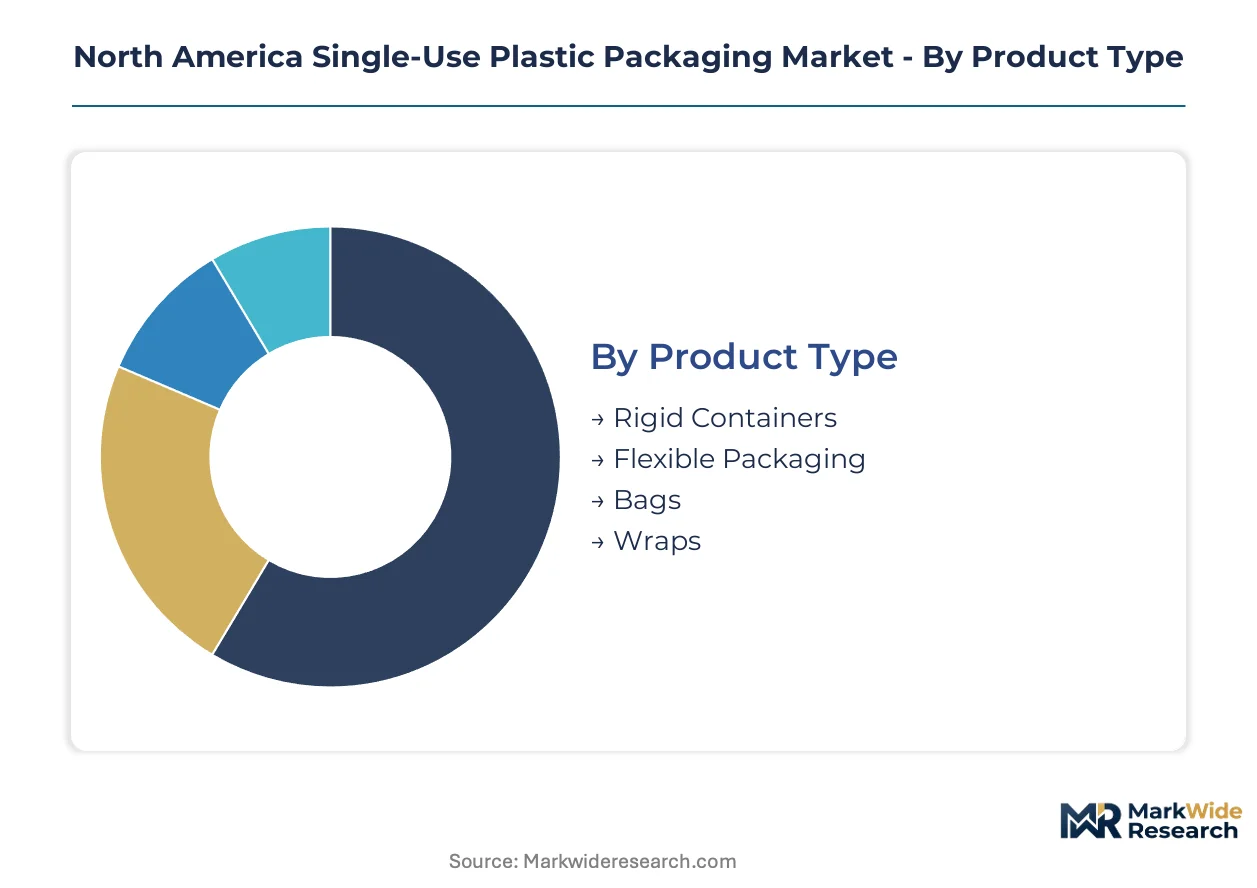
Segmentation in single-use plastic packaging reveals how material specifications, regulatory pathways, and end-use performance requirements partition procurement decisions across converters and brand owners. Understanding these divides clarifies where capital deployment and formulation R&D concentrate.
Product Type:
Equipment replacement cycles and thermoforming press retooling investments are reshaping competitive positioning across container formats.
- Flexible Packaging:Multi-layer films and pouches manufactured through blown or cast extrusion dominate resin throughput due to lower material intensity and cube efficiency in e-commerce fulfillment. Demand concentrates in quick-service restaurant back-of-house operations across the U.S. Southeast, where pooled procurement contracts are compressing unit economics for bag-in-box and pre-portioned pouch formats.
- Rigid Containers:Thermoformed and injection-molded vessels engineered for dimensional stability and barrier precision command specification premiums in dairy bottles and pharmaceutical blisters. The U.S. Southeast resin clustering attracts extrusion blow-molding investment for high-density polyethylene milk jugs and polypropylene clarity grades for prepared food visibility.
- Bags:T-shirt and gusseted configurations produced via high-speed converting lines compete on volume scale in retail grocery checkout and industrial liner applications.
- Wraps:Stretch and shrink films for pallet unitization and retail overwrap serve logistics and food retail segments with commodity-grade polyethylene specifications.
Volume placements concentrate in Flexible Packaging; the faster expansion belongs to Rigid Containers.
End User:
Customer procurement sophistication and regulatory compliance burden stratify margin capture across application verticals.
- Food:Thermoformed trays, clamshells, and lidded containers for protein, produce, and prepared meals face the steepest EPR compliance pressure. California's SB 54 recycled content mandates are forcing reformulation toward chemically recycled polyethylene for direct food-contact approval.
- Pharmaceuticals:Unit-dose blister packs and compliance bottles demand migration-tested additives and barrier precision that mechanical recycling cannot satisfy. Health Canada and FDA notification backlogs are extending qualification timelines for novel barrier technologies.
- Beverages:Carbonated soft drink bottles and dairy containers drive PET and HDPE resin demand with established collection infrastructure.
- Personal Care:Cosmetic tubes and dispensing closures utilize polypropylene and polystyrene with lower barrier requirements but higher aesthetic specifications.
Revenue concentration sits with Food; Pharmaceuticals is climbing the fastest on compliance-driven specification premiums.
Material:
Resin selection trade-offs between barrier performance, recyclability, and regulatory approval status are displacing legacy formulations.
- Polyethylene:Low-density and linear low-density grades dominate flexible film production for moisture barrier applications. FDA food-contact pathways for chemically recycled polyethylene are opening virgin displacement routes ahead of state-mandated minimums.
- Polypropylene:Random copolymer clarity grades are capturing foodservice container demand as Health Canada's polystyrene prohibition accelerates material switching.
- Polystyrene:General-purpose and high-impact grades face regulatory phase-out in Canadian provinces and California jurisdictions.
- Polyethylene Terephthalate:Bottle-grade resin with established mechanical recycling infrastructure serves beverage and pharmaceutical applications.
Polyethylene retains volume leadership; Polypropylene is gaining share fastest on thermoforming clarity and EPR compliance advantages.
Distribution Channel:
Channel control points and inventory velocity requirements segment customer relationships and working capital intensity.
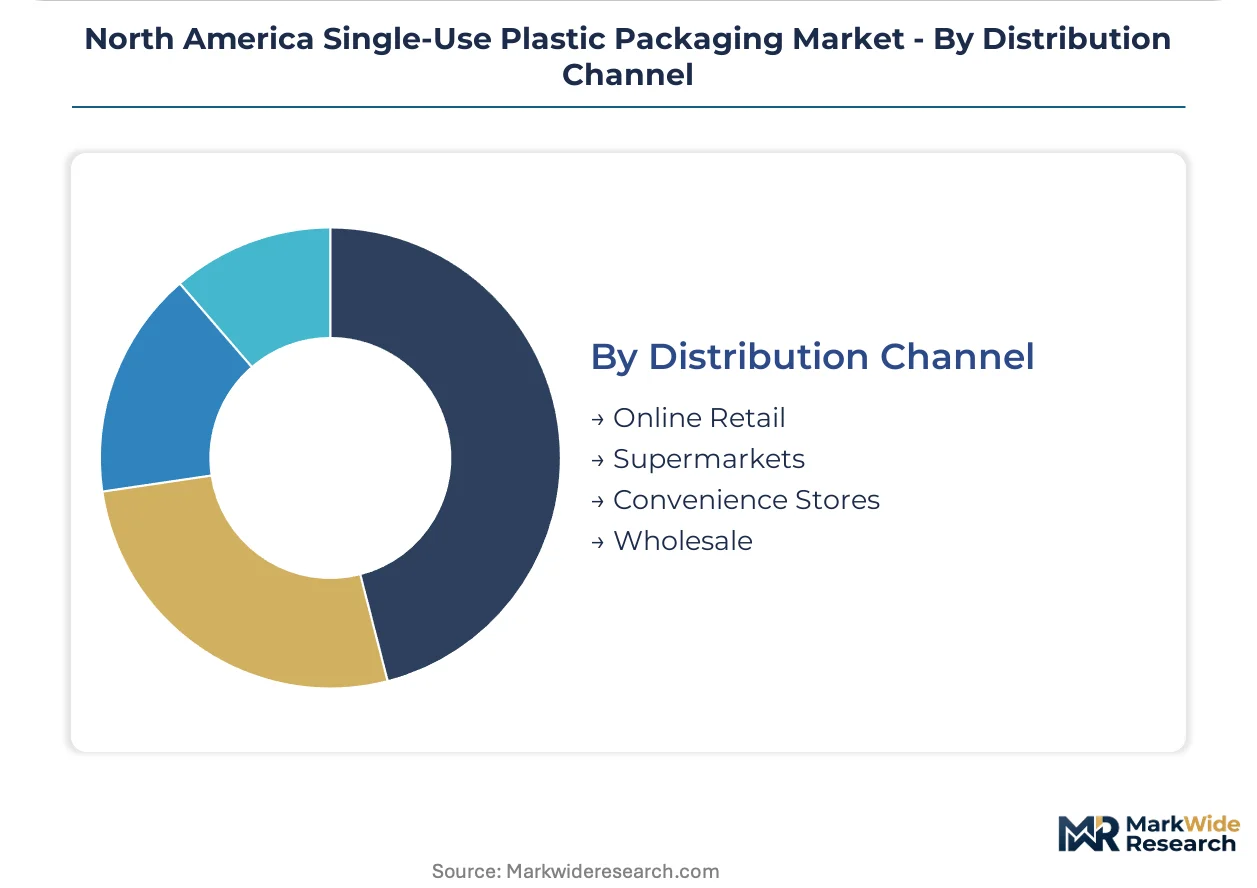
- Wholesale:Broadline foodservice distributors and industrial packaging suppliers manage bulk pallet and truckload shipments to converter and end-user facilities. The U.S. Southeast concentration of resin production and thermoforming capacity reinforces regional wholesale hub positioning.
- Supermarkets:Retail grocery chains procure private-label bags, wraps, and disposable containers through direct converter relationships.
- Online Retail:E-commerce platforms for restaurant supplies and industrial MRO are consolidating small-lot procurement.
- Convenience Stores:Impulse and immediate-consumption packaging for prepared foods and beverages.
Wholesale channels handle the greatest tonnage; Online Retail is expanding most quickly on subscription replenishment model adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston-Gulf Coast petrochemical corridor anchors North American resin production, with ethane crackers and downstream conversion facilities clustering within fifty miles of Port Houston. This concentration shapes packaging investment flows across the continent.
United States
Quick-service restaurant chains are scaling thermoformed container procurement for delivery formats across the Southeast. California's SB 54 mandates recycled content thresholds that accelerate chemical recycling infrastructure deployment. The Gulf Coast resin corridor attracts extrusion and thermoforming capital from converters seeking feedstock proximity.
Canada
Ontario and Quebec quick-service operators are pre-emptively shifting procurement from polystyrene to polypropylene ahead of federal prohibition timelines. Health Canada's draft single-use plastics prohibition targets black plastic cutlery and expanded polystyrene with 2025 implementation. Toronto and Montreal serve as distribution hubs for foodservice packaging serving the Great Lakes and St. Lawrence corridors.
Mexico
Beverage bottlers in the Bajío region and Mexico City metro area are expanding PET bottle production for domestic consumption and U.S. export markets. Mexican environmental regulations on single-use plastics vary by state, with Mexico City and Oaxaca implementing stricter restrictions than federal baselines. Monterrey's industrial base hosts thermoforming operations supplying prepared food containers to Texas and California markets.
North America Single-Use Plastic Packaging Market Competitive Landscape
Capital-heavy resin producers and integrated converters compete with asset-light packaging designers and regional thermoformers across specification tiers. The market structure concentrates around three to five vertically integrated players with captive resin access, while mid-cap specialists occupy niche barrier film and pharmaceutical blister segments. Strategic archetypes include Gulf Coast-integrated resin converters, barrier technology licensors, and foodservice-focused thermoformers. Dominant competitive moves center on chemical recycling partnerships and thermoforming press retooling for monomaterial compliance.
Among North American-integrated packaging conglomerates, Pactiv LLC, Sealed Air Corporation, and Berry Global Inc occupy positions across the resin-to-converter value chain. Pactiv exemplifies the thermoforming scale archetype with supply agreements anchored in pooled procurement contracts. Sealed Air represents the barrier technology specialist tier, sustaining positioning through proprietary film formulations. Berry Global sits within the rigid container mass-production segment, serving dairy and prepared food applications where specification premiums concentrate.
| Leading Market Players |
|---|
| Pactiv LLC |
| Sealed Air Corporation |
| Berry Global Inc |
| Winpak Ltd. |
| Sonoco Products Company |
| Amcor Group GmbH |
| Dart Container Corporation |
| Graphic Packaging International Inc |
| Novolex |
| Others |
Pricing and Supply Chain Analysis
Chemical recycling scale-up is compressing virgin resin premiums while concentrating converter margins among Gulf Coast-integrated players. California SB 54 mandates and Canadian EPR frameworks simultaneously reshape cost structures and procurement geography across the North American market.
Pricing Analysis
Food-contact certification tiers anchor value-based pricing across recycled content grades. Three-tier pricing structure across premium, standard, and economy levels separates FDA-approved chemically recycled polyethylene from mechanical recycling and virgin resin alternatives. Pricing pressure stems from post-consumer resin bale supply volatility as converters strain to meet state-mandated recycled content floors. Quick-service restaurant chains exhibit highest price sensitivity through pooled procurement contracts, while pharmaceutical blister pack buyers accept specification premiums for migration-tested barrier additives.
Supply Chain Analysis
Dual-sourcing requirements from national restaurant chains and dairy cooperatives mandate multi-supplier qualification across resin grades and thermoforming capacity. Supply concentrates in the United States Gulf Coast, Canada Ontario corridor, and Mexico Bajío region for ethane feedstock proximity and conversion infrastructure. Raw material dependencies center on ethane feedstock, catalyst additives for barrier films, and FDA-compliant colorants. Tariff exposure on Canadian and Mexican converted goods creates structural risk amid USMCA renegotiation pressures. Distribution runs through wholesale foodservice distributors and direct converter relationships with retail grocery chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Chemical recycling capacity bottlenecks prop pricing power for early movers with food-contact regulatory approvals. Supply constraints in post-consumer resin qualification timelines reinforce incumbent positioning.
For Market Incumbents: Hedge polystyrene displacement risk by accelerating polypropylene clarity grade capacity in the U.S. Southeast. Secure backward integration into pyrolysis-oflex output to capture virgin displacement premiums ahead of California SB 54 recycled content mandates. Prioritize mold retooling partnerships with mid-cap thermoformers facing balance sheet constraints. For New Entrants and Emerging Players: Capture pharmaceutical blister-to-bottle conversion demand in Ontario and Quebec as Health Canada prohibition timelines accelerate material switching. Target senior care and clinical trial packaging segments where FDA notification backlogs create qualification barriers for established players. Pursue direct-to-foodservice distributor relationships outside pooled national chain contracts. For Investors and Strategic Acquirers: Exit pathways concentrate in chemical recycling technology licensors and Gulf Coast-integrated converters with captive resin access. Five-to-ten year viability favors players with simultaneous thermoforming scale and pyrolysis partnerships. Watch FDA food-contact substance notification clearance timelines as inflection indicator for barrier additive commercialization velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Partnership | Pyrolysis-oflex integration unlocks food-contact pathways mechanical recycling cannot satisfy. |
| Thermoforming Press Retooling | Polystyrene-to-polypropylene mold redesign addresses Health Canada prohibition timelines. |
| Subscription Replenishment Contract | Pooled volume commitments from national chains reshape converter capacity allocation decisions. |
| Barrier Film R&D Investment | Proprietary oxygen and moisture technologies capture protein packaging specification premiums. |
| Extended Producer Responsibility Compliance | California SB 54 funding obligations accelerate monomaterial design across food applications. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with thermoforming plant managers, foodservice distributor procurement leads, resin supplier technical directors, and quick-service restaurant supply chain executives combined with bottom-up and top-down triangulation. Secondary sources included EPA municipal solid waste reports, FDA food-contact substance notification databases, Health Canada regulatory proposals, and state-level EPR legislation tracking.
Granularity-level modeling operated at product type, end user, material, and distribution channel dimensions across the analysis window. CAGRs derived from resin throughput projections, thermoforming capacity expansion announcements, and regulatory compliance timeline assumptions. Industry-specific inputs incorporated chemical recycling facility commissioning schedules and state-by-state recycled content mandate phase-in curves.
The model holds under stable regulatory enforcement timelines and resin feedstock cost structures; deviation in pyrolysis capacity deployment rates or EPR funding mechanism litigation would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Saudi Arabia Plastic Bottles Market
Plastic Packaging
Asia Pacific Plastic Packaging Market
Plastic Packaging
Low Density Polyethylene (LDPE) Packaging Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
South America Polyethylene Terephthalate (PET) Market
Plastic Packaging
Europe Polyethylene Terephthalate (PET) Market
Plastic Packaging
BOPP Tobacco Films Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
Global Plastic Container Market
Plastic Packaging
Plastic Vials Market
Plastic Packaging
Australia Plastic Packaging Market
Plastic Packaging
Middle East and Africa Plastic Bottles Market
Plastic Packaging
Global Plastic Tarpaulin Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
Conductive Plastic Boxes Market