
 UVI Stretch Films Market | 2026-2036
UVI Stretch Films Market Size, Share, and Industry Trends Forecast 2026-2036
UVI Stretch Films Market Analytics
Buyer concentration among food packaging distributors is recalibrating procurement leverage across the UVI stretch films supply base. Berry Global Group, Inc. leverages its North American manufacturing footprint to serve consolidated retail grocery networks. Paragon Films, Inc. specializes in high-performance machine films for automated palletizing lines. Dana Poly, Inc. anchors its position through backward integration into resin compounding operations.
UVI stretch films incorporate ultraviolet inhibitors—typically hindered amine light stabilizers and benzotriazole derivatives—into polyethylene or polypropylene substrates to prevent photodegradation during outdoor storage and transit. These films maintain tensile strength above 20 MPa after prolonged sun exposure, protecting palletized goods in open-yard logistics. Machine stretch films dominate volume throughput in automated distribution centers, while pharmaceutical packaging commands premium pricing due to validated barrier requirements. Pre-stretched films are gaining share in hand-application settings where labor efficiency matters. Thickness segments below 20 micron face margin compression as resin volatility outpaces pricing power.
The EPA regulates volatile organic compound emissions from film extrusion processes under Clean Air Act standards, while FDA compliance governs food-contact additive migration limits. REACH restrictions in Europe constrain certain UV stabilizer chemistries, redirecting formulation investments toward compliant alternatives. ISO 9001 and ISO 14001 certifications function as baseline qualifiers for supplier qualification at major industrial buyers. Stakeholders must monitor evolving state-level extended producer responsibility mandates that could reshape collection and recycling infrastructure obligations.
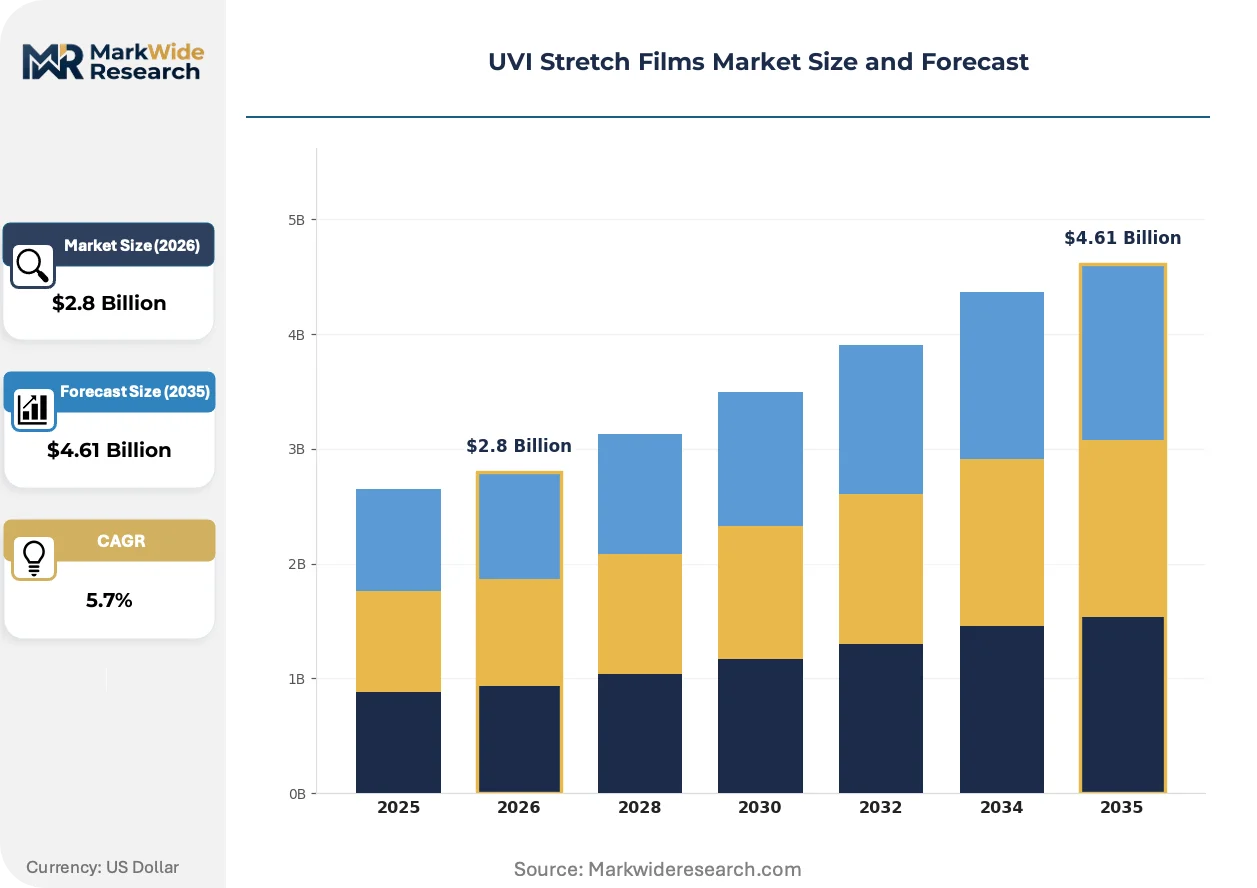
Market Dynamics
Consolidation among North American food packaging distributors is compressing supplier margins while REACH migration limits in Europe force reformulation investments. Machine film automation in Germany's logistics corridor is concentrating volume with high-throughput producers capable of validated barrier performance.
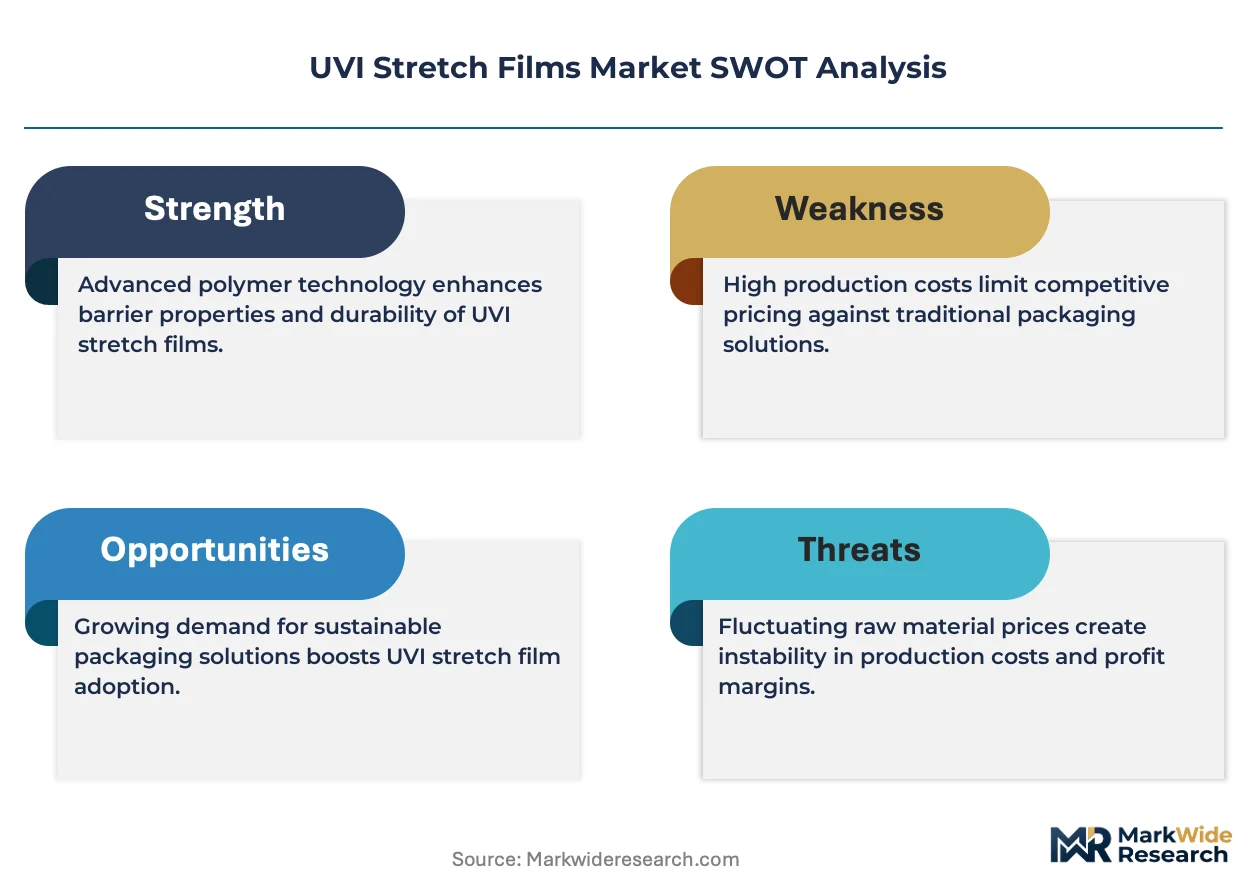
Growth Catalysts
- Automated Palletizing Expansion:Distribution centers across Germany and the Netherlands are retrofitting lines for high-speed stretch wrapping. Machine films with validated cling and puncture resistance capture disproportionate volume.
- REACH Compliance Investments:ECHA's tightening additive migration limits are accelerating substitution toward benzotriazole-free stabilizer packages. Early movers secure pharmaceutical and food-contact qualifications ahead of enforcement deadlines.
- Outdoor Storage Logistics:Open-yard container terminals in Spain and Italy require UVI films maintaining tensile integrity above 20 MPa after prolonged Mediterranean sun exposure. Port operators specify certified outdoor-grade specifications.
Market Restraints
- Resin Cost Volatility:Ethylene and propylene feedstock swings compress margins on sub-20 micron commodity grades. Producers lack pricing power to pass through input spikes.
- Supplier Concentration Risk:UV stabilizer production concentrates among three European specialty chemical houses. Disruption to hindered amine light stabilizer supply chains halts compliant film extrusion.
- Mechanical Recycling Limitations:Cross-linked metallocene polyethylene structures resist conventional reprocessing. Circular economy mandates face technical barriers without chemical recycling infrastructure.
Strategic Opportunities
- Pharmaceutical Cold Chain:Temperature-validated UVI films for vaccine pallet shipments command premium positioning. EMA serialization requirements create barrier-to-entry for qualified suppliers.
- Pre-Stretched Hand Films:Labor-constrained warehouses in France and Poland are converting from conventional hand-wrap to pre-stretched formats. Reduced operator fatigue and material yield drive adoption.
- Extended Producer Responsibility:France's AGEC law and impending EU Packaging Regulation mandate recycled content minimums. Film producers with in-house reprocessing capabilities capture compliance-driven demand.
Industry Challenges
- Additive Migration Testing Timelines:EFSA food-contact notifications require 12-18 month evaluation cycles. New stabilizer introductions face extended commercialization horizons.
- Metrology Standardization Gaps:Inconsistent UV exposure testing protocols across ISO, ASTM, and EN methods create specification mismatches between buyers and suppliers.
- Skilled Extrusion Technician Scarcity:Multi-layer blown film operations require operators capable of die gap adjustment and gauge control. Training pipelines lag automation investments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UVI Stretch Films Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.61 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Machine Stretch Films, Hand Stretch Films, Pre-Stretched Films, Micro-Perf Films Application: Food Packaging, Pharmaceutical Packaging, Industrial Packaging, Retail Packaging Thickness: Below 15 Micron, 15-20 Micron, 20-25 Micron, Above 25 Micron Formulation: Polyethylene, Polypropylene, PVC, Others |
| Companies Covered | Dana Poly, Inc., Transhield, Inc., Nexus Plastics, Inc., Navrang Polyfilms, Reliant Packaging Films Ltd., Johnson Plastic & Supply Co., Larsen Packaging Products, Paragon Films, Inc., Berry Global Group, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UVI Stretch Films Market Evolving Landscape
Formulation science and film architecture are converging to address outdoor durability requirements while regulatory pressure accelerates substitution away from legacy stabilizer chemistries.
Metallocene polyethylene resins with narrow molecular weight distribution are decentralizing performance film production away from commodity-grade suppliers. Automated distribution centers in Belgium and the Netherlands specify these materials for high-speed pre-stretch applications. The technology enables thinner-gauge films to match legacy puncture resistance, compressing resin intensity per pallet wrapped.
ECHA's restriction roadmap for certain benzotriazole UV absorbers is forcing reformulation toward hindered amine light stabilizer alternatives. Film extruders must revalidate food-contact compliance and outdoor performance claims under accelerated aging protocols. Pharmaceutical packaging buyers in Switzerland and Germany are tightening supplier qualification requirements to exclude restricted substances ahead of formal deadlines.
Consolidated retail grocery networks are consolidating stretch film procurement through centralized category management functions. Regional distributors in Italy and Spain are losing direct supplier relationships as buying power concentrates at headquarters level. This shift favors producers with pan-European manufacturing footprints capable of consistent specification delivery across multiple national markets.
UVI Stretch Films Market Segmentation
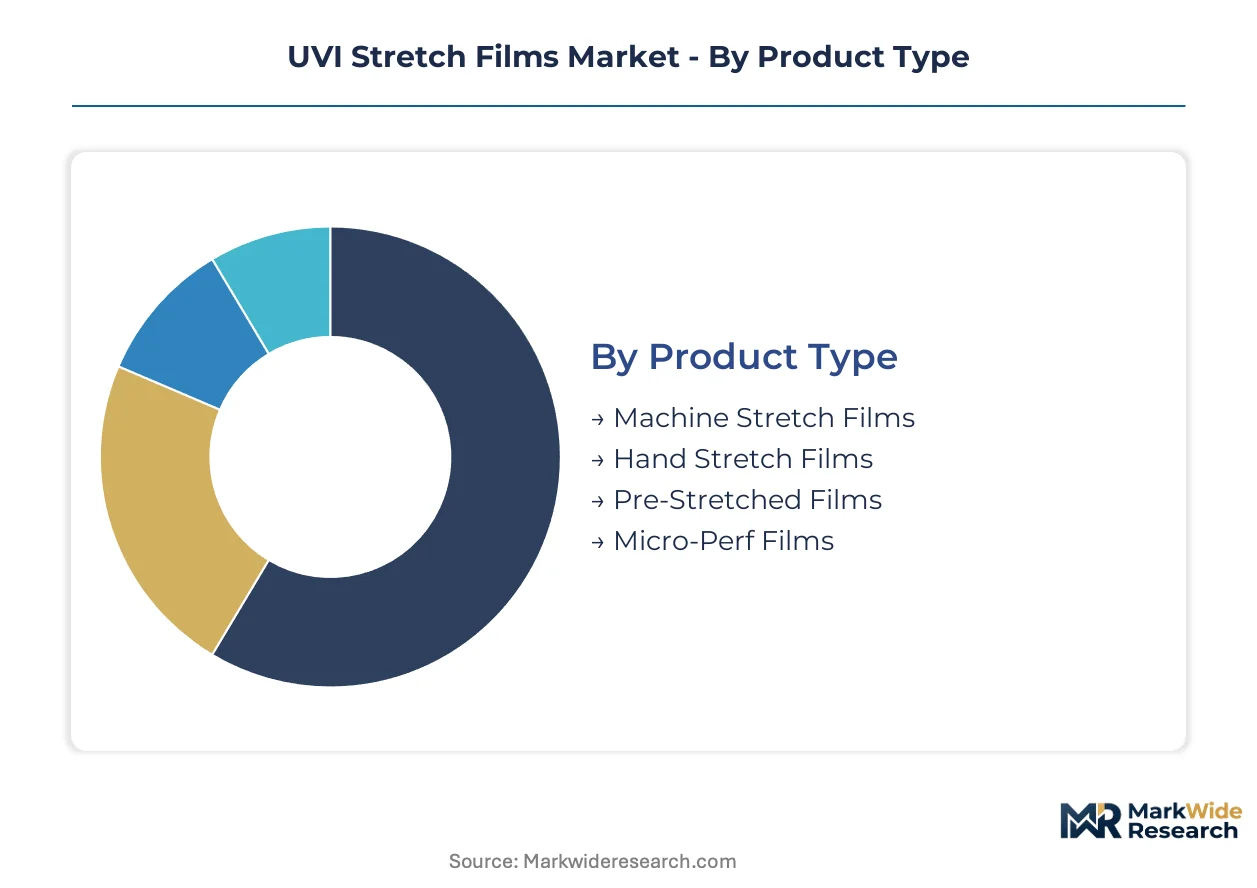
UVI stretch film purchasing decisions diverge sharply between automated distribution centers requiring validated machine specifications and hand-application settings where labor efficiency dominates. Thickness and formulation choices directly determine compliance pathways under REACH additive restrictions and outdoor performance warranties.
Product Type:
Supply concentration among high-throughput extruders favors formats compatible with continuous production runs and minimal changeover complexity.
- Machine Stretch Films:High-speed cast extrusion produces films with consistent cling and puncture resistance for automated palletizing lines. Distribution centers across Germany and the Netherlands specify these materials for throughput rates exceeding 100 pallets per hour, with validated barrier performance commanding supplier qualification premiums.
- Pre-Stretched Films:In-line orientation reduces film thickness while maintaining tensile integrity, cutting resin consumption per pallet by 30-40%. Labor-constrained warehouses in France and Poland are converting from conventional hand-wrap to pre-stretched formats where operator fatigue reduction drives procurement decisions.
- Hand Stretch Films:Blown extrusion yields higher puncture resistance for irregular loads in construction and agriculture applications.
- Micro-Perf Films:Perforation patterns enable moisture escape for fresh produce pallet shipments requiring breathable barriers.
Today's leader: Machine Stretch Films. Tomorrow's challenger: Pre-Stretched Films.
Application:
End-use qualification requirements create tiered margin structures, with pharmaceutical and food-contact segments demanding additive migration documentation that commodity industrial buyers bypass.
- Food Packaging:EFSA food-contact notifications govern hindered amine light stabilizer selection, with 12-18 month evaluation cycles delaying new formulation commercialization. Berry Global Group serves consolidated North American retail grocery networks through centralized category management contracts.
- Pharmaceutical Packaging:Temperature-validated UVI films for vaccine cold chain shipments command premium positioning. EMA serialization requirements and barrier validation protocols create qualification barriers that exclude commodity extruders.
- Industrial Packaging:Open-yard container terminals in Spain and Italy specify outdoor-grade specifications maintaining tensile integrity above 20 MPa after Mediterranean sun exposure.
- Retail Packaging:Hand-application settings in smaller distribution operations favor convenience over performance optimization.
Food Packaging captures current volume concentration. Pharmaceutical Packaging offers the steepest expansion trajectory.
Thickness:
Downgauging pressure from resin cost volatility is compressing margins on ultra-thin commodity grades while thicker specifications retain pricing power through performance differentiation.
- Below 15 Micron:Metallocene polyethylene resins with narrow molecular weight distribution enable puncture resistance matching legacy 20-micron films. Automated lines in Belgium and the Netherlands specify these materials for resin intensity reduction per pallet wrapped.
- 15-20 Micron:The historical standard for general-purpose pallet wrapping faces margin compression as producers lack pricing power to pass through ethylene feedstock spikes.
- 20-25 Micron:Heavy-duty applications in construction materials and metal coil shipping require elevated puncture resistance.
- Above 25 Micron:Specialty agricultural and maritime applications specify maximum UV inhibitor loading for multi-season outdoor exposure.
Below 15 Micron leads current technology adoption. Above 25 Micron defends margin through performance specialization.
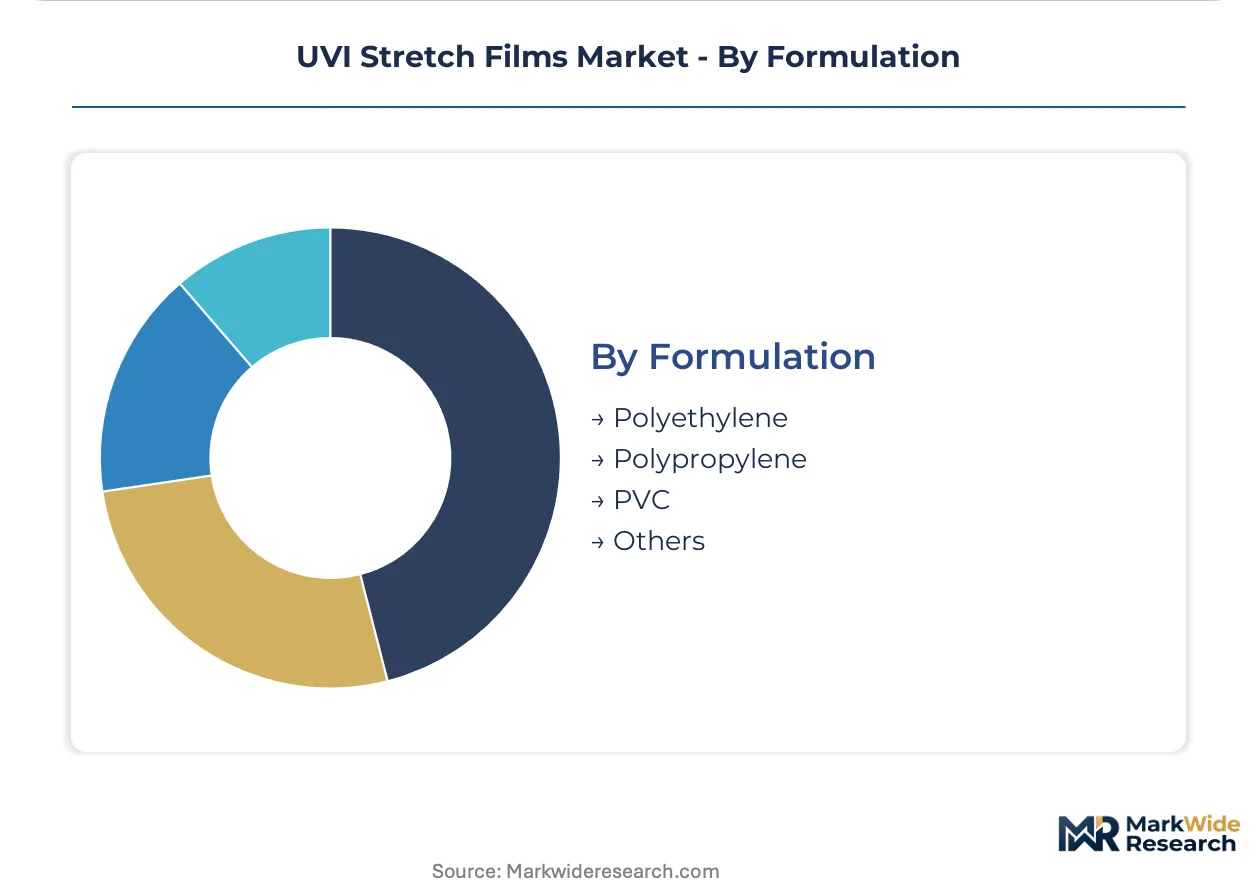
Formulation:
REACH restrictions on benzotriazole UV absorbers are redirecting resin-stabilizer compatibility investments toward compliant alternative chemistries.
- Polyethylene:Linear low-density and metallocene grades dominate machine film production for their processability and cling characteristics. Dana Poly's backward integration into resin compounding secures formulation control for food-contact qualifications.
- Polypropylene:Higher stiffness and temperature resistance suit pharmaceutical cold chain applications where pallet stability during transit matters.
- PVC:Legacy formulations persist in specific industrial applications requiring cling without adhesive additives.
- Others:Bio-based and recycled-content experimental grades face mechanical property limitations in high-speed wrapping applications.
Polyethylene holds incumbent supply chain integration. Polypropylene gains share fastest in premium barrier segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's logistics corridor commands machine film volumes that dwarf Spain's outdoor-grade specifications, yet both markets face divergent regulatory pressures under REACH and national packaging laws.
Germany
Automated distribution centers along the Rhine-Ruhr and Bavarian logistics corridors specify high-throughput machine films for palletizing rates exceeding 100 units hourly. ECHA's benzotriazole restriction roadmap forces reformulation investments among extruders serving pharmaceutical buyers in Baden-Württemberg. The Port of Hamburg's container terminals require certified outdoor-grade tensile integrity for open-yard steel coil storage.
United States
Consolidated retail grocery networks in the Midwest and Southeast are centralizing stretch film procurement through category management functions. EPA Clean Air Act standards govern volatile organic compound emissions from extrusion operations in Ohio and Texas resin processing corridors. Berry Global Group anchors supply relationships through its North American manufacturing footprint serving automated Walmart and Kroger distribution hubs.
Spain
Mediterranean container terminals in Valencia and Barcelona specify UVI films maintaining above 20 MPa tensile strength after prolonged sun exposure. The national packaging waste law implements extended producer responsibility mandates that reshape collection infrastructure obligations. Agricultural export cooperatives in Andalusia drive demand for micro-perforated breathable formats for fresh produce pallet shipments.
France
Labor-constrained warehouses in Île-de-France and Hauts-de-France are converting from conventional hand-wrap to pre-stretched films where operator fatigue reduction determines procurement. The AGEC anti-waste law mandates recycled content minimums that favor producers with in-house reprocessing capabilities. Lyon-based pharmaceutical cold chain operators require temperature-validated barrier specifications for vaccine distribution.
Netherlands
Rotterdam port logistics and the Eindhoven distribution cluster specify metallocene polyethylene machine films for resin intensity reduction per pallet wrapped. Dutch implementation of EU Packaging Regulation creates compliance-driven demand for circular economy infrastructure investments. Automated fulfillment centers serving Benelux retail networks validate cling and puncture resistance through continuous production run qualifications.
UVI Stretch Films Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered supply positions. The vendor base concentrates among resin-integrated extruders, independent film converters, and regional packaging distributors. Three archetypes dominate: backward-integrated resin compounders controlling formulation pipelines, high-throughput machine film specialists serving automated logistics, and niche outdoor-grade producers targeting Mediterranean port terminals. Competitive moves center on M&A for geographic footprint expansion and strategic partnerships for REACH-compliant stabilizer supply security.
Among North American resin-integrated players, Dana Poly, Inc. and Berry Global Group, Inc. exemplify the backward-integration archetype through captive compounding operations. Paragon Films, Inc. occupies a position within the high-performance machine film tier. These three names anchor the competitive structure without exhausting the supplier base.
| Leading Market Players |
|---|
| Dana Poly, Inc. |
| Transhield, Inc. |
| Nexus Plastics, Inc. |
| Navrang Polyfilms |
| Reliant Packaging Films Ltd. |
| Johnson Plastic & Supply Co. |
| Larsen Packaging Products |
| Paragon Films, Inc. |
| Berry Global Group, Inc. |
| Others |
Value Network & Pricing Analysis
Backward integration into resin compounding operations anchors both supply security and pricing leverage for UVI stretch film producers serving REACH-regulated European markets and consolidated North American retail networks. Captive stabilizer formulation control separates qualified pharmaceutical suppliers from commodity extruders facing margin compression on sub-20 micron grades.
Pricing Analysis
Capacity additions in Germany's logistics corridor are reshaping price floors for machine-grade UVI films as high-throughput producers capture volume from automated distribution centers. Three-tier pricing structure across pharmaceutical-certified, food-contact standard, and industrial commodity levels reflects migration documentation requirements and barrier validation intensity. Pricing pressure stems from ethylene feedstock volatility that producers cannot pass through on thin-gauge commodity contracts. Industrial packaging buyers exhibit highest price sensitivity, while pharmaceutical cold chain operators accept premium positioning for temperature-validated specifications.
Supply Chain Analysis
UV stabilizer supply rests on German, Swiss, and Belgian specialty chemical producers controlling hindered amine light stabilizer and benzotriazole derivative production. Ethylene and propylene feedstocks draw from North American shale corridors and Middle Eastern naphtha crackers. Single-source vulnerability concentrates around three European additive houses capable of REACH-compliant formulation. Distribution runs through pan-European film converters, North American resin-integrated extruders, and regional packaging distributors serving port logistics clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UVI stretch films market functions as a stable compounder anchored by automation investments in European logistics infrastructure that sustain replacement demand cycles.
For Market Incumbents: Extend formulation qualification pipelines ahead of ECHA benzotriazole enforcement deadlines to secure pharmaceutical buyer relationships. Deepen captive resin compounding capabilities to defend margin position against ethylene price volatility. Target pre-stretched film capacity expansion in France and Poland where labor-constrained warehouses are converting formats.
For New Entrants and Emerging Players: Enter via pharmaceutical cold chain specializations where EMA serialization requirements create qualification barriers excluding commodity extruders. Target micro-perforated breathable formats for Spanish agricultural export cooperatives. Pursue toll manufacturing arrangements with established compounders to bypass additive supply security constraints.
For Investors and Strategic Acquirers: Roll-up economics work for regional film converters with in-house reprocessing capabilities because France's AGEC law and impending EU Packaging Regulation mandate recycled content minimums. Focus on five-to-ten year viability windows for REACH-compliant stabilizer technology platforms. Monitor EFSA food-contact notification backlogs as inflection indicator for new formulation commercialization timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Dana Poly's captive formulation control secures food-contact qualification pipelines ahead of competitor submissions. |
| REACH-Compliant Stabilizer Reformulation | Early movers toward benzotriazole-free packages capture pharmaceutical buyer relationships before enforcement deadlines. |
| Pre-Stretched Film Capacity Expansion | France and Poland warehouse conversions create demand pull for labor-reducing hand-application formats. |
| In-House Reprocessing Capability Buildout | Producers with circular infrastructure capture compliance-driven demand under France's AGEC law mandates. |
| Pharmaceutical Cold Chain Qualification | Temperature-validated barrier specifications command premium positioning for vaccine distribution networks. |
Research Methodology
Multiple input streams — extrusion plant manager interviews, procurement lead surveys at downstream distributors, and regulatory filing analysis — were reconciled to construct demand estimates. Primary fieldwork engaged blown film technicians, category buyers at consolidated retail grocery networks, and ECHA regulatory affairs specialists. Secondary validation drew from customs trade databases, SEC 10-K resin segment disclosures, and Cefic chemical industry reports. Bottom-up capacity modeling and top-down end-use consumption estimates were triangulated to anchor volume projections.
Data-stream reconciliation across machine film throughput rates, hand-application conversion trends, and pharmaceutical barrier qualification timelines generated segment-level growth trajectories across the projection horizon. Modeled dimensions span product type, application end-use, thickness tier, and base resin formulation. CAGRs were derived from elasticity-adjusted demand curves and capacity utilization benchmarks. Forecast inputs incorporated REACH restriction implementation schedules and automated palletizing line installation rates at German distribution centers.
The model holds under stable regulatory enforcement timelines; deviation in ECHA additive restriction acceleration or extended producer responsibility mandate timing would shift commercialization horizons. Forecasts reflect assumptions about resin price volatility bands and qualification backlog durations. A small set of named triggers — stabilizer supply disruption, feedstock price spike duration, and pharmaceutical serialization requirement changes — warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Blow Molded Plastic Bottles Market
Plastic Packaging
Europe Plastic Bottles Market
Plastic Packaging
Plastic T-Shirt Bags Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Plastic Aerosol Packaging Market
Plastic Packaging
MDPE Bottles Market
Plastic Packaging
France Plastic Bottles Market
Plastic Packaging
Germany Plastic Bottles Market
Plastic Packaging
Plastic Crates Market
Plastic Packaging
Plastic Medicine Bottles Market
Plastic Packaging
Fluorinated Bottle Market
Plastic Packaging
United Kingdom Plastic Packaging Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
South Africa Plastic Packaging Market
Plastic Packaging
Banding Stretch Film Market
Plastic Packaging
France Plastic Packaging Market