
 Russia Plastic Packaging Market | 2026-2036
Russia Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Plastic Packaging Market Analytics
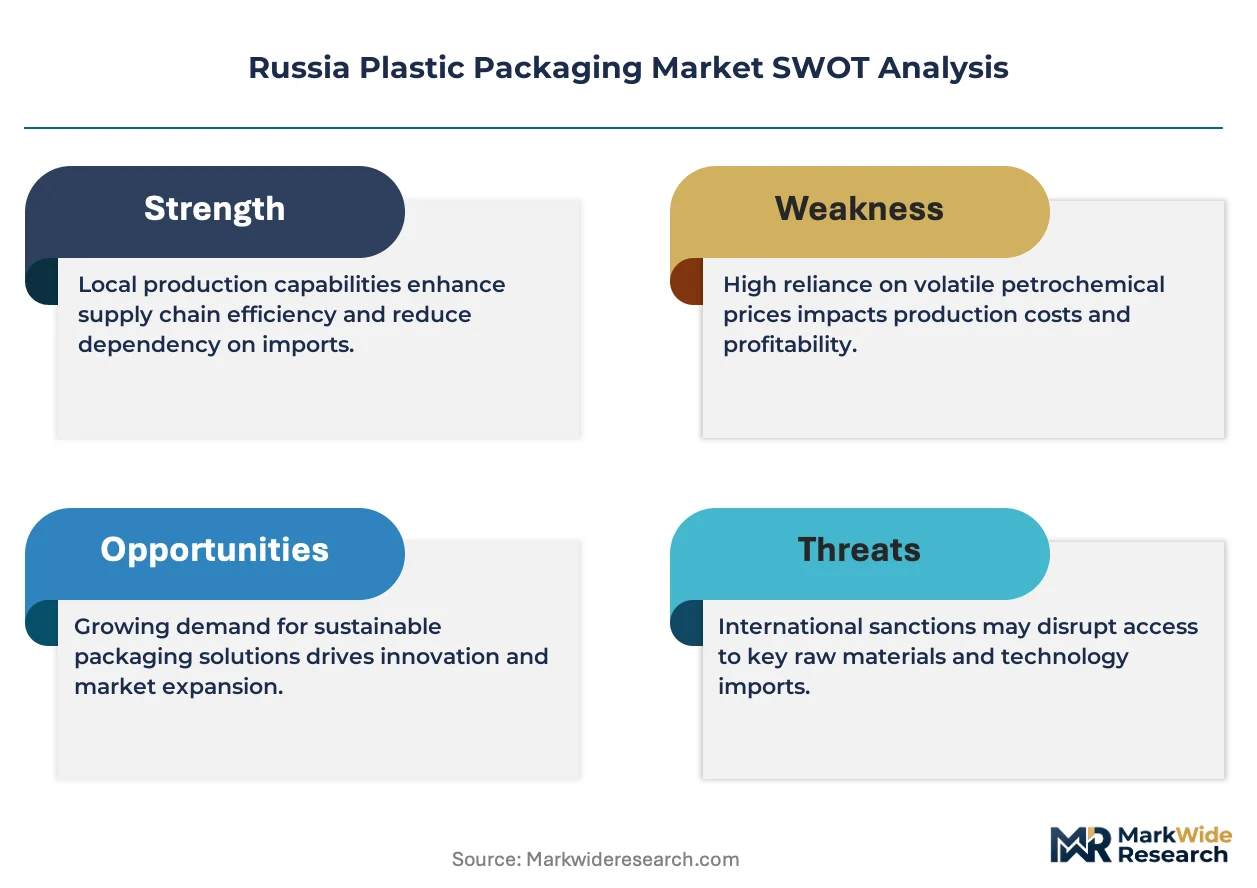
The gap between premium barrier films and commodity-grade polyethylene wrap is restructuring competitive tiers across Russia. SIBUR Holding leverages its upstream petrochemical base to dominate resin supply for mid-market converters. ALPLA anchors its position through rigid container specialization for beverage and dairy clients. Mondi Group competes with integrated paper-plastic hybrid formats that address sustainability-sensitive retail chains.
Russia plastic packaging encompasses thermoplastic resin-based containment systems formed through blow molding, injection molding, thermoforming, or extrusion processes, typically specified by barrier performance, seal integrity, and migration limits for direct food contact. Flexible packaging leads volume due to its lightweight profile and cost efficiency in long-distance distribution across Russia's sparse rail networks. Blow molding occupies a mature but stable position in beverage and personal care rigid formats where dimensional consistency matters. Injection molding concentrates margin pools in pharmaceutical and medical device trays where precision tolerances and cleanroom compatibility command premium pricing.
Russia's Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces TR CU 005/2011, while the Eurasian Economic Commission harmonizes cross-border packaging standards among member states. These frameworks shape material selection, migration testing protocols, and market access for imported packaging substrates. Stakeholders must monitor regulatory alignment between Russian national standards and EAEU technical regulations as customs barriers and local content requirements evolve.
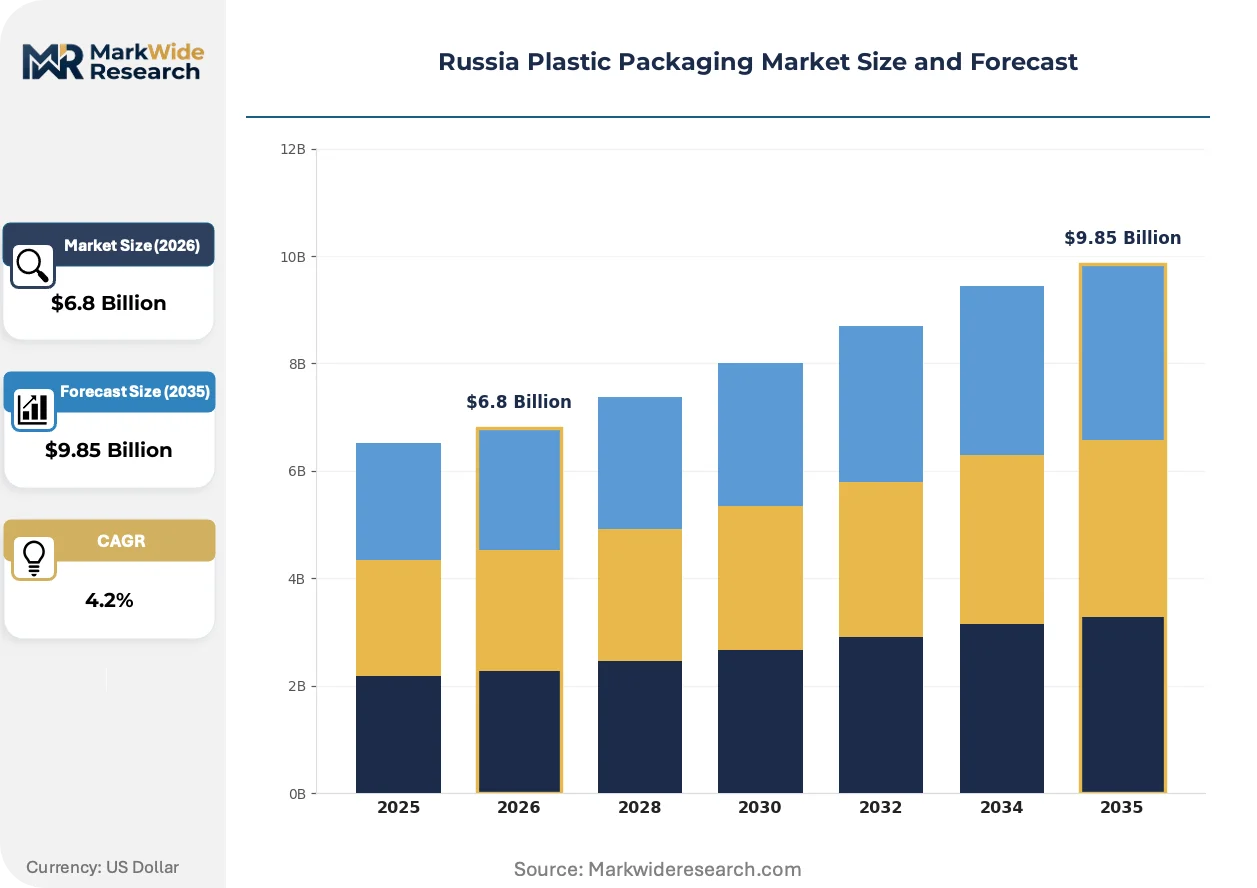
Market Dynamics
TR CU 005/2011 migration limits are forcing domestic converters to rebuild material qualification pipelines, compressing time-to-market for new barrier film grades while elevating testing costs across Russia's Central Federal District production cluster.
Growth Catalysts
- Flexible barrier film specification:Food and beverage producers across Russia's rail-linked distribution corridors are specifying oxygen-scavenging multilayer structures for extended shelf-life dairy and meat products.
- TR CU 005/2011 harmonization:EAEU technical regulation alignment is reducing cross-border certification friction for packaging substrates moving between Russia, Belarus, and Kazakhstan.
- Central Federal District concentration:Moscow-region logistics density and retail chain procurement centralization are pulling volume toward high-throughput extrusion and printing facilities.
Market Restraints
- Polyethylene resin import dependency:Sanctions-constrained supply channels for high-density polyethylene and metallocene-grade linear low-density polyethylene are elevating raw material cost volatility for non-integrated converters.
- Barrier technology licensing concentration:Core oxygen barrier and aroma-seal coating intellectual property remains concentrated with European and Japanese technology licensors, extracting royalty burdens from domestic film producers.
- Substitution by molded fiber:Quick-service restaurant chains and fresh produce distributors are trialing molded cellulose pulp trays and clamshells for cold-chain applications previously served by thermoformed PET.
Strategic Opportunities
- North Caucasus Federal District penetration:Underdeveloped converter infrastructure in Stavropol and Rostov regions creates first-mover positioning for flexible packaging suppliers with regional distribution partnerships.
- Pharmaceutical serialization integration:Russia's Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing track-and-trace mandates for pharmaceutical packaging are opening specification windows for tamper-evident barrier films with embedded authentication features.
- Post-consumer film collection infrastructure:Extended producer responsibility framework development is creating feedstock access opportunities for mechanical recycling lines producing food-contact-compliant recycled polyethylene.
Industry Challenges
- Migration testing laboratory capacity:Bottlenecks at Rospotrebnadzor-accredited testing facilities are extending material approval timelines from 8 weeks to 20 weeks, freezing new product launches.
- Extrusion line reconfiguration costs:Seven-layer barrier film coextrusion equipment requires capital outlays that mid-market converters cannot access under current Russian banking conditions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Plastic Packaging Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Blow Molding, Injection Molding, Thermoforming, Flexible Packaging End User: Food & Beverage, Pharmaceuticals, Consumer Goods, Electronics Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Application: Food Packaging, Medical Packaging, Industrial Packaging, Retail Packaging |
| Companies Covered | Mondi Group, Gotek, AptarGroup, ALPLA, SIBUR Holding, Amcor, RPC Group, Greiner Packaging, Tetra Laval, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Plastic Packaging Market Evolving Landscape
Digital printing and inline quality verification systems are compressing minimum order quantities and lead times across Russia's packaging supply base, enabling regional brand owners to compete with national players on packaging refresh velocity.
Electron beam curing technology for solvent-free adhesive lamination is automating bond formation in high-barrier flexible packaging production. Regional dairy cooperatives in Tver and Yaroslavl oblasts are adopting these systems to eliminate solvent retention risks while accelerating lamination line speeds. This automation is compressing the cost gap between domestic production and imported pre-laminated film structures.
Russia's Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing is tightening enforcement of TR CU 005/2011 migration limit protocols for aromatic amines and heavy metals in food-contact plastics. Converters are responding by shifting specification authority toward certified raw material suppliers with documented supply chain traceability. Pharmaceutical and infant nutrition packaging segments are experiencing the most intensive audit frequency and are building dedicated cleanroom extrusion capacity.
Consolidated retail procurement through X5 Retail Group and Magnit centralized buying desks is compressing supplier rosters and extending payment terms for packaging vendors. Regional converters in the Volga Federal District are responding by forming cooperative logistics arrangements to achieve truckload-scale delivery volumes. This concentration is most visible in the edible oils and confectionery categories where private label penetration exceeds sixty percent of shelf space.
Russia Plastic Packaging Market Segmentation
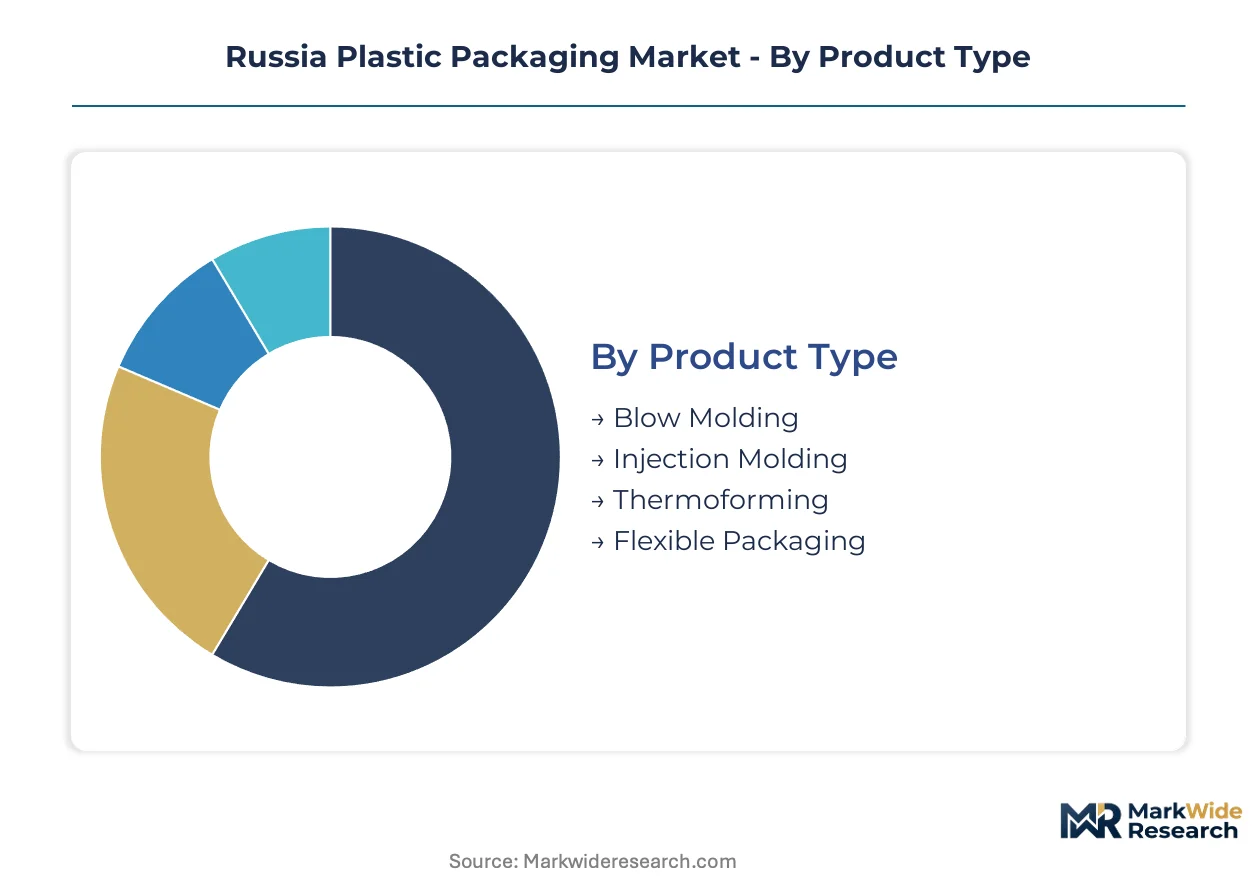
Segmentation in Russia's plastic packaging market reveals how TR CU 005/2011 compliance requirements, sanctions-driven supply restructuring, and Central Federal District logistics density reshape converter specialization across product categories.
Product Type:
Blow molding and injection molding dominate capital deployment, while flexible packaging commands volume throughput across Russia's sparse distribution networks.
- Blow Molding:High-density polyethylene and PET resin systems produce dimensional-consistent bottles for carbonated beverages and personal care products. Demand clusters around Moscow-region dairy and soft drink bottlers seeking lightweight rigid formats for rail distribution to Siberian retail networks.
- Injection Molding:Precision-tolerance polypropylene and polystyrene containers serve pharmaceutical blister packs and medical device trays requiring cleanroom compatibility. TR CU 005/2011 migration testing bottlenecks at Rospotrebnadzor-accredited laboratories freeze new product launches for 20 weeks, compressing margin pools to established converters with pre-qualified material pipelines.
- Thermoforming:PET and polystyrene sheet-based clamshells and trays address fresh produce and ready-meal segments.
- Flexible Packaging:Multilayer coextruded films with oxygen-scavenging barriers extend shelf life for meat and dairy products across Russia's extended cold chains.
Mature deployment sits with blow molding. Newer deployment is concentrated in seven-layer barrier flexible films requiring extrusion line reconfiguration.
End User:
Food and beverage procurement centralization through X5 Retail Group and Magnit buying desks restructures supplier rosters and payment terms across converter tiers.
- Food & Beverage:Oxygen-barrier flexible films and rigid containers for dairy, edible oils, and confectionery. Private label penetration exceeding sixty percent of shelf space in these categories drives specification toward high-throughput, low-SKU production.
- Pharmaceuticals:Tamper-evident barrier films with embedded authentication features respond to Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing track-and-trace mandates. Serialization integration opens specification windows for converters with cleanroom extrusion capacity.
- Consumer Goods:Personal care and household product containers prioritize aesthetic differentiation through in-mold labeling and digital printing compatibility.
- Electronics:Antistatic and moisture-barrier formats for component shipping and retail display protection.
Margin concentration tracks pharmaceutical compliance burden. Volume expansion is fastest in food and beverage private label supply.
Material:
Resin supply security divides integrated petrochemical players from import-dependent converters facing sanctions-constrained polyethylene channels.
- Polyethylene:High-density and linear low-density grades dominate flexible films and blow-molded bottles. SIBUR Holding's upstream petrochemical base secures domestic supply for mid-market converters while non-integrated competitors face raw material cost volatility.
- Polypropylene:Injection-molded pharmaceutical trays and thermoformed food containers leverage clarified random copolymer grades for optical properties and heat resistance.
- Polyvinyl Chloride:Blister packs and pharmaceutical primary packaging with established migration testing protocols.
- Polystyrene:Thermoformed trays and protective packaging for electronics and consumer goods distribution.
Polyethylene maintains supply chain dominance. Polypropylene is gaining specification share in pharmaceutical and premium food segments.
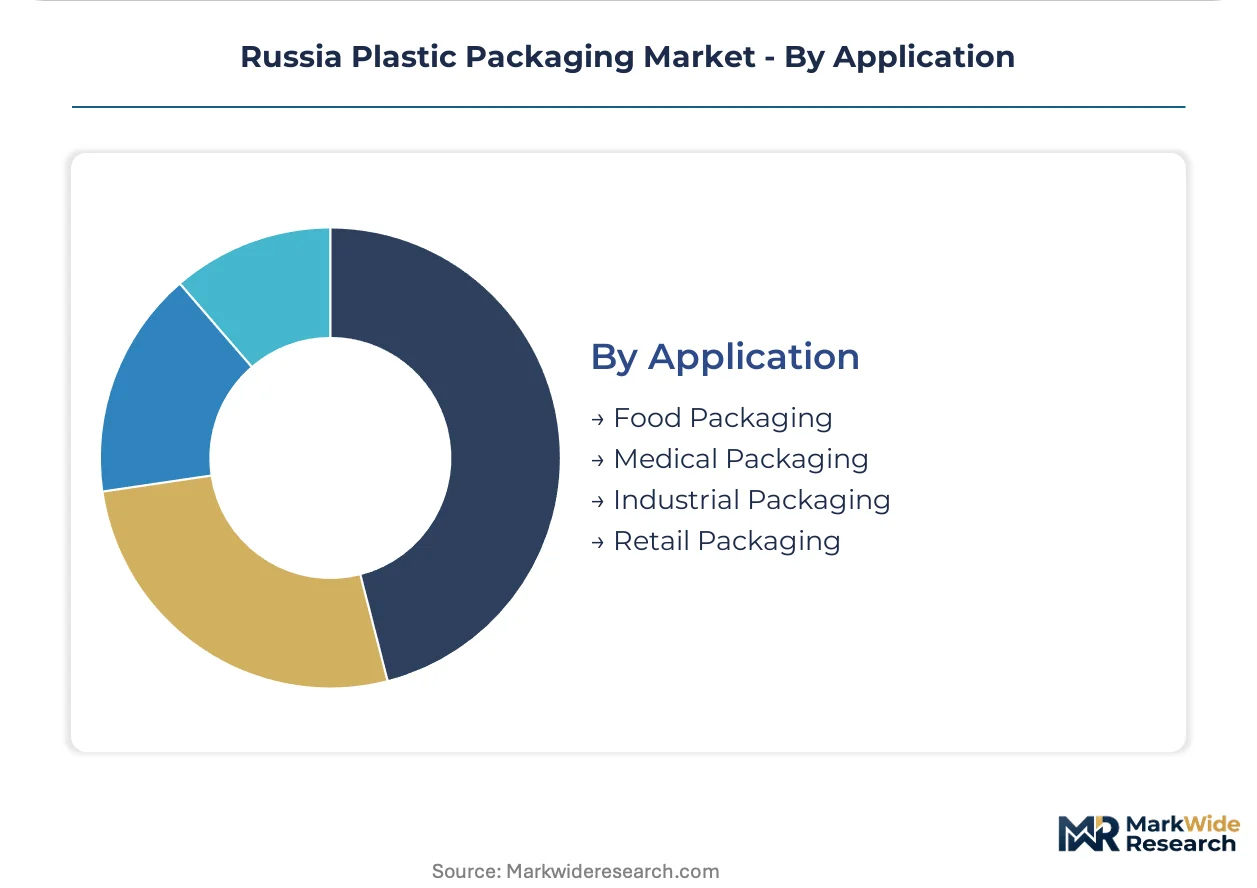
Application:
Application segmentation tracks regulatory intensity divergence between food-contact migration limits and industrial packaging performance specifications.
- Food Packaging:Multilayer barrier structures with EVOH and nylon cores address extended shelf-life requirements for dairy and meat distribution across Russia's rail-linked corridors. Electron beam curing technology eliminates solvent retention risks while accelerating lamination speeds.
- Medical Packaging:Sterile barrier systems and pharmaceutical serialization-ready formats face intensive Rospotrebnadzor audit frequency. Cleanroom extrusion capacity builds dedicated production lines for infant nutrition and injectable drug segments.
- Industrial Packaging:Stretch film and shrink wrap for palletized goods movement through Central Federal District logistics hubs.
- Retail Packaging:Point-of-sale display readiness and digital printing compatibility for regional brand refresh velocity.
Regulatory scrutiny concentrates on medical packaging. Cost pressure is most acute in industrial stretch film commoditization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Moscow anchors Russia's plastic packaging demand through its concentration of retail procurement headquarters, dairy processing clusters, and Central Federal District logistics infrastructure serving rail distribution corridors eastward.
Central Federal District
X5 Retail Group and Magnit centralized buying desks in Moscow compress supplier rosters and extend payment terms for packaging vendors. TR CU 005/2011 migration testing requirements are enforced most intensively here, with Rospotrebnadzor-accredited laboratories experiencing 20-week approval bottlenecks. The Tver and Yaroslavl oblasts host expanding electron beam curing installations for solvent-free flexible film lamination.
Volga Federal District
Regional converters in Samara and Kazan are forming cooperative logistics arrangements to achieve truckload-scale delivery volumes for edible oils and confectionery private label supply. The district's lower labor and facility costs attract mid-market extrusion operations seeking relief from Moscow-region real estate premiums. Local banks remain reluctant to finance seven-layer barrier film equipment upgrades.
North Caucasus Federal District
Underdeveloped converter infrastructure in Stavropol and Rostov regions creates first-mover positioning for flexible packaging suppliers with regional distribution partnerships. Agricultural processing cooperatives drive demand for extended shelf-life meat and dairy packaging. The district's distance from Moscow testing facilities extends material qualification timelines.
Siberian Federal District
Long-distance rail distribution from Western Siberian petrochemical feedstock sources shapes specification toward lightweight flexible formats that minimize freight cost per unit. Novosibirsk serves as a secondary procurement hub for retail chains operating east of the Urals. Cold-chain reliability requirements intensify barrier performance specifications for frozen food distribution.
Northwestern Federal District
St. Petersburg's port infrastructure supports imported resin and pre-laminated film structures for converters serving Baltic-facing export markets. Pharmaceutical serialization mandates from the Federal Service for Surveillance in Consumer Rights Protection and Human Wellbeing concentrate specification authority here for tamper-evident barrier films. The district's proximity to European technology licensors influences coating and adhesive selection.
Russia Plastic Packaging Market Competitive Landscape
Capital-heavy integrated petrochemical producers compete with asset-light specialized converters for specification authority across Russia's packaging supply base. SIBUR Holding's captive resin supply secures mid-market positioning, while Mondi Group and ALPLA anchor premium tiers through differentiated format capabilities. Three strategic archetypes dominate: upstream-integrated resin suppliers, rigid container specialists, and flexible film converters. Competitive moves concentrate on regional distribution partnerships and cleanroom extrusion capacity builds for pharmaceutical compliance.
Within the integrated petrochemical tier, SIBUR Holding exemplifies upstream-backed supply security, while ALPLA occupies rigid container specialization. Mondi Group represents hybrid paper-plastic format capabilities. Among international participants, Amcor and Greiner Packaging sit within premium barrier and pharmaceutical packaging positioning. The competitive dynamic pits resin cost advantage against format innovation and regulatory compliance infrastructure.
| Leading Market Players |
|---|
| Mondi Group |
| Gotek |
| AptarGroup |
| ALPLA |
| SIBUR Holding |
| Amcor |
| RPC Group |
| Greiner Packaging |
| Tetra Laval |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap converters across Russia's Central Federal District are consolidating under private-equity-backed platforms to secure working capital for TR CU 005/2011 compliance investments, tightening pricing discipline among survivors while squeezing margin-vulnerable competitors out of barrier film supply.
Pricing Analysis
Throughput-linked contract structures dominate procurement between Moscow-region dairy processors and flexible film suppliers, with pricing stratifying across premium oxygen-scavenging multilayer grades, standard three-layer barrier formats, and economy polyethylene wrap tiers. Price differentiation tracks certification grade against Rospotrebnadzor migration protocols and volume scale through X5 Retail Group centralized buying desks. Cost compression in commodity polyethylene wrap is intensifying because sanctions-constrained resin import channels elevate raw material volatility for non-integrated converters. Small regional cooperatives in the North Caucasus Federal District exhibit highest price sensitivity, while pharmaceutical serialization-ready barrier film buyers accept premium positioning for cleanroom-extruded grades.
Supply Chain Analysis
Freight cost per unit shapes specification authority across Russia's sparse rail networks, with lightweight flexible formats displacing rigid containers for Siberian distribution corridors extending from Western Siberian petrochemical feedstock sources. Domestic supply concentrates in Russia, Belarus, and Kazakhstan under EAEU technical regulation harmonization. Raw material dependencies rest on high-density polyethylene, metallocene-grade linear low-density polyethylene, and EVOH barrier resin systems. Single-source vulnerability runs through European and Japanese oxygen barrier coating technology licensors extracting royalty burdens. Distribution runs through Central Federal District logistics hubs serving rail-linked procurement clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
TR CU 005/2011 migration testing bottlenecks and sanctions-driven resin cost volatility are forcing undercapitalized converters into distressed sales, consolidating specification authority among integrated petrochemical-backed survivors with pre-qualified material pipelines.
For Market Incumbents: Deploy cleanroom extrusion capacity builds to capture pharmaceutical serialization mandate windows before Rospotrebnadzor audit frequency intensifies further. Anchor position through backward integration into post-consumer film collection infrastructure under developing extended producer responsibility frameworks, neutralizing feedstock cost volatility that threatens non-integrated competitors. Electron beam curing technology adoption separates premium barrier film suppliers from solvent-lamination-dependent mid-market players facing compliance risk. For New Entrants and Emerging Players: Digital printing platforms with inline quality verification offer lowest-capital entry points for regional brand owners seeking packaging refresh velocity against national players. North Caucasus Federal District agricultural cooperatives present most penetrable white-space, with Stavropol and Rostov regions lacking established converter infrastructure for extended shelf-life meat and dairy packaging. Partner with regional distribution networks to overcome Moscow-centric logistics concentration. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-market flexible film converters with TR CU 005/2011 pre-qualified material pipelines in the Volga Federal District, where local bank financing gaps freeze equipment upgrade cycles. Long-term viability hinges on regulatory compliance infrastructure rather than commodity resin access alone. Watch Rospotrebnadzor laboratory capacity expansion as inflection indicator for new product launch velocity recovery.| Strategic Initiative | Industry Significance |
|---|---|
| Cleanroom Extrusion Capacity Build | Captures pharmaceutical serialization mandate windows from Rospotrebnadzor track-and-trace requirements. |
| Electron Beam Curing Technology Adoption | Eliminates solvent retention risks while accelerating lamination speeds for Tver and Yaroslavl dairy cooperatives. |
| Post-Consumer Film Collection Infrastructure | Secures food-contact-compliant recycled polyethylene feedstock under extended producer responsibility frameworks. |
| Regional Distribution Partnership Formation | Achieves truckload-scale delivery volumes for Volga Federal District private label edible oils supply. |
| Seven-Layer Barrier Film Coextrusion Upgrade | Enables oxygen-scavenging multilayer structures for extended shelf-life meat distribution across Siberian rail corridors. |
Research Methodology
Trade statistics from Russian customs authorities, EAEU technical regulation harmonization documents, and Rospotrebnadzor migration testing protocols formed the secondary backbone for supply chain and compliance analysis. Primary interviews with flexible film plant managers, dairy procurement leads at X5 Retail Group and Magnit, pharmaceutical regulatory affairs directors, and Central Federal District logistics operators combined with bottom-up and top-down triangulation across converter capacity databases and retail shelf-space audit data.
Historical trendline analysis of resin cost volatility, barrier technology licensing patterns, and migration testing approval timelines informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, end-use vertical, material grade tier, and regional production hub cluster. CAGRs were derived from extrusion line capacity deployment trajectories and private-label penetration curves in edible oils and confectionery categories. Forecast inputs incorporated electron beam curing adoption rates and extended producer responsibility framework development pace.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sanctions regime intensification or Rospotrebnadzor laboratory capacity constraints extending material approval timelines beyond current bottlenecks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
PET Jars Market
Plastic Packaging
Plastic Canister Market
Plastic Packaging
Mexico Plastic Bottles Market
Plastic Packaging
United Arab Emirates Plastic Bottles Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
PCR Bottles Market
Plastic Packaging
PET Preforms Market
Plastic Packaging
Blow Moulded Plastic Packaging Market
Plastic Packaging
Malaysia and Thailand Thermoformed Plastic Market
Plastic Packaging
CPET Trays Market
Plastic Packaging
PLA Cup Market
Plastic Packaging
United States Plastic Bottles Market
Plastic Packaging
Conductive Plastic Boxes Market
Plastic Packaging
Plastic Buckets Market
Plastic Packaging
Plastic Bottles and Containers Market
Plastic Packaging
United Arab Emirates Plastic Packaging Market