
 South Africa Flexible Plastic Packaging Market | 2026-2036
South Africa Flexible Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
South Africa Flexible Plastic Packaging Market Insights
Gauteng province is reconfiguring South Africa's flexible packaging production geography through concentrated industrial zone development. Amcor PLC leverages its integrated film-to-pouch manufacturing footprint to sustain supply chain efficiency across Southern African markets. Mondi PLC anchors its competitive stance through kraft paper and plastic hybrid solutions that navigate sustainability transitions. Mpact Ltd specializes in recycled-content flexible formats that differentiate its offering for domestic retail channels.
South Africa flexible plastic packaging comprises polymer-based films, pouches, wrappers, and bags engineered from polyethylene, polypropylene, PVC, or PET resins, typically manufactured through blown film extrusion, cast extrusion, or lamination processes to achieve barrier properties against moisture, oxygen, and light for perishable goods protection. Stand-up pouches command premium positioning in food and beverage applications due to their shelf presence and material efficiency, while polyethylene films dominate volume flows across industrial and retail end users. E-commerce channels represent the fastest-growing demand vector as last-mile delivery requirements reshape specifications for durable, lightweight protective formats.
South Africa's Department of Forestry, Fisheries and the Environment enforces extended producer responsibility frameworks that mandate post-consumer collection targets, while the National Regulator for Compulsory Specifications governs food-contact material safety standards under SANS codes. The South African Bureau of Standards certifies compliance for recycled content claims, creating tiered market access conditions that favor producers with verified circular material streams. Stakeholders must monitor regulatory tightening on single-use plastics and alignment with EU export standards to preserve market position.
Market Dynamics
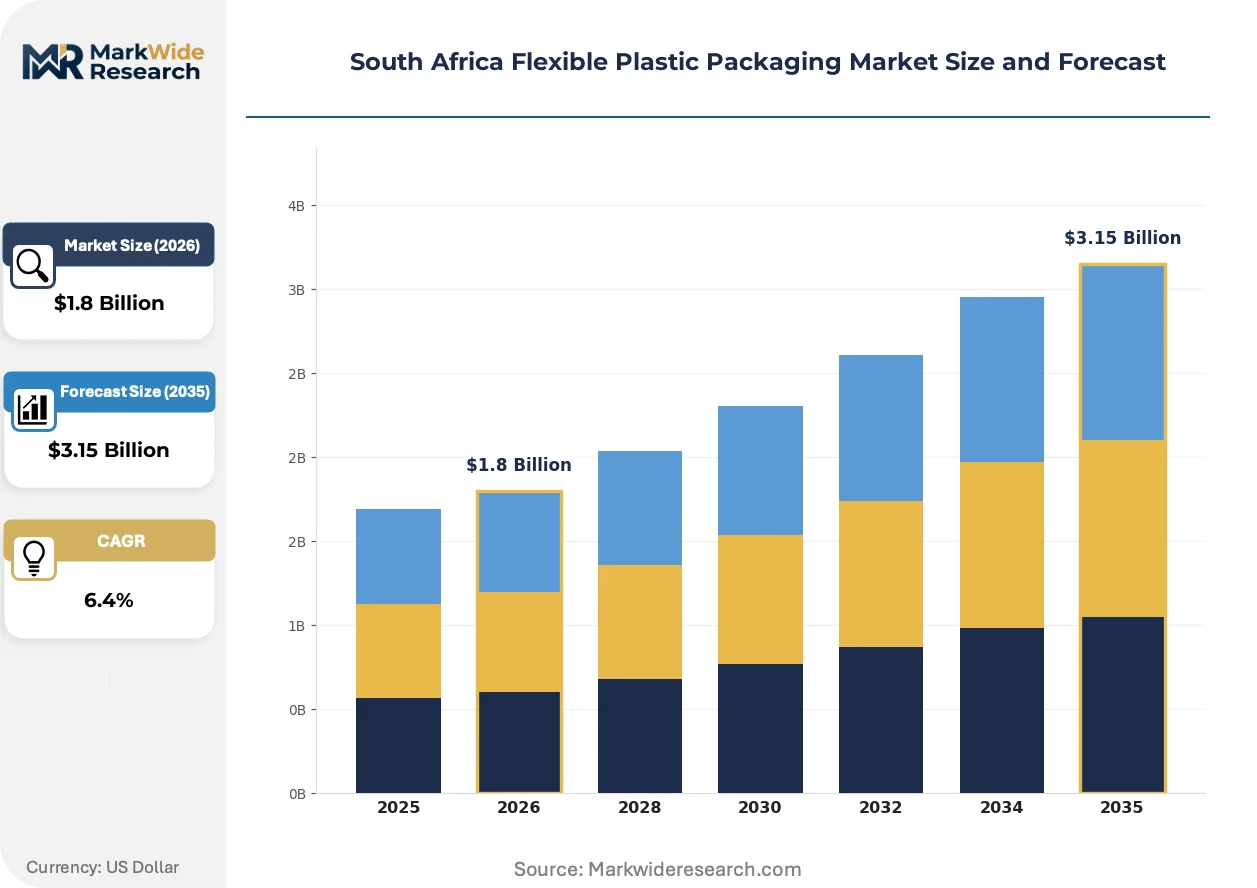
South Africa's extended producer responsibility regulations are compressing operational timelines for flexible packaging converters while simultaneously opening premium positioning for circular-material specialists. The regulatory pivot is forcing capital reallocation across Gauteng's industrial corridor faster than technical adaptation cycles can match.
Growth Catalysts
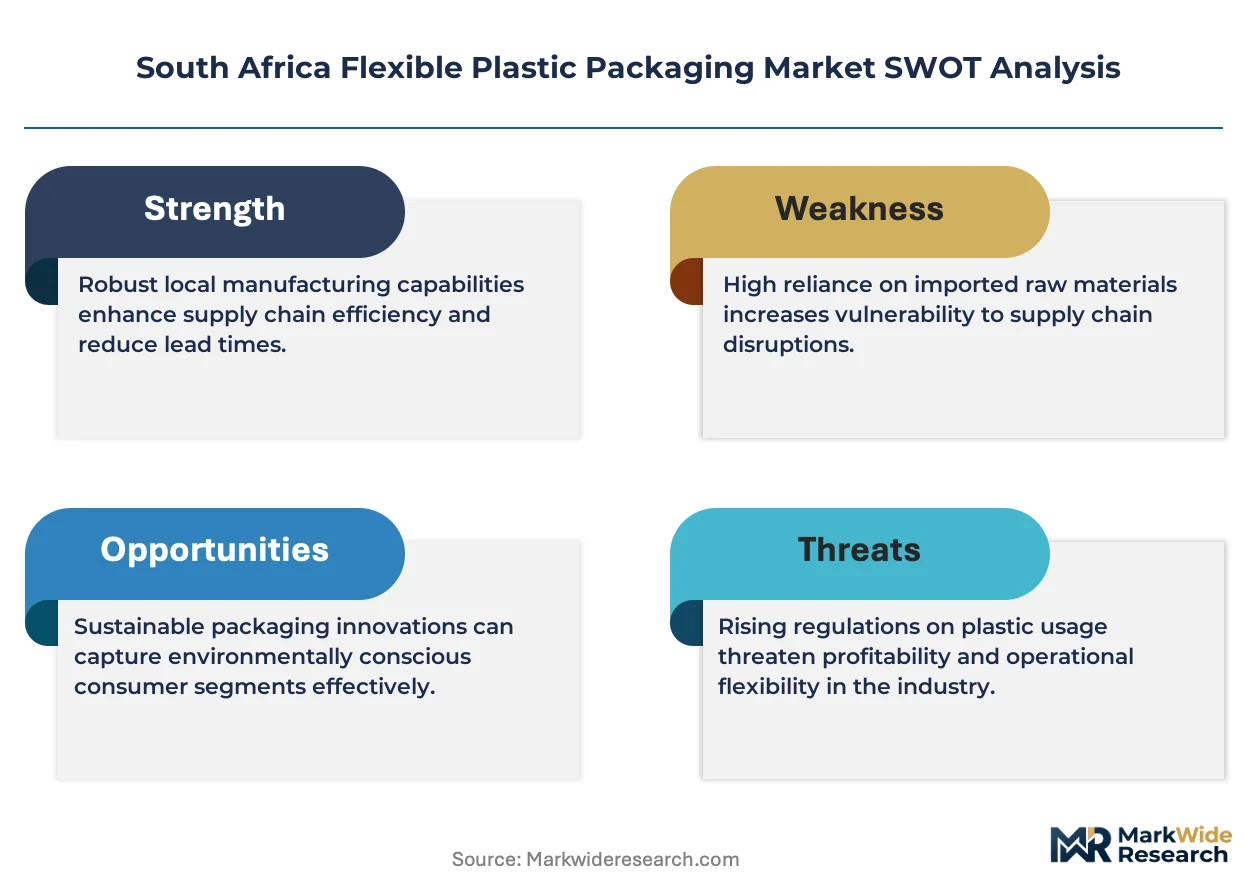
- EPR Compliance Deadlines:South Africa's Department of Forestry, Fisheries and the Environment mandates escalating post-consumer collection targets that pull investment into domestic recycling infrastructure.
- E-commerce Last-Mile Surge:Online retail fulfillment requirements for durable lightweight protective formats are accelerating specification changes in polyethylene film orders.
- Food Contact Safety Upgrades:SANS code revisions under National Regulator for Compulsory Specifications jurisdiction are driving replacement cycles in perishable goods packaging.
Market Restraints
- Petrochemical Feedstock Volatility:Polyethylene and polypropylene resin prices track international oil benchmarks, compressing converter margins during supply shocks.
- Import Dependency for Barrier Films:Specialized coextruded and metallized substrates concentrate supply among a narrow base of European and Asian exporters.
- Mechanical Recycling Quality Ceiling:Post-consumer film streams face contamination limits that cap recycled content percentages in food-contact applications.
Strategic Opportunities
- KwaZulu-Natal Industrial Expansion:Durban's port logistics infrastructure supports export-oriented flexible packaging manufacturing for Southern African Development Community markets.
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization technologies promise food-grade resin output from mixed plastic waste streams currently landfilled.
- Digital Print Integration:Short-run variable data printing on flexible substrates enables mass customization for regional brand campaigns without plate costs.
Industry Challenges
- Polymer Chemist Talent Scarcity:Formulation expertise for bio-based and recycled-content films concentrates among retiring specialists without adequate pipeline replacement.
- Multi-Site Certification Complexity:SABS verification for recycled content claims requires parallel audit tracks across Gauteng, Western Cape, and KwaZulu-Natal production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South Africa Flexible Plastic Packaging Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stand-up Pouches, Bags, Wrappers, Films Material: Polyethylene, Polypropylene, PVC, PET Application: Food Packaging, Beverage Packaging, Pharmaceuticals, Personal Care End User: FMCG, Retail, Industrial, E-commerce |
| Companies Covered | Amcor PLC, Huhtamaki Oyj, Constantia Flexibles, Berry Global Inc., Flexible Packagers Convertors (Pty) Ltd, Mondi PLC, Nampak Ltd, Mpact Ltd, RPC Astrapak Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South Africa Flexible Plastic Packaging Market Trends and Innovations
Active and intelligent packaging functionalities are migrating from European premium applications into South African retail channels as local converters invest in oxygen-scavenging and moisture-control film capabilities. The convergence is compressing technology adoption cycles that previously lagged Northern Hemisphere markets by five to seven years.
Mono-material polyethylene structures are collapsing the historical multi-layer barrier film paradigm by delivering comparable shelf-life performance through advanced resin grades and orientation techniques. Major retail chains in Johannesburg and Cape Town are adopting these formats to meet SANS recyclability guidelines without sacrificing product protection. The shift is collapsing demand for aluminum-foil laminates and PET/PE composites in dry goods segments.
South Africa's extended producer responsibility framework is accelerating compliance technology deployment across the value chain. The Department of Forestry, Fisheries and the Environment's mandatory reporting portals require real-time tracking of post-consumer collection volumes. Large FMCG brand owners are responding by embedding QR-coded return incentives directly into pouch designs, creating closed-loop data flows that satisfy regulator audit requirements.
Buyer consolidation among national supermarket chains is compressing supplier negotiation cycles and unbundling technical service from base material supply contracts. Retail procurement teams in Pretoria and Durban now separate film specification development from volume purchasing decisions, forcing converters to compete on technical advisory capabilities rather than price alone. This bifurcation is most visible in private-label snack and frozen food categories where packaging innovation serves as brand differentiation.
South Africa Flexible Plastic Packaging Market Segmentation
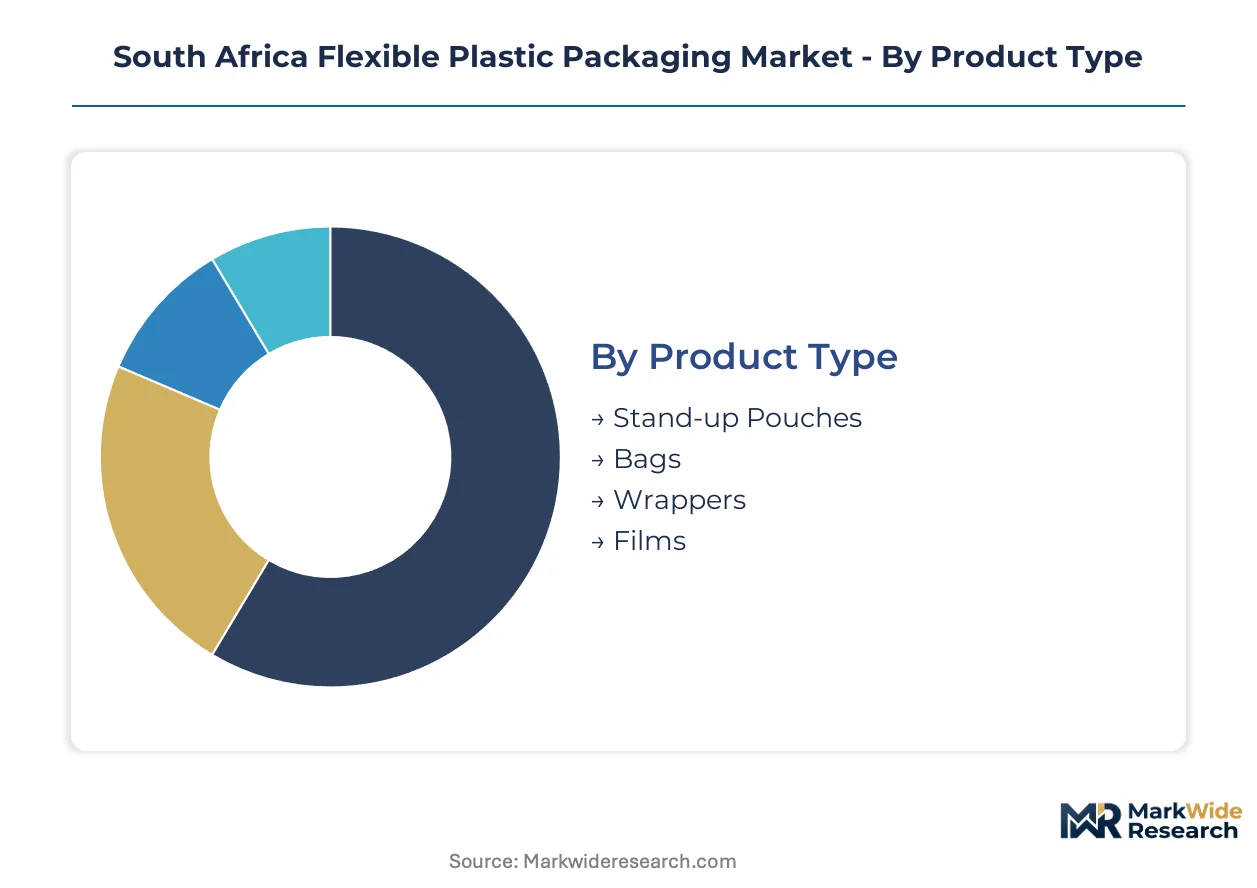
Flexible plastic packaging in South Africa serves divergent performance requirements across food preservation, pharmaceutical safety, and e-commerce logistics. Segment boundaries are blurring as converters develop hybrid formats that satisfy multiple regulatory and functional specifications simultaneously. Understanding these divisions reveals where capital investment and technical differentiation concentrate.
Product Type:
Converters engineer distinct structural formats that balance material efficiency against barrier performance and shelf presence.
- Stand-up Pouches:Multi-layer laminated structures with gusseted bases provide vertical shelf stability and high graphic impact. FMCG brand owners in Johannesburg and Cape Town specify these for premium snack and frozen food lines where differentiation drives repeat purchase.
- Bags:Side-sealed or bottom-sealed configurations dominate bulk industrial and retail grocery applications through cost-efficient polyethylene construction. Gauteng province's packaging corridor processes the highest bag volumes for maize meal, sugar, and agricultural inputs.
- Wrappers:Single-web films with heat-seal coatings protect individual confectionery, bakery, and fresh produce items. SANS food-contact compliance requirements constrain recycled-content integration in these direct-touch formats.
- Films:Roll-stock substrates supply downstream converting operations or direct-use applications in stretch wrapping and pallet stabilization. E-commerce fulfillment centers in Durban specify puncture-resistant grades for last-mile damage prevention.
The dominant share belongs to Bags, while Stand-up Pouches is closing the gap fastest.
Material:
Resin selection traces directly to end-use barrier requirements, mechanical performance needs, and circularity compliance deadlines.
- Polyethylene:LDPE and LLDPE grades constitute the volume foundation across food bags, stretch films, and e-commerce mailers. Blown film extruders in KwaZulu-Natal favor polyethylene for its compatibility with existing mechanical recycling infrastructure and SABS certification pathways.
- Polypropylene:Cast and oriented films deliver clarity, stiffness, and temperature resistance for retort pouches and microwaveable formats. The material's higher melting point supports hot-fill applications in beverage and ready-meal segments where shelf stability requirements intensify.
- PVC:Shrink sleeves and blister formats exploit the resin's clarity and sealability despite environmental scrutiny. Pharmaceutical packaging in Gauteng maintains PVC demand for tablet and medical device visibility requirements.
- PET:Metallized and clear films provide oxygen barrier properties for extended shelf-life applications. Import dependency constrains domestic PET film availability, with converters sourcing specialized grades from European suppliers.
Polyethylene commands installed capacity leadership, though Polypropylene is gaining share through retort and hot-fill format expansion.
Application:
Regulatory intensity and performance specifications vary sharply across end-use categories, dictating converter specialization patterns.
- Food Packaging:Oxygen and moisture barrier films protect perishable goods through modified atmosphere and vacuum formats. National supermarket chains specify mono-material polyethylene structures to satisfy Department of Forestry, Fisheries and the Environment recyclability mandates without sacrificing shelf life.
- Beverage Packaging:Spouted pouches and bag-in-box formats challenge rigid bottle conventions in wine, juice, and dairy segments. Cape Town's wine industry drives premium pouch adoption for export markets where shipping weight reduction translates to freight cost savings.
- Pharmaceuticals:Child-resistant and senior-friendly flexible formats comply with stringent barrier and stability requirements. The National Regulator for Compulsory Specifications governs material safety certifications that limit supplier qualification pools.
- Personal Care:Stand-up pouches and sachets deliver unit-dose convenience for shampoo, lotion, and cosmetic samples. Private-label penetration among pharmacy chains accelerates specification standardization in this segment.
Food Packaging anchors converter revenue, while E-commerce adjacent demand is expanding most quickly through protective format requirements.
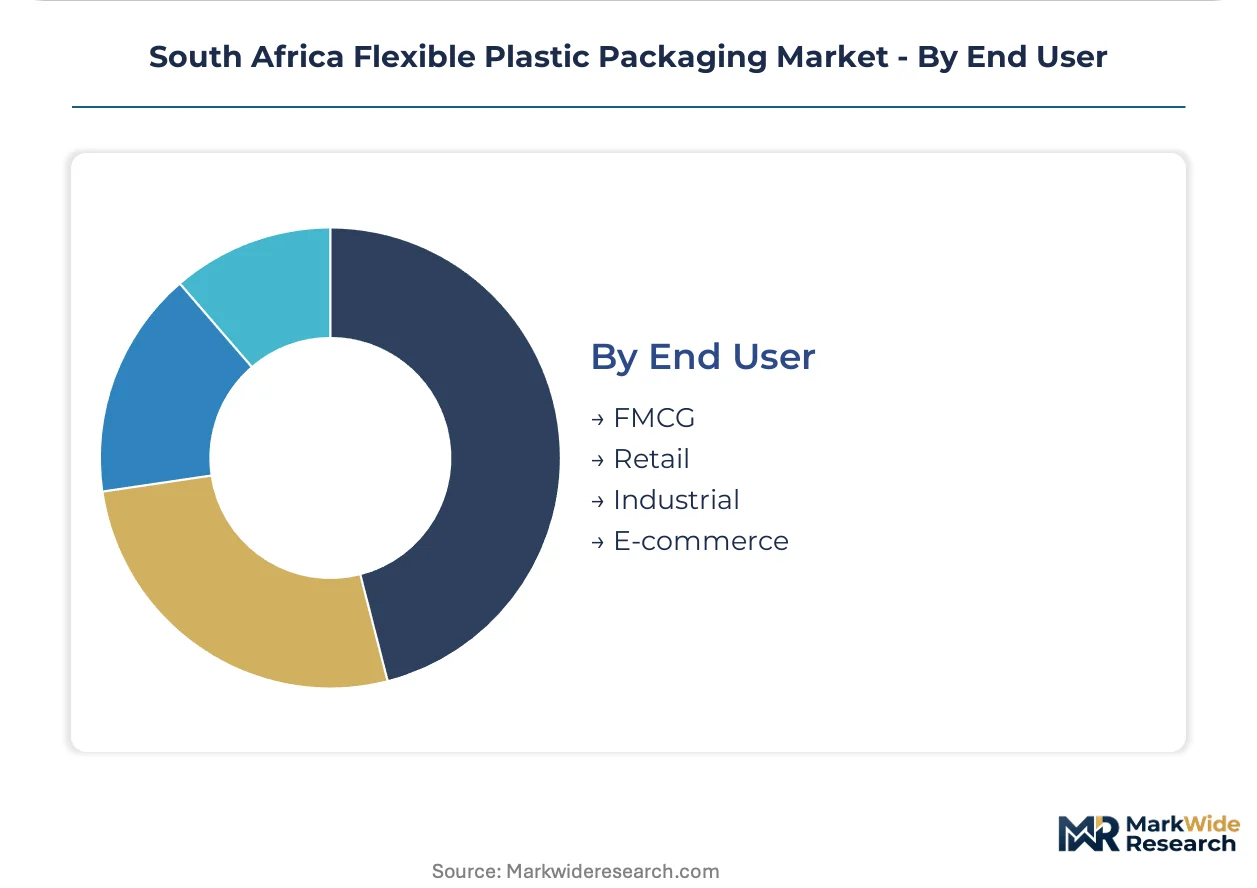
End User:
Procurement sophistication and technical service expectations diverge substantially across buyer categories.
- FMCG:Multinational and domestic brand owners mandate extended producer responsibility compliance, recycled-content verification, and supply chain transparency. Technical service teams embed directly with Unilever, Tiger Brands, and Pioneer Foods packaging development functions.
- Retail:Supermarket private-label programs separate film specification from volume purchasing, forcing converters to compete on innovation advisory rather than price alone. Shoprite Checkers and Pick n Pay procurement consolidation compresses supplier negotiation cycles.
- Industrial:Agricultural, chemical, and construction sectors prioritize puncture resistance and UV stability over graphic sophistication. Bulk fertilizer and cement bagging in Mpumalanga and Limpopo drives heavy-duty polyethylene demand.
- E-commerce:Takealot and Superbalist fulfillment specifications prioritize lightweight durability and return logistics compatibility. Last-mile damage rates dictate investment in bubble-lined mailers and tamper-evident pouches.
FMCG retains the largest procurement volume, though E-commerce is climbing the fastest on fulfillment infrastructure expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Department of Forestry, Fisheries and the Environment anchors South Africa's regulatory framework for flexible plastic packaging. Provincial industrial corridors concentrate converting capacity and recycling infrastructure development. Sub-regional specialization patterns reflect port access, petrochemical feedstock proximity, and FMCG customer density.
Gauteng Province
Johannesburg and Pretoria host the densest cluster of flexible packaging converters serving FMCG brand owners. The province's industrial corridor processes maize meal, sugar, and snack packaging volumes that exceed other regions combined. Department of Forestry, Fisheries and the Environment EPR compliance deadlines are accelerating capital reallocation toward mechanical recycling upgrades in Ekurhuleni manufacturing zones.
KwaZulu-Natal
Durban's port infrastructure positions the province as the export gateway for Southern African Development Community markets. Local blown film extruders favor polyethylene grades compatible with SABS certification pathways. Chemical recycling pilot projects in Richards Bay industrial precincts target mixed plastic waste streams currently directed to landfill.
Western Cape
Cape Town's wine industry drives premium pouch adoption for export markets where shipping weight reduction cuts freight costs. The province's converter base specializes in modified atmosphere formats for perishable agricultural exports. National Regulator for Compulsory Specifications food-contact audits concentrate technical compliance resources in Paarl-Stellenbosch packaging corridors.
Eastern Cape
Port Elizabeth automotive supplier networks generate demand for protective film formats in component logistics. The province's industrial development zones attract polyethylene bag manufacturers serving Eastern Cape retail expansion. Coega Special Economic Zone infrastructure supports import substitution for barrier films previously sourced from European suppliers.
South Africa Flexible Plastic Packaging Market Competitive Landscape
Integrated multinationals and domestic specialists split the market between export-scale efficiency and local compliance agility. Three strategic archetypes dominate: global film-to-pouch integrators with Southern African manufacturing footprints, regional paper-plastic hybrid specialists leveraging kraft expertise, and recycled-content focused domestic converters targeting SABS-verified circular material streams. Competitive moves center on EPR-aligned recycling infrastructure partnerships and mono-material format R&D to preempt regulatory bans on multi-layer laminates.
Among the integrated multinational tier, Amcor PLC and Mondi PLC exemplify divergent strategic positioning. Amcor PLC represents the film-to-pouch vertical integration archetype with supply chain efficiency priorities across Southern African markets. Mondi PLC anchors the paper-plastic hybrid specialist position, leveraging kraft expertise to navigate sustainability transitions. Within the domestic specialist tier, Mpact Ltd occupies the recycled-content verification niche, differentiating through SABS-certified circular material streams for retail channel compliance.
| Leading Market Players |
|---|
| Amcor PLC |
| Huhtamaki Oyj |
| Constantia Flexibles |
| Berry Global Inc. |
| Flexible Packagers Convertors (Pty) Ltd |
| Mondi PLC |
| Nampak Ltd |
| Mpact Ltd |
| RPC Astrapak Ltd |
| Others |
Pricing and Supply Chain Analysis
Saudi Arabian polyethylene resin suppliers and European metallized film exporters anchor South Africa's upstream material costs, concentrating margin pools among converters with captive polymer supply or SABS-certified circular material streams. Gauteng's industrial corridor absorbs the highest feedstock volatility, while coastal provinces leverage port access to arbitrage import pricing spreads.
Pricing Analysis
Price spreads between Johannesburg inland delivery and Durban port-side sourcing exceed transport-cost differentials alone, reflecting inventory carrying premiums and import duty timing. Three-tier pricing structure across premium certified-recycled, standard virgin-grade, and economy import-substitute tiers dominates converter quotations. Pricing pressure stems from petrochemical feedstock volatility tracking international oil benchmarks, compressing margins during supply shocks. FMCG brand owners exhibit lowest price sensitivity due to EPR compliance mandates, while industrial bulk buyers in Mpumalanga drive hardest volume negotiations.
Supply Chain Analysis
Extended payment terms from 60 to 90 days are becoming standard among Gauteng converters serving national retail chains, straining working capital for smaller extruders. Raw material supply draws from Saudi Arabia for polyethylene resin, China for specialized additives and masterbatch, and Germany for metallized barrier substrates. Single-source vulnerability concentrates in metallized PET films where European suppliers dominate food-grade specifications. Distribution runs through converter-direct relationships with FMCG technical teams, supplemented by regional distributors serving fragmented industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South Africa's flexible plastic packaging market rewards service-attach capabilities as technical advisory and EPR compliance management expand faster than base film supply margins. Recycled-content verification services and closed-loop collection program design represent the fastest-growing recurring revenue layers.
For Market Incumbents: Harden circular material certification advantages through SABS audit automation across Gauteng, Western Cape, and KwaZulu-Natal production sites. Deepen backward integration into mechanical recycling infrastructure before chemical recycling scales disrupt quality hierarchies. Consolidate formulation expertise through targeted retention programs as polymer chemist talent scarcity intensifies. For New Entrants and Emerging Players: Pursue digital print integration for short-run FMCG brand campaigns where legacy converters maintain plate-cost disadvantages. Target Eastern Cape industrial development zones for polyethylene bag manufacturing serving underpenetrated retail expansion. Lead with mass-customization capabilities and rapid specification turnaround rather than commodity volume pricing. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed mid-tier converters holding SABS certifications but lacking EPR-aligned recycling infrastructure partnerships. Five-to-ten-year viability hinges on regulatory tightening pace and chemical recycling technology maturation. Monitor Department of Forestry, Fisheries and the Environment enforcement intensity as the critical inflection signal for asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Mono-Material Format R&D Investment | Preempts regulatory bans on multi-layer laminates under SANS recyclability guidelines. |
| Chemical Recycling Pilot Scale-Up | Richards Bay industrial precincts target food-grade resin from mixed plastic waste streams. |
| EPR Compliance Technology Deployment | QR-coded return incentives embedded in pouch designs satisfy regulator audit requirements. |
| KwaZulu-Natal Export Manufacturing Expansion | Durban port logistics infrastructure supports Southern African Development Community market access. |
| Digital Print Platform Integration | Short-run variable data printing enables mass customization without plate costs for regional brands. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with blown film extrusion plant managers, FMCG packaging development directors, SABS certification auditors, and retail procurement leads at national supermarket chains. Secondary validation drew from Department of Forestry, Fisheries and the Environment regulatory filings, South African Bureau of Standards certification databases, petrochemical import customs records, and National Regulator for Compulsory Specifications SANS code documentation. Bottom-up volume modeling across product types, materials, applications, and end users triangulated against top-down industry value chain estimates.
Calibration against historical resin price volatility patterns and EPR implementation timelines in comparable emerging markets anchored projection assumptions across the analysis window. Segmentation dimensions modeled include product structural format, polymer resin type, end-use application category, and provincial production cluster. CAGRs were derived from elasticity-adjusted demand forecasting incorporating e-commerce penetration curves and food-contact safety upgrade replacement cycles. Industry-specific inputs encompassed mechanical recycling contamination rate trajectories and chemical recycling technology cost curves.
Sensitivities concentrate around Department of Forestry, Fisheries and the Environment enforcement intensity, international oil benchmark volatility, and chemical recycling technology commercialization pace. Forecasts reflect documented assumptions regarding regulatory deadline adherence and infrastructure investment flows. Macroeconomic deviation, regulatory acceleration, or technological breakthrough would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Plastic Packaging
Asia-Pacific Plastic Bottles and Containers Market
Plastic Packaging
Europe Single-Use Plastic Packaging Market
Plastic Packaging
Thermoforming Plastic Market
Plastic Packaging
Transparent Plastic Packaging Market
Plastic Packaging
PET Jars Market
Plastic Packaging
Global Single Use Plastic Packaging Market
Plastic Packaging
United Kingdom Plastic Bottles Market
Plastic Packaging
Australia and New Zealand Plastic Bottles Market
Plastic Packaging
Plastic Tumblers Market
Plastic Packaging
MENA Thermoform Plastic Packaging Market
Plastic Packaging
Plastic Cans Market
Plastic Packaging
Japan Plastic Bottles Market
Plastic Packaging
North America Blow Molded Plastics Market
Plastic Packaging
Folding Plastic Crates Market
Plastic Packaging
Egypt Plastic Packaging Market
Plastic Packaging
Plastic Battery Containers Market