
 China Marine Coatings Market | 2026-2036
China Marine Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
China Marine Coatings Market Outlook
Marine coatings distribution through bonded warehouse networks is fragmenting as regional shipyards bypass traditional port-city intermediaries. Akzo Nobel N.V. leverages its Shanghai technical service center to sustain direct relationships with Yangtze Delta builders. Jotun anchors its position through specialized antifouling supply agreements with state-owned shipyards. Hempel A/S competes via localized blending operations that reduce lead times for repair yard customers.
China marine coatings are protective films formulated with epoxy resins, zinc-rich primers, and copper-based biocides, applied to steel hulls and offshore structures to prevent corrosion and biofouling in saltwater environments. Antifouling products dominate volume as fleet operators face dry-docking schedules mandated by classification societies, while high-performance coatings capture premium margins from offshore structure owners seeking extended maintenance intervals. Water-based technology segments are gaining share as MEE enforcement tightens, though solvent-based systems still lead in military ship applications where performance specifications override environmental compliance.
China's Ministry of Ecology and Environment enforces GB standards limiting volatile organic compound emissions from marine coating production and application, while the Maritime Safety Administration inspects hull coating compliance under international convention protocols. The national dual carbon goals are forcing reformulation across solvent-based product lines, with SAMR tracking quality certification for imported coating systems. Stakeholders must monitor how Jiangsu and Shandong provincial environmental bureaus interpret national VOC reduction timelines, as local implementation variance will reshape supplier qualification requirements and manufacturing location decisions.
Market Dynamics
The China Marine Coatings Market is being fundamentally restructured by MEE enforcement of GB volatile organic compound standards, which is forcing solvent-based formulators to accelerate water-based reformulation while state-owned shipyards consolidate procurement around certified suppliers.
Growth Catalysts
- Yangtze Delta Shipyard Expansion:Jiangsu and Zhejiang provinces are consolidating newbuild orders, concentrating demand for high-performance hull protection systems among clustered builders.
- GB Standards Enforcement:MEE volatile organic compound limits are compelling fleet operators to advance dry-docking schedules, compressing replacement cycles for antifouling coatings.
- Offshore Structure Investment:Extended maintenance interval specifications from platform operators are pulling premium epoxy formulations into deepwater asset protection.
Market Restraints
- Copper Biocide Cost Volatility:Raw material price swings for copper-based biocides are squeezing margins on conventional antifouling product lines.
- Import Certification Friction:SAMR quality certification requirements for foreign coating systems are extending qualification timelines for international suppliers.
- Technical Performance Gap:Water-based formulations still lag solvent-based systems in military ship applications where saltwater corrosion resistance specifications are non-negotiable.
Strategic Opportunities
- Shandong Port Cluster Penetration:Repair yard consolidation around Qingdao and Yantai is opening direct supply relationships bypassing traditional bonded warehouse networks.
- Dual Carbon Policy Tailwind:National carbon neutrality targets are incentivizing low-emission coating application methods and bio-based resin development.
- Silicone-Epoxy Convergence:Hybrid foul-release systems combining silicone surface chemistry with epoxy adhesion are creating new performance tiers for container vessels.
Industry Challenges
- Formulation Chemist Scarcity:Shortage of specialists capable of balancing VOC compliance with saltwater performance specifications is extending R&D cycles.
- Classification Society Coordination:Multi-agency hull coating compliance inspections under Maritime Safety Administration protocols are complicating dry-docking logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Marine Coatings Market |
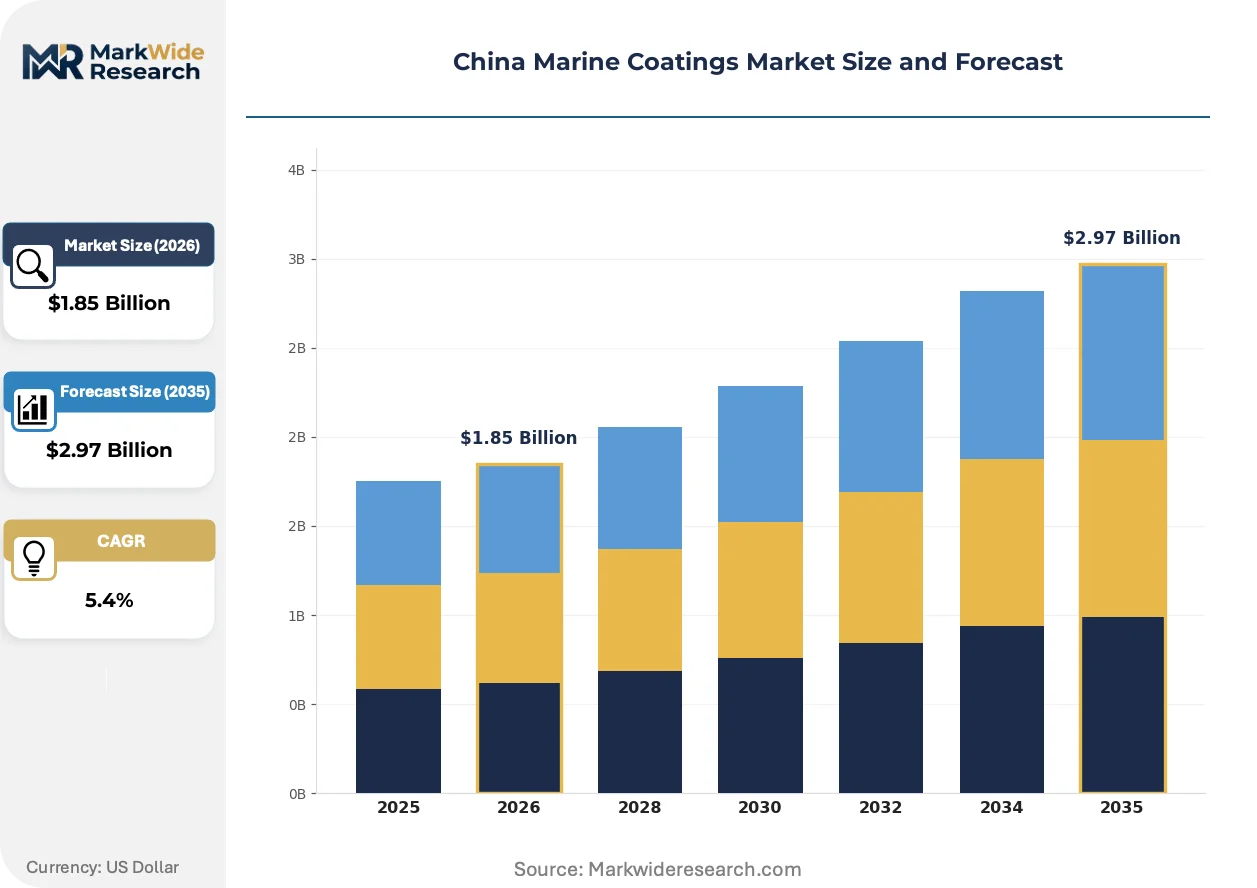
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antifouling, Barrier Coatings, Topcoats, Epoxy Coatings Application: Commercial Vessels, Military Ships, Yachts, Offshore Structures End User: Shipbuilders, Repair Yards, Fleet Operators, Original Equipment Manufacturers Technology: Water-Based, Solvent-Based, Powder Coating, High-Performance Coatings |
| Companies Covered | Akzo Nobel N.V., Jotun, PPG Industries, Hempel A/S, Chugoku Marine Paints Ltd, Nippon Paint Marine, Kansai Paint Marine Co Ltd, Xiamen Sunrui Ship Coating Co., Ltd., JDmarine Paint, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Marine Coatings Market Strategic Shifts
Reformulation pressure from environmental regulators is intersecting with procurement centralization among state-owned yards, creating simultaneous technology and distribution model disruptions across the supply base.
Silicone-based foul-release coatings are eliminating the need for toxic biocide loading through low-surface-energy mechanisms that prevent organism attachment. Container fleet operators at Ningbo-Zhoushan are piloting these systems at scale. The technology is rendering obsolete conventional copper-based ablative systems in routes with predictable speed profiles.
MEE implementation of GB volatile organic compound emission limits is tightening enforcement timelines for solvent-based marine coating production facilities. Manufacturers in Jiangsu province are retooling blending operations to maintain operating licenses. Military ship applications remain exempt, preserving a shrinking solvent-based niche.
Direct technical service relationships are displacing traditional port-city distributor intermediaries as Yangtze Delta shipyards consolidate procurement decisions. Akzo Nobel's Shanghai center and Jotun's specialized antifouling agreements exemplify this channel compression. The shift is most visible in Jiangsu where bonded warehouse networks are losing volume to mill-direct supply.
China Marine Coatings Market Segmentation
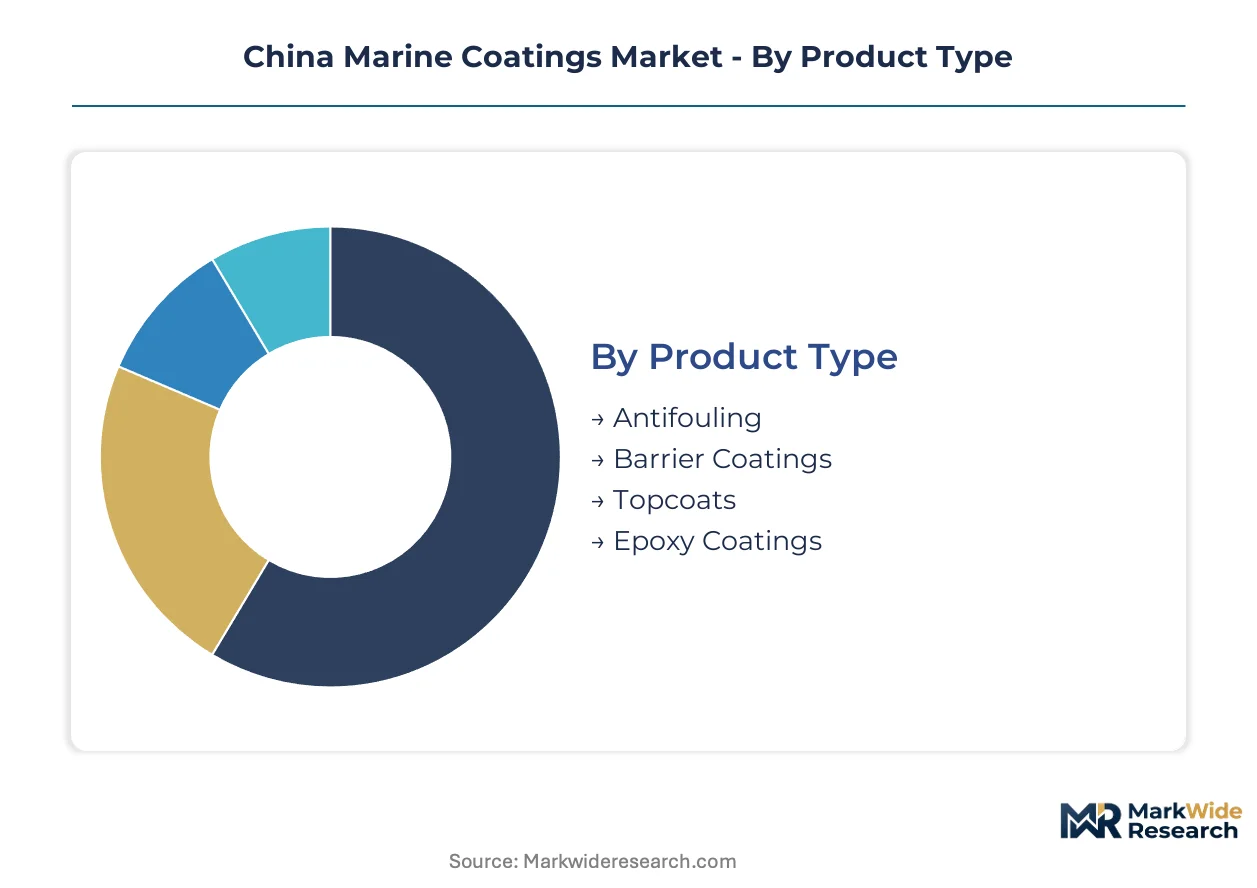
Segmentation in China's marine coatings market reveals how environmental compliance and vessel specialization are splitting procurement patterns across product lines and customer types. Understanding these divides clarifies where formulation investments concentrate and which application channels offer entry points for new suppliers.
Product Type:
Mature antifouling formulations dominate current volume while emerging silicone-epoxy hybrids reshape performance expectations in premium tiers.
- Antifouling:Copper-based biocide systems and silicone foul-release formulations prevent biofouling on hull surfaces operating in saltwater environments. Jiangsu shipyard clusters are consolidating procurement around extended-service antifouling products that compress dry-docking intervals mandated by classification society protocols.
- Epoxy Coatings:Two-component systems combining epoxy resins with zinc-rich primers deliver corrosion protection for ballast tanks and underwater hull areas. Offshore structure owners in the Bohai Bay are specifying high-build epoxy formulations that extend maintenance intervals beyond conventional coating lifecycles.
- Barrier Coatings:High-density film systems block moisture and chemical ingress in cargo holds and tank internals.
- Topcoats:UV-resistant finish layers provide aesthetic protection and weathering resistance for superstructure surfaces.
Antifouling handles the majority of throughput; epoxy coatings are climbing the fastest on share as offshore asset owners prioritize lifecycle cost reduction.
Application:
Volume concentrates in commercial newbuilds while margin expansion tracks toward specialized military and offshore segments with non-standard performance specifications.
- Commercial Vessels:Container ships, bulk carriers, and tankers require comprehensive hull protection systems spanning antifouling, anticorrosive, and cargo tank coatings. Yangtze Delta shipbuilders are expanding orders for high-performance hull protection systems as fleet operators face compressed dry-docking schedules under MEE enforcement timelines.
- Offshore Structures:Fixed platforms, FPSO units, and subsea equipment demand coating systems resistant to cathodic disbondment and high-pressure saltwater immersion. Deepwater developments in the South China Sea are pulling premium epoxy formulations from suppliers capable of meeting extended maintenance interval specifications.
- Military Ships:Naval vessels operate under performance specifications that override environmental compliance, preserving solvent-based system demand.
- Yachts:Recreational craft require aesthetic topcoats with lower technical specifications than commercial applications.
Commercial vessels absorb the bulk of coating volume; offshore structures are expanding most quickly as deepwater investment accelerates.
End User:
Procurement authority is shifting from fragmented repair yards toward centralized shipbuilder and fleet operator purchasing functions.
- Shipbuilders:New construction yards specify coating systems during vessel design, locking in supplier relationships for initial application and warranty periods. State-owned yards are consolidating procurement around certified suppliers with direct technical service capabilities.
- Fleet Operators:Container lines and bulk shipping companies manage coating specifications across vessel lifecycles, influencing dry-docking material selection. Classification society dry-docking mandates are compressing replacement cycles for operators with aging fleets.
- Repair Yards:Maintenance facilities execute coating removal and reapplication during scheduled dry-dockings.
- Original Equipment Manufacturers:Marine equipment suppliers apply protective coatings to components prior to vessel integration.
Shipbuilders control the largest share of specification authority; fleet operators are gaining influence fastest as procurement centralizes.
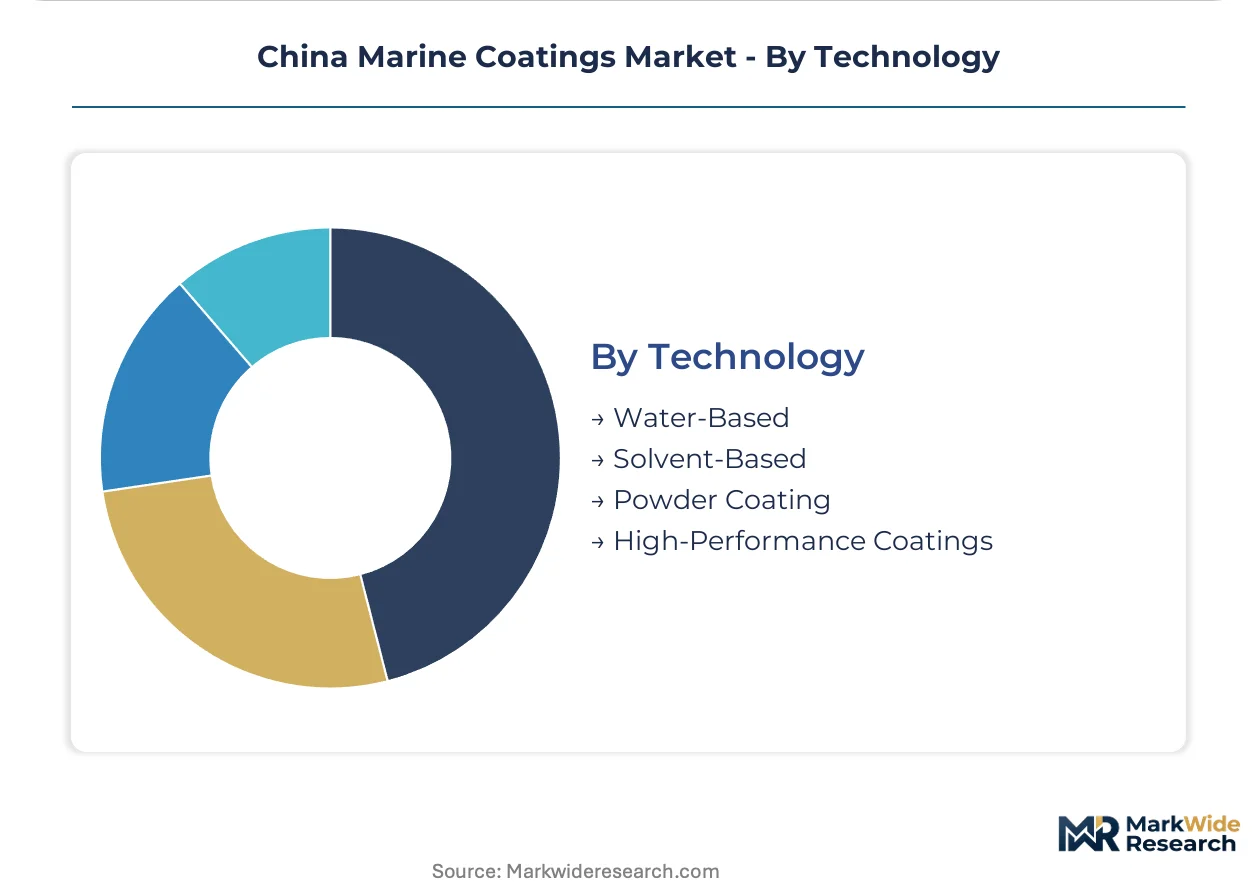
Technology:
Cost tiers separate established solvent systems from reformulated water-based alternatives competing on compliance rather than performance parity.
- Water-Based:Acrylic and polyurethane dispersions reduce volatile organic compound emissions during application and curing. MEE enforcement of GB standards is compelling manufacturers in Jiangsu province to retool blending operations toward water-based production to maintain operating licenses.
- Solvent-Based:Traditional alkyd and epoxy formulations deliver superior saltwater corrosion resistance through higher solids content and penetration characteristics. Military ship applications remain exempt from MEE volatile organic compound limits, preserving demand for solvent systems where performance specifications override environmental compliance.
- High-Performance Coatings:Specialized formulations including silicone-epoxy hybrids and foul-release systems command premium positioning.
- Powder Coating:Thermoset powder systems offer zero-VOC application for specific marine components and equipment.
Solvent-based technology still handles the majority of current volume; water-based systems are gaining share fastest as MEE enforcement tightens production facility compliance timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces command premium pricing power through Yangtze Delta shipyard consolidation, while Shandong's repair yards compete on volume throughput at compressed margins.
Yangtze River Delta
Jiangsu and Zhejiang shipbuilders concentrate newbuild orders for container vessels and bulk carriers, driving specification authority toward high-performance hull systems. MEE enforcement of GB volatile organic compound standards compresses dry-docking schedules for fleet operators based in Ningbo-Zhoushan. Shanghai's technical service infrastructure anchors supplier relationships as bonded warehouse networks lose intermediation share.
Shandong Peninsula
Qingdao and Yantai repair yards consolidate maintenance capacity for aging domestic fleets, pulling volume demand for recoating and hull refurbishment. Provincial environmental bureaus interpret national VOC reduction timelines with stricter facility compliance windows than Yangtze counterparts. Local blending operations reduce lead times for spot repair contracts at Yantai Port clusters.
Pearl River Delta
Guangdong's shipbuilding output concentrates in smaller specialized craft and offshore support vessels with differentiated coating specifications. The province's manufacturing base supplies epoxy resin feedstocks to marine formulators serving South China Sea platforms. Shenzhen and Guangzhou port authorities coordinate hull inspection protocols with Maritime Safety Administration regional offices.
Bohai Bay Rim
Tianjin and Dalian anchor offshore structure maintenance demand as deepwater platform operators specify extended-interval epoxy systems for fixed installations. State-owned yard procurement centralization in Dalian favors certified suppliers with direct technical service capabilities. The region's cold-water exposure requirements drive specification divergence from southern provinces.
South China Sea Development Zone
Hainan and adjacent coastal zones absorb offshore structure investment as deepwater oil and gas developments expand fixed platform footprints. Tropical biofouling pressure accelerates antifouling replacement cycles compared to temperate northern waters. Local environmental enforcement follows MEE baseline standards with limited provincial augmentation.
China Marine Coatings Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream blending operations and biocide supply. The China Marine Coatings Market structures around three tiers: multinational formulators with technical service infrastructure, regional blenders with localized production licenses, and state-owned yard captive suppliers. Competitive moves concentrate on direct shipyard relationship formation and water-based reformulation acceleration to maintain Jiangsu and Zhejiang operating permits.
Among multinational formulators, Akzo Nobel N.V., Jotun, and Hempel A/S occupy positions defined by technical service proximity to Yangtze Delta shipbuilders. Akzo Nobel's Shanghai center exemplifies platform-tier investment in direct relationship maintenance. Jotun anchors specialized antifouling positioning through state-owned yard agreements. Hempel A/S represents localized blending archetypes competing on repair yard lead time compression. PPG Industries and Chugoku Marine Paints Ltd sit within the same tier with differentiated geographic emphases. Xiamen Sunrui Ship Coating Co., Ltd. and JDmarine Paint exemplify domestic specialists consolidating around bonded warehouse bypass strategies.
| Leading Market Players |
|---|
| Akzo Nobel N.V. |
| Jotun |
| PPG Industries |
| Hempel A/S |
| Chugoku Marine Paints Ltd |
| Nippon Paint Marine |
| Kansai Paint Marine Co Ltd |
| Xiamen Sunrui Ship Coating Co., Ltd. |
| JDmarine Paint |
| Others |
Value Chain & Pricing Dynamics
Epoxy resin and copper biocide feedstock concentration in Jiangsu and Shandong provinces anchors margin pools at the formulation tier, where blending operations with direct shipyard relationships capture premium positioning. MEE enforcement timelines compress procurement cycles, forcing price discipline on solvent-based product lines while water-based alternatives compete on compliance value.
Pricing Analysis
The customization-premium spread between silicone-epoxy foul-release systems and standard antifouling formulations runs wide based on performance certification tier and volume commitment scale. Three-tier pricing structure across premium, standard, and economy levels separates extended-service antifouling from conventional ablative systems and basic repair-grade epoxies. Pricing pressure stems from copper biocide cost volatility squeezing conventional product margins. Fleet operators with aging vessels show highest price sensitivity; offshore platform owners with extended maintenance interval specifications demonstrate lowest.
Supply Chain Analysis
Supplier-financing facilities with extended payment terms have become standard procurement instruments as state-owned shipyards consolidate purchasing authority. Raw material sourcing draws from domestic epoxy resin production in Jiangsu, imported copper biocide concentrates, and specialty silicone feedstocks from Japan and South Korea. Single-source vulnerability concentrates in military-grade solvent-based formulation supply where SAMR certification timelines extend qualification windows. Distribution runs through direct technical service relationships displacing traditional bonded warehouse networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China marine coatings incumbents face substitution defense against silicone-based foul-release systems eliminating copper biocide demand in container fleet applications.
For Market Incumbents: Build formulation moats around water-based epoxy systems that satisfy MEE GB standards without sacrificing saltwater corrosion resistance. Accelerate R&D cycles to close performance gaps with solvent-based military specifications. Secure direct technical service presence in Jiangsu shipyard clusters before procurement centralization locks out intermediaries. Threat vector: silicone foul-release technology rendering copper ablative systems obsolete on predictable-speed routes. For New Entrants and Emerging Players: Build out specialized positioning in Shandong repair yard consolidation around Qingdao and Yantai, where bonded warehouse bypass creates entry openings. Target spot recoating contracts with compressed lead time requirements that favor local blending operations. White-space penetration: bio-based resin development aligned with dual carbon policy incentives. Go-to-market angle: supply-chain finance facilities matching state-owned yard payment terms. For Investors and Strategic Acquirers: Capital is best deployed toward regional blenders with localized production licenses and existing MEE compliance certification in Jiangsu province. Long-term viability hinges on water-based reformulation capability and direct shipyard relationship infrastructure. Acquisition target archetype: domestic specialists with bonded warehouse bypass strategies and technical service proximity to Yangtze Delta clusters. Signal to watch: SAMR import certification friction tightening qualification timelines for foreign systems.| Strategic Initiative | Industry Significance |
|---|---|
| Water-Based Reformulation Acceleration | MEE GB compliance preserves Jiangsu operating licenses against enforcement timelines. |
| Direct Technical Service Expansion | Shanghai and Ningbo centers anchor supplier relationships as bonded warehouses lose share. |
| Silicone-Epoxy Hybrid Development | Foul-release convergence creates premium tiers for container fleet operators at Ningbo-Zhoushan. |
| Shandong Repair Yard Penetration | Qingdao and Yantai consolidation opens volume demand bypassing traditional intermediaries. |
| SAMR Certification Investment | Quality certification acceleration reduces import friction for foreign formulation systems. |
Study Parameters
Two parallel data streams informed the analysis: primary interviews with marine coatings procurement managers, shipyard technical directors, and MEE regulatory compliance officers; and secondary validation through customs trade data, SAMR certification records, and SEC filings from listed suppliers. Bottom-up triangulation across product type, application, and technology segments anchored volume estimates against top-down market sizing.
Forecast inputs considered Yangtze Delta shipyard expansion trajectories, MEE enforcement timeline acceleration, and offshore structure investment patterns across the analysis window. Segmentation dimensions modeled included product formulation chemistry, vessel type specification authority, end-user procurement centralization, and technology compliance tier. CAGRs derived from regression analysis against historical coating consumption and fleet dry-docking cycle compression.
Practitioners should monitor MEE provincial implementation variance and copper biocide price volatility for early signals of forecast deviation. Forecasts reflect assumptions around dual carbon policy continuity and classification society dry-docking mandate adherence. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Waterproof Coating Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Protective Antimicrobial Coatings for High-Touch Surfaces Market
Coatings
Pure Epoxy Powder Coatings Market
Coatings
Europe Super Hydrophobic Coatings Market
Coatings
Carbon Fiber Coatings Market
Coatings
Hydrophilic Coatings Market
Coatings
Coated Casing Market
Coatings
Coating Resins Market
Coatings
Polyurethane Powder Coatings Market
Coatings
Global Abrasion Resistant Coatings Market
Coatings
Global Pipe Coatings Market
Coatings
Global Optical Coating Market
Coatings
Protective and Marine Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
ASEAN Protective Coatings Market