
 Flexible Waterproof Coating Market | 2026-2036
Flexible Waterproof Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Flexible Waterproof Coating Market Foresight
China's manufacturing corridor expansion for polymer-based construction materials is reshaping regional supply availability for flexible waterproof coatings. BASF SE leverages its integrated polyurethane precursor operations to sustain feedstock cost advantages across Asian project markets. Sherwin-Williams Company anchors North American distribution through dedicated waterproofing contractor channels. Sika AG competes on specification depth in tunnel and bridge elastomeric systems across European infrastructure tenders.
Flexible waterproof coatings are polymer-modified liquid or sheet membranes engineered to elongate 200-800% without fracture while maintaining hydrostatic resistance exceeding 50 psi, designed to protect structural substrates from water ingress, chloride penetration, and thermal cycling damage. Acrylic and polyurethane chemistries dominate product type volumes due to their balance of UV stability and crack-bridging elasticity, though nano-coating technology is gaining specification in high-performance building envelopes where minimal film thickness matters. Water-based formulations lead technology adoption in residential and indoor applications driven by VOC regulations, while solvent-based systems retain share in heavy civil infrastructure where cure speed and subzero application tolerance prove critical.
REACH restrictions on isocyanate content and the EU Green Deal's embodied carbon thresholds for construction products are elevating compliance costs for imported formulations across European member states. China's GB/T 19250 polyurethane waterproofing standard and India's BIS certification for bituminous membranes create divergent testing protocols that fragment market access requirements. Stakeholders must monitor regulatory convergence between regional green building codes and chemical hazard classifications to anticipate reformulation investments and qualification timeline shifts.
Market Dynamics
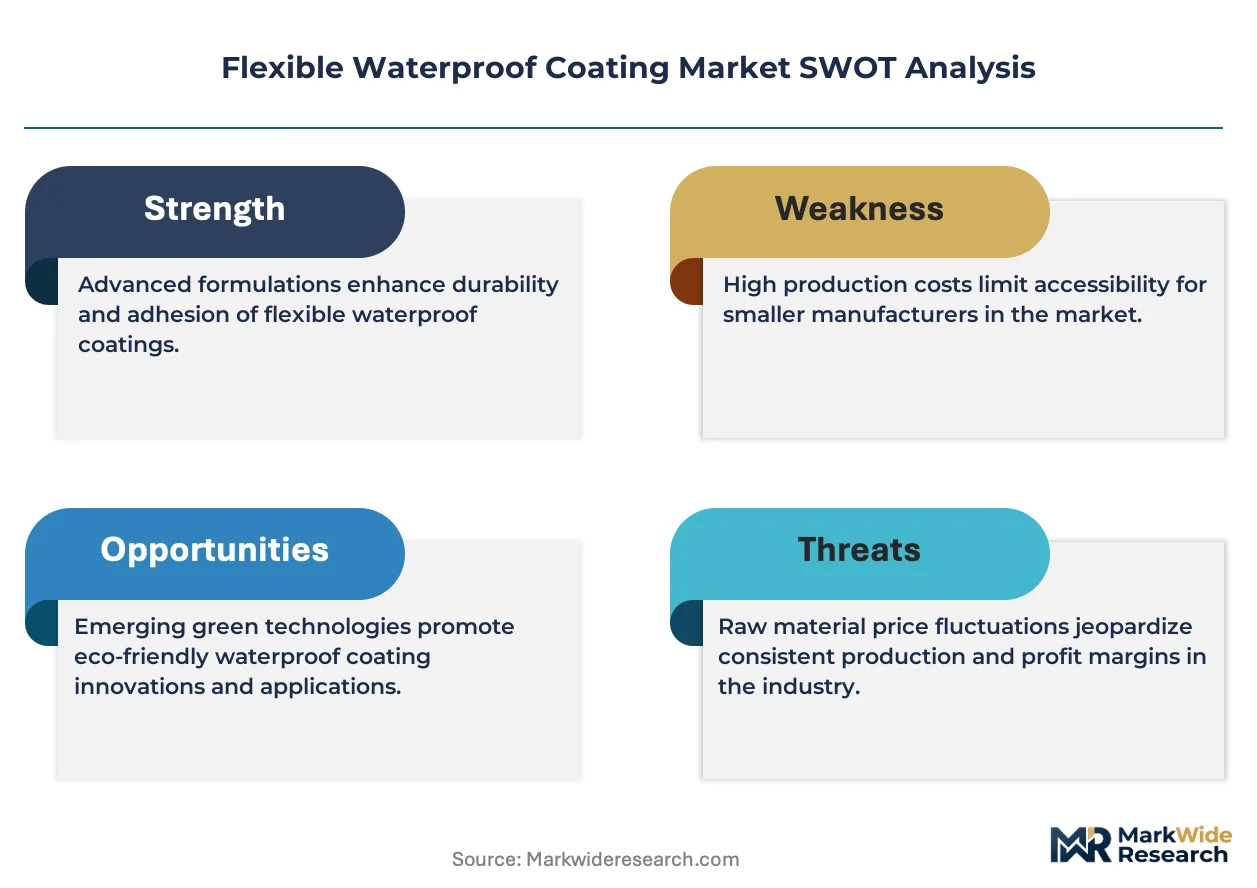
Polymer feedstock volatility and divergent national certification standards are compressing formulation margins while fragmenting market access pathways for flexible waterproof coating suppliers.
Growth Catalysts
- GB/T 19250 Standard Convergence:China's tightening polyurethane waterproofing benchmarks are accelerating replacement of conventional bituminous systems in high-rise residential towers across the Yangtze River Delta.
- Metro Rail Infrastructure:Underground transit expansion in India is specifying elastomeric liquid membranes for station box structures and tunnel linings.
- Nano-Coating Technology:Ultra-thin film formulations are penetrating high-performance commercial envelopes where minimal build-up and crack-bridging elasticity prove critical.
Market Restraints
- Isocyanate Input Volatility:REACH restrictions on diisocyanate content are elevating raw material qualification costs for polyurethane-based formulations entering European member states.
- Regional Supply Concentration:Polymer precursor production clusters in coastal China create dependency risks for formulators lacking backward integration into propylene oxide supply.
- Technical Substitution:Pre-applied bonded sheet membranes are displacing liquid-applied systems in certain below-grade applications where installation speed dominates specification criteria.
Strategic Opportunities
- EU Green Deal Alignment:Embodied carbon thresholds for construction products are creating first-mover advantages for water-based, low-VOC formulations with verified environmental product declarations.
- Smart Building Integration:Convergence of waterproofing membranes with embedded moisture sensors is opening specification channels in data center and healthcare facility envelopes.
- German Distributor Networks:Direct contractor channel partnerships are enabling specification capture in renovation-heavy markets where green building certification drives material selection.
Industry Challenges
- Formulation Chemist Scarcity:Specialized expertise in hybrid polymer systems combining acrylic flexibility with polyurethane hydrolytic stability remains concentrated among legacy technical staff.
- BIS Certification Timelines:India's bituminous membrane testing protocols create extended qualification periods that delay product launch in rapidly tendering infrastructure corridors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flexible Waterproof Coating Market |
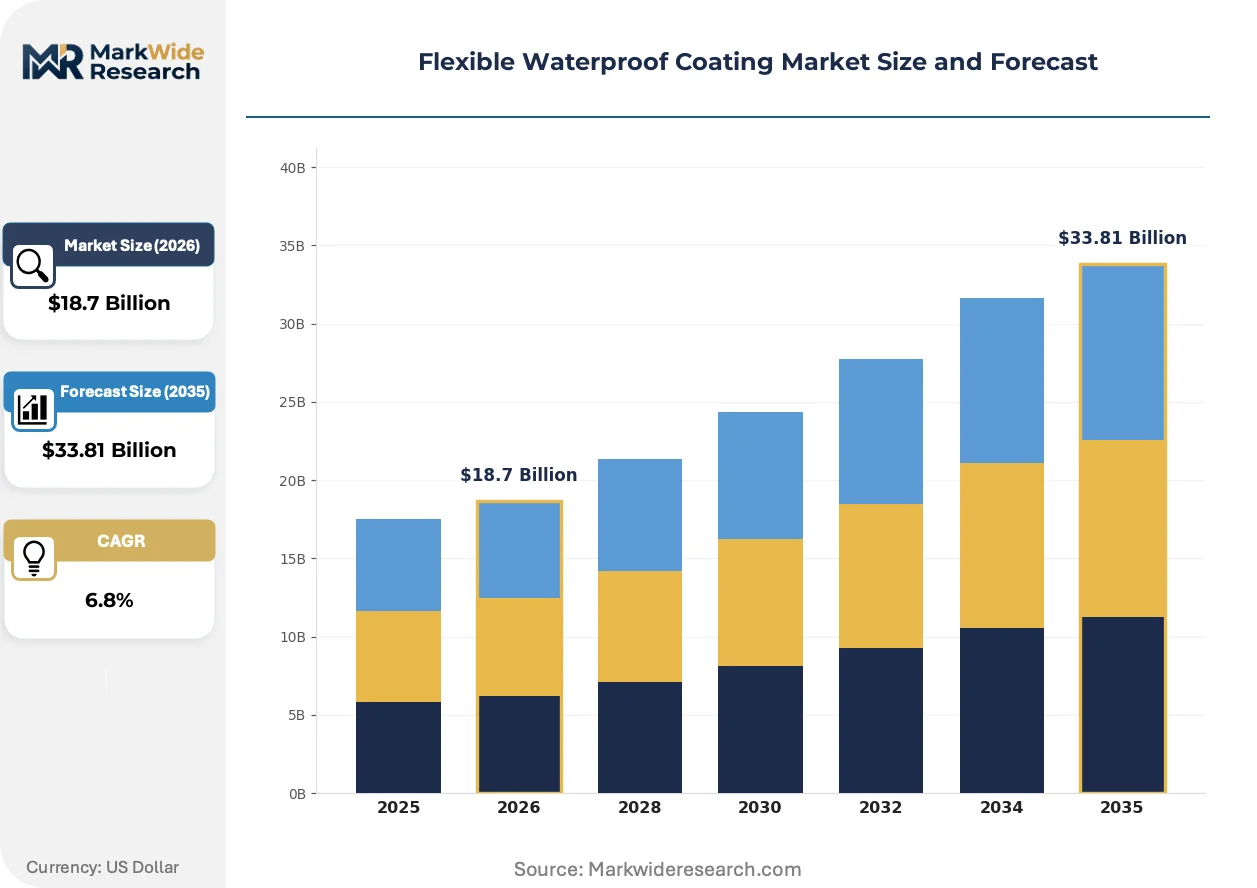
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polyurethanes, Acrylics, Bituminous, Silicone, Epoxy Application: Roofing Membranes, Basements, Balconies, Tunnels, Bridges End User: Construction Contractors, Infrastructure Developers, Marine Engineers, Waterproofing Specialists, Residential Builders Technology: Solvent-based, Water-based, UV-cured, Elastomeric, Nano-coating |
| Companies Covered | Sherwin-Williams Company, Akzo Nobel N.V., BASF SE, GAF Materials Corporation, RPM International Inc., The Dow Chemical Company, Sika AG, Tremco Incorporated, PPG Industries, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flexible Waterproof Coating Market Shifts & Advancements
Digital quality assurance and predictive specification tools are compressing traditional contractor decision cycles while elevating performance verification standards across project types.
Embedded sensor technology within elastomeric membrane systems is digitizing substrate condition monitoring for commercial building owners. Facility managers in German and Dutch logistics parks are piloting these installations to transition from scheduled maintenance to condition-based intervention. The shift is digitizing warranty risk allocation between applicators and material suppliers.
REACH authorization requirements for isocyanate-containing preparations are tightening occupational exposure benchmarks across European manufacturing and application sites. Formulators are restructuring supply chains to source blocked isocyanate alternatives or water-based polyurethane dispersions. Heavy civil infrastructure contractors are absorbing compliance costs while residential applicators face qualification bottlenecks.
Specification databases and digital product selectors are displacing traditional distributor-led recommendation patterns among mid-sized commercial contractors. German waterproofing specialists are accessing performance data directly through manufacturer platforms, compressing the specification cycle from weeks to days. The behavioral shift is most pronounced in renovation markets where rapid tender response determines contract capture.
Flexible Waterproof Coating Market Segmentation
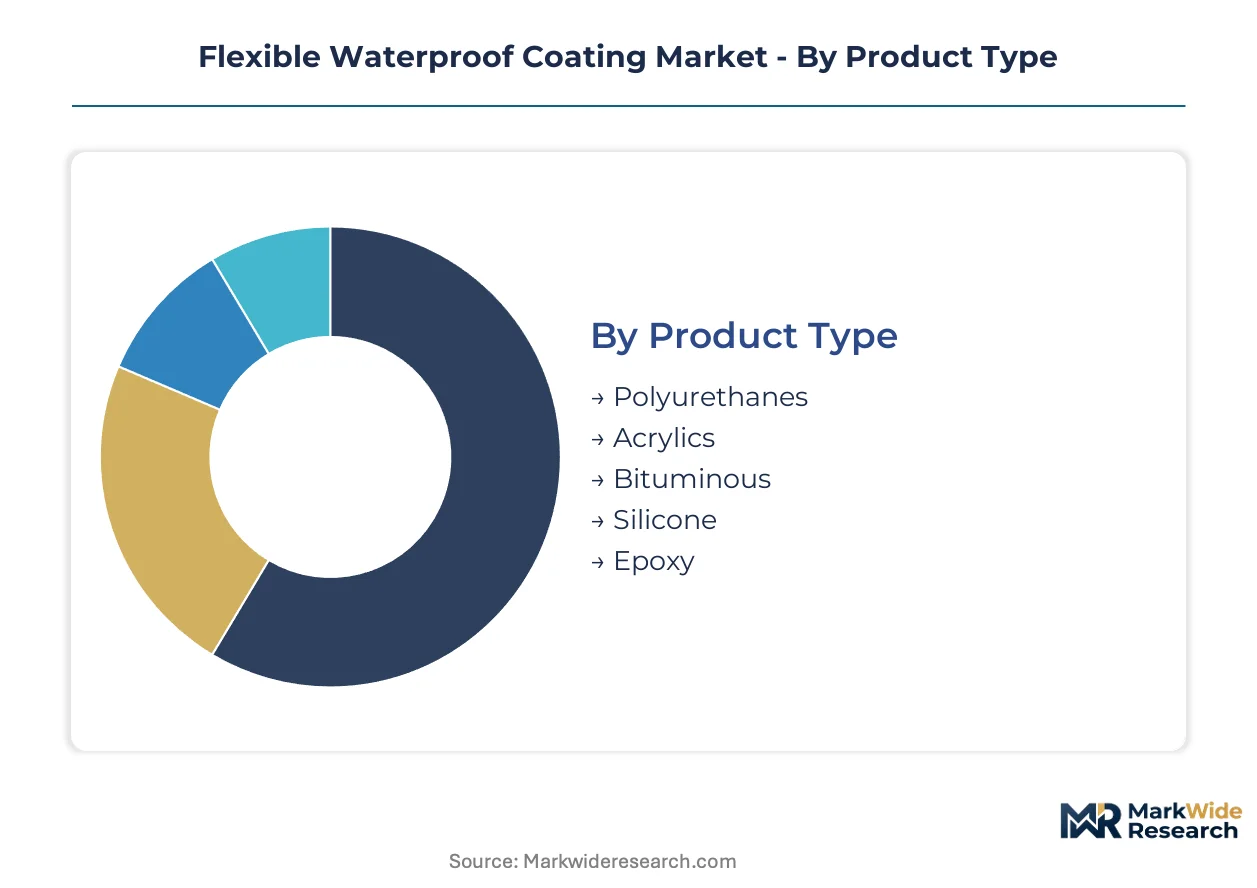
Segmentation in flexible waterproof coatings determines specification pathways, contractor qualification requirements, and reformulation investments. Product chemistry and application environment together dictate warranty terms, applicator training intensity, and after-sales service obligations.
Product Type:
After-sales service intensity varies sharply by chemistry — polyurethane systems demand applicator recertification and substrate moisture testing, while bituminous coatings require minimal technical support.
- Polyurethanes:Two-component systems combining isocyanate resins with polyol hardeners deliver 400-800% elongation and hydrostatic resistance exceeding 70 psi. Metro rail tunnel specifications in India and high-rise basements in China's Yangtze River Delta concentrate demand, though REACH isocyanate restrictions elevate European compliance costs.
- Acrylics:Water-dispersed styrene-acrylic copolymers achieve 200-350% elongation with UV stability for exposed roofing. German green building certification programs and Dutch logistics park renovations drive specification, with low-VOC formulations capturing first-mover advantages under EU Green Deal embodied carbon thresholds.
- Bituminous:Oxidized asphalt or polymer-modified emulsions dominate cost-sensitive below-grade applications.
- Silicone:Moisture-cure alkoxy systems penetrate high-temperature industrial roofing.
- Epoxy:Rigid amine-cured systems serve secondary containment and chemical resistance.
By volume, bituminous leads. By growth pace, polyurethanes are expanding most quickly.
Application:
Application environment determines film thickness requirements, cure conditions, and inspection protocols — tunnel linings demand continuous elastomeric integrity where roofing tolerates seam-dependent systems.
- Roofing Membranes:Liquid-applied acrylic and polyurethane systems achieve 80-120 mil dry film thickness across structural decks and green roof assemblies. German distributor networks and Dutch commercial renovation markets concentrate demand, with digital product selectors compressing specification cycles from weeks to days.
- Basements:Negative-side and positive-side waterproofing of below-grade concrete requires hydrostatic resistance exceeding 50 psi and crack-bridging elasticity. India's urban infrastructure corridors and China's high-rise residential towers drive volume, though pre-applied bonded sheet membranes are displacing liquid systems where installation speed dominates.
- Balconies:Pedestrian traffic-bearing systems with slip-resistant topcoats serve multi-unit residential.
- Tunnels:Elastomeric membranes for segmental lining gaskets and station box structures.
- Bridges:Deck waterproofing with chloride penetration resistance for expansion joint compatibility.
Basements generate highest volume. Roofing membranes show steepest specification growth.
End User:
End-user technical sophistication shapes procurement patterns — infrastructure developers embed performance specifications in tender documents while residential builders prioritize distributor availability.
- Construction Contractors:Commercial envelope specialists specify liquid-applied membranes through direct manufacturer platforms, bypassing traditional distributor channels. German waterproofing contractors access performance data digitally, enabling rapid tender response in renovation-heavy markets.
- Infrastructure Developers:Metro rail and highway authorities mandate elastomeric systems with embedded moisture sensors for condition-based maintenance. Facility managers in German and Dutch logistics parks pilot these installations, digitizing warranty risk allocation.
- Marine Engineers:Offshore platform and port structure applications.
- Waterproofing Specialists:Certified applicators with manufacturer-direct relationships.
- Residential Builders:Volume purchasers of water-based systems for single-family foundations.
Construction contractors dominate volume. Infrastructure developers are gaining share fastest.
Technology:
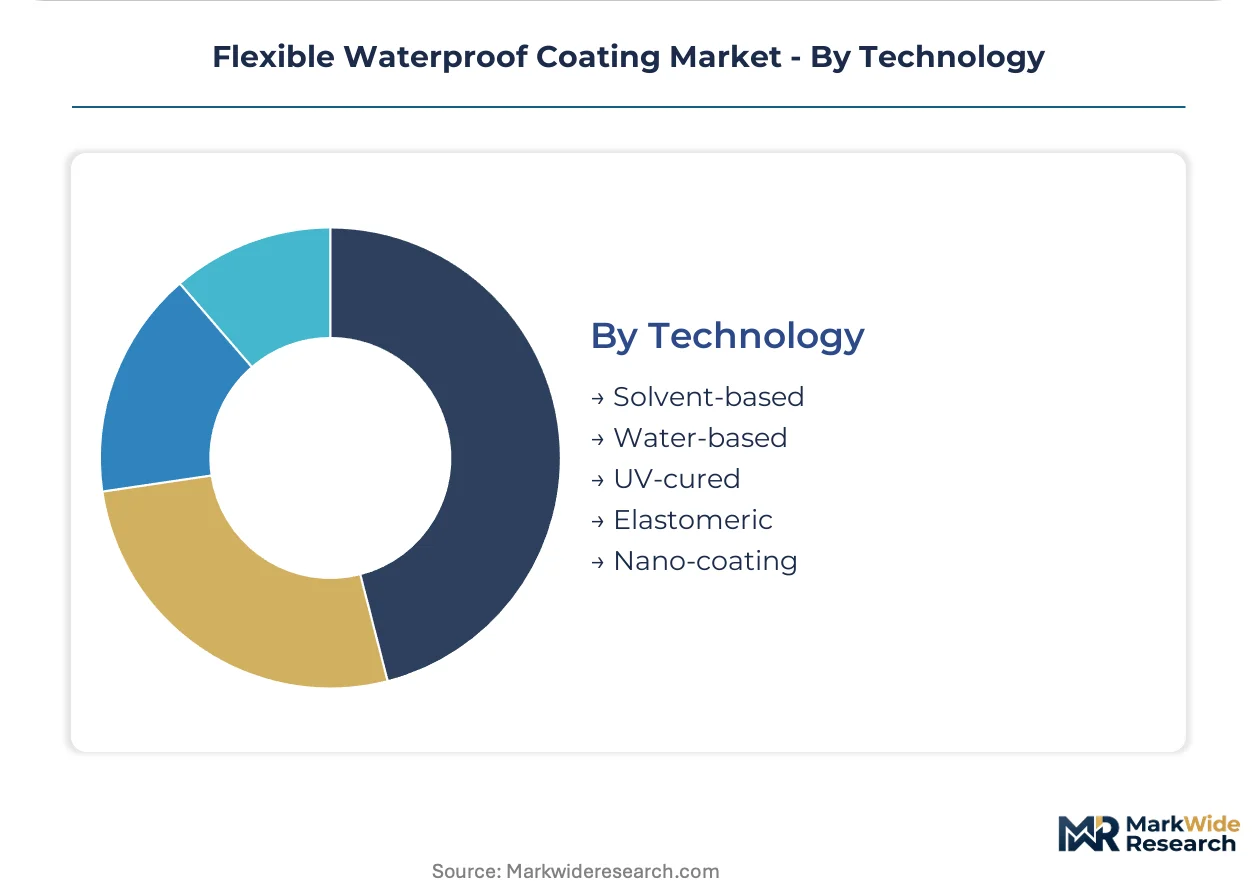
Technology selection balances cure speed, VOC compliance, and application temperature tolerance — solvent-based systems retain infrastructure share where subzero conditions prevail.
- Solvent-based:Rapid-cure polyurethane and epoxy formulations maintain specification in heavy civil infrastructure. Tunnel and bridge contractors in northern climates absorb elevated material costs for subzero application tolerance, though occupational exposure regulations tighten across European manufacturing sites.
- Water-based:Acrylic and polyurethane dispersions lead residential and indoor applications. India's BIS certification timelines for bituminous membranes create qualification bottlenecks, while water-based alternatives penetrate faster in rapidly tendering corridors.
- UV-cured:Instant-cure systems for production line roofing panel manufacturing.
- Elastomeric:High-elongation formulations for dynamic crack bridging.
- Nano-coating:Ultra-thin film technology for high-performance commercial envelopes.
Water-based leads by volume. Nano-coating shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polymer precursor manufacturing clusters in coastal China dominate upstream feedstock availability for flexible waterproof coating formulators. This concentration creates supply dependencies for regional compounders lacking captive propylene oxide operations. Distributor networks in Germany and specification-driven procurement in India are reshaping downstream access patterns.
China
Metro rail expansion and high-rise residential construction across the Yangtze River Delta concentrate demand for polyurethane-based elastomeric systems. GB/T 19250 standards for waterproofing materials are tightening performance benchmarks and accelerating replacement of conventional bituminous membranes. Shanghai and Hangzhou manufacturing corridors host integrated polymer production facilities serving domestic project markets.
Germany
Green building certification programs and logistics park renovation cycles drive specification of low-VOC acrylic formulations. EU Green Deal embodied carbon thresholds and REACH restrictions on isocyanate content are elevating compliance costs for imported polyurethane systems. The Rhine-Ruhr industrial region anchors distributor networks where digital product selectors compress contractor decision cycles.
India
Urban infrastructure corridors in Mumbai, Delhi, and Bangalore generate concentrated demand for basement and tunnel waterproofing systems. BIS certification timelines for bituminous membranes create qualification bottlenecks that delay product launches in rapidly tendering metro rail projects. Water-based formulations penetrate faster where certification pathways prove more streamlined.
United States
Commercial building envelope retrofits and data center construction specify liquid-applied membranes through dedicated contractor channels. EPA VOC regulations vary by state and influence formulation chemistry selection for indoor applications. The Gulf Coast petrochemical corridor supplies acrylic and polyurethane precursors to regional compounders.
United Arab Emirates
Megaproject construction and coastal infrastructure development specify high-performance waterproofing for basement and podium structures. MOHAP chemical registration requirements and green building certification mandates from Estidama influence material qualification pathways. Dubai and Abu Dhabi construction markets concentrate specification activity for premium elastomeric systems.
Flexible Waterproof Coating Market Competitive Landscape
Integrated chemical conglomerates and specialized construction material suppliers split the market between feedstock-integrated scale and specification-depth agility. The vendor base concentrates around three strategic archetypes: multinational coatings manufacturers with backward integration into polymer precursors, regional formulators with distributor-channel dominance, and specialty chemical suppliers focused on infrastructure-grade elastomeric systems. Competitive moves center on digital specification platform deployment and direct contractor channel partnerships that bypass traditional distribution.
Among multinational coatings manufacturers, Sherwin-Williams Company and BASF SE exemplify the feedstock-integrated archetype with captive supply advantages across North American and Asian project markets. Sika AG occupies a position within the specialty infrastructure tier, anchoring specification depth in tunnel and bridge applications where elastomeric performance requirements prove most stringent. These three companies represent divergent strategic postures on vertical integration, geographic footprint, and end-market specialization.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| Akzo Nobel N.V. |
| BASF SE |
| GAF Materials Corporation |
| RPM International Inc. |
| The Dow Chemical Company |
| Sika AG |
| Tremco Incorporated |
| PPG Industries, Inc. |
| Others |
Supply & Pricing Matrix
Coastal China's polymer precursor manufacturing clusters concentrate propylene oxide and isocyanate feedstock availability, positioning backward-integrated formulators to capture margin pools in specification-grade elastomeric systems while independent compounders absorb volatility-driven cost compression.
Pricing Analysis
REACH restrictions on diisocyanate content dictate the pricing tier structure across European member states. Three-tier pricing structure across premium certified, standard compliant, and economy bituminous levels separates warranty-backed elastomeric systems from basic below-grade applications. Price differentiation hinges on GB/T 19250 certification status and applicator recertification bundling. Cost compression in mid-tier polyurethane formulations is intensifying because blocked isocyanate alternatives carry 15-20% raw material premia. Residential builders exhibit highest price sensitivity, while infrastructure developers prioritize hydrostatic performance over unit cost.
Supply Chain Analysis
Propylene oxide and aromatic isocyanate feedstocks draw from manufacturing corridors in coastal China, the US Gulf Coast, and the Rhine-Ruhr industrial region. Formulation output rests on MDI, polyether polyols, and acrylic emulsion inputs. Single-source vulnerability concentrates in Yangtze River Delta polymer plants serving Asian project markets. Distribution runs through German specialist distributors and direct contractor platforms in North American commercial envelope markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized expertise in hybrid polymer systems combining acrylic flexibility with polyurethane hydrolytic stability remains concentrated among legacy technical staff at established suppliers, creating acquisition premiums for firms possessing captive formulation knowledge.
For Market Incumbents: Pre-empt technical substitution threats from pre-applied bonded sheet membranes by embedding moisture sensor technology into elastomeric warranty packages. Deepen backward integration into propylene oxide supply through long-term offtake agreements with Yangtze River Delta producers. Capture specification lock-in via direct digital platform deployment targeting German renovation contractors. For New Entrants and Emerging Players: Pursue water-based polyurethane dispersion gaps in India's rapidly tendering metro rail corridors where BIS certification bottlenecks delay incumbent product launches. Target logistics park renovation cycles in the Netherlands and Germany where EU Green Deal embodied carbon thresholds favor low-VOC formulations. Establish German distributor partnerships as the primary go-to-market angle to bypass specification cycle compression. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional formulators possessing BIS certification and Indian infrastructure corridor relationships but lacking nano-coating R&D capabilities. Five-to-ten year viability hinges on regulatory convergence between REACH isocyanate restrictions and emerging Asian green building codes. Watch for inflection signals in China's GB standard tightening velocity and Indian metro rail tender acceleration rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Precursors | Captive propylene oxide supply insulates margin pools from Yangtze River Delta feedstock volatility. |
| Digital Specification Platform Deployment | Direct contractor access compresses German renovation market decision cycles from weeks to days. |
| Embedded Sensor Technology Integration | Moisture-sensor membranes digitize warranty risk allocation for Dutch logistics park facility managers. |
| Water-Based Formulation Transition | Low-VOC acrylic systems capture first-mover advantages under EU Green Deal embodied carbon thresholds. |
| BIS Certification Acceleration | Streamlined Indian bituminous membrane qualification unlocks metro rail infrastructure corridor access. |
Research Methodology
Operator-level perspectives from waterproofing contractors, infrastructure procurement officers, polymer plant managers, and German distributor principals anchored the qualitative base. Secondary validation drew from customs/trade data, SEC 10-K filings of coatings manufacturers, Cefic chemical industry reports, and GB/T standard documentation. Bottom-up volume modeling triangulated against top-down construction spending projections across the analysis window.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions modeled include product chemistry tier, application environment, end-user sophistication level, and technology compliance pathway. CAGRs derived from elasticity-adjusted construction output correlations and specification penetration curves. Forecast inputs incorporated REACH regulatory trajectory assumptions and Indian infrastructure tender pipeline visibility.
Sensitivities concentrate around isocyanate input cost volatility, BIS certification timeline shifts, and Chinese GB standard convergence pace. Forecasts reflect documented assumptions on polymer feedstock availability and regional green building code adoption. Cross-checking against construction materials trade flow data and national infrastructure budget disclosures is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
South Africa Automotive OEM Coatings Market
Coatings
Africa Automotive Refinish Coatings Market
Coatings
Batters and Coatings Market
Coatings
PU Coatings Market
Coatings
2K Coatings Market
Coatings
Marking Coatings Market
Coatings
United Arab Emirates Protective Coatings Market
Coatings
Global UV-Cured Coatings Market
Coatings
Tablet Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
Australia Industrial Coatings Market
Coatings
South Korea Marine Coatings Market
Coatings
Global Water-Based Coatings Market
Coatings
Coating Pre-Treatment Market
Coatings
Global Automotive Specialty Coatings Market
Coatings
Global Fireproofing Coatings for Wood Market