
 Fillers and Coating Market | 2026-2036
Fillers and Coating Market Size, Share, and Industry Trends Forecast 2026-2036
Fillers and Coating Market Analytics
Market Overview
China is fragmenting as domestic producers scale powder coating resin capacity while European incumbents defend automotive OEM contracts. Sherwin-Williams Company leverages its North American architectural distribution network to control shelf space in big-box retail. BASF SE anchors European industrial coatings through backward integration into acrylic monomers and specialty additives. PPG Industries Inc. competes on aerospace and automotive refinish specifications where certification timelines create switching costs.
Technical Definition and Segment Structure
Fillers and coatings comprise particulate additives and surface-applied films that modify substrate properties such as hardness, corrosion resistance, or optical performance, with typical filler loadings ranging from five to sixty percent by weight depending on the polymer matrix and end-use performance target. These materials serve primarily to extend resin systems, reduce unit costs, and impart functional characteristics including UV stability, thermal conductivity, or barrier protection across manufacturing sectors. Mineral fillers dominate volume in construction applications where calcium carbonate and talc provide cost reduction and dimensional stability in PVC profiles and polypropylene building products. Powder coating technology is displacing liquid systems in metal fabrication as EPA and MEE enforcement of VOC limits tightens, while UV-cured coatings command premium positioning in wood furniture and electronics due to instant cure and line-speed advantages.
Regulatory Environment and Outlook
EPA NESHAP standards for surface coating operations and China's MEE VOC emission controls are forcing reformulation across solvent-borne industrial segments, with REACH registration requirements in Europe adding compliance cost layers for imported filler minerals. FDA indirect food contact regulations and BIS certification for construction-grade coatings in India further segment market access by compliance tier rather than pure performance. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized formulation platforms or regional product variants yield lower total compliance burden.
Market Dynamics
Automotive OEMs are expanding specification requirements for lightweight filler systems while China's NMPA tightens VOC emission standards, redirecting formulation priorities across industrial coating segments. This dual pressure from performance demands and environmental compliance is restructuring supplier relationships and R&D allocation.
Growth Catalysts
- EPA NESHAP enforcement:Surface coating operations face stricter emission controls, accelerating waterborne and powder system adoption in metal fabrication across the United States.
- UV-cured coating technology:Instant cure properties command premium positioning in wood furniture and electronics manufacturing, compressing production cycle times.
- Stuttgart supplier corridor:Germany's automotive supplier concentration around Stuttgart and Wolfsburg drives specialized filler specification development for lightweight vehicle applications.
Market Restraints
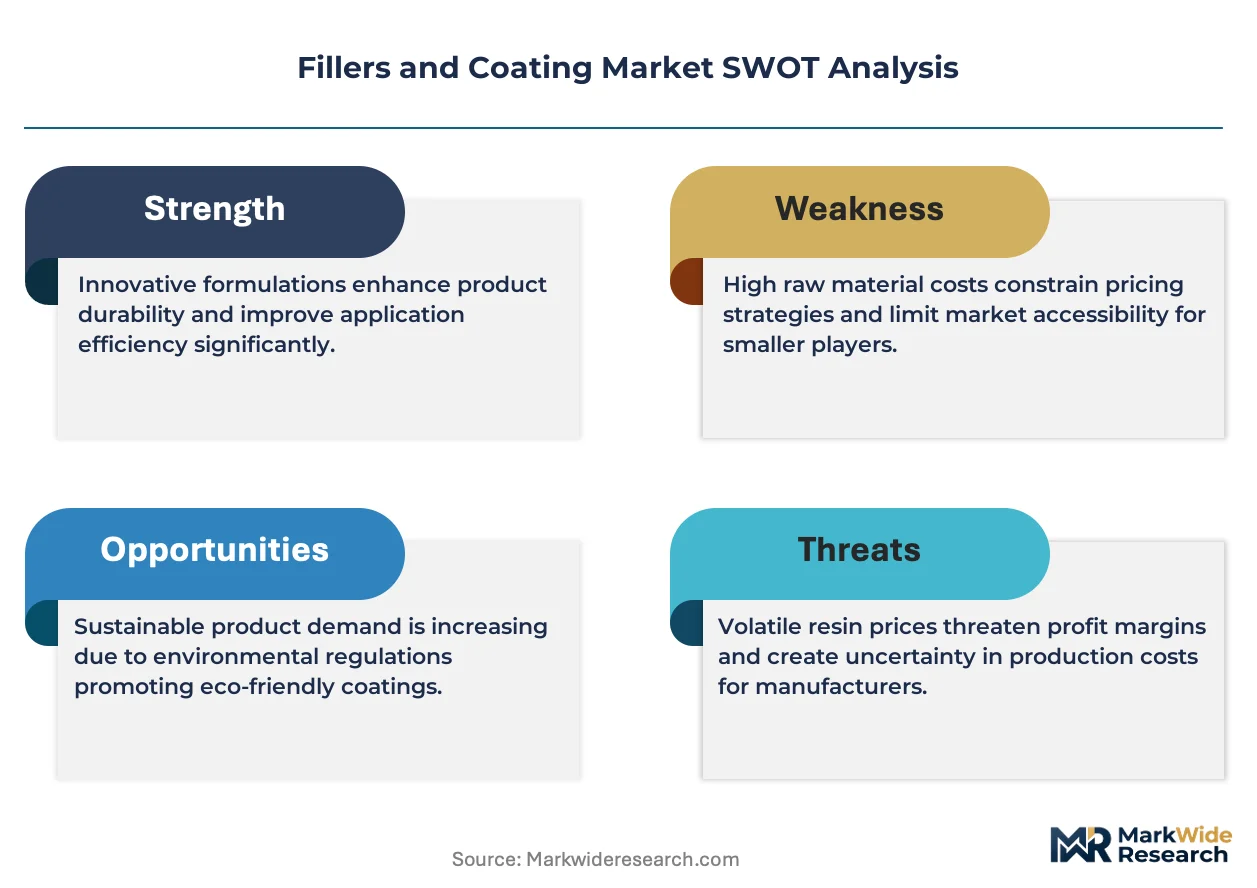
- Titanium dioxide price volatility:White pigment cost swings destabilize coating formulation economics and margin predictability for architectural and industrial producers.
- Chinese mineral filler concentration:Global supply dependence on domestic Chinese calcium carbonate and talc producers creates geopolitical and logistics vulnerability.
- Solvent-borne technical ceiling:High-performance corrosion protection in heavy equipment remains difficult to replicate with current low-VOC alternatives.
Strategic Opportunities
- India construction-grade coatings:BIS certification requirements create tiered market access where compliant international suppliers capture premium infrastructure project specifications.
- Bio-based resin convergence:Integration of agricultural feedstock-derived polymers with conventional mineral fillers opens sustainable product lines for packaging and consumer goods.
- Direct-to-fabricator digital channels:E-procurement platforms bypass traditional distributor markups in North American architectural coatings, capturing margin and customer data.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in hybrid resin systems and filler surface modification commands premium compensation and extends hiring timelines.
- REACH registration burden:European chemical compliance costs for imported specialty minerals force difficult choices between market withdrawal and localized sourcing investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fillers and Coating Market |
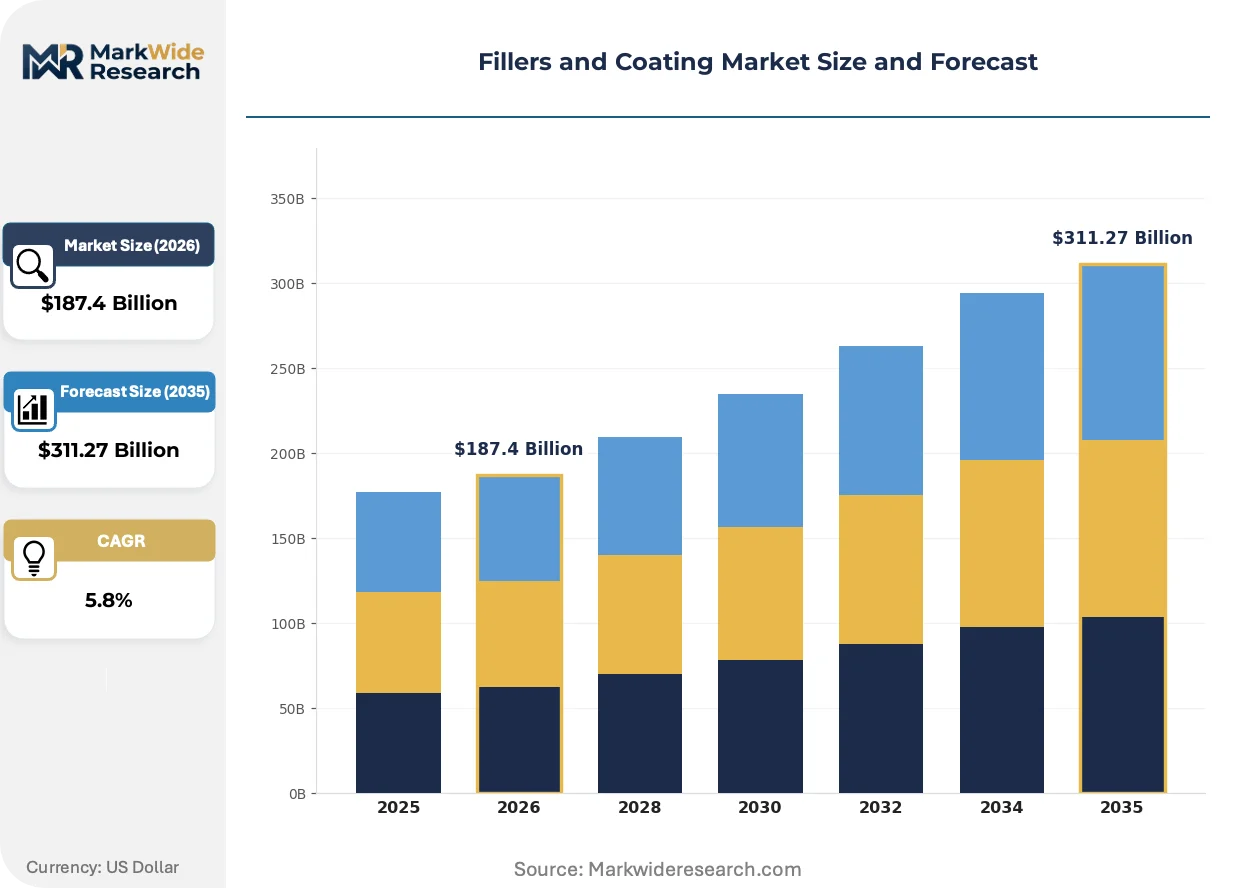
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $311.27 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Mineral Fillers, Polymer Fillers, Vegetable Fillers, Synthetic Fillers Application: Construction, Automotive, Industrial, Packaging Material: Plastic, Rubber, Wood, Metal Technology: Powder Coating, Liquid Coating, Electrostatic Coating, UV-Cured Coating |
| Companies Covered | Sherwin-Williams Company, RPM International Inc., Akzo Nobel N.V., Wacker Chemie AG, The Dow Chemical Company, BASF SE, Axalta Coating Systems LLC, Cabot Corporation, PPG Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fillers and Coating Market Evolving Landscape
Reformulation pressures from VOC restrictions are intersecting with digital manufacturing adoption, creating simultaneous demands for cleaner chemistry and process-integrated coating systems. These forces are compressing development cycles and reshaping how specifications propagate from OEMs to raw material suppliers.
Smart coating formulations incorporating embedded sensors and self-healing microcapsules are digitizing condition monitoring in aerospace and wind turbine applications. Siemens Gamesa and Vestas specify these systems for offshore blade protection where manual inspection access is limited. The technology is digitizing maintenance scheduling and extending service intervals beyond conventional epoxy barrier coatings.
China's MEE VOC emission controls for industrial coatings are forcing solvent-borne system phaseouts in metal furniture and automotive refinish segments. Provincial enforcement variations create compliance complexity for national coating producers operating across multiple manufacturing zones. Formulators respond with hybrid waterborne-UV systems that meet Shanghai and Guangdong limits while maintaining productivity metrics.
Automotive OEMs now bundle coating specifications into platform engineering contracts rather than treating them as commodity procurement. Tier-1 suppliers to Volkswagen and BMW must demonstrate filler traceability and carbon footprint data through blockchain-linked documentation. This behavioral shift concentrates specification influence in Stuttgart and Munich engineering centers while marginalizing regional purchasing autonomy.
Fillers and Coating Market Segmentation
Fillers and coatings serve divergent performance requirements across substrate types and curing technologies. Segmentation reveals where formulation complexity commands premium pricing versus commodity volume plays.
Product Type:
Mature mineral systems dominate tonnage while emerging bio-based alternatives reshape sustainability positioning.
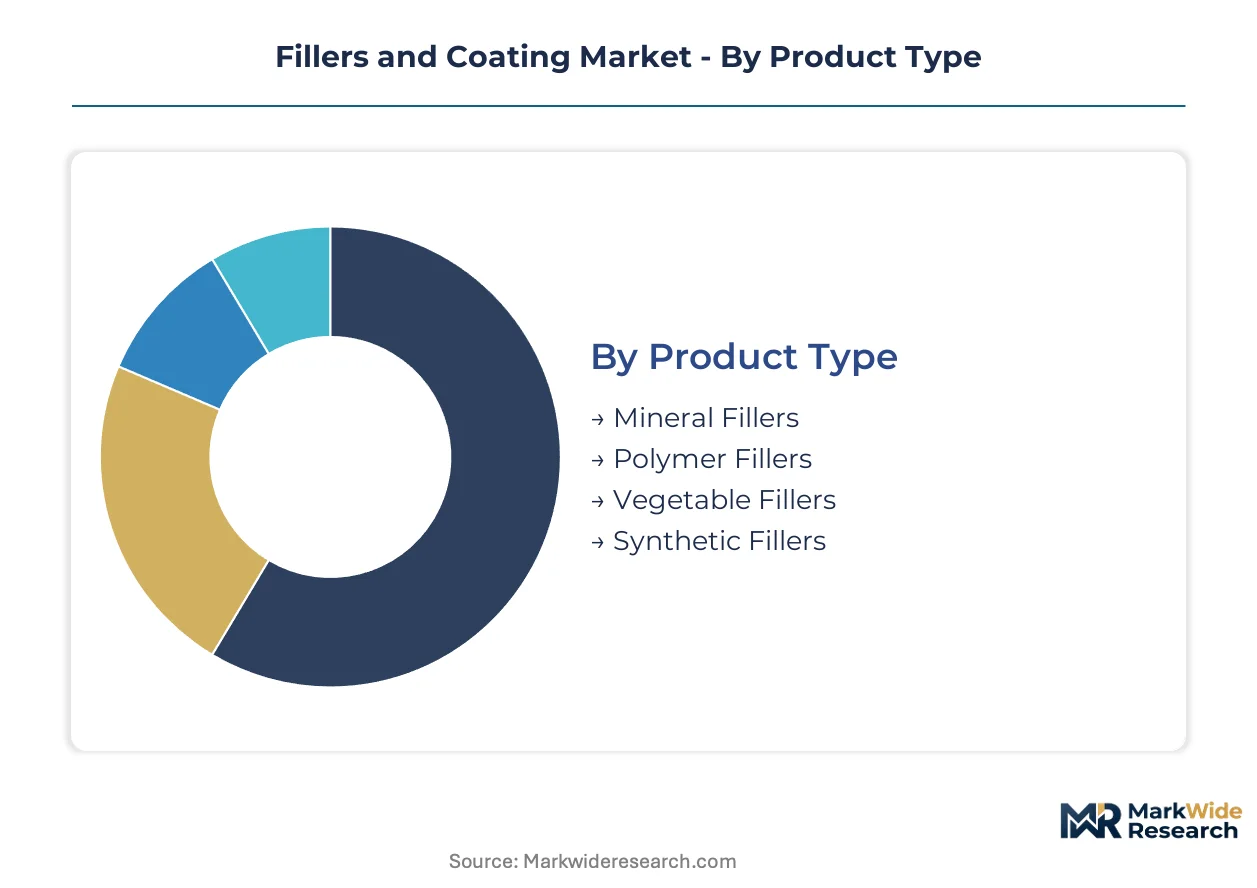
- Mineral Fillers:Calcium carbonate and talc provide cost reduction and dimensional stability in PVC profiles and polypropylene building products. Demand concentrates in China's construction sector where domestic producers scale powder coating resin capacity alongside filler supply.
- Polymer Fillers:Thermoplastic and thermoset resin additives modify rheology and impact resistance in automotive interior components. Stuttgart's automotive supplier corridor drives specialized lightweight filler specification development for electric vehicle weight reduction targets.
- Vegetable Fillers:Agricultural fiber derivatives serve sustainable packaging and consumer goods applications requiring biodegradability certification.
- Synthetic Fillers:Engineered silicas and hollow glass microspheres deliver controlled density and thermal insulation in aerospace composites.
Mineral fillers handle the majority of throughput; polymer fillers are expanding most quickly on share as automotive lightweighting accelerates.
Application:
Cost tier separation distinguishes project-specified industrial systems from retail architectural products.
- Construction:Exterior wall coatings and concrete admixtures require weathering resistance and BIS certification for infrastructure project eligibility in India. Formulators balance titanium dioxide loading against pigment price volatility.
- Automotive:OEM clearcoats and underbody sealants demand blockchain-traceable filler documentation for carbon footprint verification. Volkswagen and BMW platform engineering contracts now bundle coating specifications into centralized procurement.
- Industrial:Heavy equipment corrosion protection maintains solvent-borne technical performance where low-VOC alternatives face formulation ceilings.
- Packaging:Food-contact compliant coatings face FDA indirect additive regulations and migration testing requirements.
Construction absorbs the greatest raw material volume; automotive commands the steepest expansion trajectory on specification value.
Material:
Substrate chemistry dictates filler compatibility and surface preparation protocols.
- Plastic:Polyolefin and engineering thermoplastic substrates require silane-treated fillers for adhesion promotion in automotive interior panels.
- Rubber:Tire and industrial hose compounds utilize carbon black and precipitated silica for reinforcement and abrasion resistance.
- Wood:Furniture and flooring applications favor UV-cured coatings for instant cure and line-speed advantages in high-volume manufacturing.
- Metal:Coil-coated steel and aluminum demand pretreatment-compatible filler systems for appliance and building panel applications.
Plastic substrates carry the heaviest filler loading requirements; wood coating specifications are climbing fastest on UV technology conversion.
Technology:
Regulatory enforcement patterns determine geographic adoption curves for low-emission curing systems.
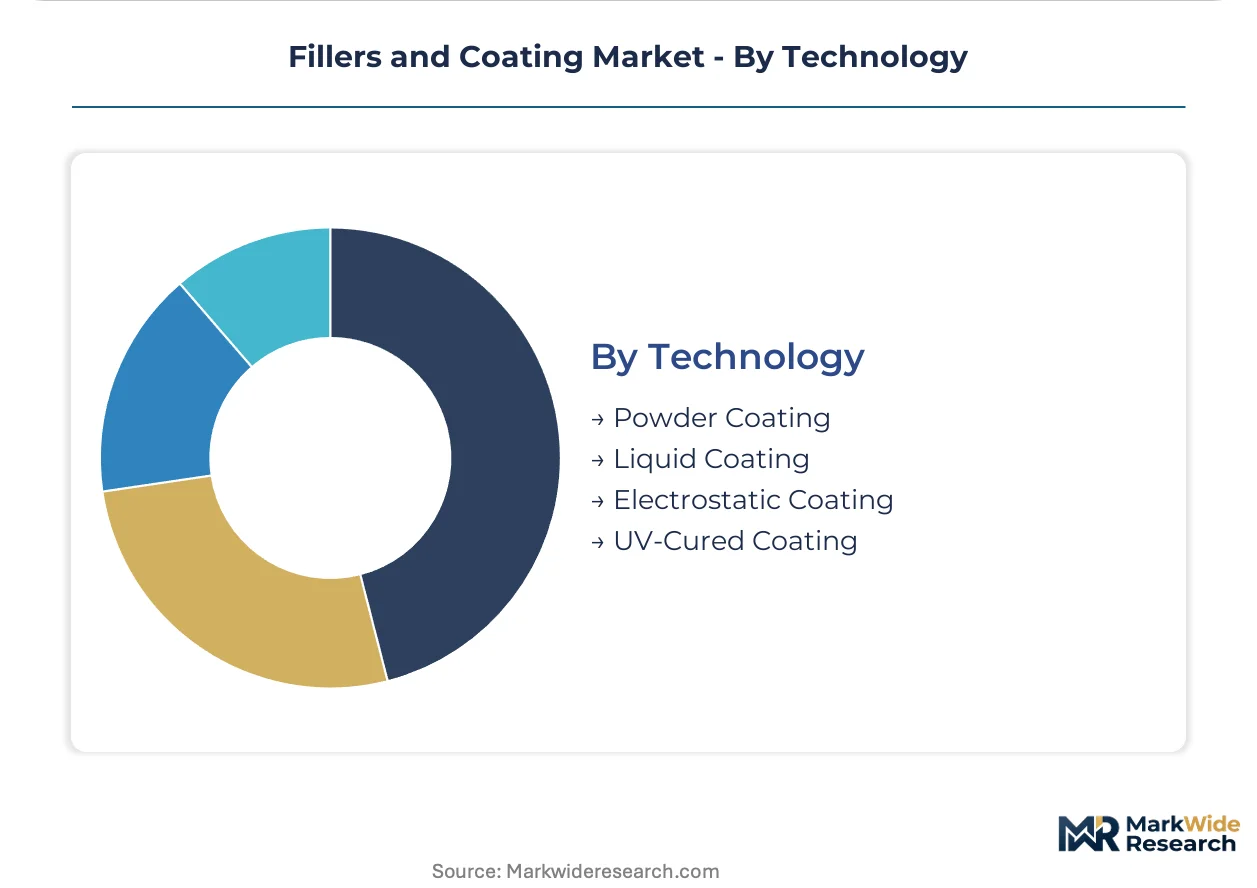
- Powder Coating:Zero-VOC thermoset systems displace liquid alternatives in metal fabrication as EPA NESHAP and China's MEE tighten emission enforcement.
- Liquid Coating:Solvent-borne and waterborne systems retain dominance in touch-up and repair applications requiring ambient cure.
- Electrostatic Coating:Automated spray systems maximize transfer efficiency in automotive and appliance manufacturing lines.
- UV-Cured Coating:Electron beam and ultraviolet initiation deliver instant polymerization for electronics and wood furniture where production velocity determines economics.
Powder coating leads on environmental compliance adoption; UV-cured systems are gaining share fastest in premium electronics and furniture segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China controls the majority of mineral filler supply chains while Germany and the United States concentrate high-value coating formulation expertise. This bifurcation shapes procurement strategies across automotive, construction, and industrial end-uses.
China
Domestic producers scale powder coating resin capacity alongside calcium carbonate and talc mining operations. The MEE enforces VOC emission controls that force solvent-borne system phaseouts in Shanghai and Guangdong manufacturing zones. Provincial enforcement variations create compliance complexity for national coating producers operating across multiple industrial clusters.
Germany
Automotive OEMs in Stuttgart and Wolfsburg drive specialized lightweight filler specification development for electric vehicle weight reduction targets. REACH registration requirements add compliance cost layers for imported specialty minerals. The supplier corridor concentrates blockchain-traceable filler documentation capabilities for carbon footprint verification.
United States
EPA NESHAP enforcement accelerates waterborne and powder system adoption in metal fabrication across the Midwest and Southeast. Sherwin-Williams leverages its architectural distribution network to control shelf space in big-box retail. The Pacific Northwest and Texas industrial corridors absorb reformulated low-VOC coating volumes.
India
BIS certification for construction-grade coatings segments market access by compliance tier rather than pure performance. Infrastructure project eligibility requires weathering resistance validation and formal certification documentation. Maharashtra and Gujarat host the majority of domestic coating formulation capacity serving government contract specifications.
Japan
METI industrial standards govern filler compatibility protocols for automotive interior panels and electronics manufacturing. UV-cured coating specifications climb fastest in premium electronics segments where production velocity determines economics. The Kanto and Kansai industrial belts concentrate precision coating application equipment and technical service capabilities.
Fillers and Coating Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in mineral supply and additive synthesis. The market structures around consolidated formulation leaders with backward integration into acrylic monomers and fragmented mineral filler producers competing on logistics proximity. Three archetypes dominate: diversified chemical conglomerates with captive resin production, coating specialists with specification-locked OEM relationships, and regional mineral processors with cost-driven construction market positions. Competitive moves concentrate on M&A for geographic coverage and capacity expansion in powder coating resin to capture EPA and MEE-driven substitution demand.
Among diversified chemical conglomerates, BASF SE and The Dow Chemical Company exemplify platform integrators with upstream control over acrylic monomers and specialty additives. PPG Industries Inc. occupies a position within the specification-locked tier where aerospace and automotive refinish certification timelines create switching costs. These three anchors demonstrate how competitive positioning stratifies between supply chain control and customer relationship durability.
| Leading Market Players |
|---|
| Sherwin-Williams Company |
| RPM International Inc. |
| Akzo Nobel N.V. |
| Wacker Chemie AG |
| The Dow Chemical Company |
| BASF SE |
| Axalta Coating Systems LLC |
| Cabot Corporation |
| PPG Industries Inc. |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor transmits freight cost volatility directly into mineral filler landed costs, amplifying price spreads between regional construction-grade suppliers and automotive OEM specification holders while compressing margins for mid-tier industrial coating formulators caught between input inflation and contract pricing rigidities.
Pricing Analysis
EPA NESHAP and China's MEE VOC emission controls dictate the pricing tier structure across industrial coating segments. Three-tier pricing structure across premium, standard, and economy levels separates blockchain-traceable automotive OEM specifications from BIS-certified infrastructure coatings and commodity architectural products. Cost compression in standard-tier waterborne systems is intensifying because titanium dioxide price volatility destabilizes formulation economics. Construction contractors exhibit highest price sensitivity, while aerospace and automotive OEMs accept premium positioning for certification-locked supply security.
Supply Chain Analysis
Specialty chemical contract manufacturers in Germany and the United States hold concentrated capacity for automotive-grade coating formulation, while Chinese domestic producers scale powder coating resin operations alongside captive calcium carbonate mining. Raw material flows draw from Vietnamese talc processing, Saudi petrochemical feedstocks, and Brazilian precipitated silica operations. Single-source vulnerability concentrates in high-purity titanium dioxide pigment supply. Distribution runs through regional distributor networks for architectural coatings and direct mill-to-plant logistics for automotive OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from bio-based resin systems converging with conventional mineral fillers, requiring defensive positioning around specification-locked OEM relationships and carbon footprint verification capabilities.
For Market Incumbents: Harden specification control through blockchain-traceable filler documentation for Volkswagen and BMW platform engineering contracts. Deepen backward integration into acrylic monomer production to insulate margin from petrochemical feedstock volatility. Prioritize REACH registration completion for imported specialty minerals to defend European automotive supplier corridor positioning against compliance-driven market withdrawal. For New Entrants and Emerging Players: Establish a beachhead in India's BIS-certified construction-grade coatings segment where infrastructure project eligibility requirements create tiered market access barriers. Target Maharashtra and Gujarat domestic formulation capacity gaps with compliant import substitution. Lead with weathering resistance validation services bundled with coating supply to differentiate from commodity importers. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates seeking to divest non-core coating additive portfolios. Five-to-ten year viability favors specialists with captive powder coating resin capacity positioned for EPA and MEE-driven substitution demand. Monitor provincial enforcement variations across China's industrial manufacturing zones as inflection indicator for national coating producer consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Acrylic Monomers | BASF SE anchors European industrial coatings through captive specialty additive supply security. |
| Powder Coating Resin Capacity Expansion | Domestic Chinese producers capture EPA and MEE-driven substitution demand from solvent-borne systems. |
| Blockchain-Traceable Filler Documentation | Automotive OEMs now bundle coating specifications into centralized platform engineering contracts. |
| BIS Certification Investment | Compliant international suppliers capture premium infrastructure project specifications in India. |
| UV-Cured Technology Platform Development | Instant cure properties command premium positioning in Siemens Gamesa offshore wind blade protection. |
Research Methodology
A spread of perspectives from coating formulation chemists, automotive OEM procurement directors, mineral filler plant managers, and industrial distributor channel heads converged on the working assumptions driving this analysis. Primary fieldwork combined with secondary validation from EPA NESHAP enforcement records, China MEE provincial emission disclosures, REACH registration databases, and customs trade data for calcium carbonate and talc flows. Bottom-up segment sizing triangulated against top-down chemical industry production estimates.
Demand-supply balance modeling across the analysis window incorporated filler loading requirements by polymer matrix, curing technology adoption curves, and regional regulatory enforcement intensity. Segmentation dimensions included product type, application end-use, substrate material compatibility, and curing technology. CAGRs derived from volume trajectory analysis calibrated to OEM specification change cycles and infrastructure investment patterns. Forecast inputs integrated titanium dioxide price correlation effects and powder coating resin capacity buildout timelines.
Sensitivities concentrate around MEE enforcement uniformity across Chinese provinces, REACH registration cost pass-through viability, and automotive lightweighting target acceleration. Forecasts reflect documented assumptions on substitution elasticity between solvent-borne and waterborne systems. Quarterly review of provincial emission disclosure trends, filler import customs volumes, and OEM platform engineering contract award patterns is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coating Binders Market
Coatings
Electron Beam Curable Coating Market
Coatings
North America Thermal Spray Market
Coatings
Asia-Pacific Marine Coatings Market
Coatings
Non-Stick Coatings Market
Coatings
Global Waterborne Coatings Market
Coatings
Waterborne Automobile Coating Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Marine Nanocoating Market
Coatings
North America Anti-Friction Coatings Market
Coatings
UV Coatings Market
Coatings
Fluid Bed and Coating System Market
Coatings
Solvent Borne Coatings Market
Coatings
Anti-Corrosion Nanocoatings Market
Coatings
Acrylic Protective Coating Market
Coatings
Carpet Back Coatings Market