
 Ultrasound-Guided Breast Biopsy Market | 2026-2036
Ultrasound-Guided Breast Biopsy Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasound-Guided Breast Biopsy Market Analytics
A widening capital-intensity gap between integrated imaging-device makers and standalone disposable suppliers is reorganizing competitive tiers in the ultrasound-guided breast biopsy space. Hologic, Inc. leverages its vertically controlled mammography-to-biopsy workflow to dominate installed-base conversions. Danaher Corporation anchors its position through sustained R&D intensity across precision instrument platforms. Siemens Healthineers competes by extending its imaging hardware leadership into proprietary biopsy guidance software.
Ultrasound-guided breast biopsy denotes a percutaneous tissue-sampling technique employing real-time sonographic visualization to localize lesions and direct needle placement, typically utilizing 14-gauge core needles or vacuum-assisted devices operating at 10–12 MHz transducer frequencies for sub-millimetric spatial resolution. The procedure serves primarily to obtain histopathological diagnosis of suspicious breast masses while minimizing surgical intervention and patient morbidity. Vacuum-assisted biopsy systems command the dominant margin pool within procedure-type segmentation due to larger tissue yields and reduced sampling error rates. Needle assemblies represent the highest-volume product category, though imaging systems capture disproportionate value per unit through bundled service contracts. Outpatient delivery mode is expanding fastest as ambulatory surgical centers deploy dedicated breast biopsy suites to capture same-day discharge reimbursement.
FDA 510(k) clearance pathways and EPA sterilization standards govern device commercialization and reprocessing protocols, respectively, shaping product development timelines and manufacturing location decisions for market participants. The EU MDR and ISO 13485 quality management requirements impose additional conformity burdens on companies seeking dual-territory market access, favoring organizations with established regulatory affairs infrastructure. Stakeholders must monitor evolving CMS reimbursement determinations for image-guided biopsy procedures and assess whether outpatient site-of-service differentials will shift capital deployment toward ambulatory settings or reinforce hospital-based infrastructure investments.
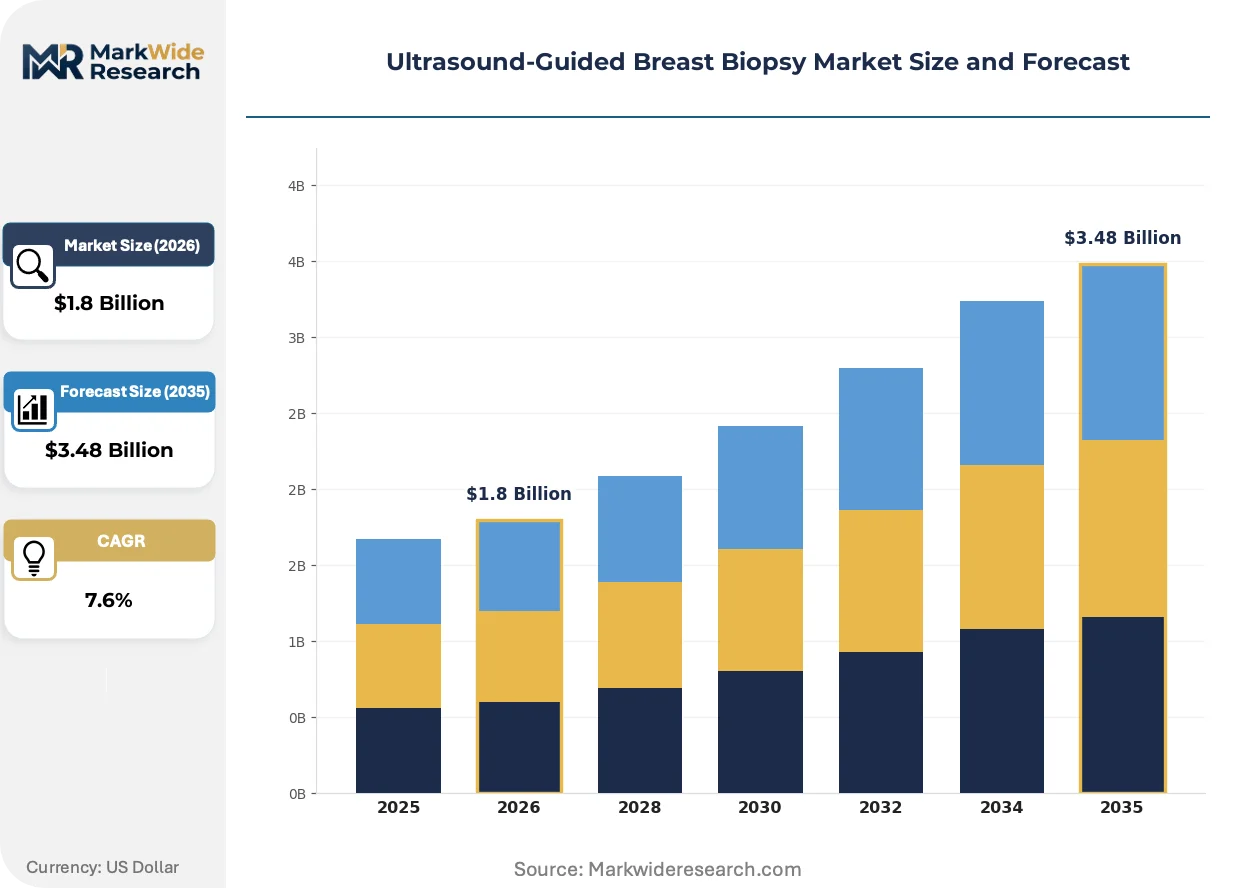
Market Dynamics
Hospital-based breast imaging departments are consolidating purchasing power around integrated workflow platforms, forcing disposable suppliers to choose between capitulation on pricing or exit from core needle assembly contracts.
Growth Catalysts
- FDA 510(k) pathway streamlining:The FDA's updated guidance on image-guided biopsy device classifications compresses premarket review timelines for manufacturers with predicate device portfolios, accelerating new entrant commercialization.
- Ambulatory surgical center expansion:CMS reimbursement clarity for same-day discharge procedures drives capital deployment toward dedicated breast biopsy suites in outpatient settings across the United States.
- Vacuum-assisted tissue yield superiority:Core needle sampling error rates of 2-4% versus sub-1% for vacuum-assisted systems concentrate hospital procurement preference toward higher-yield devices despite unit cost premiums.
Market Restraints
- Sterilization reagent cost volatility:EPA-compliant ethylene oxide and hydrogen peroxide plasma sterilization chemistries face supply intermittency from concentrated specialty chemical production in the US Gulf Coast corridor.
- Transducer frequency standardization gaps:Non-uniform 10-12 MHz probe calibration protocols across imaging system OEMs fragment interoperability and inflate service contract complexity for multi-vendor installed bases.
- Surgical excision residual preference:Radiologists in certain academic medical centers retain diagnostic confidence in open surgical biopsy for lesions with indeterminate imaging characteristics, constraining percutaneous procedure volume ceilings.
Strategic Opportunities
- AI-augmented lesion localization:Machine learning algorithms trained on annotated sonographic datasets enable novice operators to achieve expert-equivalent needle placement accuracy, expanding addressable physician pools beyond fellowship-trained breast imagers.
- Rural hospital outreach programs:Mobile breast imaging units equipped with portable ultrasound systems and disposable biopsy kits penetrate geographic service deserts where permanent mammography infrastructure remains uneconomical.
- EU MDR notified body capacity expansion:The European Medicines Agency's acceleration of conformity assessment timelines for Class IIa medical devices reduces dual-territory market entry friction for manufacturers with ISO 13485 certification.
Industry Challenges
- Cross-modality credentialing complexity:Technologists certified in mammography-guided stereotactic biopsy require supplemental ultrasound physics training and supervised case volumes to achieve independent practice privileges, extending workforce scaling timelines.
- Legacy PACS integration friction:Proprietary biopsy guidance software from imaging system OEMs demands custom DICOM middleware development for seamless connectivity with third-party radiology information systems, inflating IT implementation budgets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasound-Guided Breast Biopsy Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Procedure Type: Core Needle Biopsy, Vacuum-Assisted Biopsy, Fine Needle Aspiration, Image-Guided Biopsy End User: Hospitals, Diagnostic Centers, Breast Clinics, Research Institutions Product Type: Needle Assemblies, Biopsy Devices, Imaging Systems, Accessories Delivery Mode: Inpatient, Outpatient, Telehealth, Mobile Services |
| Companies Covered | Hologic, Inc., Danaher Corporation, Becton, Dickinson and Company, Argon Medical Devices, Merit Medical Systems, GE HealthCare, Cook Medical, Siemens Healthineers, Fujifilm Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasound-Guided Breast Biopsy Market Evolving Landscape
Real-time three-dimensional volumetric imaging and automated needle trajectory planning are compressing the skill gradient required for diagnostic accuracy, while regulatory harmonization efforts reshape competitive entry barriers across major markets.
Automated core needle biopsy devices with integrated post-fire specimen verification sensors are supplanting manual needle positioning techniques in high-volume breast imaging centers. Hospital radiology departments in the United States adopt these systems at replacement-cycle velocities of 18-24 months for legacy device fleets. The technology is supplanting operator-dependent variability in tissue core adequacy, reducing nondiagnostic sampling rates and associated repeat procedure costs.
The EU Medical Device Regulation's enhanced clinical evidence requirements for Class IIa devices impose substantial post-market surveillance infrastructure investments on manufacturers seeking CE marking renewal. European notified bodies now mandate periodic safety update reports and proactive implant card traceability for biopsy needle assemblies. Vacuum-assisted biopsy system suppliers with established quality management systems capture disproportionate certification velocity versus mid-tier disposable-only competitors.
After-sales service unbundling from capital equipment purchases accelerates as ambulatory surgical centers negotiate à la carte preventive maintenance contracts separate from imaging system acquisition financing. Independent service organizations with ISO 13485-certified repair capabilities displace OEM captive service networks in secondary and tertiary US markets. This procurement pattern shift concentrates most visibly in the Southeastern United States, where ASC joint ventures pursue aggressive operating margin targets through vendor diversification.
Ultrasound-Guided Breast Biopsy Market Segmentation
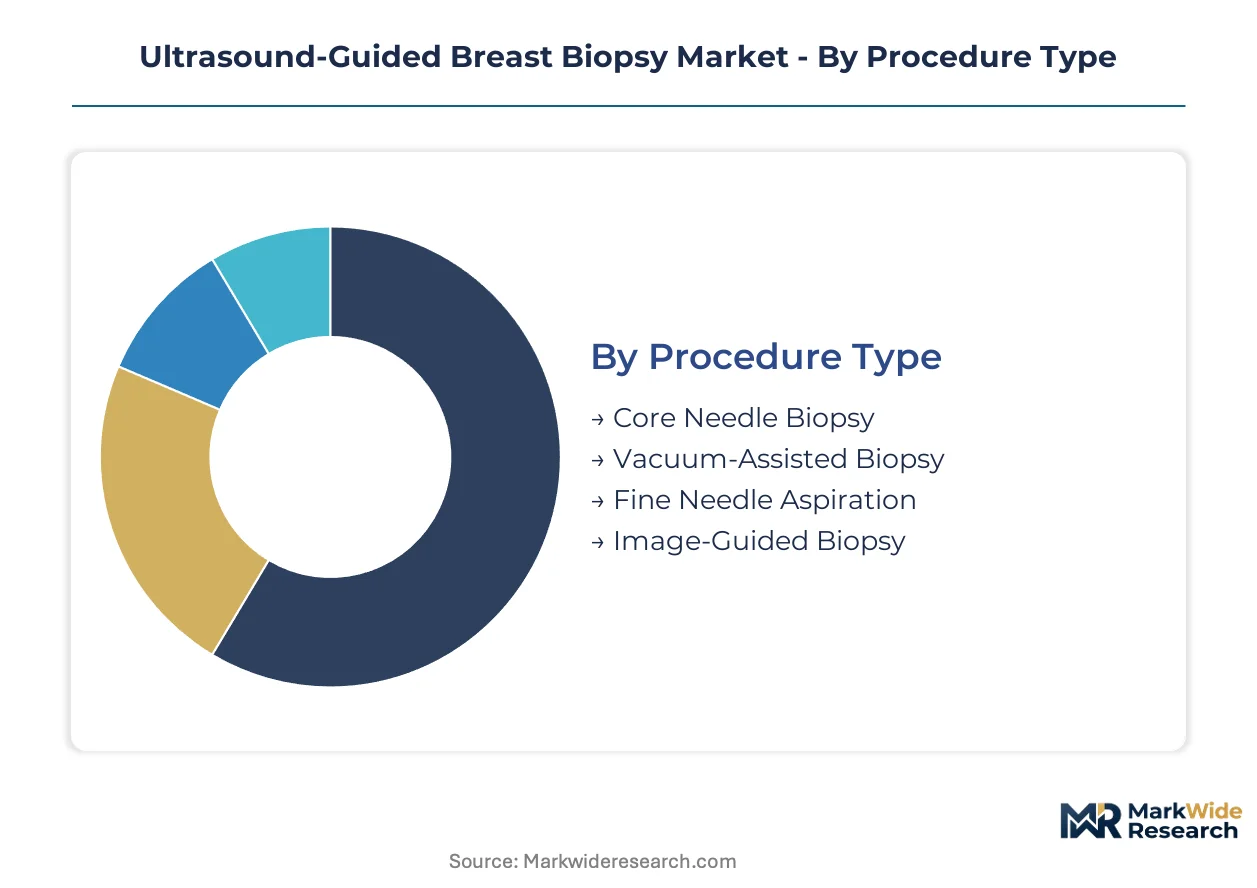
Segmentation in the ultrasound-guided breast biopsy market reveals how regulatory pathways, reimbursement structures, and clinical workflow requirements reshape procurement patterns across procedure types and care settings. Understanding these divisions illuminates where capital concentrates and where disposable volumes accumulate.
Procedure Type:
FDA 510(k) clearance complexity varies substantially across sampling techniques, with vacuum-assisted systems requiring more extensive predicate comparisons than manual core needle alternatives due to integrated suction mechanics and larger tissue acquisition volumes.
- Core Needle Biopsy:Manual spring-loaded devices fire 14-gauge cutting needles through spring mechanisms to extract cylindrical tissue cores. Hospital radiology departments in the United States favor these systems for cost-sensitive screening programs where procedure volume exceeds capital replacement budgets.
- Vacuum-Assisted Biopsy:Continuous suction draws tissue through an aperture into a sampling chamber, enabling multiple specimens without needle withdrawal. Academic medical centers prioritize these systems for lesions requiring extensive histological sampling, accepting higher per-procedure costs for reduced nondiagnostic rates.
- Fine Needle Aspiration:22-25 gauge needles extract cellular material for cytological examination rather than histological architecture. Rapid on-site evaluation protocols in breast clinics drive residual demand despite declining reimbursement relative to core techniques.
- Image-Guided Biopsy:Integrated software overlays needle trajectory onto real-time ultrasound visualization. Research institutions adopt these systems for protocol standardization across multi-site clinical trials.
Established volume favors core needle biopsy; emerging adoption favors vacuum-assisted biopsy.
End User:
Capital intensity requirements and staffing credentialing standards fragment purchasing authority across institutional types, with hospitals consolidating procurement through integrated delivery networks while independent breast clinics negotiate device contracts directly.
- Hospitals:Multi-specialty institutions with dedicated breast imaging departments command economies of scale in disposable contracting. CMS inpatient prospective payment systems influence capital equipment replacement cycles through bundled reimbursement calculations.
- Diagnostic Centers:Freestanding imaging facilities prioritize throughput-optimized workflows and same-day result delivery. These centers concentrate in suburban corridors surrounding metropolitan hospital systems.
- Breast Clinics:Specialized facilities combine screening, diagnostic imaging, and biopsy services under single-roof coordination. Patient navigation programs at these clinics reduce time-to-diagnosis intervals.
- Research Institutions:Academic medical centers with NCI-designated cancer centers maintain separate procurement tracks for investigational device protocols. Tissue banking requirements drive preference for vacuum-assisted systems with standardized core dimensions.
Capital deployment concentrates in hospitals; patient volume growth climbs the fastest in diagnostic centers.
Product Type:
Margin structures invert across the product hierarchy, with needle assemblies generating recurring revenue streams and imaging systems capturing disproportionate value through bundled service contracts and software licensing.
- Needle Assemblies:Single-use sterile components including coaxial introducers, biopsy needles, and specimen collection chambers. Ambulatory surgical centers in the Southeastern United States negotiate multi-year supply agreements to lock pricing against ethylene oxide sterilization cost volatility.
- Biopsy Devices:Handheld drivers and vacuum-assisted consoles constitute the capital equipment layer. Replacement demand accelerates as 18-24 month product cycles displace legacy manual systems.
- Imaging Systems:High-frequency linear array transducers operating at 10-12 MHz with integrated biopsy guidance software. Service contract unbundling trends pressure OEM pricing on preventive maintenance packages.
- Accessories:Sterile drapes, local anesthetic delivery systems, and post-biopsy compression devices. These products face commoditization pressure from group purchasing organization tender processes.
Recurring revenue concentrates in needle assemblies; margin expansion favors imaging systems.
Delivery Mode:
Site-of-service reimbursement differentials between inpatient and outpatient settings reshape capital location decisions, with CMS payment clarity for same-day discharge procedures accelerating ambulatory infrastructure deployment.
- Inpatient:Hospital admission required for complex cases with comorbidity management needs or anticipated bleeding risks. This mode retains preference for lesions near vascular structures.
- Outpatient:Ambulatory surgical centers and hospital-based outpatient departments dominate procedure volume. Dedicated breast biopsy suites with rapid recovery protocols capture same-day discharge reimbursement.
- Telehealth:Remote pre-procedure consultation and post-biopsy result delivery expand access in rural service areas. Licensing reciprocity agreements between states enable cross-border radiologist coverage.
- Mobile Services:Portable ultrasound systems mounted in customized vehicles penetrate geographic deserts lacking permanent mammography infrastructure. These units require EPA-compliant sterilization workflows adapted to field conditions.
Procedure volume concentrates in outpatient delivery; geographic penetration expands most quickly through mobile services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between mature screening economies and emerging diagnostic markets, with the United States deploying vacuum-assisted systems at triple the per-capita rate of European hospital systems while Asian markets concentrate procurement in portable core needle platforms for rural outreach.
United States
FDA 510(k) pathway streamlining accelerates device commercialization timelines for predicate-rich portfolios, while CMS reimbursement clarity for same-day discharge procedures drives capital deployment toward ambulatory surgical centers in Texas and Florida. The Southeastern United States exhibits the fastest outpatient suite expansion as ASC joint ventures pursue aggressive operating margin targets.
Germany
EU MDR conformity assessment timelines compress market entry friction for ISO 13485-certified manufacturers, with notified body capacity expansion favoring established quality management systems. The Baden-Württemberg medical technology cluster concentrates vacuum-assisted biopsy system R&D, leveraging precision instrument heritage from adjacent industrial automation supply chains.
Japan
PMDA regulatory harmonization with FDA predicate device frameworks reduces dual-territory filing burdens for manufacturers seeking Asian market access. The Kanto region around Tokyo anchors diagnostic imaging device procurement, where hospital consolidation into regional medical care zones standardizes purchasing specifications across prefectural networks.
China
NMPA Class II medical device registration reforms compress technical review timelines for domestically manufactured biopsy needles, while provincial health commissions in Jiangsu and Guangdong pilot centralized procurement for high-volume disposable categories. The Yangtze River Delta concentrates imaging system assembly operations serving both domestic demand and Southeast Asian export markets.
India
CDSCO medical device rules implementation creates registration clarity for imported biopsy guidance systems, though state-level tender fragmentation persists across Maharashtra and Karnataka hospital procurement. The Delhi-NCR corridor attracts mobile breast imaging service operators targeting tier-two city diagnostic gaps where permanent mammography infrastructure remains uneconomical.
Ultrasound-Guided Breast Biopsy Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-platform manufacturers controlling imaging-to-biopsy workflows while disposable-focused suppliers compete on sterilization reliability and needle gauge consistency. Strategic archetypes include vertically integrated imaging-device makers, precision instrument conglomerates with diversified life science portfolios, and standalone disposable specialists with concentrated manufacturing footprints. Competitive moves center on service contract unbundling negotiations with ambulatory centers and regulatory affairs infrastructure investments for dual-territory FDA-MDR market access.
Within the integrated platform tier, Hologic, Inc. and Danaher Corporation occupy positions exemplifying contrasting scale strategies, with the former anchoring mammography-to-biopsy workflow control and the latter representing precision instrument R&D intensity across diversified diagnostic platforms. Siemens Healthineers sits within the imaging hardware extension archetype, competing through proprietary biopsy guidance software layered onto established ultrasound installed bases.
| Leading Market Players |
|---|
| Hologic, Inc. |
| Danaher Corporation |
| Becton, Dickinson and Company |
| Argon Medical Devices |
| Merit Medical Systems |
| GE HealthCare |
| Cook Medical |
| Siemens Healthineers |
| Fujifilm Healthcare |
| Others |
Value Network & Pricing Analysis
FDA 510(k) clearance requirements and ISO 13485 certification standards simultaneously gate supplier qualification and stratify price tiers across the ultrasound-guided breast biopsy market. Manufacturers bearing these credentials command contract premiums from hospital procurement committees while uncertified competitors face exclusion from integrated delivery network vendor panels entirely.
Pricing Analysis
Long-term supply agreements dominate hospital and ambulatory surgical center procurement, with multi-year disposable needle contracts locking unit pricing against ethylene oxide sterilization cost volatility. Three-tier pricing structure across premium, standard, and economy levels separates vacuum-assisted biopsy systems with integrated imaging software from manual core needle alternatives and commodity accessories. Cost compression in needle assemblies intensifies as group purchasing organizations consolidate volumes across regional health systems. Diagnostic centers exhibit highest price sensitivity due to thin per-procedure margins, while academic medical centers prioritize tissue yield metrics over unit cost.
Supply Chain Analysis
Ethylene oxide sterilization capacity concentrated along the US Gulf Coast corridor underwrites downstream device availability for domestic manufacturers. Precision instrument components draw from Germany, Japan, and the United States, with linear array transducer crystals sourcing from specialized semiconductor foundries in Taiwan and South Korea. Single-source vulnerability in specialty chemical sterilization reagents threatens production continuity during hurricane season disruptions. Distribution runs through medical device distributors with ISO 13485-certified warehousing, feeding directly into hospital materials management systems and ambulatory center consignment programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat environment where regulatory entrenchment protects incumbent positions. FDA 510(k) predicate device portfolios and established notified body relationships create switching costs that compound over successive product generations.
For Market Incumbents: Fortify installed-base control through backward integration into disposable needle manufacturing, capturing margin pools currently accruing to standalone assembly suppliers. Deepen software companion development for proprietary biopsy guidance algorithms, raising interoperability barriers against third-party device competitors. Prioritize service contract unbundling negotiations with Southeastern United States ambulatory surgical centers to defend pricing power against independent service organization encroachment. For New Entrants and Emerging Players: Lead with AI-augmented lesion localization platforms targeting rural hospital outreach programs, where mobile imaging unit deployment creates white-space access beyond established mammography-to-biopsy workflows. Concentrate initial commercialization on diagnostic centers in suburban corridors surrounding metropolitan hospital systems, leveraging faster procurement cycles and lower credentialing barriers than academic medical center penetration. Pursue regulatory harmonization strategies spanning FDA and EU MDR pathways to accelerate dual-territory market entry velocity against single-jurisdiction competitors. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified precision instrument conglomerates seeking to divest non-core biopsy device portfolios amid portfolio rationalization pressures. Long-term viability hinges on software-integrated platform control rather than disposable commodity exposure, favoring acquisition targets with proprietary guidance algorithm development capabilities. Monitor CMS reimbursement determinations for outpatient site-of-service differentials as the critical inflection signal for capital deployment timing between ambulatory infrastructure and hospital-based equipment replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Pathway Streamlining | Accelerated predicate device clearances compress commercialization timelines for manufacturers with established regulatory affairs infrastructure. |
| CE Marking Pathway Investment | EU MDR notified body capacity expansion favors ISO 13485-certified quality management systems in conformity assessment velocity. |
| Hospital System Partnership | Integrated delivery network contracting consolidates procurement authority around full-platform vendors controlling imaging-to-biopsy workflows. |
| Software Companion Development | Proprietary biopsy guidance algorithms raise switching costs and capture recurring revenue through annual licensing arrangements. |
| Reimbursement Strategy | CMS site-of-service payment clarity for same-day discharge procedures directs capital deployment toward ambulatory surgical center suites. |
Research Methodology
Operator-level perspectives from breast imaging radiologists, hospital purchasing committee chairs, ambulatory surgical center administrators, and biomedical equipment technicians anchored the qualitative base for this analysis. These primary insights combined with secondary validation from FDA 510(k) device clearances, CMS Medicare reimbursement determinations, hospital procurement databases, and GPO contract disclosures. Bottom-up procedure volume modeling and top-down market sizing triangulation ensured cross-verification across independent analytical paths.
Sensitivity analysis frameworks tested forecast robustness across alternative reimbursement scenarios and regulatory timeline assumptions over the projection horizon. Segmentation dimensions modeled span procedure type, end user institution category, product tier, and delivery mode, with additional granularity on vacuum-assisted versus core needle technology splits. CAGRs derived from fitted growth curves applied to base-year estimates, incorporating procedure volume elasticity to screening program expansion and capital replacement cycle dynamics as industry-specific forecast inputs.
Underlying assumptions cover reimbursement stability, sterilization reagent supply continuity, and regulatory pathway efficiency, with deviation risk concentrated in EPA compliance changes and notified body capacity constraints. Practitioners should keep alternative scenarios live as CMS site-of-service payment differentials and EU MDR implementation timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Gram Staining System Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Polygraph Instrument (Lie Detector) Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Electroporation Instruments Market
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Pathology Instruments Market