
 Global Chemiluminescence Immunoassay (CLIA) Analyzers Market | 2026-2036
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market Foresight
High-sensitivity detection thresholds is collapsing the acceptable performance floor for new analyzer installations. Abbott Laboratories leverages its installed base of diagnostic instruments to sustain recurring reagent revenue streams. DiaSorin S.p.A. anchors its competitive stance through specialized infectious disease and autoimmune assay menus. Siemens Healthineers dominates premium hospital laboratory contracts with integrated workflow automation.
Chemiluminescence immunoassay analyzers are automated diagnostic instruments that detect analyte concentrations through light-emitting chemical reactions, typically achieving detection limits in the picogram-per-milliliter range for hormones, tumor markers, and infectious agents. Their primary commercial purpose centers on high-throughput quantitative screening in clinical laboratories where speed and reproducibility outperform manual enzyme-linked immunosorbent assay methods. Fully automated analyzers command the largest installed base due to labor cost reduction and error-rate compression in high-volume settings. Electrochemiluminescence technology captures expanding share in oncology screening applications where multiplexing capability and broad dynamic range reduce repeat testing rates.
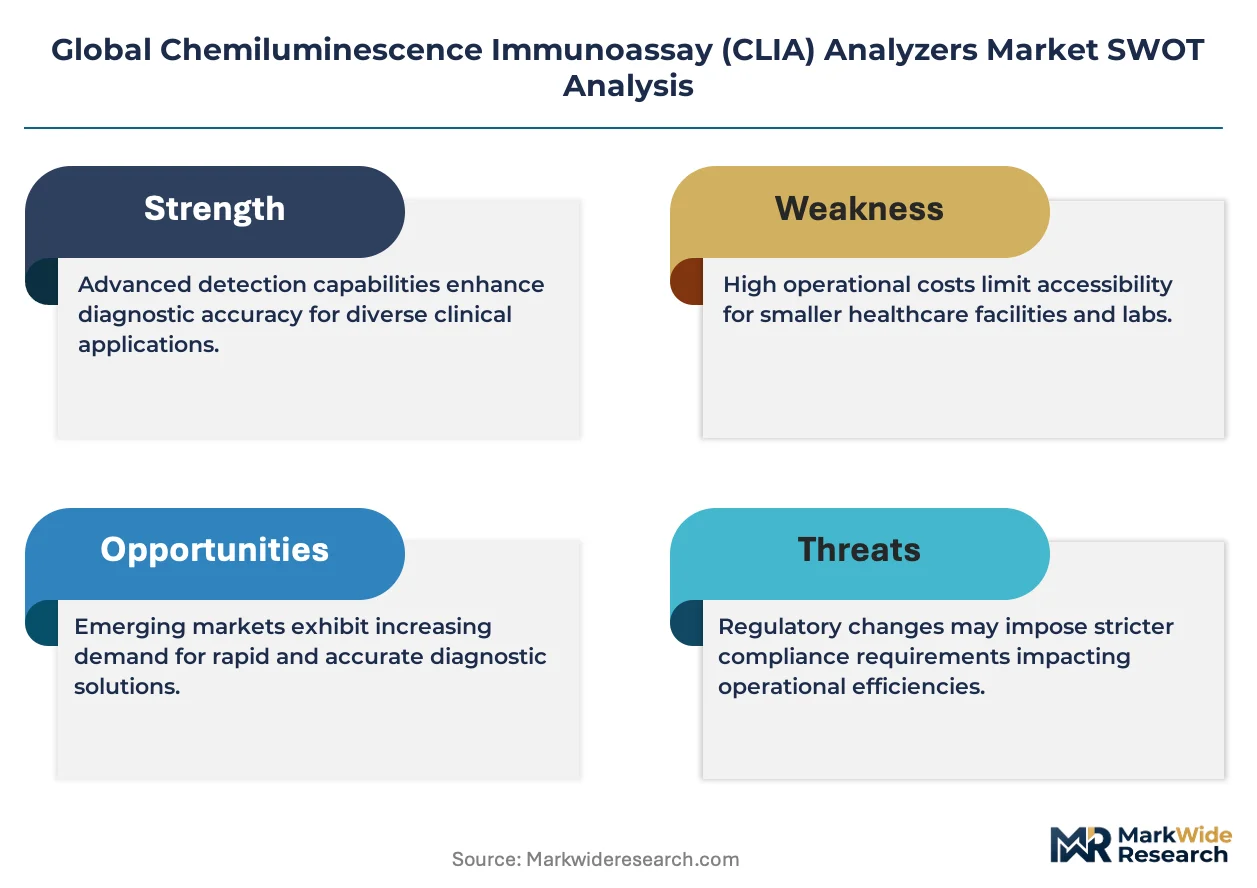
FDA premarket notification requirements and EPA waste-handling standards for chemical reagents shape analyzer design specifications and service infrastructure investments in the United States. EMA's In Vitro Diagnostic Regulation compliance deadlines in Europe are forcing manufacturers to rebalance certification resources across product portfolios. China's NMPA streamlined review pathways for domestically manufactured Class III diagnostics are accelerating local production scale-up. Stakeholders must monitor how divergent regulatory timelines across FDA, EMA, and NMPA jurisdictions reshape competitive access and service model economics.
Market Dynamics
Electrochemiluminescence detection architectures are compressing the performance gap between mid-tier and premium analyzer platforms, forcing incumbent manufacturers to recalibrate service bundling strategies and reagent lock-in mechanisms.
Growth Catalysts
- FDA premarket notification pathways:Streamlined Class II device clearances for automated immunoassay systems are accelerating replacement cycles in hospital laboratories.
- Infectious disease surveillance expansion:National screening programs for hepatitis and HIV in China are driving fleet expansion at provincial CDC laboratories.
- Multiplexing chemistry advances:Simultaneous detection of multiple analytes from single sample volumes is reducing per-test costs in high-throughput oncology panels.
Market Restraints
- Reagent supply concentration:Proprietary chemiluminescent substrate formulations remain captive to original equipment manufacturers, limiting third-party alternatives.
- EMA In Vitro Diagnostic Regulation compliance:Extended technical documentation requirements are stretching certification timelines for European market entry.
- Manual ELISA substitution in low-volume settings:Smaller clinical laboratories continue deploying enzyme-linked immunosorbent assays for test volumes below automation break-even thresholds.
Strategic Opportunities
- Point-of-care CLIA miniaturization:Benchtop analyzers with reduced reagent consumption are opening emergency departments and satellite clinics previously excluded from automated testing.
- China NMPA domestic manufacturer incentives:Streamlined review pathways for locally manufactured Class III diagnostics are accelerating indigenous production scale-up.
- Artificial intelligence-assisted result interpretation:Machine learning algorithms for pattern recognition in complex autoimmune panels are differentiating next-generation platforms.
Industry Challenges
- Field service engineer scarcity:Specialized electrochemistry and optical calibration expertise remains concentrated among veteran technicians approaching retirement.
- Legacy LIS integration complexity:Hospital information system interoperability requirements are extending installation timelines and inflating deployment costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Chemiluminescence Immunoassay (CLIA) Analyzers Market |
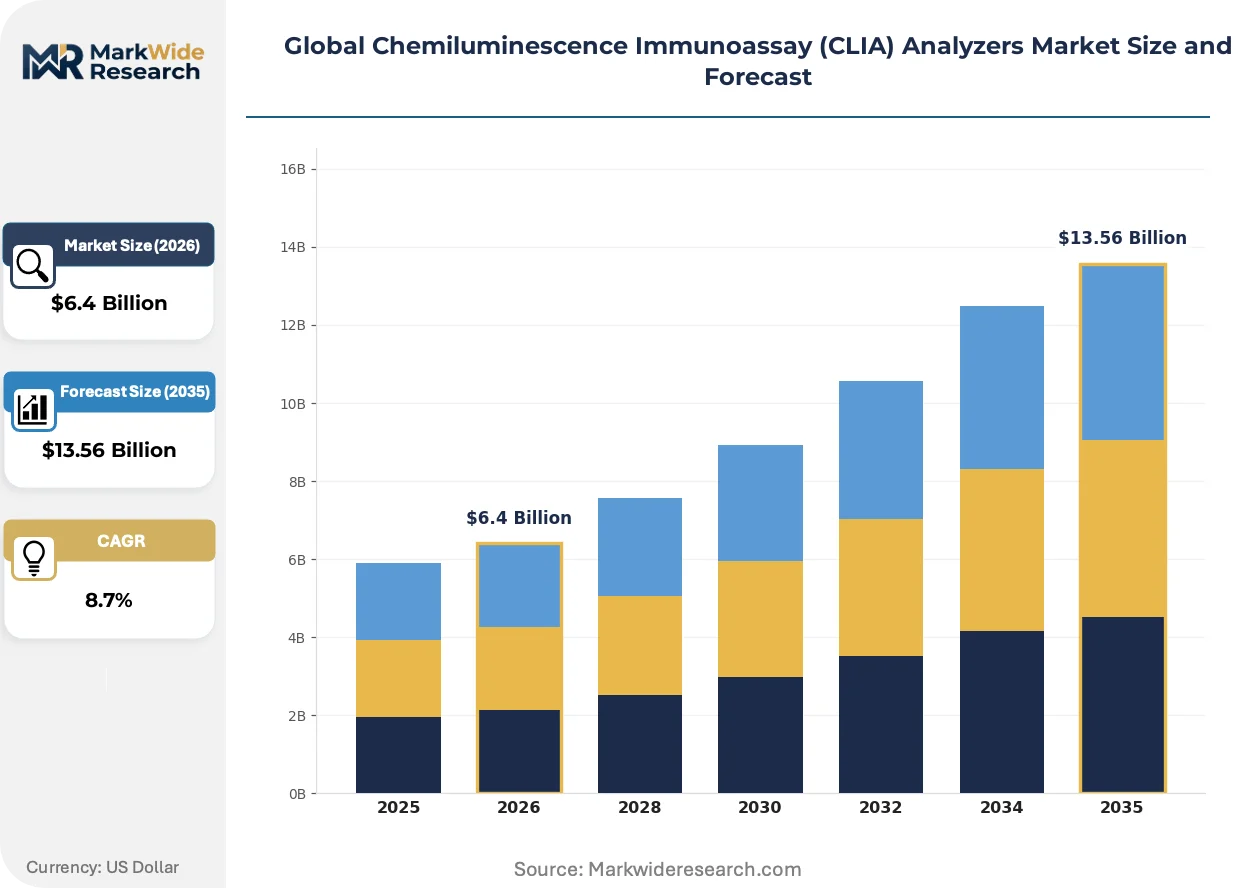
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $13.56 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Mode Analyzers, Multi-Mode Analyzers, Fully Automated Analyzers, Semi-Automated Analyzers Technology: Direct Chemiluminescence, Indirect Chemiluminescence, Enhanced Chemiluminescence, Electrochemiluminescence Application: Endocrinology Testing, Infectious Disease Detection, Oncology Screening, Cardiology Biomarker Analysis, Allergology Assessment End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Academic Institutions |
| Companies Covered | DiaSorin S.p.A., Shenzhen Mindray Bio-Medical Electronics Co., Ltd., F. Hoffmann-La Roche AG, Sysmex Corporation, Thermo Fisher Scientific Inc., Danaher Corporation, Abbott Laboratories, Shenzhen New Industries Biomedical Engineering Co., Ltd. (SNIBE), Siemens Healthineers AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market Shifts & Advancements
Analyzer architectures are fragmenting into modular, software-defined platforms that decouple hardware throughput from assay menu depth, enabling subscription-based reagent access models.
Magnetic microparticle separation technology is decomposing the throughput limitations of traditional solid-phase chemiluminescence systems. Reference laboratories in Germany and Japan are adopting these platforms for STAT testing workflows. The shift is decomposing the historical trade-off between speed and sensitivity that constrained mid-tier analyzer positioning.
REACH chemical substance restrictions on europium and ruthenium complexes are forcing reformulation of proprietary detection reagents. Manufacturers are accelerating rare-earth substitution programs to maintain supply continuity. European IVD producers face compressed margins as alternative chemistries require validation against established clinical cutoffs.
Hospital procurement consortia are consolidating analyzer purchasing decisions at regional health system levels rather than individual laboratory autonomy. Independent sales representatives and distributor networks are losing access to decision-makers. This concentration is most visible in United States integrated delivery networks and Chinese provincial hospital alliances.
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market Segmentation
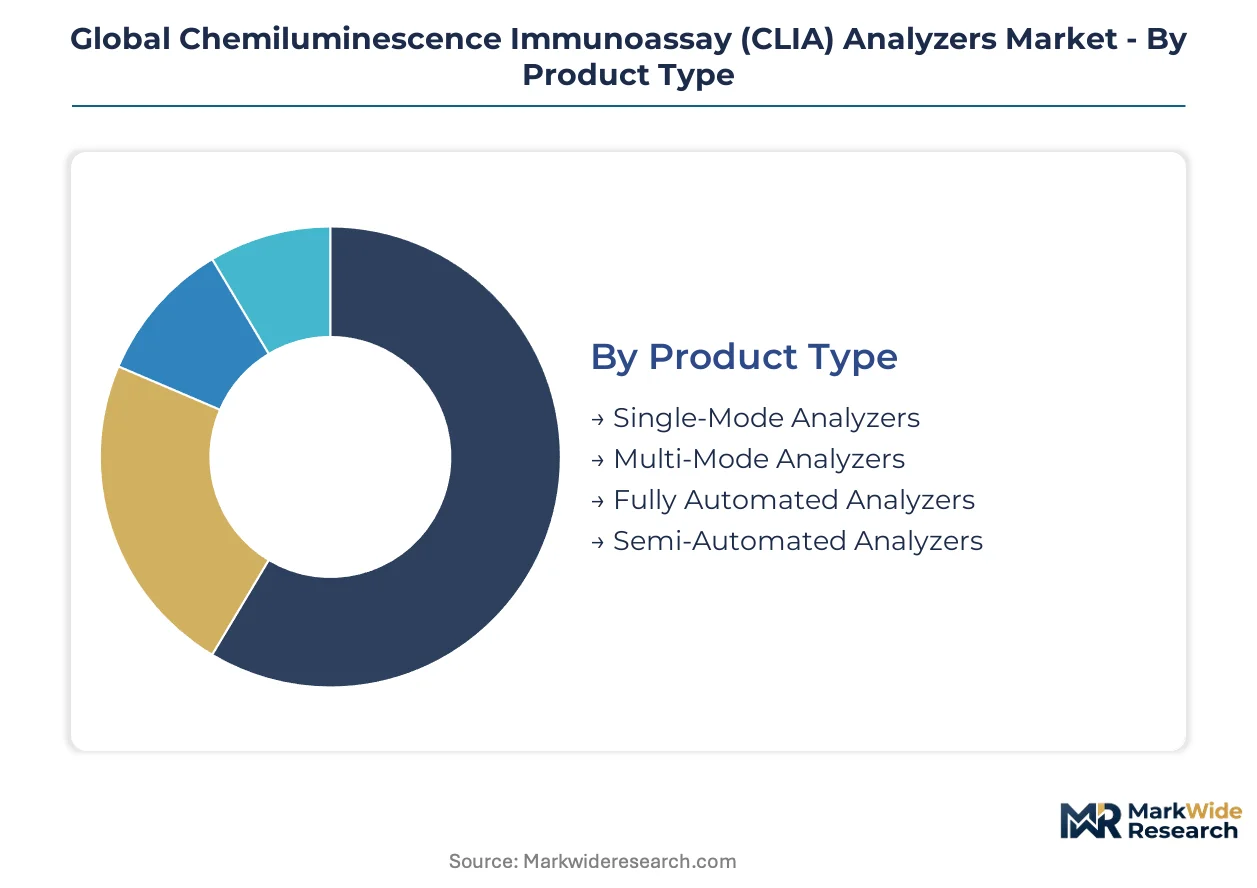
Segmentation reveals how CLIA analyzer purchasing splits between high-volume reference laboratories and decentralized testing sites. Channel economics differ sharply: hospital networks favor capital-intensive platforms with reagent lock-in, while research buyers prioritize assay flexibility over throughput.
Product Type:
Channel mix varies by automation level—fully automated systems flow through direct manufacturer sales with service contracts, while semi-automated units distribute through regional laboratory supply distributors.
- Fully Automated Analyzers:These systems integrate sample handling, reagent dispensing, and optical detection in enclosed architectures achieving walkaway operation. Demand concentrates in German and Japanese reference laboratories where labor costs and error-rate sensitivity justify premium capital outlay. Siemens Healthineers and Abbott Laboratories dominate this channel with bundled reagent supply agreements.
- Semi-Automated Analyzers:Units requiring manual sample preparation and intermittent operator intervention occupy the mid-tier. Chinese provincial hospital alliances are expanding fleets here, balancing throughput needs against constrained capital budgets under procurement reform mandates.
- Single-Mode Analyzers:Dedicated instruments optimized for specific chemiluminescence reaction formats serve niche infectious disease panels in blood bank screening networks.
- Multi-Mode Analyzers:Modular platforms accommodating varied detection chemistries attract academic medical centers with diverse assay development requirements.
Fully automated analyzers dominate installed base. Semi-automated systems are where expansion concentrates in cost-sensitive procurement environments.
Technology:
Cost tiers separate legacy direct chemiluminescence from electrochemiluminescence platforms commanding 40-60% price premiums for enhanced sensitivity specifications.
- Electrochemiluminescence:Voltage-triggered light emission from ruthenium-labeled antibodies achieves sub-picogram detection limits with exceptional dynamic range. Oncology screening applications in United States integrated delivery networks drive adoption, where multiplexing capability reduces repeat biopsy rates. Roche Diagnostics anchors this segment with proprietary ECL chemistry patents.
- Enhanced Chemiluminescence:Enzyme-amplified signal generation using luminol derivatives balances sensitivity against reagent stability. Indian diagnostic chains deploy these platforms for thyroid and fertility panels where test volume supports medium-throughput automation.
- Direct Chemiluminescence:Acridinium ester labels enable rapid flash kinetics suited to STAT testing workflows in emergency department satellite laboratories.
- Indirect Chemiluminescence:Secondary antibody signal amplification retains cost advantage in research settings where absolute quantification precision is secondary.
Electrochemiluminescence commands premium pricing tiers. Enhanced chemiluminescence is climbing the fastest in emerging market hospital procurement.
Application:
Volume concentration follows disease burden patterns—oncology and infectious disease testing generate recurring revenue streams that amortize analyzer placement costs.
- Infectious Disease Detection:Hepatitis B surface antigen and HIV antibody quantification require high-sensitivity cutoffs for blood safety screening. China's CDC network expansion at provincial level is reshaping demand geography, with domestic manufacturers capturing share through NMPA streamlined review pathways.
- Oncology Screening:Tumor marker panels for PSA, CA-125, and AFP monitoring demand broad dynamic range to track therapeutic response. German oncology networks are adopting electrochemiluminescence platforms for multiplexed monitoring of metastatic progression.
- Endocrinology Testing:Thyroid stimulating hormone and cortisol assays represent high-frequency routine chemistry in hospital core laboratories.
- Cardiology Biomarker Analysis:Troponin I and NT-proBNP testing for acute coronary syndrome evaluation prioritizes rapid turnaround in emergency department settings.
- Allergology Assessment:Specific IgE quantification serves specialized immunology reference centers with lower throughput requirements.
Infectious disease detection anchors reagent consumption volumes. Oncology screening is where technology upgrading concentrates.
End User:
Customer type determines procurement authority—diagnostic laboratories make centralized fleet decisions while academic buyers prioritize grant-funded flexibility over total cost optimization.
- Diagnostic Laboratories:Commercial and hospital-affiliated testing facilities process thousands of samples daily, demanding continuous loading capacity and minimal downtime. United States integrated delivery networks are consolidating purchasing decisions at regional health system level, eliminating independent distributor access.
- Blood Banks:Transfusion safety screening mandates drive zero-defect performance requirements with full audit trail documentation for FDA compliance.
- Research Institutes:Assay development flexibility and open reagent protocols outweigh throughput specifications in biotechnology and pharmaceutical research settings.
- Academic Institutions:Training hospitals and university medical centers balance educational access against clinical service obligations with mixed procurement criteria.
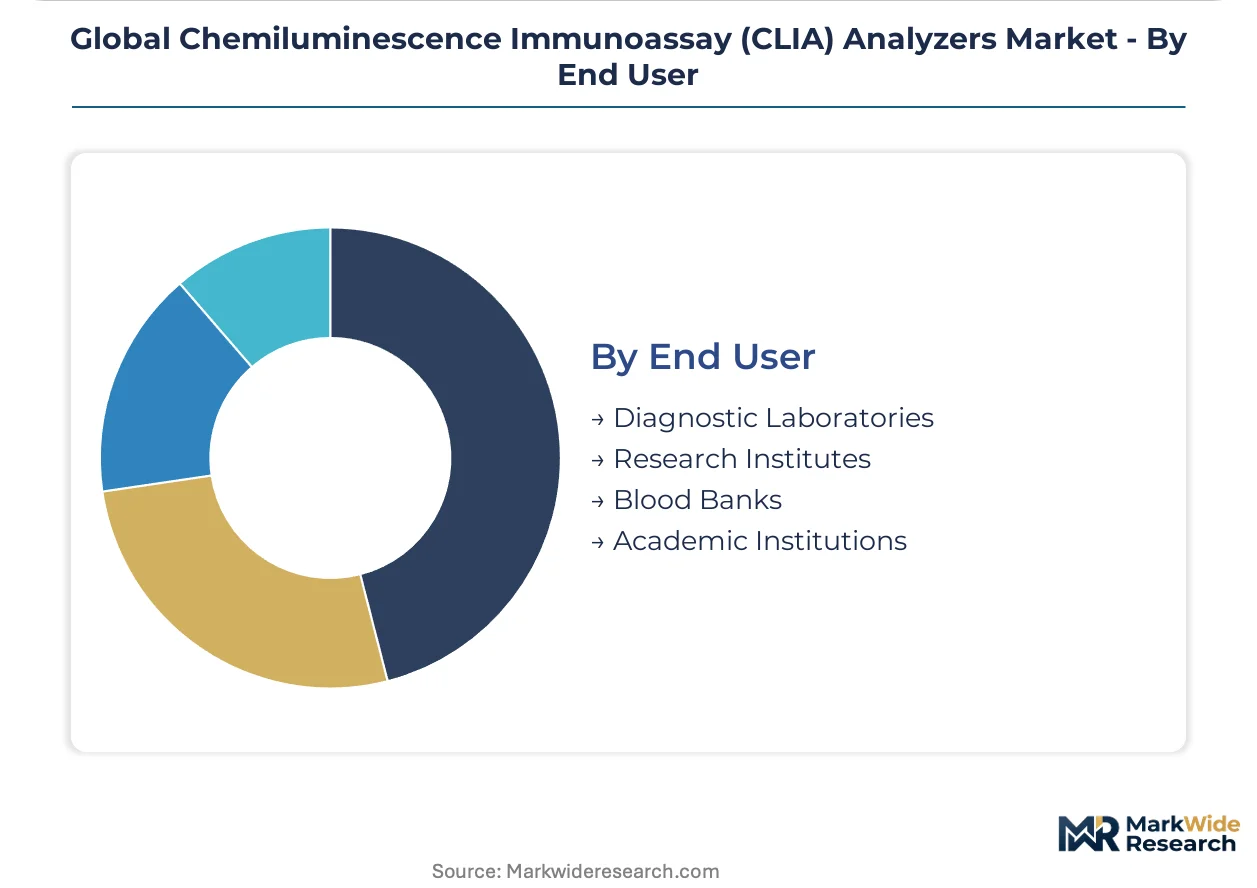
Diagnostic laboratories dominate installed base. Blood banks are where regulatory compliance requirements concentrate procurement specification authority.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German manufacturers export precision diagnostic platforms to hospital networks across the United States and China. This trade corridor shapes regional demand patterns for high-throughput CLIA instrumentation. Domestic regulatory environments in buyer markets then determine installation timelines and service infrastructure requirements.
United States
Integrated delivery networks in Texas and Florida are consolidating laboratory purchasing decisions at regional health system levels. FDA premarket notification pathways for Class II automated immunoassay systems are compressing replacement cycles for aging analyzer fleets. Boston-area academic medical centers are adopting electrochemiluminescence platforms for oncology screening workflows.
Germany
Reference laboratories in Bavaria and North Rhine-Westphalia are deploying magnetic microparticle separation technology for STAT testing workflows. EMA In Vitro Diagnostic Regulation compliance deadlines are stretching certification timelines for new platform introductions. The Munich-Stuttgart corridor hosts concentrated technical service capabilities for electrochemistry calibration.
China
Provincial CDC networks are expanding hepatitis and HIV screening programs under national surveillance mandates. NMPA streamlined review pathways for domestically manufactured Class III diagnostics are accelerating local production scale-up. Shenzhen-based manufacturers are capturing share in hospital procurement reforms across Guangdong and Jiangsu provinces.
Japan
Tokyo-Osaka metropolitan laboratories are prioritizing multiplexing capability for tumor marker panels in oncology monitoring. METI standards for in vitro diagnostic performance are shaping analyzer specification requirements for domestic market entry. Nagoya-area diagnostic chains are integrating AI-assisted result interpretation for complex autoimmune panels.
India
Diagnostic chains in Maharashtra and Karnataka are deploying enhanced chemiluminescence platforms for thyroid and fertility panels. CDSCO regulatory pathways for imported automated immunoassay systems are extending product registration timelines. Mumbai and Bangalore are emerging as service hubs for mid-tier analyzer maintenance and reagent logistics.
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity and geographic coverage dimensions. The vendor base separates into three tiers: multinational conglomerates with integrated workflow automation, mid-scale regional manufacturers with cost-optimized platforms, and niche specialists with targeted assay menus. Strategic moves concentrate on reagent lock-in mechanisms and service bundling rather than hardware differentiation alone. Consolidation pressures are mounting as procurement authority shifts to hospital consortia.
Within the multinational tier, Abbott Laboratories and Siemens Healthineers occupy positions defined by installed base leverage and premium contract capture. DiaSorin S.p.A. exemplifies the specialist archetype with concentrated expertise in infectious disease and autoimmune diagnostics. Shenzhen Mindray Bio-Medical Electronics Co., Ltd. represents the regional scale manufacturer segment with domestic production advantages in China. These three patterns—global installed base leverage, specialized assay depth, and regional cost optimization—structure competitive positioning across procurement environments.
| Leading Market Players |
|---|
| DiaSorin S.p.A. |
| Shenzhen Mindray Bio-Medical Electronics Co., Ltd. |
| F. Hoffmann-La Roche AG |
| Sysmex Corporation |
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| Abbott Laboratories |
| Shenzhen New Industries Biomedical Engineering Co., Ltd. (SNIBE) |
| Siemens Healthineers AG |
| Others |
Supply & Pricing Matrix
Analyzer manufacturing scale at Shenzhen and Stuttgart facilities compresses unit economics for magnetic microparticle separation modules, concentrating pricing power among producers operating above three-million-test annual throughput thresholds while elevating cost floors for mid-tier entrants lacking comparable utilization rates.
Pricing Analysis
Electrochemiluminescence platforms command 40-60% premiums over enhanced chemiluminescence systems, with direct chemiluminescence units occupying entry positions. Pricing stratifies across premium, standard, and economy tiers based on multiplexing capability and FDA clearance tier. Cost compression in the mid-tier is intensifying because Chinese domestic manufacturers are leveraging NMPA streamlined pathways to undercut legacy import pricing. Research institutes demonstrate highest price sensitivity due to grant-funded capital constraints, while blood banks prioritize zero-defect performance over acquisition cost.
Supply Chain Analysis
Rare-earth element refining capacity in China, Germany, and the United States underwrites global access to europium and ruthenium complexes essential for proprietary detection chemistries. Manufacturing draws from specialized optical component foundries in Japan, precision fluidics suppliers in Switzerland, and magnetic bead substrate producers in South Korea. Single-source vulnerability concentrates around electrochemiluminescence reagent formulations protected by Roche Diagnostics patent estates. Distribution runs through direct manufacturer sales for fully automated systems and regional laboratory supply distributors for semi-automated configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement decentralization across China's provincial hospital alliances fragments purchasing authority, creating specialist entry points for assay-focused competitors against integrated workflow giants.
For Market Incumbents: Secure reagent lock-in through exclusive supply agreements with integrated delivery networks in Texas and Florida before NMPA-certified domestic alternatives achieve performance parity. Expand field service engineer training pipelines to address electrochemistry calibration expertise approaching retirement cliff. Vertical integration into magnetic microparticle substrate production reduces exposure to South Korean supply concentration.
For New Entrants and Emerging Players: Lead with point-of-care CLIA miniaturization targeting emergency departments and satellite clinics excluded from high-throughput automation economics. India's diagnostic chains in Maharashtra and Karnataka offer penetrable white space for enhanced chemiluminescence platforms at thyroid and fertility panel price points. Pursue CDSCO regulatory partnerships to compress registration timelines against entrenched import competition.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialists with concentrated infectious disease and autoimmune assay depth over diversified conglomerates facing margin compression from electrochemiluminescence patent expirations. Target acquisition candidates with established NMPA Class III clearances and provincial CDC relationships in Guangdong and Jiangsu. Monitor EMA IVDR compliance cost burdens as consolidation catalyst for European mid-scale manufacturers lacking certification bandwidth.
| Strategic Initiative | Industry Significance |
|---|---|
| Reagent Subscription Model Deployment | Converts capital equipment sales into recurring revenue streams with hospital laboratory customers. |
| AI-Assisted Result Interpretation Integration | Differentiates next-generation platforms in complex autoimmune panel applications at Nagoya diagnostic chains. |
| Domestic Manufacturing Scale-Up in China | Captures procurement reform mandates through NMPA streamlined review pathways for Class III diagnostics. |
| Magnetic Microparticle Technology Licensing | Decomposes throughput limitations for STAT testing workflows in German reference laboratories. |
| Field Service Engineer Certification Pipeline | Addresses electrochemistry calibration expertise scarcity concentrated among veteran technicians. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of FDA 510(k) clearances, EMA IVDR technical documentation, NMPA registration databases, and hospital procurement records. Interviews with biomedical engineers, GPO contracts managers, clinical laboratory directors, and diagnostic manufacturer product managers informed demand-side validation. Bottom-up instrument placement modeling triangulates against top-down reagent consumption estimates across the analysis window.
Segmentation dimensions modeled include automation level, detection technology, application category, and end-user type throughout the forecast period. CAGRs derive from installed base replacement cycle analysis, reagent pull-through assumptions, and regional procurement reform impacts. Forecast inputs incorporate EMA IVDR compliance cost trajectories and NMPA domestic manufacturer incentive program uptake rates.
The analysis sits within stated boundaries; outcomes outside sustained FDA premarket notification streamlining, EMA IVDR deadline extensions, or NMPA policy continuity would require recalibration. Forecasts reflect documented assumptions regarding infectious disease surveillance program expansion and oncology screening protocol adoption. Practitioners should keep alternative scenarios live as rare-earth element supply restrictions and field service engineer labor market conditions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Global Cell Surface Markers Detection Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market