
 Global Radioimmunoassay Market | 2026-2036
Global Radioimmunoassay Market Size, Share, and Industry Trends Forecast 2026-2036
Global Radioimmunoassay Market Foresight
The EU In Vitro Diagnostic Regulation is expanding compliance burdens for reagent manufacturers entering European markets. PerkinElmer leverages its established CE-IVD portfolio to navigate these requirements with minimal disruption. DiaSorin S.p.A. anchors its competitive position through in-house isotope sourcing and assay development capabilities. DRG International differentiates by specializing in niche endocrine panels that larger competitors often overlook.
Radioimmunoassay quantifies antigen concentrations through competitive binding between labeled and unlabeled ligands for antibody sites, typically employing iodine-125 or tritium isotopes with detection thresholds reaching picogram-per-milliliter sensitivity. The technique serves as a gold-standard reference method for endocrine biomarker validation in clinical and research settings. Reagents and kits command the largest value share due to recurring consumption patterns, while analyzers face longer replacement cycles. Non-competitive assay formats are gaining preference in oncology applications where sensitivity requirements exceed competitive method capabilities. Diagnostic laboratories represent the dominant end-user channel, though pharmaceutical companies are emerging as a faster-growing segment for bioanalytical services in drug development.
FDA 510(k) pathways and EMA IVDR conformity assessments shape product development timelines and market access costs for radioimmunoassay manufacturers. ISO 13485 quality management standards and CLIA laboratory certification requirements further define operational parameters across the value chain. WHO prequalification programs influence procurement decisions in emerging markets where public health systems dominate diagnostics funding. Stakeholders must monitor isotope supply security and regulatory convergence between FDA and EMA digital health frameworks to anticipate competitive shifts.
Market Dynamics
The EU In Vitro Diagnostic Regulation (IVDR) is forcing reagent manufacturers to rebuild conformity documentation from scratch, compressing timelines for market access while reference laboratories in Germany and Japan accelerate validation of high-sensitivity hormone platforms.
Growth Catalysts
- IVDR Compliance Deadlines:The EU In Vitro Diagnostic Regulation mandates enhanced technical documentation for immunodiagnostic reagents, creating pull-through demand for certified assay kits as laboratories replace non-conforming inventory ahead of enforcement dates.
- Endocrine Biomarker Expansion:Thyroid and fertility testing panels are capturing expanded reimbursement coverage in United States reference laboratories, driving recurring reagent consumption through standardized hormone quantification protocols.
- Isotope Supply Security:Captive production of iodine-125 and tritium isotopes by specialized radiochemical facilities is stabilizing input costs for kit manufacturers with backward integration into isotope sourcing.
Market Restraints
- Radioisotope Supply Concentration:Production of high-specific-activity iodine-125 concentrates in a limited number of government-subsidized reactors, exposing kit manufacturers to geopolitical disruption in isotope availability.
- Non-Radioactive Substitutes:Chemiluminescence immunoassay platforms are capturing share in high-volume clinical laboratories where sensitivity requirements permit label-free detection methods.
- IVDR Conformity Costs:The EU In Vitro Diagnostic Regulation requires expanded clinical evidence for Class C and D devices, extending time-to-market for novel radioimmunoassay reagents by 18-24 months.
Strategic Opportunities
- Pharmaceutical Bioanalytical Services:Drug developers in United States and Switzerland are outsourcing biomarker validation for endocrine-disrupting compound trials, creating premium service revenue for contract research organizations with radioimmunoassay capabilities.
- Emerging Market Procurement:WHO prequalification programs are opening centralized procurement channels for hormone testing kits in public health systems across Sub-Saharan Africa and Southeast Asia.
- Non-Competitive Assay Formats:Sandwich immunoassay architectures with enzymatic amplification are enabling picogram-per-milliliter detection limits for oncology biomarkers where competitive binding methods lack requisite sensitivity.
Industry Challenges
- CLIA Personnel Requirements:United States clinical laboratories face persistent shortages of medical technologists with radioisotope handling certification, constraining operational scale-up for high-complexity testing.
- Legacy Analyzer Integration:Reference laboratories with embedded gamma counter infrastructure encounter friction when migrating to automated liquid handling systems, requiring custom middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Radioimmunoassay Market |
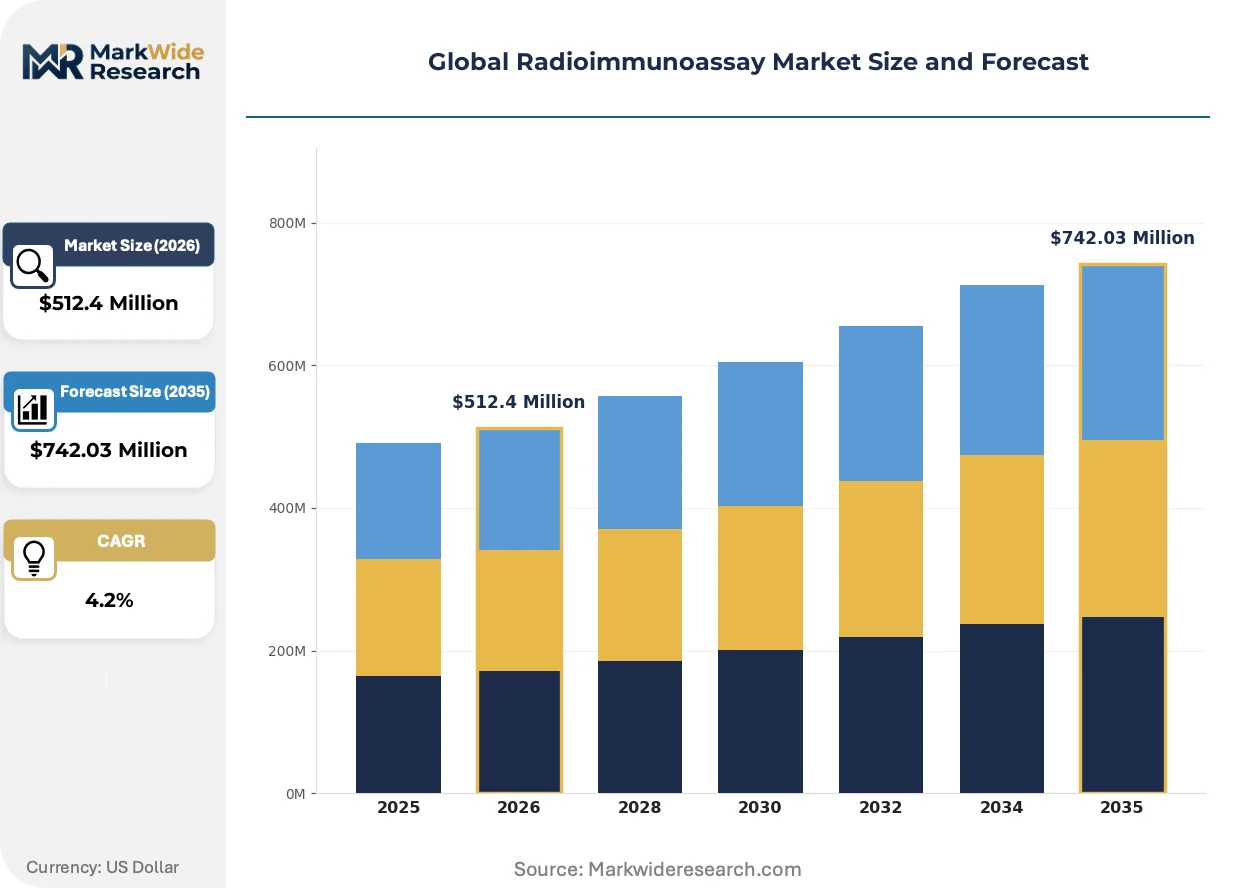
| Market Size in 2026 | $512.4 Million |
| Market Size in 2035 | $742.03 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reagents, Kits, Analyzers, Accessories Application: Endocrinology, Oncology, Infectious Diseases, Allergies, Toxicology End User: Diagnostic Laboratories, Research Institutes, Blood Banks, Pharmaceutical Companies Technology: Competitive Assay, Non-Competitive Assay, Sandwich Assay, Direct Assay |
| Companies Covered | IBL International, PerkinElmer, DIAsource ImmunoAssays, DiaSorin S.p.A., MP Biomedicals, Danaher, DRG International, Revvity, Berthold Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Radioimmunoassay Market Shifts & Advancements
Radioimmunoassay technology is absorbing methodological pressures from adjacent immunoassay platforms while regulatory frameworks in Europe and the United States impose divergent evidence requirements. Three forces are compressing competitive timelines and reshaping investment priorities across the value chain.
Automated liquid handling systems with integrated gamma counting are absorbing workflow consolidation demands from high-throughput clinical laboratories. Reference laboratories in Germany and Japan are deploying these platforms to reduce manual pipetting steps and isotope exposure. The technology is absorbing capital that would otherwise flow to chemiluminescence infrastructure, preserving radioimmunoassay position in endocrine reference testing.
EMA IVDR conformity assessments are extending clinical evidence requirements for Class C immunodiagnostic devices beyond prior In Vitro Diagnostic Directive standards. Kit manufacturers must now submit expanded analytical and clinical performance studies for hormone assays previously grandfathered under self-certification. European notified bodies are prioritizing thyroid panel submissions, creating queue congestion that delays market entry for niche endocrine tests.
Consolidated procurement by United States health system networks is compressing vendor qualification cycles and unbundling after-sales service from reagent contracts. Integrated delivery networks are demanding multi-year supply agreements with guaranteed isotope availability clauses. This pattern is most visible in the Midwest and Southeast regions where hospital system mergers have concentrated purchasing authority.
Global Radioimmunoassay Market Segmentation
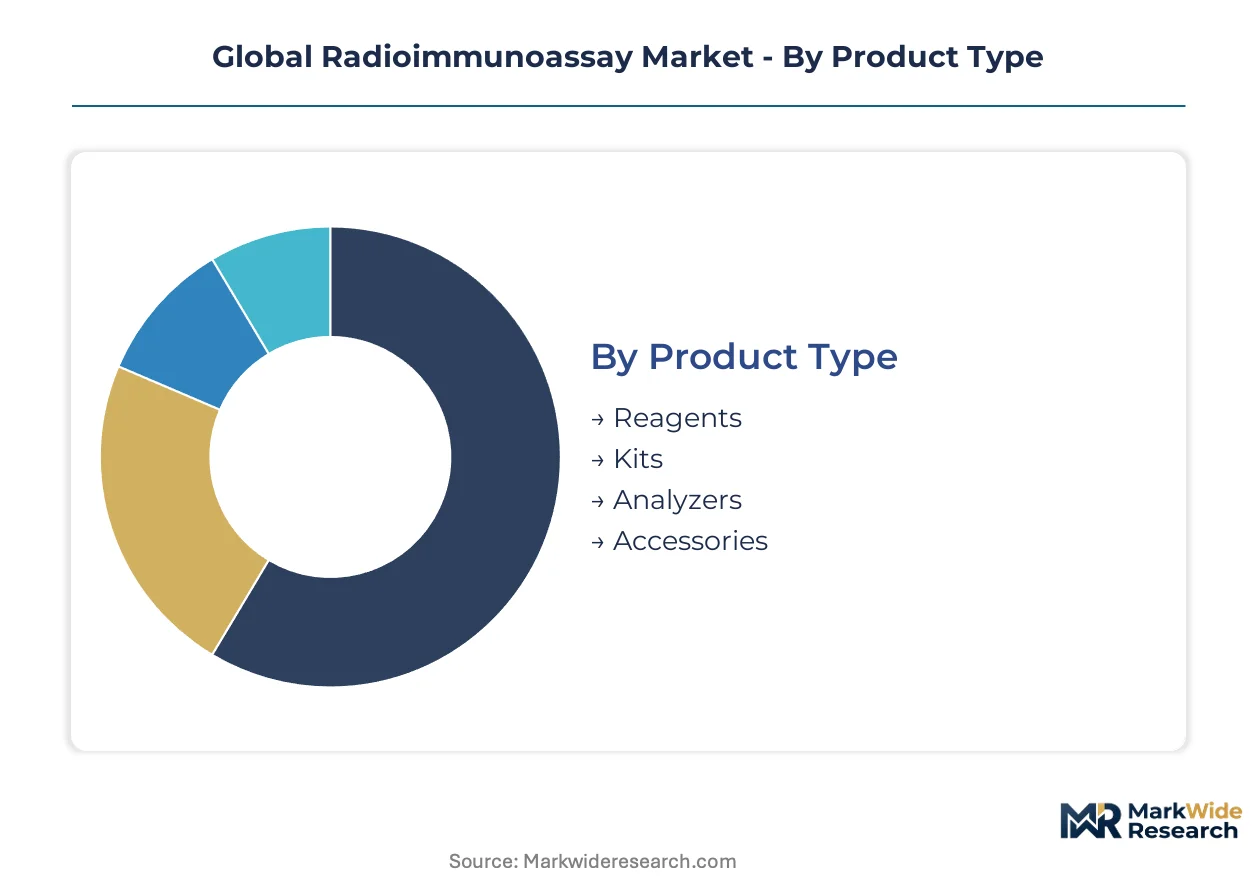
Radioimmunoassay market segmentation reveals divergent margin profiles across the value chain. Recurring reagent consumption generates stable revenue streams while analyzer sales concentrate in replacement cycles. Technology choices increasingly split between legacy competitive formats and emerging non-competitive architectures for high-sensitivity applications.
Product Type:
Reagents and kits command premium pricing through recurring purchase patterns, while analyzers face extended replacement timelines and accessories track installed base expansion.
- Reagents:Iodine-125 and tritium-labeled antigens with specific activity exceeding 2000 Ci/mmol enable picogram-per-milliliter detection thresholds. Demand concentrates in United States reference laboratories validating thyroid panels under CLIA high-complexity certification. IVDR conformity deadlines in Europe are accelerating inventory replacement cycles ahead of enforcement dates.
- Kits:Pre-configured assay panels bundle antibodies, standards, and quality controls for standardized hormone quantification. German clinical laboratories are scaling procurement of CE-IVD certified thyroid and fertility kits to meet EMA IVDR technical documentation requirements. Kit manufacturers with backward integration into isotope sourcing capture margin advantages during supply disruptions.
- Analyzers:Gamma counters and liquid scintillation systems with integrated data acquisition.
- Accessories:Pipette tips, vials, and shielding equipment for isotope handling protocols.
Mature deployment sits with Reagents. Newer deployment is concentrated in Analyzers with automated liquid handling integration.
Application:
Endocrine biomarker validation anchors current volume, while oncology applications are absorbing methodological innovation for ultra-low detection requirements.
- Endocrinology:Thyroid-stimulating hormone, cortisol, and reproductive steroid quantification using competitive binding kinetics. United States reference laboratories drive standardized panel adoption through Medicare reimbursement alignment for fertility and metabolic disorder diagnostics.
- Oncology:Tumor marker detection with non-competitive sandwich architectures enabling sub-picogram sensitivity. Research institutes in Switzerland and Japan are validating radioimmunoassay as reference method for circulating tumor biomarker standardization in immuno-oncology trials.
- Infectious Diseases:Viral antigen and antibody quantification for seroepidemiological studies.
- Allergies:Specific IgE measurement for atopic disease characterization.
- Toxicology:Drug and environmental contaminant screening in forensic matrices.
Standardized protocols dominate Endocrinology. Methodological experimentation is expanding fastest in Oncology.
End User:
Diagnostic laboratories generate the majority of reagent pull-through, while pharmaceutical companies are emerging as premium-priced service customers for bioanalytical validation.
- Diagnostic Laboratories:High-complexity CLIA-certified facilities performing hormone panels for hospital networks and independent physician practices. Consolidated procurement by United States integrated delivery networks is compressing vendor qualification timelines and demanding multi-year supply agreements with isotope security clauses.
- Pharmaceutical Companies:Contract research organizations and sponsor bioanalytical groups outsourcing endocrine-disrupting compound validation. Drug developers in Basel and Boston corridors are establishing dedicated radioimmunoassay capabilities for biomarker-supported regulatory submissions.
- Research Institutes:Academic and government laboratories conducting reference method development.
- Blood Banks:Serological screening and donor health assessment programs.
Established infrastructure characterizes Diagnostic Laboratories. Capacity building is accelerating most quickly in Pharmaceutical Companies.
Technology:
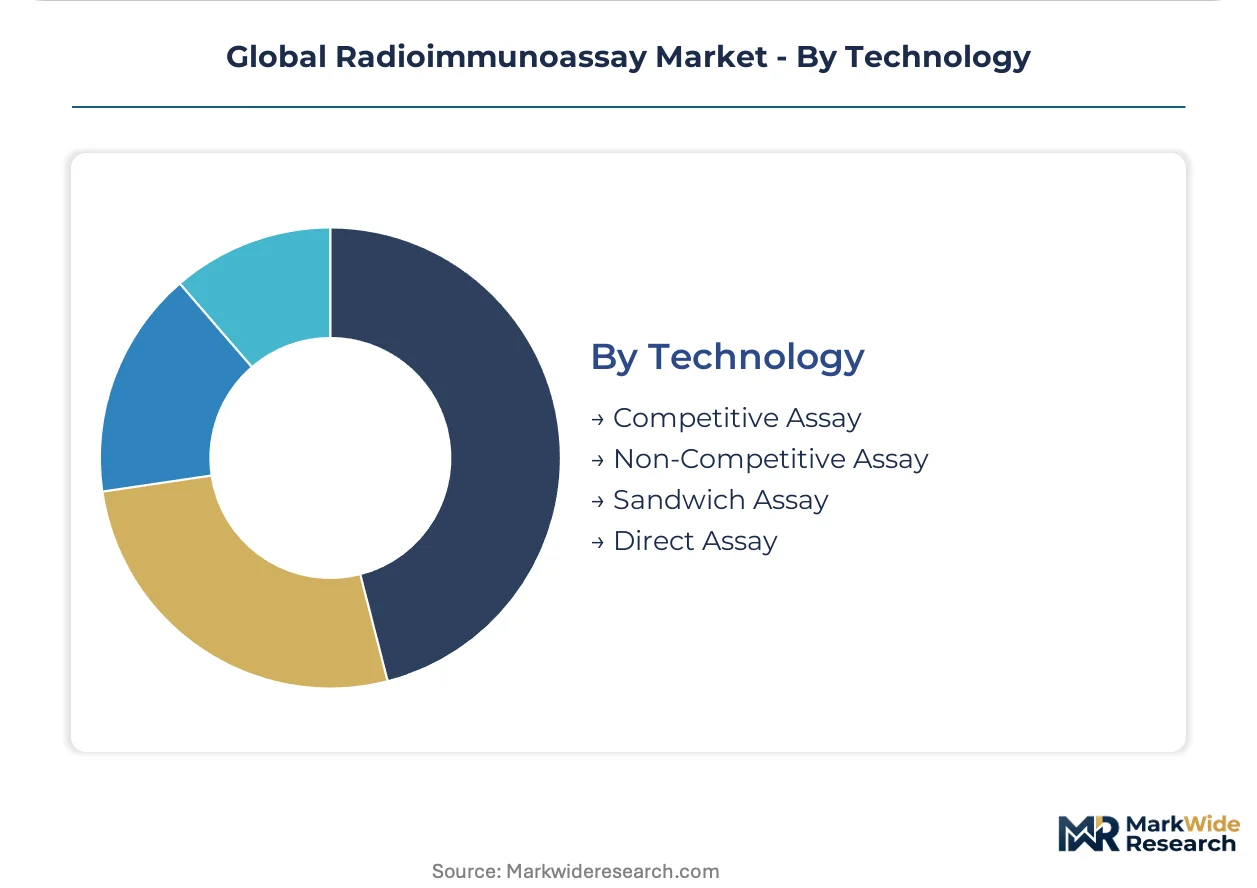
Competitive formats retain installed base dominance, while non-competitive architectures capture investment for sensitivity-demanding applications.
- Competitive Assay:Labeled and unlabeled ligand competition for limited antibody binding sites with quantification through displacement curves. Clinical laboratories in Germany maintain extensive gamma counter infrastructure optimized for competitive thyroid hormone protocols.
- Non-Competitive Assay:Sandwich and immunometric configurations with enzymatic or radiometric signal amplification. Oncology biomarker applications in Japan are driving adoption of non-competitive formats where competitive method sensitivity proves inadequate for circulating tumor DNA companion diagnostics.
- Sandwich Assay:Dual-antibody capture with labeled detection antibody for high-specificity quantification.
- Direct Assay:Single-step labeled ligand binding without separation requirements.
Proven protocols anchor Competitive Assay deployment. Technical migration is proceeding fastest toward Non-Competitive Assay platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bio-pharmaceutical special economic zones in Switzerland and Singapore concentrate contract research capacity for isotope-labeled assay development. These zones attract capital through accelerated regulatory pathways and tax-advantaged R&D structures. Germany and Japan maintain parallel concentrations of reference laboratory infrastructure.
United States
Reference laboratories in the Midwest and Southeast drive standardized thyroid panel adoption through Medicare-aligned reimbursement. FDA 510(k) pathways shape product development timelines for kit manufacturers seeking clinical laboratory access. The Boston and Basel corridor pharmaceutical clusters outsource endocrine biomarker validation to specialized contract research organizations.
Germany
Clinical laboratories in Bavaria and North Rhine-Westphalia scale CE-IVD certified hormone detection platforms ahead of IVDR enforcement deadlines. EMA IVDR conformity assessments extend documentation requirements for Class C immunodiagnostic devices. The Rhine-Main biotechnology cluster anchors gamma counter infrastructure optimized for competitive binding protocols.
Japan
PMDA regulatory frameworks govern isotope handling certification for medical technologists in high-complexity testing facilities. METI industrial policy supports domestic radiochemical production capacity for iodine-125 supply security. The Kanto region around Tokyo concentrates automated liquid handling deployment for workflow consolidation.
Switzerland
Swissmedic oversees marketing authorization for radioimmunoassay reagents used in pharmaceutical bioanalytical services. The Basel pharmaceutical corridor demands reference-method validation for endocrine-disrupting compound trials. Canton Basel-Stadt hosts specialized contract research organizations with captive isotope sourcing capabilities.
Global Radioimmunoassay Market Competitive Landscape
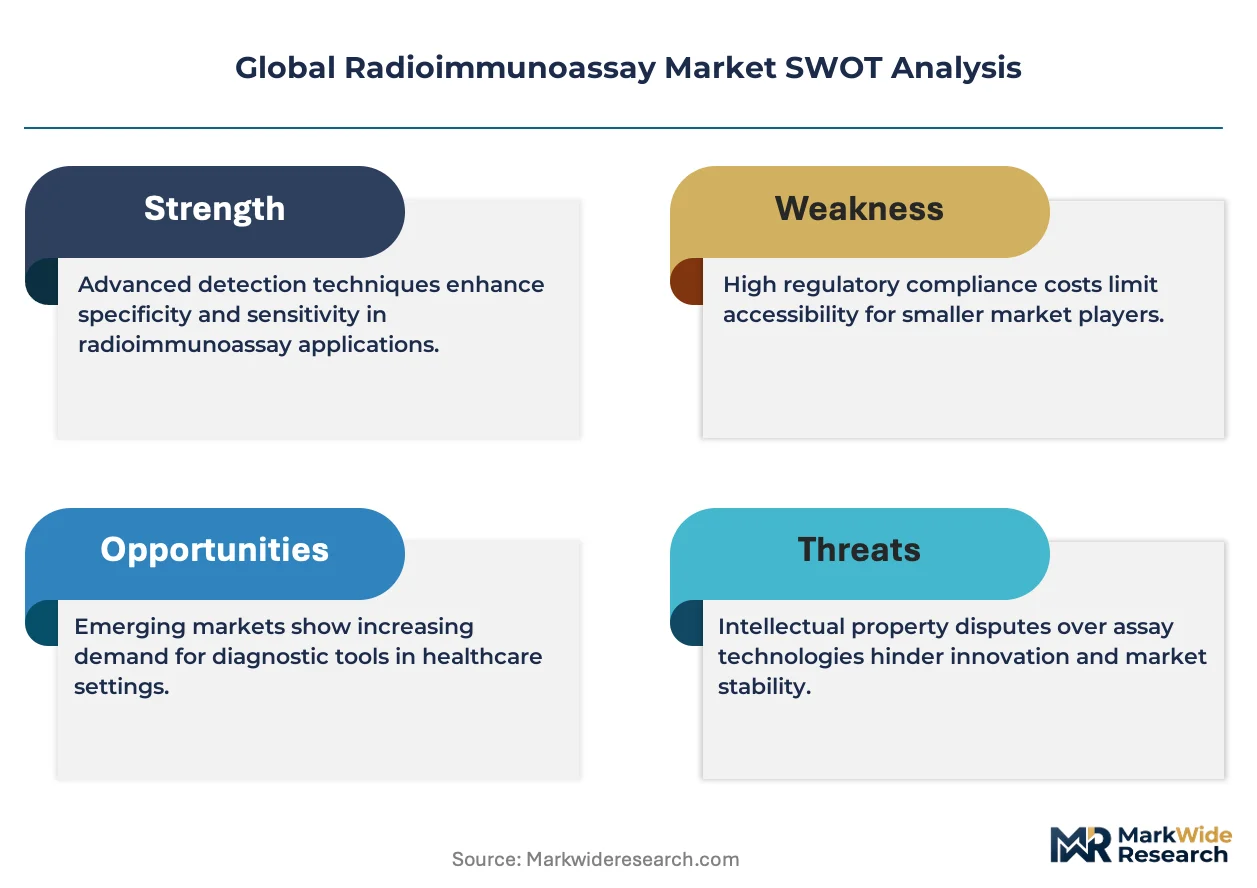
Diversified conglomerates compete with focused pure-play specialists across the radioimmunoassay value chain. The market structure splits between integrated life science conglomerates with broad diagnostic portfolios and specialized reagent manufacturers with captive isotope supply. Three archetypes dominate: diversified conglomerates leveraging cross-selling infrastructure, mid-cap specialists with backward integration into radiochemical production, and niche endocrine panel developers serving overlooked biomarker segments. Consolidation through strategic acquisitions and geographic expansion into WHO prequalification markets represent the primary competitive vectors.
Among diversified conglomerates with diagnostic divisions, Danaher and Revvity occupy positions spanning multiple immunoassay modalities. PerkinElmer exemplifies the CE-IVD portfolio archetype navigating European regulatory transitions. DiaSorin S.p.A. sits within the specialist tier with demonstrated radiochemical supply chain control.
| Leading Market Players |
|---|
| IBL International |
| PerkinElmer |
| DIAsource ImmunoAssays |
| DiaSorin S.p.A. |
| MP Biomedicals |
| Danaher |
| DRG International |
| Revvity |
| Berthold Technologies |
| Others |
Supply & Pricing Matrix
Consolidated procurement by United States integrated delivery networks is forcing kit manufacturers to absorb inventory risk and guarantee isotope availability, compressing margins while shifting pricing power toward buyers with multi-year contract leverage.
Pricing Analysis
Short lead-time premiums for IVDR-compliant reagents command substantial markups over spot inventory as European laboratories face enforcement deadlines. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in economy tiers is intensifying because reference laboratories in Germany and Japan are standardizing on automated platforms. Pharmaceutical bioanalytical services exhibit least price sensitivity due to regulatory submission timelines.
Supply Chain Analysis
Refurbishment flows for legacy gamma counters extend equipment lifecycles and delay analyzer replacement demand across installed bases. Production of high-specific-activity iodine-125 concentrates in Belgium, South Africa, and Russia exposes kit manufacturers to geopolitical disruption in isotope availability. Captive supply of tritium isotopes draws from specialized radiochemical facilities with government-subsidized reactor access. Distribution runs through diagnostic laboratory distributors and direct contracts with reference laboratory networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The radioimmunoassay market sits in a technology-transition phase as chemiluminescence immunoassay platforms displace legacy competitive binding methods in high-volume clinical settings.
For Market Incumbents: Anchor competitive position through backward integration into iodine-125 isotope sourcing and accelerated CE-IVD certification for thyroid panel reagents ahead of IVDR enforcement. Defend against chemiluminescence substitution by embedding automated liquid handling systems in German and Japanese reference laboratories with long-term service contracts. For New Entrants and Emerging Players: Contract research organizations serving pharmaceutical bioanalytical services represent the most penetrable channel for specialty endocrine panel development. Target WHO prequalification pathways for hormone testing kits in Sub-Saharan African public health procurement. Differentiate through niche biomarker assays that diversified conglomerates deprioritize in their portfolio rationalization. For Investors and Strategic Acquirers: The window for entry favors mid-cap specialists with demonstrated radiochemical supply chain control and established notified body relationships for IVDR conformity. Long-term viability rests on isotope security and regulatory navigation capabilities rather than volume scale. Monitor EMA notified body queue congestion for Class C immunodiagnostic devices as an inflection indicator for competitive access timelines.| Strategic Initiative | Industry Significance |
|---|---|
| CE-IVD Certification Acceleration | EMA IVDR technical documentation requirements compress market access timelines for non-compliant inventory. |
| Backward Integration into Isotope Sourcing | Captive iodine-125 production insulates margin structure from reactor supply disruptions in Belgium and Russia. |
| Automated Liquid Handling Deployment | Integrated gamma counting platforms preserve radioimmunoassay position against chemiluminescence substitution in German laboratories. |
| Pharmaceutical CRO Partnership | Bioanalytical service contracts with Basel and Boston drug developers generate premium pricing for endocrine biomarker validation. |
| WHO Prequalification Pathway | Centralized procurement channels in Sub-Saharan Africa open volume opportunities for standardized hormone testing kits. |
Research Methodology
Independent corroboration across regulatory filing databases, hospital procurement records, and radiochemical supply chain disclosures underwrites the qualitative findings in this study. Primary interviews with diagnostic laboratory directors, regulatory affairs specialists at kit manufacturers, biomedical engineers, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EMA IVDR submission databases, and WHO prequalification records. Bottom-up reagent consumption estimates and top-down market sizing triangulate through gamma counter installed base analysis and reference laboratory survey data.
Comparable-period anchoring to historical thyroid panel adoption curves and fertility testing reimbursement trajectories shaped the projection framework across the analysis window. Segmentation dimensions modeled include product type, application area, end-user category, and technology format alongside regional regulatory cluster differentiation. CAGRs derive from weighted average of isotope supply security scenarios and IVDR compliance timeline assumptions. Forecast inputs incorporate PMDA certification pathways for Japanese clinical laboratories and Medicare reimbursement alignment for United States reference testing.
Several conditions sit outside the modeled scope, including abrupt reactor shutdowns affecting iodine-125 availability, accelerated chemiluminescence sensitivity improvements, and harmonization between FDA and EMA digital health frameworks. Forecasts reflect documented assumptions about isotope supply continuity and regulatory enforcement timelines. Practitioners should monitor EMA notified body capacity expansion and PMDA medical technologist certification policy for early signals of competitive access shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Eye Testing Equipment Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Dry Chemistry Analyzers Market
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Electroporation Instruments Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Global Chemiluminescence Immunoassay (CLIA) Analyzers Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Luminometers Market