
 Tympanometers Market | 2026-2036
Tympanometers Market Size, Share, and Industry Trends Forecast 2026-2036
Tympanometers Market Intelligence
The EU Medical Device Regulation is restructuring procurement criteria for middle-ear diagnostic equipment across European ENT clinics and audiology centers. Natus Medical Incorporated leverages its vertical integration in neurodiagnostics to sustain channel control in North American hospital systems. Happersberger Otopront GmbH anchors its position through specialized German manufacturing of precision otologic instruments. Interacoustics differentiates via R&D intensity in multi-frequency tympanometry platforms for pediatric applications.
A tympanometer is an electroacoustic instrument that measures middle-ear compliance by varying air pressure in the ear canal while transmitting a probe tone, typically at 226 Hz for adults and 1000 Hz for infants. Its primary commercial purpose is to detect otitis media, eustachian tube dysfunction, and ossicular chain disruptions in clinical and screening settings. Desktop tympanometers occupy the highest-margin segment due to advanced diagnostic protocols demanded by hospital-based audiology departments, while handheld and portable digital systems represent the fastest-expanding category as community health programs decentralize hearing screening. Automated tympanometers are maturing in developed markets but remain underpenetrated in primary care networks where operator training gaps persist.
The FDA governs tympanometer clearance through Class II medical device pathways requiring 510(k) submissions with acoustic output safety data, while the EU MDR mandates notified-body conformity assessments for impedance audiometry equipment under stricter clinical-evidence rules. Japan's PMDA enforces JIS-T-1201 calibration standards that shape product design for Asian-market entry. Stakeholders must monitor divergence between FDA acoustic-emission limits and EU MDR biocompatibility requirements for probe assemblies when configuring regional product portfolios.
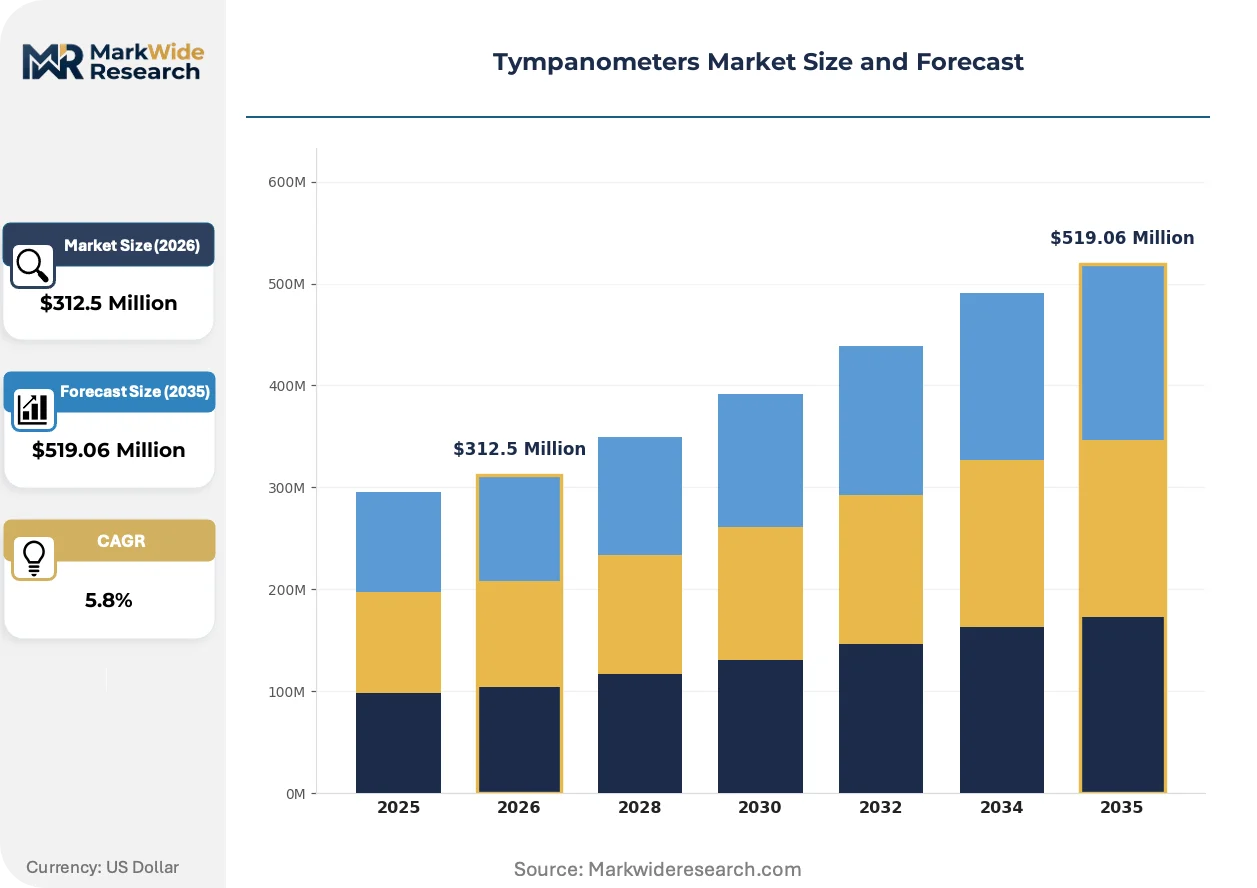
Market Dynamics
The EU Medical Device Regulation's tightened acoustic calibration standards are forcing equipment redesigns across impedance audiometry platforms, compressing certification timelines while elevating R&D overhead for manufacturers serving European ENT clinics.
Growth Catalysts
- Pediatric Screening Mandates:United States state-level newborn hearing protocols drive replacement cycles in hospital audiology departments, creating predictable equipment refresh demand.
- EU MDR Compliance Windows:Stricter clinical-evidence rules for Class IIa medical devices accelerate notified-body conformity assessments, favoring manufacturers with established quality management systems.
- Tele-audiology Infrastructure:Cloud-connected tympanometry platforms enable remote diagnostic review, expanding addressable markets beyond traditional clinic footprints.
Market Restraints
- Probe Assembly Biocompatibility Costs:EU MDR biocompatibility testing requirements for patient-contact components inflate per-unit material expenses without commensurate reimbursement expansion.
- Calibration Standard Fragmentation:Divergence between FDA acoustic-emission limits and Japan's JIS-T-1201 specifications forces regional SKU proliferation, eroding manufacturing scale economies.
- Primary Care Training Gaps:Automated tympanometer penetration stalls in community health networks where operator competency requirements exceed available continuing education bandwidth.
Strategic Opportunities
- Rural India Diagnostic Networks:Ayushman Bharat health infrastructure expansion creates demand for portable, battery-operated screening devices with simplified user interfaces.
- Multi-frequency Platform Convergence:Integration of 226 Hz adult and 1000 Hz infant probe tones into single hardware units reduces capital duplication for mixed-population clinics.
- Screening-as-a-Service Models:Subscription-based equipment access decouples upfront capital requirements from utilization, penetrating price-sensitive municipal health systems.
Industry Challenges
- Clinical Engineer Scarcity:Specialized training in acoustic calibration and middle-ear pathology interpretation concentrates in tertiary audiology centers, limiting deployment velocity.
- Legacy System Integration Friction:Hospital information system compatibility gaps between new tympanometry platforms and existing electronic health record architectures delay purchase approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tympanometers Market |
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $519.06 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Handheld Tympanometers, Desktop Tympanometers, Screening Devices, Automated Tympanometers Application: Middle Ear Assessment, Eustachian Tube Function Testing, Hearing Screening, Otitis Media Diagnosis End User: ENT Clinics, Audiology Centers, Diagnostic Laboratories, Research Institutions Technology: Impedance Audiometry, Multi-Frequency Tympanometry, Portable Digital Systems, Analog Devices |
| Companies Covered | Natus Medical Incorporated, Happersberger Otopront GmbH, MedRx Inc., Interacoustics, INVENTIS s.r.l., MAICO Diagnostic GmbH, Demant Group, PATH Medical Solutions, Grason-Stadler, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tympanometers Market Strategic Shifts & Innovations
Portable digital tympanometry platforms are compressing the traditional equipment hierarchy, enabling point-of-care deployment models that bypass centralized audiology department gatekeeping. Three interconnected developments define this transition.
Handheld battery-operated tympanometers is decentralizing diagnostic access from hospital-based audiology suites to school-based screening programs and primary care clinics. School districts in the United States and municipal health services in Germany are procuring these units for mass pediatric screening events. This diffusion pattern is compressing the addressable market for desktop systems while expanding total procedure volume.
The EU Medical Device Regulation's clinical-evidence requirements for acoustic output safety data are extending 510(k) equivalence pathways for impedance audiometry equipment. Manufacturers must now compile post-market surveillance documentation previously unnecessary for legacy device renewals. European notified bodies are prioritizing submissions from firms with established pediatric clinical datasets, advantaging incumbents with historical trial access.
Hospital procurement committees are unbundling after-sales service contracts from equipment purchases, shifting toward third-party calibration and maintenance providers. This disintermediation pressures original equipment manufacturers to compete on hardware margins alone. The trend is most visible in United States integrated delivery networks where standardization mandates favor multi-vendor service aggregators over captive manufacturer support programs.
Tympanometers Market Segmentation
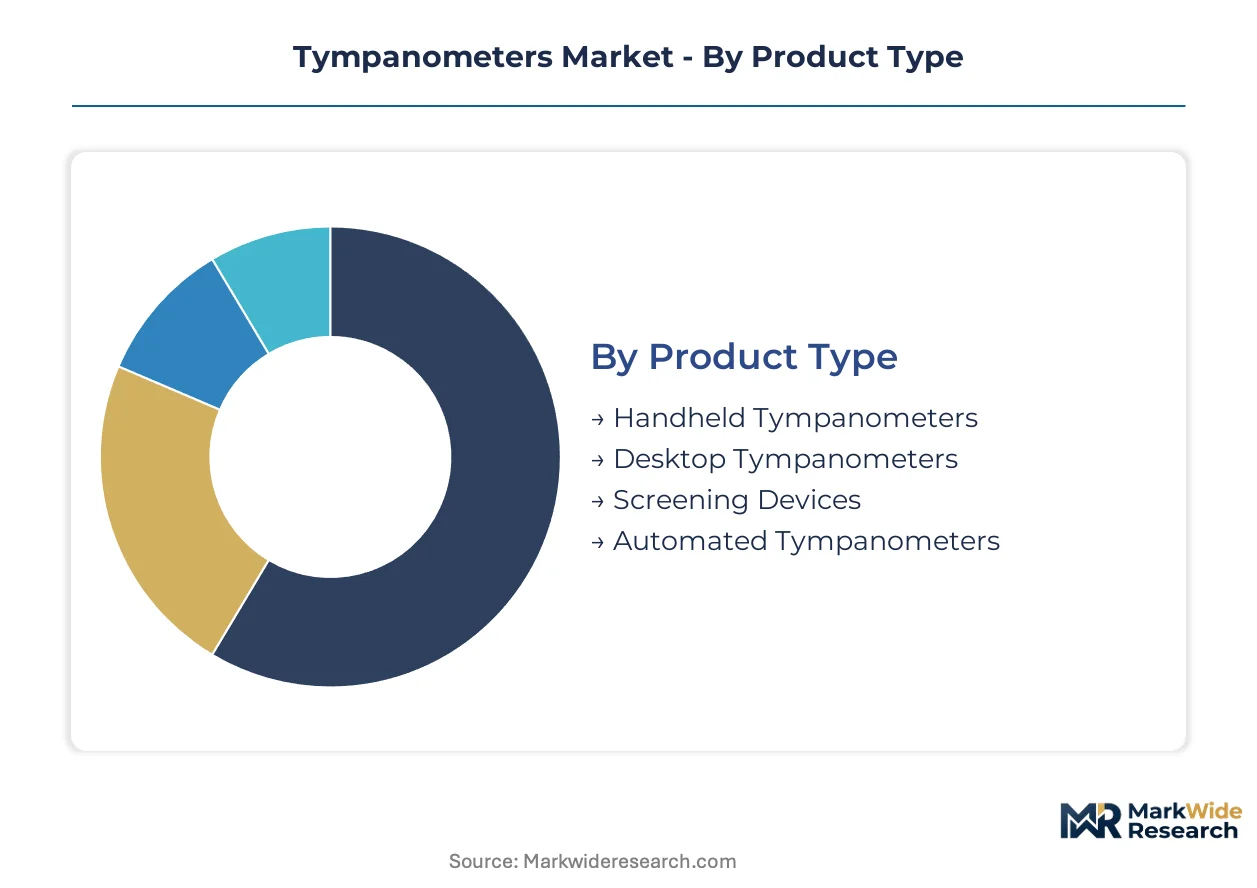
Tympanometer procurement patterns diverge sharply across clinical settings, with technology sophistication and mobility requirements driving equipment selection. Understanding these segment boundaries clarifies where manufacturers must configure distinct product architectures versus unified platforms.
Product Type:
Form factor and automation level define capital allocation priorities across ENT departments and community health networks.
- Handheld Tympanometers:Battery-operated units weighing under 500 grams enable school-based screening programs and primary care deployment. Demand concentrates in United States school districts executing state-mandated pediatric hearing protocols, though EU MDR biocompatibility testing for probe assemblies elevates per-unit costs.
- Desktop Tympanometers:Full-featured systems with multi-frequency protocols and integrated thermal printers anchor hospital audiology departments. Procurement in Germany's tertiary ENT centers prioritizes acoustic calibration precision under tightening EU MDR standards.
- Screening Devices:Simplified pass-fail units for high-volume community programs.
- Automated Tympanometers:Self-calibrating platforms reducing operator dependency in resource-limited settings.
Desktop systems lead on scale; handheld units lead on momentum.
Application:
Diagnostic purpose shapes probe tone selection and pressure sweep protocols.
- Middle Ear Assessment:Core compliance measurement at 226 Hz for adults and 1000 Hz for infants detects ossicular chain disruptions. United States audiology centers drive replacement cycles as pediatric screening mandates expand procedure volumes.
- Eustachian Tube Function Testing:Pressure-sweep protocols with extended positive/negative pressure ranges evaluate tubal patency. Japanese ENT clinics under PMDA JIS-T-1201 calibration standards demand precision pressure control.
- Hearing Screening:Rapid bilateral testing for newborn and school-age protocols.
- Otitis Media Diagnosis:Differential detection of fluid accumulation versus tympanic membrane perforation.
Middle ear assessment dominates installed base; hearing screening climbs fastest.
End User:
Facility type determines equipment sophistication thresholds and service contract structures.
- ENT Clinics:Specialized otologic practices requiring full diagnostic protocols including multi-frequency tympanometry and acoustic reflex measurement.
- Audiology Centers:Dedicated hearing facilities in the United States refresh equipment most frequently due to pediatric mandate compliance and third-party reimbursement density.
- Diagnostic Laboratories:High-throughput centralized testing with integration demands for laboratory information systems.
- Research Institutions:Custom calibration requirements and longitudinal data capture for clinical trials.
Audiology centers concentrate procurement velocity; ENT clinics concentrate margin capture.
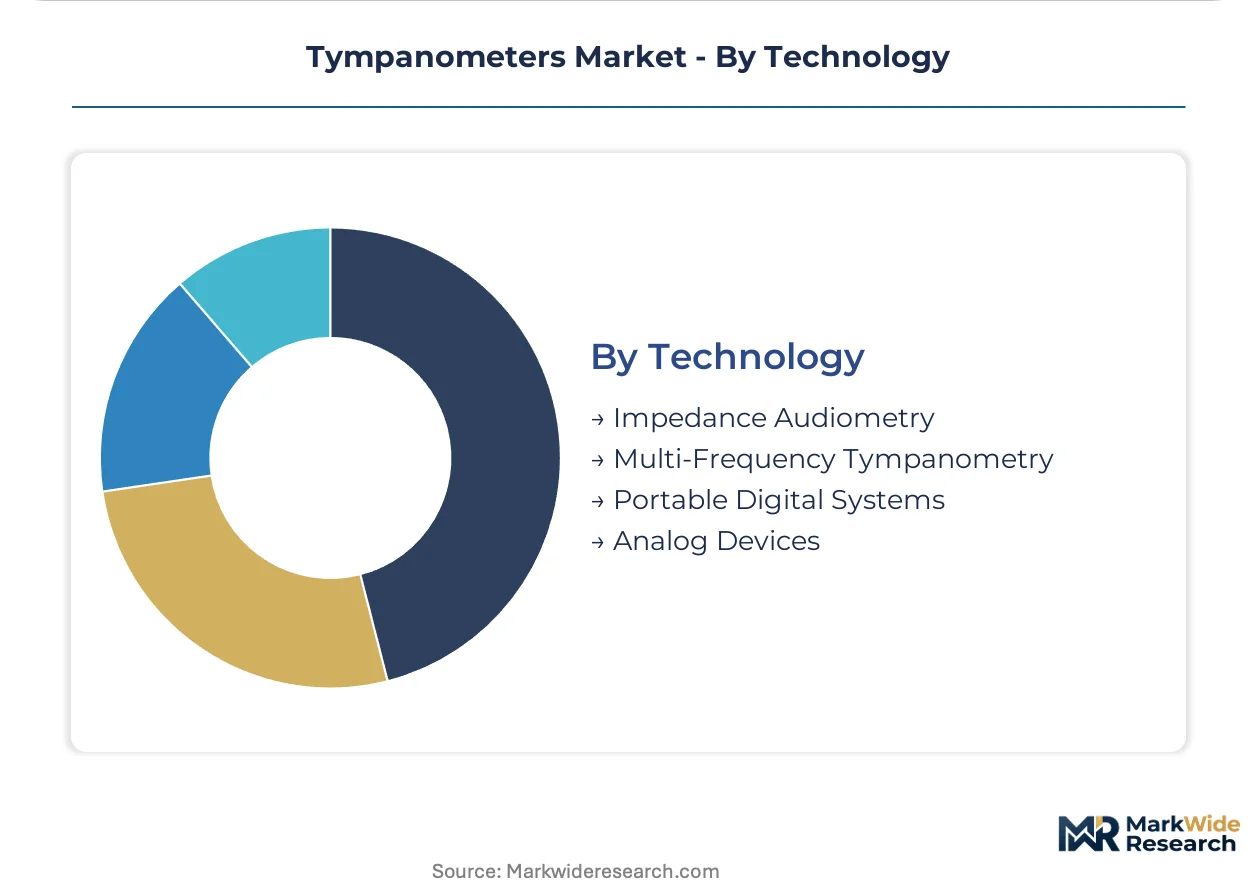
Technology:
Signal processing architecture separates legacy installations from next-generation platforms.
- Impedance Audiometry:Established electroacoustic measurement of middle-ear compliance through probe tone transmission and reflected sound pressure analysis.
- Multi-Frequency Tympanometry:Sequential or simultaneous probe tones at 226 Hz, 678 Hz, and 1000 Hz enable resonance frequency analysis for differential diagnosis of ossicular versus cochlear pathology.
- Portable Digital Systems:Handheld units with cloud connectivity and simplified user interfaces expanding access beyond traditional audiology suites.
- Analog Devices:Legacy electromechanical systems with limited upgrade paths, concentrated in developing market installations with extended replacement cycles.
Impedance audiometry anchors installed base; portable digital systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Diagnostic audiometry originated in German university hospitals during the mid-20th century, with precision electroacoustic instrumentation later diffusing through North American pediatric screening programs and Japanese ENT specialty networks.
United States
State-mandated newborn hearing protocols and school-based screening programs drive equipment refresh cycles in hospital audiology departments. The FDA's Class II 510(k) clearance pathway governs acoustic output safety submissions for impedance audiometry devices. Procurement concentrates in Texas and California health systems where integrated delivery networks standardize multi-site equipment purchases.
Germany
Tertiary ENT centers in Bavaria and Baden-Württemberg prioritize precision acoustic calibration under tightening EU MDR standards for Class IIa medical devices. The EU Medical Device Regulation mandates notified-body conformity assessments with stricter clinical-evidence rules than predecessor directives. Manufacturing clusters around Tuttlingen anchor precision otologic instrument production for European export markets.
Japan
Pediatric otitis media diagnosis and aging-related hearing assessment sustain demand in Tokyo and Osaka metropolitan ENT clinics. The PMDA enforces JIS-T-1201 calibration standards that shape probe tone specifications and pressure control protocols. Regional production around Nagoya supplies domestic hospitals with impedance audiometry platforms tuned to Japanese acoustic emission limits.
India
Ayushman Bharat health infrastructure expansion creates procurement opportunities for portable, battery-operated screening devices in rural diagnostic networks. The CDSCO regulates medical device imports under tightened quality management system requirements aligned with global harmonization initiatives. Equipment deployment concentrates in Maharashtra and Karnataka where municipal health systems decentralize hearing screening to primary care centers.
United Kingdom
NHS audiology service consolidation drives standardized equipment procurement across England's hospital trusts and community clinics. The MHRA post-Brexit regulatory framework maintains EU MDR technical standards while operating independent conformity assessment procedures. London and Manchester academic medical centers pilot cloud-connected tympanometry platforms for tele-audiology service delivery.
Tympanometers Market Key Industry Players
Premium-margin players sit above commodity-margin players across calibration precision and pediatric clinical-evidence depth. The vendor base organizes into three tiers: integrated neurodiagnostics conglomerates with captive hospital system relationships; specialized German and Italian precision instrument fabricators; and emerging portable digital specialists attacking community screening price points. Consolidation pressure operates through M&A activity among audiology device portfolios and strategic partnerships linking hardware manufacturers with third-party calibration service networks.
Among German precision manufacturers, Happersberger Otopront GmbH and MAICO Diagnostic GmbH exemplify the specialized instrument fabricator archetype with deep regional manufacturing heritage. Interacoustics occupies a position within the multi-frequency platform specialist tier, while Natus Medical Incorporated represents the integrated neurodiagnostics conglomerate model with channel control across North American hospital systems.
| Leading Market Players |
|---|
| Natus Medical Incorporated |
| Happersberger Otopront GmbH |
| MedRx Inc. |
| Interacoustics |
| INVENTIS s.r.l. |
| MAICO Diagnostic GmbH |
| Demant Group |
| PATH Medical Solutions |
| Grason-Stadler |
| Others |
Cost & Logistics Intelligence
Acoustic sensor component indices in precision electroacoustic instrumentation cascade through three distinct pricing tiers, compressing margins at the economy level while sustaining premium capture for EU MDR-certified desktop systems in German tertiary centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the tympanometer market by calibration precision and after-sales bundling. Price differentiation hinges on EU MDR certification tier and acoustic calibration protocol sophistication, with German-manufactured desktop units commanding sustained premiums. Cost compression in handheld segments intensifies as battery-operated platforms proliferate in United States school districts. Municipal health systems in India exhibit highest price sensitivity, while hospital audiology departments in Japan demonstrate lowest sensitivity due to reimbursement density.
Supply Chain Analysis
Refurbishment flows for probe assemblies and acoustic calibration modules create secondary supply channels, extending equipment lifecycles in developing markets. Manufacturing concentrates in Germany, Japan, and the United States, with Tuttlingen precision clusters anchoring European production. Component sourcing draws from specialized electroacoustic transducer foundries in South Korea and Taiwan, with single-source vulnerability concentrated in MEMS pressure sensor supply. Distribution runs through hospital procurement committees in integrated delivery networks and third-party medical device distributors serving independent ENT clinics.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in tympanometry equipment rests on probe assembly cost-down trajectories and the shift toward multi-frequency premium platforms in pediatric screening networks.
For Market Incumbents: Cement channel control through captive calibration service networks and backward integration into acoustic transducer production. Entrenched relationships with United States integrated delivery networks defend against portable digital specialists attacking community screening price points. Priority investment in EU MDR pediatric clinical datasets preserves notified-body submission advantages. For New Entrants and Emerging Players: Cloud-connected tympanometry platforms with simplified user interfaces offer the most penetrable wedge into rural Indian diagnostic networks under Ayushman Bharat expansion. Tele-audiology infrastructure partnerships with municipal health systems bypass traditional hospital procurement gatekeeping. Target subscription-based equipment access models to decouple upfront capital barriers in price-sensitive segments. For Investors and Strategic Acquirers: Asymmetric upside sits with specialized German precision instrument fabricators possessing multi-frequency platform depth and established EU MDR quality systems. Long-term viability over the coming decade favors manufacturers with vertical integration into neurodiagnostics portfolios. Monitor notified-body conformity assessment backlogs as inflection indicator for certification-constrained market share shifts.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment | Notified-body prioritization accelerates market access for pediatric clinical-evidence holders. |
| Multi-Frequency Platform Convergence | Single hardware units reduce capital duplication for mixed-population audiology centers. |
| Tele-Audiology Infrastructure Partnership | Cloud connectivity expands addressable markets beyond traditional clinic footprints. |
| Backward Integration into Transducer Supply | In-house production of acoustic components defends margin against sensor cost volatility. |
| Subscription-Based Equipment Access | Service models penetrate municipal health systems with constrained capital budgets. |
Research Approach
Bottom-up audiology center modeling reconciled against top-down impedance audiometry equipment production tracking forms the analytical core of this study. Primary interviews with hospital purchasing committees, biomedical engineers, ENT clinicians, and GPO contracts managers combined with secondary validation from FDA 510(k) filings, EU MDR notified-body databases, PMDA submission records, and hospital procurement databases. Triangulation across these sources ensures segmentation integrity across product type, application, end user, and technology dimensions.
Historical trendline analysis of replacement cycles in United States hospital audiology departments and German tertiary ENT centers informs projection frameworks across the analysis window. Segmentation modeling spans form factor sophistication, diagnostic protocol complexity, facility type, and signal processing architecture. CAGRs derive from equipment shipment trajectories, pediatric mandate expansion patterns, and tele-audiology infrastructure deployment rates calibrated against acoustic calibration standard evolution.
The model holds under stable regulatory transition timelines; deviation in EU MDR notified-body capacity or FDA acoustic-emission limit revisions would shift certification timelines and procurement patterns. Practitioners should monitor pediatric screening mandate expansion in United States state legislatures and CDSCO quality management system alignment progress for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Electroporation Instruments Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Europe Immunoassay Analyzers Market
Diagnostic Instruments
Global Blood Coagulation Analyzer Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Immunochemistry Analyzer Market
Diagnostic Instruments
Visual Field Testing Equipment Market
Diagnostic Instruments
Pachymeter Market
Diagnostic Instruments
Global Radioimmunoassay Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Pathology Instruments Market
Diagnostic Instruments
Vascular Testing Devices Market