
 Europe Immunoassay Analyzers Market | 2026-2036
Europe Immunoassay Analyzers Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Immunoassay Analyzers Market Intelligence
A widening capability gap in reagent manufacturing is rotating competitive advantage toward vertically integrated European instrument makers. Siemens Healthineers leverages captive bioreagent production to lock in hospital system contracts across Germany. bioMérieux SA anchors its position through specialized microbiology immunoassay menus that competitors struggle to replicate. Abbott Laboratories extends reach via compact point-of-care platforms suited for decentralized European clinic networks.
Europe Immunoassay Analyzers comprise automated clinical diagnostic systems that detect target analytes through antigen-antibody binding reactions, with chemiluminescence systems achieving detection thresholds below one picogram per milliliter for high-sensitivity cardiac troponin assays. These instruments process hundreds of samples hourly in centralized laboratories, enabling rapid infectious disease screening and endocrinology panels. Chemiluminescence analyzers command premium pricing due to superior throughput and reagent stability, while point-of-care technology gains traction in emergency departments seeking turnaround times under twenty minutes. Diagnostic laboratories represent the dominant revenue pool, though research institutions drive demand for multiplexed cytokine profiling platforms.
EMA's IVDR framework tightens clinical evidence requirements for immunoassay kits, forcing manufacturers to expand post-market surveillance infrastructure. REACH compliance adds complexity to reagent chemical sourcing, particularly for enzyme conjugates and detection substrates. Germany's KBA and France's ANSM coordinate notified body capacity, creating uneven certification speeds across member states. Stakeholders must monitor IVDR transition deadlines and reagent supply chain qualification status to avoid portfolio disruption.
Market Dynamics
EMA's IVDR implementation is compressing certification timelines and forcing manufacturers to restructure clinical evidence portfolios, while diagnostic laboratories in Germany and France accelerate automation investments to offset staffing constraints.
Growth Catalysts
- IVDR Compliance Deadlines:EMA's phased transition requirements are pulling forward replacement cycles for legacy analyzers as laboratories seek pre-certified platforms to avoid service interruptions.
- Centralized Laboratory Automation:Hospital networks across France are consolidating testing volumes onto high-throughput chemiluminescence systems to reduce per-sample operational costs.
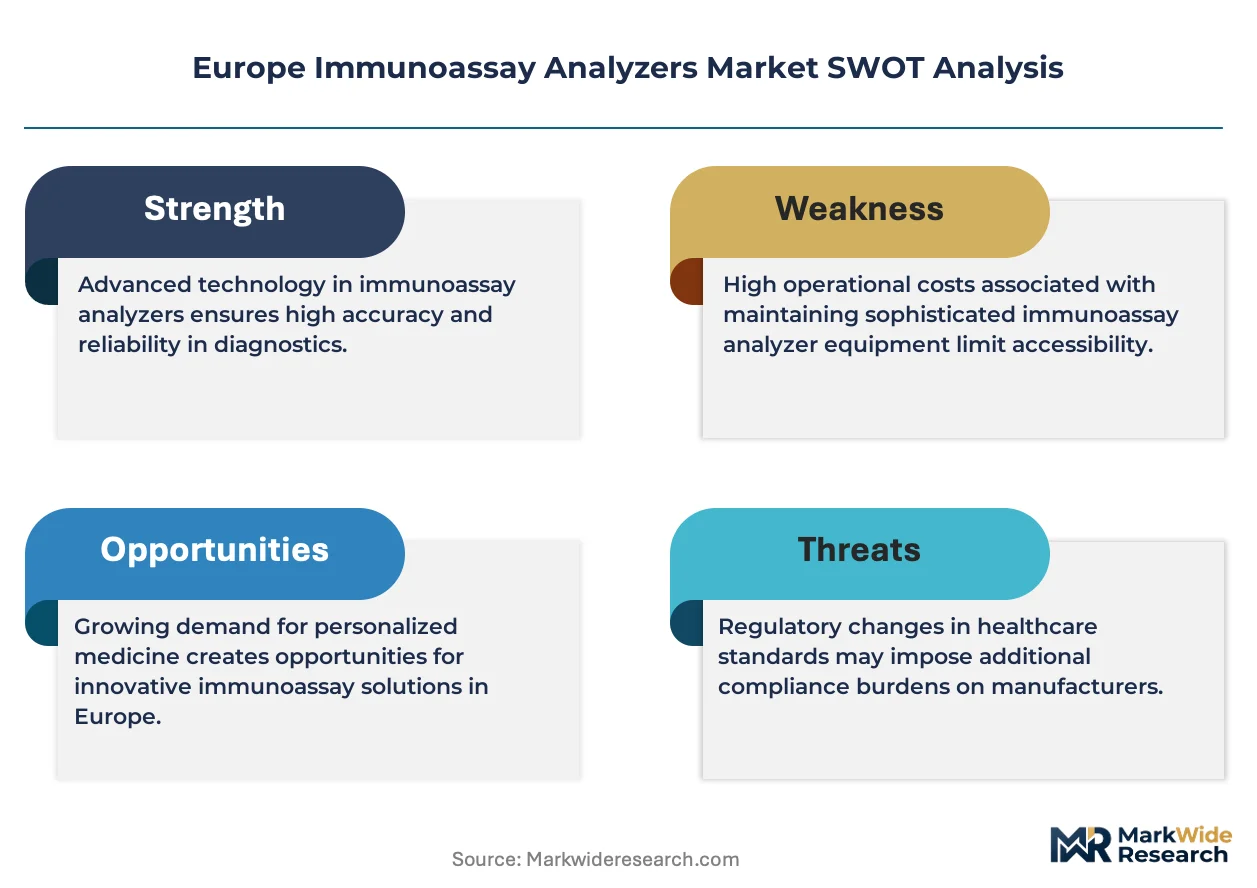
- Infectious Disease Surveillance Mandates:European health ministries are expanding respiratory and sepsis panel testing requirements, directly expanding installed base demand for multiplex immunoassay capacity.
Market Restraints
- Reagent Supply Concentration:Enzyme conjugate manufacturing clusters in Southern Germany create single-source vulnerability for detection chemistry inputs.
- IVDR Certification Friction:Notified body capacity bottlenecks between Germany's KBA and France's ANSM are extending time-to-market for new assay kits by twelve to eighteen months.
- Capital Intensity Barriers:Full-automation immunoassay lines require substantial upfront investment, limiting access for mid-sized diagnostic laboratories in Southern Europe.
Strategic Opportunities
- Emergency Department Decentralization:Point-of-care troponin and D-dimer testing protocols are creating demand for compact analyzers in Spanish and Italian hospital networks.
- Multiplex Cytokine Profiling:Research institutions in the Netherlands are adopting high-plex immunoassay platforms for immunotherapy monitoring applications.
- CE-IVDR Early Certification:Manufacturers achieving IVDR compliance ahead of transition deadlines capture locked-in procurement contracts from risk-averse laboratory directors.
Industry Challenges
- Specialized Field Service Engineering:Maintenance of chemiluminescence optics and fluidic systems requires scarce technical expertise, constraining deployment velocity for instrument makers.
- Legacy Middleware Integration:New analyzers must interface with entrenched laboratory information systems across heterogeneous hospital IT environments, complicating rollout timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Immunoassay Analyzers Market |
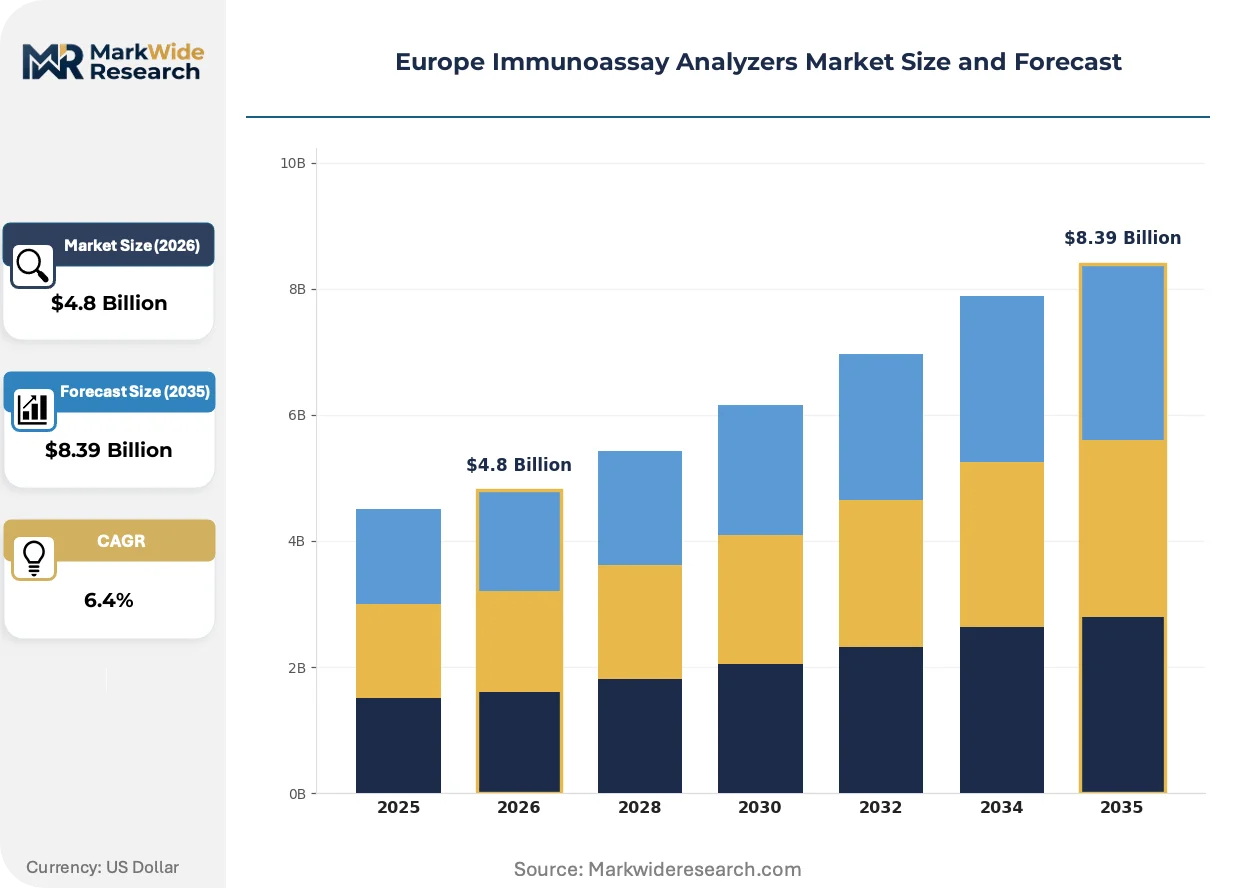
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: ELISA, Chemiluminescence, Radioimmunoassay, Fluorescent Immunoassay End User: Hospitals, Diagnostic Laboratories, Research Institutions, Clinics Technology: Microplate, Point-of-Care, Automation, Lateral Flow Application: Oncology, Infectious Diseases, Cardiovascular, Hormonal Disorders |
| Companies Covered | Siemens Healthineers, bioMérieux SA, Abbott Laboratories, Danaher Corporation, F. Hoffmann-La Roche AG, Thermo Fisher Scientific, Ortho Clinical Diagnostics, Sysmex Corporation, Bio-Rad Laboratories, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Immunoassay Analyzers Market Strategic Shifts & Innovations
Digital pathology integration and AI-assisted result interpretation are reshaping workflow architectures, while regulatory data requirements push manufacturers toward closed-system reagent strategies.
Chemiluminescence detection technology with enhanced signal-to-noise ratios is supplanting colorimetric and fluorescence methods in cardiac marker applications. High-volume clinical laboratories in Germany are adopting these platforms for troponin testing protocols. The shift is compressing competitive differentiation around sensitivity specifications and locking customers into proprietary reagent ecosystems.
EMA's IVDR framework tightens clinical evidence requirements for Class C and D devices, mandating expanded post-market surveillance infrastructure. Manufacturers must now maintain systematic performance data collection across installed bases. This disproportionately affects oncology biomarker assay developers, who are restructuring quality management systems to meet documentation burdens.
Diagnostic procurement directors are consolidating vendor relationships to reduce qualification overhead and streamline service contracting. Multi-year reagent rental agreements with bundled maintenance are displacing capital purchase models in French hospital networks. This concentration is most visible in the Ile-de-France region, where public hospital groups negotiate system-wide analyzer placements.
Europe Immunoassay Analyzers Market Segmentation
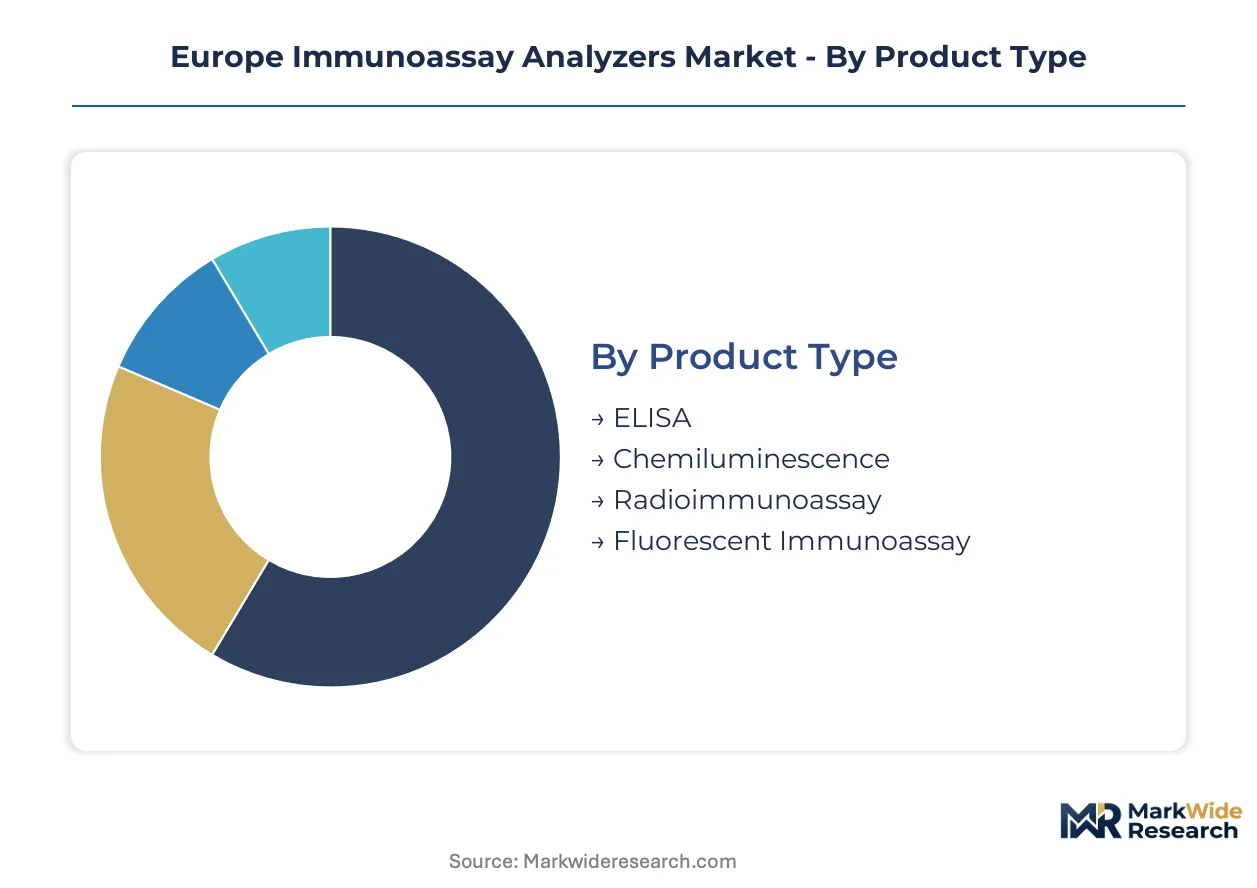
Segmentation reveals how procurement channels fragment across centralized laboratory networks versus decentralized clinic infrastructure. Channel-mix dynamics determine which analyzer configurations achieve scale in Germany's hospital systems versus France's public laboratory consortia.
Product Type:
Channel-mix patterns show chemiluminescence systems dominating German hospital procurement through bundled reagent contracts, while ELISA platforms persist in research procurement channels with lower automation requirements.
- Chemiluminescence:High-sensitivity detection systems achieve sub-picogram thresholds for cardiac troponin protocols. Demand concentrates in French and German centralized laboratories seeking throughput above 400 samples hourly to offset staffing constraints.
- ELISA:Enzyme-linked immunosorbent assay platforms retain cost advantages for lower-volume infectious disease panels. Research institutions in the Netherlands favor these systems for cytokine research where batch flexibility outweighs speed requirements.
- Radioimmunoassay:Specialized endocrinology applications in Swiss and Austrian reference laboratories maintain residual demand despite declining installed base.
- Fluorescent Immunoassay:Multiplex detection capabilities serve oncology biomarker profiling in academic medical centers.
Chemiluminescence dominates installed base. Fluorescent immunoassay is where expansion concentrates.
End User:
Customer-type segmentation exposes diverging automation maturity between consolidated hospital networks and fragmented clinic infrastructure.
- Diagnostic Laboratories:High-throughput automation lines process infectious disease and cardiac marker panels for regional health networks. France's Ile-de-France public hospital groups drive consolidation onto single-vendor platforms to reduce per-test operational costs.
- Hospitals:Emergency departments in Spain and Italy deploy point-of-care troponin analyzers to achieve sub-twenty-minute turnaround times for chest pain protocols.
- Research Institutions:Multiplex cytokine profiling platforms support immunotherapy monitoring in Dutch and Belgian academic centers.
- Clinics:Smaller diagnostic volumes favor compact analyzers with reduced reagent consumption in Southern European primary care networks.
Diagnostic laboratories dominate installed base. Clinics are where expansion concentrates.
Technology:
Technology segmentation tracks the shift from batch-processing microplate systems toward continuous-flow automation and decentralized point-of-care deployment.
- Automation:Random-access analyzers with continuous loading capabilities serve high-volume laboratories in Germany seeking overnight unattended operation. These systems command premium positioning through reduced labor cost per reportable result.
- Point-of-Care:Handheld and compact benchtop devices enable decentralized D-dimer and troponin testing in Italian and Spanish emergency departments bypassing central laboratory queues.
- Microplate:Batch-processing architectures retain cost efficiency for research applications with variable assay menus.
- Lateral Flow:Qualitative screening applications persist in resource-constrained settings despite limited quantitative capability.
Automation dominates installed base. Point-of-Care is where expansion concentrates.
Application:
Application segmentation reflects disease burden priorities and reimbursement structures across European health systems.
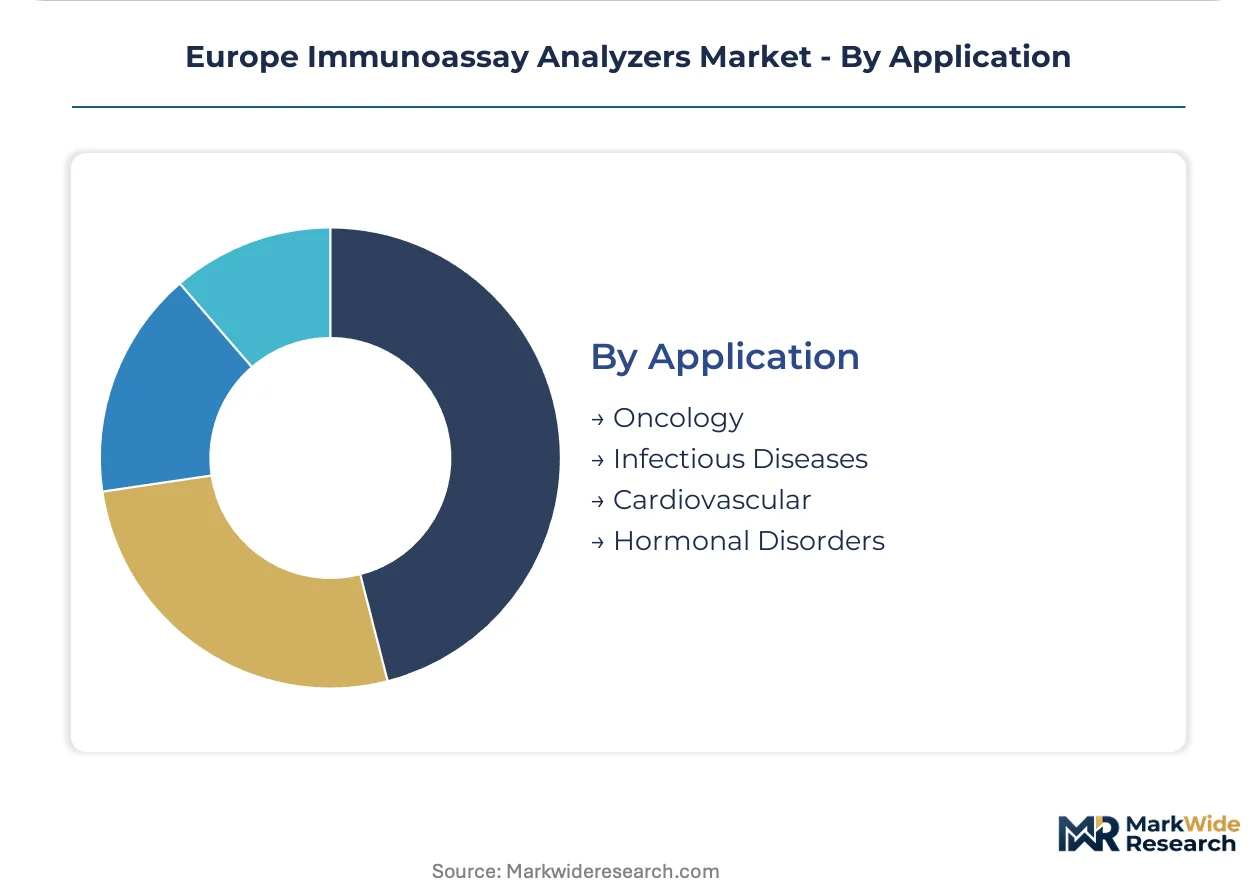
- Infectious Diseases:Respiratory and sepsis panel mandates from European health ministries expand multiplex analyzer demand. German laboratories prioritize syndromic testing platforms for rapid pathogen identification.
- Oncology:Biomarker profiling for immunotherapy monitoring drives high-plex platform adoption in Netherlands and Belgium research institutions. EMA's IVDR documentation burdens disproportionately affect this segment's assay development timelines.
- Cardiovascular:High-sensitivity troponin protocols mandate chemiluminescence sensitivity thresholds in French and German emergency departments.
- Hormonal Disorders:Endocrinology panels maintain steady demand through reference laboratory networks in Switzerland and Austria.
Infectious diseases dominates installed base. Oncology is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Europe's immunoassay analyzer trade flows reveal a net import dependency for high-sensitivity detection components, with Germany and France driving intra-regional demand while Swiss and Dutch facilities specialize in reagent exports. Southern European markets remain penetration opportunities for decentralized testing platforms.
Germany
Hospital network consolidation across Bavaria and North Rhine-Westphalia accelerates high-throughput chemiluminescence procurement. KBA notified body capacity constraints extend IVDR certification timelines for new assay kits. The Munich-Stuttgart corridor anchors captive bioreagent manufacturing for vertically integrated instrument makers.
France
Ile-de-France public hospital groups negotiate system-wide analyzer placements through multi-year reagent rental agreements. ANSM coordinates with EMA on IVDR transition deadlines, creating procurement urgency for pre-certified platforms. The Lyon-Grenoble cluster specializes in infectious disease panel development for syndromic testing protocols.
Netherlands
Academic medical centers in Amsterdam and Rotterdam drive multiplex cytokine profiling adoption for immunotherapy monitoring. REACH compliance requirements shape reagent chemical sourcing strategies for enzyme conjugates. The Eindhoven-Tilburg corridor concentrates microfluidics research for next-generation point-of-care devices.
Italy
Emergency departments in Lombardy and Lazio deploy compact troponin analyzers to achieve sub-twenty-minute turnaround times for chest pain protocols. Regional health ministry mandates expand respiratory panel testing requirements. The Milan-Bologna axis serves as distribution hub for Southern European decentralized clinic networks.
Switzerland
Reference laboratories in Zurich and Basel maintain specialized endocrinology and radioimmunoassay applications for premium diagnostic segments. Swissmedic alignment with EMA IVDR frameworks streamlines cross-border kit certification for Alpine region hospitals. The Basel biotech corridor anchors oncology biomarker assay development.
Europe Immunoassay Analyzers Market Key Industry Players
Concentration sits with diversified health technology conglomerates that leverage captive reagent production and established hospital system relationships. The vendor base stratifies across three tiers: vertically integrated instrument-reagent platforms, specialized microbiology menu providers, and compact point-of-care specialists. Dominant competitive moves include backward integration into enzyme conjugate manufacturing and strategic partnerships with diagnostic laboratory consortia for long-term reagent supply contracts.
Among Germany-based diversified health technology groups, Siemens Healthineers exemplifies the vertically integrated archetype through in-house bioreagent production. French specialist bioMérieux SA occupies a position within the microbiology-focused tier. Abbott Laboratories represents the point-of-care expansion archetype with compact platform development for decentralized networks.
| Leading Market Players |
|---|
| Siemens Healthineers |
| bioMérieux SA |
| Abbott Laboratories |
| Danaher Corporation |
| F. Hoffmann-La Roche AG |
| Thermo Fisher Scientific |
| Ortho Clinical Diagnostics |
| Sysmex Corporation |
| Bio-Rad Laboratories |
| Others |
Cost & Logistics Intelligence
EMA's IVDR certification regime gates both supply qualification and price differentiation simultaneously, forcing manufacturers to absorb compliance costs into premium-tier positioning while laboratories face reagent lock-in penalties for non-certified platforms. The resulting cost structure stratifies procurement budgets across German hospital networks versus Southern European mid-sized laboratories.
Pricing Analysis
The customization-premium spread separates configured-to-order chemiluminescence systems from standard ELISA platforms by a substantial margin. Contract-based long-term reagent rental agreements dominate French hospital procurement, with price differentiation anchored in IVDR certification tier and bundled field service coverage. Cost compression in economy-tier analyzers is intensifying because Spanish and Italian clinics prioritize capital expenditure minimization over sensitivity specifications. Mid-sized diagnostic laboratories in Southern Europe exhibit highest price sensitivity, while German university hospital networks accept premium positioning for throughput guarantees.
Supply Chain Analysis
Enzyme conjugate manufacturing clusters in Southern Germany create a chokepoint for detection chemistry inputs across the European installed base. Captive bioreagent production in Germany, Switzerland, and the Netherlands draws from specialized fermentation capacity and precision optics foundries. Single-source vulnerability concentrates in monoclonal antibody supply for oncology assay menus. Distribution runs through instrument-reagent bundled contracts negotiated directly with hospital procurement consortia rather than through independent distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized field service engineering capability represents the critical scarcity asset in this market, constraining deployment velocity and locking in incumbent advantages through technician certification networks. Laboratories cannot absorb analyzer downtime, making responsive maintenance infrastructure the decisive competitive moat.
For Market Incumbents: Fortify captive bioreagent production capacity in the Munich-Stuttgart corridor to preempt supply disruption risks from REACH compliance tightening. Expand IVDR-certified assay menus ahead of transition deadlines to capture risk-averse laboratory directors seeking uninterrupted service contracts. Prioritize field service engineering pipelines through apprenticeship partnerships with German technical universities. For New Entrants and Emerging Players: Differentiate on compact point-of-care platforms for Italian and Spanish emergency departments where sub-twenty-minute turnaround protocols create procurement urgency. Target Southern European clinic networks with reduced reagent consumption analyzers, exploiting underpenetration in decentralized testing infrastructure. Pursue direct distribution partnerships with regional health ministries rather than competing for consolidated German hospital network contracts. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across multiplex cytokine profiling platforms as research institutions demand higher-plex capabilities. Long-term viability favors vertically integrated instrument-reagent platforms with established IVDR documentation systems over pure-play device manufacturers. Monitor notified body capacity allocation between Germany's KBA and France's ANSM as an inflection indicator for certification timeline risk.| Strategic Initiative | Industry Significance |
|---|---|
| IVDR Early Certification Pathway | CE-IVDR compliance ahead of deadlines captures locked-in procurement from risk-averse French laboratory directors. |
| Backward Integration into Enzyme Conjugate Manufacturing | In-house production of detection chemistry reduces single-source vulnerability from Southern German supply clusters. |
| Hospital System Partnership Agreements | Multi-year reagent rental contracts with Ile-de-France public hospital groups displace capital purchase models. |
| Compact Point-of-Care Platform Development | Handheld troponin analyzers penetrate Italian and Spanish emergency departments bypassing central laboratory queues. |
| Multiplex Cytokine Profiling Expansion | High-plex platforms serve Dutch academic medical centers monitoring immunotherapy response biomarkers. |
Research Approach
The analysis maps chemiluminescence systems, ELISA platforms, point-of-care devices, and multiplex research instruments, each validated through laboratory procurement directors, biomedical engineers, regulatory affairs specialists, and GPO contracts managers. Primary interviews with hospital purchasing committees and diagnostic laboratory directors combined with secondary validation from EMA IVDR submission databases, notified body capacity reports, and hospital procurement databases. Bottom-up instrument shipment tracking and top-down healthcare expenditure triangulation anchored market sizing.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, end-user channel, automation technology, and application segmentation dimensions. CAGRs derived from installed base replacement cycles, IVDR transition deadline pull-forward effects, and laboratory automation investment trajectories. Forecast inputs incorporated chemiluminescence sensitivity specification evolution and respiratory panel testing mandate expansion.
Material uncertainties — IVDR certification timeline delays, enzyme conjugate supply disruptions, and regional health ministry budget reallocations — sit outside the modeled envelope. Forecasts reflect assumptions regarding notified body capacity expansion and reagent chemical sourcing stability. Practitioners should keep alternative scenarios live as EMA transition deadline enforcement and REACH compliance stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Immunoassay Instruments Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Hair Mineral Analyzer Market
Diagnostic Instruments
Platelet Aggregation Devices Market
Diagnostic Instruments
Point-of-Care Diagnostic Analyzer Accuracy and Interference Test Equipment Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Nasometry Devices Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Lower GI Series Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Pathological Examination Market
Diagnostic Instruments
Global Wavefront Aberrometers Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market