
 Polygraph Instrument (Lie Detector) Market | 2026-2036
Polygraph Instrument (Lie Detector) Market Size, Share, and Industry Trends Forecast 2026-2036
Polygraph Instrument (Lie Detector) Market Insights
EU AI Act scrutiny of algorithmic credibility assessment tools is realigning the cost-of-entry calculus for European vendors. Limestone Technologies leverages its North American installed base to sustain aftermarket revenue from law enforcement agencies. Lafayette Instrument Company anchors its position through deep specialization in analog-to-digital upgrade pathways. Converus competes via proprietary eye-detection technology that differentiates its offering from conventional galvanic skin response systems.
A polygraph instrument measures physiological responses including respiration rate, galvanic skin resistance, cardiovascular activity, and relative blood pressure to assess veracity during controlled questioning sessions. These devices employ pneumatic rubber tubes, finger electrodes, and cardio cuffs transduced through hydraulic or electronic sensors into computerized recording systems for forensic and security screening purposes. Digital polygraph systems now dominate new procurement as agencies replace aging analog chart recorders, while software integration capabilities increasingly determine vendor selection in criminal investigation applications. Portable polygraph units represent the fastest-growing product configuration, driven by field-deployable requirements from military and private investigator end users who operate outside fixed laboratory environments.
FDA oversight of medical-grade sensor components, FCC certification for wireless data transmission modules, and ISO 13485 quality management standards collectively shape product development timelines and international market access for manufacturers. NHTSA guidelines on employee screening protocols influence procurement specifications for transportation sector polygraph deployments. Stakeholders must monitor evolving admissibility standards for polygraph evidence across federal and state court systems, as judicial acceptance directly determines replacement demand from law enforcement budgets.
Market Dynamics
Digital polygraph systems with integrated software platforms are displacing analog chart recorders across law enforcement procurement cycles, compressing vendor margins on hardware while expanding recurring revenue from analytics subscriptions and cloud-based case management tools.
Growth Catalysts
- EU AI Act compliance pathways:European vendors investing in algorithmic transparency documentation gain preferential access to security agency tenders across Germany, France, and the Netherlands.
- Field-deployable military requirements:Portable polygraph units with battery-operated sensors and ruggedized housings address expeditionary screening needs from defense departments operating in contested environments.
- Transportation sector screening mandates:NHTSA guidelines for commercial driver vetting sustain replacement demand from logistics companies and public transit authorities in the United States.
Market Restraints
- Judicial admissibility fragmentation:Polygraph evidence remains excluded from federal criminal proceedings under Daubert standards, limiting law enforcement budget justification for equipment upgrades.
- Sensor component supply concentration:Medical-grade pneumatic transducers and precision cardio cuffs source primarily from specialized German and Japanese component manufacturers.
- Alternative credibility assessment tools:Voice stress analysis and ocular-motor deception detection systems compete for the same security screening budgets with lower per-test operational costs.
Strategic Opportunities
- Private security sector penetration:Corporate espionage investigations and executive screening protocols in China create demand outside traditional government channels.
- Convergence with biometric identity systems:Integration of polygraph data with fingerprint and facial recognition databases enables unified screening workflows for border control applications.
- ISO 13485 certification acceleration:Quality management standardization opens medical-adjacent markets including clinical psychology research and pharmaceutical trial integrity monitoring.
Industry Challenges
- Forensic examiner certification bottlenecks:Polygraph operator training programs require 400+ supervised examinations before independent credentialing, constraining deployment velocity for new equipment installations.
- Legacy analog-to-digital migration complexity:Agencies with decades of archived chart recordings face data format incompatibility when upgrading to computerized systems, requiring expensive transcription services or parallel record-keeping.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Polygraph Instrument (Lie Detector) Market |
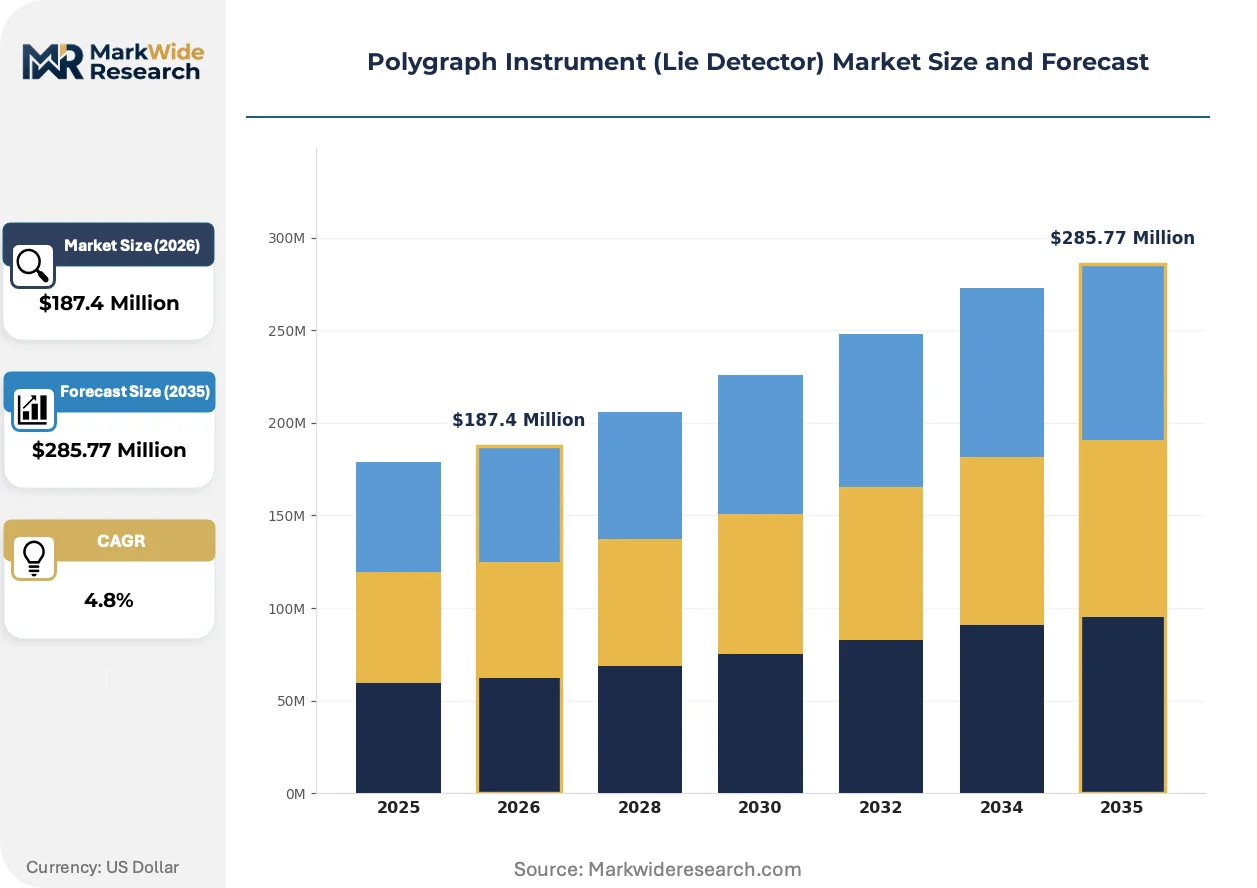
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog Polygraph, Digital Polygraph, Portable Polygraph, Webcam Polygraph End User: Law Enforcement, Private Investigators, Employment Screening, Military Technology: Hydraulic Sensors, Electronic Sensors, Computerized Systems, Software Integration Application: Criminal Investigation, Pre-Employment Screening, Fraud Detection, Security Assessments |
| Companies Covered | Limestone Technologies, Nihon Kohden, Lafayette Instrument Company, Beijing Tongfang Shenhuo, Bear Forensics, Stoelting, Converus, Diogenes Ltd., Axciton Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Polygraph Instrument (Lie Detector) Market Trends and Innovations
Software-defined sensor architectures and artificial intelligence-assisted response interpretation are transforming how credibility assessments are conducted, stored, and defended in legal proceedings. These developments compress the expertise required to operate equipment while raising new questions about algorithmic accountability.
Cloud-based polygraph platforms with remote monitoring capabilities are expanding into private sector security operations and cross-border law enforcement collaboration frameworks. Corporate risk management departments and international investigative agencies adopt these systems to conduct screenings without transporting subjects to fixed laboratory facilities. This expansion into distributed deployment models is compressing the addressable market for traditional benchtop instruments while creating subscription revenue pools that hardware-centric vendors struggle to capture.
EU AI Act algorithmic impact assessments now govern the deployment of automated credibility scoring tools across European Union member states. Manufacturers must document training data provenance, bias testing protocols, and human oversight mechanisms before securing public sector contracts. French national police and German federal criminal police office procurement specifications now embed these requirements as mandatory technical criteria, forcing non-European vendors to establish local compliance engineering functions.
Law enforcement agencies increasingly unbundle equipment purchases from examiner training and ongoing quality assurance services. State-level police departments in the United States negotiate directly with regional training academies rather than accepting vendor-bundled certification programs. This disintermediation is most visible in Texas, Florida, and California where large agency consortiums have established independent procurement frameworks for polygraph services, pressuring manufacturers to decouple hardware margins from service revenue streams.
Polygraph Instrument (Lie Detector) Market Segmentation
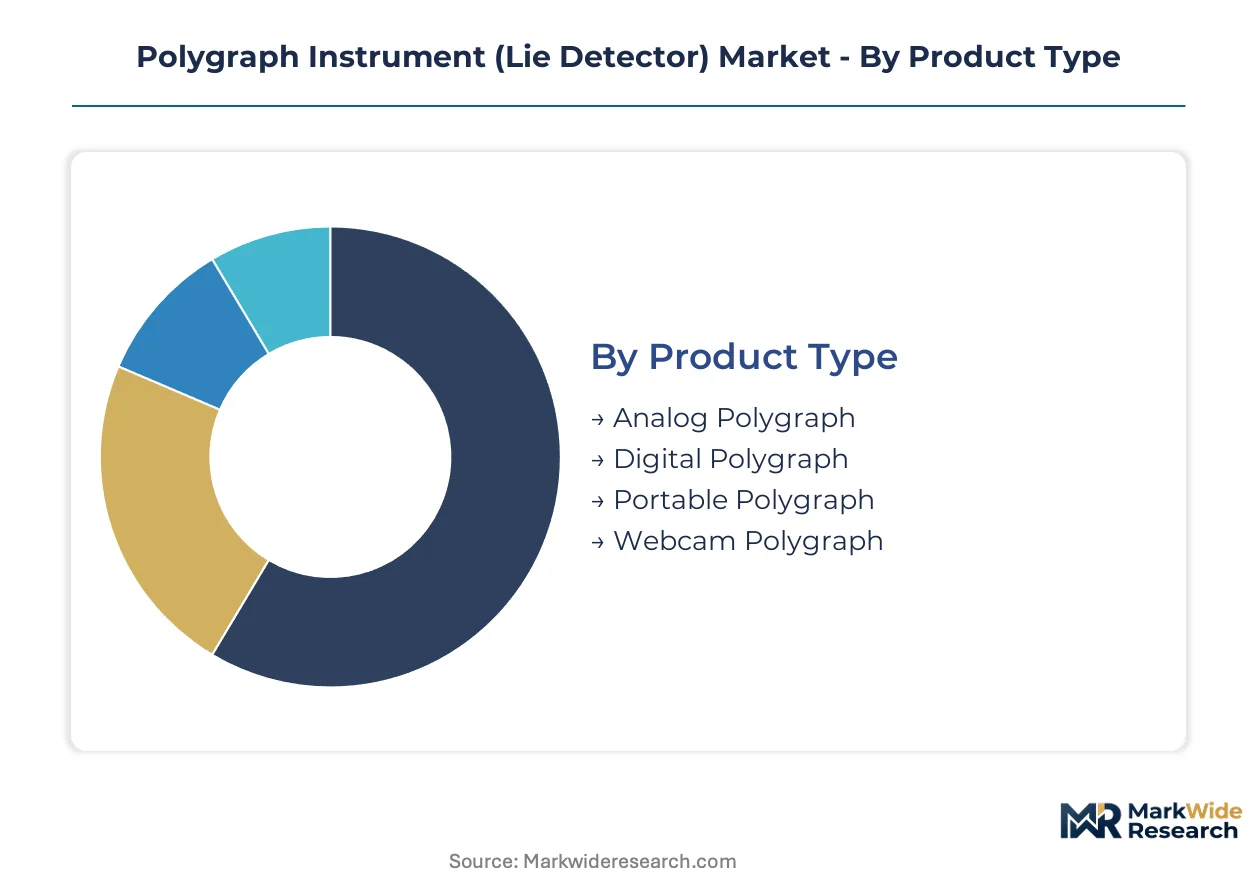
Procurement patterns across the polygraph instrument market diverge sharply between fixed laboratory installations and field-deployable configurations. Vendor selection criteria increasingly weight software integration depth over hardware specifications as agencies modernize credibility assessment workflows.
Product Type:
Standalone benchtop systems dominate institutional procurement while embedded sensor modules gain traction in mobile screening applications.
- Digital Polygraph:Computerized recording systems with multi-channel physiological monitoring replace aging analog chart recorders in federal and state law enforcement facilities. United States police departments concentrate replacement demand here, driven by evidence admissibility requirements and digital archiving mandates.
- Portable Polygraph:Battery-operated units with ruggedized housings and wireless data transmission enable expeditionary screening outside fixed laboratory environments. Military end users in contested operational theaters generate fastest expansion as defense departments prioritize field-deployable credibility assessment.
- Analog Polygraph:Pneumatic-mechanical chart recorders with ink stylus output persist in budget-constrained agencies and training academies.
- Webcam Polygraph:Remote credibility assessment platforms leveraging ocular-motor and micro-expression analysis without physical sensor attachment.
Volume placements concentrate in Digital Polygraph; the faster expansion belongs to Portable Polygraph.
End User:
Public sector procurement cycles sustain baseline demand while private sector adoption creates incremental volume pools outside government channels.
- Law Enforcement:Municipal, state, and federal police agencies conduct criminal interrogations and witness credibility assessments using standardized equipment protocols. China and Germany sustain equipment refresh cycles through centralized government security spending.
- Employment Screening:Corporate security departments and background investigation firms deploy polygraph protocols for executive vetting and integrity verification. Chinese corporate espionage investigations drive fastest segment expansion as private sector screening protocols expand beyond traditional government channels.
- Military:Defense intelligence and counterintelligence units operate polygraph screening for security clearance adjudication and detainee interrogation.
- Private Investigators:Individual practitioners and small agencies conduct civil litigation support and domestic case investigations.
Law Enforcement commands the dominant placement volume; Employment Screening is climbing the fastest.
Technology:
Sensor transduction methods determine equipment cost structures while software layers increasingly capture recurring revenue streams.
- Software Integration:Cloud-based case management platforms with AI-assisted response interpretation and remote monitoring capabilities transform how examinations are conducted and documented. United States agencies lead adoption as examiner training disintermediation accelerates demand for standardized analytics tools.
- Electronic Sensors:Solid-state transducers for galvanic skin resistance, cardio activity, and respiration rate provide digital signal output directly to computerized recording systems. German component manufacturers supply precision pneumatic transducers that constrain supply availability.
- Computerized Systems:Integrated hardware-software platforms combining sensor acquisition, real-time visualization, and automated scoring algorithms.
- Hydraulic Sensors:Fluid-filled pressure transducers for cardiovascular and respiratory measurement in legacy analog configurations.
Electronic Sensors anchor current placement volume; Software Integration shows the steepest expansion trajectory.
Application:
Forensic admissibility standards differentiate procurement specifications between criminal justice and administrative screening contexts.
- Criminal Investigation:Controlled questioning sessions for suspect interrogation and witness verification where evidence standards govern equipment calibration and operator certification requirements. United States federal and state court admissibility fragmentation constrains budget justification for equipment upgrades.
- Pre-Employment Screening:Integrity verification protocols for security-sensitive positions in transportation, government contracting, and financial services. NHTSA guidelines for commercial driver vetting sustain replacement demand from United States logistics companies and public transit authorities.
- Fraud Detection:Corporate internal investigations and insurance claim verification using polygraph protocols as part of broader forensic accounting procedures.
- Security Assessments:Ongoing personnel reliability programs and counterintelligence screening for cleared personnel in defense and intelligence agencies.
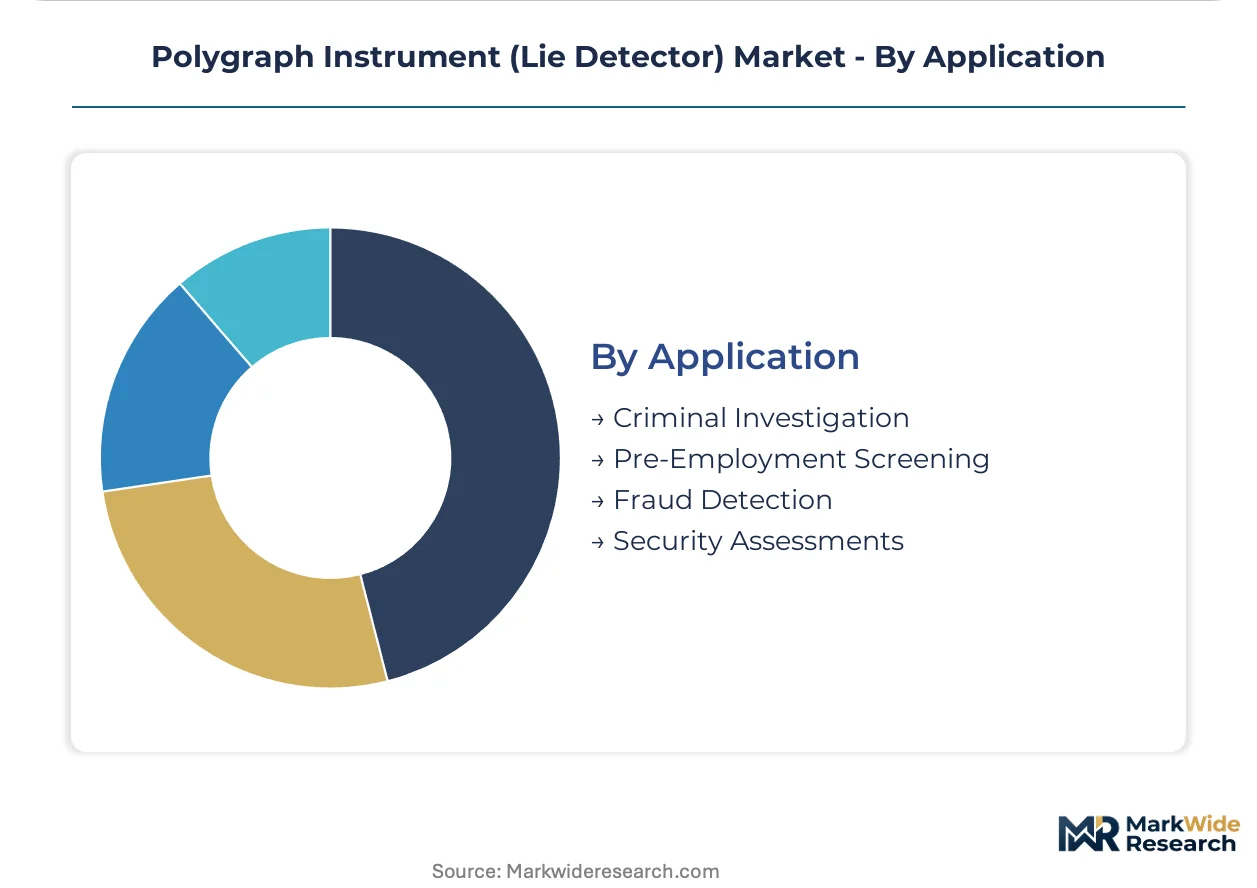
Criminal Investigation retains the largest placement base; Pre-Employment Screening is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States federal and state law enforcement agencies generate the dominant procurement volume for digital polygraph systems, while Chinese government security spending and German federal police modernization sustain concentrated demand clusters in those markets.
United States
Federal Bureau of Investigation and state-level police departments drive equipment refresh cycles for computerized recording systems. NHTSA guidelines for commercial driver vetting sustain replacement demand from logistics companies and public transit authorities. Texas, Florida, and California host large agency consortiums that have established independent procurement frameworks for polygraph services.
China
Centralized government security spending supports equipment acquisition for criminal investigation and corporate espionage screening protocols. The country's national security apparatus mandates standardized credibility assessment tools across provincial law enforcement hierarchies. Beijing and Shanghai concentrate manufacturing and procurement activity for domestic polygraph system producers.
Germany
Federal Criminal Police Office procurement specifications embed EU AI Act algorithmic impact assessment requirements as mandatory technical criteria. German federal police modernization programs sustain replacement demand for analog-to-digital upgrade pathways. Precision pneumatic transducer manufacturers in Baden-Württemberg constrain component supply availability for international vendors.
Japan
Ministry of Defense counterintelligence units generate demand for portable polygraph units with battery-operated sensors for expeditionary screening applications. METI standards influence domestic equipment certification protocols for security-sensitive deployments. Tokyo and Osaka metropolitan police departments anchor institutional procurement for fixed laboratory installations.
United Kingdom
National Crime Agency and metropolitan police services conduct criminal interrogations using standardized equipment protocols subject to judicial admissibility constraints. The country's national forensic regulator oversees examiner certification standards that influence training program specifications. London concentrates private security sector adoption for corporate executive vetting applications.
Polygraph Instrument (Lie Detector) Market Competitive Landscape
North American producers anchor one tier; European and Asian specialists hold differentiated positions through component supply and regional compliance engineering. The vendor base clusters around three strategic archetypes: legacy analog-to-digital migration specialists, software-integrated platform developers, and portable field-deployable unit fabricators. Competitive moves concentrate on geographic expansion into private security channels and technology licensing for biometric identity system convergence.
Within the legacy equipment tier, Lafayette Instrument Company occupies a position representing deep specialization in analog-to-digital upgrade pathways. Among North American software-integrated developers, Limestone Technologies exemplifies the installed-base aftermarket revenue model for law enforcement agencies. Converus sits within the alternative technology vector, representing proprietary eye-detection differentiation from conventional galvanic skin response systems.
| Leading Market Players |
|---|
| Limestone Technologies |
| Nihon Kohden |
| Lafayette Instrument Company |
| Beijing Tongfang Shenhuo |
| Bear Forensics |
| Stoelting |
| Converus |
| Diogenes Ltd. |
| Axciton Systems |
| Others |
Pricing and Supply Chain Analysis
EU AI Act algorithmic impact assessment documentation gates qualified supply for European public sector tenders while simultaneously filtering vendor access to premium-tier pricing brackets. Manufacturers lacking transparent training data provenance and bias testing protocols face exclusion from German federal police and French national police procurement cycles, compressing their addressable market to private security channels with lower price realization.
Pricing Analysis
Short lead-time premiums command pricing separation from standard fulfillment windows, with expeditionary military orders and urgent law enforcement replacements absorbing material uplifts. Three-tier pricing structure across premium certified systems, standard digital platforms, and economy analog configurations stratifies the market, with ISO 13485 quality management certification and FCC wireless module approval serving as the primary price differentiation drivers. Cost compression in the standard tier is intensifying because software-integrated platforms displace hardware-centric revenue models. Municipal police departments exhibit the highest price sensitivity due to constrained capital budgets, while defense intelligence units demonstrate the lowest sensitivity given mission-critical deployment requirements.
Supply Chain Analysis
Direct-to-government agency channels handle hyperscale procurement from federal law enforcement and defense departments, while authorized distributors serve smaller municipal police and private investigator segments. Component manufacturing concentrates in Germany and Japan, where precision pneumatic transducers and medical-grade cardio cuffs originate from specialized suppliers in Baden-Württemberg and Osaka prefecture. Solid-state electronic sensors for galvanic skin resistance and respiration monitoring draw from Taiwanese semiconductor fabrication and South Korean sensor packaging operations. Single-source vulnerability in German pneumatic transducer supply creates procurement risk for vendors seeking rapid scaling. Distribution runs through manufacturer-direct field sales teams for institutional accounts, supplemented by regional security equipment distributors for training academy and private sector placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The polygraph instrument market sits in a technology-transition phase, with software-defined sensor architectures and AI-assisted response interpretation displacing conventional galvanic skin response systems. This shift compresses hardware margins while expanding recurring revenue pools from analytics subscriptions and cloud-based case management tools.
For Market Incumbents: Cement installed-base retention through aggressive analog-to-digital upgrade financing programs that lock law enforcement agencies into proprietary software ecosystems. Deepen backward integration into precision pneumatic transducer supply by acquiring German component specialists or establishing captive production facilities, defending against supply concentration risk while capturing margin from sensor manufacturing. Prioritize EU AI Act compliance engineering investments to maintain access to German and French federal procurement specifications as algorithmic transparency mandates harden.
For New Entrants and Emerging Players: Begin with private security sector penetration in China, where corporate espionage investigations and executive screening protocols create demand outside saturated government channels. Target employment screening applications in United States logistics companies and public transit authorities, where NHTSA commercial driver vetting guidelines sustain replacement demand with lower certification barriers than criminal investigation contexts. Pursue biometric identity system convergence partnerships as the primary go-to-market angle, integrating polygraph data streams with fingerprint and facial recognition database workflows for unified border control screening solutions.
For Investors and Strategic Acquirers: Large agency consortium procurement framework announcements in Texas, Florida, and California are the leading indicator that examiner training disintermediation is accelerating demand for standardized analytics tools independent of vendor-bundled certification programs. The market presents long-term viability through software subscription revenue pools that hardware-centric vendors struggle to capture, with quality management standardization opening medical-adjacent markets including clinical psychology research. Target acquisition candidates with established ISO 13485 certification and cloud platform deployment capabilities, avoiding pure hardware manufacturers dependent on transactional equipment sales.
| Strategic Initiative | Industry Significance |
|---|---|
| Software Platform Integration | Cloud-based case management with AI-assisted response interpretation transforms examination workflows for United States agencies. |
| EU AI Act Compliance Engineering | Algorithmic transparency documentation secures preferential access to German federal police and French national police tenders. |
| Portable Unit Development | Battery-operated ruggedized systems address expeditionary screening requirements from defense departments in contested environments. |
| Biometric System Convergence | Integration with fingerprint and facial recognition databases enables unified screening workflows for border control applications. |
| ISO 13485 Certification Acceleration | Quality management standardization opens medical-adjacent markets including clinical psychology research and pharmaceutical trial monitoring. |
Research Methodology
Multi-period observation of equipment procurement cycles, examiner certification program completions, and judicial admissibility standard evolutions anchored the trend analysis, supplemented by interviews with polygraph equipment manufacturers, federal law enforcement procurement officers, forensic examiner training academy directors, and private security sector risk management executives. Secondary validation drew from FDA medical device filings, FCC wireless certification databases, federal court admissibility rulings, and ISO 13485 registrar audit records. Bottom-up triangulation across vendor shipment records and top-down reconciliation against government security spending appropriations ensured methodological consistency.
Input-output matrices mapped sensor component supply availability against end-user procurement specifications across product type, end user, technology, and application dimensions over the projection horizon. CAGRs were derived from regression analysis of historical replacement cycles and projected refresh demand from military field-deployable requirements and transportation sector screening mandates. Forecast inputs incorporated EU AI Act implementation timelines and NHTSA guideline revision trajectories affecting commercial driver vetting protocols.
Underlying measurement precision varies by segment; digital polygraph and portable polygraph categories carry tighter precision than legacy analog configurations given clearer shipment tracking through government procurement databases. Forecasts reflect assumptions regarding sustained federal security spending levels and stable judicial admissibility standards, with periodic stress-testing of base assumptions recommended given regulatory uncertainty around algorithmic credibility assessment tools.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Diagnostic Instruments
Diagnostic Electrocardiograph Market
Diagnostic Instruments
Dental Fluorescence Analyzer Market
Diagnostic Instruments
Ultrasound-Guided Breast Biopsy Market
Diagnostic Instruments
US Medical Thermometer Market
Diagnostic Instruments
Luminometers Market
Diagnostic Instruments
Tympanometers Market
Diagnostic Instruments
Blood Flow Measurement Devices Market
Diagnostic Instruments
Vascular Testing Devices Market
Diagnostic Instruments
Trichoscope Devices Market
Diagnostic Instruments
Immunoassay Analyzers Market
Diagnostic Instruments
Auto Chemistry Analyzers Market
Diagnostic Instruments
Global Blood Gas and Electrolyte Analyzer Market
Diagnostic Instruments
Gastroesophageal Ph Meter Market
Diagnostic Instruments
Electroporation Instruments Market
Diagnostic Instruments
Genetic Analyzers Market
Diagnostic Instruments
Nasometry Devices Market