
 UK Imaging Services Market | 2026-2036
UK Imaging Services Market Size, Share, and Industry Trends Forecast 2026-2036
UK Imaging Services Market Intelligence
The gap between premium diagnostic networks and commodity imaging providers is shifting toward technology intensity and accreditation depth. Alliance Medical sustains one of the UK's largest fixed-site and mobile MRI fleets, giving it channel control across NHS contracts. InHealth Group specializes in community-based diagnostic centers, competing on accessibility rather than academic prestige. Medica Group dominates teleradiology reporting, extending its radiologist pool across overnight and emergency coverage for hospital trusts.
UK imaging services encompass the provision of diagnostic image acquisition, interpretation, and reporting using modalities operating at field strengths from 1.5 to 7 Tesla for MRI, tube voltages from 40 to 150 kVp for CT, and frequencies from 2 to 18 MHz for ultrasound, primarily to detect, monitor, or rule out disease in clinical pathways. MRI and CT scan segments command the deepest margin pools due to capital intensity and specialist radiologist scarcity, while ultrasound retains volume leadership in primary and maternity care. Digital imaging technology is displacing analog systems in NHS estate renewal programs, and remote imaging is expanding fastest through teleradiology platforms that decouple reporting from physical scanner location.
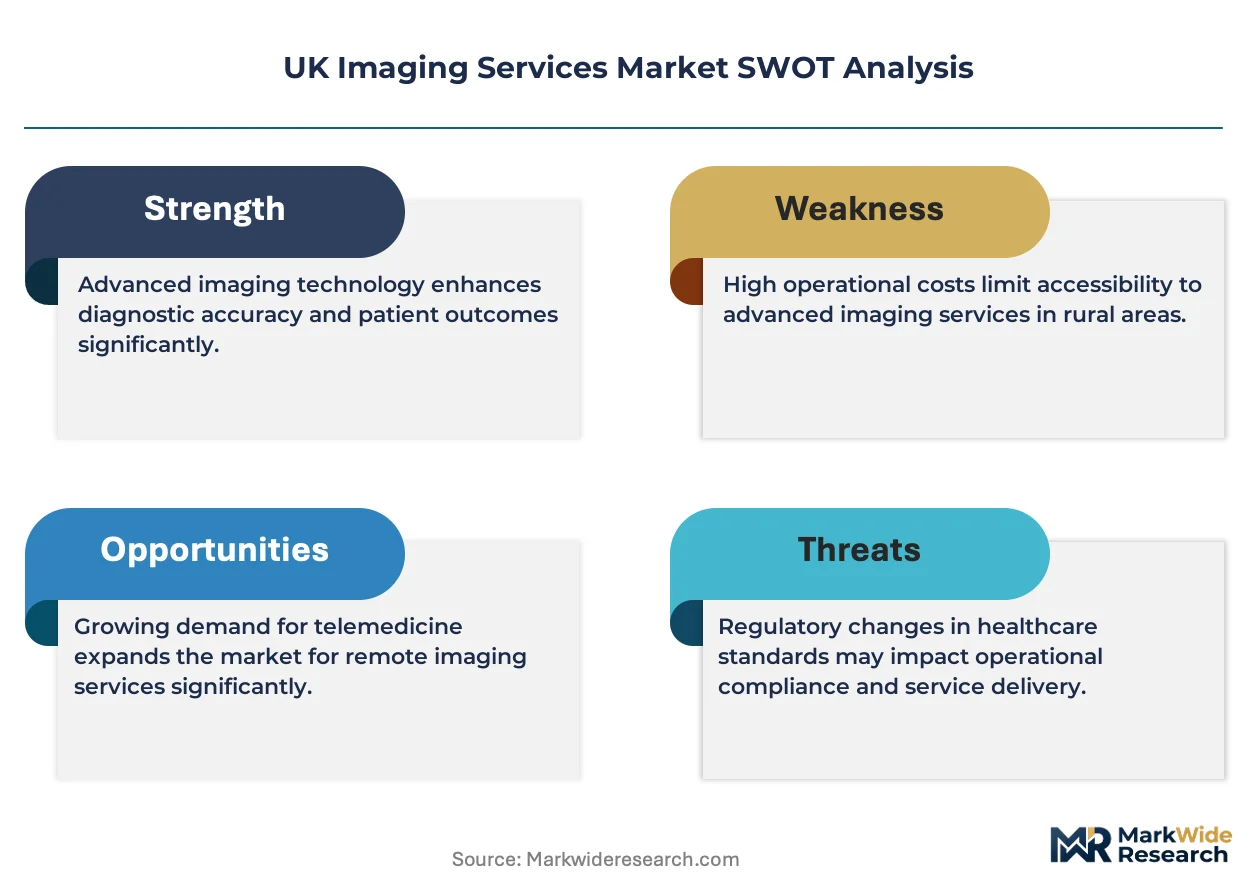
The Care Quality Commission enforces equipment performance and patient safety standards that shape capital replacement timelines across NHS and independent providers. MHRA regulation of medical device software governs AI-assisted diagnostic tools entering UK reporting workflows. NICE technology appraisals influence which advanced imaging applications gain reimbursement traction in oncology and cardiology pathways. Stakeholders must weigh the pace of AI validation against radiologist workforce constraints when planning service expansion or technology procurement.
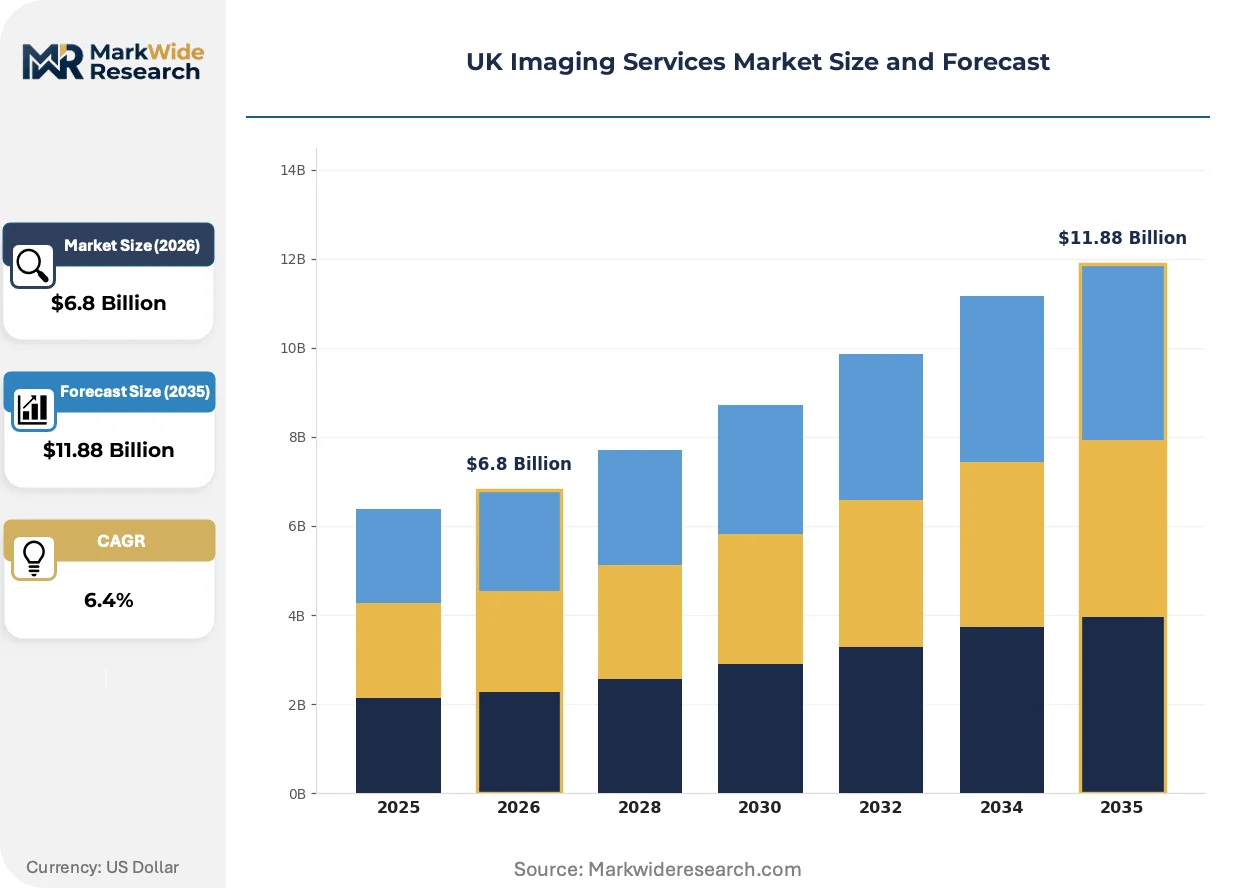
Market Dynamics
NHS hospital trusts are accelerating outsourced radiology partnerships to clear diagnostic backlogs, while the Care Quality Commission's stricter equipment safety standards force faster digital replacement cycles across independent and public providers.
Growth Catalysts
- Diagnostic Backlog Clearance Mandates:NHS England's elective recovery targets push hospital trusts toward teleradiology and mobile imaging fleets to reduce patient wait times for MRI and CT scans.
- AI-Assisted Reporting Validation:MHRA regulatory pathways for medical device software are creating clearer routes for machine-learning diagnostic tools to enter clinical workflows.
- Community Diagnostic Centre Expansion:Government capital funding for CDCs in England is concentrating new fixed-site imaging capacity in underserved urban peripheries and coastal towns.
Market Restraints
- Radiologist Workforce Scarcity:The Royal College of Radiologists reports persistent consultant vacancies that cap reporting throughput regardless of scanner capacity expansion.
- Capital Equipment Cost Concentration:MRI systems at 3 Tesla and above require £1-3 million per unit, constraining independent sector entrants without NHS contract guarantees.
- Reimbursement Rate Compression:NHS tariff pricing for standard imaging procedures limits margin expansion even as operational costs rise.
Strategic Opportunities
- Overnight and Emergency Reporting Gaps:Teleradiology platforms can capture unmet demand from trusts lacking 24/7 on-site specialist coverage.
- Cardiac and Oncologic AI Applications:NICE technology appraisals for advanced imaging in cancer staging and coronary artery disease create reimbursement tailwinds for validated algorithms.
- Mobile Fleet Penetration:Trailer-based MRI and CT units can reach rural Scotland, Wales, and Northern England where fixed-site density remains lowest.
Industry Challenges
- Legacy PACS Integration Complexity:Hospital trusts operate fragmented picture archiving systems that resist seamless connection to cloud-based reporting platforms.
- Radiographer Recruitment and Retention:Training pipeline bottlenecks and burnout rates in diagnostic imaging departments constrain service expansion timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UK Imaging Services Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, Ultrasound, CT Scan Technology: Digital Imaging, Analog Imaging, 3D Imaging, Remote Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Clinics Service Type: Routine Imaging, Emergency Imaging, Preventive Imaging, Therapeutic Imaging |
| Companies Covered | Siemens Healthineers, GE Healthcare, Koninklijke Philips, Alliance Medical, InHealth Group, Medica Group, Canon Medical Systems, Affidea Group, FUJIFILM, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UK Imaging Services Market Strategic Shifts & Innovations
Digital infrastructure is decoupling image acquisition from specialist interpretation, while regulatory frameworks accelerate validation timelines for AI-assisted diagnostics.
Photon-counting CT detector technology is electrifying diagnostic accuracy in cardiac and pulmonary imaging. NHS teaching hospitals in London and Manchester are piloting these systems for coronary plaque characterization. The shift is compressing the performance gap between academic medical centers and standard community hospitals.
The Care Quality Commission's 2023 updated ionising radiation regulations mandate dose optimization software and automated exposure controls across all new CT installations. Independent diagnostic chains must retrofit existing fleets or face registration restrictions. Oncology and paediatric imaging departments face the tightest compliance deadlines.
Hospital trusts are unbundling reporting from scanning contracts, creating spot-purchase markets for radiologist capacity. Teleradiology platforms and insourcing agencies compete for overnight and weekend coverage previously handled by on-call rotas. This fragmentation is most advanced in the Midlands and North West, where trust consolidation has outpaced specialist hiring.
UK Imaging Services Market Segmentation
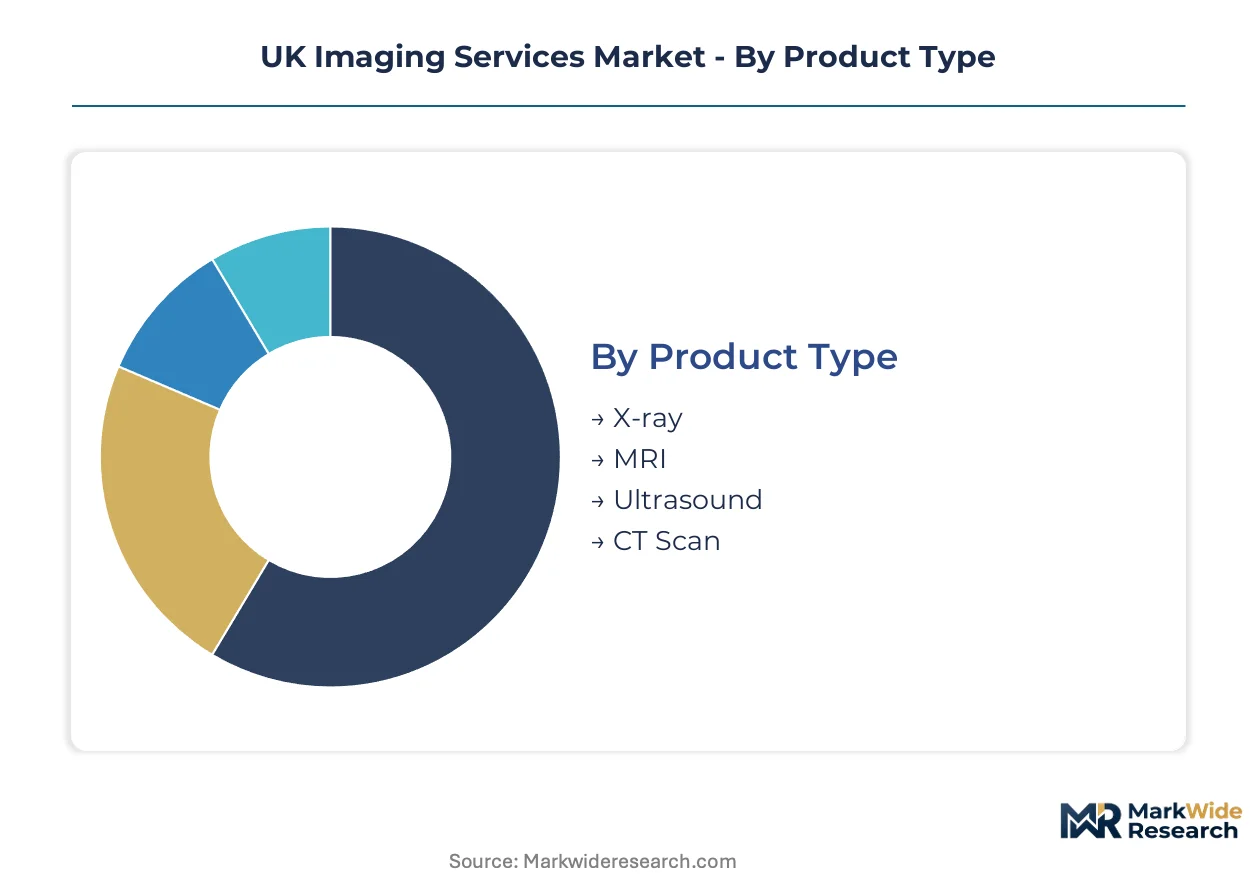
Segmentation in UK imaging services reveals how capital intensity, regulatory compliance, and workforce constraints fragment competitive positioning across modalities and delivery settings. Understanding these divisions exposes where margin pools concentrate and where NHS procurement patterns create volume anchors.
Product Type:
Volume leadership sits with legacy modalities, while premium margins cluster around capital-intensive systems requiring scarce specialist interpretation.
- MRI:Systems operate at 1.5 to 7 Tesla field strengths, demanding £1-3 million capital outlay per unit and consultant radiologist reporting capacity. Demand concentrates in London and South East England where private diagnostic networks achieve scale economies, constrained by Royal College of Radiologists workforce shortages that cap throughput regardless of scanner expansion.
- CT Scan:Tube voltages from 40 to 150 kVp enable cardiac, oncologic, and emergency applications with photon-counting detector technology now piloting in Manchester and London teaching hospitals. NHS England's elective recovery targets push trusts toward mobile CT fleets to clear diagnostic backlogs in Midlands and North West regions where fixed-site density lags.
- Ultrasound:Frequencies from 2 to 18 MHz dominate primary care and maternity pathways with lower capital barriers and radiographer-delivered service models.
- X-ray:Digital displacement of analog systems accelerates under Care Quality Commission equipment safety mandates across NHS estate renewal programs.
Today's leader: MRI. Tomorrow's challenger: CT Scan with photon-counting validation.
Technology:
Regulatory frameworks and infrastructure maturity separate established digital platforms from emerging remote delivery models.
- Digital Imaging:Picture archiving and communication systems form the backbone of NHS diagnostic workflows, though legacy PACS fragmentation across hospital trusts resists seamless cloud integration. Care Quality Commission ionising radiation regulations mandate dose optimization software on all new installations.
- Remote Imaging:Teleradiology platforms decouple reporting from scanner location, capturing overnight and emergency coverage gaps where trusts lack 24/7 on-site specialist capacity. This segment expands fastest through spot-purchase markets unbundled from scanning contracts.
- 3D Imaging:Advanced reconstruction algorithms enhance surgical planning and interventional guidance in cardiac and oncologic pathways.
- Analog Imaging:Replacement cycles accelerate as CQC registration restrictions force retrofit or retirement of non-compliant equipment.
Digital Imaging commands current procurement volume. Remote Imaging shows steepest expansion trajectory as workforce scarcity deepens.
End User:
Capital access and patient throughput separate institutional buyers from distributed community providers.
- Hospitals:NHS hospital trusts anchor demand through block contracts and elective recovery mandates, outsourcing radiology partnerships to clear MRI and CT backlogs. Teaching hospitals in London and Manchester pilot photon-counting CT and AI-assisted reporting validation.
- Diagnostic Centers:Independent chains concentrate in London and South East England where population density supports fixed-site and mobile fleet operations, competing on accessibility rather than academic prestige.
- Clinics:Primary care networks drive ultrasound volume for maternity and point-of-care applications.
- Research Institutions:Academic medical centers validate AI diagnostic tools through MHRA regulatory pathways for medical device software.
Hospitals dominate contract value. Diagnostic Centers capture share through Community Diagnostic Centre expansion funding.
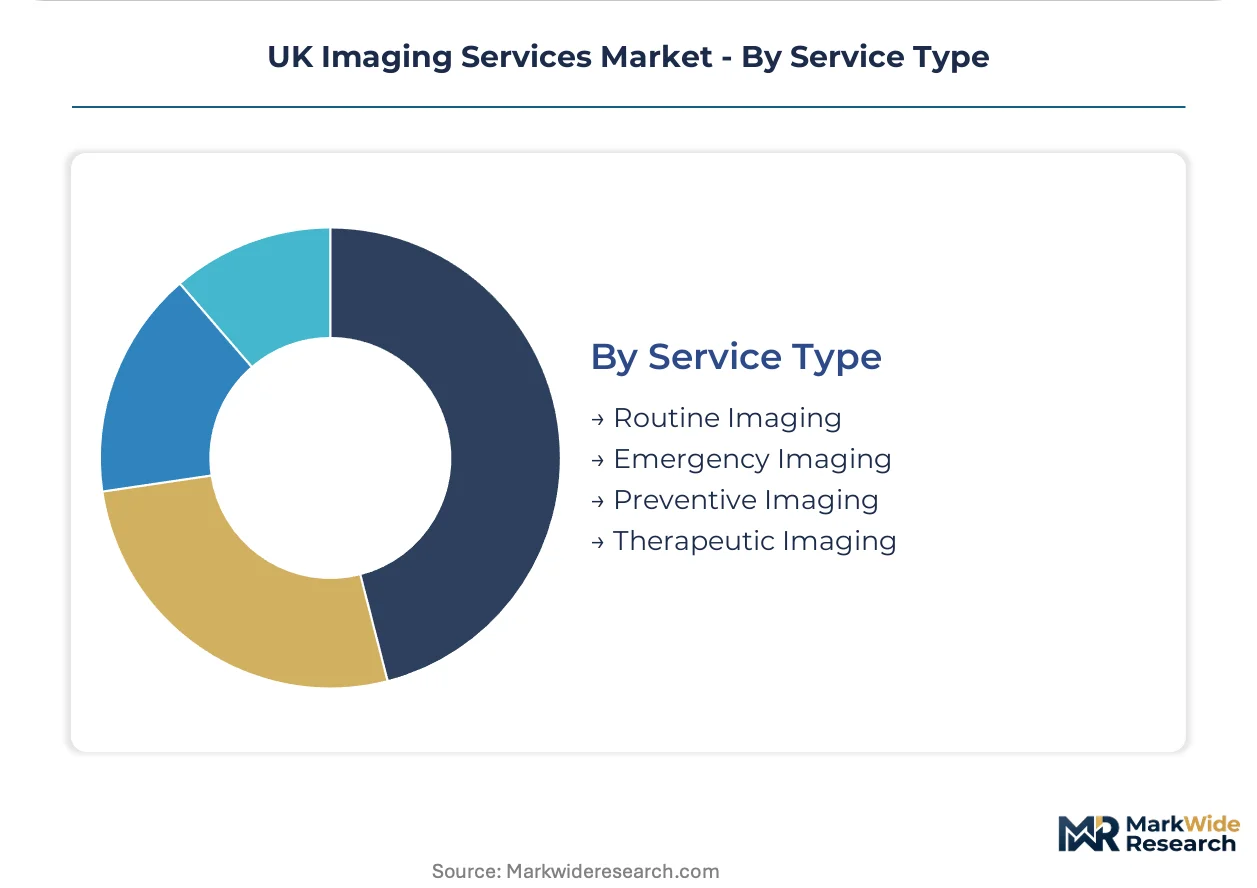
Service Type:
Urgency tier and reimbursement structure determine whether services anchor routine workflows or capture premium spot pricing.
- Emergency Imaging:Overnight and weekend coverage gaps create spot-purchase markets where teleradiology platforms compete with insourcing agencies, most advanced in Midlands and North West England where trust consolidation outpaced specialist hiring.
- Routine Imaging:NHS tariff pricing for standard MRI and CT procedures limits margin expansion even as operational costs rise, anchoring volume through elective recovery targets.
- Preventive Imaging:Screening programs in oncology and cardiology pathways gain reimbursement traction through NICE technology appraisals.
- Therapeutic Imaging:Image-guided interventions require specialized interventional radiologist capacity concentrated in major teaching centers.
Emergency Imaging commands pricing power. Routine Imaging absorbs volume scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Radiologist workforce density anchors regional service capacity across the United Kingdom, with London and the South East commanding the deepest specialist pools while northern regions and devolved nations face persistent reporting shortages.
London and the South East
Private diagnostic center networks achieve scale economies through fixed-site and mobile MRI fleets serving NHS contracts. The Care Quality Commission's 2023 ionising radiation regulations mandate dose optimization software on all new CT installations across teaching hospitals. Imperial College Healthcare NHS Trust and Guy's and St Thomas' NHS Foundation Trust pilot photon-counting CT systems for coronary plaque characterization.
Midlands
Trust consolidation has outpaced specialist hiring, creating overnight and weekend coverage gaps filled by teleradiology spot-purchase markets. NHS England's elective recovery targets push hospital groups toward outsourced radiology partnerships to clear MRI and CT backlogs. University Hospitals Birmingham NHS Foundation Trust anchors academic validation of AI-assisted reporting tools through MHRA regulatory pathways.
North England
Mobile fleet penetration reaches rural communities where fixed-site imaging density remains lowest across Yorkshire and the North East. Community Diagnostic Centre expansion funding from government capital programs concentrates new capacity in underserved urban peripheries. Manchester University NHS Foundation Trust pilots photon-counting detector technology for cardiac and pulmonary imaging applications.
Scotland
NHS Scotland health boards contract with mobile MRI and CT trailer units to serve Highland and Island populations distant from fixed-site infrastructure. The Scottish Government's elective care recovery program accelerates outsourced reporting partnerships with teleradiology platforms. NHS Greater Glasgow and Clyde anchors specialist interventional radiology capacity for image-guided procedures.
Wales
Diagnostic backlogs in oncologic and cardiac pathways drive Welsh health boards toward cross-border teleradiology arrangements with English reporting pools. NHS Wales capital investment programs prioritize digital PACS replacement to enable cloud-based reporting integration. Cardiff and Vale University Health Board concentrates advanced imaging validation for NICE technology appraisal pathways.
UK Imaging Services Market Key Industry Players
Top-tier vendors anchor equipment supply through MRI and CT system manufacturing, while service provision fragments across NHS-contracted diagnostic chains, community-based operators, and teleradiology platforms. Three strategic archetypes dominate: capital equipment manufacturers extending into service contracts, independent diagnostic chains competing on accessibility and mobile reach, and specialist reporting platforms decoupling interpretation from physical scanner location. Competitive moves concentrate on strategic partnerships between equipment vendors and service operators, plus geographic expansion of mobile fleets into underserved regions.
Within the independent diagnostic chain tier, Alliance Medical, InHealth Group, and Medica Group exemplify distinct positioning vectors. Alliance Medical represents the fixed-site and mobile fleet archetype with channel control across NHS block contracts. InHealth Group occupies the community-based accessibility position, competing through diagnostic center density rather than academic affiliation. Medica Group anchors the teleradiology reporting archetype, extending radiologist pool coverage across overnight and emergency gaps for hospital trusts lacking 24/7 on-site specialists.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Koninklijke Philips |
| Alliance Medical |
| InHealth Group |
| Medica Group |
| Canon Medical Systems |
| Affidea Group |
| FUJIFILM |
| Others |
Cost & Logistics Intelligence
Radiologist concentration in London and the South East drives labor-cost differentials that widen pricing-tier spreads between premium academic reporting and commodity teleradiology services across NHS procurement.
Pricing Analysis
The bundled-vs-unbundled service split separates scanning contracts from reporting spot-purchases across NHS trusts. Pricing stratifies across premium, standard, and economy tiers based on accreditation depth and after-hours coverage guarantees. Cost compression in routine imaging is intensifying because NHS tariff ceilings constrain margin expansion against rising radiographer wages. NHS hospital trusts show highest price sensitivity for standard elective procedures, while private payers absorb premium rates for rapid-turnaround oncology reporting.
Supply Chain Analysis
Reverse-logistics flows for MRI magnet refurbishment and CT tube remanufacturing extend asset lifecycles across independent diagnostic chains. Equipment supply concentrates in Germany, the Netherlands, and the United States for superconducting magnet assemblies and photon-counting detector arrays. The installed base draws from helium supply chains anchored in Qatar and Algeria, plus rare-earth magnet sourcing from China. Single-source vulnerability in liquid helium logistics threatens service continuity for 3 Tesla and 7 Tesla MRI fleets. Distribution runs through manufacturer-direct service contracts and third-party leasing arrangements to NHS trusts and independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where radiologist salary differentials between London and northern England create cost-advantaged reporting hubs for teleradiology platforms.
For Market Incumbents: Anticipate AI-assisted reporting validation disrupting overnight coverage premiums by securing MHRA regulatory clearance for machine-learning diagnostic tools before tariff compression erodes emergency reporting margins. Consolidate mobile fleet capacity in Yorkshire and North East England where fixed-site density lags NHS elective recovery targets. Channel control through long-term NHS block contracts remains the critical defensive lever against spot-purchase market fragmentation.
For New Entrants and Emerging Players: Capture Community Diagnostic Centre expansion funding in coastal towns and urban peripheries where government capital programs concentrate new fixed-site capacity. The most penetrable segment lies in rural Scotland and Wales where mobile MRI trailer units serve populations distant from hospital infrastructure. A direct-to-trust teleradiology pitch emphasizing 24-hour turnaround guarantees bypasses incumbent block contract relationships faster than capital-intensive scanner deployment.
For Investors and Strategic Acquirers: Private equity consolidators with healthcare service portfolios are the most active acquirer in this space, targeting independent diagnostic chains with NHS contract visibility and underutilized radiologist capacity. Long-term viability hinges on workforce retention models that outlast radiologist scarcity. Monitor NICE technology appraisal timelines for cardiac and oncologic AI applications as the inflection signal for reimbursement-driven reporting automation.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Diagnostic Validation | MHRA clearance for machine-learning tools reshapes overnight reporting economics for trusts. |
| Mobile Fleet Expansion | Trailer-based MRI and CT units penetrate rural Scotland and northern England where fixed-site density remains lowest. |
| Community Diagnostic Centre Buildout | Government capital funding concentrates new imaging capacity in underserved urban peripheries and coastal towns. |
| Teleradiology Platform Integration | Cloud-based reporting decouples radiologist location from scanner geography across NHS trust networks. |
| Photon-Counting CT Adoption | Teaching hospitals in Manchester and London pilot detector technology for coronary plaque characterization. |
Research Approach
Coverage spans England, Scotland, Wales, and Northern Ireland, with primary inputs from each combining structured interviews with NHS radiology directors, independent diagnostic chain executives, biomedical equipment procurement leads, and teleradiology platform operators. Secondary validation draws from Care Quality Commission inspection reports, NHS England elective recovery statistics, MHRA medical device registration databases, and Royal College of Radiologists workforce surveys. Bottom-up scanner installation counts and top-down NHS procurement expenditure figures undergo triangulation to anchor market sizing.
Granularity-level modeling disaggregates volume and value across product type, technology platform, end-user setting, and service urgency tier throughout the forecast period. CAGRs derive from segment-specific growth trajectories weighted by NHS capital allocation patterns and private diagnostic center expansion plans. Industry-specific forecast inputs include radiologist vacancy rates from Royal College workforce censuses and Community Diagnostic Centre capital commitment schedules from NHS England infrastructure tracking.
Radiologist training pipeline bottlenecks, AI regulatory approval delays, and NHS tariff renegotiation cycles are the dominant revision risks to projection assumptions. Practitioners should monitor Royal College workforce vacancy reports and MHRA medical device software clearance timelines for early signals of capacity constraint shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Radiology Services Market
Medical Imaging
Ultrasound Elastography Systems Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Portable X-Ray Devices Market
Medical Imaging
Radiography-Fluoroscopy Combo System Market
Medical Imaging
Image-Guided Biopsy Market
Medical Imaging
US Teleradiology Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Ultrasound Systems Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Breast MRI Screening Market
Medical Imaging
Netherlands Diagnostic Imaging Equipment Market
Medical Imaging
AI Surgical Video Intelligence System Market
Medical Imaging
Imaging Agents Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
South Korea Nuclear Imaging Market