
 Netherlands Diagnostic Imaging Equipment Market | 2026-2036
Netherlands Diagnostic Imaging Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands Diagnostic Imaging Equipment Market Foresight
Aftermarket service revenue is narrowing the profitability gap between original equipment sales and long-term maintenance contracts across Dutch healthcare procurement. Koninklijke Philips N.V. anchors its domestic position through deep vertical integration in MRI coil manufacturing and local service infrastructure. Siemens Healthineers AG competes by leveraging its digital imaging platform to secure multi-year managed equipment contracts with university medical centers. GE HealthCare differentiates through specialized ultrasound applications targeting outpatient cardiology workflows.
Diagnostic imaging equipment encompasses systems that generate visual representations of internal body structures for clinical diagnosis, utilizing electromagnetic radiation, magnetic fields, or acoustic energy with spatial resolution thresholds typically below one millimeter. These systems serve radiologists and clinicians in detecting pathological changes, guiding interventions, and monitoring therapeutic responses across hospital and ambulatory settings. CT scanner deployments dominate capital expenditure among Dutch acute care facilities due to emergency department throughput requirements and trauma protocol standardization. Digital imaging technology leads replacement cycles as hospitals retire analog fluoroscopy rooms to meet EU radiation safety directives and integrate PACS networks. Portable systems represent the fastest-expanding technology segment, driven by point-of-care ultrasound adoption in emergency departments and intensive care units where bedside triage accelerates clinical decision-making.
The Dutch Ministry of Health, Welfare and Sport enforces medical device vigilance reporting aligned with EU MDR requirements, while the Health and Youth Care Inspectorate (IGJ) conducts facility-level audits that directly influence hospital procurement timelines and vendor qualification. CE marking under the EU Medical Device Regulation mandates clinical evidence thresholds for new imaging modalities, extending product registration timelines and favoring established manufacturers with robust quality management systems. Stakeholders must monitor reimbursement code revisions by the Dutch Healthcare Authority (NZa) and radiology workforce capacity constraints when calibrating capital deployment and service expansion strategies.
Market Dynamics
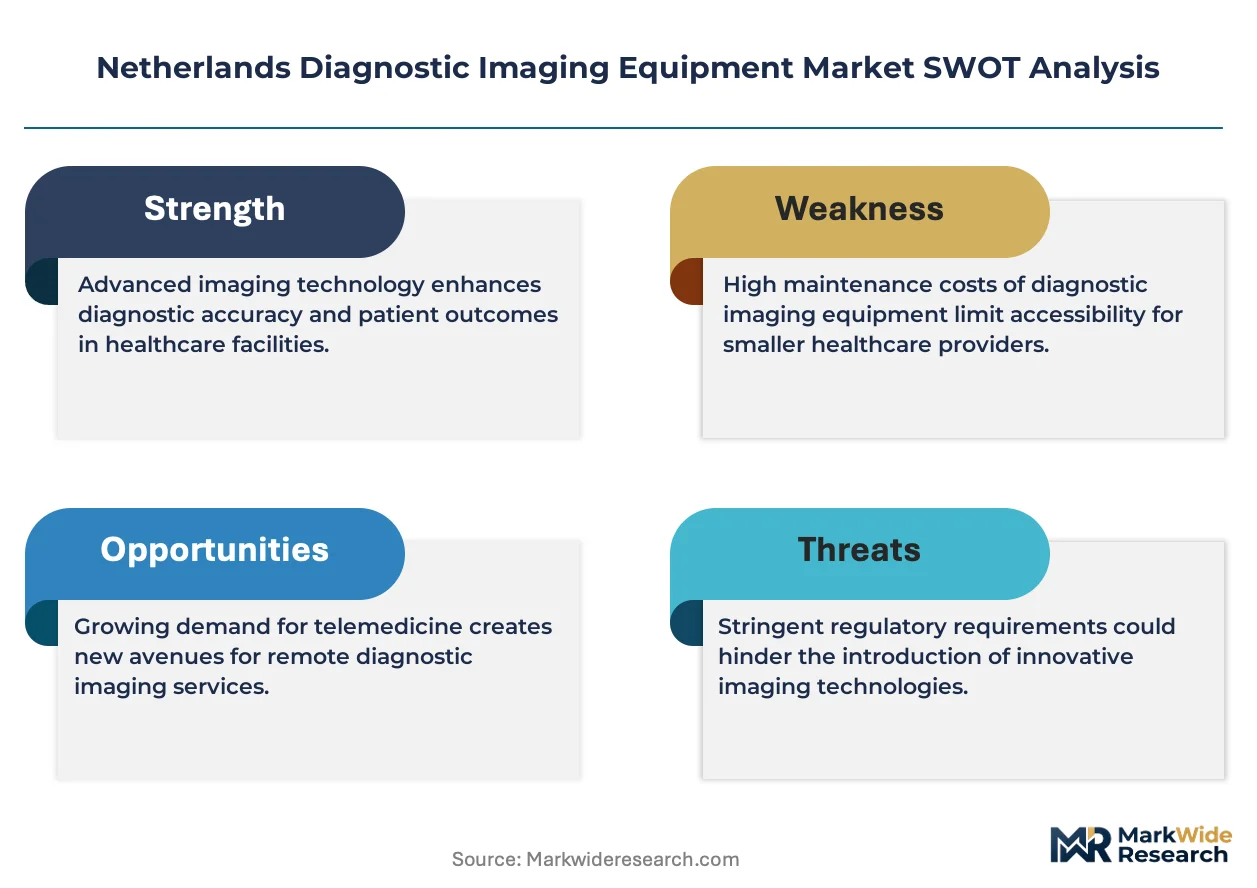
EU MDR compliance timelines are compressing procurement cycles across Dutch hospital networks as facilities accelerate replacement schedules to avoid certification gaps in installed imaging fleets.
Growth Catalysts
- Randstad Hospital Cluster Expansion:Amsterdam, Rotterdam, and Utrecht medical centers are adding MRI suites to address cardiovascular and oncological screening backlogs among aging patient populations.
- Point-of-Care Ultrasound Adoption:Emergency departments and intensive care units are deploying portable systems at bedside to accelerate triage decisions and reduce transfer times.
- EU Radiation Safety Directives:Analog fluoroscopy room retirements are forcing digital imaging replacements that integrate with PACS networks.
Market Restraints
- MDR Clinical Evidence Thresholds:CE marking requirements under EU Medical Device Regulation extend product registration timelines and favor established manufacturers with robust quality management systems.
- Superconducting Magnet Supply Concentration:MRI coil manufacturing relies on concentrated rare earth and cryogenic component suppliers, creating input cost volatility.
- Radiologist Workforce Constraints:Netherlands specialist shortages limit throughput expansion even where equipment capacity exists.
Strategic Opportunities
- Managed Equipment Service Contracts:Multi-year performance-based agreements are displacing traditional capital purchase models at university medical centers.
- Aftermarket Service Revenue Streams:Long-term maintenance contracts are narrowing profitability gaps versus original equipment sales across Dutch healthcare procurement.
- Outpatient Cardiology Workflows:Specialized ultrasound applications targeting ambulatory settings remain underpenetrated relative to hospital-based diagnostics.
Industry Challenges
- IGJ Audit-Driven Procurement Delays:Health and Youth Care Inspectorate facility-level audits directly influence vendor qualification timelines and contract awards.
- Legacy PACS Integration Complexity:Digital imaging replacements must interface with heterogeneous hospital information systems, extending deployment cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands Diagnostic Imaging Equipment Market |
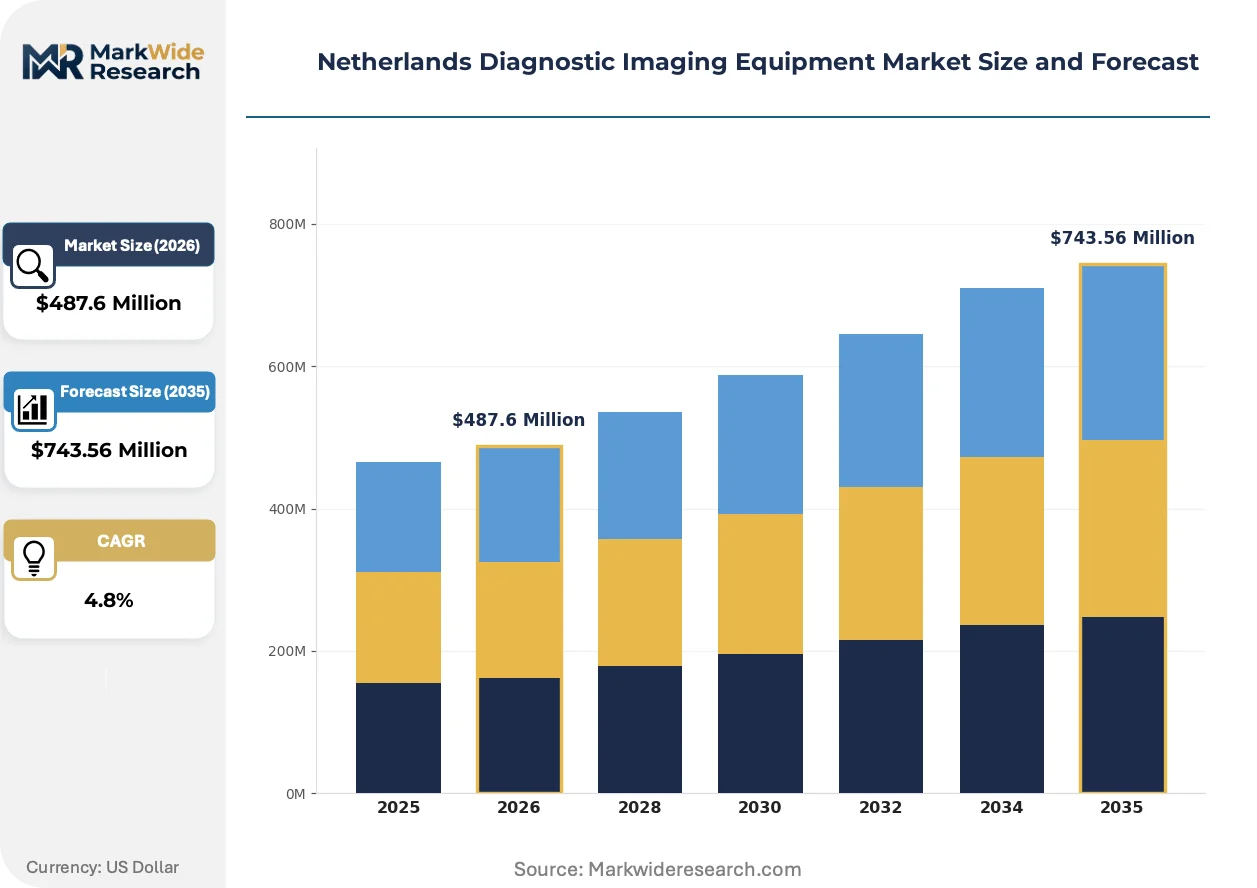
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: X-ray, MRI, Ultrasound, CT Scanner Technology: Digital Imaging, Analog Imaging, Portable Systems, Smart Imaging End User: Hospitals, Diagnostic Centers, Research Institutions, Outpatient Clinics Application: Cardiology, Oncology, Neurology, Orthopedics |
| Companies Covered | Koninklijke Philips N.V., Siemens Healthineers AG, GE HealthCare, Canon Medical Systems Corporation, FUJIFILM Holdings Corporation, Esaote SpA, Samsung Medison, Hitachi Medical Corporation, Shimadzu Medical, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands Diagnostic Imaging Equipment Market Shifts & Advancements
Artificial intelligence inference engines are embedding directly into imaging acquisition workflows, compressing reconstruction times and enabling real-time decision support at the scanner console.
Photon-counting CT detector technology is virtualizing spectral imaging capabilities that previously required dual-source hardware configurations. Academic medical centers in Leiden and Groningen are piloting these systems for cardiac and pulmonary protocols. The shift is virtualizing the premium tier of CT product segmentation by collapsing dual-energy functionality into single-source platforms.
EU MDR Article 10 clinical evaluation requirements are mandating post-market surveillance systems that track device performance across installed bases. Dutch notified bodies are extending technical documentation review periods for novel imaging modalities. Manufacturers with predicate device libraries are accelerating submissions while newcomers face compressed approval windows.
Hospital purchasing consortia are consolidating radiology capital decisions through centralized tendering platforms that unbundle equipment from service contracts. University Medical Center Utrecht and Erasmus MC Rotterdam have adopted multi-vendor framework agreements. The pattern concentrates negotiating leverage among Randstad academic centers while peripheral hospitals face reduced vendor responsiveness.
Netherlands Diagnostic Imaging Equipment Market Segmentation
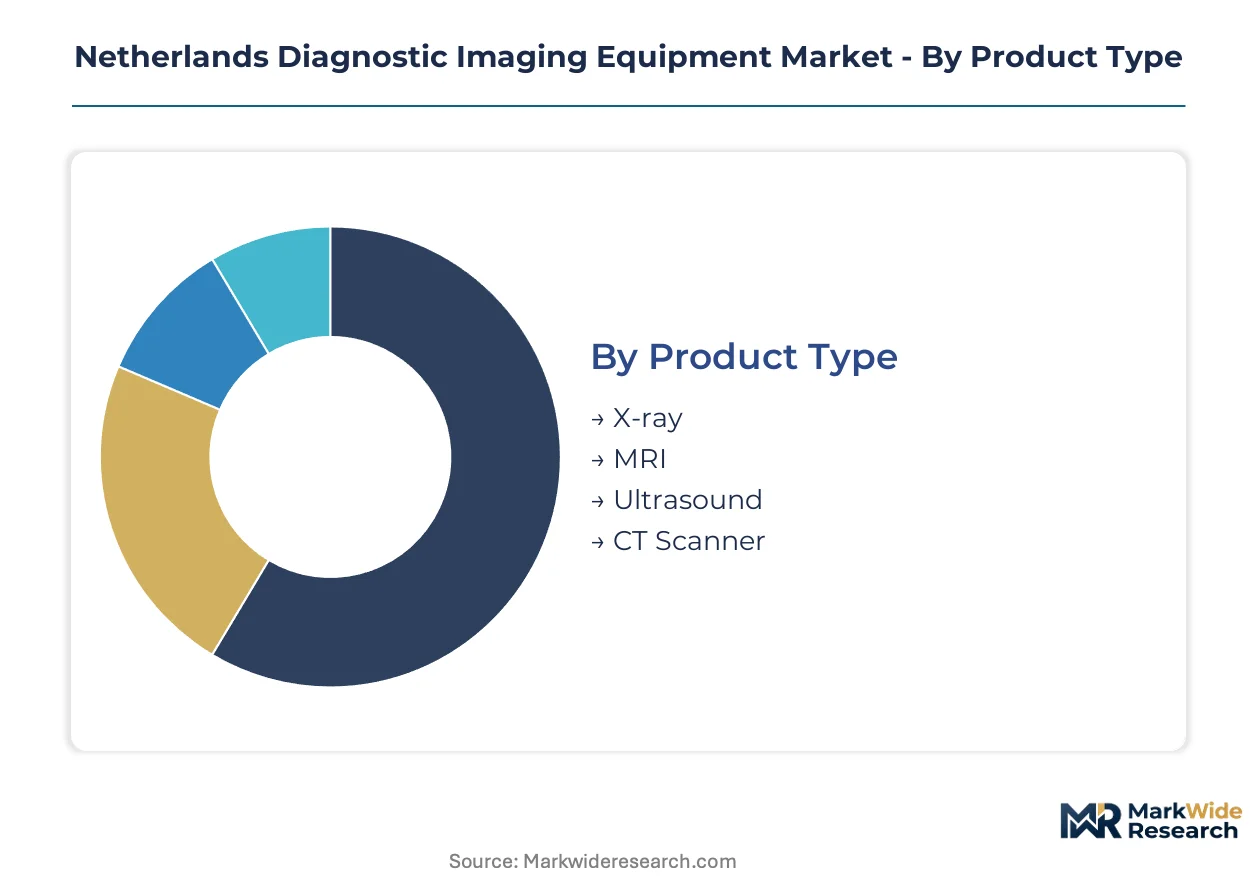
Equipment replacement cycles in Dutch healthcare diverge sharply across modalities, with digital imaging platforms turning over every 5-7 years while superconducting MRI magnets remain installed for 12-15 years. Procurement patterns concentrate in Randstad hospital clusters where aging infrastructure and EU MDR compliance deadlines are compressing decision timelines.
Product Type:
CT scanners and MRI systems exhibit the longest replacement cycles due to capital intensity and infrastructure requirements, while X-ray and ultrasound platforms turn over more rapidly as point-of-care applications expand.
- CT Scanner:Multi-detector systems with 64- to 256-slice configurations generate cross-sectional anatomical datasets through rotating X-ray tube assemblies. Amsterdam UMC and Erasmus MC Rotterdam are prioritizing photon-counting detector upgrades to reduce contrast agent volumes and improve coronary plaque characterization. These deployments dominate capital expenditure among Dutch acute care facilities due to emergency department throughput requirements.
- MRI:Superconducting systems utilizing 1.5T and 3.0T magnetic field strengths produce high-contrast soft tissue visualization without ionizing radiation. Randstad academic centers are adding cardiovascular and oncological screening suites to address aging-population diagnostic backlogs, though radiologist workforce constraints limit throughput expansion.
- Ultrasound:Piezoelectric transducer arrays emitting high-frequency acoustic pulses enable real-time anatomical and hemodynamic assessment. Outpatient cardiology workflows in Utrecht and Eindhoven are driving demand for specialized transesophageal and intravascular applications.
- X-ray:Digital radiography panels with cesium iodide or gadolinium oxysulfide scintillators convert X-ray photons to electrical signals. General hospitals across Gelderland and North Brabant are retiring computed radiography systems to meet EU radiation safety directives.
CT scanners dominate installed base capital allocation. Portable ultrasound is where expansion concentrates fastest.
Technology:
Cost tiers separate premium integrated platforms from modular retrofit solutions, with Dutch procurement patterns favoring mid-tier digital systems that balance PACS interoperability against total cost of ownership.
- Digital Imaging:Flat-panel detectors and solid-state sensor arrays replace film-screen and computed radiography workflows, enabling immediate image review and network distribution. Analog fluoroscopy room retirements are forcing replacements that integrate with hospital information systems, extending deployment cycles due to legacy PACS integration complexity.
- Portable Systems:Battery-powered ultrasound and X-ray units with wireless DICOM transmission enable bedside acquisition in emergency departments and intensive care units. These configurations are climbing the fastest as point-of-care triage protocols reduce patient transfer times at University Medical Center Utrecht and Leiden University Medical Center.
- Smart Imaging:Embedded AI inference engines automate organ segmentation, lesion detection, and protocol selection at the acquisition console. Academic medical centers in Groningen and Maastricht are piloting these capabilities for workflow standardization.
- Analog Imaging:Film-based radiography and image intensifier fluoroscopy persist in select peripheral facilities with constrained capital budgets. IGJ audit findings are accelerating phase-out timelines where radiation dose tracking remains manual.
Digital imaging commands replacement cycle volume. Smart imaging capabilities are where vendor differentiation concentrates.
End User:
Customer type determines procurement authority structure, with university medical centers operating centralized tendering platforms while outpatient clinics negotiate through purchasing consortia.
- Hospitals:Acute care facilities with emergency departments, surgical suites, and intensive care units require 24/7 imaging availability with rapid turnaround protocols. Randstad hospital clusters around Amsterdam, Rotterdam, and Utrecht are expanding MRI suite capacity to address cardiovascular and oncological screening demand.
- Diagnostic Centers:Dedicated outpatient imaging facilities optimize throughput through scheduled appointment workflows and specialized technologist staffing. These settings concentrate CT and MRI volume for elective procedures outside hospital cost structures.
- Outpatient Clinics:Ambulatory cardiology and orthopedic practices deploy compact ultrasound and extremity X-ray systems for immediate diagnostic confirmation. Underpenetration relative to hospital-based diagnostics creates expansion opportunity for specialized applications.
- Research Institutions:Academic centers with clinical trial portfolios require imaging platforms with advanced reconstruction algorithms and quantitative biomarker extraction capabilities. Leiden and Groningen medical centers are piloting photon-counting CT for cardiac and pulmonary research protocols.
Hospitals dominate installed base. Outpatient clinics are where ambulatory workflow expansion concentrates.
Application:
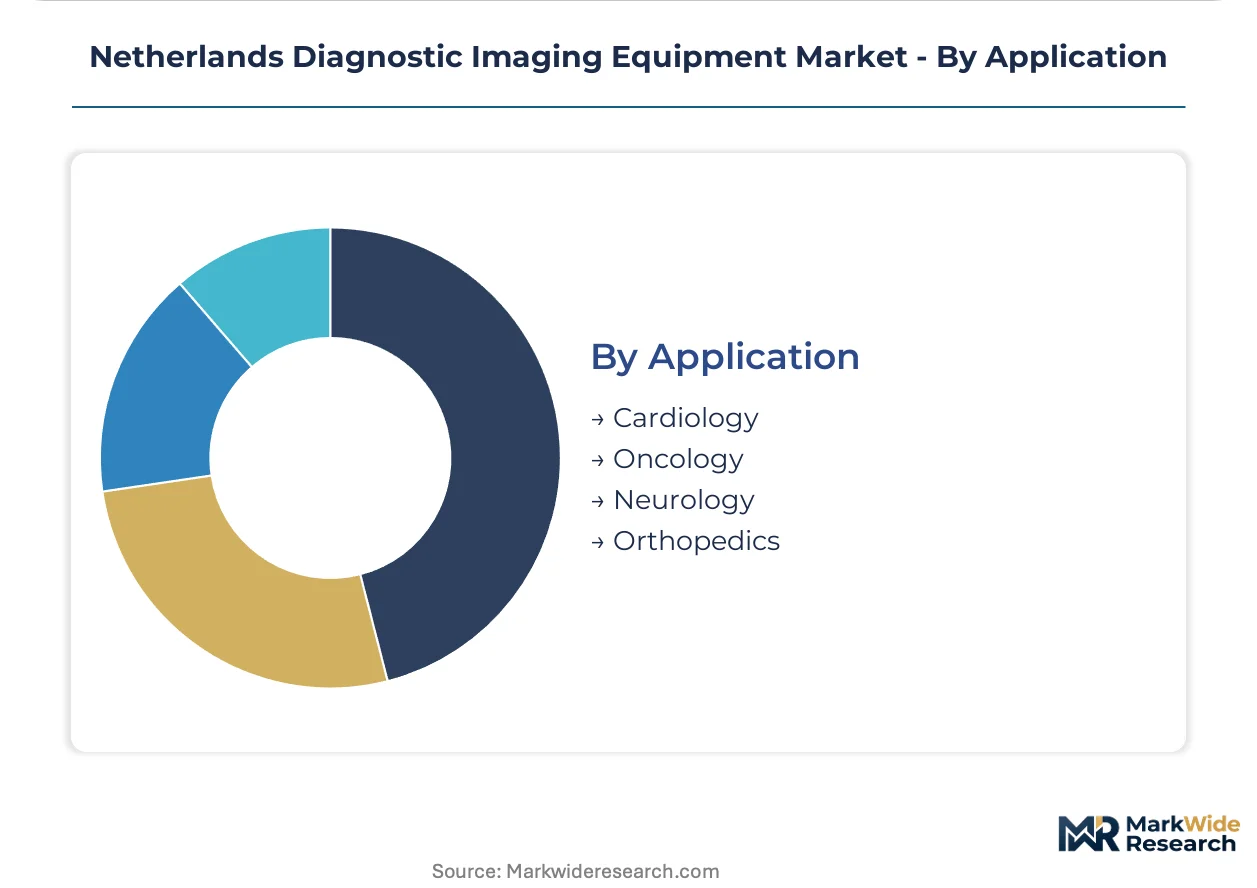
Clinical use case drives modality selection, with oncology and cardiology commanding premium system configurations while orthopedics tolerates more standardized platforms.
- Oncology:Staging and treatment response assessment requires multi-parametric MRI, PET-CT hybrid systems, and contrast-enhanced CT with perfusion mapping. Dutch cancer centers are prioritizing digital imaging replacements that integrate with radiotherapy planning systems.
- Cardiology:Coronary CT angiography, cardiac MRI with late gadolinium enhancement, and transesophageal echocardiography demand specialized acquisition protocols and dedicated technologist training. These applications are gaining share fastest as preventive screening protocols expand among aging populations.
- Neurology:Diffusion-weighted MRI for stroke triage, functional MRI for pre-surgical mapping, and CT perfusion for hemorrhage detection require rapid availability and specialized post-processing software. Academic centers maintain dedicated neuroimaging suites with 3.0T field strength.
- Orthopedics:Weight-bearing X-ray, musculoskeletal ultrasound, and metal-artifact-reduction CT for post-arthroplasty evaluation constitute high-volume, lower-complexity applications. These procedures tolerate extended equipment depreciation cycles.
Oncology dominates premium system deployment. Cardiology is where screening protocol expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dutch diagnostic imaging consumption diverges from neighboring Germany and Belgium through tighter hospital network consolidation and accelerated EU MDR compliance timelines compressing replacement cycles.
Germany
University hospital networks in Berlin and Munich drive demand for photon-counting CT and 7.0T MRI research platforms. The Federal Institute for Drugs and Medical Devices enforces MDR transition deadlines that accelerate fleet modernization. Bavarian medical centers concentrate procurement authority through centralized tendering.
Belgium
Flemish hospital associations prioritize digital radiography replacements to meet federal radiation protection standards. The Federal Agency for Medicines and Health Products coordinates CE marking enforcement with Dutch notified bodies. Brussels academic hospitals anchor Benelux imaging research consortia.
United Kingdom
NHS England's diagnostic imaging network expansion targets cardiovascular and cancer screening backlogs. The Medicines and Healthcare products Regulatory Agency operates parallel MDR recognition pathways. London teaching hospitals concentrate AI-embedded imaging pilot programs.
France
Regional hospital groups in Île-de-France and Auvergne-Rhône-Alpes deploy mobile MRI units for rural access gaps. The National Agency for Food, Environmental and Occupational Health Safety enforces post-market surveillance under MDR Article 10. Lyon-based imaging clusters drive interventional radiology platform development.
Switzerland
Cantonal hospital procurement favors premium-tier systems with extended service contracts. Swissmedic maintains independent device authorization timelines that diverge from EU MDR synchronization. Zurich and Geneva university hospitals anchor alpine medical technology evaluation networks.
Netherlands Diagnostic Imaging Equipment Market Competitive Landscape
Capability concentration sits with integrated manufacturers commanding coil fabrication and service infrastructure; scale advantage sits with diversified health technology conglomerates leveraging cross-divisional procurement relationships. The Dutch market structures around three tiers: domestic-anchored integrated manufacturers, German-engineered platform specialists, and Asian electronics conglomerates with imaging divisions. Dominant competitive moves include multi-year managed equipment service contracting and AI-embedded workflow differentiation.
Within the integrated manufacturer tier, Koninklijke Philips N.V. occupies a position exemplifying domestic vertical control over MRI coil production and service networks. Siemens Healthineers AG and GE HealthCare represent the German-engineered and American-diversified archetypes respectively, each anchoring distinct approaches to university medical center contracting.
| Leading Market Players |
|---|
| Koninklijke Philips N.V. |
| Siemens Healthineers AG |
| GE HealthCare |
| Canon Medical Systems Corporation |
| FUJIFILM Holdings Corporation |
| Esaote SpA |
| Samsung Medison |
| Hitachi Medical Corporation |
| Shimadzu Medical |
| Others |
Supply & Pricing Matrix
Single-source dependency on superconducting magnet suppliers from Germany and Japan compresses pricing tier spreads between premium MRI platforms and mid-tier configurations while forcing Dutch hospital consortia into long-term service bundling. This concentration simultaneously elevates input cost volatility and narrows vendor negotiation leverage across Randstad procurement clusters.
Pricing Analysis
Long-term managed equipment service contracts dominate Dutch hospital procurement, displacing capital purchase models through multi-year performance-based agreements that bundle hardware, software, and maintenance. Price differentiation stems from CE marking tier under EU MDR and after-sales service integration depth, with university medical centers least sensitive due to research funding buffers while peripheral hospitals face acute budget constraints. Cost compression in mid-tier digital imaging intensifies because IGJ audit-driven compliance deadlines compress replacement timelines. General hospitals across Gelderland and North Brabant exhibit highest price sensitivity as analog fluoroscopy retirements strain capital reserves.
Supply Chain Analysis
Tariff exposure between China and the European Union threatens rare earth component flows for MRI coil manufacturing, disrupting cost structures for Dutch-anchored producers. Superconducting wire production concentrates in Germany, Japan, and the United States, while flat-panel detector assemblies source from South Korea and Taiwan. Cryogenic cooling systems and gradient amplifier modules constitute critical dependencies with limited qualified suppliers. Distribution runs through hospital purchasing consortia that centralize tendering authority across Randstad academic centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Photon-counting CT detector commercialization represents a technological inflection that collapses dual-energy functionality into single-source platforms, compressing premium tier pricing and reshaping vendor competitive positioning across Dutch radiology departments.
For Market Incumbents: Harden EU MDR technical documentation capabilities to accelerate predicate device submissions while newcomers face extended review periods. Deepen backward integration into MRI coil manufacturing to insulate against rare earth supply volatility. Secure multi-year managed equipment service contracts with University Medical Center Utrecht and Erasmus MC Rotterdam before framework agreement consolidation concentrates buyer leverage. For New Entrants and Emerging Players: Build out specialized ultrasound applications for outpatient cardiology workflows in Utrecht and Eindhoven, where hospital-based diagnostic concentration leaves ambulatory settings underpenetrated. Target diagnostic centers outside Randstad core clusters, where purchasing consortium influence weakens and vendor responsiveness gaps persist. Pursue software companion development partnerships with academic medical centers piloting AI-embedded imaging capabilities. For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors service-revenue-heavy manufacturers with installed base density and MDR-compliant predicate libraries. Long-term viability rests on aftermarket contract renewal rates and photon-counting CT adoption curves rather than equipment shipment volumes. Watch for IGJ audit enforcement intensity as a signal of procurement timeline compression and vendor qualification barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | Accelerated EU MDR submission leverages predicate device libraries against extended notified body review periods. |
| Hospital System Partnership | Multi-year framework agreements with Randstad academic centers lock out competing vendors through integrated service bundling. |
| Software Companion Development | AI-embedded organ segmentation and lesion detection differentiate acquisition consoles at Groningen and Maastricht pilot sites. |
| Backward Integration | In-house MRI coil manufacturing reduces exposure to concentrated superconducting magnet and rare earth suppliers. |
| Reimbursement Strategy | Alignment with Dutch Healthcare Authority code revisions ensures procedure coverage for photon-counting CT cardiac protocols. |
Research Methodology
Desk research of EU MDR technical documentation requirements, hospital procurement databases, and GPO contract filings preceded structured interviews with biomedical engineers, hospital purchasing committee members, radiology department heads, and notified body auditors. Secondary validation drew from Health and Youth Care Inspectorate audit reports, Dutch Healthcare Authority reimbursement schedules, and manufacturer quality management system disclosures. Bottom-up equipment shipment estimates triangulated against top-down healthcare capital expenditure projections.
Assumptions held fixed include EU MDR enforcement timelines, Randstad hospital cluster expansion plans, and superconducting magnet supplier concentration. Variables modeled across the projection horizon encompassed point-of-care ultrasound adoption rates, photon-counting CT penetration curves, and AI-embedded imaging workflow integration. Segmentation dimensions included product type, technology tier, end-user category, and clinical application. CAGRs derived from installed base replacement cycles and ambulatory workflow expansion patterns, with radiologist workforce constraints and IGJ audit frequency as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Asian electronics conglomerates with imaging divisions would shift outcomes through price disruption in portable ultrasound segments. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Diagnostic Imaging Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Diagnostic X-Ray System Market
Medical Imaging
Weightbearing Low Dose (CT) Systems Market
Medical Imaging
Image Guided Therapy Market
Medical Imaging
Malaysia Digital Radiography Market
Medical Imaging
Teleradiology Services Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Angiography Imaging Systems Market
Medical Imaging
Global Image-Guided Radiation Therapy (IGRT) Market
Medical Imaging
Medical X-Ray Equipment and Imaging Software Market
Medical Imaging
Mexico Nuclear Imaging Market
Medical Imaging
Medical Holography Market
Medical Imaging
Ultrasound Imaging Solution Market
Medical Imaging
Digital Radiography Detectors Market
Medical Imaging
Global Mini C-Arm Market