
 Thymus Cancer Market | 2026-2036
Thymus Cancer Market Size, Share, and Industry Trends Forecast 2026-2036
Thymus Cancer Market Outlook
The EU Green Deal's pharmaceutical sustainability criteria is pivoting procurement standards across European hospital networks. Bristol-Myers Squibb leverages its immuno-oncology infrastructure to sustain leadership in checkpoint inhibitor development for thymic epithelial tumors. Merck & Co. anchors its competitive position through broad clinical trial networks spanning academic medical centers with dedicated thoracic oncology programs. Novartis differentiates via targeted therapy platforms that address molecular subsets of thymoma and thymic carcinoma.
Thymus cancer encompasses malignant neoplasms arising from thymic epithelial cells, classified histologically as thymoma subtypes (A, AB, B1-B3) or thymic carcinoma, with Masaoka-Koga staging guiding treatment intensity based on capsular invasion and metastatic spread. The disease requires multimodal management combining surgical resection with adjuvant systemic therapy, reflecting its anatomical location in the anterior mediastinum and propensity for local invasion. Immunotherapy represents the fastest-expanding product category as PD-1/PD-L1 inhibitors demonstrate durable responses in previously treated thymic carcinoma patients, while chemotherapy maintains volume leadership as first-line standard of care across all Masaoka stages. Cancer treatment centers command disproportionate margin pools by concentrating complex thymoma resections and postoperative radiation therapy within high-volume thoracic surgery units.
The FDA's orphan drug designation framework and EMA's PRIME eligibility pathway for rare cancers jointly accelerate regulatory review timelines and incentivize manufacturer investment in thymic malignancy drug development. NMPA's streamlined approval channels for innovative oncology therapies are expanding patient access to novel agents within China's tier-one hospital system. Stakeholders must monitor evolving biomarker definitions for thymic tumor classification, as molecular profiling increasingly segments treatment-responsive populations and reshapes clinical trial enrollment criteria across regulatory jurisdictions.
Market Dynamics
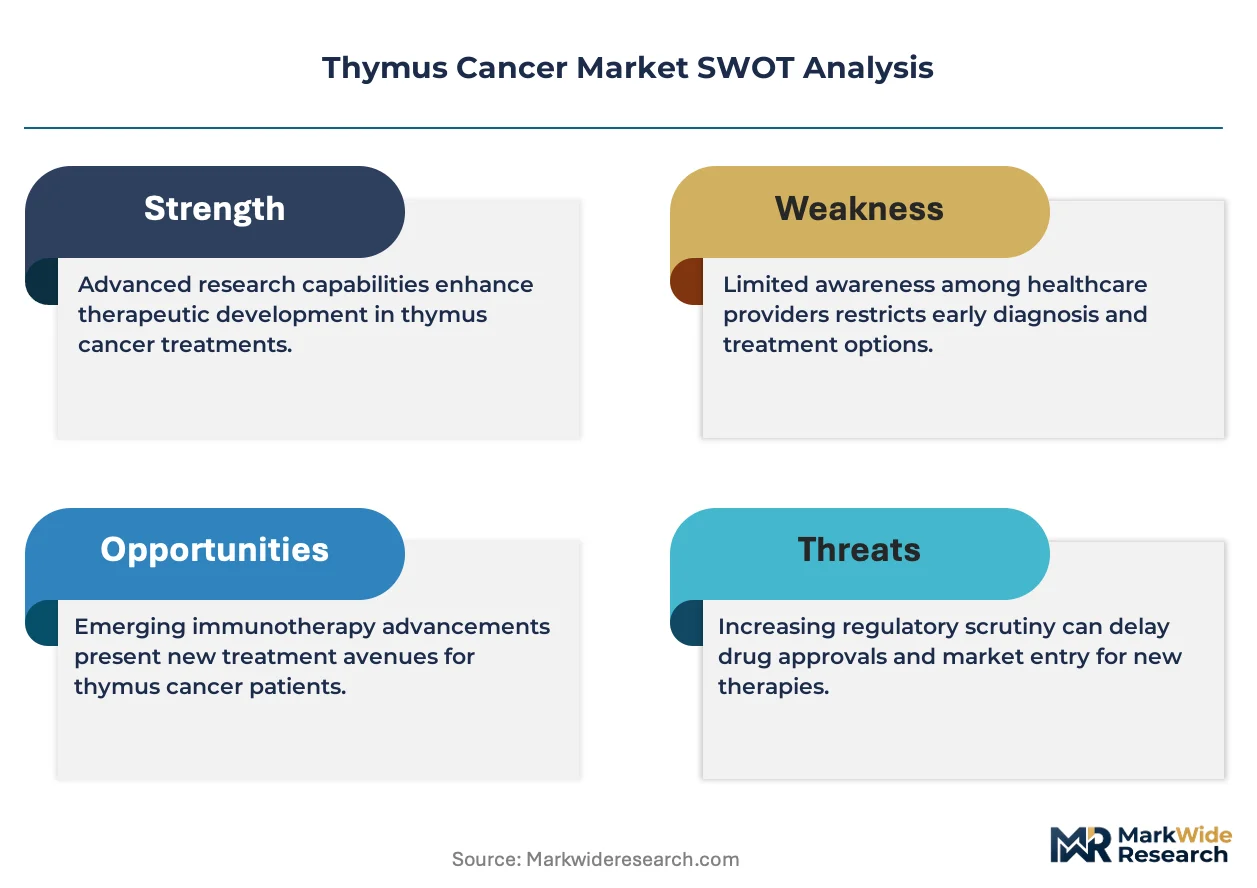
The thymus cancer market pivots on FDA and EMA regulatory incentives for rare oncology indications, which compress development timelines and redirect R&D investment toward thymic epithelial tumor subtypes with unmet medical need.
Growth Catalysts
- Orphan Drug Designation Framework:The FDA's accelerated approval pathways reduce clinical trial duration for thymic malignancy therapies, attracting biopharmaceutical investment into previously neglected indications.
- Multidisciplinary Thoracic Oncology Centers:Academic medical centers in the United States and Germany are consolidating complex thymoma resections and postoperative care protocols, concentrating patient volumes and expertise.
- PD-1/PD-L1 Checkpoint Inhibitors:Immunotherapy platforms demonstrate durable responses in thymic carcinoma patients who have progressed on platinum-based chemotherapy, expanding the addressable patient pool.
Market Restraints
- Platinum Salt Supply Concentration:Cisplatin and carboplatin production concentrates in limited manufacturing facilities, creating vulnerability in first-line chemotherapy supply for thymoma protocols.
- Diagnostic Pathology Bottlenecks:WHO classification updates for thymic epithelial tumors require specialized immunohistochemistry panels that few reference laboratories can execute consistently.
- Reimbursement Complexity:NMPA provincial formularies in China create access friction for novel oncology agents despite central regulatory approval.
Strategic Opportunities
- Biomarker-Guided Patient Stratification:Molecular profiling for GTF2I mutations and chromosomal alterations enables enrichment strategies for targeted therapy clinical trials.
- EU Green Deal Pharmaceutical Criteria:Sustainability procurement standards create first-mover advantage for manufacturers with carbon-neutral active pharmaceutical ingredient synthesis.
- Telemedicine-Enabled Referral Networks:Virtual tumor boards connect community oncology practices to specialized thymoma centers, expanding geographic reach without physical infrastructure investment.
Industry Challenges
- Thoracic Surgeon Training Pipelines:Complex mediastinal resection techniques require fellowship-level expertise that academic programs are not producing at sufficient scale.
- Cross-Border Clinical Trial Harmonization:Divergent biomarker acceptance criteria between FDA and EMA complicate global enrollment for thymic carcinoma studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thymus Cancer Market |
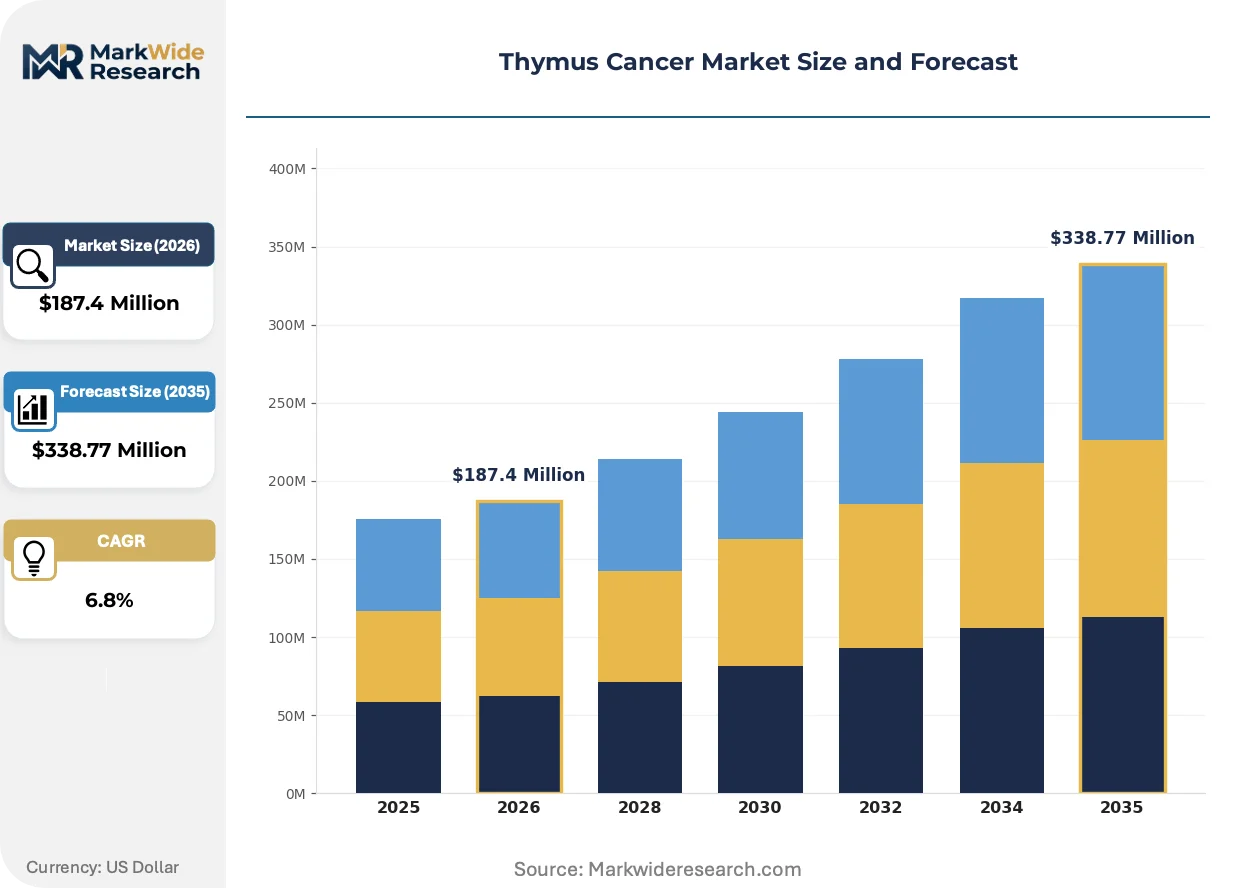
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Chemotherapy, Radiation Therapy, Immunotherapy, Targeted Therapy End User: Hospitals, Oncology Clinics, Research Laboratories, Cancer Treatment Centers Therapy Area: Stage I, Stage II, Stage III, Stage IV Administration Route: Intravenous, Oral, Subcutaneous, Intramuscular |
| Companies Covered | Bristol-Myers Squibb, Merck & Co., Novartis, Pfizer, AstraZeneca, Roche, Eli Lilly and Company, Johnson & Johnson, Amgen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thymus Cancer Market Strategic Shifts
Immunotherapy platforms and precision diagnostic tools are restructuring treatment hierarchies in thymic malignancies, compressing the interval between molecular characterization and therapeutic selection.
Next-generation sequencing panels for thymic epithelial tumors is modularizing the diagnostic workflow in thoracic pathology laboratories. Academic medical centers in Boston and Heidelberg are adopting comprehensive genomic profiling as standard-of-care for all newly diagnosed thymoma subtypes. This technology is modularizing tissue-based testing from sequential single-marker assays into parallel multiplex platforms, reducing time-to-treatment initiation.
EMA's PRIME eligibility pathway for rare cancers accelerates scientific advice and accelerated assessment procedures for thymic malignancy drug developers. European biotechnology firms are prioritizing PRIME qualification in their regulatory strategies to compress development timelines. Thoracic oncology programs in France and Italy are restructuring clinical trial infrastructure to accommodate compressed regulatory review schedules.
Consolidation of complex cancer surgery into high-volume centers is displacing community hospital resection programs for thymoma cases. United States payers are narrowing network coverage to NCI-designated cancer centers and accredited thoracic surgery programs. This concentration pattern is most visible in California and Texas, where patient travel distances to specialized centers have expanded substantially.
Thymus Cancer Market Segmentation
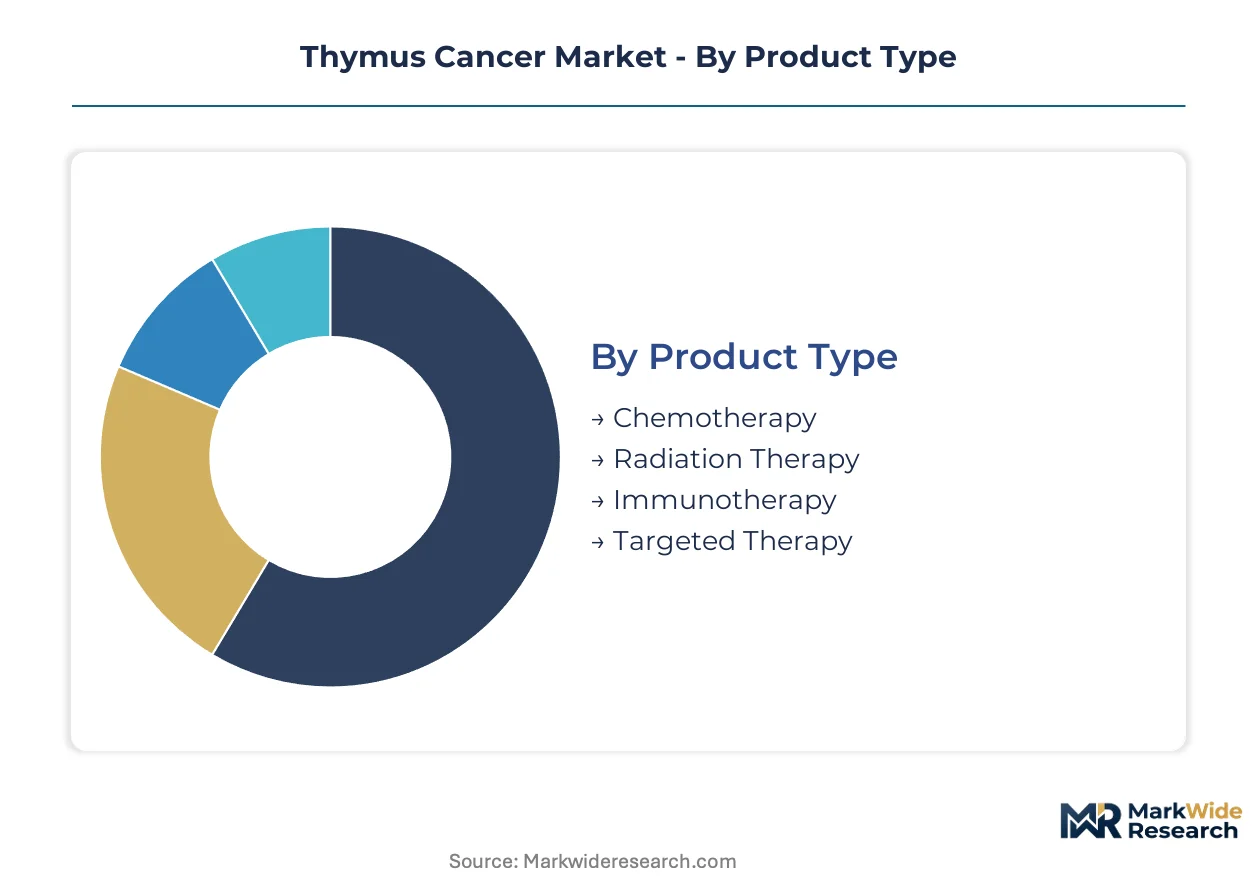
Thymus cancer treatment selection hinges on histological subtype, Masaoka-Koga staging, and molecular profiling, creating distinct demand pockets across therapeutic modalities and care settings. Segmentation reveals how immunotherapy platforms are displacing chemotherapy in relapsed thymic carcinoma while radiation therapy retains primacy in localized disease management.
Product Type:
Treatment modality selection pivots on mechanism of action specificity and biomarker eligibility criteria across thymoma and thymic carcinoma subtypes.
- Immunotherapy:PD-1 and PD-L1 checkpoint inhibitors deliver durable responses in platinum-refractory thymic carcinoma patients. Demand concentrates in NCI-designated cancer centers in the United States and Germany's reference hospital networks, driven by FDA accelerated approval pathways and EMA PRIME eligibility for rare oncology indications.
- Chemotherapy:Platinum-based regimens (cisplatin, carboplatin, doxorubicin) constitute first-line standard of care across all Masaoka stages. Volume leadership persists in China’s tier-one hospital system and community oncology practices in Texas and California, constrained by manufacturing concentration risks in platinum salt supply chains.
- Radiation Therapy:Adjuvant and neoadjuvant protocols target microscopic residual disease following surgical resection.
- Targeted Therapy:Small-molecule inhibitors address molecular subsets defined by GTF2I mutations and chromosomal alterations.
Mature deployment sits with chemotherapy. Newer deployment is concentrated in immunotherapy.
End User:
Care delivery fragmentation reflects the complexity of multimodal thymoma management and the scarcity of specialized thoracic surgical expertise.
- Cancer Treatment Centers:High-volume thoracic surgery units command disproportionate margin pools by concentrating complex mediastinal resections and postoperative radiation protocols. United States payers are narrowing network coverage to NCI-designated centers and accredited thoracic surgery programs, consolidating patient referrals in California and Texas.
- Oncology Clinics:Community-based practices manage chemotherapy administration and patient monitoring for stable disease. Access friction emerges in China where NMPA provincial formularies create reimbursement delays despite central regulatory approval of novel agents.
- Hospitals:General acute care facilities handle initial diagnosis and emergency complications.
- Research Laboratories:Academic medical centers in Boston and Heidelberg deploy next-generation sequencing panels for comprehensive genomic profiling.
Patient volume concentrates in cancer treatment centers. Geographic expansion is occurring through oncology clinics.
Therapy Area:
Staging intensity determines treatment aggressiveness, with capsular invasion and metastatic spread guiding multimodal protocol selection.
- Stage IV:Metastatic thymic carcinoma requires systemic therapy prioritization with palliative radiation for symptomatic control. Demand clusters in specialized centers with immuno-oncology infrastructure, reflecting the fastest-expanding addressable pool as PD-1/PD-L1 inhibitors demonstrate activity in previously treated populations.
- Stage I:Encapsulated thymoma without invasion permits surgical monotherapy with excellent prognosis. Volume concentrates in high-resection-volume programs where fellowship-trained thoracic surgeons execute complete excision with minimal morbidity.
- Stage II:Microscopic capsular invasion necessitates adjuvant radiation following complete resection.
- Stage III:Macroscopic invasion into adjacent structures demands neoadjuvant chemotherapy and en-bloc resection.
Complex multimodal protocols dominate Stage IV. Surgical monotherapy characterizes Stage I.
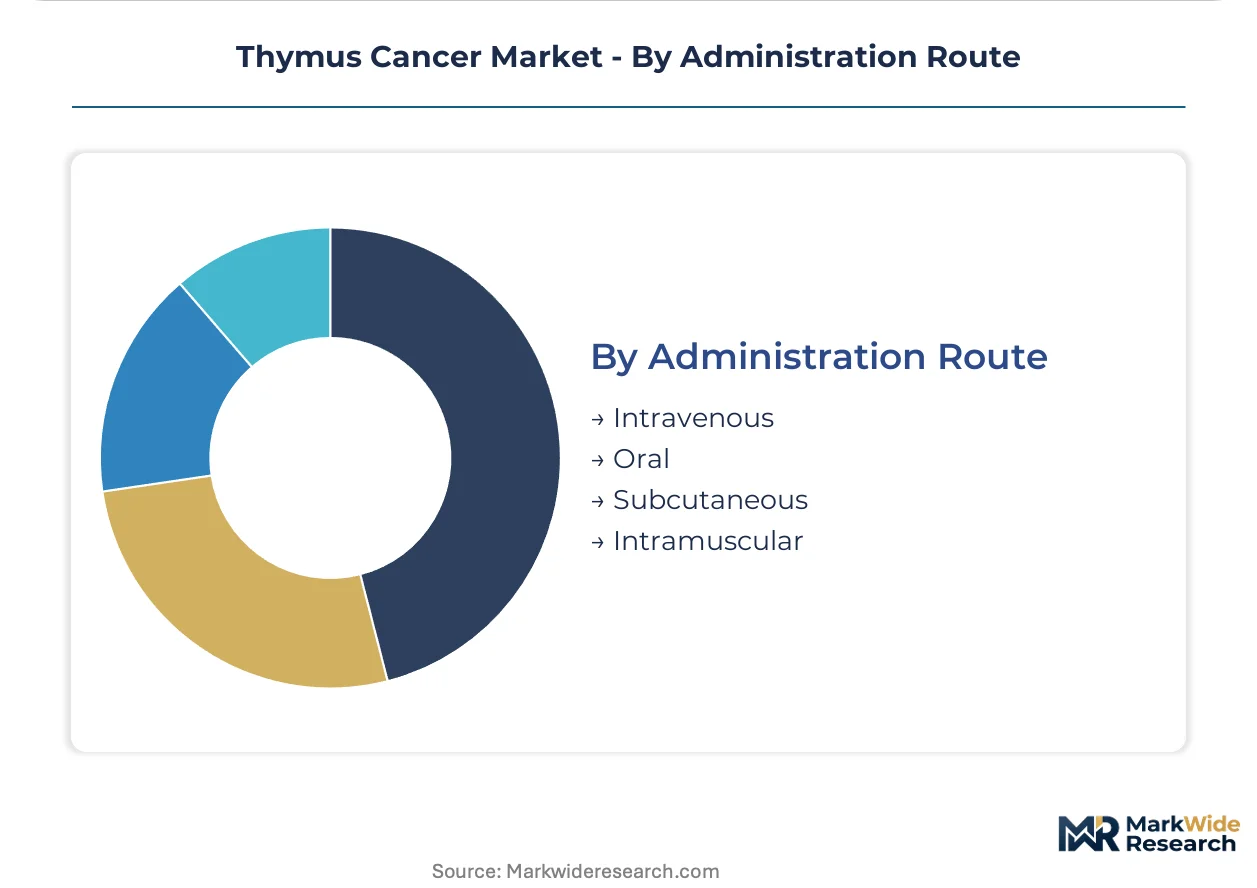
Administration Route:
Delivery mechanism selection reflects pharmacokinetic requirements, treatment setting constraints, and patient compliance considerations across chronic therapy courses.
- Intravenous:Infusion-based delivery of platinum agents, checkpoint inhibitors, and monoclonal antibodies requires clinical infrastructure for monitoring and adverse event management. Demand anchors in hospital-based oncology units and cancer treatment centers with dedicated infusion suites.
- Oral:Targeted therapy agents enable outpatient self-administration with reduced clinic burden. Adoption expands in Germany and France where reference networks support remote monitoring protocols.
- Subcutaneous:Alternative delivery for select supportive care agents and emerging immuno-oncology formulations.
- Intramuscular:Limited application for hormonal and supportive therapies in thymoma-associated autoimmune conditions.
Clinic-based administration dominates intravenous routes. Home-based delivery is expanding through oral formulations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Drug development for thymic malignancies concentrates in the United States and Germany, while patient access expansion drives procurement growth in China and Japan. Consumption of checkpoint inhibitors and platinum-based regimens anchors in specialized cancer centers across these markets.
United States
NCI-designated cancer centers in Boston and Houston concentrate complex thymoma resections and immuno-oncology trials. FDA orphan drug designation accelerates regulatory timelines for thymic epithelial tumor therapies. Thoracic surgery fellowship programs at Massachusetts General and MD Anderson expand training pipelines for mediastinal oncology.
Germany
Reference hospital networks in Heidelberg and Berlin consolidate multidisciplinary care pathways for rare thoracic cancers. EMA PRIME eligibility pathway compresses scientific advice timelines for biotechnology developers. The EU Green Deal pharmaceutical sustainability criteria pivot procurement standards across university hospital systems toward carbon-neutral API synthesis.
China
Tier-one hospitals in Shanghai and Beijing expand access to novel oncology agents through NMPA streamlined approval channels. Provincial formulary fragmentation creates reimbursement friction despite central regulatory clearance. Domestic pharmaceutical manufacturers invest in platinum salt production capacity to reduce import dependency.
Japan
Academic medical centers in Tokyo and Osaka deploy next-generation sequencing panels for thymic tumor molecular profiling. PMDA regulatory pathways for rare cancers align with international trial standards. Thoracic oncology programs concentrate in the Kanto region with dedicated referral networks for mediastinal malignancies.
United Kingdom
Royal Marsden and Christie NHS Foundation Trusts anchor specialized thymoma treatment protocols. NHS England commissioning frameworks concentrate complex cancer surgery in high-volume centers. London-based biotechnology firms pursue EMA centralized procedures for thymic carcinoma drug registration.
Thymus Cancer Market Competitive Environment
The competitive structure tilts toward diversified immuno-oncology platforms with established checkpoint inhibitor infrastructure. Large-cap pharmaceutical conglomerates dominate clinical trial sponsorship and regulatory engagement for thymic malignancies. Three archetypes prevail: broad oncology portfolio holders, rare disease specialists, and precision therapy platform operators. Capacity expansion into thoracic oncology trial networks and strategic partnerships with academic medical centers constitute the dominant competitive moves.
Within the broad oncology portfolio tier, Bristol-Myers Squibb, Merck & Co., and Novartis occupy positions anchored by checkpoint inhibitor development infrastructure and rare disease regulatory expertise. These companies exemplify the integrated archetype combining immuno-oncology platforms with specialized thoracic surgery center partnerships.
| Leading Market Players |
|---|
| Bristol-Myers Squibb |
| Merck & Co. |
| Novartis |
| Pfizer |
| AstraZeneca |
| Roche |
| Eli Lilly and Company |
| Johnson & Johnson |
| Amgen |
| Others |
Value Chain & Pricing Dynamics
Fellowship-trained thoracic surgeons in the United States and Germany command premium compensation differentials that propagate through treatment pricing tiers, with labor-cost spreads between high-volume academic centers and community hospitals creating three-tier pricing structure across premium, standard, and economy levels for multimodal thymoma protocols.
Pricing Analysis
Margin tightening in platinum-based chemotherapy reflects manufacturing concentration risks in cisplatin and carboplatin active pharmaceutical ingredient production. Pricing stratifies across premium, standard, and economy tiers based on institutional certification level and surgical volume scale. Cost-down pressure on checkpoint inhibitor infusions accelerates because NMPA provincial formulary fragmentation in China creates reimbursement delays despite central regulatory clearance. Community oncology practices exhibit highest price sensitivity; NCI-designated cancer centers demonstrate lowest.
Supply Chain Analysis
China's domestic-content mandates for platinum salt production are reshaping sourcing patterns as domestic pharmaceutical manufacturers invest in captive production capacity to reduce import dependency. Active pharmaceutical ingredient synthesis concentrates in India, China, and the United States. Supply chains draw from platinum group metals, specialized immunohistochemistry reagents, and radiopharmaceutical isotopes. Single-source vulnerability in platinum salt manufacturing creates structural exposure. Distribution runs through hospital-based pharmacy networks and specialized oncology distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thymus cancer treatment capacity bottlenecks at fellowship-trained thoracic surgeon level prop pricing premiums, with academic medical center concentration limiting addressable surgical volume expansion.
For Market Incumbents: Deepen immuno-oncology infrastructure partnerships with NCI-designated cancer centers to defend against emerging biotechnology firms with PRIME-qualified development programs. Anchor capacity addition in Germany's reference hospital networks where EMA scientific advice timelines compress competitive windows. Prioritize carbon-neutral API synthesis certification to capture EU Green Deal procurement pivots. For New Entrants and Emerging Players: Capture biomarker-guided patient stratification white space in thymic carcinoma molecular profiling, where GTF2I mutation testing penetration remains underdeveloped. Target China's tier-one hospital system through NMPA streamlined approval channels as the most penetrable geography. Deploy telemedicine-enabled virtual tumor board partnerships as go-to-market angle to bypass physical infrastructure requirements. For Investors and Strategic Acquirers: Re-rating potential sits with precision therapy platform operators given EMA PRIME eligibility pathway acceleration for rare oncology indications. Long-term viability favors developers with integrated diagnostic-therapeutic positioning in thoracic malignancies. Monitor biomarker acceptance criteria harmonization between FDA and EMA as inflection signal for global clinical trial scalability.| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | EMA PRIME eligibility compresses scientific advice timelines for thymic carcinoma developers in Heidelberg and Berlin networks. |
| Regulatory Approval Pathway | FDA orphan drug designation accelerates commercialization timelines for rare thymic epithelial tumor indications. |
| Manufacturing Scale-Up | Carbon-neutral API synthesis investment captures EU Green Deal pharmaceutical sustainability procurement pivots. |
| Hospital System Partnership | NCI-designated cancer center alliances concentrate complex mediastinal resection volumes in Boston and Houston. |
| Pipeline Diversification | PD-1/PD-L1 checkpoint inhibitor expansion addresses fastest-growing addressable pool in platinum-refractory thymic carcinoma. |
Study Parameters
Document review covered FDA orphan drug designation filings, EMA PRIME eligibility submissions, ClinicalTrials.gov protocol registrations, and NMPA approval databases, complemented by interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors. Secondary validation drew from SEC 10-K pharmaceutical disclosures, hospital procurement databases, and GPO contract repositories. Bottom-up patient-flow modeling and top-down market sizing were triangulated.
Output generation employed treatment-line segmentation by Masaoka-Koga staging, administration route differentiation, and regional regulatory clustering across the analysis window. CAGRs were derived from epidemiological incidence projections, therapy penetration curves, and pricing trajectory assumptions. Forecast inputs incorporated thoracic surgeon training pipeline constraints and platinum salt supply concentration risks.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to biomarker definition evolution and cross-border clinical trial harmonization progress. Forecasts reflect documented assumptions regarding regulatory pathway timelines and reimbursement access expansion. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oncology
Throat Cancer Market
Oncology
Australia Cancer Treatment Market
Oncology
Asia-Pacific Radiation Oncology Market
Oncology
Ewing Sarcoma Treatment Market
Oncology
Global Metastatic Cancer Treatment Market
Oncology
Global Non-Small Cell Lung Cancer (NSCLC) Market
Oncology
Particle Therapy Systems Market
Oncology
Europe Ovarian Cancer Diagnostics and Therapeutics Market
Oncology
Paranasal Sinus Cancer Market
Oncology
Unresectable Hepatocellular Carcinoma Market
Oncology
Adrenocortical Carcinoma Treatment Market
Oncology
Single-Room Proton Therapy Systems Market
Oncology
Glottic Cancer Treatment Market
Oncology
South Korea Radiotherapy Market
Oncology
Testicular Cancer Treatment Market
Oncology
Global Proton Therapy Market