
 India Ultrasound Devices Market | 2026-2036
India Ultrasound Devices Market Size, Share, and Industry Trends Forecast 2026-2036
India Ultrasound Devices Market Foresight
India is tilting toward indigenous ultrasound manufacturing as the PLI scheme draws component suppliers and assembly plants to Gujarat and Tamil Nadu. GE Healthcare leverages its long-standing Bengaluru engineering center to sustain R&D intensity for mid-range cart-based systems. Mindray Medical anchors its competitive stance through aggressive channel control in government hospital tenders across northern states. BPL Medical Technologies competes on price-performance positioning for clinic-grade portable units in Kerala and Tamil Nadu.
Ultrasound devices generate acoustic images through piezoelectric transducers operating at frequencies from two to eighteen megahertz, with beamforming algorithms processing reflected echoes into real-time anatomical visualizations for non-invasive diagnostic screening. Cart-based systems dominate hospital procurement budgets due to superior thermal management and multi-probe connectivity, while handheld segments are capturing margin pools in point-of-care emergency medicine deployments where mobility outweighs image depth. Doppler technology leads cardiology applications, whereas 3D ultrasound is displacing conventional 2D protocols in obstetrics workflows at metro diagnostic centers.
CDSCO's Medical Device Rules mandate risk-based classification and quality management system certification for all ultrasound equipment sold domestically, while BIS enforces electrical safety and electromagnetic compatibility standards that shape product design cycles for manufacturers. The PLI scheme's production-linked incentives are forcing multinational assemblers to rebalance import dependency against local value-add thresholds. Stakeholders must monitor how state-level public health mission budgets allocate capital expenditure between imaging modalities in the coming procurement cycles.
Market Dynamics
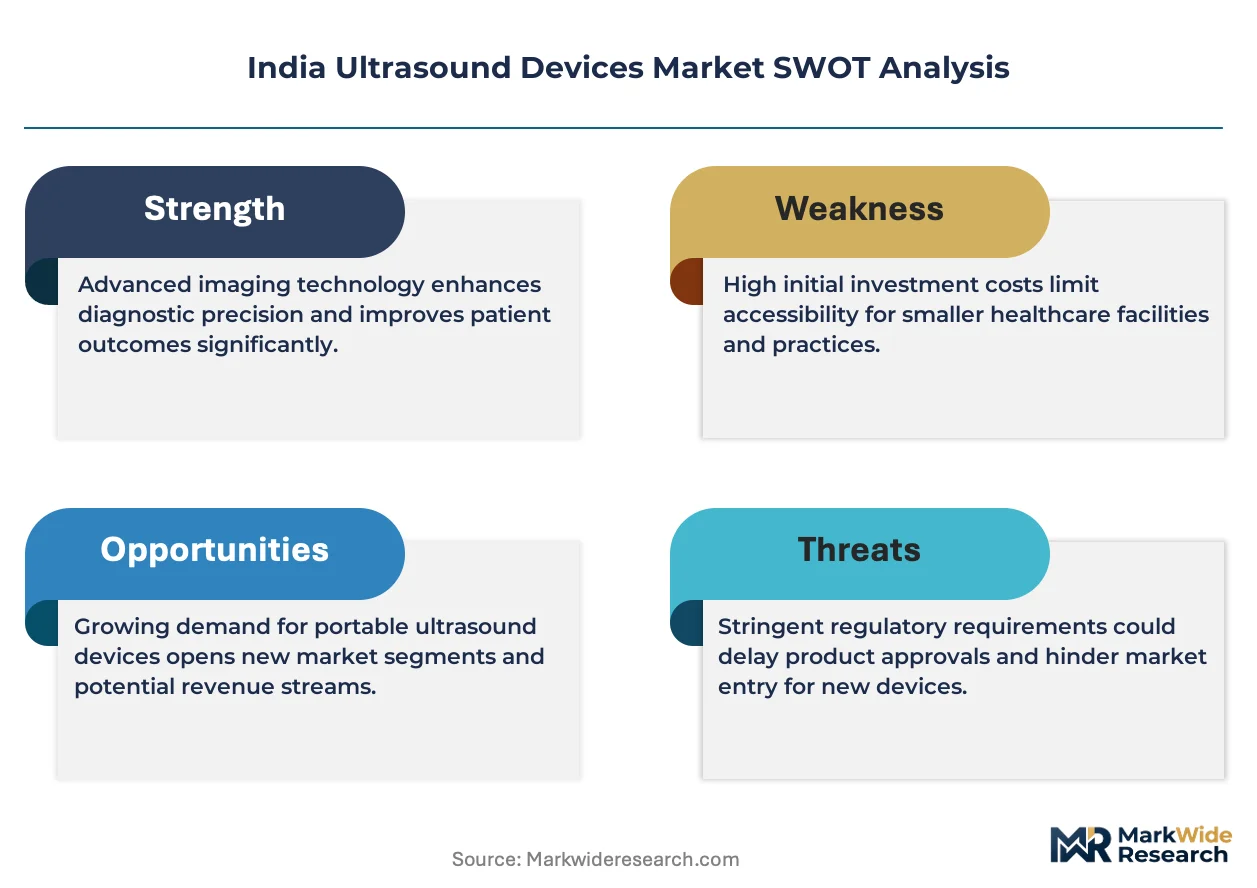
The PLI scheme is restructuring India's ultrasound supply base by mandating local value-add thresholds that multinational assemblers must meet to qualify for production-linked incentives, forcing component localization decisions across transducer manufacturing and system assembly.
Growth Catalysts
- CDSCO Medical Device Rules:Risk-based classification and quality management system certification requirements are professionalizing domestic manufacturing standards and filtering out informal importers.
- Diagnostic center chains:Fleet deployment programs by multi-site operators in Maharashtra, Karnataka, and Tamil Nadu are standardizing procurement volumes for mid-range cart-based systems.
- Tertiary hospital expansion:Tier-2 city hospitals are upgrading imaging infrastructure as state public health missions allocate capital expenditure toward non-invasive diagnostic screening capabilities.
Market Restraints
- Piezoelectric crystal supply:Import dependency on specialized ceramic substrates for transducer manufacturing creates input cost volatility and foreign exchange exposure for domestic assemblers.
- Technical imaging limitations:Handheld ultrasound devices sacrifice penetration depth and thermal management capacity compared to cart-based systems, restricting cardiology and deep-tissue applications.
- BIS electromagnetic compatibility standards:Electrical safety certification timelines extend product design cycles and delay market entry for new equipment categories.
Strategic Opportunities
- Point-of-care emergency medicine:Mobile ultrasound deployment in accident response and rural triage settings creates demand for portable units where image depth is secondary to immediate availability.
- 3D obstetrics protocols:Metro diagnostic centers are displacing conventional 2D workflows with volumetric imaging for fetal assessment, opening premium service tier differentiation.
- Gujarat-Tamil Nadu manufacturing clusters:PLI scheme incentives are concentrating component suppliers and assembly plants in these states, enabling integrated domestic supply chains.
Industry Challenges
- Beamforming algorithm expertise:Shortage of signal processing engineers with ultrasound-specific firmware experience constrains R&D scaling for domestic manufacturers.
- CDSCO quality management certification:Extended audit timelines and documentation requirements delay product launches for first-time market entrants.
- Multi-probe connectivity integration:Legacy hospital IT infrastructure in government facilities creates compatibility friction during system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Ultrasound Devices Market |
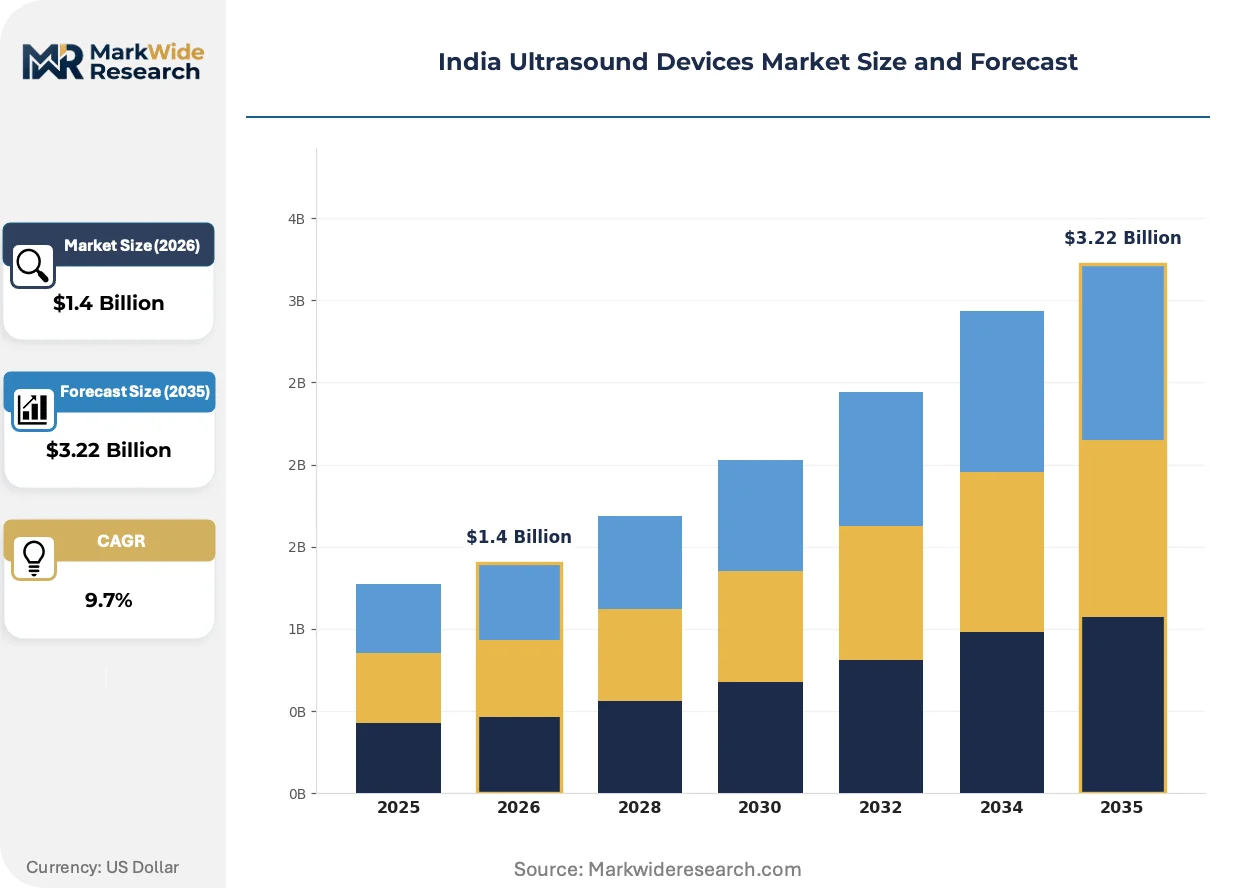
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $3.22 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Portable, Cart-based, Handheld, Trolley-based Technology: 3D Ultrasound, Doppler Ultrasound, Color Ultrasound, 2D Ultrasound End User: Clinics, Hospitals, Diagnostic Centers, Research Institutions Application: Obstetrics, Cardiology, Urology, Emergency Medicine |
| Companies Covered | Mindray Medical, FUJIFILM Healthcare, Philips Healthcare, Samsung Medison, Hitachi Healthcare, GE Healthcare, Canon Medical Systems, BPL Medical Technologies, Siemens Healthineers, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Ultrasound Devices Market Shifts & Advancements
Ultrasound technology is fragmenting across performance tiers as artificial intelligence inference engines and cloud-based image archiving compress the functional gap between premium hospital systems and portable point-of-care devices.
AI-assisted image interpretation is hybridizing conventional ultrasound workflows by embedding real-time anatomical recognition algorithms directly into system firmware. Tertiary care radiology departments in tier-2 cities are piloting these capabilities to reduce operator-dependent variability in cardiac and obstetric screening. The technology is compressing training requirements for sonographers while enabling faster diagnostic turnaround in high-volume outpatient settings.
BIS enforcement of updated electromagnetic compatibility standards is reshaping product design cycles for equipment manufacturers serving the domestic market. Compliance testing now requires documented shielding validation and emissions control that extends prototype-to-production timelines. Cart-based system assemblers with established Bengaluru and Chennai engineering centers are absorbing these costs more readily than new market entrants dependent on fully-imported platforms.
Government hospital tender processes are consolidating vendor relationships through multi-year maintenance contracts that bundle equipment supply with technician training and spare part availability. Northern state health departments are leading this transition, displacing transaction-based purchasing that prioritized lowest capital cost over total cost of ownership. Kerala and Tamil Nadu diagnostic chains are mirroring this approach in private procurement, favoring suppliers with localized service networks over distant distributors.
India Ultrasound Devices Market Segmentation
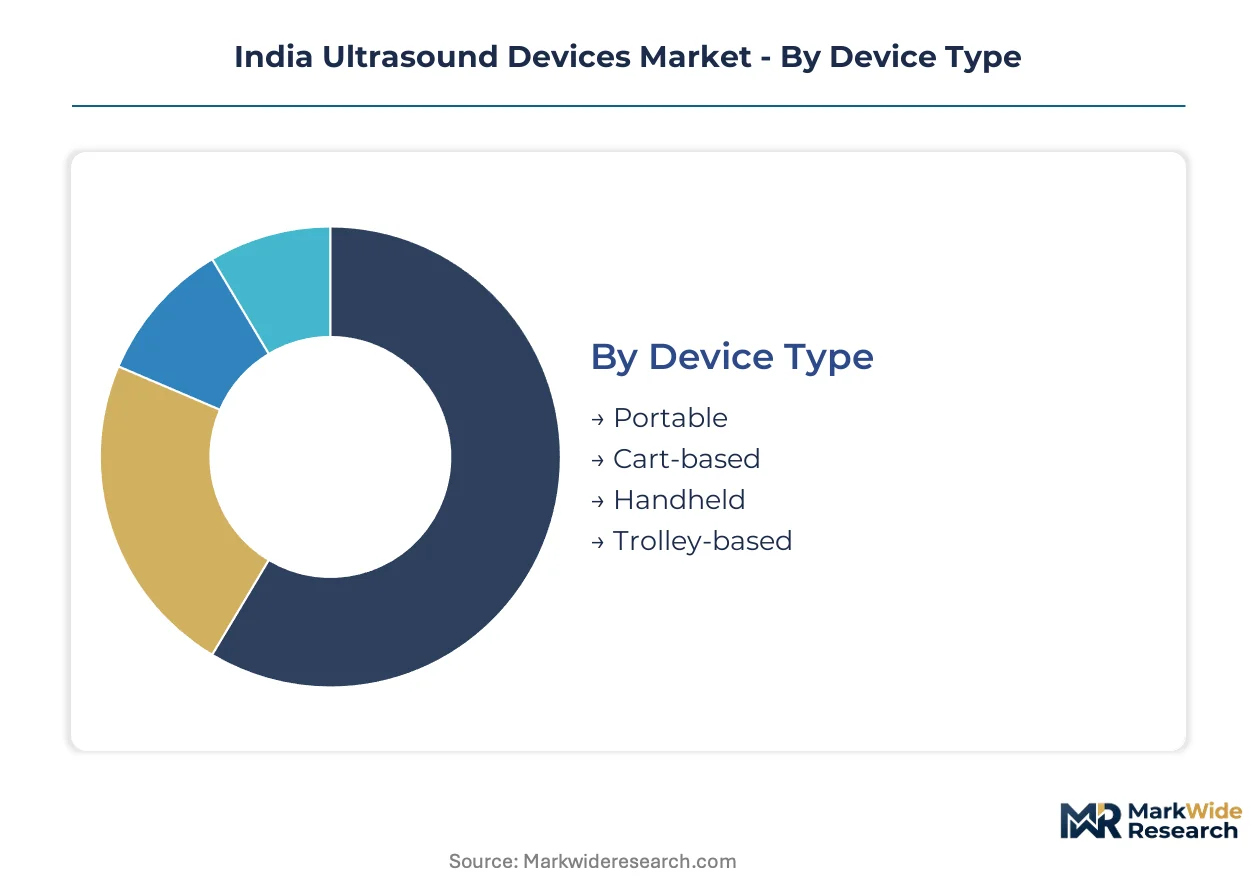
Ultrasound device segmentation in India reflects divergent procurement priorities across care settings. State health missions, diagnostic chains, and private clinics each drive distinct specification requirements that manufacturers must address through targeted product portfolios.
Device Type:
The use-case spectrum spans emergency response vehicles to tertiary radiology departments, with mobility and thermal capacity defining procurement trade-offs.
- Cart-based:These systems integrate multi-probe connectivity and superior thermal management for sustained high-volume scanning. Tertiary hospitals in tier-2 cities across Maharashtra and Karnataka prioritize these units for cardiology and deep-tissue protocols where image fidelity is non-negotiable.
- Portable:Battery-powered units with simplified probe interfaces serve point-of-care deployments. Government hospital tenders in northern states are scaling portable procurement for rural outreach programs where infrastructure constraints limit cart-based installation.
- Handheld:Smartphone-connected transducers deliver basic imaging for triage screening. Kerala's clinic networks are piloting these for preliminary obstetric assessments in remote panchayats.
- Trolley-based:Intermediate form factors balance mobility with probe expansion capability. Tamil Nadu diagnostic chains deploy these for multi-specialty outpatient centers requiring flexible room utilization.
The dominant share belongs to cart-based systems, while handheld units are gaining share fastest through emergency medicine adoption.
Technology:
Cost tier stratification separates premium volumetric imaging from standard grayscale protocols, with reimbursement rates reinforcing this hierarchy.
- Doppler Ultrasound:Frequency-shift detection enables real-time blood flow visualization for cardiac valve assessment and vascular patency evaluation. Cardiology departments at Bengaluru and Chennai metro hospitals mandate Doppler capability for structural heart disease screening programs.
- 3D Ultrasound:Volumetric reconstruction from multiple 2D planes generates surface-rendered fetal images. Premium diagnostic chains in Mumbai and Delhi NCR are displacing conventional protocols with 3D workflows for expectant parents seeking enhanced visualization.
- 2D Ultrasound:Conventional grayscale imaging remains the workhorse for general abdominal and pelvic screening. Government hospital procurement specifications continue standardizing on 2D systems for cost-controlled fleet deployment.
- Color Ultrasound:Velocity-encoded overlay maps flow direction and turbulence onto anatomical frames. Urology and nephrology practices utilize color Doppler for renal artery stenosis assessment in hypertension management protocols.
Doppler systems command the largest installed base, though 3D platforms are climbing the fastest through private diagnostic center upgrade cycles.
End User:
Volume concentration varies sharply across customer types, with capital allocation cycles and maintenance requirements reshaping vendor relationships.
- Hospitals:Tertiary and secondary facilities drive procurement through state public health mission budgets. Multi-year maintenance contracts bundling technician training and spare part availability are displacing transaction-based purchasing in northern state health departments.
- Diagnostic Centers:Multi-site operators standardize fleet deployments to achieve procurement scale and reporting consistency. Maharashtra, Karnataka, and Tamil Nadu chains are consolidating vendor relationships around suppliers with localized service networks.
- Clinics:Single-physician and small-group practices prioritize price-performance positioning for basic obstetric and abdominal screening. BPL Medical Technologies and similar domestic assemblers compete aggressively in this tier through Kerala and Tamil Nadu distribution.
- Research Institutions:Academic medical centers and biotechnology incubators utilize specialized transducers for preclinical imaging and device validation studies. Bengaluru's engineering research ecosystem generates concentrated demand for experimental beamforming platforms.
Hospital procurement absorbs the dominant equipment volume, while diagnostic center chains are expanding their share fastest through standardized fleet programs.
Application:
Margin structure and reimbursement intensity vary across clinical domains, with obstetrics and cardiology commanding premium positioning.
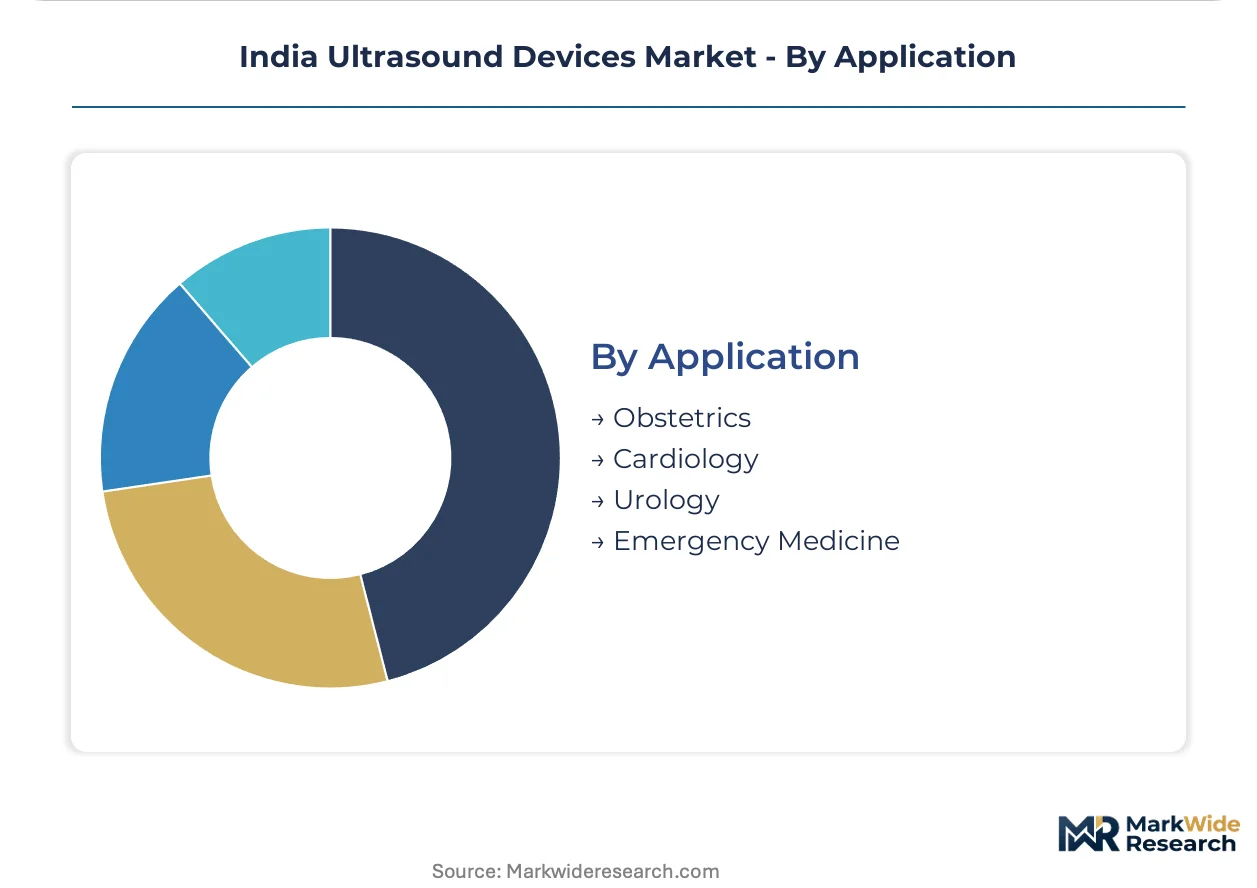
- Obstetrics:Fetal biometry and anatomical survey protocols constitute the highest-volume ultrasound application nationwide. Metro diagnostic centers are differentiating service tiers through 3D volumetric imaging for enhanced parental visualization.
- Cardiology:Echocardiography demands specialized phased-array transducers and Doppler processing for structural and functional assessment. Tier-2 city hospital expansion programs are prioritizing cardiac imaging capacity in state cardiovascular disease control missions.
- Emergency Medicine:Point-of-care deployment for trauma triage and procedural guidance prioritizes immediate availability over image depth. Accident response infrastructure in Gujarat and Tamil Nadu is integrating portable ultrasound into pre-hospital care protocols.
- Urology:Renal, bladder, and prostate imaging supports nephrolithiasis management and cancer screening workflows. Specialist urology chains in Delhi NCR and Mumbai are standardizing on mid-range systems with dedicated endocavity probes.
Obstetrics maintains the dominant procedure volume, though emergency medicine is expanding most quickly through government pre-hospital care investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Karnataka deploy cart-based systems for high-volume tertiary screening, while Kerala's clinic networks favor portable units for rural outreach. Tamil Nadu diagnostic chains standardize on mid-range trolley systems for flexible outpatient utilization.
Maharashtra
Mumbai and Pune metro hospitals drive demand for 3D obstetrics and Doppler cardiology systems. CDSCO's Medical Device Rules mandate quality management certification for all equipment imports. Multi-site diagnostic chains in Mumbai-Nashik corridor consolidate procurement around vendors with localized service networks.
Karnataka
Bengaluru's tertiary hospitals anchor procurement of AI-assisted cart-based systems for cardiac screening programs. The PLI scheme accelerates component localization for transducer manufacturing. GE Healthcare's Bengaluru engineering center sustains R&D intensity for mid-range system development.
Tamil Nadu
Chennai diagnostic chains scale 3D ultrasound deployment for premium obstetrics differentiation. BIS electromagnetic compatibility standards extend product design cycles for domestic assemblers. PLI scheme incentives concentrate assembly plants and component suppliers in Chennai-Coimbatore manufacturing corridor.
Gujarat
Ahmedabad and Surat hospitals expand portable ultrasound procurement for government rural health missions. State public health mission budgets allocate capital expenditure toward point-of-care emergency medicine infrastructure. Manufacturing clusters in Sanand and Vadodara attract PLI-qualified component suppliers for transducer assembly.
Kerala
Thiruvananthapuram and Kochi clinic networks pilot handheld ultrasound for preliminary obstetric screening in remote panchayats. CDSCO risk-based classification filters informal importers from formal procurement channels. BPL Medical Technologies competes aggressively on price-performance positioning for clinic-grade portable units.
India Ultrasound Devices Market Competitive Landscape
Capability concentration sits with multinational engineering centers; scale advantage sits with domestic assemblers leveraging PLI incentives. The market structures around three tiers: premium cart-based system suppliers, mid-range portable specialists, and economy clinic-grade fabricators. Dominant competitive moves include backward integration into transducer component manufacturing and multi-year maintenance contract bundling for government tenders.
Among multinational healthcare technology groups, GE Healthcare, Philips Healthcare, and Siemens Healthineers occupy positions anchored by established engineering infrastructure and long-standing hospital relationships. GE Healthcare exemplifies the R&D-intensive archetype through its Bengaluru center, while Philips Healthcare and Siemens Healthineers represent scale-driven procurement consolidation in northern state government tenders. Domestic specialists including Mindray Medical and BPL Medical Technologies sit within the price-performance tier, with Mindray anchoring government hospital channel control and BPL Medical Technologies exemplifying clinic-focused portable system deployment in southern states.
| Leading Market Players |
|---|
| Mindray Medical |
| FUJIFILM Healthcare |
| Philips Healthcare |
| Samsung Medison |
| Hitachi Healthcare |
| GE Healthcare |
| Canon Medical Systems |
| BPL Medical Technologies |
| Siemens Healthineers |
| Others |
Supply & Pricing Matrix
Chennai-Coimbatore manufacturing corridor capacity expansion feeds downstream pricing leverage for domestic assemblers qualifying under PLI scheme thresholds, compressing import-dependent competitors' margin room as local value-add requirements harden.
Pricing Analysis
Mumbai-Delhi price spreads for equivalent cart-based systems reach 15-20% due to service network density and state-level tender bundling practices. Three-tier pricing structure across premium, standard, and economy levels separates GE Healthcare and Siemens Healthineers installations from Mindray Medical government contracts and BPL Medical Technologies clinic deployments. Cost compression in portable segments intensifies because domestic assemblers exploit PLI incentives to undercut multinational landed costs. Government hospital procurement committees exhibit highest price sensitivity, while metro diagnostic chains prioritize total cost of ownership over capital outlay.
Supply Chain Analysis
Extended payment terms from Tamil Nadu component suppliers to Gujarat assembly plants have become standard practice under PLI scheme working capital support facilities. China, Japan, and Germany supply piezoelectric ceramic substrates, precision acoustic lenses, and FPGA chipsets that domestic transducer manufacturing draws from. Single-source vulnerability concentrates in specialized PZT crystal vendors located in Osaka and Shenzhen industrial zones. Distribution runs through regional medical equipment distributors with state-level tender registration, who warehouse inventory in Bengaluru, Mumbai, and Delhi NCR logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory-entrenchment defensive moat where CDSCO quality management certification and PLI localization thresholds create switching costs that favor established assemblers with sunk compliance investment.
For Market Incumbents: Pre-empt emerging domestic competitors by accelerating backward integration into transducer crystal manufacturing through Tamil Nadu supplier partnerships, while locking northern state government tenders with multi-year maintenance contracts that bundle technician training and spare part availability to raise replacement friction. For New Entrants and Emerging Players: Kerala's handheld ultrasound underpenetration in remote panchayat clinics offers white-space access where smartphone-connected transducers bypass cart-based infrastructure constraints. Target tier-2 city emergency medicine departments in Gujarat and Rajasthan with portable units priced below Mindray Medical government contract rates, leveraging direct clinic sales relationships to circumvent distributor margin stacking. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because PLI scheme maturation will strand sub-scale assemblers unable to meet local value-add thresholds, creating acquisition targets with certified manufacturing infrastructure and state tender relationships. Signal to monitor: CDSCO audit queue length for first-time market entrants, which indicates regulatory barrier height and incumbent protection intensity.| Strategic Initiative | Industry Significance |
|---|---|
| CDSCO Quality Management Certification | Filters informal importers from formal procurement channels under Medical Device Rules risk-based classification. |
| Backward Integration into Transducer Manufacturing | Reduces import dependency on Japanese and Chinese piezoelectric crystal suppliers for domestic assemblers. |
| Multi-Year Maintenance Contract Bundling | Displaces transaction-based purchasing in northern state health departments through total cost of ownership positioning. |
| AI-Assisted Image Interpretation Development | Compresses sonographer training requirements for tier-2 city cardiac screening program expansion. |
| Gujarat-Tamil Nadu Manufacturing Cluster Concentration | Enables integrated domestic supply chains under PLI scheme component localization incentives. |
Research Methodology
Operator-level perspectives from hospital biomedical engineers, diagnostic center procurement heads, CDSCO regulatory affairs specialists, and state health mission budget officers anchored the qualitative base, cross-referenced with secondary validation from CDSCO medical device registration databases, BIS electromagnetic compatibility certification records, PLI scheme beneficiary disclosures, and hospital tender award documents published by Maharashtra, Karnataka, and Tamil Nadu e-procurement portals. Bottom-up equipment installation tracking and top-down healthcare capital expenditure allocation analysis triangulated volume estimates.
Scenario-bracketing framed demand projections across the analysis window, modeling segmentation dimensions including device mobility tier, imaging technology protocol, end-user facility type, and clinical application intensity. CAGRs derived from weighted average of historical procurement trajectory, state public health mission budget allocation patterns, and diagnostic chain fleet expansion announcements. Industry-specific inputs incorporated transducer replacement cycle timing and AI firmware upgrade penetration assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese portable ultrasound manufacturers or accelerated PLI scheme relaxation would shift outcomes. Macroeconomic rupee depreciation against yen and euro, CDSCO regulatory enforcement intensity variation, or breakthrough solid-state transducer technology commercialization would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
South Africa Nuclear Imaging Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Global Pediatric Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Magnetoencephalography (MEG) Market
Medical Imaging
Global Medical Image Management Market
Medical Imaging
Global Colposcopy Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
3D Medical and Surgical Imaging Platform Market
Medical Imaging
Australia Magnetic Resonance Imaging Market
Medical Imaging
Nuclear Magnetic Resonance Spectroscopy Market
Medical Imaging
Orthopedic Imaging Market
Medical Imaging
Remanufactured Medical Imaging Devices Market
Medical Imaging
Cone Beam Computed Tomography (CBCT) System Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Forensic Imaging Market
Medical Imaging
Global Image Guided Therapy System Market