
 Italy Infectious Disease in-Vitro Diagnostics Market | 2026-2036
Italy Infectious Disease in-Vitro Diagnostics Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Infectious Disease in-Vitro Diagnostics Market Insights
Consolidation among hospital procurement consortia in northern Italy is repositioning vendor access across the infectious disease diagnostics landscape. Roche Diagnostics leverages its installed base of automated immunoassay systems to sustain service contracts with major regional health authorities. Abbott Laboratories anchors its position through point-of-care molecular platforms deployed in emergency departments.
Infectious disease in-vitro diagnostics encompasses laboratory-based and near-patient testing systems that detect bacterial, viral, fungal, or parasitic pathogens through nucleic acid amplification, antigen-antibody binding, or culture-based methods, typically requiring specimen volumes of 10-500 microliters and turnaround times ranging from 15 minutes to 48 hours depending on platform complexity. PCR reagent kits command premium pricing in centralized hospital laboratories where batch throughput justifies capital investment, while rapid test formats gain traction in clinic settings where same-day clinical decisions reduce patient leakage. Digital diagnostics platforms represent the fastest-expanding technology segment as Italian laboratories integrate cloud-based result interpretation to offset staffing constraints.
Italy's Ministry of Health reimbursement protocols, CE marking requirements under EU MDR, and regional health authority procurement frameworks collectively shape product commercialization timelines and pricing negotiations. The National Institute of Health coordinates reference standard validation that manufacturers must complete before inclusion in public tender lists. Stakeholders must monitor evolving EU AI Act implementation timelines for algorithm-based diagnostic software that could reclassify certain digital pathology tools as regulated medical devices.
Market Dynamics
Hospital procurement consortia consolidation across Lombardy, Veneto, and Emilia-Romagna is concentrating purchasing power into fewer regional health authority clusters, forcing diagnostic vendors to restructure contract negotiations around multi-year service agreements rather than discrete instrument sales.
Growth Catalysts
- EU MDR framework:Updated CE marking requirements under the Medical Device Regulation are accelerating laboratory upgrades to compliant platforms, creating replacement demand for legacy systems in centralized hospital laboratories.
- Point-of-care molecular platforms:Emergency departments in Milan and Bologna are deploying rapid nucleic acid amplification systems to reduce patient leakage and compress antibiotic stewardship decision timelines.
- Lombardy clinical laboratory cluster:Dense concentration of tertiary care centers around Milan generates batch throughput volumes that justify premium PCR reagent kit procurement and automated liquid handling investments.
Market Restraints
- Reagent supply concentration:Dependence on German and Swiss polymerase enzyme suppliers exposes Italian laboratories to cross-border logistics friction and euro-denominated input cost volatility.
- EU AI Act implementation timelines:Uncertainty around algorithm-based diagnostic software classification is freezing procurement decisions for cloud-enabled result interpretation tools pending regulatory clarity.
- Skilled technician scarcity:Northern Italy faces persistent vacancies in clinical laboratory technologist roles, constraining utilization rates for complex molecular testing platforms even where capital equipment is installed.
Strategic Opportunities
- Southern Italy underpenetration:Campania, Sicily, and Calabria maintain lower molecular testing density per capita, presenting whitespace for decentralized point-of-care networks and mobile laboratory services.
- Digital diagnostics convergence:Integration of artificial intelligence-assisted image analysis with traditional immunoassay workflows is opening new reimbursement pathways under Italy's Ministry of Health early pathogen detection protocols.
- Pharmacy channel expansion:Legislative pilot programs in Tuscany and Piedmont are authorizing community pharmacies to administer rapid infectious disease screening, bypassing traditional hospital laboratory gatekeeping.
Industry Challenges
- Laboratory information system integration:Legacy hospital IT architectures in Emilia-Romagna and Veneto require costly middleware development to connect new diagnostic platforms with electronic health record systems.
- Reference standard validation timelines:National Institute of Health certification processes for novel assay formats extend commercialization lead times by 12-18 months, compressing effective patent protection windows.
- Antimicrobial resistance surveillance data interoperability:Fragmented reporting standards between regional health authorities impede nationwide pathogen resistance pattern aggregation for assay development targeting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Infectious Disease in-Vitro Diagnostics Market |
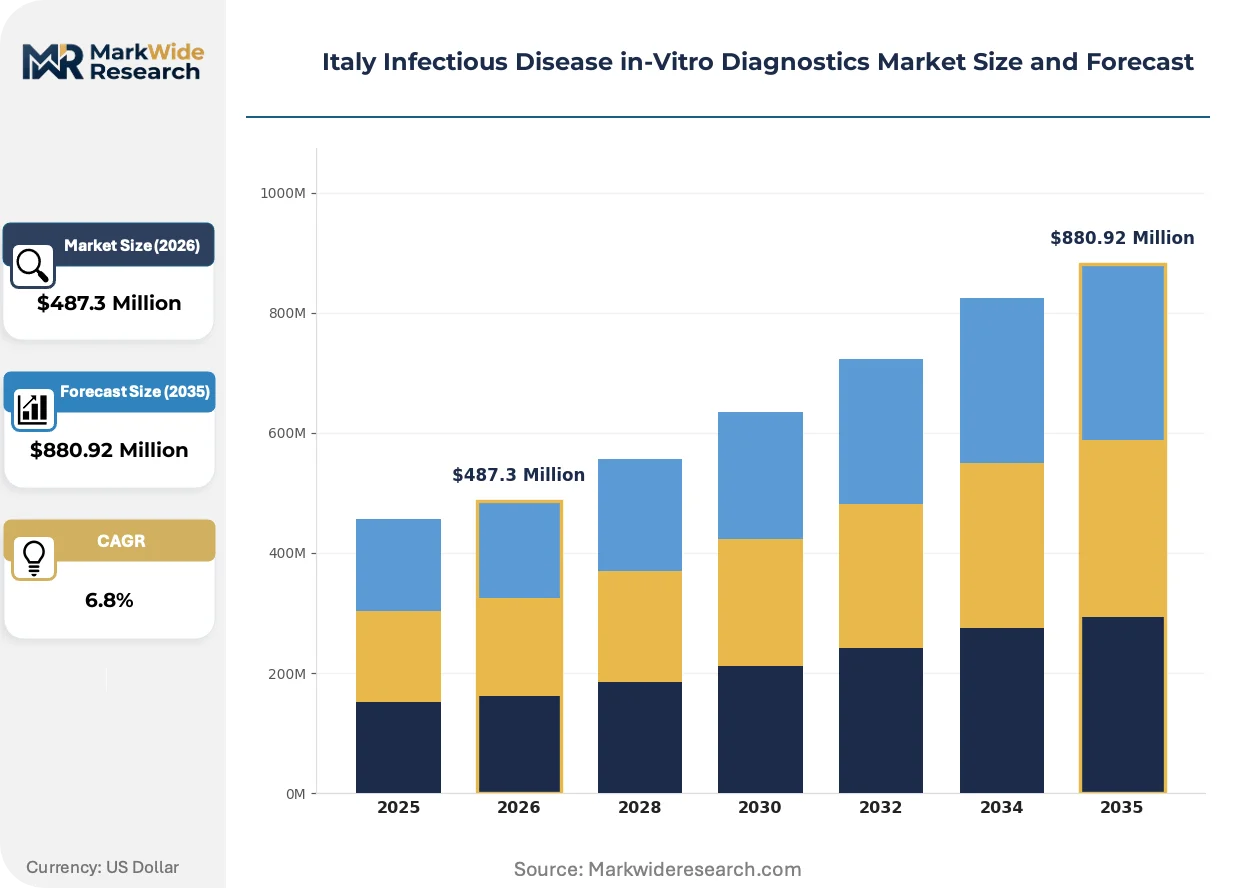
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PCR, ELISA, Microarray, Rapid Tests Technology: Reagent Kits, Automation Systems, Assay Platforms, Digital Diagnostics End User: Hospitals, Laboratories, Clinics, Research Institutions Delivery Mode: Point-of-Care Testing, Centralized Laboratory Testing, Home Testing, Mobile Testing Units |
| Companies Covered | Roche Diagnostics, Abbott Laboratories, Siemens Healthineers, Danaher, Thermo Fisher Scientific, bioMérieux, QIAGEN, Becton Dickinson, DiaSorin, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Infectious Disease in-Vitro Diagnostics Market Trends and Innovations
Automation of specimen processing and result interpretation is compressing turnaround times while cloud-based connectivity is enabling remote quality oversight across Italy's distributed laboratory network.
Random access molecular analyzers are automating nucleic acid extraction, amplification, and detection workflows within single integrated instruments. Tertiary hospital laboratories in Turin and Genoa are deploying these platforms to eliminate batch processing delays and extend operating hours without proportional staffing increases. This automation is compressing the cost-per-test economics that previously favored centralized reference laboratories, enabling mid-volume hospital sites to retain infectious disease testing in-house rather than outsourcing.
Italy's Ministry of Health reimbursement protocol revisions now prioritize early pathogen detection assays over culture-based methods in public tender evaluations. The industrial consequence is a pricing premium for molecular platforms demonstrating superior time-to-result metrics versus traditional microbiology workflows. Lombardy's regional health authority has responded by mandating multiplex respiratory panel adoption across its emergency department network, displacing sequential single-target testing protocols.
Consolidated procurement through northern Italy's hospital purchasing consortia is replacing individual hospital tender processes with framework agreements spanning multiple regional health authorities. Instrument vendors now negotiate multi-year service contracts covering reagent supply, maintenance, and software updates rather than competing on capital equipment price alone. This behavioral shift is most visible in Veneto, where the Azienda Zero procurement hub aggregates demand from 21 hospital trusts into single-source diagnostic platform selections.
Italy Infectious Disease in-Vitro Diagnostics Market Segmentation
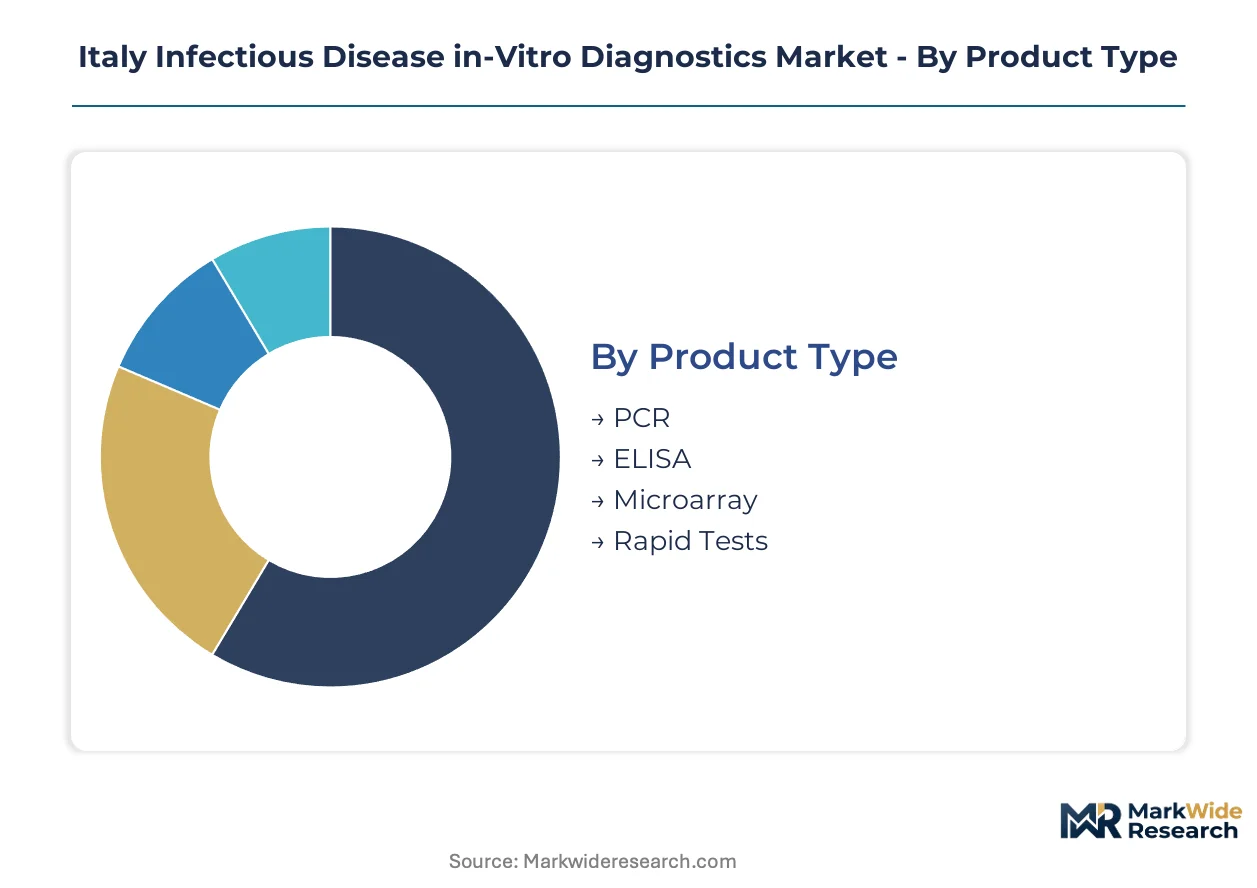
Segmentation of Italy's infectious disease in-vitro diagnostics market reveals how procurement concentration, reimbursement protocols, and laboratory infrastructure shape technology adoption patterns across the peninsula. Understanding these divisions exposes where vendor contracting power concentrates and where whitespace opportunities persist.
Product Type:
Standardization dominates PCR and ELISA platforms where CE marking under EU MDR enables broad hospital laboratory deployment, while rapid tests retain customization flexibility for clinic-level procurement outside consolidated purchasing frameworks.
- PCR:Nucleic acid amplification platforms detect pathogen genetic material with analytical sensitivity reaching single-copy detection thresholds. Lombardy's tertiary hospital cluster around Milan deploys multiplex respiratory panels to compress antibiotic stewardship timelines. EU MDR compliance requirements are accelerating replacement of legacy thermal cyclers with integrated extraction-amplification systems.
- ELISA:Enzyme-linked immunosorbent assays bind antigen-antibody pairs for quantitative serological screening. Veneto's Azienda Zero procurement hub aggregates demand for automated immunoassay workstations across 21 hospital trusts. Reagent kit standardization enables multi-year service contracting that locks in vendor relationships.
- Microarray:High-density probe arrays enable parallel pathogen detection from single specimens. Research institutions in Turin and Genoa deploy these for antimicrobial resistance surveillance.
- Rapid Tests:Lateral flow and immunochromatographic formats deliver qualitative results within 15-30 minutes. Tuscany's pharmacy pilot programs authorize community-based screening outside hospital gatekeeping.
Most installed capacity flows through PCR. Expansion is steepest in rapid tests.
Technology:
Margin structures diverge sharply between consumable reagents with recurring revenue streams and capital equipment requiring upfront procurement committee approval.
- Reagent Kits:Polymerase enzymes, primers, and master mixes constitute the recurring consumable base for molecular platforms. German and Swiss suppliers dominate enzyme manufacturing, exposing Italian laboratories to euro-denominated input cost volatility and cross-border logistics friction.
- Automation Systems:Robotic liquid handlers and integrated sample-to-result platforms reduce manual technologist touchpoints. Northern Italy faces persistent clinical laboratory staffing vacancies that constrain utilization rates even where capital equipment is installed.
- Assay Platforms:Instrument-reagent combinations validated for specific pathogen menus. National Institute of Health certification extends commercialization timelines.
- Digital Diagnostics:Cloud-enabled result interpretation and AI-assisted image analysis. EU AI Act uncertainty is freezing procurement decisions pending algorithm classification clarity.
Reagent kits generate the recurring revenue base. Digital diagnostics is climbing the fastest.
End User:
Procurement authority concentration varies from centralized regional health authority frameworks to fragmented individual clinic purchasing.
- Hospitals:Tertiary care centers with centralized laboratory infrastructure and consolidated procurement consortia. Lombardy, Veneto, and Emilia-Romagna health authorities negotiate multi-year framework agreements spanning instrument, reagent, and service bundles.
- Laboratories:Independent and hospital-affiliated testing facilities with batch throughput economics. Milan's dense clinical laboratory cluster justifies premium PCR reagent kit procurement through volume aggregation.
- Clinics:Outpatient facilities with limited on-site testing capability. Point-of-care molecular platforms reduce patient leakage to external reference laboratories.
- Research Institutions:Academic and public health laboratories conducting surveillance and assay development. Antimicrobial resistance data interoperability gaps between regional authorities impede nationwide pattern aggregation.
Hospital procurement commands the largest contract values. Clinic deployment is expanding most quickly.
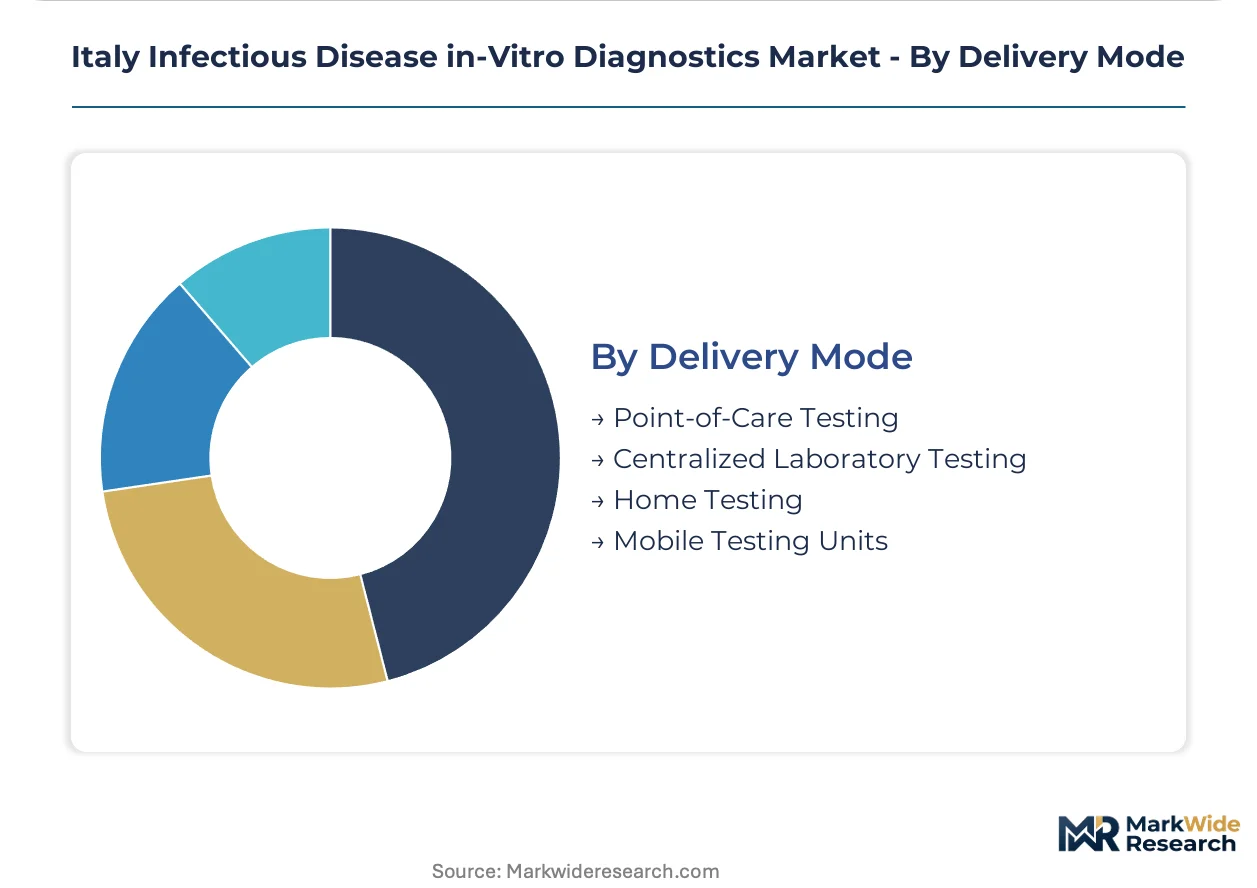
Delivery Mode:
Geographic reach and infrastructure requirements separate centralized high-throughput models from distributed access strategies.
- Point-of-Care Testing:Near-patient platforms deployed in emergency departments and clinics. Milan and Bologna hospitals deploy rapid nucleic acid amplification to compress time-to-treatment decisions.
- Centralized Laboratory Testing:High-volume reference facilities with automated batch processing. Northern Italy's procurement consortia concentrate purchasing power into fewer vendor relationships.
- Home Testing:Self-collected specimen kits with mail-back or digital result delivery. Regulatory pathways under Italy's Ministry of Health remain less developed than hospital-based protocols.
- Mobile Testing Units:Deployable laboratory capacity for outbreak response and rural access. Campania, Sicily, and Calabria present whitespace for decentralized network expansion.
Centralized laboratory testing anchors current infrastructure investment. Mobile testing units show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands Europe's largest molecular diagnostics installed base while Italy's procurement consortia consolidation is accelerating vendor contract restructuring across the Mediterranean basin.
Germany
Bavaria's medical technology corridor around Munich and Erlangen houses polymerase enzyme manufacturing facilities that supply Italian hospital laboratories. EMA guidance on companion diagnostics shapes assay validation protocols that Italian manufacturers reference for CE marking submissions. The Baden-Württemberg cluster around Heidelberg and Freiburg anchors automated liquid handler production for export to Lombardy.
France
Île-de-France's diagnostic reagent manufacturers export respiratory panel components to northern Italian procurement consortia. ANSM oversight of in-vitro medical devices creates regulatory precedent that Italian laboratories monitor for MDR compliance timing. The Lyon biotech cluster specializes in antimicrobial resistance surveillance tools deployed in Turin and Genoa research partnerships.
Switzerland
Swissmedic's streamlined CE marking procedures attract Italian manufacturers seeking faster EU MDR transition pathways. Basel's pharmaceutical-diagnostics nexus supplies thermostable polymerase enzymes to Milan's tertiary hospital laboratories. The Zurich instrumentation corridor exports random access molecular analyzers to Veneto's Azienda Zero procurement hub.
United Kingdom
Greater London's digital health infrastructure influences Italian cloud-based diagnostics platform architecture. MHRA guidance on algorithm-based medical devices precedes EU AI Act implementation timelines that freeze Italian procurement decisions. The Cambridge life sciences cluster develops multiplex assay formats later validated through Italy's National Institute of Health.
Italy Infectious Disease in-Vitro Diagnostics Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Italy's infectious disease diagnostics procurement landscape. Consolidated hospital purchasing consortia in Lombardy and Veneto favor vendors offering multi-year service bundles over discrete instrument transactions. Three archetypes dominate: integrated diagnostics conglomerates with automated platform portfolios, molecular testing specialists with PCR assay depth, and point-of-care platform developers targeting emergency department deployment. Competitive positioning hinges on securing framework agreements with regional health authorities and achieving National Institute of Health reference standard validation.
Among the integrated diagnostics tier, Roche Diagnostics and Siemens Healthineers exemplify vendors leveraging installed bases of automated immunoassay systems to sustain service contracts. Abbott Laboratories occupies a distinct position through point-of-care molecular platforms deployed in emergency departments. Danaher represents the life sciences conglomerate archetype with exposure across reagent manufacturing and instrumentation segments.
| Leading Market Players |
|---|
| Roche Diagnostics |
| Abbott Laboratories |
| Siemens Healthineers |
| Danaher |
| Thermo Fisher Scientific |
| bioMérieux |
| QIAGEN |
| Becton Dickinson |
| DiaSorin |
| Others |
Pricing and Supply Chain Analysis
Hospital procurement consortia concentration across Lombardy, Veneto, and Emilia-Romagna anchors contract-based pricing where multi-year service bundles displace discrete instrument transactions. EU MDR compliance timelines and National Institute of Health certification requirements compress vendor pricing flexibility while locking in reagent supply commitments.
Pricing Analysis
Capacity additions in Switzerland and Germany are reshaping price floors for thermostable polymerase enzymes and automated liquid handling systems. Three-tier pricing structure across premium, standard, and economy levels stratifies by CE marking tier and batch throughput volume. Pricing pressure stems from consolidated procurement frameworks that aggregate demand across 21-hospital trust networks. Emergency departments demonstrate lowest price sensitivity due to antibiotic stewardship decision timelines, while independent laboratories face acute cost compression.
Supply Chain Analysis
CE marking under EU MDR and National Institute of Health reference standard validation function as dual gating mechanisms for vendor market access. Manufacturing concentrates in Germany, Switzerland, and France for polymerase enzymes, robotic components, and respiratory panel reagents. Italian laboratories draw from German and Swiss suppliers for critical inputs including thermostable polymerases, magnetic bead extraction kits, and optical detection modules. Single-source vulnerability runs through cross-border enzyme supply chains exposed to euro-denominated cost volatility. Distribution runs through regional health authority procurement hubs that aggregate demand into framework agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
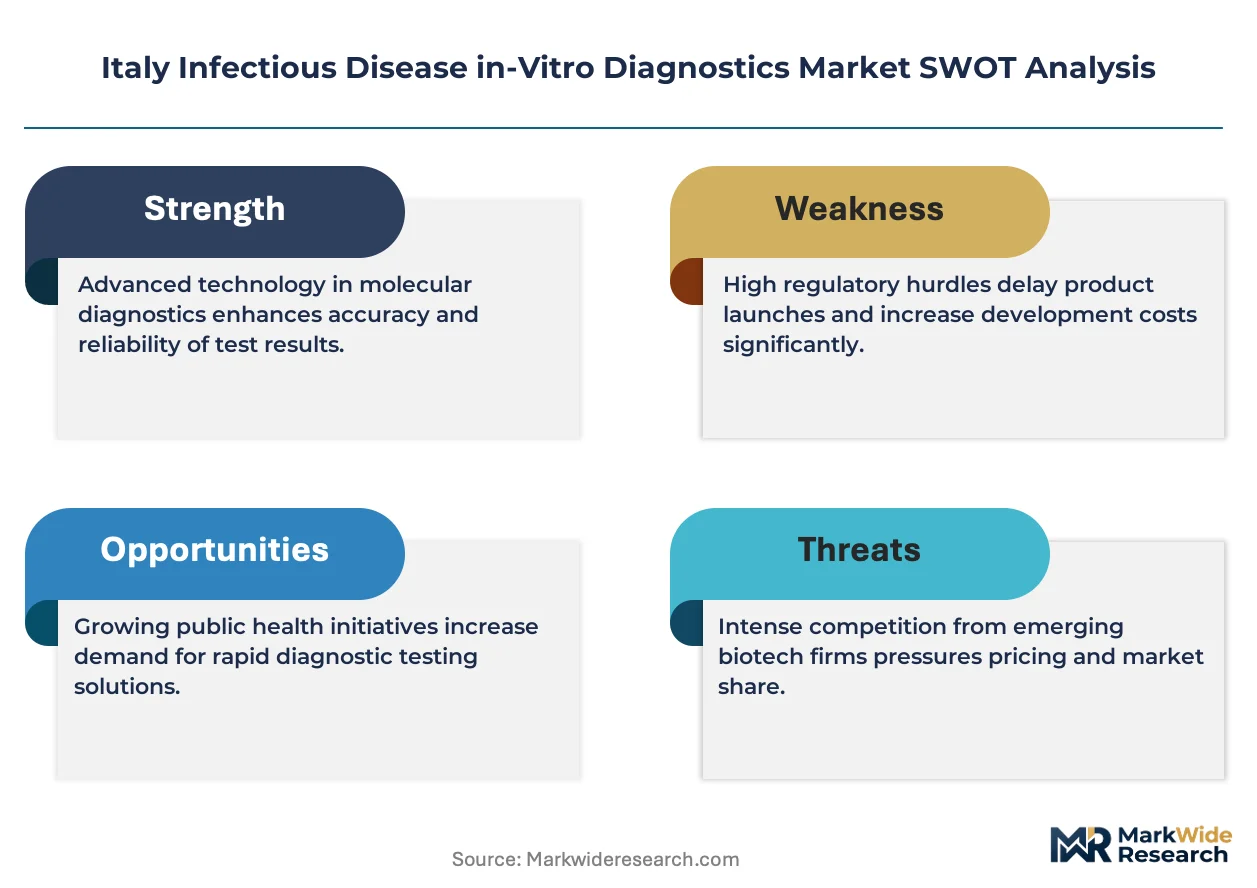
The Italy infectious disease in-vitro diagnostics market functions as a geographic-arbitrage play where southern underpenetration offers expansion runway against northern procurement consolidation. Switzerland's streamlined Swissmedic CE marking pathways attract manufacturers seeking faster EU MDR transitions than Italian domestic routes permit.
For Market Incumbents: Extend service contract durations with Lombardy and Veneto regional health authorities to preempt competitive displacement. Secure backward integration into polymerase enzyme manufacturing to offset cross-border logistics friction from German and Swiss suppliers. Invest in AI-assisted image analysis platforms ahead of EU AI Act classification clarity to capture early pathogen detection reimbursement premiums. For New Entrants and Emerging Players: EU AI Act implementation timelines in Italy open a window for cloud-enabled result interpretation tools pending regulatory clarity. Target Campania, Sicily, and Calabria with mobile testing units and decentralized point-of-care networks bypassing entrenched northern procurement consortia. Pursue pharmacy channel authorization through Tuscany and Piedmont legislative pilot programs as a hospital laboratory bypass strategy. For Investors and Strategic Acquirers: Life sciences conglomerates with diagnostics divisions are the most active acquirer in this space, seeking point-of-care molecular platform capabilities. Viability over the medium-term projection horizon rests on securing National Institute of Health reference standard validation and framework agreement positioning with Azienda Zero or equivalent procurement hubs. Monitor EU AI Act algorithm classification rulings as the inflection indicator for digital diagnostics platform revaluation.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR compliance accelerates laboratory upgrade cycles across Lombardy's hospital cluster. |
| Hospital System Partnership | Multi-year service contracts with Veneto's Azienda Zero lock in reagent revenue streams. |
| Software Companion Development | AI-assisted result interpretation aligns with Italy's Ministry of Health early detection protocols. |
| Reimbursement Strategy | Positioning for early pathogen detection premium pricing under updated national protocols. |
| Geographic Expansion | Southern Italy deployment addresses per-capita molecular testing density gaps in Campania and Sicily. |
Research Methodology
Direct dialogue with hospital laboratory directors, regional health authority procurement managers, biomedical engineers, and GPO contracts specialists grounded qualitative insights. Secondary validation drew from EU MDR implementation databases, Italian National Institute of Health certification records, hospital procurement tender documents, and regional health authority framework agreements. Bottom-up instrument installation tracking and top-down reimbursement protocol analysis enabled cross-verification.
Bottom-up modeling aggregated installed base estimates by platform type across Lombardy, Veneto, Emilia-Romagna, and southern regions. Top-down validation referenced Ministry of Health diagnostic expenditure allocations and regional health authority capital budgets. Segmentation dimensions included product type, technology tier, end-user category, and delivery mode. CAGRs derived from reagent consumption velocity and replacement cycle timing across the analysis window.
Revisions become necessary when EU AI Act algorithm classification rulings materialize or when National Institute of Health reference standard validation timelines shift materially. Forecasts reflect assumptions regarding procurement consortia consolidation continuity and polymerase enzyme supply chain stability. A model refresh is warranted upon material change in regional health authority tender evaluation criteria.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Infectious Disease
Global Leptospirosis Market
Infectious Disease
Mycobacterium Infections Treatment Market
Infectious Disease
Global Herpes Zoster Infection Treatment Market
Infectious Disease
Measles Market
Infectious Disease
Difficile Infections (Clostridium Difficile Associated Disease) Market
Infectious Disease
Mosquito-Borne Diseases Treatment Market
Infectious Disease
Valley Fever Market
Infectious Disease
Chikungunya Fever Market
Infectious Disease
Typhoid Treatment Market
Infectious Disease
APAC Infectious Disease Diagnosis & Treatment Market
Infectious Disease
Global Infectious Disease Therapeutics Market
Infectious Disease
Hepatitis C Market
Infectious Disease
Herpes Infection Treatment Market
Infectious Disease
Global Acute Bacterial Skin and Skin Structure Infection (ABSSSI) Market
Infectious Disease
Efavirenz Market
Infectious Disease
Actinomycosis Market