
 Breast MRI Screening Market | 2026-2036
Breast MRI Screening Market Size, Share, and Industry Trends Forecast 2026-2036
Breast MRI Screening Market Outlook
ACR accreditation for breast MRI is bifurcating the competitive landscape into qualified and non-qualified equipment suppliers. Siemens Healthineers leverages its 7 Tesla research platforms to anchor premium positioning in academic medical centers. GE Healthcare sustains broad installed base penetration through integrated coil designs and workflow optimization. Philips Healthcare differentiates via proprietary dStream digital broadband architecture that reduces scan times.
Breast MRI screening employs magnetic resonance imaging with dedicated breast coils and gadolinium-based contrast agents to detect malignancies in dense tissue or high-risk populations, typically operating at 1.5T or 3T field strengths with spatial resolution below 1 millimeter. Contrast-enhanced MRI captures the dominant share of procedure volume due to its sensitivity for invasive carcinoma detection, while screening MRI represents the fastest-growing product category as asymptomatic high-risk protocols expand beyond BRCA mutation carriers. Diagnostic MRI occupies mature margin pools in biopsy guidance and lesion characterization, whereas outpatient delivery mode leads volume as hospital systems shift elective imaging to dedicated breast centers.
FDA 510(k) clearance requirements and ACR MRI accreditation standards govern equipment deployment and physician interpretation qualifications in the United States, directly constraining market entry for non-compliant manufacturers. EMA guidance on gadolinium retention and evolving EU MDR technical documentation requirements are elevating contrast agent safety scrutiny and post-market surveillance obligations across European installations. Stakeholders must monitor regulatory divergence between FDA and notified body approaches to software-as-medical-device classification for AI-assisted breast MRI interpretation tools.
Market Dynamics
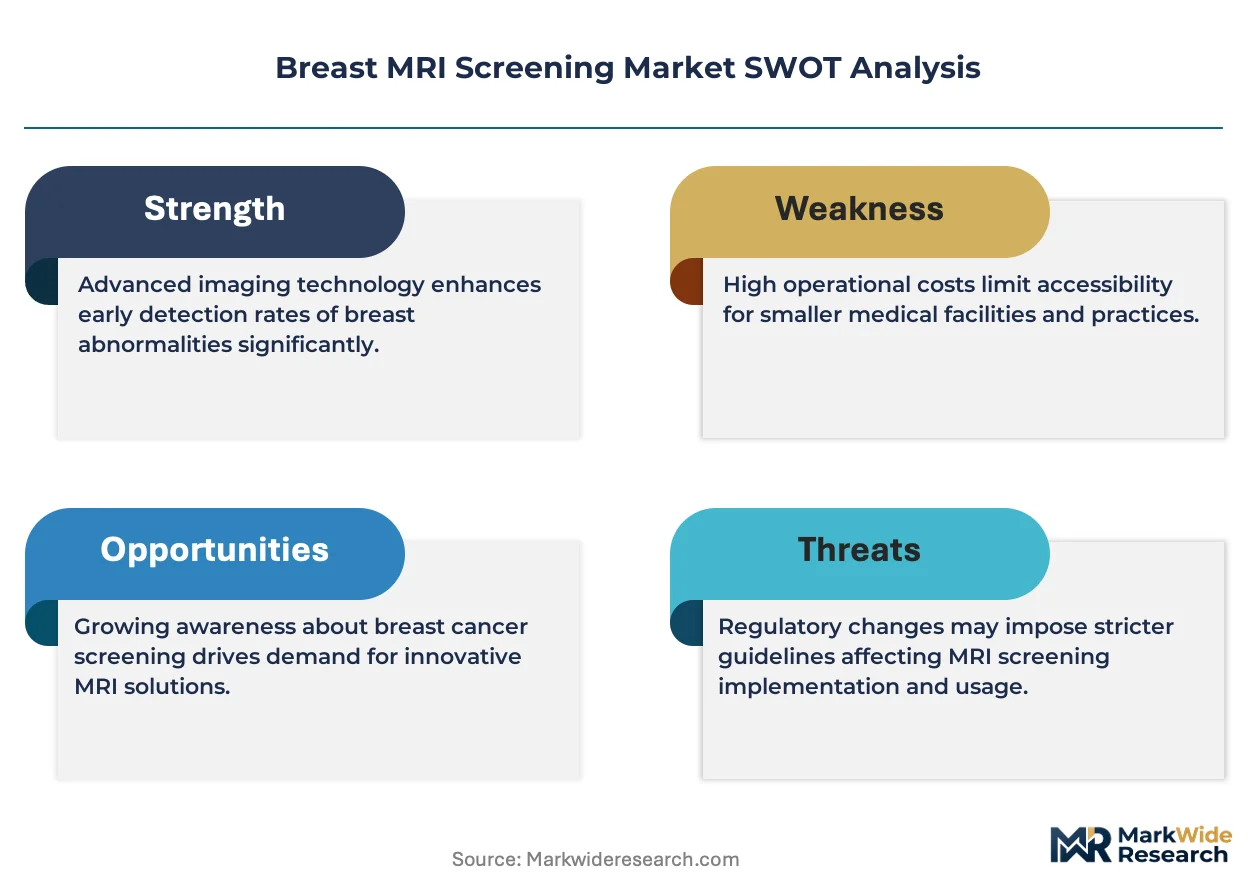
ACR BI-RADS MRI criteria revisions and state-level dense breast notification laws are accelerating protocol standardization while fragmenting reimbursement pathways across hospital systems and dedicated breast imaging centers.
Growth Catalysts
- State Dense Breast Notification Mandates:Legislation in California, New York, Texas, and Illinois requires physicians to discuss supplemental screening with patients having heterogeneously or extremely dense tissue, directly expanding eligible populations for contrast-enhanced MRI protocols.
- Gadolinium Formulation Advances:Macrocyclic chelate designs with higher kinetic stability reduce retention concerns and expand repeat screening eligibility for high-risk surveillance programs in tertiary oncology centers.
- High-Risk Genetic Screening Expansion:BRCA1/BRCA2, TP53, and PALB2 mutation carriers now represent a standardized annual MRI surveillance cohort, with academic medical centers building dedicated high-volume screening slots.
Market Restraints
- Gadolinium Supply Concentration:Three manufacturers control over 90% of macrocyclic contrast agent production, creating vulnerability to batch shortages or EMA-mandated formulation changes.
- ACR MRI Accreditation Barriers:Interpretation volume requirements and phantom testing protocols exclude smaller imaging centers from billing commercial payers for screening studies.
- Substitution by Contrast-Enhanced Mammography:Lower-cost CESM protocols compete for dense-tissue diagnostic workups in cost-constrained health systems, compressing MRI volume in non-surveillance indications.
Strategic Opportunities
- AI-Assisted Interpretation Tools:FDA 510(k) software-as-medical-device pathways for automated lesion detection and kinetic curve analysis address radiologist shortage constraints in high-volume screening programs.
- Ambulatory Surgery Center Deployment:Freestanding breast centers with dedicated 1.5T extremity magnets capture shift from hospital-based elective imaging, enabled by streamlined ACR accreditation for single-modality facilities.
- Ultra-High-Field Research Translation:7 Tesla platforms in National Cancer Institute-designated centers generate biomarker data for risk-stratified screening protocols, creating premium service differentiation.
Industry Challenges
- Radiologist Subspecialty Pipeline:Fellowship-trained breast imagers with MRI interpretation competency remain concentrated in coastal metropolitan markets, limiting protocol expansion in interior regions.
- Scanner Coil Standardization:Proprietary multi-channel coil designs from Siemens, GE, and Philips fragment second-hand equipment markets and elevate maintenance costs for mid-capital imaging centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Breast MRI Screening Market |
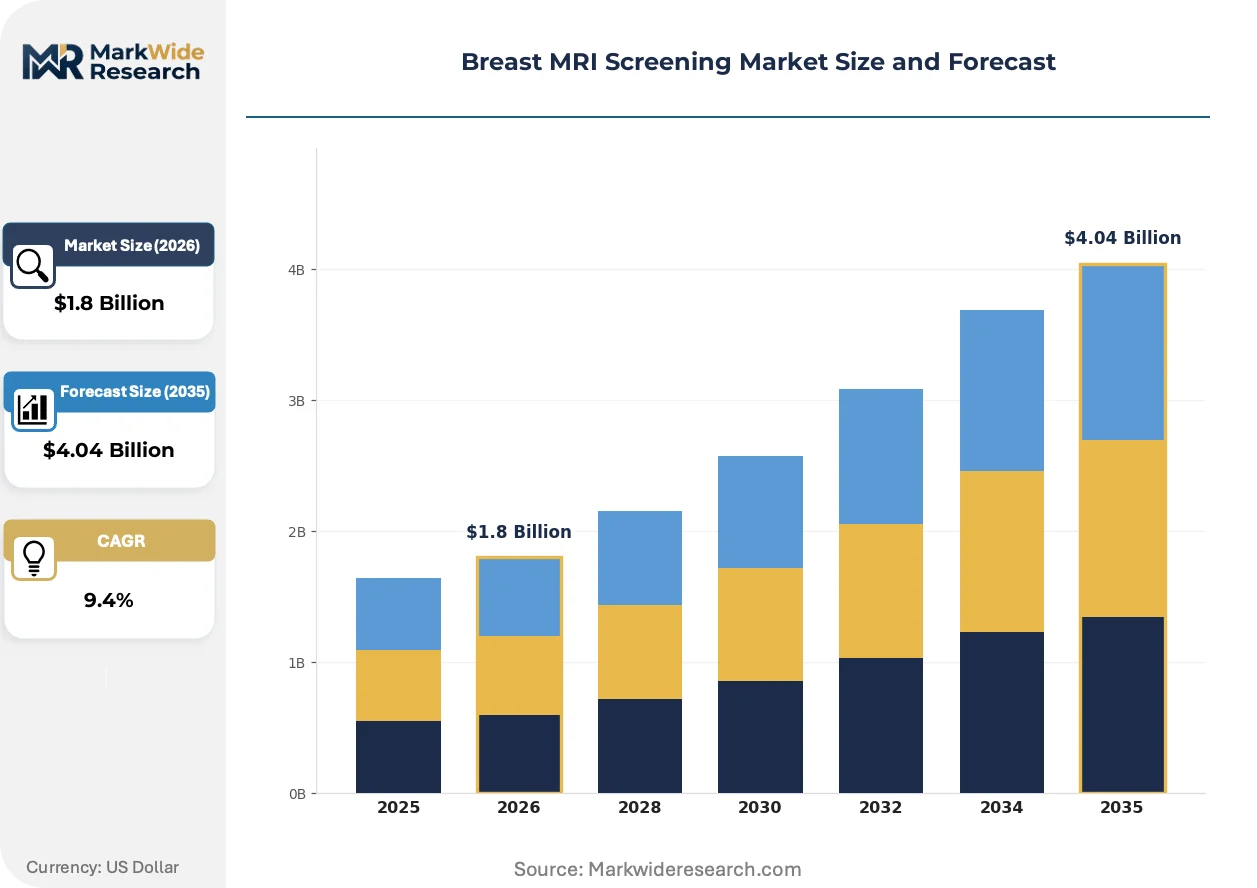
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.04 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contrast-Enhanced MRI, Screening MRI, Diagnostic MRI, Specialized MRI End User: Hospitals, Diagnostic Centers, Research Institutions, Imaging Clinics Procedure Type: Routine Screening, Follow-Up Screening, Research Studies, High-Risk Assessment Delivery Mode: Outpatient Services, Inpatient Services, Mobile Imaging, Telehealth Services |
| Companies Covered | Hologic, Siemens Healthineers, GE Healthcare, Philips Healthcare, Fujifilm Holdings, Canon Medical Systems, Aurora Imaging Technology, SonoCiné, Gamma Medica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Breast MRI Screening Market Strategic Shifts
Workflow automation and artificial intelligence integration are compressing scan-to-report intervals while gadolinium stewardship programs reshape contrast utilization patterns across accountable care organizations.
Compressed sensing reconstruction algorithms paired with deep learning denoising are miniaturizing the hardware footprint required for diagnostic-quality breast MRI. Community hospitals with space-constrained radiology departments are adopting these accelerated protocols to avoid capital-intensive magnet replacements. The technology is miniaturizing the economic threshold for entry-level breast MRI service lines, enabling 15-minute scan windows that match mammography throughput expectations.
FDA's evolving software-as-medical-device guidance for AI-assisted breast MRI interpretation is creating premarket notification bottlenecks for algorithm developers seeking 510(k) clearance. The agency's predicate device requirements for kinetic curve analysis tools favor established players with legacy mammography AI portfolios. European installations face parallel scrutiny under EU AI Act high-risk system classifications, with notified bodies demanding clinical validation datasets that span multiple ethnic phenotypes and breast density categories.
After-sales service unbundling is disrupting traditional equipment financing models as hospital procurement departments negotiate coil maintenance, helium management, and software upgrades as separate line items. Large integrated delivery networks in the Midwest and Southeast are piloting third-party ISO-certified service contracts for 1.5T breast-dedicated magnets, displacing manufacturer captive service agreements. This fragmentation is most visible in Texas and Florida health systems where equipment ownership concentrates in for-profit imaging center chains with standardized multi-vendor fleets.
Breast MRI Screening Market Segmentation
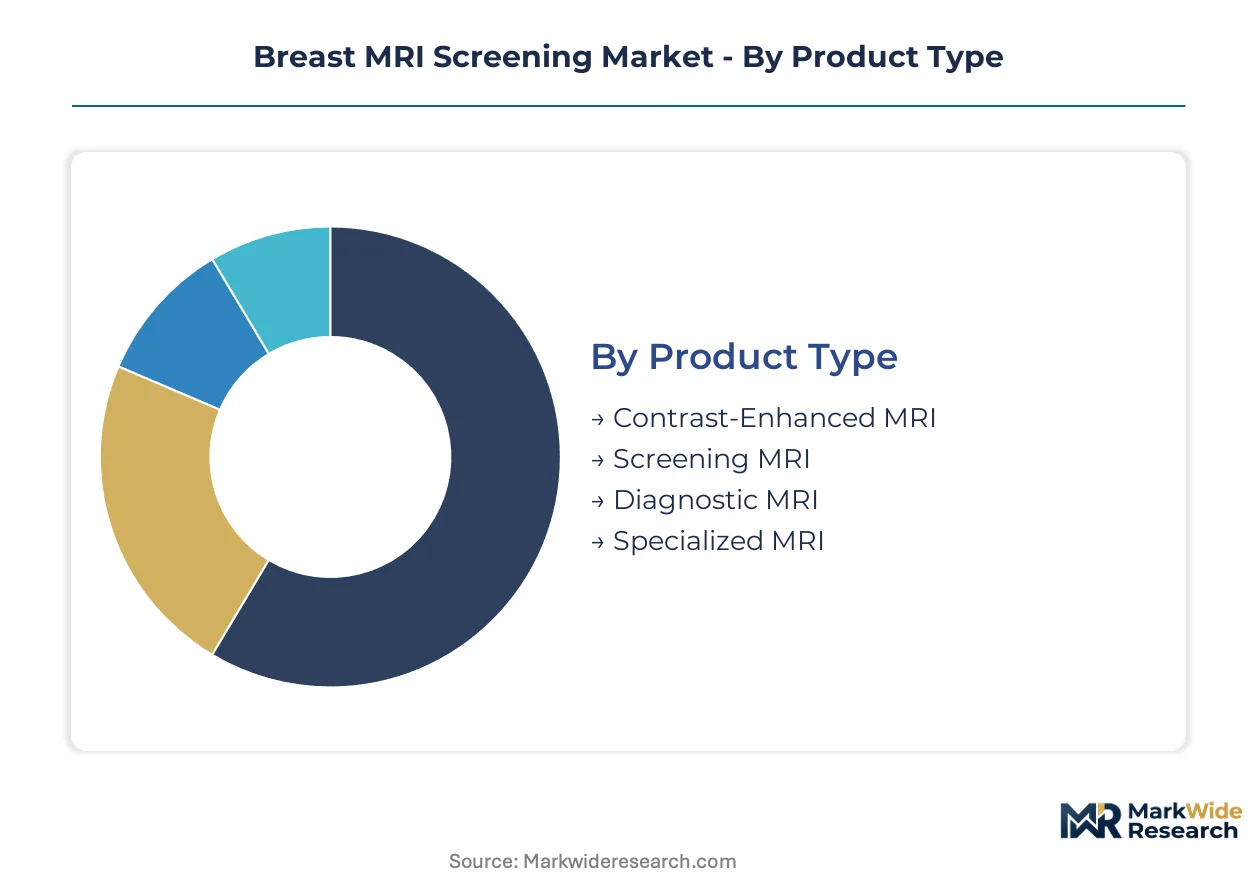
Breast MRI screening segments fragment across regulatory boundaries, with FDA 510(k) clearance tiers and ACR accreditation standards determining which modalities qualify for commercial reimbursement. Each segment carries distinct capital requirements, interpretation protocols, and patient eligibility criteria that shape competitive positioning.
Product Type:
FDA premarket notification pathways bifurcate this category into reimbursable and non-reimbursable modalities, with ACR BI-RADS MRI criteria governing which products qualify for screening program inclusion.
- Contrast-Enhanced MRI:Gadolinium-based protocols with dedicated breast coils at 1.5T or 3T field strengths capture vascular kinetics through T1-weighted sequences. Tertiary oncology centers in California and Texas concentrate demand for this modality, driven by state dense breast notification laws mandating supplemental screening discussions.
- Screening MRI:Asymptomatic surveillance protocols for BRCA mutation carriers and high-risk cohorts employ abbreviated scan sequences to enable high-volume throughput. Academic medical centers in Illinois and New York are expanding dedicated screening slots, propelled by standardized annual surveillance guidelines for TP53 and PALB2 mutation carriers.
- Diagnostic MRI:Lesion characterization and biopsy guidance applications occupy mature reimbursement tiers with established CPT coding.
- Specialized MRI:Ultra-high-field 7 Tesla research platforms serve National Cancer Institute-designated centers with biomarker development protocols.
Contrast-Enhanced MRI handles the majority of throughput; Screening MRI is climbing the fastest on share.
End User:
Capital intensity and ACR MRI accreditation requirements stratify this category, with interpretation volume thresholds excluding smaller facilities from billing commercial payers.
- Hospitals:Integrated delivery networks with fellowship-trained breast imagers maintain captive referral bases and complex case capabilities. Hospital systems in Florida and Georgia are consolidating elective breast imaging into dedicated women's health pavilions, enabled by streamlined ACR accreditation for single-modality facilities.
- Diagnostic Centers:Freestanding facilities with 1.5T extremity magnets capture shift from hospital-based elective imaging through lower cost per scan. Independent imaging chains in Texas concentrate equipment ownership, negotiating third-party ISO-certified service contracts that displace manufacturer captive agreements.
- Research Institutions:NCI-designated cancer centers operate 7 Tesla platforms for risk-stratified protocol development.
- Imaging Clinics:Community-based facilities face ACR accreditation barriers that limit screening program participation.
Hospitals retain the dominant installed base; Diagnostic Centers are expanding most quickly as outpatient migration accelerates.
Procedure Type:
Patient risk stratification and insurance authorization requirements create distinct workflow patterns across this category, with genetic testing results increasingly gating access to surveillance protocols.
- Routine Screening:Annual surveillance for average-risk dense breast populations operates on abbreviated protocols with 15-minute scan windows. California and New York imaging centers concentrate volume for this procedure type, driven by state legislation requiring physicians to discuss supplemental screening with heterogeneously or extremely dense tissue patients.
- High-Risk Assessment:BRCA1/BRCA2, TP53, and PALB2 mutation carriers constitute a standardized annual MRI surveillance cohort with dedicated scheduling blocks. Academic medical centers in Illinois and Massachusetts are building high-volume screening slots, propelled by expanded genetic testing eligibility criteria.
- Follow-Up Screening:Post-treatment surveillance for breast cancer survivors occupies established reimbursement pathways.
- Research Studies:Protocols for novel biomarker validation and AI training dataset generation operate on grant-funded models.
Routine Screening commands the largest eligible population; High-Risk Assessment is gaining share fastest as genetic screening expands.
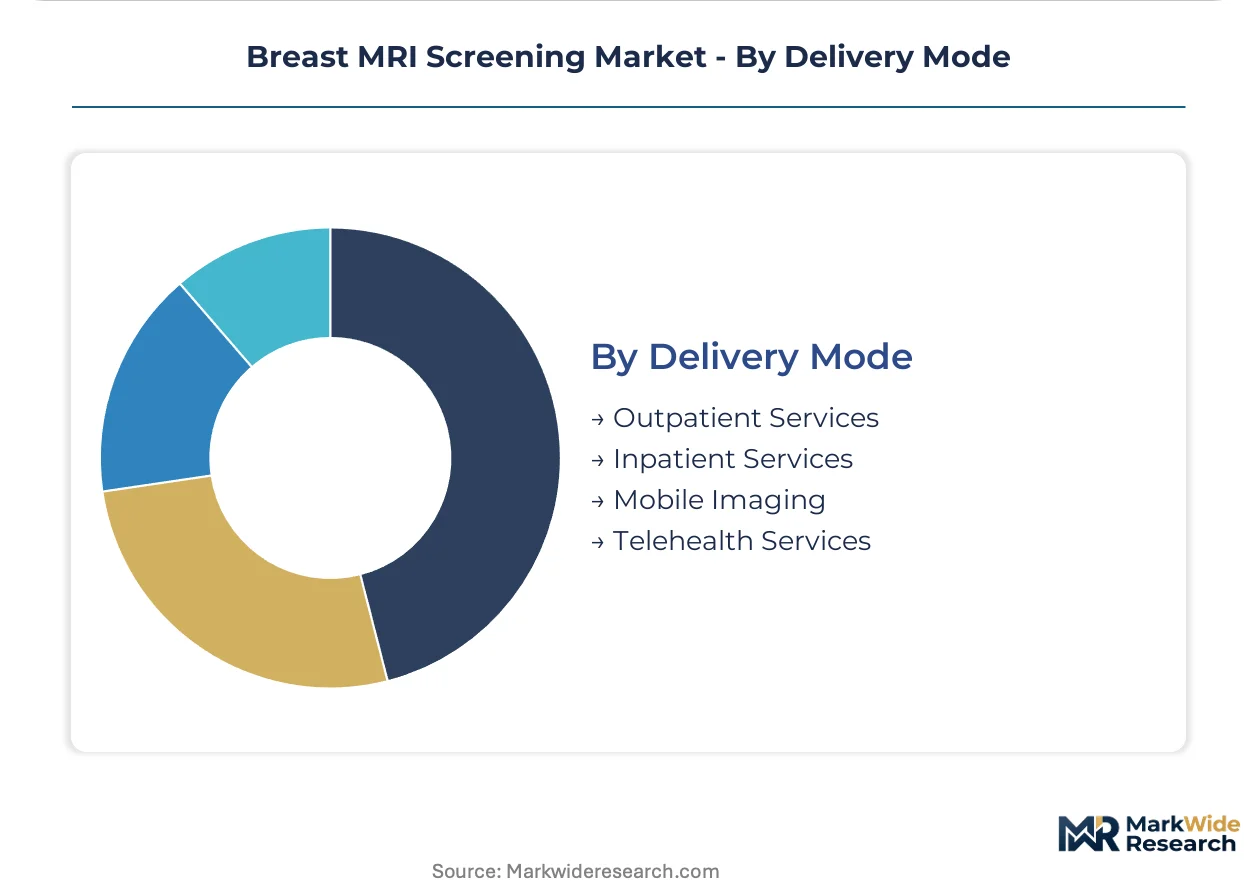
Delivery Mode:
Reimbursement rate differentials and patient convenience preferences are reshaping site-of-service patterns, with accountable care organizations steering volume toward lower-cost settings.
- Outpatient Services:Dedicated breast centers with streamlined scheduling and same-day results reporting match mammography throughput expectations. Freestanding facilities in Texas and Florida concentrate this delivery mode, enabled by for-profit imaging center chains with standardized multi-vendor fleets.
- Mobile Imaging:Trailer-mounted 1.5T magnets serve rural and underserved markets lacking fixed MRI infrastructure. Community hospital systems in the Midwest deploy mobile units to extend screening access without capital-intensive magnet installations.
- Inpatient Services:Acute care settings handle diagnostic workups for symptomatic patients and preoperative staging.
- Telehealth Services:Remote interpretation and patient consultation models address radiologist shortage constraints in interior regions.
Outpatient Services processes the highest scan volume; Mobile Imaging shows the steepest expansion trajectory as rural access programs proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
State-level dense breast notification laws in the United States are accelerating supplemental screening adoption, while EMA gadolinium retention guidance and EU MDR technical documentation reshape European deployment patterns. Academic medical centers in Illinois and Massachusetts are expanding high-risk surveillance slots for BRCA mutation carriers.
United States
California, New York, Texas, and Illinois mandate physician-patient discussions about supplemental screening for dense breast tissue, directly expanding eligible populations for contrast-enhanced MRI protocols. FDA 510(k) clearance requirements and ACR MRI accreditation standards govern equipment deployment and interpretation qualifications. Tertiary oncology centers in Houston and Dallas concentrate demand for high-throughput screening slots.
Germany
Academic medical centers in Bavaria and North Rhine-Westphalia operate 7 Tesla research platforms for biomarker development in risk-stratified screening protocols. EMA guidance on macrocyclic chelate stability elevates post-market surveillance obligations for contrast agent utilization. Siemens Healthineers anchors premium equipment positioning through integrated coil designs in Munich and Erlangen clusters.
United Kingdom
NHS England's targeted screening programs for BRCA mutation carriers are standardizing annual MRI surveillance in London and Manchester academic centers. MHRA post-Brexit regulatory divergence from EMA creates parallel compliance pathways for AI-assisted interpretation tools. The Cambridge-Oxford-London triangle concentrates 7 Tesla research infrastructure for ultra-high-field protocol translation.
Japan
PMDA accelerated approval pathways for abbreviated MRI sequences are enabling high-volume screening deployment in Tokyo and Osaka metropolitan areas. METI funding for AI diagnostic software supports automated lesion detection algorithm development. National cancer centers in Kashiwa and Tsukuba pilot 15-minute scan protocols for dense breast populations.
France
ANSM pharmacovigilance requirements for gadolinium-based contrast agents mandate retention monitoring in Paris and Lyon university hospital networks. HAS reimbursement guidelines differentiate screening eligibility between average-risk and high-risk genetic cohorts. The Île-de-France region concentrates equipment installation in dedicated breast imaging pavilions within integrated delivery networks.
Breast MRI Screening Market Competitive Environment
Listed leaders compete with private specialists across equipment financing and service contract unbundling. The market structure consolidates around three dominant imaging equipment manufacturers with captive coil architectures, while mid-cap diagnostic center chains negotiate third-party maintenance agreements. Strategic archetypes include integrated platform vendors, freestanding imaging center operators, and AI software developers seeking FDA 510(k) clearance. M&A activity concentrates on ambulatory surgery center rollups and AI algorithm licensing partnerships.
Within the integrated platform tier, Siemens Healthineers and GE Healthcare exemplify divergent positioning strategies—Siemens anchors academic medical center relationships through 7 Tesla research platforms, while GE sustains broad installed base penetration via workflow optimization and coil design integration. Philips Healthcare occupies a position emphasizing proprietary digital broadband architecture for scan time reduction. Hologic represents the specialized diagnostic systems archetype, with equipment portfolios concentrated in women's health screening applications rather than full-modality MRI platforms.
| Leading Market Players |
|---|
| Hologic |
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Fujifilm Holdings |
| Canon Medical Systems |
| Aurora Imaging Technology |
| SonoCiné |
| Gamma Medica |
| Others |
Value Chain & Pricing Dynamics
FDA 510(k) clearance tiers and ACR MRI accreditation standards simultaneously gate supply qualification and stratify price differentiation across equipment and service tiers. Manufacturers with dual certification capture premium positioning in academic medical centers, while non-accredited suppliers compete on capital cost alone in price-sensitive outpatient settings. This regulatory bifurcation compresses margins for mid-tier diagnostic centers caught between compliance investment and reimbursement pressure.
Pricing Analysis
Certification level creates the primary spread between premium and standard tiers, with FDA-cleared 3T platforms commanding substantial capital premiums over 1.5T alternatives lacking ACR qualification. Three-tier pricing structure across premium, standard, and economy levels reflects field strength, coil channel density, and bundled service contracts. Pricing pressure stems from third-party ISO-certified maintenance contracts displacing manufacturer captive agreements in Texas and Florida imaging chains. Hospital systems exhibit lowest price sensitivity due to captive referral bases, while independent diagnostic centers negotiate aggressively on equipment financing terms.
Supply Chain Analysis
Strategic stockpiling of helium and gadolinium chelates dominates inventory strategy given supply concentration risks and batch volatility concerns. Superconducting magnet production concentrates in Germany, the United States, and Japan, with coil winding and cryogenic component assembly feeding from specialized facilities in these markets. Raw material dependencies include niobium-titanium superconducting wire, liquid helium for cryogenic cooling, and macrocyclic gadolinium formulations from concentrated pharmaceutical suppliers. Single-source vulnerability in helium supply chains elevates risk exposure for mid-cap imaging centers lacking long-term offtake agreements. Distribution runs through integrated delivery networks in the Midwest and Southeast, with direct manufacturer relationships dominating academic medical center procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Breast MRI screening sits in early-cycle expansion as state dense breast notification laws in California, New York, Texas, and Illinois mandate supplemental screening discussions, expanding eligible populations beyond traditional high-risk genetic cohorts.
For Market Incumbents: Compound installed base defenses through backward integration into coil maintenance and helium management services, displacing vulnerable third-party contracts. Deepen ACR accreditation consulting capabilities to lock smaller diagnostic centers into captive service ecosystems before ISO-certified alternatives mature. Contrast-enhanced mammography substitution in cost-constrained health systems represents the primary technology threat requiring proactive surveillance protocol differentiation. For New Entrants and Emerging Players: Anchor in ambulatory surgery center deployment models where streamlined single-modality ACR accreditation enables faster market entry than hospital system integration. Target mobile imaging services for rural Midwest markets lacking fixed MRI infrastructure, where community hospital systems seek screening access without capital-intensive magnet installations. Pursue AI-assisted interpretation software pathways through FDA 510(k) premarket notification to address radiologist shortage constraints in interior regions. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed diagnostic center chains in Texas and Florida operating standardized multi-vendor fleets with unbundled service contracts. Long-term viability hinges on consolidation capture as outpatient migration accelerates and reimbursement pathways fragment across hospital systems and freestanding facilities. Watch for inflection when state dense breast notification legislation crosses threshold coverage of 75% of United States population, signaling protocol standardization maturity.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Clearance Pathway | Accelerates AI-assisted lesion detection algorithm deployment in high-volume screening programs. |
| ACR Accreditation Investment | Enables billing commercial payers for screening studies in dedicated breast imaging centers. |
| Hospital System Partnership | Captures captive referral bases through integrated women's health pavilion consolidation. |
| Software Companion Development | Addresses radiologist shortage constraints with automated kinetic curve analysis tools. |
| Reimbursement Strategy | Navigates fragmented pathways across Medicare, commercial payers, and state mandate implementations. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with breast imaging radiologists, hospital purchasing committee members, GPO contracts managers, and biomedical engineers; and secondary validation against FDA 510(k) filings, ACR accreditation databases, CMS Medicare reimbursement data, and state legislative tracking systems. Bottom-up equipment shipment analysis triangulated with top-down screening procedure volume estimates across hospital systems and diagnostic centers.
Across the analysis window, the forecasting framework modeled product type segmentation, end-user capital intensity tiers, procedure type eligibility criteria, and delivery mode site-of-service patterns. CAGRs derived from procedure volume trajectories weighted by reimbursement rate evolution and equipment replacement cycles. Forecast inputs incorporated gadolinium formulation stability profiles, ACR BI-RADS MRI criteria revision timelines, and AI software-as-medical-device clearance velocity.
Material uncertainties — regulatory divergence between FDA and EU MDR for AI-assisted interpretation tools, EMA-mandated gadolinium retention formulation changes, and radiologist subspecialty pipeline constraints — sit outside the modeled envelope. Forecasts reflect assumptions about state dense breast notification law expansion and macrocyclic contrast agent supply continuity. Revision becomes warranted when substitution by contrast-enhanced mammography crosses clinical acceptance thresholds in cost-constrained health systems.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Specimen Radiography Systems Market
Medical Imaging
SPECT Scanning Services Market
Medical Imaging
Refurbished Medical Imaging Devices Market
Medical Imaging
Intraoperative Imaging Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Digital X Ray Market
Medical Imaging
Middle East and Africa Magnetic Resonance Imaging (MRI) Market
Medical Imaging
Small Animal Imaging (in-Vivo) Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
Breast Imaging Market
Medical Imaging
Fluoroscopy Devices Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
Coronary Heart Disease Diagnostic Imaging Market
Medical Imaging
Germany Magnetic Resonance Imaging Market
Medical Imaging
Transesophageal Echocardiography (TEE) Market
Medical Imaging
Canada Magnetic Resonance Imaging (MRI) Market