
 Imaging Agents Market | 2026-2036
Imaging Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Imaging Agents Market Analysis
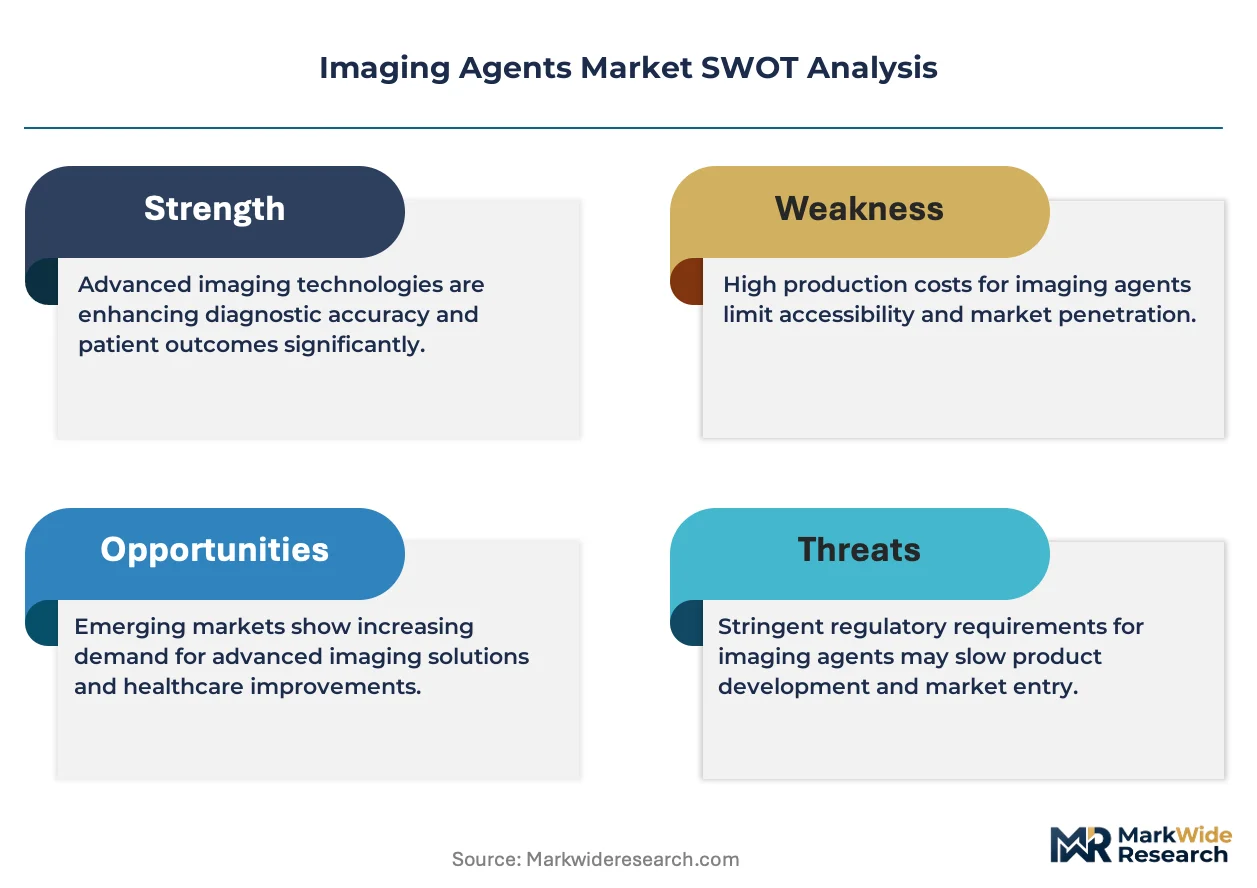
The divergence between premium radiopharmaceuticals and commodity iodinated contrast media is recalibrating how suppliers allocate manufacturing capacity and R&D budgets across the Imaging Agents Market. GE HealthCare leverages its cyclotron network and tracer production infrastructure to dominate North American supply of fluorodeoxyglucose and gallium-based agents. Bracco Imaging anchors its position through integrated iodine supply chains and proprietary viscosity formulations for CT protocols. Fujifilm Holdings competes in ultrasound contrast with perfluorobutane microsphere technology, differentiating through specialized cardiology applications.
Imaging agents comprise chemically engineered substances that enhance visualization of tissues, organs, or physiological processes during diagnostic procedures, with formulations ranging from gadolinium chelates for MRI to technetium-99m labeled compounds for nuclear medicine. These agents function by altering local magnetic properties, attenuating X-ray beams, or emitting detectable gamma radiation to distinguish pathological from normal tissue. Contrast media for CT scanning represents the largest revenue pool due to high procedure volumes, yet radiopharmaceuticals for nuclear imaging command superior margins as therapeutic radioligands expand beyond diagnostics into theranostics. Diagnostic imaging applications in hospitals sustain the broadest demand base, while MRI scanning segments benefit from macrocyclic gadolinium formulations with improved safety profiles.
The FDA oversees radiopharmaceutical approval through its Center for Drug Evaluation and Research and Center for Devices and Radiological Health, enforcing current good manufacturing practice for positron emission tomography drugs. The EMA's Committee for Medicinal Products for Human Use harmonizes centralized marketing authorizations across EU member states, while Japan's PMDA implements sakigake designation pathways to accelerate novel diagnostic agent reviews. Stakeholders must monitor evolving reimbursement frameworks for theranostic pairings, as payment policies increasingly determine whether radiopharmaceutical innovation translates to accessible clinical adoption.
Market Dynamics
The FDA's updated radiopharmaceutical guidance is compressing approval timelines for novel PET tracers while concentrating manufacturing investment around cyclotron-equipped hubs in the United States, Germany, and Japan.
Growth Catalysts
- Oncology diagnostics acceleration:Hospital networks are expanding PET-CT infrastructure for precision tumor characterization, driving radiopharmaceutical uptake in cancer staging protocols.
- Theranostic expansion:Radioligand therapy paired with diagnostic imaging is creating dual-revenue streams that justify premium pricing for gallium and lutetium-based agents.
- Japan's sakigake pathway:PMDA's accelerated review designation is shortening time-to-market for novel diagnostic agents, incentivizing R&D investment in Tokyo-Osaka pharmaceutical clusters.
Market Restraints
- Molybdenum-99 supply fragility:Reactor concentration in the Netherlands, Belgium, and South Africa creates single-point-of-failure risk for technetium-99m generators used in SPECT imaging.
- Gadolinium retention concerns:EMA's PRAC safety reviews have restricted linear chelate formulations, forcing costly reformulation to macrocyclic alternatives.
- Contrast media commoditization:Iodinated CT agents face price erosion from Asian contract manufacturers, compressing margins for established suppliers.
Strategic Opportunities
- India diagnostic imaging penetration:CDSCO streamlined approval pathways and government hospital procurement expansion are opening access for MRI and CT contrast agents in tier-2 cities.
- AI-integrated image reconstruction:Machine learning algorithms paired with low-dose radiopharmaceutical protocols are enabling reduced tracer volumes per scan.
- Direct-to-hospital cyclotron networks:On-site fluorodeoxyglucose production bypasses distributor markups and cold-chain logistics constraints for high-volume oncology centers.
Industry Challenges
- Radiochemist talent scarcity:PET tracer synthesis requires specialized expertise in half-life management and GMP compliance that outpaces training program output.
- Multi-jurisdiction dossier complexity:Divergent FDA, EMA, and PMDA stability testing requirements force redundant validation studies for global product registrations.
- Cold-chain infrastructure capex:Radiopharmaceutical distribution requires validated temperature-controlled logistics that strain regional distributor balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Imaging Agents Market |
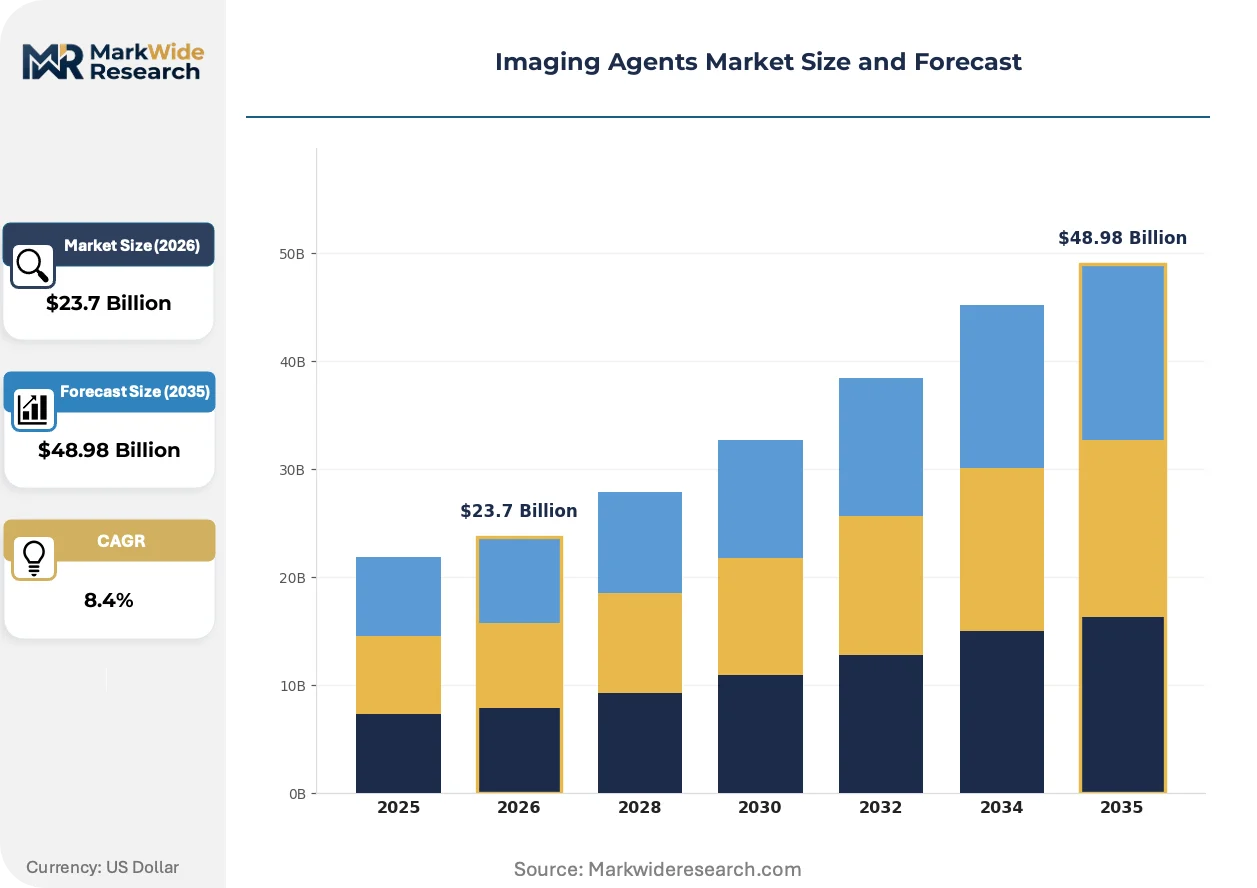
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $48.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Contrast Media, Radiopharmaceuticals, Ultrasound Agents, CT Agents Application: Diagnostic Imaging, Nuclear Imaging, MRI Scanning, CT Scanning End User: Hospitals, Diagnostic Labs, Imaging Centers, Research Institutions Delivery Mode: Intravenous, Oral, Inhalation, Topical |
| Companies Covered | Lantheus Medical Imaging, Fujifilm Holdings, GE HealthCare, Curium Pharma, Bracco Imaging, Siemens Healthineers, Canon Medical Systems Corporation, Bayer, Koninklijke Philips, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Imaging Agents Market Emerging Trajectories
Tracer chemistry advances and regulatory harmonization efforts are reconfiguring how imaging agents move from manufacturing facilities to clinical protocols across hospital networks.
Copper-64 radiochemistry is electrifying theranostic development cycles by offering longer half-life stability than fluorine-18, enabling centralized production and extended distribution radii. Academic medical centers in the United States and Germany are adopting copper-labeled somatostatin analogues for neuroendocrine tumor imaging. This isotope shift is compressing the economic viability of on-site cyclotron investments for smaller hospital systems.
EMA's Clinical Trials Regulation harmonization is eliminating redundant national ethics submissions across EU member states, accelerating multi-center radiopharmaceutical studies. The centralized portal reduces protocol amendment timelines from months to weeks. France, Germany, and Italy are consolidating investigator-initiated trials under this framework, concentrating Phase II activity in established nuclear medicine departments.
Hospital procurement departments are consolidating imaging agent purchasing through group purchasing organizations, displacing traditional distributor relationships with direct manufacturer contracts. This concentration is most visible in United States integrated delivery networks, where formulary committees now mandate bioequivalence documentation for contrast media substitutions. Price transparency platforms are exposing historical markup variations between academic and community hospital contracts.
Imaging Agents Market Segmentation
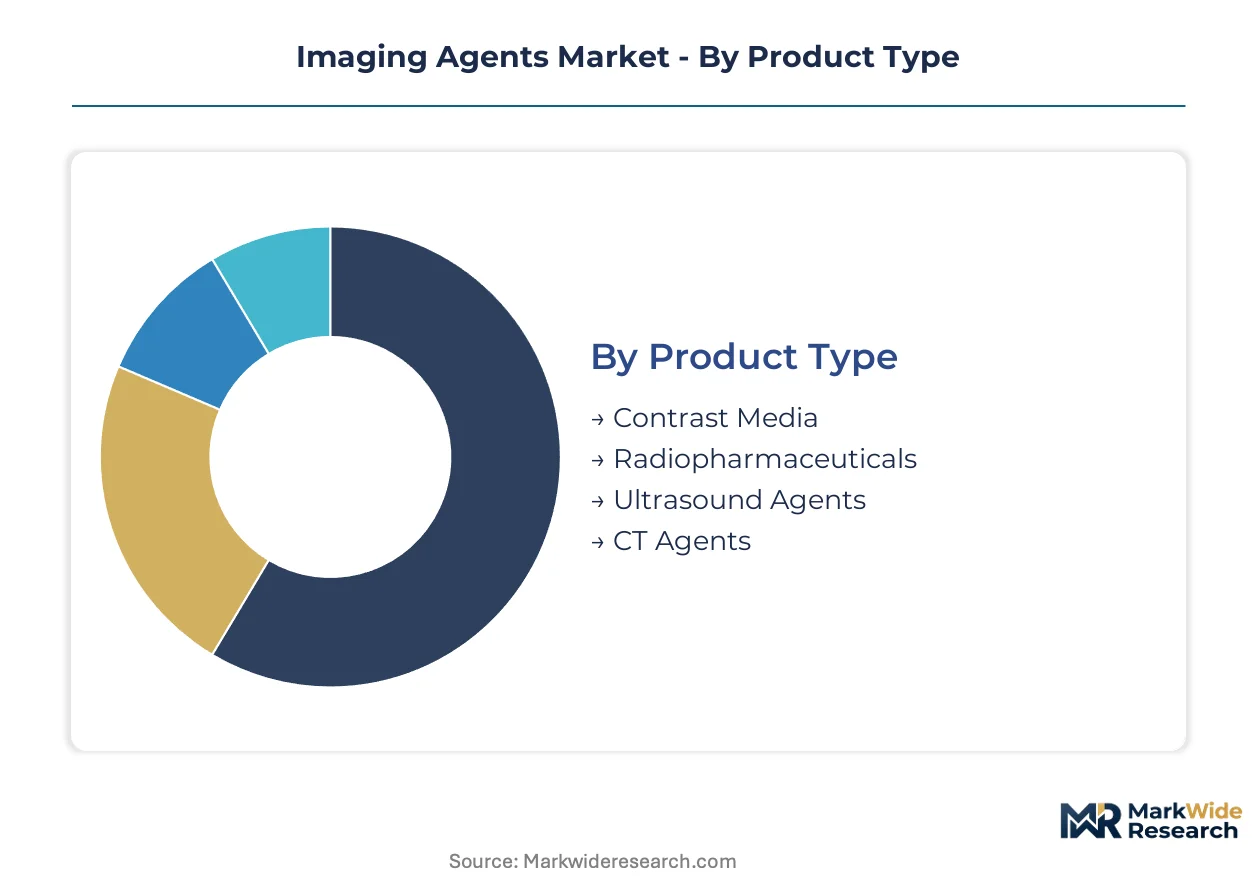
Imaging agents traverse divergent regulatory pathways depending on their radioactive content and clinical application, with radiopharmaceuticals requiring cyclotron manufacturing licenses while contrast media face simpler pharmaceutical filings. Hospital procurement teams segment purchasing strategies around cold-chain requirements and half-life constraints that vary dramatically across product categories.
Product Type:
Radiopharmaceuticals demand FDA cyclotron registration and EMA's centralized nuclear medicine authorization, while contrast media navigate standard pharmaceutical approval pathways with lighter manufacturing oversight.
- Contrast Media:Iodinated and gadolinium-based formulations alter X-ray attenuation or magnetic resonance properties to enhance tissue differentiation. Hospital networks in the United States and Germany concentrate procurement around macrocyclic gadolinium chelates following EMA safety restrictions on linear alternatives.
- Radiopharmaceuticals:Positron-emitting tracers like fluorodeoxyglucose and gallium-labeled compounds require on-site or regional cyclotron production with half-life management protocols. Oncology departments in Japan's Tokyo-Osaka corridor are accelerating uptake through PMDA's sakigake accelerated review pathway.
- Ultrasound Agents:Perfluorobutane microspheres enhance echogenicity for cardiology and hepatology applications.
- CT Agents:Iodinated formulations dominate procedure volumes but face margin compression from Asian contract manufacturing.
Leading the category by volume: Contrast Media. Growing fastest: Radiopharmaceuticals.
Application:
Procedure reimbursement codes and capital equipment requirements segment demand across imaging modalities, with PET-CT infrastructure investments concentrating uptake in hospital systems with dedicated nuclear medicine departments.
- Diagnostic Imaging:Broad category encompassing X-ray, ultrasound, and fluoroscopy enhancement protocols with established reimbursement frameworks. Community hospitals in the United States prioritize this segment for routine screening volumes.
- Nuclear Imaging:SPECT and PET procedures utilizing technetium-99m or fluorine-18 tracers require specialized gamma camera or coincidence detection hardware. German university hospitals are expanding theranostic programs pairing diagnostic gallium imaging with lutetium therapy.
- MRI Scanning:Gadolinium-based agents for soft tissue visualization with safety profiles driving macrocyclic formulation preferences.
- CT Scanning:High procedure volumes sustain largest revenue pool despite iodinated contrast commoditization pressures.
Dominating procedure counts: CT Scanning. Expanding most quickly: Nuclear Imaging.
End User:
Capital intensity and regulatory licensing requirements stratify purchasing power across customer types, with integrated hospital networks leveraging formulary control against distributor markups.
- Hospitals:Comprehensive imaging departments with in-house cyclotron capabilities or centralized radiopharmacy contracts. United States integrated delivery networks are consolidating purchasing through group purchasing organizations that mandate bioequivalence documentation for contrast substitutions.
- Diagnostic Labs:Specialized facilities focusing on high-throughput screening with standardized protocols. India's tier-2 cities are opening access as CDSCO streamlines approval pathways for MRI and CT agents.
- Imaging Centers:Outpatient facilities dependent on referral networks and procedure volume economics.
- Research Institutions:Academic medical centers driving tracer development under EMA's harmonized Clinical Trials Regulation.
Capturing largest procurement volumes: Hospitals. Gaining share fastest: Diagnostic Labs.
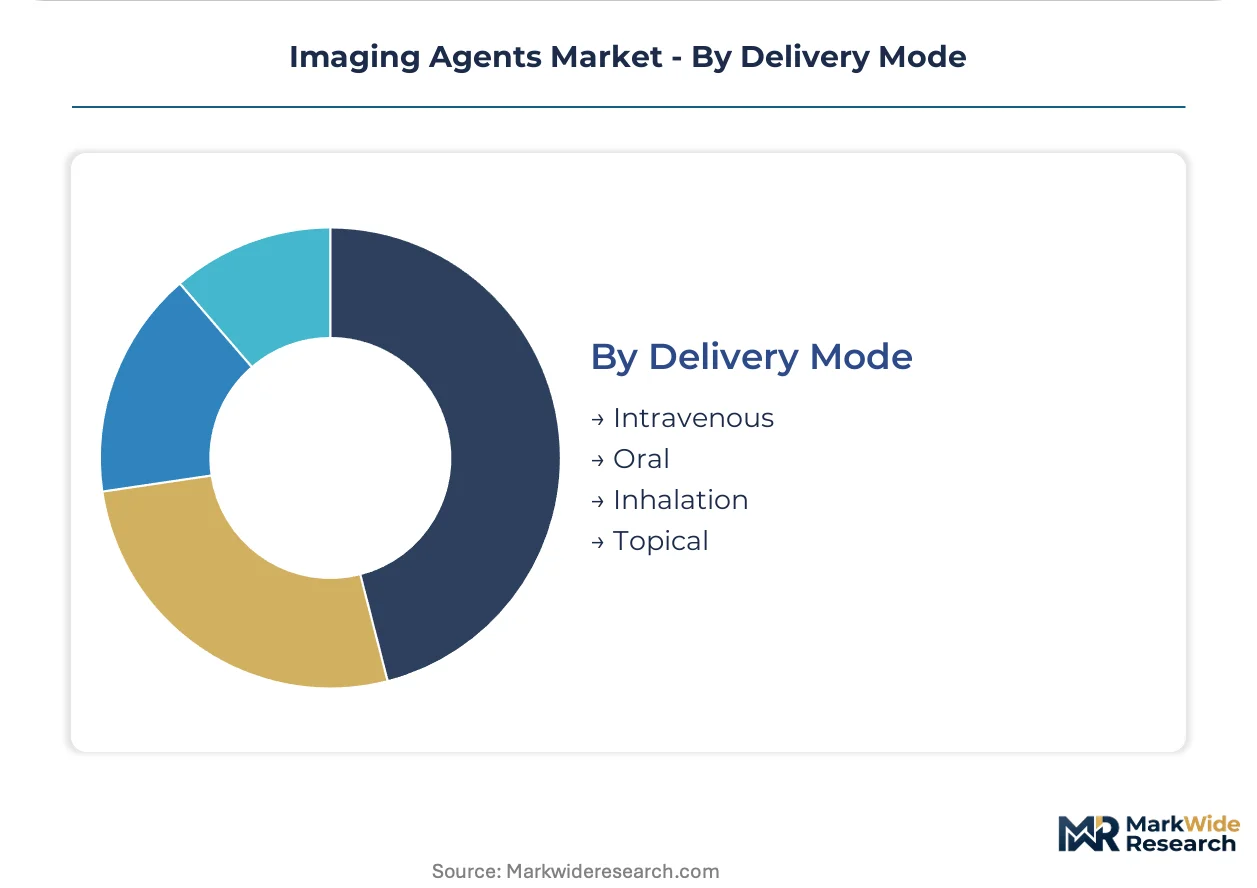
Delivery Mode:
Route of administration determines formulation chemistry, patient throughput logistics, and adverse event monitoring protocols that shape supplier R&D allocation.
- Intravenous:Direct vascular injection enables rapid systemic distribution for CT angiography and cardiac perfusion imaging. Japanese and German hospital networks prioritize automated injector compatibility for high-volume protocols.
- Oral:Barium suspensions and iodinated solutions for gastrointestinal tract delineation with lower technical staffing requirements.
- Inhalation:Xenon-133 and specialized ventilation agents for pulmonary function assessment with limited commercial availability.
- Topical:Surface applications for fistulography and specialized interventional procedures representing niche demand.
Commanding procedure volume: Intravenous. Steepest expansion trajectory: Oral formulations for ambulatory settings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Boston-Cambridge pharmaceutical corridor anchors radiopharmaceutical innovation through proximity to MIT nuclear engineering facilities and Mass General Brigham's cyclotron infrastructure. FDA's updated PET drug guidance has compressed approval timelines from 18 months to under 12 months for novel tracers.
United States
Oncology departments at MD Anderson and Memorial Sloan Kettering are expanding theranostic programs pairing gallium imaging with lutetium therapy. FDA's Center for Drug Evaluation and Research oversees radiopharmaceutical approvals through dedicated PET drug teams. The Research Triangle Park corridor in North Carolina concentrates contract manufacturing for technetium-99m generators.
Germany
University hospitals in Munich and Heidelberg are consolidating Phase II radiopharmaceutical trials under EMA's harmonized Clinical Trials Regulation. The country's national pharmaceutical regulator enforces centralized nuclear medicine authorizations across EU member states. The Rhine-Main region around Frankfurt hosts Europe's densest cyclotron network for fluorodeoxyglucose distribution.
Japan
Tokyo-Osaka hospital networks are accelerating PET-CT infrastructure deployment for precision cancer staging. PMDA's sakigake designation pathway shortens novel diagnostic agent reviews from 12 months to 6 months. The Kansai Science City corridor concentrates tracer development partnerships between Osaka University and domestic pharmaceutical manufacturers.
India
Tier-2 cities including Pune and Ahmedabad are opening diagnostic imaging centers as government hospital procurement expands. CDSCO has streamlined approval pathways for MRI and CT contrast agents through risk-based classification systems. The Hyderabad pharmaceutical cluster is developing regional radiopharmacy capabilities for technetium-99m distribution.
United Kingdom
NHS England's specialized commissioning frameworks are consolidating radiopharmaceutical purchasing through designated academic medical centers. The Medicines and Healthcare products Regulatory Agency implements post-Brexit recognition routes for EMA-approved imaging agents. The Oxford-Cambridge arc concentrates PET tracer research through university hospital partnerships.
Imaging Agents Market Vendor Landscape
Premium-margin players sit above commodity-margin players across radiopharmaceutical versus contrast media lines, with cyclotron-dependent tracers commanding threefold pricing power over iodinated CT agents. The vendor base stratifies into three tiers: integrated health technology conglomerates with captive cyclotron networks, specialized radiopharmaceutical manufacturers with regional distribution footprints, and commodity contrast suppliers facing Asian manufacturing pressure. Dominant competitive moves include backward integration into isotope production and strategic partnerships with academic medical centers for tracer co-development.
Among diversified health technology conglomerates, GE HealthCare and Siemens Healthineers occupy positions spanning cyclotron manufacturing through hospital imaging system integration. Lantheus Medical Imaging exemplifies the specialized radiopharmaceutical archetype with concentrated expertise in PET tracer commercialization. Fujifilm Holdings represents the imaging-centric conglomerate model with differentiated ultrasound contrast capabilities. Bayer anchors the traditional pharmaceutical tier with established iodinated contrast portfolios.
| Leading Market Players |
|---|
| Lantheus Medical Imaging |
| Fujifilm Holdings |
| GE HealthCare |
| Curium Pharma |
| Bracco Imaging |
| Siemens Healthineers |
| Canon Medical Systems Corporation |
| Bayer |
| Koninklijke Philips |
| Others |
Supply Flow & Price Mechanics
Cyclotron isotope production costs cascade through three distinct pricing tiers, with fluorine-18 and gallium-68 tracers commanding premium positioning against commoditized iodinated CT agents. Hospital procurement concentration in the United States and Germany is compressing distributor margins while rewarding direct manufacturer contracts for high-volume oncology centers.
Pricing Analysis
Throughput-based pricing anchors radiopharmaceutical valuation, with per-dose rates tied to PET-CT scanner utilization guarantees rather than raw material input costs. Pricing stratifies across premium cyclotron-produced tracers, standard generator-derived technetium-99m, and economy-tier iodinated contrast media. Cost compression in CT agents is intensifying because Asian contract manufacturers are flooding hospital tenders with bioequivalent formulations. Community hospital networks exhibit highest price sensitivity, while academic medical centers with theranostic programs prioritize supply security over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with molybdenum-99 reactor concentration in the Netherlands, Belgium, and South Africa, creating catastrophic failure exposure for technetium-99m generator supply. Manufacturing draws from specialized radiochemistry feedstocks including enriched uranium targets, cyclotron-produced isotopes, and iodine extraction from brine deposits. Tariff exposure runs through cross-border radiopharmaceutical shipments subject to nuclear material transport regulations. Distribution runs through validated cold-chain networks anchored by regional radiopharmacy hubs serving hospital networks within isotope half-life constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Imaging agent supply consolidation is accelerating as cyclotron infrastructure requirements and GMP compliance costs force subscale manufacturers toward exit. Margin compression in iodinated contrast is amplifying acquisition pressure on undifferentiated regional players.
For Market Incumbents: Deepen cyclotron network density in the United States, Germany, and Japan to defend radiopharmaceutical pricing power against emerging copper-64 centralized production models. Secure backward integration into isotope supply through long-term reactor offtake agreements. Expand macrocyclic gadolinium capacity ahead of further EMA safety restrictions on linear chelate alternatives. For New Entrants and Emerging Players: Tier-2 Indian diagnostic labs represent the most penetrable buyer archetype as CDSCO streamlines contrast agent approvals and government hospital procurement expands. Target oral formulation CT agents for ambulatory settings where intravenous administration staffing constraints limit incumbent penetration. Pursue direct-to-hospital cyclotron partnerships bypassing distributor markups in high-volume oncology corridors. For Investors and Strategic Acquirers: FDA's updated PET drug guidance compressing approval timelines to under 12 months is the leading indicator that radiopharmaceutical development platforms will command sustained valuation premiums over commodity contrast portfolios. The acquisition target archetype comprises specialized radiochemistry firms with established GMP facilities and tracer development partnerships with academic medical centers. Watch for copper-64 theranostic trial readouts as the signal for isotope shift investment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Hospital Cyclotron Network | Bypasses distributor markups and cold-chain constraints for high-volume oncology centers in the United States. |
| Copper-64 Theranostic Development | Enables centralized production with extended distribution radii compared to fluorine-18 tracers. |
| Macrocyclic Gadolinium Reformulation | Addresses EMA safety restrictions while preserving MRI contrast revenue against unenhanced imaging alternatives. |
| India Diagnostic Lab Penetration | Captures tier-2 city expansion as CDSCO risk-based approvals streamline contrast agent market entry. |
| Academic Medical Center Partnership | Secures tracer co-development pipelines and preferred formulary positioning for novel radiopharmaceuticals. |
Methodological Framework
Multi-period observation of PET-CT infrastructure deployment, cyclotron licensing patterns, and hospital procurement consolidation anchored the trend analysis, supplemented by interviews with nuclear medicine department heads, radiopharmacy operations managers, GPO contract specialists, and regulatory affairs directors at tracer manufacturers. Secondary validation drew from FDA PET drug guidance documents, EMA centralized authorization records, PMDA sakigake designation announcements, and hospital procurement database tracking. Bottom-up facility-level capacity modeling was triangulated against top-down revenue estimates across product categories.
Segment-weighting approaches distributed value projections across radiopharmaceutical, contrast media, and ultrasound agent categories, with further disaggregation by application modality and end-user type. CAGRs were derived from procedure volume elasticity models incorporating reimbursement code changes and capital equipment installation trajectories. Industry-specific forecast inputs included technetium-99m generator supply reliability indices and cyclotron manufacturing license issuance rates across the analysis window.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to molybdenum-99 reactor retirement schedules and theranostic reimbursement policy shifts. Forecasts reflect documented assumptions regarding isotope supply continuity, regulatory harmonization progress, and hospital capital expenditure cycles. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Japan Mammography Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Diagnostic Imaging Services Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Asia Pacific Nuclear Imaging Market
Medical Imaging
North America Nuclear Imaging Market
Medical Imaging
Argentina Computed Tomography Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
United States Nuclear Imaging Market
Medical Imaging
Europe MRI (Magnetic Resonance Imaging) Market
Medical Imaging
North America Computed Tomography (CT) Market
Medical Imaging
Spain Computed Tomography Market
Medical Imaging
China Diagnostic Imaging Equipment Market
Medical Imaging
Asia-Pacific Fluoroscopy Market
Medical Imaging
Global Cone Beam Computed Tomography Market
Medical Imaging
Germany Nuclear Imaging Market