
 Radiography-Fluoroscopy Combo System Market | 2026-2036
Radiography-Fluoroscopy Combo System Market Size, Share, and Industry Trends Forecast 2026-2036
Radiography-Fluoroscopy Combo System Market Analytics
Aftermarket service revenue is reshaping margin distribution across the installed base. Siemens Healthineers leverages its remote diagnostics infrastructure to lock in long-term service contracts. GE Healthcare anchors its competitive stance through predictive maintenance algorithms embedded in fleet management. Philips Healthcare differentiates by bunding software upgrades with hardware refresh cycles.
A radiography-fluoroscopy combo system integrates static X-ray capture with real-time dynamic imaging in a single C-arm or ceiling-suspended gantry architecture, typically employing flat-panel detectors with cesium iodide scintillators and pulsed fluoroscopy modes to reduce patient dose while enabling interventional guidance. Fixed systems dominate capital allocation in tertiary hospitals performing complex hybrid procedures, while mobile configurations are gaining traction in emergency departments and hybrid operating rooms where space flexibility commands premium pricing. Digital direct radiography segments capture the bulk of replacement demand as analog and computed radiography installations age out of serviceable life.
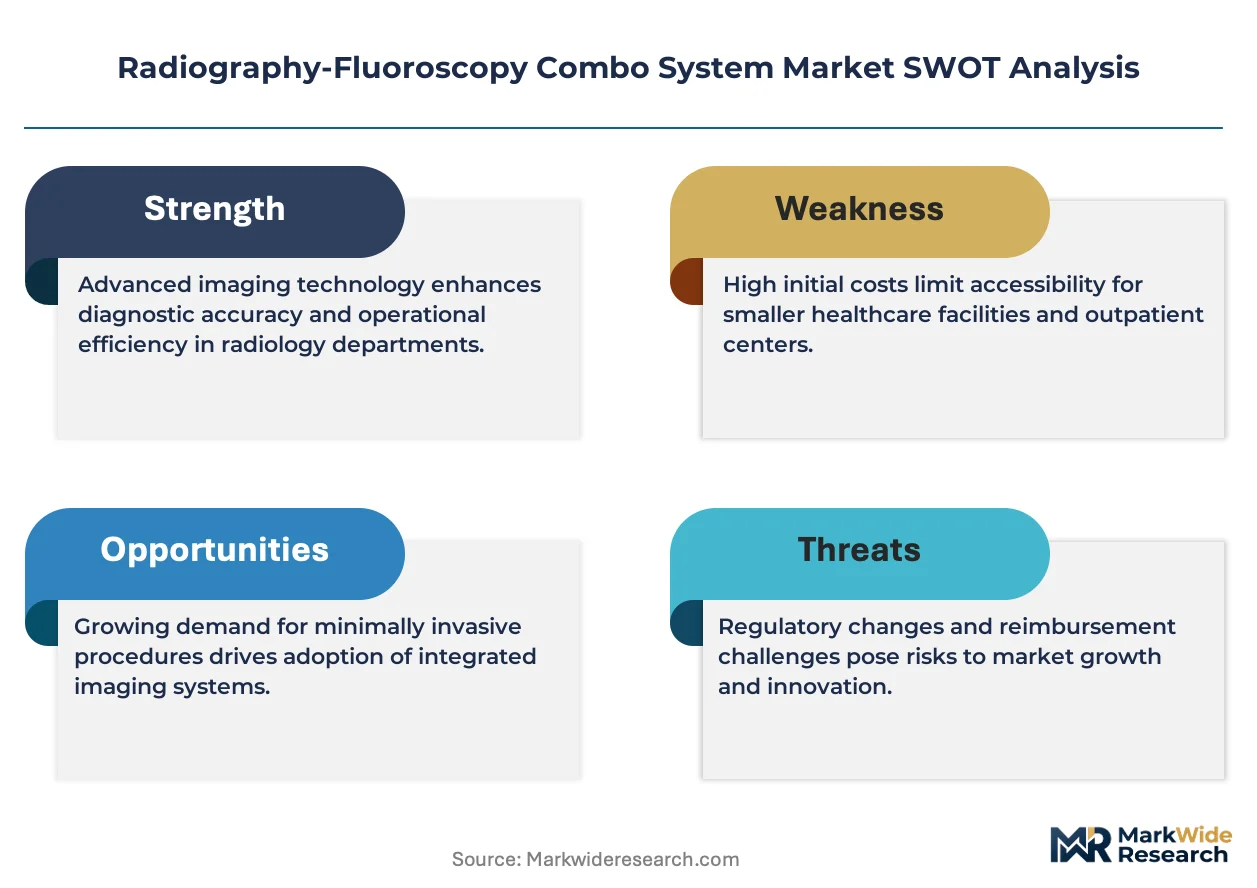
The FDA enforces radiation safety standards under 21 CFR 1020.32 for fluoroscopic equipment, while the EPA administers disposal protocols for lead-shielded components and mercury-containing high-voltage rectifiers. In Europe, the MDR and CE marking frameworks govern clinical performance validation and post-market surveillance obligations for electro-mechanical medical devices. Stakeholders must weigh regulatory compliance costs against the revenue stability of multi-year hospital service agreements as procurement committees tighten total-cost-of-ownership evaluations.
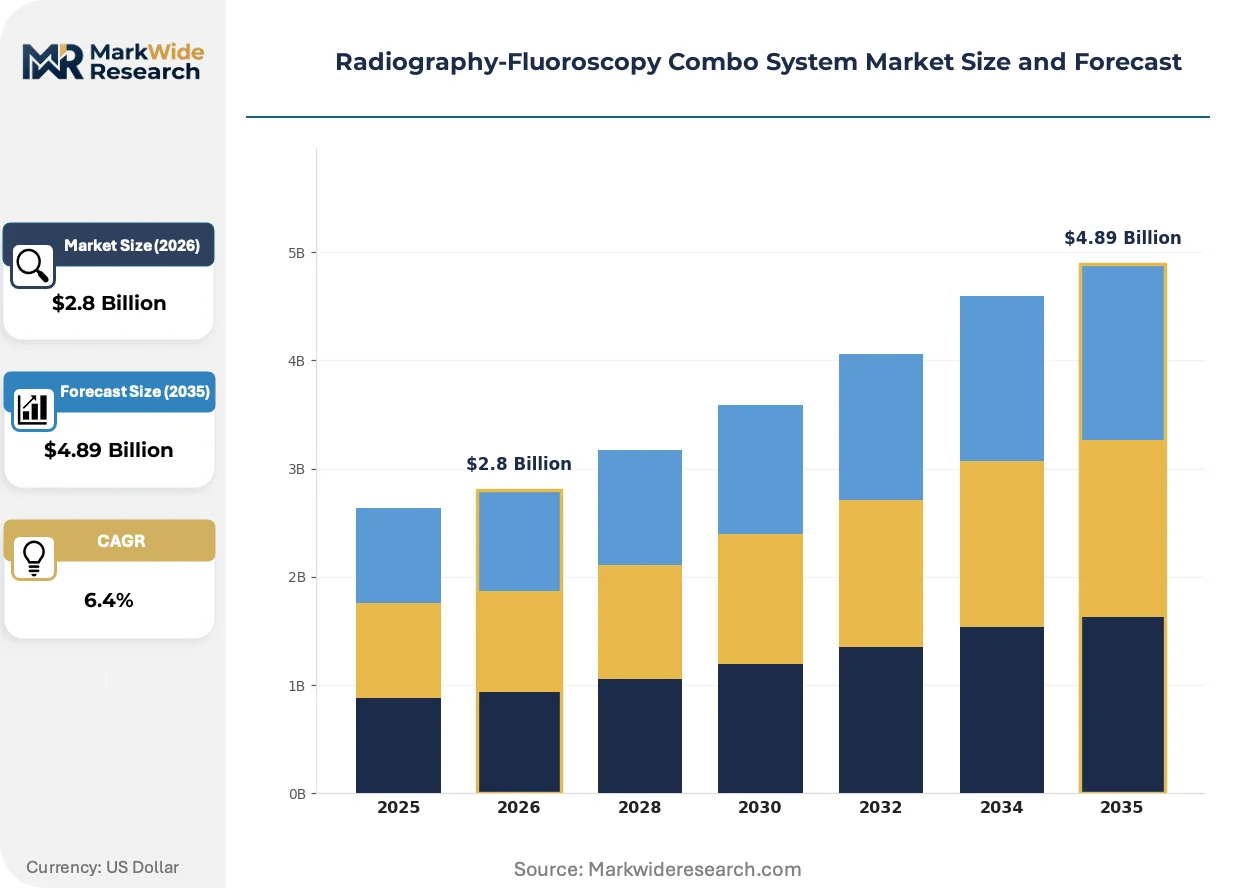
Market Dynamics
Hospital capital equipment consolidation is compressing procurement cycles for multi-modality imaging platforms, forcing vendors to bundle software, hardware, and long-term service into unified contracts that lock out point-product competitors.
Growth Catalysts
- MDR Compliance Deadlines:European hospitals are accelerating replacement of legacy fluoroscopy systems ahead of stricter post-market surveillance requirements under the EU Medical Device Regulation.
- Hybrid Operating Room Expansion:Tertiary surgical centers are installing ceiling-suspended combo systems to enable single-procedure imaging without patient transfer.
- Flat-Panel Detector Maturation:Cesium iodide scintillator technology has reached cost parity with image intensifiers, eliminating the price barrier to digital fluoroscopy adoption.
Market Restraints
- Lead-Shielded Component Disposal:EPA-administered hazardous waste protocols for mercury-containing rectifiers and leaded shielding impose end-of-life costs that extend replacement cycles.
- Detector Supply Concentration:Flat-panel sensor production concentrates in East Asian foundries, exposing OEMs to single-source risk for amorphous silicon backplanes.
- Dose-Reduction Technical Ceiling:Pulsed fluoroscopy modes have approached quantum noise limits, constraining further patient exposure reduction without image quality trade-offs.
Strategic Opportunities
- India Diagnostic Infrastructure:Government-funded health cities and medical college expansion create demand for mobile C-arm configurations in tier-2 cities.
- AI-Enabled Workflow Convergence:Real-time anatomy recognition algorithms are hybridizing with fluoroscopy guidance to reduce operator-dependent positioning errors.
- Remote Service Channel Development:Predictive maintenance telemetry enables vendors to unbundle on-site engineer visits, capturing margin from distributed hospital networks.
Industry Challenges
- Interventional Radiologist Training Pipeline:Fellowship program capacity constraints limit the specialist workforce required to operate advanced hybrid suites at full utilization.
- Legacy PACS Integration Complexity:New digital radiography installations must bridge DICOM compatibility gaps with decade-old hospital information systems, extending deployment timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Radiography-Fluoroscopy Combo System Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.89 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed Systems, Mobile Systems, Digital Systems, Analog Systems End User: Hospitals, Clinics, Diagnostic Centers, Research Institutions Technology: X-Ray Technology, Computed Radiography, Direct Radiography, Fluoroscopy Technology Application: Orthopedics, Cardiology, Gastroenterology, Oncology |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Canon Medical Systems Corporation, Shimadzu Corporation, Hologic Inc., Ziehm Imaging GmbH, Carestream Health Inc., Fujifilm Holdings Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Radiography-Fluoroscopy Combo System Market Evolving Landscape
Software-defined imaging architectures are displacing fixed-function hardware, enabling vendors to deliver capability upgrades through firmware rather than capital replacement.
Photon-counting detector technology is hybridizing spectral imaging with conventional fluoroscopy, enabling tissue characterization during interventional procedures. Academic medical centers in Germany and the United States are piloting these systems for cardiac and vascular applications. The technology is compressing the distinction between diagnostic and interventional imaging platforms.
MDR Article 10 clinical evidence requirements are forcing manufacturers to maintain post-market clinical follow-up databases for fluoroscopy systems. This obligation is raising compliance costs for mid-tier OEMs without established surveillance infrastructure. European notified bodies are prioritizing combo system submissions, creating approval bottlenecks for standalone product lines.
Hospital procurement committees are consolidating imaging capital into multi-year enterprise agreements with single vendors. Independent distributors and regional equipment lessors are losing access to decision-makers as health systems centralize supplier relationships. This concentration is most visible in United States integrated delivery networks, where radiology service line directors now control fleet-wide refresh decisions.
Radiography-Fluoroscopy Combo System Market Segmentation
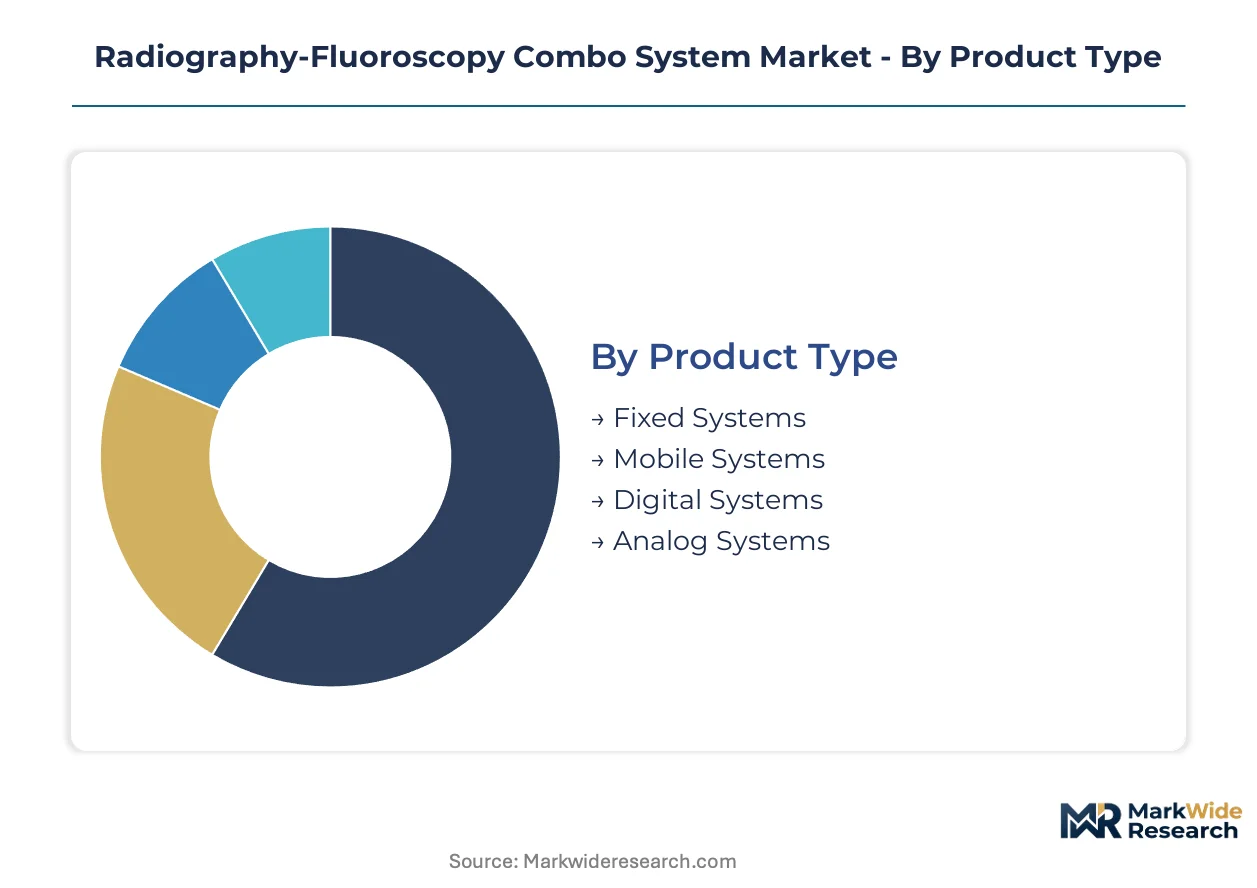
Segmentation in the radiography-fluoroscopy combo system market reveals divergent replacement cycles and margin profiles across hardware configurations and clinical settings. Procurement committees weigh total-cost-of-ownership differently depending on whether systems serve high-throughput diagnostic workflows or specialized interventional suites.
Product Type:
Fixed systems turn over slowest due to installation infrastructure and shielding requirements, while mobile units refresh faster as emergency departments prioritize flexibility over longevity.
- Fixed Systems:Ceiling-suspended or floor-mounted gantry architectures with integrated flat-panel detectors and specialized interventional tables. Tertiary hospitals in the United States anchor demand for these configurations as hybrid operating room construction accelerates, though lead-shielded component disposal under EPA protocols extends replacement timelines.
- Mobile Systems:C-arm configurations on motorized bases with battery-powered operation for intraoperative positioning. Emergency departments and hybrid surgical suites drive procurement, with space-constrained facilities in Germany and Japan paying premium pricing for compact footprint designs that enable rapid room turnover.
- Digital Systems:Flat-panel detector-based platforms with DICOM-native workflow integration.
- Analog Systems:Legacy film-screen and cassette-based architectures nearing end-of-serviceable life.
Fixed systems anchor the volume base while mobile systems gain share at the steepest rate.
End User:
Cost tier differentiation separates capital-rich integrated delivery networks from price-sensitive independent diagnostic operators.
- Hospitals:Multi-modality imaging departments with centralized procurement committees and enterprise vendor contracts. Health system consolidation in the United States concentrates fleet-wide refresh decisions at the service line director level, locking out point-product competitors through bundled hardware-software-service agreements.
- Diagnostic Centers:Outpatient imaging facilities with high patient throughput and rapid equipment utilization. These operators in India and Brazil prioritize mobile C-arm configurations for cost efficiency, though MDR compliance deadlines in Europe are accelerating replacement of aging fluoroscopy units ahead of stricter post-market surveillance requirements.
- Clinics:Smaller-scale operators with limited capital budgets and refurbished equipment preference.
- Research Institutions:Academic medical centers piloting photon-counting detector technology and spectral imaging applications.
Hospitals command the largest capital allocation while diagnostic centers expand most quickly in emerging markets.
Technology:
Volume concentration favors direct radiography as computed radiography installations age out and image intensifiers face obsolescence.
- Direct Radiography:Amorphous silicon or selenium-based flat-panel detectors capturing X-ray photons without intermediate conversion steps. Replacement demand concentrates in the United States and Germany as digital direct radiography reaches cost parity with legacy systems, while East Asian foundry concentration for amorphous silicon backplanes exposes OEMs to single-source supply risk.
- Fluoroscopy Technology:Real-time dynamic imaging with pulsed exposure modes and cesium iodide scintillators. Cardiac and vascular interventional suites in academic medical centers drive adoption, though quantum noise limits on pulsed fluoroscopy constrain further patient dose reduction without image quality trade-offs.
- X-Ray Technology:Conventional static radiography with rotating anode tubes and grid-controlled exposures.
- Computed Radiography:Photostimulable phosphor plate systems in declining installed base.
Direct radiography anchors the volume base while fluoroscopy technology climbs the fastest as interventional procedure volumes rise.
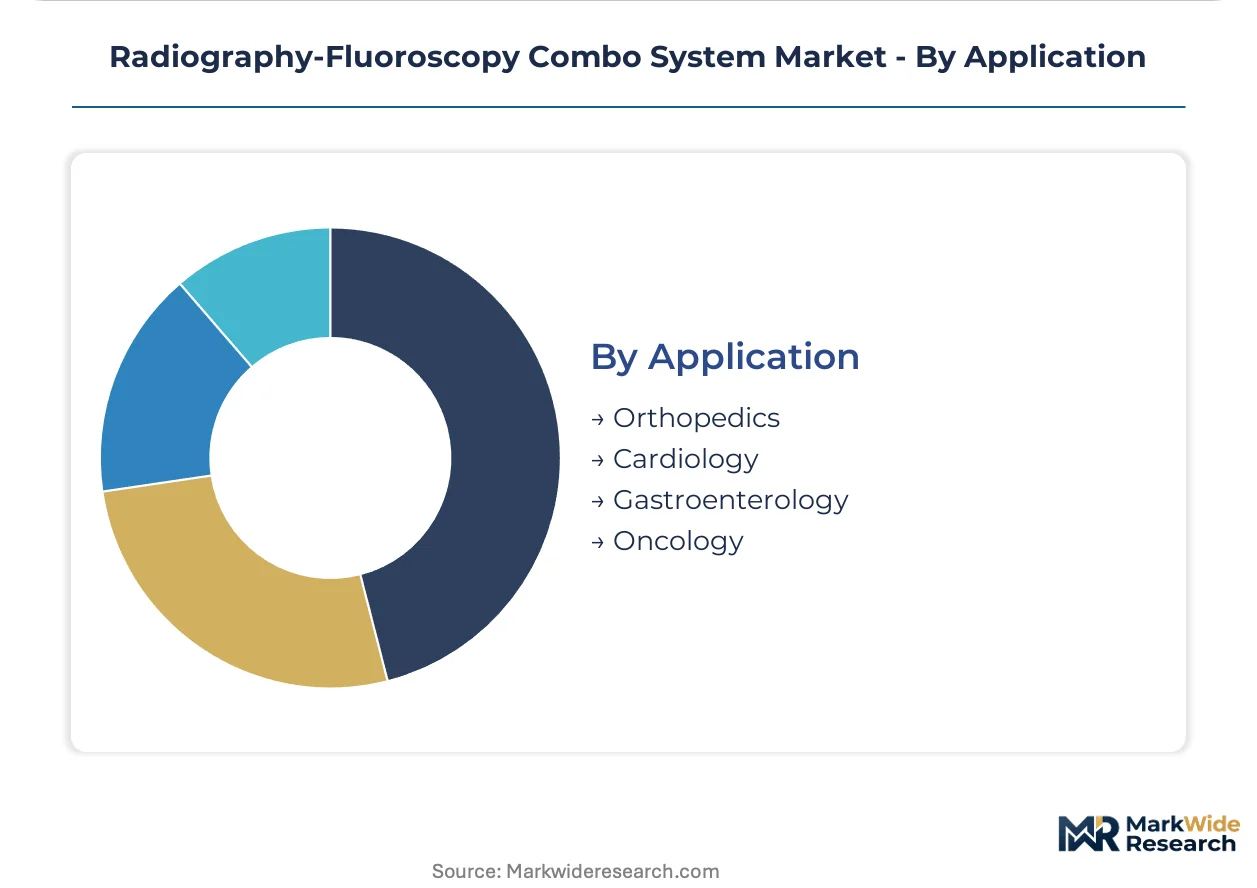
Application:
Procedure reimbursement rates and specialist workforce availability determine technology deployment intensity across clinical domains.
- Orthopedics:Weight-bearing extremity imaging and intraoperative fracture reduction guidance. Demand concentrates in sports medicine centers and trauma hospitals, with mobile C-arm configurations enabling fluoroscopic confirmation of implant positioning without patient transfer to fixed radiography suites.
- Cardiology:Coronary angiography and electrophysiology procedures requiring high-frame-rate fluoroscopy. Tertiary cardiac centers in the United States and Germany drive specification requirements for low-dose pulsed modes, though fellowship program capacity constraints limit the interventional cardiologist workforce required for full suite utilization.
- Gastroenterology:Contrast studies and interventional biliary procedures with moderate frame-rate requirements.
- Oncology:Image-guided biopsy and tumor ablation with fusion imaging compatibility demands.
Orthopedics anchors the volume base while cardiology gains share at the steepest rate as structural heart interventions expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity diverges sharply between mature health systems with bundled procurement power and emerging markets where capital constraints stretch replacement cycles. Buyers in the United States and Germany negotiate enterprise-scale service contracts that absorb premium hardware pricing. Operators in India and Brazil prioritize mobile configurations that maximize throughput per dollar deployed.
United States
Integrated delivery networks consolidate fleet-wide refresh decisions at the radiology service line director level, locking out point-product competitors through bundled hardware-software-service agreements. FDA 510(k) modernization tightens premarket validation requirements for radiological devices. Academic medical centers in Boston and Stanford pilot photon-counting detector technology for cardiac applications.
Germany
Tertiary surgical centers accelerate ceiling-suspended combo system installations to enable single-procedure imaging without patient transfer. MDR Article 10 clinical evidence requirements force manufacturers to maintain post-market clinical follow-up databases. Medical device clusters in Munich and Erlangen concentrate notified body expertise, creating approval bottlenecks for standalone product lines.
India
Government-funded health cities and medical college expansion create demand for mobile C-arm configurations in tier-2 cities. CDSCO regulates radiological device imports under the Medical Devices Rules framework. Diagnostic infrastructure investments concentrate in Maharashtra and Karnataka, where private hospital chains consolidate capital equipment procurement.
Japan
Space-constrained facilities pay premium pricing for compact footprint designs that enable rapid room turnover in hybrid surgical suites. PMDA enforces radiation safety standards aligned with IAEA guidelines. Industrial clusters in Tokyo and Osaka anchor flat-panel detector assembly operations for regional OEM supply chains.
Brazil
Independent diagnostic operators prioritize refurbished equipment and extended service intervals to manage currency-driven capital volatility. ANVISA governs medical device registration and post-market surveillance for electro-mechanical imaging systems. São Paulo's private hospital networks drive replacement demand as aging computed radiography installations exit serviceable life.
Radiography-Fluoroscopy Combo System Market Competitive Landscape
Capability concentration sits with full-stack imaging conglomerates; scale advantage sits with diversified health technology portfolios. The vendor base stratifies across three tiers: integrated diagnostic imaging platforms, specialized interventional equipment fabricators, and regional distributors losing access as procurement centralizes. Dominant competitive moves include predictive maintenance telemetry unbundling and software-defined architecture roadmaps that extend hardware replacement cycles.
Among diversified health technology conglomerates, Siemens Healthineers, GE Healthcare, and Philips Healthcare exemplify the integrated-platform archetype. Each anchors competitive positioning through distinct service model configurations rather than hardware differentiation alone. Specialized interventional equipment manufacturers including Ziehm Imaging GmbH and Shimadzu Corporation occupy positions emphasizing compact footprint engineering and mobile C-arm mobility. The competitive terrain rewards vendors capable of embedding predictive algorithms into fleet management infrastructure while navigating MDR compliance cost escalations that disproportionately burden mid-tier OEMs without established clinical surveillance databases.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Canon Medical Systems Corporation |
| Shimadzu Corporation |
| Hologic Inc. |
| Ziehm Imaging GmbH |
| Carestream Health Inc. |
| Fujifilm Holdings Corporation |
| Others |
Value Network & Pricing Analysis
The Shanghai-Rotterdam maritime corridor's freight cost volatility directly shapes procurement economics for flat-panel detector assemblies, amplifying margin compression for mid-tier OEMs while allowing Siemens Healthineers and GE Healthcare to leverage captive logistics contracts that insulate premium pricing tiers from spot-rate fluctuations.
Pricing Analysis
Aftermarket service revenue streams anchor lifetime value realization across the installed base, with predictive maintenance contracts and software upgrade subscriptions now exceeding hardware margins in mature markets. Three-tier pricing structure across premium, standard, and economy levels separates integrated delivery networks with enterprise bargaining power from independent diagnostic centers facing cost compression. Price differentiation hinges on FDA 510(k) clearance tier and bundled service intensity, with academic medical centers least sensitive and tier-2 hospital procurement committees in emerging markets most reactive to capital outlay thresholds.
Supply Chain Analysis
Single-source vulnerability for amorphous silicon backplanes concentrates in Taiwanese and South Korean foundries, exposing OEMs to geopolitical disruption risk that has prompted Philips Healthcare and Canon Medical to diversify sourcing toward Japanese sensor fabricators. Cesium iodide scintillator crystals draw from Chinese and Belgian processing facilities, while high-voltage generator assemblies rest on German and Japanese component suppliers. Tariff exposure between the United States and China dominates strategic procurement planning, with distribution running through authorized dealer networks in fragmented markets and direct enterprise contracts in consolidated health systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is accelerating toward integrated delivery networks as hospital consolidation compresses vendor counts, fragmenting access for point-product competitors while concentrating negotiation leverage in radiology service line directors.
For Market Incumbents: Harden predictive maintenance telemetry infrastructure to lock in multi-year service contracts before MDR compliance costs escalate. Deepen backward integration into flat-panel detector assembly through partnerships with Taiwanese foundries, countering emerging entrant price aggression in mobile C-arm configurations. Prioritize software-defined architecture roadmaps that extend hardware replacement cycles while capturing recurring revenue from firmware upgrades. For New Entrants and Emerging Players: Establish a beachhead in India's tier-2 diagnostic infrastructure, where government-funded health cities create procurement windows outside entrenched vendor relationships. Target mobile C-arm configurations for orthopedic trauma centers with compact footprint engineering and localized service partnerships, bypassing the enterprise contract barriers that protect incumbents in United States integrated delivery networks. For Investors and Strategic Acquirers: Regional service specialists with MDR-compliant clinical surveillance databases represent the most defensible acquisition archetype as compliance costs disproportionately burden mid-tier OEMs. Long-term viability rests on software-attach-rate trajectories rather than hardware shipment volumes. Monitor photon-counting detector pilot outcomes at academic medical centers in Germany and the United States as the critical inflection signal for platform consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Remote Diagnostics Infrastructure Deployment | Siemens Healthineers leverages telemetry to unbundle on-site engineer visits across distributed hospital networks. |
| Predictive Maintenance Algorithm Integration | GE Healthcare embeds fleet analytics to preempt component failures before clinical workflow disruption occurs. |
| Software-Defined Imaging Architecture Roadmap | Philips Healthcare delivers capability upgrades through firmware rather than capital replacement cycles. |
| MDR Clinical Evidence Database Construction | Mid-tier OEMs must build post-market surveillance infrastructure to satisfy Article 10 compliance deadlines. |
| Photon-Counting Detector Pilot Expansion | Academic medical centers in Germany and the United States validate spectral imaging for cardiac interventions. |
Research Methodology
Operator-level perspectives from hospital procurement committee chairs, biomedical engineering directors, GPO contracts managers, and interventional radiology fellowship program directors anchored the qualitative base, cross-referenced with FDA 510(k) clearance databases, EUDAMED post-market surveillance records, hospital capital equipment procurement disclosures, and OEM service contract filings. Bottom-up installation base modeling and top-down health system expenditure analysis were triangulated against flat-panel detector shipment data from East Asian component suppliers.
Scenario-bracketing across regulatory compliance cost trajectories, health system consolidation velocities, and detector technology substitution curves shaped the analytical framework over the projection horizon. Segmentation dimensions included fixed versus mobile system architecture, direct radiography versus fluoroscopy technology intensity, and academic medical center versus community hospital end-use profiles. CAGRs were derived from replacement cycle compression rates and interventional procedure volume elasticity, with photon-counting detector adoption curves and AI-enabled workflow penetration serving as key forecast inputs.
Stress conditions across EPA lead-shielded disposal cost escalations, Taiwanese foundry supply disruptions, and fellowship program capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding MDR enforcement intensity and hybrid operating room construction rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Imaging
Digital Pathology Scanner Calibration and Image Quality Test Systems Market
Medical Imaging
United Arab Emirates Diagnostic Imaging Equipment Market
Medical Imaging
Global Positron Emission Tomography [PET] Scanners Market
Medical Imaging
Advanced Computed Tomography (CT) Scanner Market
Medical Imaging
Digital Mobile X-Ray Products Market
Medical Imaging
Veterinary CT Imaging Market
Medical Imaging
Mobile Computed Tomography Scanners Market
Medical Imaging
Medical Radiation Detection Market
Medical Imaging
Digital Breast Tomosynthesis Market
Medical Imaging
Breast Imaging Technologies Market
Medical Imaging
Asia Pacific Open System MRI Market
Medical Imaging
AI-Enabled Diagnostic Imaging Market
Medical Imaging
Saudi Arabia Digital Radiology Market
Medical Imaging
Global Vendor-Neutral Archive (VNA) and PACS Market
Medical Imaging
North America Nuclear Medicine Market
Medical Imaging
Australia Mammography Market