
 Honduras Construction Market | 2026-2036
Honduras Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Honduras Construction Market Insights
Prefabricated concrete panel systems is narrowing the gap between informal masonry and industrial-grade construction across Honduras. Salvador Gracia Constructions leverages its vertically integrated ready-mix and block production to dominate mid-rise residential commissions in Tegucigalpa. Constructora Celaque anchors the western highlands with specialized seismic-resistant designs for institutional clients. Aceros Alfa Honduras competes through captive steel distribution that controls rebar pricing for government infrastructure tenders.
Construction in Honduras encompasses the assembly of buildings and civil works using concrete, steel reinforcement, timber framing, and glass curtain systems, with compressive strength specifications for structural concrete typically ranging from 21 to 35 MPa depending on seismic zone classification. The primary purpose spans shelter provision, commercial activity facilitation, and transport connectivity for a population of roughly ten million. Residential project types currently absorb the largest share of material throughput, particularly in the Sula Valley where developer-financed subdivisions are expanding. Infrastructure segments represent the fastest-growing category as the Honduran government prioritizes highway interconnection and port capacity upgrades financed through multilateral lending. Concrete materials dominate volume flows, though steel reinforcement commands disproportionate margin pools due to import dependency and currency fluctuation exposure.
The Honduran Institute of Cement and Concrete (IHCC) maintains material testing protocols that shape contractor eligibility for public works, while the Secretariat of Infrastructure and Transport (SIT) enforces bidding standards that favor firms with certified quality management systems. The national building code, updated after seismic events, mandates structural calculations that drive demand for engineered designs over traditional builder-experience methods. Stakeholders must monitor whether proposed fiscal incentives for low-income housing translate into sustained developer participation or merely concentrate risk among state-backed contractors.
Market Dynamics
The Honduran government's public-private partnership framework is redirecting foreign direct investment toward transport infrastructure, compressing project timelines and concentrating contractor eligibility among firms with certified quality management systems. This structural shift favors capital-backed operators over traditional builder-experience methods.
Growth Catalysts
- Port Modernization Drive:Northern coastal corridor upgrades are absorbing expanded cement and rebar volumes as logistics hubs reshape the built environment.
- IHCC Material Testing Protocols:The Honduran Institute of Cement and Concrete maintains contractor eligibility standards that channel public works toward certified firms.
- Seismic-Resistant Design Mandates:Updated national building codes after seismic events drive demand for engineered structural calculations over informal masonry.
Market Restraints
- Steel Import Dependency:Currency fluctuation exposure disproportionately impacts rebar margin pools due to captive distribution concentration.
- Informal Construction Persistence:Traditional builder-experience methods in residential segments resist industrial-grade prefabricated concrete panel adoption.
- Multilateral Lending Cycles:Highway interconnection financing depends on external debt instruments with irregular disbursement schedules.
Strategic Opportunities
- Sula Valley Developer-Financed Subdivisions:Residential project types in this corridor currently absorb the largest share of material throughput expansion.
- Prefabricated Concrete Convergence:Panel systems integration with ready-mix production narrows the gap between informal masonry and industrial-grade construction.
- Low-Income Housing Fiscal Incentives:Proposed state-backed contractor participation programs may concentrate risk or sustain developer engagement.
Industry Challenges
- Engineered Design Skill Scarcity:Structural calculation certification requirements outpace technical training pipeline capacity in Tegucigalpa and San Pedro Sula.
- Quality Management System Compliance:Secretariat of Infrastructure and Transport bidding standards demand documentation that smaller contractors struggle to assemble.
- Seismic Zone Classification Complexity:Compressive strength specifications ranging from 21 to 35 MPa require material testing protocols that extend project pre-construction phases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Honduras Construction Market |
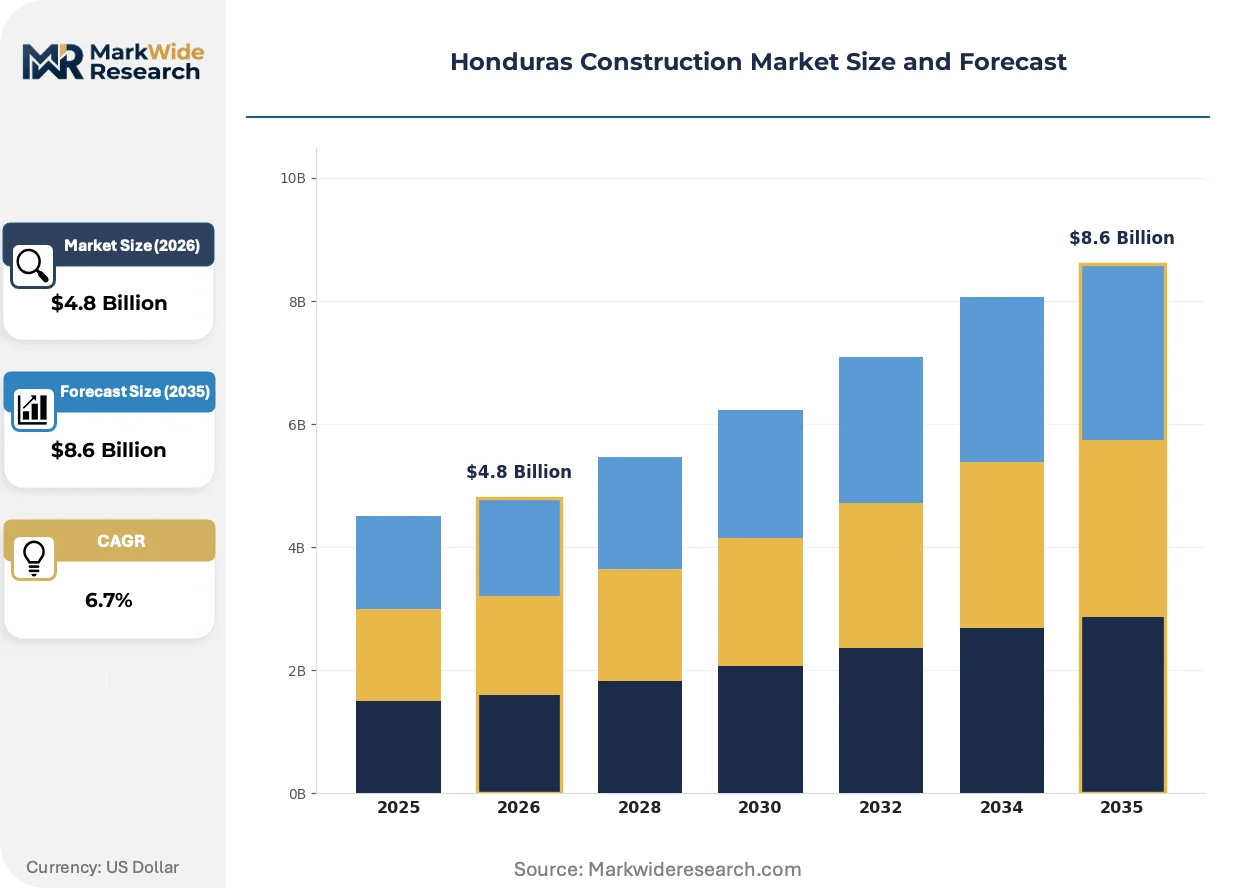
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Project Type: Residential, Commercial, Infrastructure, Institutional Material: Concrete, Steel, Wood, Glass End User: Government, Developers, Contractors, Homeowners Construction Stage: Design, Planning, Execution, Finishing |
| Companies Covered | Salvador Gracia Constructions, Roatan Zelaya Construction, Ingenieros Civiles Asociados Inversiones, Conmoxa SRL, Santos Y Compania SA DE CV, Larach Y Cia, Aceros Alfa Honduras, Constructora Celaque, CONCREMIX, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Honduras Construction Market Trends and Innovations
Construction practice in Honduras is pivoting from informal masonry toward industrialized methods as seismic codes tighten and foreign capital seeks deployable infrastructure assets. Three intersecting developments are compressing traditional project delivery models.
Building Information Modeling software is virtualizing project coordination across the Sula Valley developer corridor. Mid-rise residential commissions in Tegucigalpa now require digital clash detection and quantity takeoff precision that informal builders cannot match. This technology is virtualizing the traditional architect-contractor relationship, compressing design-to-construction handoff timelines.
The Secretariat of Infrastructure and Transport enforces bidding standards that favor firms with ISO-certified quality management systems. This regulatory pressure disqualifies traditional builder-experience operators from highway and bridge tenders. Western highlands institutional clients now specify seismic-resistant calculations that only engineered design firms can deliver.
Developer-financed procurement is displacing owner-managed construction in residential segments. Buyers in San Pedro Sula subdivisions now purchase completed units rather than hiring independent contractors. This channel consolidation concentrates material throughput among vertically integrated ready-mix and block producers.
Honduras Construction Market Segmentation
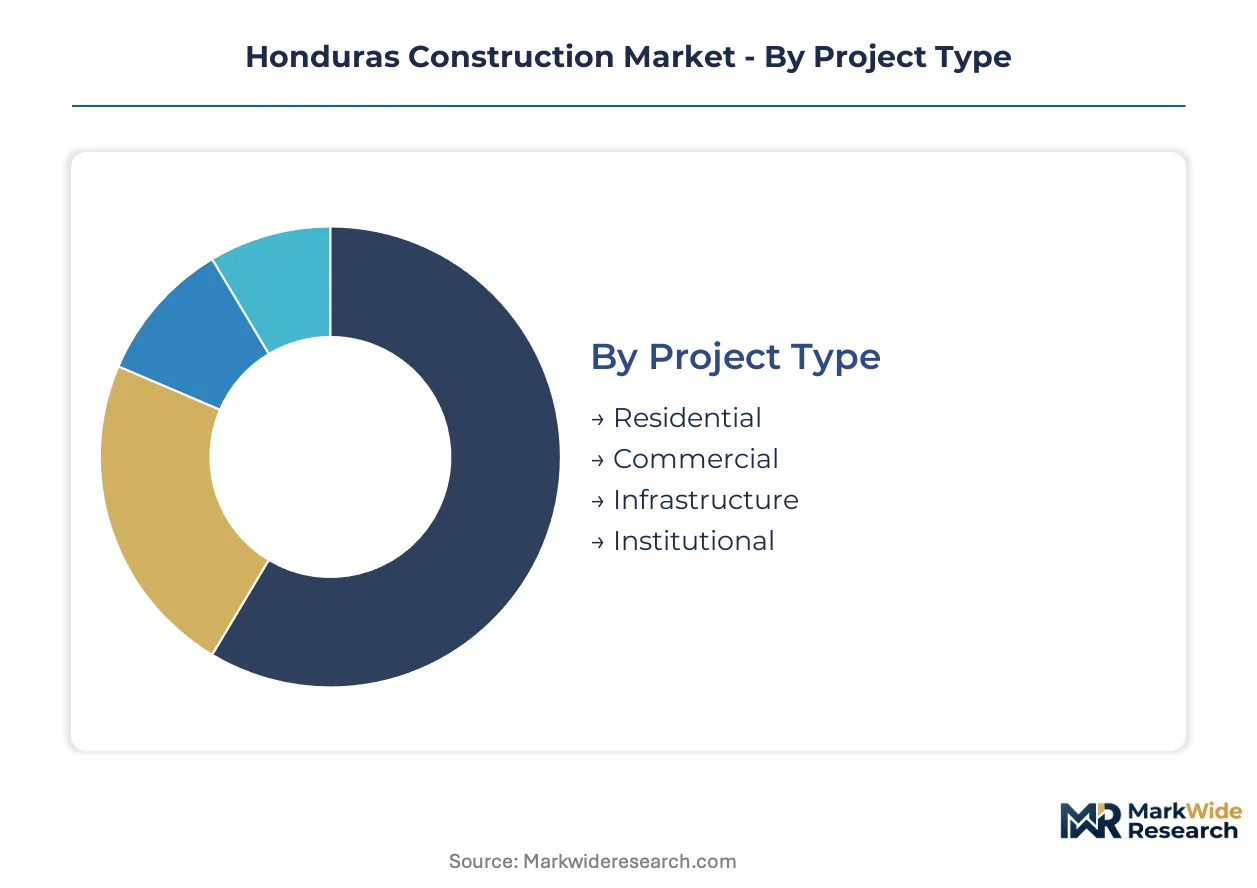
Segmentation in the Honduras construction market reveals how seismic codes, import dependencies, and public-private financing reshape competitive positioning across project types and material flows. Understanding these divisions exposes where certified contractors capture margin and where informal builders retain footholds.
Project Type:
Application focus determines contractor eligibility and financing access across Honduras.
- Residential:Compressive strength specifications of 21-28 MPa dominate Sula Valley subdivisions where developer-financed procurement displaces owner-managed construction. Tegucigalpa mid-rise commissions absorb expanded ready-mix volumes as prefabricated panel systems narrow the gap from informal masonry.
- Infrastructure:Highway interconnection and port modernization projects concentrate material throughput in the northern coastal corridor. Multilateral lending cycles and SIT bidding standards favor firms with ISO-certified quality management systems for bridge and logistics hub delivery.
- Commercial:Glass curtain systems and engineered structural calculations serve San Pedro Sula corporate clients demanding seismic-resistant designs per updated national building codes.
- Institutional:Western highlands commissions require specialized seismic-resistant calculations that only certified design firms can deliver for schools and healthcare facilities.
Residential commands the established base. The steepest expansion runs through Infrastructure.
Material:
Volume flows and margin pools diverge sharply based on import exposure and local production capacity.
- Concrete:Ready-mix and block production anchors vertically integrated operators dominating mid-rise residential commissions. IHCC material testing protocols shape contractor eligibility for public works tenders.
- Steel:Rebar pricing fluctuates with currency exposure due to import dependency, concentrating margin control among captive distribution networks serving government infrastructure projects.
- Wood:Timber framing persists in informal residential segments resisting industrial-grade adoption across rural construction zones.
- Glass:Curtain wall specifications concentrate in commercial developments where Building Information Modeling clash detection requirements filter out traditional builders.
Concrete maintains volume leadership. Steel captures disproportionate margin attention.
End User:
Customer type dictates procurement sophistication and certification requirements.
- Government:SIT bidding standards and IHCC protocols channel public works toward firms with documented quality management systems and seismic calculation capabilities.
- Developers:Financier-backed subdivisions in the Sula Valley concentrate material throughput among vertically integrated producers capable of design-to-construction handoff compression.
- Contractors:Smaller operators struggle with ISO documentation and engineered design skill scarcity in Tegucigalpa and San Pedro Sula.
- Homeowners:Independent hiring persists in informal segments where traditional builder-experience methods resist panel system adoption.
Government tenders concentrate certified capacity. Developer procurement is expanding most quickly.
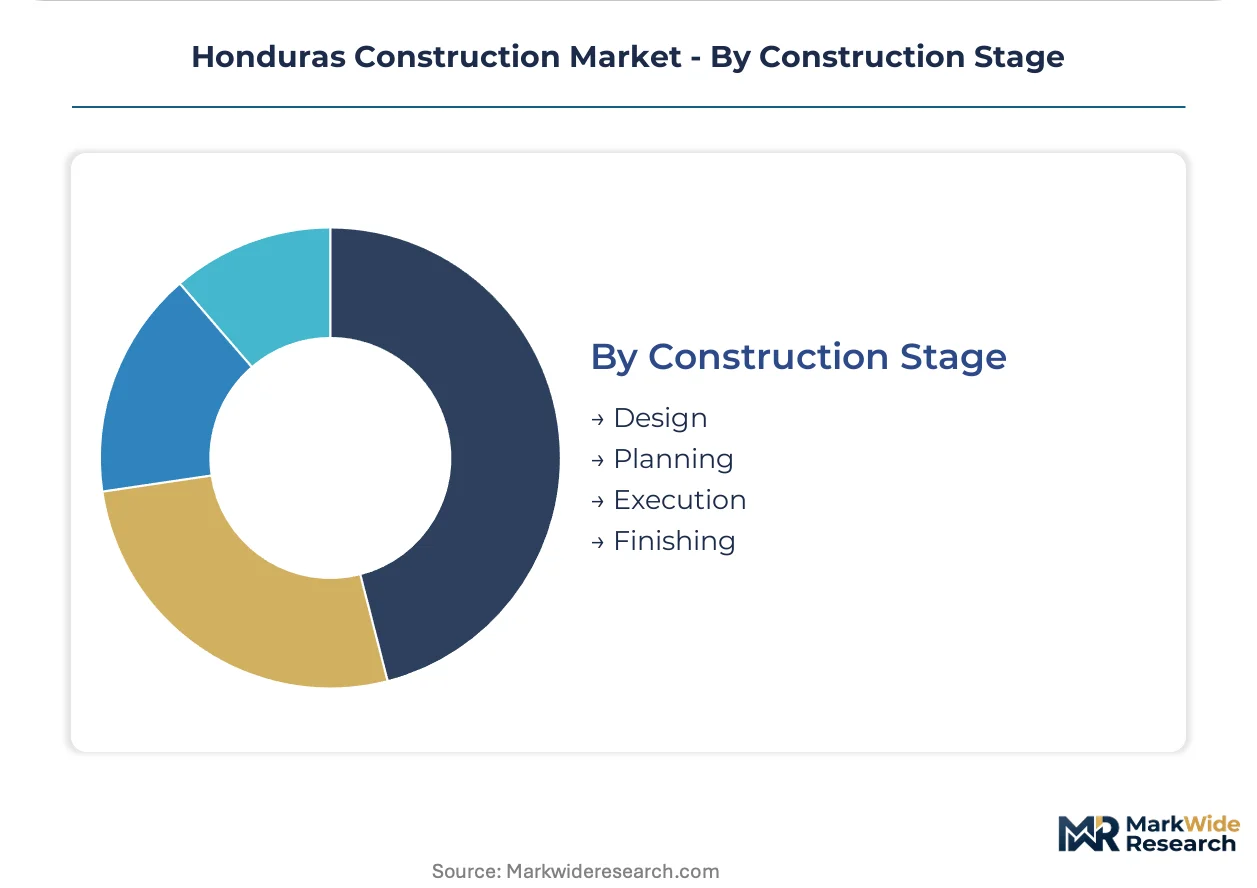
Construction Stage:
Maturity across project phases determines where technology integration and regulatory pressure apply.
- Design:Building Information Modeling virtualizes coordination for commercial and institutional clients requiring digital clash detection.
- Planning:Seismic zone classification complexity extends pre-construction phases as compressive strength specifications of 21-35 MPa demand IHCC testing protocols.
- Execution:Material throughput concentrates here as ready-mix volumes and rebar placement absorb largest cost share across all project types.
- Finishing:Glass and interior systems deployment filters toward contractors with certified quality management systems meeting SIT standards.
Execution absorbs dominant cost share. Design is gaining sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cement exports flow into Central American port modernization projects, while Colombian steel traders supply rebar for Honduran infrastructure tenders. This trade corridor shapes material cost structures across the isthmus.
Costa Rica
The Inter-American Development Bank finances seismic retrofitting programs in Greater San José, where compressive strength specifications of 28-35 MPa dominate institutional tenders. The National Quality System enforces ISO-certified contractor eligibility for public works. Cartago province anchors precast concrete production serving cross-border residential developments.
Guatemala
Guatemala City corridor developers absorb expanded ready-mix volumes as prefabricated panel systems displace informal masonry in mid-rise housing. The Ministry of Communications, Infrastructure and Housing mandates Building Information Modeling for highway tenders exceeding specific thresholds. Quetzaltenango anchors western highlands seismic-resistant design specialization for healthcare facilities.
El Salvador
San Salvador metropolitan area concentrates government-backed low-income housing fiscal incentives channeling material throughput toward certified contractors. The National Directorate of Public Works enforces quality management system documentation for bridge and logistics hub delivery. La Libertad port zone modernization absorbs disproportionate rebar volumes due to currency-exposed import dependency.
Nicaragua
Managua's developer-financed subdivisions represent the fastest-growing residential procurement channel, compressing design-to-construction handoff timelines. The Nicaraguan Institute of Territorial Studies maintains seismic zone classifications that drive engineered structural calculation demand. León corridor construction clusters around vertically integrated block producers capturing Sula Valley-style material concentration.
Panama
Panama City logistics hub expansion absorbs cement volumes transshipped through the canal corridor toward Honduran northern coastal projects. The Public-Private Partnership Authority structures transport infrastructure financing that concentrates contractor eligibility among capital-backed operators. Colón Free Trade Zone steel distribution networks control rebar pricing for regional government tenders.
Honduras Construction Market Competitive Landscape
On the supply side, the industry is bifurcated between vertically integrated material producers and specialized engineering contractors competing for certified public works eligibility. Capital-backed operators with captive ready-mix and block production dominate Sula Valley residential throughput, while seismic-design specialists capture institutional commissions in high-risk zones. Two strategic archetypes define competitive positioning: integrated material-to-construction platforms and certified engineering-led project delivery. Dominant competitive moves include backward integration into aggregate quarrying and strategic partnerships with multilateral lenders for infrastructure financing access.
Within the integrated production tier, Salvador Gracia Constructions and CONCREMIX exemplify capital-backed operators combining captive supply with design-to-construction compression. Constructora Celaque occupies a position among specialized seismic-resistant design firms serving western highlands institutional clients. Aceros Alfa Honduras anchors the captive steel distribution archetype, representing how import-dependent rebar sourcing concentrates margin control for government tender participation.
| Leading Market Players |
|---|
| Salvador Gracia Constructions |
| Roatan Zelaya Construction |
| Ingenieros Civiles Asociados Inversiones |
| Conmoxa SRL |
| Santos Y Compania SA DE CV |
| Larach Y Cia |
| Aceros Alfa Honduras |
| Constructora Celaque |
| CONCREMIX |
| Others |
Pricing and Supply Chain Analysis
Steel import dependency exposes rebar pricing to currency fluctuation risk that widens spreads between certified government-tier contracts and informal residential procurement. This vulnerability compresses margins for distributors lacking captive sourcing while concentrating pricing power among vertically integrated operators controlling both material throughput and project delivery.
Pricing Analysis
Construction-method pricing gaps separate BIM-enabled engineered design from traditional builder-experience approaches across Tegucigalpa mid-rise commissions. Three-tier pricing structure across certified seismic-resistant, standard compliant, and informal masonry tiers reflects IHCC protocol adherence and SIT bidding documentation requirements. Cost compression in economy-tier residential segments intensifies as developer-financed subdivisions displace owner-managed construction. Government infrastructure buyers show lowest price sensitivity due to multilateral lending backstops, while independent homeowners in rural zones face acute budget constraints.
Supply Chain Analysis
Export-control regimes on seismic-resistant design software and BIM coordination platforms limit technology transfer to certified Honduran engineering firms. Raw material flows draw from Chinese cement exports, Colombian steel traders, and domestic aggregate quarries serving the northern coastal corridor. Single-source vulnerability concentrates in rebar import channels exposed to currency volatility. Distribution runs through vertically integrated ready-mix producers dominating Sula Valley residential throughput and captive steel distributors controlling government tender participation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward developer-financed procurement that concentrates material throughput among capital-backed operators, fragmenting traditional contractor relationships and squeezing informal builders from eligibility pools.
For Market Incumbents: Build certification moats around ISO-compliant quality management systems that SIT bidding standards mandate for highway and bridge tenders. Secure backward integration into aggregate quarrying to defend ready-mix margin compression from Chinese cement import competition. Deepen captive steel distribution networks before currency exposure erodes rebar pricing power. For New Entrants and Emerging Players: Western highlands institutional clients present underpenetrated demand for seismic-resistant design specialization that Constructora Celaque currently dominates. Target healthcare and education facility commissions in Quetzaltenango-style corridors where engineered calculation requirements filter out informal competitors. Partner with multilateral lenders for infrastructure financing access to bypass capital barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated material-to-construction platforms over fragmented contractor bases. Long-term viability hinges on design-to-construction compression capabilities and IHCC certification eligibility. Watch for proposed low-income housing fiscal incentives as inflection signal between sustained developer engagement and risk concentration among state-backed contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aggregate Quarrying | Captive raw material supply defends ready-mix margins against Chinese cement import competition. |
| ISO Quality Management Certification | SIT bidding standards channel public works toward documented compliance, excluding informal operators. |
| Building Information Modeling Adoption | Digital clash detection requirements filter traditional builders from Tegucigalpa mid-rise commissions. |
| Multilateral Lending Partnership | Financing access unlocks highway interconnection and port modernization eligibility for infrastructure contractors. |
| Seismic-Resistant Design Specialization | Western highlands institutional demand rewards engineered calculation capabilities over builder-experience methods. |
Research Methodology
Operator-level perspectives from ready-mix plant managers, SIT procurement officers, IHCC certification auditors, and developer project directors anchored the qualitative base. Secondary validation drew from Secretariat of Infrastructure and Transport tender databases, Honduran Institute of Cement and Concrete testing protocols, multilateral lender project disclosure filings, and customs records tracking cement and steel import flows. Bottom-up project pipeline analysis triangulated against top-down material throughput estimates across the analysis window.
Scenario-bracketing framed projections across conservative, baseline, and expansion cases reflecting multilateral lending disbursement cycles and seismic code enforcement intensity. Segmentation dimensions modeled include project type, material category, end user archetype, and construction stage maturity. CAGRs derived from historical material volume trends and announced infrastructure commitments. Forecast inputs incorporated IHCC certification pipeline capacity and developer-financed subdivision absorption rates.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese cement exporters or Colombian steel traders would shift outcomes. Material shifts in low-income housing fiscal incentive implementation or seismic zone classification updates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Construction
Spain Prefab Wood Buildings Market
Building Construction
Precast Construction Market
Building Construction
Australia Construction Market
Building Construction
UAE Facade Market
Building Construction
Swiss Prefabricated Buildings Market
Building Construction
UAE Prefab Wood Buildings Market
Building Construction
Asia Pacific Modular Construction Market
Building Construction
GCC Construction Market
Building Construction
Vertical Garden Construction Market
Building Construction
South Korea Data Center Construction Market
Building Construction
ASEAN Prefab Wood Buildings Market
Building Construction
Middle East Data Center Construction Market
Building Construction
Saudi Arabia Prefabricated Buildings Market
Building Construction
Middle East & Africa Infrastructure Construction Market
Building Construction
Japan Commercial Construction Market
Building Construction
Saudi Arabia Construction Market