
 Europe HVAC Services Market | 2026-2036
Europe HVAC Services Market Size, Share, and Industry Trends Forecast 2026-2036
Europe HVAC Services Market Foresight
Natural refrigerants are decoupling service economics from synthetic refrigerant dependencies across the European HVAC services sector. Daikin Industries Ltd. leverages its VRF technology leadership to capture premium maintenance contracts in commercial districts. Bosch Thermotechnik GmbH anchors its position through backward integration into heat pump manufacturing and captive service networks. Carrier Global Corporation competes on scale, operating centralized service hubs that reduce response times for industrial clients.
Europe HVAC Services encompasses the installation, maintenance, repair, and consulting of climate control systems including chillers, boilers, rooftop units, and variable refrigerant flow configurations, typically operating within temperature ranges of minus twenty to plus fifty degrees Celsius for commercial and industrial thermal management. The primary purpose is sustaining indoor environmental quality while optimizing energy consumption across building portfolios. Installation services dominate revenue pools given capital-intensive equipment replacement cycles, while maintenance contracts generate recurring margin streams that expand with smart system penetration. Consulting segments are accelerating as building owners navigate F-Gas phase-down timelines and decarbonization pathways.
The EU F-Gas Regulation and Ecodesign Directive shape equipment replacement schedules and refrigerant handling protocols, forcing service providers to certify technicians on CO2 and hydrocarbon systems. CE marking requirements under the Machinery Directive govern market access for replacement components and control systems. National regulators including Germany's KBA-referenced building codes and France's ANSM-adjacent energy audit mandates layer additional compliance complexity. Stakeholders must monitor refrigerant quota allocations and technician certification bottlenecks as structural constraints on service capacity expansion.
Market Dynamics
The EU F-Gas Regulation is compressing refrigerant replacement cycles and forcing service providers to reconfigure technician training pipelines around CO2 and hydrocarbon handling protocols.
Growth Catalysts
- Building retrofit mandates:Germany's KBA-referenced energy codes and France's ANSM-adjacent audit requirements are accelerating equipment replacement schedules across Class A office portfolios.
- Heat pump deployment:Netherlands building stock electrification targets are expanding installation service demand for hybrid and all-electric thermal systems.
- Smart system penetration:IoT-enabled predictive maintenance platforms are extending contract durations and attaching recurring revenue streams to hardware deployments.
Market Restraints
- Technician certification bottlenecks:F-Gas quota allocations under EU regulation are constraining the supply of qualified refrigerant handlers across member states.
- Copper and aluminum input volatility:Raw material price swings for heat exchanger components are compressing margin predictability on fixed-price installation contracts.
- Specialized equipment concentration:Recovery and recycling machinery for lower-GWP refrigerants remains concentrated among German and Italian OEM supply chains.
Strategic Opportunities
- Poland and Romania building stock:Underpenetrated districts in Eastern Europe present expansion terrain for service networks ahead of EU cohesion fund infrastructure deployment.
- Industrial process cooling:Data center thermal management contracts represent emerging application volume as hyperscale facilities cluster in the Netherlands and Ireland.
- CSRD disclosure requirements:Corporate sustainability reporting mandates are creating advisory service attach rates for decarbonization pathway planning alongside hardware sales.
Industry Challenges
- Hydrocarbon safety certification:Technician licensing for flammable refrigerant systems requires extended training timelines that outpace contract award velocity.
- Legacy control integration:BACnet and Modbus protocol fragmentation across installed building automation systems complicates unified service platform deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe HVAC Services Market |
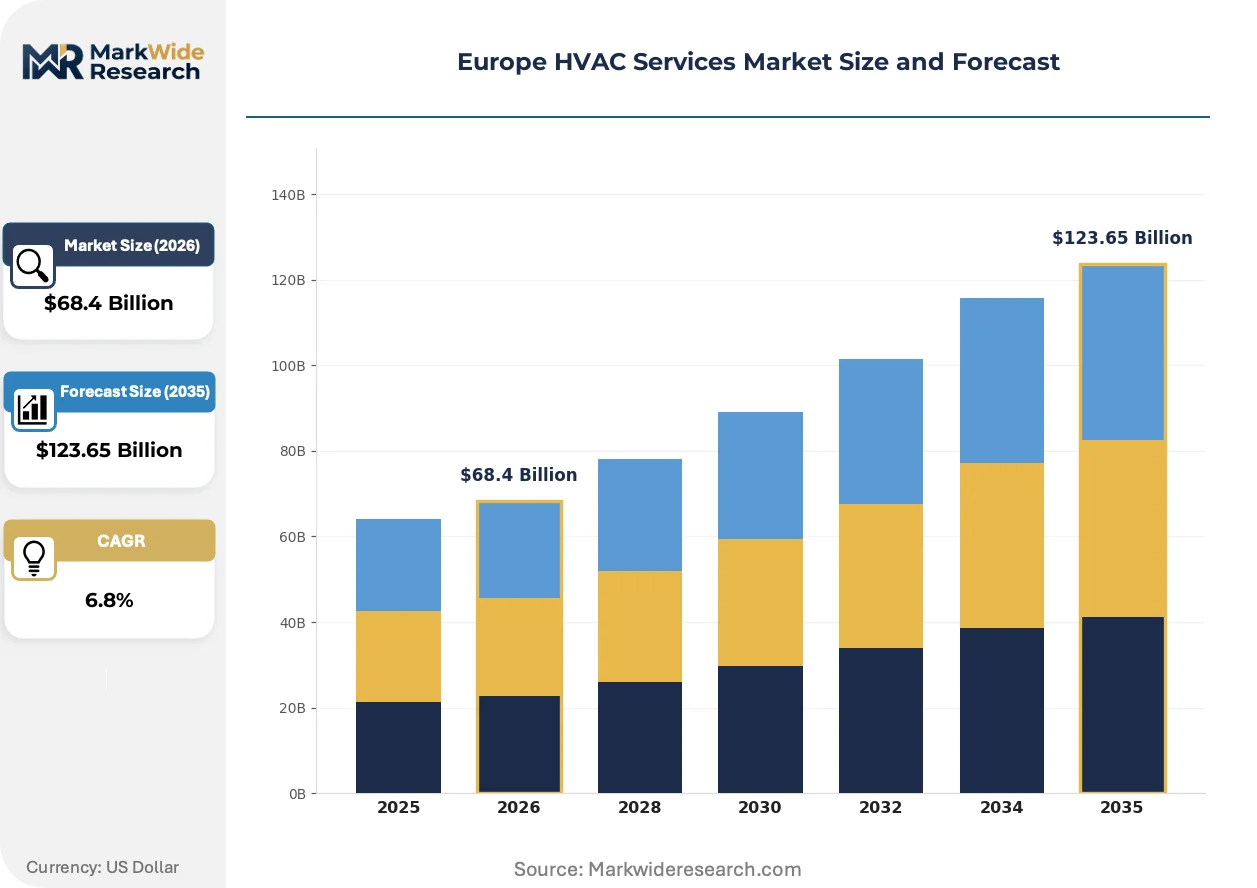
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $123.65 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Installation, Maintenance, Repair, Consulting End User: Residential, Commercial, Industrial, Government Technology: VRF, Chillers, Rooftop Units, Boilers System Type: Centralized, Decentralized, Hybrid, Smart Systems |
| Companies Covered | Daikin Industries Ltd., Bosch Thermotechnik GmbH, Carrier Global Corporation, Viessmann Climate Solutions SE, Vaillant Group, NIBE Industrier AB, Mitsubishi Electric Corporation, Johnson Controls International plc, Systemair AB, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe HVAC Services Market Shifts & Advancements
Service delivery models across Europe are pivoting from reactive break-fix operations toward continuous performance contracts anchored by sensor infrastructure and remote diagnostics capability.
Heat pump technology is electrifying thermal service economics across the European commercial building sector. These systems replace gas-fired boilers in district heating connections and standalone applications. Facility managers in Nordic countries and the Netherlands are specifying air-source and ground-source configurations for new construction and deep retrofit projects. This transition is electrifying the skill requirements for installation crews and reshaping spare parts inventory toward electrical components rather than combustion assemblies.
The EU F-Gas Regulation mandates an 80% phase-down of hydrofluorocarbon refrigerants by 2030 against 2015 baseline levels. Equipment manufacturers must redesign chiller and rooftop unit architectures around CO2, propane, and ammonia alternatives. Service providers in Germany, France, and Belgium are experiencing the steepest compliance cost curves as their installed bases skew toward high-GWP legacy systems requiring early retirement or refrigerant conversion.
Building owners are unbundling equipment procurement from long-term service agreements and awarding these contracts to separate vendors. This pattern fragments vendor relationships that historically combined sale and service under single-source arrangements. Property management firms in London, Paris, and Frankfurt are driving this disintermediation through competitive tender processes that evaluate service capability independently of equipment brand affiliation.
Europe HVAC Services Market Segmentation
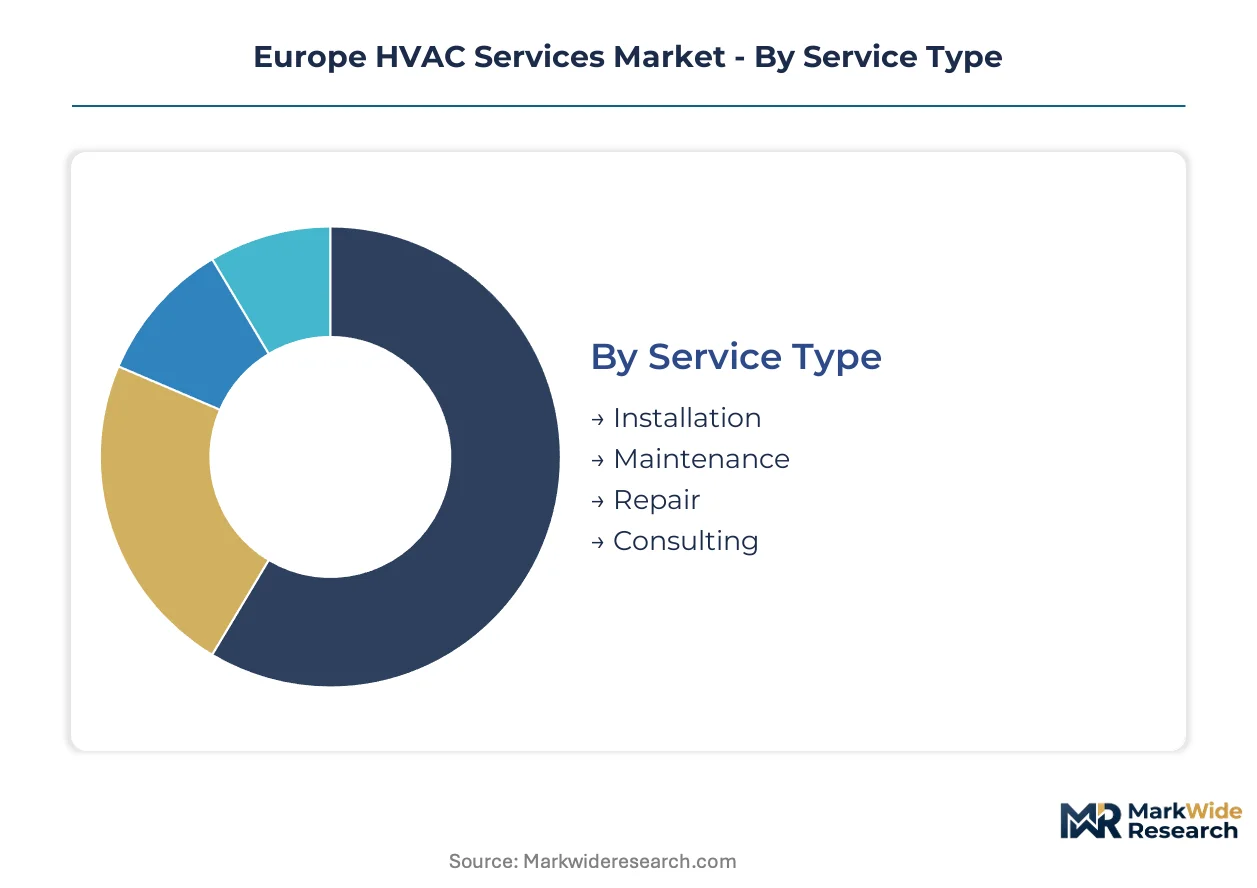
Service providers across Europe calibrate resource allocation around distinct technical and customer archetypes. Segmentation reveals where refrigerant handling certifications concentrate and where predictive maintenance platforms achieve attach rates.
Service Type:
Technical complexity and contract duration separate the four service categories, with capital intensity and recurring revenue potential defining competitive positioning.
- Installation:Equipment replacement cycles drive project-based revenue, with Germany's KBA-referenced building codes compressing timelines for chiller and heat pump deployments. France's ANSM-adjacent audit mandates accelerate retrofit volumes across Class A office stock.
- Maintenance:Long-term service agreements generate recurring margins as IoT-enabled predictive platforms extend contract durations. Netherlands facility managers increasingly specify performance-based terms tied to energy outcomes.
- Repair:Break-fix demand concentrates in legacy refrigerant systems facing F-Gas quota constraints. Technician availability limits response capacity during peak seasonal loads.
- Consulting:Advisory services attach to decarbonization pathway planning under CSRD disclosure requirements. Building owners in Belgium and the Netherlands procure independent guidance on refrigerant transition strategies.
Installation leads on scale; Consulting leads on momentum.
End User:
Customer procurement sophistication determines contract structure, with public tender requirements and sustainability mandates reshaping vendor selection criteria.
- Commercial:Property management firms in London, Paris, and Frankfurt unbundle equipment procurement from service agreements through competitive tender processes. Class A office operators prioritize vendor neutrality and response time guarantees.
- Industrial:Data center thermal management contracts in the Netherlands and Ireland represent emerging application volume with stringent uptime requirements. Process cooling specifications demand specialized refrigerant handling expertise.
- Residential:Heat pump electrification targets in Nordic countries expand installation demand for hybrid and all-electric systems. Single-family retrofits face technician capacity constraints.
- Government:Public building mandates under EU Green Deal implementation drive centralized procurement frameworks. National agencies specify extended warranty terms and local content requirements.
Commercial dominates contract value; Industrial climbs the fastest.
Technology:
Refrigerant chemistry and system architecture determine service skill requirements and spare parts inventory economics.
- VRF:Variable refrigerant flow configurations enable zoned climate control with heat recovery capabilities. Daikin Industries Ltd. leverages technology leadership to capture premium maintenance contracts in commercial districts.
- Chillers:Large-capacity centralized cooling systems face accelerated replacement schedules under F-Gas phase-down timelines. CO2 and ammonia alternatives require specialized safety certifications.
- Rooftop Units:Packaged systems serve retail and light commercial applications with standardized maintenance protocols. Equipment replacement cycles align with building lease renewals.
- Boilers:Gas-fired combustion systems face electrification pressure from heat pump substitution. Service revenue shifts toward electrical component expertise.
Chillers command highest per-unit service value; VRF gains share fastest.
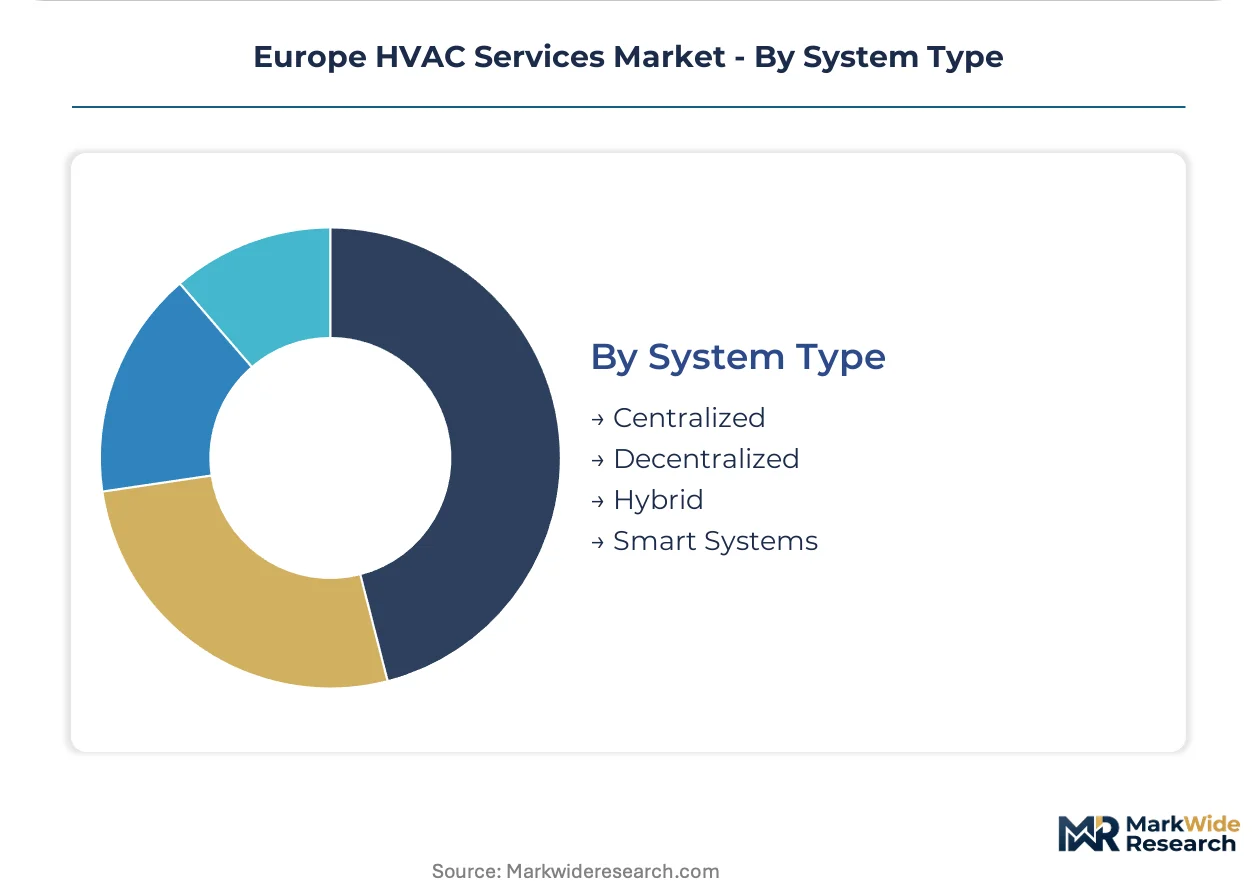
System Type:
Control architecture and distribution topology determine remote monitoring feasibility and technician dispatch frequency.
- Smart Systems:Sensor infrastructure enables predictive maintenance and continuous performance contracts. BACnet and Modbus protocol fragmentation complicates unified platform deployment.
- Centralized:Single-plant configurations serve large commercial and industrial facilities with dedicated maintenance crews. Equipment concentration reduces per-site service logistics costs.
- Hybrid:Combined thermal systems integrate heat pumps with backup combustion equipment. Dual-technology expertise requirements extend technician training timelines.
- Decentralized:Distributed units across building portfolios demand higher technician dispatch frequency. Property managers prioritize vendor networks with geographic density.
Centralized retains installed base dominance; Smart Systems show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr metropolitan region anchors European HVAC service demand through its dense concentration of industrial facilities and commercial building stock requiring thermal management upgrades.
Germany
Deep retrofit mandates under the KBA-referenced building energy codes are accelerating chiller replacement cycles across Class A office portfolios. The Federal Ministry for Economic Affairs and Climate Action coordinates heat pump deployment subsidies that expand installation service pipelines. Munich and Frankfurt property managers increasingly unbundle equipment procurement from long-term maintenance agreements.
France
ANSM-adjacent energy audit requirements and the national low-carbon strategy are compressing equipment replacement timelines for legacy refrigerant systems. The French Environment and Energy Management Agency administers building renovation grant schemes that elevate consulting service attach rates. Paris commercial districts exhibit the steepest technician certification demand for CO2 and hydrocarbon handling protocols.
Netherlands
Building stock electrification targets and district heating expansion are reshaping installation demand toward hybrid thermal systems. The national climate agreement mandates phase-out of natural gas heating in new construction by 2026. Rotterdam and Amsterdam facility managers specify performance-based maintenance contracts tied to energy outcome guarantees.
United Kingdom
The Future Buildings Standard and tightening Minimum Energy Efficiency Standards are forcing refrigerant transitions across commercial property portfolios. The Department for Business, Energy and Industrial Strategy oversees heat pump deployment targets that strain installation capacity. London property management firms drive vendor neutrality in competitive service tender processes.
Poland
EU cohesion fund infrastructure deployment and building modernization programs are creating expansion terrain for service network penetration. The National Fund for Environmental Protection and Water Management channels subsidies toward thermal efficiency upgrades. Warsaw and Krakow commercial districts exhibit underpenetrated maintenance contract coverage relative to Western European benchmarks.
Europe HVAC Services Market Competitive Landscape
Strategic partnerships dominate the current landscape as service providers seek to bridge refrigerant handling certification gaps and secure geographic density. The vendor base stratifies across three tiers: integrated equipment-service conglomerates, specialized regional contractors, and emerging predictive maintenance platform operators. Scale advantages concentrate in centralized service hub configurations that reduce industrial client response times. Technology licensing arrangements and backward integration into component manufacturing represent the two most frequent competitive moves.
Within the integrated equipment-service tier, Daikin Industries Ltd., Bosch Thermotechnik GmbH, and Carrier Global Corporation exemplify divergent strategic positions. Daikin occupies a position anchored by VRF technology leadership and premium maintenance contract capture in commercial districts. Bosch Thermotechnik sits within a captive service network model built on in-house heat pump manufacturing control. Carrier represents scale-driven hub-and-spoke logistics optimization for industrial thermal management accounts.
| Leading Market Players |
|---|
| Daikin Industries Ltd. |
| Bosch Thermotechnik GmbH |
| Carrier Global Corporation |
| Viessmann Climate Solutions SE |
| Vaillant Group |
| NIBE Industrier AB |
| Mitsubishi Electric Corporation |
| Johnson Controls International plc |
| Systemair AB |
| Others |
Supply & Pricing Matrix
Commercial property management firms in London, Paris, and Frankfurt concentrate procurement authority for long-term service contracts, driving a project-to-subscription pricing evolution across the European HVAC services sector. Their competitive tender processes favor vendors bundling predictive maintenance platforms with equipment installations, compressing margins on standalone hardware sales.
Pricing Analysis
Copper and aluminum input volatility feeds directly into heat exchanger component costs, forcing service providers to renegotiate fixed-price installation contracts mid-cycle. Pricing stratifies across premium, standard, and economy tiers based on technician certification grade and after-sales service bundling. Cost compression in the standard tier is intensifying because F-Gas quota allocations constrain qualified labor supply. Residential heat pump retrofits exhibit highest price sensitivity; data center thermal management contracts show lowest.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale industrial buyer demand for chiller and VRF systems, while regional contractor networks serve fragmented commercial portfolios. Manufacturing concentrates in Germany, Italy, and the Netherlands for recovery machinery and lower-GWP refrigerant handling equipment. The supply chain draws from copper smelters in Poland, aluminum processors in Norway, and compressor assembly plants in Slovakia. Single-source vulnerability around CO2 transcritical component suppliers in Germany presents structural risk. Distribution runs through captive service networks owned by integrated manufacturers and independent contractor alliances.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation compounds service demand through mandatory refrigerant phase-down timelines, with the 2030 hydrofluorocarbon reduction target functioning as the dominant regulatory milestone reshaping contract structures.
For Market Incumbents: Extend predictive maintenance platform penetration to capture recurring revenue streams before emerging IoT-native competitors establish footholds. Consolidate technician certification capacity through acquisition of specialized training providers in France and Belgium. Defensive positioning requires backward integration into heat pump manufacturing to offset margin pressure from unbundled procurement trends.
For New Entrants and Emerging Players: Launch via performance-based contracting models targeting underpenetrated commercial districts in Warsaw and Krakow ahead of EU cohesion fund deployment. White-space concentrates in industrial process cooling for data centers in Ireland and the Netherlands. Geographic arbitrage through Polish and Romanian technician training pipelines offers the most viable go-to-market angle.
For Investors and Strategic Acquirers: Integrated equipment-service conglomerates are the most active acquirers in this space, seeking captive service network density. The five-to-ten year viability window favors targets with established CO2 and hydrocarbon safety certification infrastructure. Acquisition target archetype: regional contractors with F-Gas quota allocations and smart system integration capability. Monitor refrigerant quota auction prices as the inflection signal for service capacity constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Technician Certification Capacity Expansion | Addresses F-Gas quota bottlenecks constraining service delivery across Germany and France. |
| Predictive Maintenance Platform Integration | Extends contract durations for Daikin and Carrier through IoT-enabled remote diagnostics. |
| Backward Integration into Heat Pump Manufacturing | Mirrors Bosch Thermotechnik's captive supply model for installation margin control. |
| Eastern European Service Network Buildout | Captures EU cohesion fund infrastructure deployment in Poland and Romania. |
| CO2 Transcritical System Safety Investment | Positions providers for accelerated chiller replacement under F-Gas phase-down timelines. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with facility managers, HVAC service contractors, OEM aftermarket heads, and refrigerant handling technicians with secondary validation. Primary sources included maintenance directors at Class A office portfolios, procurement leads at property management firms, and technical training directors. Secondary data drew from EU F-Gas quota registries, national building energy code filings, and equipment manufacturer service contract disclosures. Bottom-up service contract enumeration and top-down macroeconomic scaling provided triangulation.
Segment-weighting across service type, end user, technology, and system type dimensions anchored the analytical framework. CAGRs derived from equipment replacement cycle modeling, regulatory compliance cost curves, and smart system penetration trajectories. Forecast inputs incorporated F-Gas phase-down timelines, heat pump deployment subsidies, and technician certification pipeline constraints.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt refrigerant quota allocation changes or copper price shock scenarios. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Global Chilled Beam System Market
HVAC Systems
Marine HVAC System Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Cold Insulation Market
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
HVAC Control System Market
HVAC Systems
Global Tunnel and Metro Ventilation Market
HVAC Systems
Freeze and Thaw Systems Market
HVAC Systems
Global Ductless Heating and Cooling Systems Market
HVAC Systems
Roof Vents Market
HVAC Systems
Regenerative Heat Exchanger Market
HVAC Systems
HVAC Insulation Market
HVAC Systems
AC Mitigation System Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
HVAC and Fire Protection Insulation Market