
 Throttle Cable Market | 2026-2036
Throttle Cable Market Size, Share, and Industry Trends Forecast 2026-2036
Throttle Cable Market Analytics
Mechanical engineering talent with wire-rope fabrication expertise is collapsing across North American and European supplier bases, tightening OEM qualification timelines and pushing volume toward established Asian manufacturers. Continental leverages its integrated cable-harness operations to sustain long-term supply contracts with German automakers. Denso anchors electronic throttle actuator production through captive cable manufacturing in Japan. Orscheln Products specializes in push-pull mechanical assemblies for off-highway equipment, occupying a defensible niche as electronic systems penetrate passenger vehicles.
A throttle cable transmits operator input from a pedal or lever to an engine's throttle body through a flexible wire core, typically constructed from galvanized or stainless steel strands sheathed in polyethylene or PVC conduits with liner materials to minimize friction. The assembly translates linear displacement into rotational throttle plate movement, maintaining precise engine speed control in internal combustion applications across automotive, marine, and industrial equipment. Electronic throttle cables now lead product type evolution as drive-by-wire architectures displace mechanical linkages in passenger vehicles, while stainless steel material grades command premium positioning due to corrosion resistance demands in marine and agricultural environments. Aftermarket provider channels represent the fastest-growing end-user segment as vehicle age extension and equipment fleet longevity sustain replacement part demand.
EPA tailpipe emissions enforcement and NHTSA vehicle safety standards in the United States shape throttle response calibration requirements and cable redundancy specifications for unintended acceleration prevention. ECE R79 type approval in Europe mandates specific disengagement force thresholds and durability cycles for steering-column-mounted throttle controls. China's MIIT fuel consumption regulations and GB standards for automotive components are driving domestic suppliers toward electronic throttle adoption. Stakeholders must monitor regulatory divergence between mechanical legacy system grandfathering and electronic mandate timelines across major production jurisdictions.
Market Dynamics
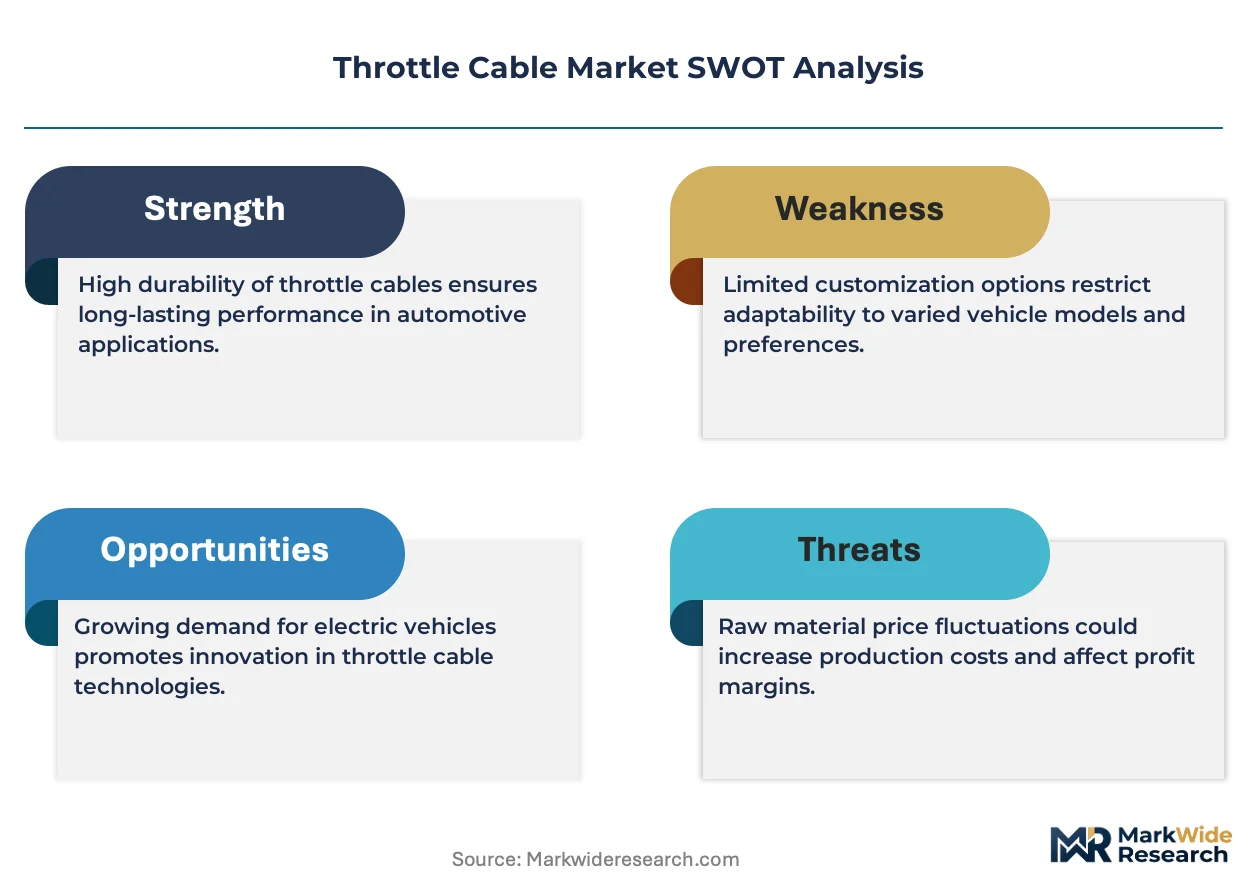
The throttle cable market is compressing under the mechanical-to-electronic transition as drive-by-wire architectures systematically displace Bowden cable assemblies in passenger vehicle powertrains, forcing suppliers to pivot production capacity toward actuators and position sensors while defending aftermarket replacement revenues.
Growth Catalysts
- EPA Emissions Enforcement:The EPA's tightened tailpipe standards are compelling OEMs to recalibrate throttle response precision, sustaining demand for high-fidelity cable assemblies in legacy internal combustion platforms during the transition window.
- Aftermarket Channel Expansion:Aging vehicle fleets across North America and Europe are extending service intervals, driving replacement part procurement through independent distributors and service chains.
- Polyurethane Material Transition:REACH compliance mandates in Europe are accelerating coating substitutions from PVC to polyurethane formulations, creating specification upgrade cycles across supplier portfolios.
Market Restraints
- Electronic Throttle Substitution:Drive-by-wire systems are eliminating mechanical linkages entirely in new passenger vehicle architectures, permanently constraining greenfield cable demand.
- Steel Input Volatility:Galvanized and stainless steel wire-rope feedstock prices fluctuate with raw material markets, compressing margin predictability for cable fabricators.
- Asian Supply Concentration:Captive production by Chinese domestic OEMs is consolidating volume within integrated supply chains, limiting third-party supplier access.
Strategic Opportunities
- Off-Highway Equipment Defense:Marine, agricultural, and construction machinery segments retain mechanical throttle dependency due to environmental exposure and reliability requirements, offering defensible niche positioning.
- India Fleet Modernization:Commercial vehicle renewal programs and tightening BS-VI emission norms are sustaining cable demand in price-sensitive truck and bus segments.
- Service Bundling Innovation:Integrated cable-and-actuator replacement kits are capturing maintenance channel shelf space, shifting transaction value from commodity hardware to system-level solutions.
Industry Challenges
- Wire-Rope Fabrication Expertise Collapse:Mechanical engineering talent with specialized cable construction knowledge is thinning across North American and European supplier bases, extending OEM qualification timelines.
- Dual Certification Burden:Suppliers must simultaneously maintain NHTSA safety compliance for mechanical redundancy and ISO 26262 functional safety for electronic interface components, straining quality systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Throttle Cable Market |
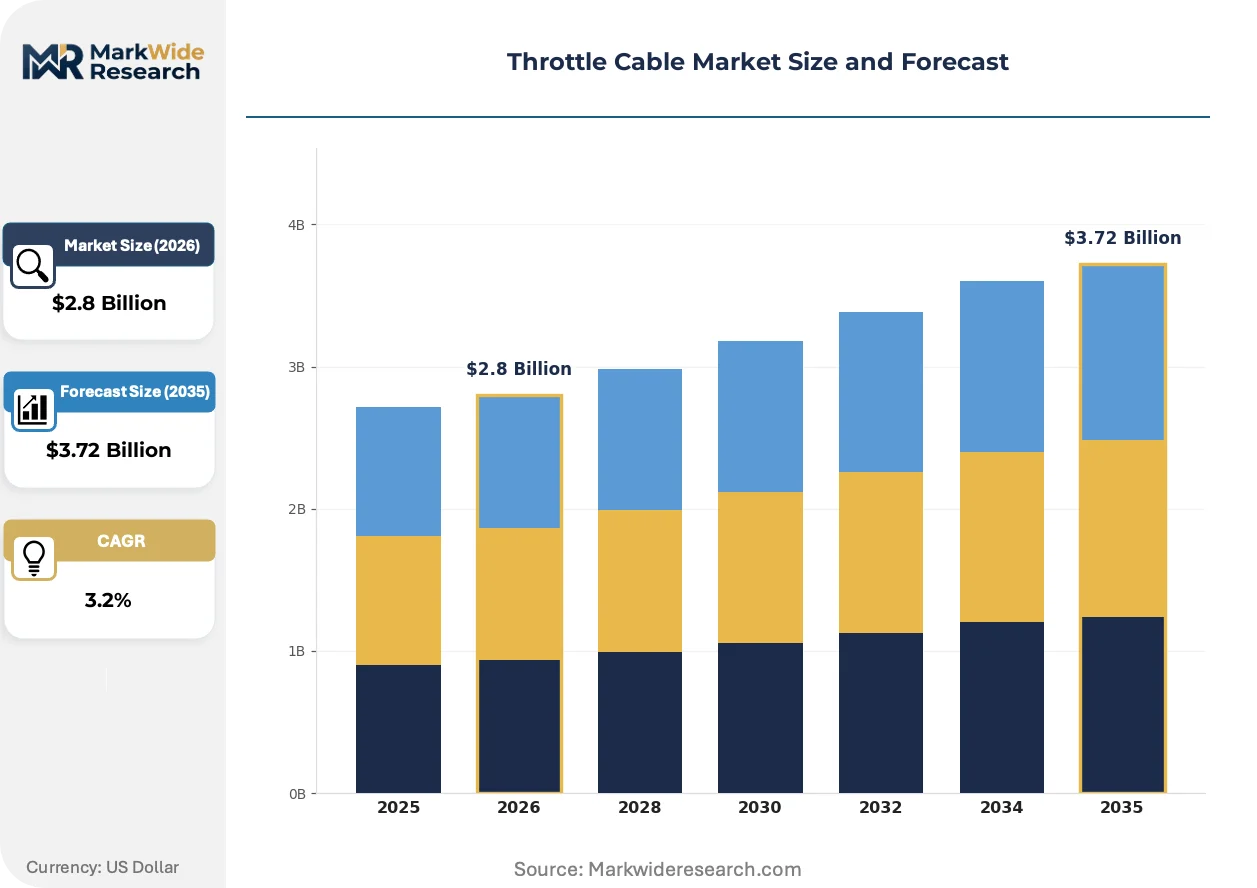
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $3.72 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Push-Pull, Mechanical, Electronic, Flexible Application: Automotive, Marine, Agricultural, Industrial Equipment Material: Stainless Steel, Polyurethane, PVC, Nylon End User: OEMs, Aftermarket Providers, Manufacturers, Distributors |
| Companies Covered | Magneti Marelli, DURA Automotive Systems, Continental, Motion Pro, Orscheln Products, Denso, SKF, Hitachi, Delphi Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Throttle Cable Market Evolving Landscape
Electronic integration is fundamentally restructuring how throttle control systems are engineered, validated, and procured. Three distinct vectors are compressing traditional cable economics while opening adjacent value pools.
Electronic throttle actuator modules are miniaturizing through integrated motor-position sensor fusion, enabling packaging within steering column assemblies previously reserved for mechanical cables. Tier 1 suppliers are adopting these compact units for mid-range vehicle platforms where space and weight constraints previously favored mechanical solutions. This miniaturization is collapsing the historical cost gap between electronic and mechanical systems, accelerating platform-level displacement timelines.
REACH substance restrictions are mandating phased elimination of phthalate-based PVC sheathings across European supply chains, forcing reformulation investments and supplier recertification. The regulation is compressing procurement flexibility as qualified material sources consolidate around polyurethane and thermoplastic elastomer alternatives. Cable assemblies for marine and agricultural export markets are most affected, with manufacturers dual-tracking specifications to maintain cross-border shipment eligibility.
Fleet operators are unbundling after-sales service contracts from original equipment procurement, creating direct sourcing relationships with cable specialists for maintenance, repair, and overhaul operations. This disintermediation is shifting volume toward aftermarket-focused distributors with technical support capabilities and degrading the historical parts-captive model of integrated OEM service networks. North American commercial vehicle and construction equipment sectors exhibit the most pronounced behavioral shift, with independent service providers capturing an expanding share of replacement transactions.
Throttle Cable Market Segmentation
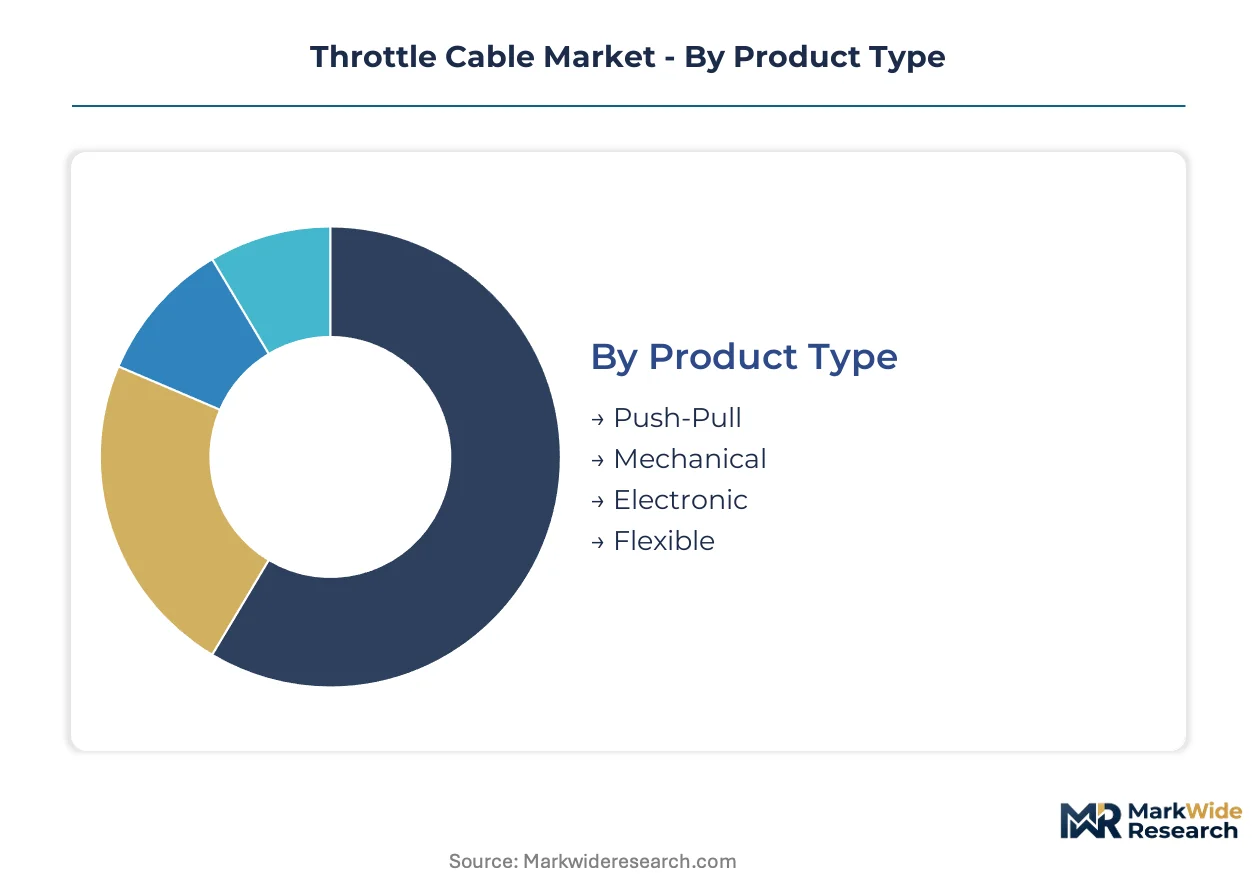
Throttle cable procurement patterns diverge sharply across mechanical versus electronic architectures, with margin capture shifting from commodity wire-rope fabrication toward integrated actuator systems. Segment boundaries are blurring as REACH-compliant material transitions and aftermarket channel disintermediation reshape supplier economics.
Product Type:
Margin pools concentrate in electronic actuator modules where sensor fusion and motor integration command premium positioning, while mechanical cable assemblies face persistent price compression from Asian supply consolidation.
- Push-Pull:Dual-direction cable assemblies translate linear force into bidirectional control movement through concentric wire-rope construction with polyethylene liners. Off-highway equipment manufacturers in agricultural and construction sectors specify these for joystick and lever applications where environmental sealing exceeds passenger vehicle requirements. Demand concentrates in North American heavy-equipment OEMs defending mechanical redundancy against electronic failure modes.
- Mechanical:Traditional Bowden cable architecture transmits pedal displacement via stranded steel cores sheathed in extruded polymer conduits with anti-friction coatings. Legacy internal combustion platforms across India's commercial vehicle fleet sustain procurement volumes as BS-VI compliance timelines extend mechanical system grandfathering. Stainless steel grades command premium positioning in marine environments where salt corrosion accelerates replacement cycles.
- Electronic:Drive-by-wire actuator modules integrate position sensors, DC motors, and control electronics within compact housing assemblies.
- Flexible:Multi-strand wire cores with spiral-wound reinforcement enable tight-radius routing through crowded engine compartments.
Mechanical holds installed capacity across legacy vehicle fleets. Electronic is rotating up the share rankings as OEM platform architectures consolidate on drive-by-wire.
Application:
Volume concentration tracks equipment durability requirements and environmental exposure severity, with marine and agricultural segments retaining mechanical dependency longest.
- Automotive:Passenger vehicle and light-truck applications span both mechanical legacy systems and electronic throttle actuators depending on platform generation and OEM sourcing strategy. China's domestic OEMs are vertically integrating cable production for cost-sensitive entry segments while importing electronic modules for premium platforms. EPA emissions calibration requirements sustain high-fidelity cable demand during the transition window.
- Marine:Outboard motor and inboard throttle controls prioritize corrosion resistance and salt-spray durability over electronic complexity given moisture ingress risks. Stainless steel construction with polyurethane sheathing dominates specifications as REACH phthalate restrictions eliminate PVC alternatives for European export eligibility. Replacement part demand concentrates in Mediterranean and Gulf Coast recreational boating markets.
- Agricultural:Tractor and harvester throttle assemblies prioritize field reliability and technician serviceability over electronic sophistication.
- Industrial Equipment:Forklift, generator, and compressor applications balance cost constraints with duty-cycle durability requirements.
Automotive carries the volume base. Marine is climbing the fastest as recreational boating fleet age extends replacement part procurement.
Material:
Specification shifts are compressing PVC's addressable market as regulatory deadlines force polyurethane and nylon substitutions across European supply chains.
- Stainless Steel:304 and 316-grade wire-rope constructions deliver tensile strength and corrosion resistance for marine, agricultural, and premium automotive applications where service life justifies material cost premiums. Galvanized alternatives dominate price-sensitive commercial vehicle segments where replacement intervals align with maintenance schedules. Salt-spray testing protocols differentiate supplier qualification tiers.
- Polyurethane:Thermoplastic elastomer formulations replace PVC sheathing under REACH substance restrictions, offering comparable flexibility with improved abrasion resistance and UV stability. Reformulation investments and recertification cycles are consolidating qualified supplier bases around established compounders. Marine export specifications are dual-tracking to maintain cross-border shipment eligibility.
- PVC:Legacy phthalate-based sheathings face phased elimination across European supply chains.
- Nylon:High-temperature liner materials reduce friction coefficients in high-cycle applications.
Stainless steel anchors premium positioning. Polyurethane is gaining share fastest as regulatory deadlines compress PVC conversion timelines.
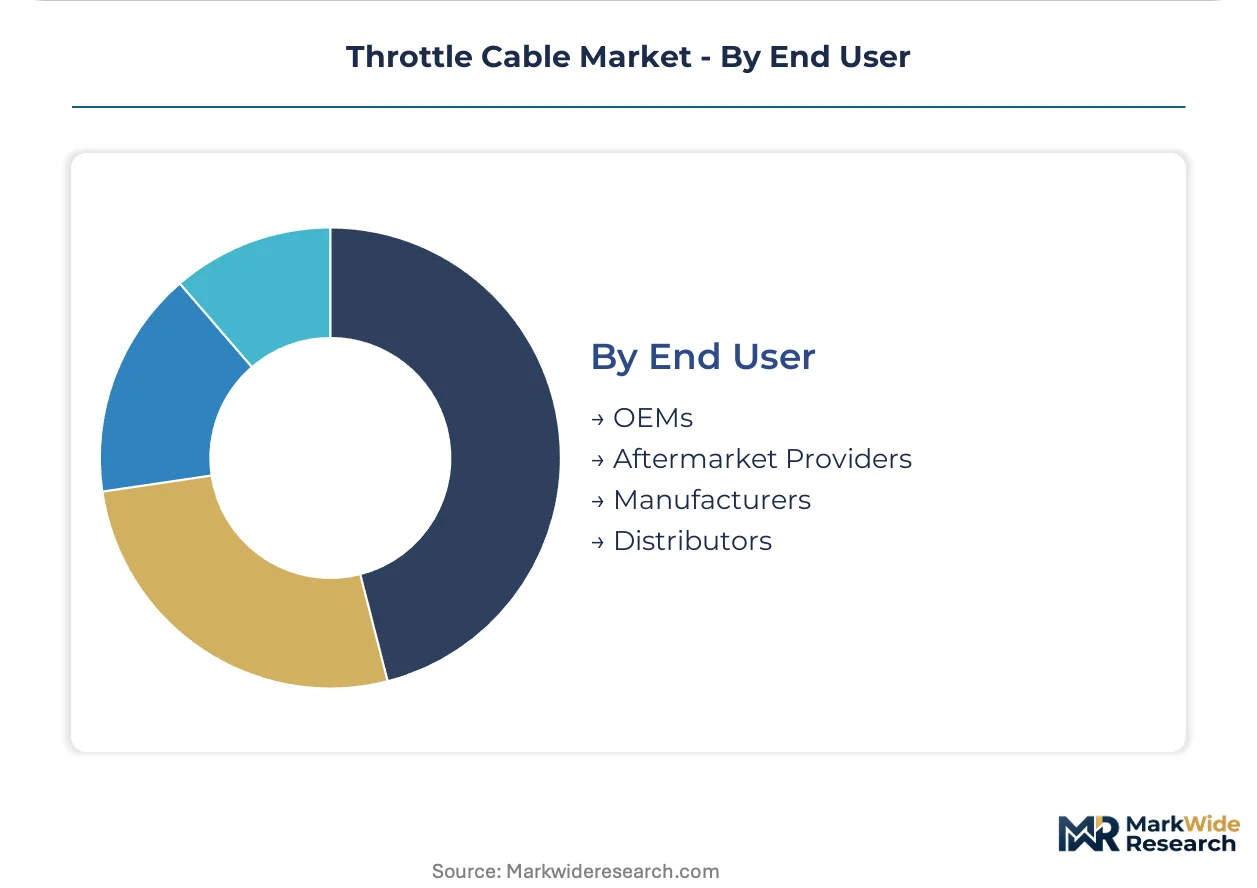
End User:
Channel economics are bifurcating as fleet operators disintermediate OEM service networks for direct aftermarket sourcing.
- OEMs:Original equipment manufacturers specify cable assemblies during vehicle platform development, with qualification timelines extending due to collapsing wire-rope fabrication expertise in North American and European supplier bases. Long-term supply contracts favor integrated harness suppliers with captive cable production. German automakers anchor volume through Continental's bundled cable-harness offerings.
- Aftermarket Providers:Independent distributors and service chains are capturing replacement volume as vehicle age extension and fleet longevity sustain parts demand. North American commercial vehicle sectors exhibit pronounced behavioral shift toward technical-support-capable specialists. Integrated cable-and-actuator replacement kits are shifting transaction value from commodity hardware to system-level solutions.
- Manufacturers:Tier 2 component suppliers produce cable subassemblies for integration into larger systems.
- Distributors:Wholesale and retail channels intermediate between producers and installation points.
OEMs control new equipment specification. Aftermarket providers are expanding fastest as fleet maintenance contracts unbundle from original procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT fuel consumption regulations and GB standards for automotive components anchor China's dominant position in throttle cable procurement. Domestic OEMs are building captive cable production capacity while importing electronic modules for premium platforms.
China
Domestic OEMs are vertically integrating cable production for cost-sensitive entry segments. MIIT fuel consumption regulations and GB standards for automotive components are driving suppliers toward electronic throttle adoption. Shanghai and Yangtze River Delta clusters concentrate captive production facilities serving BYD, Geely, and SAIC.
Germany
Continental leverages integrated cable-harness operations to sustain long-term supply contracts with German automakers. ECE R79 type approval mandates specific disengagement force thresholds and durability cycles for steering-column-mounted controls. Stuttgart and Munich anchor precision engineering clusters where tier 1 suppliers maintain qualification laboratories.
United States
EPA tailpipe emissions enforcement and NHTSA vehicle safety standards shape throttle response calibration requirements and cable redundancy specifications. Orscheln Products specializes in push-pull mechanical assemblies for off-highway equipment from its Missouri base. Detroit and Midwest industrial corridors retain aftermarket distribution hubs serving aging commercial vehicle fleets.
Japan
Denso anchors electronic throttle actuator production through captive cable manufacturing. METI industrial standards and JIS specifications govern material grades and fatigue testing protocols. Nagoya and Chubu region clusters concentrate integrated motor-position sensor fusion capabilities for compact actuator modules.
India
Commercial vehicle renewal programs and tightening BS-VI emission norms sustain cable demand in price-sensitive truck and bus segments. BIS certification requirements and DGFT import policies protect domestic fabricators from Asian supply concentration. Pune and Chennai manufacturing corridors host joint ventures supplying Mahindra, Tata Motors, and Ashok Leyland.
Throttle Cable Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier. Tier 1 automotive suppliers with captive harness operations command OEM qualification pathways. Specialist fabricators defend aftermarket channels through technical support capabilities. Competitive moves concentrate on portfolio diversification into electronic actuators and geographic expansion through distributor partnerships.
Within the integrated tier, Continental and Denso exemplify the bundled cable-harness and captive manufacturing archetypes respectively. Orscheln Products occupies a defensible position among mechanical assembly specialists serving off-highway equipment segments where environmental exposure sustains legacy demand.
| Leading Market Players |
|---|
| Magneti Marelli |
| DURA Automotive Systems |
| Continental |
| Motion Pro |
| Orscheln Products |
| Denso |
| SKF |
| Hitachi |
| Delphi Technologies |
| Others |
Value Network & Pricing Analysis
Capacity utilization at Chinese wire-rope fabricators shapes global price floors by compressing marginal production costs and forcing European and North American suppliers into premium-tier positioning or exit. This scale asymmetry concentrates procurement leverage within integrated OEM supply chains while independent aftermarket distributors absorb residual volume at compressed margins.
Pricing Analysis
Chinese domestic OEMs command 15-25% cost advantages over European suppliers due to captive cable production and Yangtze River Delta cluster density. Three-tier pricing structure across premium, standard, and economy levels separates stainless steel marine specifications from galvanized commercial vehicle grades and PVC-sheathed legacy assemblies. Cost compression in standard mechanical cables is intensifying because REACH-compliant polyurethane reformulation investments are consolidating qualified supplier bases. Fleet operators and independent aftermarket distributors exhibit highest price sensitivity, while marine OEMs purchasing corrosion-resistant specifications show lowest elasticity due to replacement cycle penalties.
Supply Chain Analysis
China, Japan, and Germany anchor throttle cable fabrication through divergent operational models — Chinese vertical integration, Japanese actuator-captive production, and German harness-bundled supply. Raw material feeds draw from galvanized steel wire-rope mills in Hebei province, stainless steel strand suppliers in Nagoya, and polyurethane compounders in the Rhine-Ruhr corridor. Single-source vulnerability concentrates in REACH-compliant coating formulations where European recertification timelines have eliminated secondary qualified sources. Distribution runs through OEM direct procurement for new equipment and independent technical distributors for aftermarket replacement, with service bundling shifting transaction value toward integrated kit solutions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical-to-electronic transition fragmentation creates defendable niche opportunities as wire-rope fabrication expertise collapses in Western supplier bases and fleet operators disintermediate OEM service networks.
For Market Incumbents: Compound defensive positioning through backward integration into polyurethane coating compounding and captive stainless steel wire-rope drawing to secure REACH-compliant supply chains against recertification bottlenecks. Denso's actuator-cable fusion model and Continental's harness-bundling approach demonstrate how integrated production architectures extend OEM qualification timelines and compress competitor access. Priority lever rests on technical service capabilities for aftermarket channels where independent distributors are capturing replacement volume. For New Entrants and Emerging Players: Anchor in India's BS-VI commercial vehicle renewal cycle where price-sensitive truck and bus segments sustain mechanical cable demand through extended grandfathering timelines. Orscheln Products' off-highway specialization demonstrates how environmental exposure requirements in agricultural and construction equipment create defensible positioning against electronic substitution. Go-to-market angle targets technical support bundling with integrated cable-and-actuator replacement kits for fleet maintenance contracts unbundling from OEM networks. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors mechanical fabrication specialists with transferable expertise into electronic actuator subassembly production. Five-to-ten year viability hinges on aftermarket channel control and marine/agricultural segment diversification as passenger vehicle volumes compress. Acquisition target archetype: regional cable fabricators with BIS certification and established relationships with Mahindra, Tata Motors, or Ashok Leyland in India's protected domestic market. Signal to watch: MIIT fuel consumption regulation enforcement tightening electronic throttle mandates in China's entry vehicle segments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Compounding | REACH recertification timelines are consolidating qualified coating suppliers around established compounders with ECHA pre-registration. |
| Marine Specification Dual-Tracking | Salt-spray testing protocols differentiate supplier tiers for Mediterranean and Gulf Coast recreational boating replacement demand. |
| Integrated Cable-Actuator Kit Development | System-level solutions capture maintenance channel shelf space as fleet operators disintermediate OEM service networks. |
| India BIS Certification Investment | DGFT import policies protect domestic fabricators supplying commercial vehicle renewal programs under BS-VI norms. |
| Off-Highway Equipment Technical Service Expansion | Environmental exposure and reliability requirements in agricultural machinery sustain mechanical throttle dependency longest. |
Research Methodology
A spread of perspectives from OEM platform engineers, Tier 1 supplier procurement leads, aftermarket distributor operations heads, and marine equipment specification managers converged on the working assumptions driving mechanical-to-electronic transition timelines. Primary fieldwork combined structured interviews with secondary validation through EPA enforcement actions, ECE R79 type approval documentation, MIIT fuel consumption regulation filings, and vehicle production database cross-referencing. Bottom-up cable assembly volume estimates triangulated against top-down OEM platform content assumptions.
Segmentation dimensions modeled span product type, application, material grade, and end-user channel across the analysis window. Mechanical, electronic, push-pull, and flexible architectures were tracked against automotive, marine, agricultural, and industrial equipment deployments. CAGRs derived from platform-level displacement curves weighted by regional regulatory grandfathering schedules and fleet age demographics. Industry-specific forecast inputs incorporated BS-VI commercial vehicle renewal program timelines and REACH substance restriction phase-out deadlines.
Material uncertainties — steel input volatility, electronic mandate acceleration, and wire-rope fabrication expertise collapse — sit outside the modeled envelope and could compress or extend transition timelines. Forecasts reflect assumptions about regulatory enforcement consistency and OEM sourcing strategy continuity. Recalibration cycles align with material shifts in EPA emissions enforcement, MIIT electronic throttle adoption mandates, and aftermarket channel consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Vehicle Components
HCV Axles Market
Vehicle Components
Air Ride Suspension Systems Market
Vehicle Components
Seating and Positioning Belts Market
Vehicle Components
Anchorage Connector Market
Vehicle Components
Saudi Arabia Refrigerated Trailer Market
Vehicle Components
Vehicle Cargo Box Market
Vehicle Components
Hooklift Trailer Market
Vehicle Components
Industrial Gearbox Market
Vehicle Components
Car Modification Market
Vehicle Components
Rail Wheel and Axle Market
Vehicle Components
Exhaust Manifolds and Downpipes Market
Vehicle Components
United States Automotive Connectors Market
Vehicle Components
Exhaust Gas Recirculation (EGR) Valve Market
Vehicle Components
Locomotive Lighting Batteries Market
Vehicle Components
Global Automotive Composite Liftgate Market
Vehicle Components
High Efficiency Rolling Bearings Market